
 Europe and MEA Food Phosphate Market | 2026-2036
Europe and MEA Food Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe and MEA Food Phosphate Market Analysis
The EU Green Deal is rebalancing phosphate sourcing priorities across European food manufacturing. ICL Group Ltd. leverages integrated phosphate rock mining and downstream purification to sustain supply security for food-grade applications. Budenheim KG anchors its position through specialized calcium phosphate portfolios tailored to bakery and dairy processors. Prayon S.A. competes on technical phosphate grades that meet evolving EU purity benchmarks.
Food phosphates comprise mineral salts derived from phosphoric acid, formulated as mono-, di-, or tricalcium variants with controlled pH buffering capacity between 2.5 and 8.0 depending on composition. These compounds function primarily as moisture-retention agents, emulsion stabilizers, and mineral fortificants in processed foods. Sodium phosphate variants dominate preservation and emulsification applications due to established efficacy in meat processing and cheese manufacturing. Dicalcium phosphate represents the fastest-growing product category as nutritional supplement applications expand across fortified dairy and bakery segments in the Middle East. Monocalcium phosphate maintains mature demand in leavening systems, though margin pools are shifting toward tricalcium phosphate for calcium-fortified clean-label formulations.
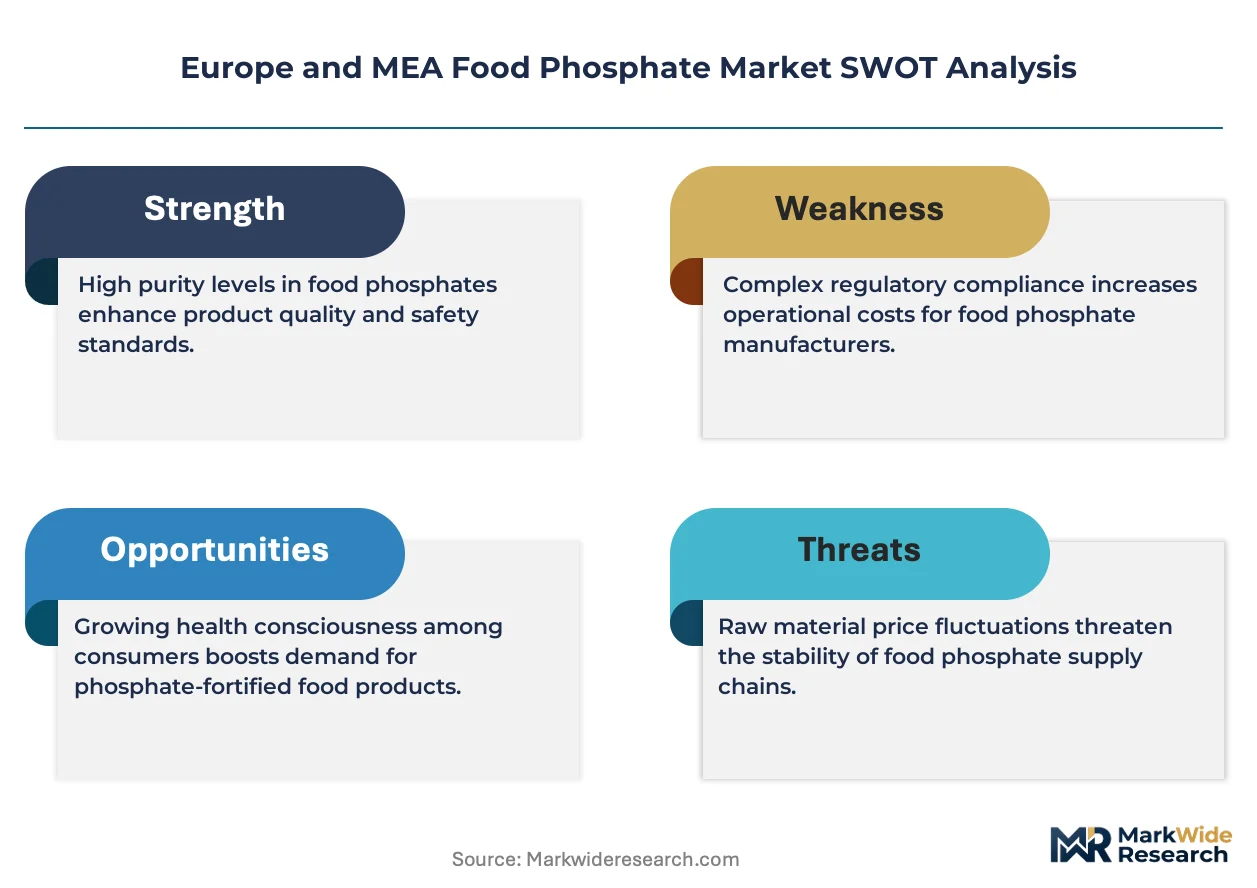
EMA food additive evaluations, REACH substance restrictions, and Saudi SFDA import specifications collectively determine market access thresholds for phosphate suppliers serving Europe and MEA. EFSA maximum level guidelines for phosphorus additives in processed meats directly influence formulation decisions by meat processors in Italy and Spain. Stakeholders must monitor divergence between EU additive harmonization and emerging Gulf Cooperation Council national standards as the UAE and Saudi Arabia develop independent food chemical regulatory capacities.
Market Dynamics
REACH substance restrictions and EFSA maximum level guidelines for phosphorus additives are compressing formulation flexibility for meat processors across Italy, Spain, and Germany. These regulatory constraints are forcing phosphate suppliers to requalify product portfolios and redirect technical resources toward compliance documentation.
Growth Catalysts
- EU F-Gas Regulation:Tightening purity standards for food-grade phosphates are accelerating investment in downstream purification capacity by integrated mining operators serving European dairy and bakery formulators.
- Processed meat sectors in Germany and Saudi Arabia:Manufacturers are expanding phosphate adoption for moisture retention and shelf-life extension, creating sustained demand pull for sodium phosphate variants.
- Calcium-fortified clean-label formulations:Tricalcium phosphate demand is rising as nutritional supplement applications expand across fortified dairy segments in the Middle East.
Market Restraints
- Phosphate rock supply concentration:Dependence on captive mining assets in select geographies creates vulnerability for European processors lacking backward integration into upstream phosphate rock extraction.
- REACH compliance costs:Registration, evaluation, and authorization requirements impose fixed cost burdens that disproportionately constrain small-scale specialty phosphate blenders.
- Plant-based protein substitutes:Clean-label meat alternatives in Northern European retail channels are reducing phosphate volume requirements in traditional processed meat applications.
Strategic Opportunities
- United Arab Emirates:The bakery and dairy sectors are scaling phosphate-enhanced formulations faster than domestic supply capacity, creating import substitution openings for qualified European suppliers.
- Saudi SFDA import specifications:Evolving national standards are creating first-mover advantages for suppliers who pre-qualify technical phosphate grades before Gulf Cooperation Council harmonization completes.
- Encapsulation technology convergence:Combining controlled-release phosphate systems with mineral fortification is opening premium positioning in pediatric and geriatric nutrition segments.
Industry Challenges
- Food-grade analytical chemistry expertise:Shortages of technicians capable of executing EMA food additive evaluation protocols are extending product requalification timelines for reformulated phosphate grades.
- Dual registration requirements:Divergence between EU additive harmonization and emerging Saudi SFDA national standards forces parallel compliance investments without guaranteed market access reciprocity.
- Legacy leavening system integration:Monocalcium phosphate replacement with tricalcium phosphate in existing bakery production lines requires capital-intensive equipment modification and process revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe and MEA Food Phosphate Market |
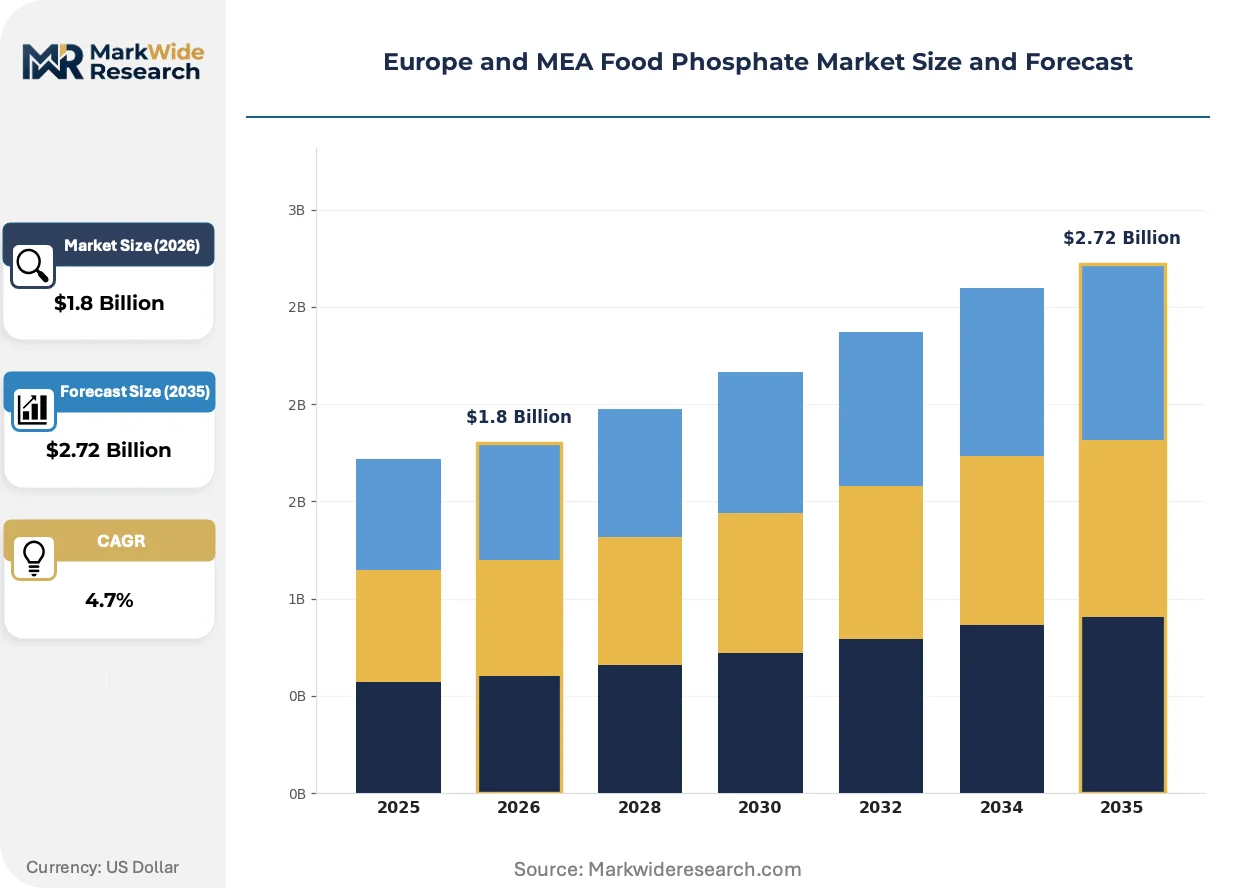
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocalcium Phosphate, Dicalcium Phosphate, Tricalcium Phosphate, Sodium Phosphate End User: Processed Food Manufacturers, Bakery, Dairy Products, Meat Processing Application: Food Preservation, Nutritional Supplement, Flavoring Agent, Emulsifier Packaging Type: Bags, Drums, Bulk Containers, Sachets |
| Companies Covered | ICL Group Ltd., Innophos Holdings, Inc., Budenheim KG, Prayon S.A., Groupe OCP, Nutrien Ltd., The Mosaic Company, Yara International ASA, EuroChem Group AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe and MEA Food Phosphate Market Emerging Trajectories
Clean-label mineral fortification is compressing traditional phosphate application boundaries across European and Middle Eastern food manufacturing. Formulators are rebalancing functionality against ingredient list simplicity.
Encapsulated tricalcium phosphate systems with controlled dissolution profiles are overtaking conventional uncoated variants in premium dairy applications. French and Italian infant nutrition manufacturers are adopting these systems at accelerated rates to meet calcium bioavailability claims without compromising sensory attributes. This technology is overtaking standard fortification approaches by enabling dual-function positioning across mineral supplementation and texture modification.
EU Green Deal sourcing requirements are redirecting phosphate procurement audits toward carbon intensity verification and circular economy feedstock documentation. ECHA substance evaluation timelines are extending for phosphate rock-derived inputs, forcing suppliers to pre-position alternative purification pathways. Meat processing sectors in Spain and Italy are most affected, with formulators accelerating phosphate reduction trials to preempt regulatory tightening.
Direct supplier relationships with bakery and dairy compounders are displacing traditional distributor intermediaries in Middle East procurement channels. Saudi and UAE food manufacturers are consolidating vendor panels to reduce qualification burden and secure volume commitments. This pattern is most visible in Dubai and Riyadh processing clusters, where procurement teams prioritize technical service proximity over multi-brand distributor access.
Europe and MEA Food Phosphate Market Segmentation
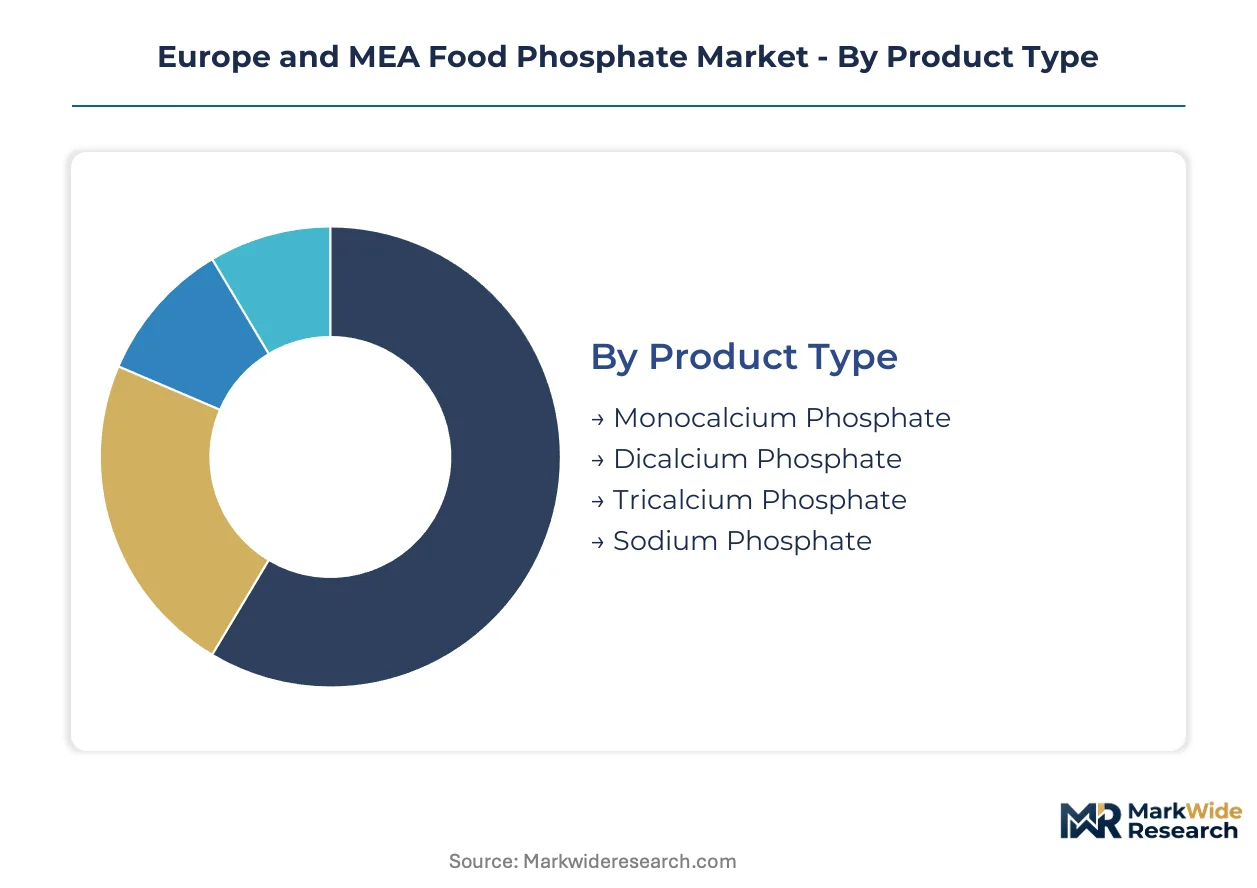
Food phosphate segmentation reveals how functional chemistry requirements diverge across preservation, fortification, and processing applications. Manufacturers configure product portfolios around end-user technical specifications rather than commodity availability.
Product Type:
Standardization dominates commodity phosphates while specialty variants demand customized purity certifications and particle engineering.
- Sodium Phosphate:Alkaline mineral salts engineered for pH buffering between 11.5 and 12.5, prized for moisture retention in cured meats. Demand concentrates with German and Spanish processors navigating EFSA maximum phosphorus thresholds in reformulated products.
- Dicalcium Phosphate:Dihydrate and anhydrous forms with 23% minimum calcium content, expanding fastest across Middle Eastern fortified dairy. UAE and Saudi dairy compounders specify this grade for clean-label calcium fortification without sensory compromise.
- Monocalcium Phosphate:Acidic leavening agent with rapid CO2 release profile, mature demand in conventional bakery systems. Italian and French industrial bakers maintain volume commitments despite margin compression.
- Tricalcium Phosphate:High-density calcium source for premium encapsulation applications, gaining traction in infant nutrition segments. Swiss and Dutch formulators specify controlled-dissolution variants for bioavailability claims.
Leading the category by volume: Sodium Phosphate. Growing fastest: Dicalcium Phosphate.
End User:
Customer concentration varies by phosphate grade sophistication, with compounders commanding technical service resources and commodity buyers prioritizing logistics reliability.
- Meat Processing:Cured and emulsified product manufacturers in Germany, Italy, and Spain drive sodium phosphate consumption for water-binding and shelf-life extension. REACH substance restrictions are forcing reformulation trials with reduced phosphate loading.
- Dairy Products:Fortified milk, yogurt, and cheese producers across France, UAE, and Saudi Arabia specify calcium phosphates for mineral enhancement. Clean-label positioning is compressing traditional emulsifier applications.
- Bakery:Industrial bread and pastry manufacturers in France and Italy maintain monocalcium phosphate volumes for chemical leavening. Equipment retrofit costs slow tricalcium phosphate substitution despite nutritional marketing advantages.
- Processed Food Manufacturers:Ready-meal and convenience food compounders in UK and Netherlands blend phosphate systems for multi-functional texture control. Procurement consolidation favors suppliers with integrated purification capabilities.
Volume leadership: Meat Processing. Steepest expansion trajectory: Dairy Products.
Application:
Application segmentation tracks the shift from preservation-centric to nutrition-centric phosphate deployment across European and Middle Eastern manufacturing.
- Food Preservation:Moisture retention and microbial inhibition in cured meats, dominant in Southern European processing. EFSA evaluation timelines are compressing permissible application rates.
- Nutritional Supplement:Calcium and phosphorus fortification in dairy and infant nutrition, fastest-growing application category. UAE and Saudi dairy sectors scale fortified product lines ahead of Gulf harmonization.
- Emulsifier:Protein stabilization in processed cheese and meat emulsions, mature demand with stable specifications. German and Dutch manufacturers optimize loading rates for cost control.
- Flavoring Agent:pH modulation and taste enhancement in beverage and sauce applications, niche positioning with specialized buffer systems. French sauce compounders specify technical grades for consistency.
Dominant by volume: Food Preservation. Climbing the fastest: Nutritional Supplement.
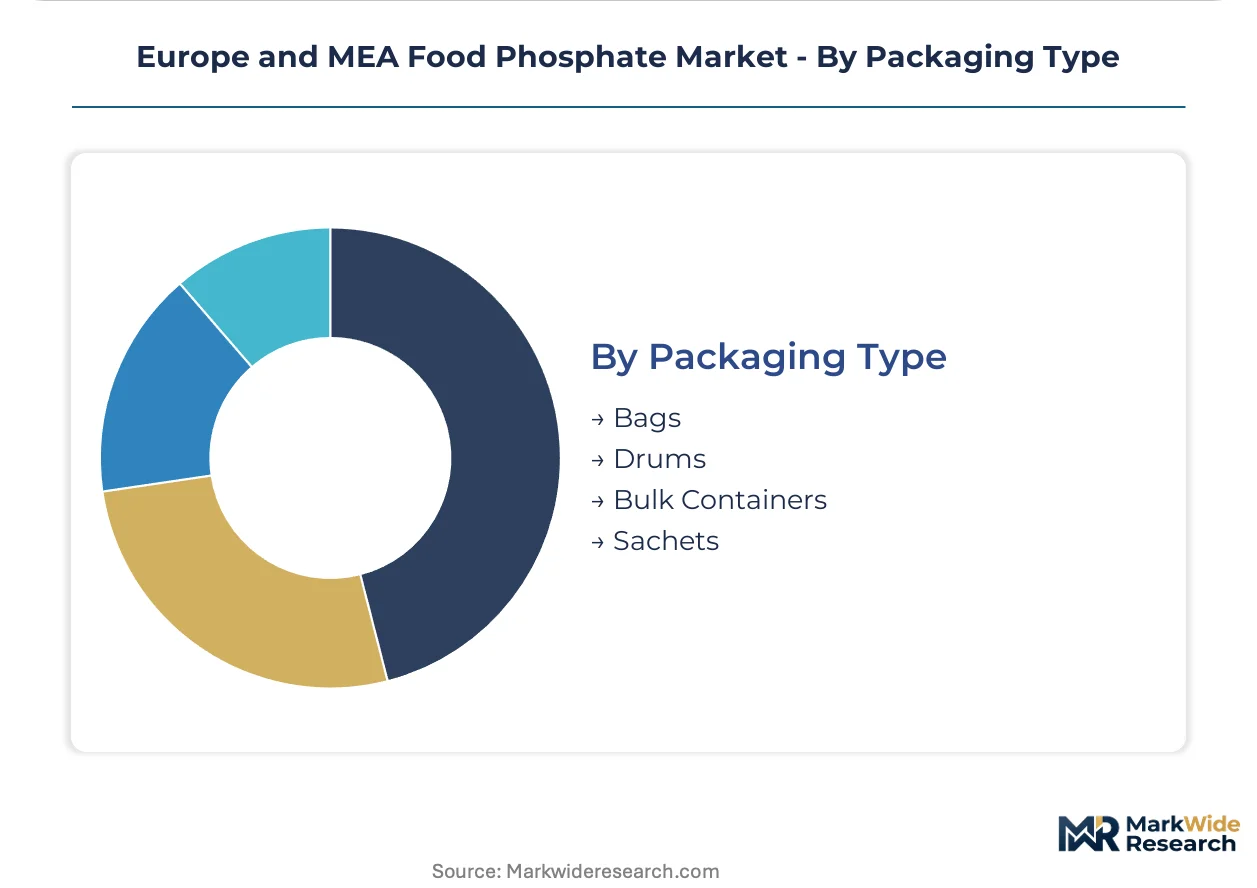
Packaging Type:
Packaging configuration reflects supply chain distance and contamination risk tolerance across direct manufacturer relationships versus distributor channels.
- Bulk Containers:Intermediate bulk containers and tanker deliveries for high-volume dairy and meat processors with dedicated unloading infrastructure. German and French industrial users favor this format for sodium phosphate procurement.
- Drums:Steel and fiber drums for mid-scale compounders requiring lot traceability and moisture protection. Italian bakery ingredient distributors stock multiple phosphate grades in this format.
- Bags:Multi-layer paper and polyethylene sacks for standard-grade leavening phosphates. UAE and Saudi importers specify palletized bag shipments for warehouse efficiency.
- Sachets:Pre-weighed unit doses for small-batch nutraceutical and specialty food manufacturers. Swiss and Dutch precision compounders pay premiums for contamination-controlled packaging.
Volume leader: Bulk Containers. Gaining share fastest: Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphate rock extraction concentrates in Morocco and Jordan while consumption clusters in German meat processing and Saudi dairy manufacturing. This geographic asymmetry shapes trade flows and regulatory compliance burdens across the Europe and MEA corridor.
Germany
Cured meat manufacturers in Lower Saxony and Bavaria drive sodium phosphate consumption for moisture retention in emulsified products. REACH substance restrictions force reformulation trials with reduced phosphorus loading. The Ruhr industrial cluster hosts technical service centers supporting phosphate requalification documentation for dairy compounders.
France
Infant nutrition formulators in Île-de-France specify encapsulated tricalcium phosphate for calcium bioavailability claims without sensory compromise. EFSA maximum level guidelines for phosphorus additives directly influence formulation decisions by Paris-region processors. Lyon-based dairy compounders scale fortified yogurt lines ahead of EU Green Deal sourcing audits.
Italy
Industrial bakers in Lombardy and Emilia-Romagna maintain monocalcium phosphate volumes for chemical leavening despite margin compression. EMA food additive evaluation protocols extend product requalification timelines for reformulated phosphate grades. Bologna processing clusters face equipment retrofit costs for tricalcium phosphate substitution in legacy production lines.
Saudi Arabia
Dairy and bakery sectors in Riyadh and Jeddah scale phosphate-enhanced formulations faster than domestic supply capacity. SFDA import specifications create first-mover advantages for suppliers who pre-qualify technical grades before Gulf Cooperation Council harmonization completes. The Eastern Province industrial corridor concentrates meat processing expansion with phosphate-dependent shelf-life extension.
United Arab Emirates
Dubai and Abu Dhabi procurement teams consolidate vendor panels to reduce qualification burden and secure volume commitments for fortified dairy applications. MOHAP regulations intersect with emerging national standards as the Emirates develop independent food chemical regulatory capacities. Sharjah distribution hubs manage palletized bag shipments for warehouse efficiency in phosphate procurement.
Europe and MEA Food Phosphate Market Vendor Landscape
The competitive structure tilts toward integrated mining operators with captive phosphate rock assets and downstream purification capabilities. Specialist blenders serving bakery and dairy segments occupy mid-tier positions with technical service differentiation. Three archetypes dominate: backward-integrated resource owners, application-focused compounders, and regional distribution intermediaries. Capacity expansion in Gulf markets and portfolio diversification toward encapsulation technologies represent the dominant competitive moves.
Among Israel-based integrated operators, ICL Group Ltd. exemplifies the resource-backed archetype with mining-to-purification control. German specialist Budenheim KG occupies a position within the application-focused tier serving bakery and dairy processors. Belgian technical phosphate producer Prayon S.A. anchors the compliance-driven segment addressing EFSA purity benchmarks. These three represent distinct strategic postures without implying specific market share or operational claims.
| Leading Market Players |
|---|
| ICL Group Ltd. |
| Innophos Holdings, Inc. |
| Budenheim KG |
| Prayon S.A. |
| Groupe OCP |
| Nutrien Ltd. |
| The Mosaic Company |
| Yara International ASA |
| EuroChem Group AG |
| Others |
Supply Flow & Price Mechanics
Phosphate rock benchmark indices from Morocco and Jordan set the cost floor for downstream food-grade purification, cascading through contract tiers that separate integrated miners from specialty blenders dependent on merchant feedstock. EFSA purity thresholds and REACH registration burdens amplify price spreads between technical-grade compounders and commodity distributors serving European meat processors.
Pricing Analysis
Yield-guaranteed moisture retention in German cured meats anchors value-based pricing for sodium phosphate variants, with EFSA-compliant grades commanding premiums over standard technical specifications. Certification tier—EMA food additive approval versus provisional REACH registration—drives price differentiation alongside volume scale and geographic delivery radius. Cost compression in standard-grade leavening phosphates intensifies as Italian bakers consolidate procurement around fewer suppliers. Small-scale nutraceutical compounders in Switzerland exhibit highest price sensitivity, while Saudi dairy integrators prioritize supply security over unit cost.
Supply Chain Analysis
EMA food additive qualification and Saudi SFDA pre-certification gate market access, extending lead times for non-integrated suppliers lacking captive phosphate rock assets. Production concentrates in Morocco, Jordan, and Israel for upstream extraction, with downstream purification clustering in Germany, Belgium, and the Netherlands. Merchant supply of phosphoric acid feedstock, specialized purification equipment, and analytical chemistry talent feeds into finished phosphate manufacturing. Single-source vulnerability in phosphate rock concentrate exposes European processors to export quota disruptions. Distribution runs through direct supplier relationships with Dubai and Riyadh compounders, displacing traditional multi-brand distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphate rock mining capacity constraints in Morocco and Jordan prop pricing power for backward-integrated operators, creating a supply-constrained market structure favoring resource owners over specialty blenders.
For Market Incumbents: Lock in long-term offtake agreements with Saudi and UAE dairy compounders before Gulf Cooperation Council harmonization completes, securing volume commitments that preempt competitor entry. Deepen captive mining positions in Jordanian phosphate rock deposits to reduce feedstock cost volatility threatening margin stability. Accelerate encapsulation technology R&D to defend premium positioning against uncoated tricalcium phosphate commoditization.
For New Entrants and Emerging Players: Launch via direct technical service partnerships with Sharjah and Dubai distribution hubs, bypassing established European distributor networks. Target UAE fortified dairy segment penetration where domestic supply capacity lags demand growth, offering pre-qualified phosphate grades ahead of incumbent requalification cycles. Emphasize pediatric and geriatric nutrition applications for controlled-release encapsulation systems with limited competitive saturation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European specialty phosphate blenders facing REACH compliance cost pressures in Germany and Italy, with acquisition multiples compressed by regulatory uncertainty. Five-to-ten year viability hinges on successful pivot toward encapsulation technologies and Gulf market qualification. Monitor Saudi SFDA technical grade approval timelines as inflection signal for first-mover advantage realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | Captive Moroccan and Jordanian feedstock secures supply continuity against export quota volatility. |
| Encapsulation Technology Development | Controlled-release tricalcium phosphate systems command premium positioning in Swiss infant nutrition. |
| Gulf Market Pre-Certification Investment | Saudi SFDA technical grade approval creates first-mover advantage before GCC harmonization finalizes. |
| Direct Supplier Relationship Consolidation | Dubai and Riyadh procurement teams prioritize technical service proximity over distributor breadth. |
| Clean-Label Fortification Portfolio Expansion | Tricalcium phosphate demand accelerates across UAE and Saudi dairy clean-label repositioning. |
Methodological Framework
Multi-period observation of EFSA phosphorus additive maximum levels, REACH substance restriction timelines, and Saudi SFDA import specification evolution anchored the trend analysis, supplemented by interviews with phosphate plant managers, dairy compounder procurement leads, bakery technical directors, and EMA regulatory affairs specialists. Secondary validation drew from ECHA substance evaluation databases, EU Green Deal policy documentation, Gulf Cooperation Council harmonization protocols, and customs trade flow records. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verification of volume and value estimates.
Segment-weighting across product type, end user, application, and packaging format dimensions structured the analytical framework, with CAGRs derived from elasticity-adjusted demand projections and capacity expansion schedules throughout the forecast period. Food-grade phosphate purity certification tiers, EMA evaluation protocol completion rates, and encapsulation technology adoption curves informed industry-specific forecast inputs.
Regulatory tightening velocity, phosphate rock export quota disruptions, and Gulf market qualification timeline delays are the dominant revision risks warranting model sensitivity testing. A model refresh is warranted upon material change in EFSA phosphorus additive maximum level guidelines or Saudi SFDA technical grade approval thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
Astaxanthin Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Food-Grade Monopotassium Phosphate Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Linoleic Acid Market