
 Food Grade Xanthan Gum Market | 2026-2036
Food Grade Xanthan Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Xanthan Gum Market Analytics
Premiumization is shifting away from commodity-grade xanthan gum as clean-label and organic certifications command widening price spreads. CP Kelco leverages its marine biotechnology heritage to dominate high-purity segments for sauces and dressings. Fufeng Group anchors volume supply through integrated fermentation complexes in Shandong Province. Jungbunzlauer Suisse AG differentiates via specialized powder grades targeting European bakery applications.
Food grade xanthan gum is a high-molecular-weight extracellular polysaccharide produced by Xanthomonas campestris fermentation, yielding a β-1,4-linked glucose backbone with trisaccharide side chains that confer shear-thinning rheology and salt-pH stability across food matrices. Powder formulations retain the largest share of food manufacturing procurement due to extended shelf stability and precise dosing in automated bakery lines, while liquid concentrates gain traction among restaurant and institutional kitchens seeking reduced dust exposure and faster hydration. Dairy applications represent the fastest-expanding segment as plant-based milk alternatives require xanthan gum for suspension of proteins and lipids in low-acid systems.
FDA food additive regulations under 21 CFR 172.695 govern xanthan gum purity and microbial limits in United States commerce, while EFSA's re-evaluation of E415 under EU Regulation 231/2012 tightens residual solvent thresholds. China's National Health Commission periodically revises GB 1886.41 standards for fermentation-derived food additives. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and supply chain disruptions as certification requirements fragment.
Market Dynamics
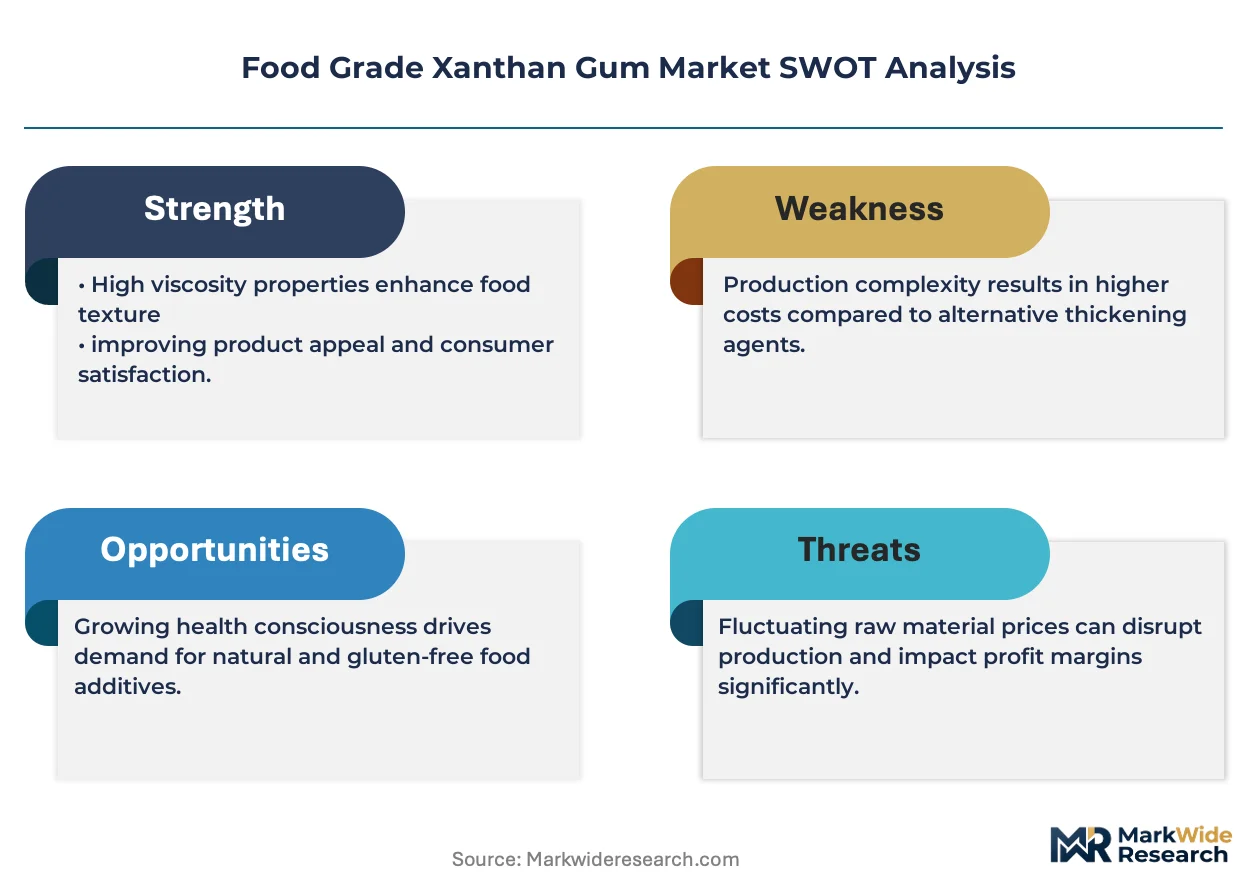
Fermentation capacity concentration in Shandong Province creates asymmetric supply power, while clean-label certification requirements fragment demand tiers and widen price spreads between commodity and premium grades.
Growth Catalysts
- Clean-label formulation mandates:EFSA's tightened E415 purity thresholds under EU Regulation 231/2012 accelerate processor migration toward non-GMO and organic-certified xanthan gum grades.
- Plant-based dairy expansion:Low-acid suspension requirements in oat and almond milk alternatives pull xanthan gum into protein-lipid stabilization matrices at industrial scale.
- Fermentation biotechnology advances:Strain optimization and continuous culture systems reduce batch-to-batch viscosity variation, improving downstream processing economics.
Market Restraints
- Feedstock cost volatility:Corn syrup and soy peptone prices fluctuate with agricultural commodity cycles, compressing margins for non-integrated producers.
- Supply concentration risk:Shandong Province fermentation clusters control disproportionate global volume, exposing buyers to regional logistics disruptions or export policy shifts.
- Regulatory divergence friction:FDA 21 CFR 172.695, EFSA E415 re-evaluations, and China's GB 1886.41 revisions create compliance fragmentation requiring parallel certification tracks.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and South Africa food processing sectors lack local xanthan gum supply infrastructure, creating import substitution openings for established exporters.
- Precision fermentation platforms:Cell-free enzymatic synthesis converging with traditional bioreactor methods promises cleaner label claims and reduced allergen cross-contamination risk.
- Direct-to-foodservice distribution:Liquid concentrate formats bypass traditional ingredient distributor markups by selling hydration-ready solutions to restaurant chains and institutional kitchens.
Industry Challenges
- Fermentation expertise scarcity:Xanthomonas campestris strain management and rheology control require specialized microbiologists that food ingredient companies compete for against pharmaceutical biotech firms.
- Clean-label certification timelines:Non-GMO Project and organic audits extend qualification cycles, delaying new supplier onboarding and locking incumbent relationships.
- Legacy equipment incompatibility:Powder-to-liquid format transitions demand capital retrofitting of dosing and mixing infrastructure at mid-sized bakery and sauce manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Xanthan Gum Market |
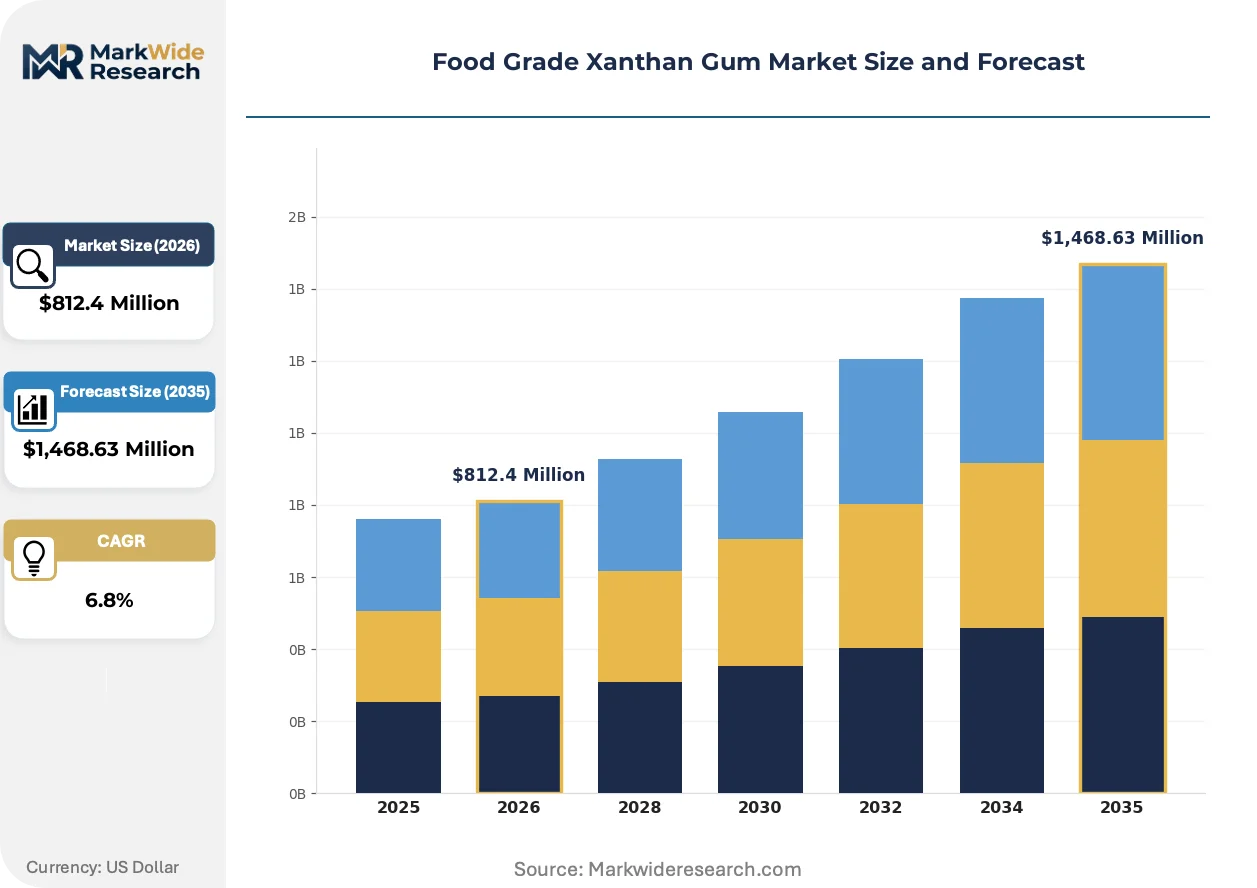
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,468.63 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Gel, Granule Application: Baking, Sauces, Dressings, Dairy Products End User: Food Manufacturers, Restaurants, Retailers, Packagers Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Archer Daniels Midland, Solvay, CP Kelco, Deosen Biochemical, Ingredion Incorporated, Tate & Lyle, Cargill, Jungbunzlauer Suisse AG, Fufeng Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Xanthan Gum Market Evolving Landscape
Biotechnology refinement and regulatory recalibration are compressing traditional grade boundaries while reshaping how manufacturers qualify and procure hydrocolloid stabilizers.
Continuous fermentation monitoring using inline viscometry and dissolved oxygen sensors is converging with automated harvest scheduling to reduce batch failure rates and improve yield consistency. Mid-cap sauce manufacturers in the United States adopt these systems fastest, attracted by reduced quality deviation penalties from retail customers. The technology is converging with predictive maintenance platforms to compress unplanned downtime and extend campaign lengths between sterilization cycles.
EFSA's 2023 E415 re-evaluation under EU Regulation 231/2012 tightened residual solvent limits and mandated updated toxicological dossiers for existing food additive approvals. European bakery and dressing manufacturers now face reformulation costs or supplier switching to meet the new purity certificates. German and French food processors are responding by consolidating supplier bases toward vertically integrated fermentation houses with captive analytical laboratories.
Ingredient buying committees at multinational food manufacturers now require sustainability scorecards alongside technical specifications, weighting carbon intensity and water stewardship in procurement decisions. Traditional distributor relationships face disintermediation pressure as direct sourcing from Shandong fermentation complexes offers traceability documentation and price transparency. This pattern concentrates most visibly in Scandinavian and Benelux markets where retailer ESG mandates cascade backward through supply chains.
Food Grade Xanthan Gum Market Segmentation
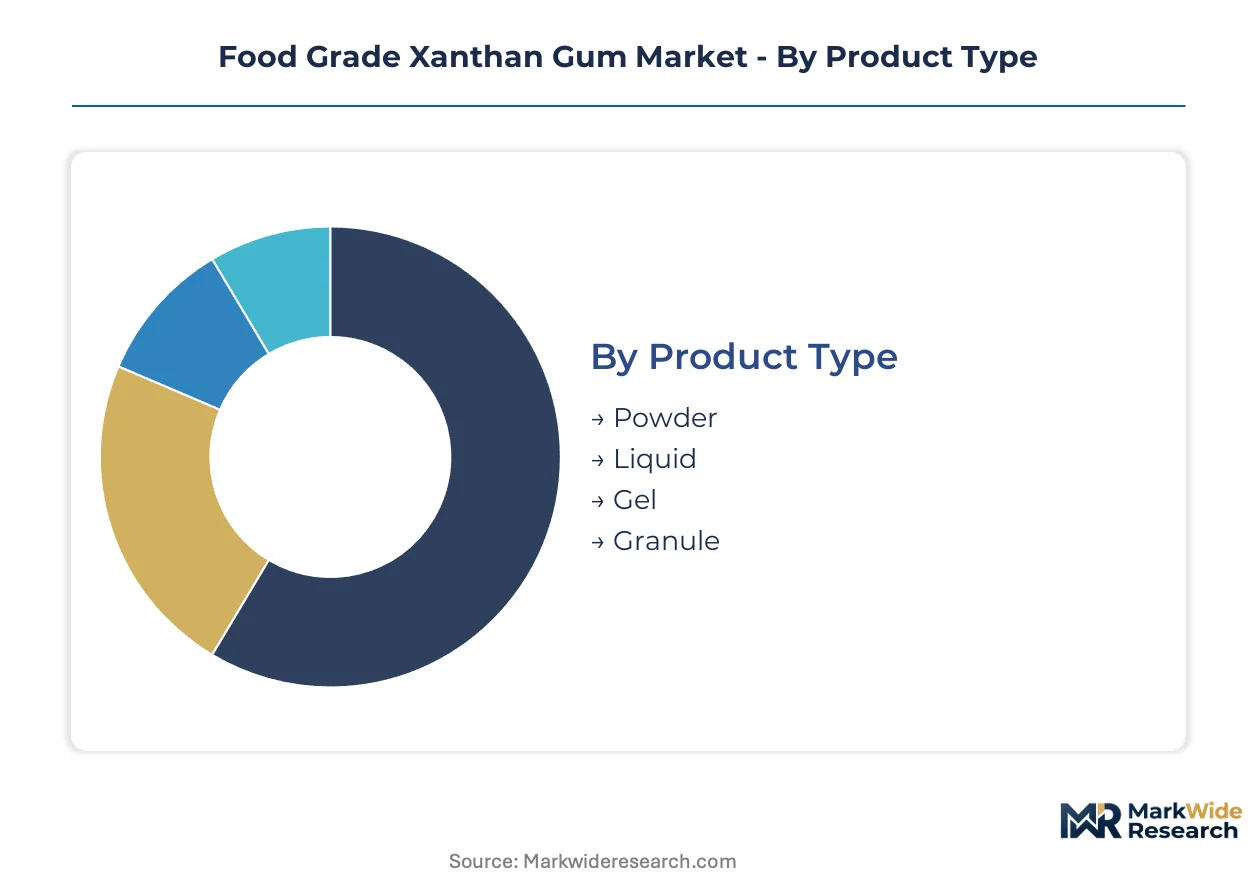
Segmentation in food grade xanthan gum reveals how formulation requirements, procurement scale, and regulatory exposure fragment purchasing behavior across the value chain. Manufacturers configure production campaigns around these divides to optimize fermentation yield against certification premiums.
Product Type:
Powder and liquid formats demand divergent capital deployment, with spray-drying towers and aseptic filling lines representing distinct investment thresholds that shape supplier specialization.
- Powder:Spray-dried particulate with controlled particle size distribution enables precise volumetric dosing in automated bakery and sauce lines. Extended shelf stability and low moisture activity make this the default procurement choice for industrial-scale food manufacturers in Shandong Province's processing corridor.
- Liquid:Pre-hydrated colloidal suspensions eliminate dust exposure and reduce mixing time for restaurant and institutional kitchen operators. Demand concentrates among foodservice chains seeking labor efficiency and faster batch turnaround in high-throughput sauce preparation.
- Gel:High-viscosity semisolid concentrates target specialty dressing manufacturers requiring immediate thickening without hydration lag.
- Granule:Agglomerated particles improve dispersibility in cold-water systems for small-batch bakery operations lacking high-shear mixing equipment.
Powder absorbs the bulk of installed capacity; liquid is expanding most quickly.
Application:
End-use rheology requirements determine fermentation strain selection and downstream purification intensity, with dairy applications imposing the most stringent low-acid stability specifications.
- Baking:Dough conditioning and moisture retention in industrial bread lines exploit xanthan gum's shear-thinning behavior during high-speed mixing. European artisan bakeries increasingly specify organic-certified grades to meet retailer clean-label mandates under EFSA's tightened E415 thresholds.
- Dairy Products:Protein-lipid suspension in oat and almond milk alternatives requires salt-stable viscosity across pH ranges that defeat other hydrocolloids. Plant-based dairy processors in Germany and France drive qualification of non-GMO grades for private-label retail contracts.
- Sauces:Emulsion stabilization and pour viscosity control dominate tomato-based and oil-in-water systems for retail and foodservice channels.
- Dressings:Cold-process mayonnaise and vinaigrette formulations leverage xanthan gum's acid tolerance to maintain shelf-stable texture without heat treatment.
Baking commands the largest share of current volume; dairy products are climbing the fastest.
End User:
Procurement scale and technical sophistication create three distinct customer tiers with diverging specification complexity and price sensitivity profiles.
- Food Manufacturers:Industrial processors with captive R&D laboratories negotiate long-term contracts tied to fermentation campaign scheduling and custom viscosity targets. These buyers dominate volume procurement and drive strain optimization investments by suppliers.
- Restaurants:Chain operators and institutional kitchens prioritize liquid concentrates and pre-blended stabilizer systems to minimize kitchen labor and equipment requirements.
- Retailers:Private-label brand owners specify certification tiers to meet shelf-positioning strategies, with organic and non-GMO claims commanding supplier qualification premiums.
- Packagers:Co-manufacturing facilities serving multiple brand owners require flexible formulation services and rapid batch documentation for regulatory compliance across jurisdictions.
Food manufacturers lock in the majority of fermentation output; retailers are gaining share fastest through private-label expansion.
Distribution Channel:
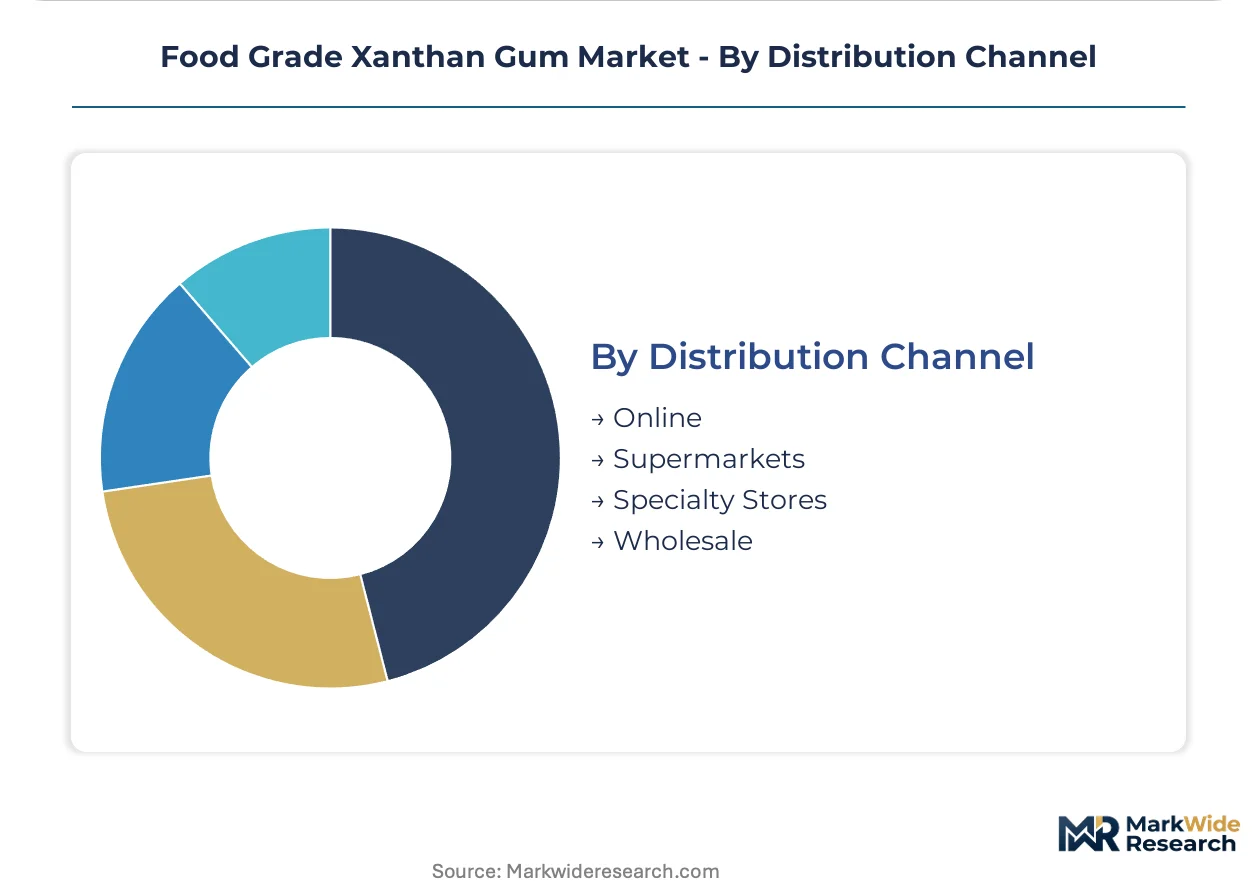
Channel selection reflects buyer scale, technical support requirements, and traceability documentation needs rather than simple price optimization.
- Wholesale:Ingredient distributors with technical sales staff serve mid-cap food manufacturers requiring formulation guidance and just-in-time delivery scheduling.
- Online:E-procurement platforms disintermediate traditional distribution for standardized powder grades, particularly among small bakery operations and startup food brands.
- Supermarkets:Limited retail pack sizes target home bakers and small commercial kitchens with consumer-oriented labeling and usage instructions.
- Specialty Stores:Organic and natural products retailers stock certified grades with full supply chain documentation for clean-label conscious buyers.
Wholesale retains the dominant channel position; online is expanding most quickly among emerging food brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province anchors fermentation capacity for food grade xanthan gum, with industrial clusters in Weifang and Dezhou supplying processors across Asia and export markets. Demand patterns diverge sharply between mature regulatory jurisdictions tightening purity standards and emerging markets building first-generation food manufacturing infrastructure.
China
Shandong Province fermentation complexes in Weifang and Dezhou generate the majority of global food grade xanthan gum volume, serving both domestic sauce manufacturers and export customers. The National Health Commission periodically revises GB 1886.41 standards for fermentation-derived food additives, tightening microbial limits and residual solvent thresholds. Integrated producers in Shandong leverage captive corn syrup supply and in-house analytical laboratories to maintain cost positions while qualifying for international certification tiers.
United States
Plant-based dairy processors in California and the Midwest drive qualification of non-GMO xanthan gum grades for oat and almond milk stabilization. FDA regulations under 21 CFR 172.695 govern purity specifications and microbial limits, with recent enforcement attention to allergen cross-contamination documentation. Chicago and Minneapolis ingredient distributors maintain regional warehousing for just-in-time delivery to mid-cap sauce and dressing manufacturers.
Germany
European bakery and dressing manufacturers face reformulation costs from EFSA's 2023 E415 re-evaluation under EU Regulation 231/2012, which tightened residual solvent limits. Cologne and Hamburg food processors consolidate supplier bases toward fermentation houses with captive analytical capabilities and organic certification. Private-label retail contracts increasingly mandate sustainability scorecards weighting carbon intensity in procurement decisions.
Brazil
São Paulo and Minas Gerais food processors rely on imported xanthan gum for sauce and dressing production, with limited domestic fermentation infrastructure. ANVISA regulates food additive purity under Resolução da Diretoria Colegiada standards, creating parallel certification requirements for international suppliers. Local distributors in the Southeast region provide technical sales support and formulation guidance to mid-cap manufacturers lacking captive R&D laboratories.
India
Maharashtra and Gujarat food manufacturers adopt xanthan gum for industrial bread and sauce applications as organized retail expands private-label offerings. FSSAI standards under the Food Safety and Standards Act govern additive specifications, with periodic alignment to Codex Alimentarius thresholds. Mumbai and Ahmedabad ingredient distributors serve growing demand from quick-service restaurant chains and institutional kitchen operators seeking pre-hydrated liquid concentrates.
Food Grade Xanthan Gum Market Competitive Landscape
Capital-heavy fermentation operators compete with asset-light formulation specialists across tiered supply relationships. Three to five integrated producers control bulk volume through captive bioreactor capacity, while mid-scale processors rely on toll manufacturing and distributor networks. Strategic archetypes separate into Shandong-based fermentation houses with upstream corn processing, European specialists in certified organic grades, and multinational ingredient distributors with technical service capabilities. Dominant competitive moves center on backward integration into corn syrup supply and geographic expansion into underpenetrated African and Southeast Asian markets.
Within the integrated fermentation tier, Fufeng Group and Deosen Biochemical exemplify Shandong-based producers leveraging captive supply chains and scale economics. CP Kelco occupies a position among biotechnology-heritage specialists targeting high-purity segments for clean-label applications. Among Swiss and European certified-grade providers, Jungbunzlauer Suisse AG represents the archetype of regional specialists with organic and non-GMO qualification capabilities serving EFSA-regulated markets.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Solvay |
| CP Kelco |
| Deosen Biochemical |
| Ingredion Incorporated |
| Tate & Lyle |
| Cargill |
| Jungbunzlauer Suisse AG |
| Fufeng Group |
| Others |
Value Network & Pricing Analysis
Continuous fermentation monitoring systems with inline viscometry are compressing batch-to-batch viscosity variation and reshaping cost economics at Shandong Province complexes, simultaneously concentrating supply power among integrated operators capable of deploying this capital-intensive infrastructure while fragmenting pricing tiers between precision-capable and commodity-grade suppliers.
Pricing Analysis
Yield-guarantee contracts tied to viscosity consistency and hydration performance anchor value-based pricing for industrial food manufacturers running automated bakery lines. Three-tier pricing structure across organic-certified, non-GMO, and commodity grades widens spreads as EFSA's tightened E415 thresholds under EU Regulation 231/2012 force reformulation investments. Price erosion runs through standard-grade powder as Shandong fermentation houses expand capacity and compress spot-market premiums. Small-batch bakery operations lacking high-shear mixing equipment exhibit highest price sensitivity, while multinational sauce manufacturers with captive R&D laboratories absorb certification premiums for supply security.
Supply Chain Analysis
Corn syrup supply rests on North American and Chinese agricultural processors, while soy peptone draws from fermentation media specialists in Germany and Japan. Shandong Province, the United States Corn Belt, and Brazilian soy processing regions anchor geographic concentration of critical inputs. Single-source vulnerability concentrates in Shandong's Weifang and Dezhou fermentation clusters, where export policy shifts or regional logistics disruptions cascade through global supply. Distribution runs through ingredient distributors with technical sales capabilities serving mid-cap food manufacturers, alongside direct procurement relationships between integrated fermentation houses and multinational processors seeking traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EFSA's 2023 E415 re-evaluation under EU Regulation 231/2012 erected a barrier-to-entry moat favoring fermentation houses with captive analytical laboratories and organic certification capabilities.
For Market Incumbents: Lock in strain optimization partnerships with biotechnology firms to defend viscosity consistency premiums against precision fermentation entrants. Capture backward integration into corn syrup supply through offtake agreements with North American agricultural processors, insulating margin positions from commodity price cycles that compress non-integrated competitors.
For New Entrants and Emerging Players: E-procurement platforms targeting small-batch bakery operations and startup food brands offer the most penetrable route, bypassing technical sales requirements that favor established distributor relationships. White-space concentrates in African import substitution markets where Nigeria and South Africa lack local fermentation infrastructure, and in liquid concentrate formats for foodservice chains seeking labor efficiency.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational ingredient distributors seeking captive fermentation capacity and clean-label certification capabilities. Long-term viability favors vertically integrated Shandong-based operators with upstream corn processing and downstream analytical services. Watch EFSA enforcement patterns on residual solvent documentation as the inflection signal for supplier consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Syrup Supply | Captive agricultural input sourcing insulates margin compression from commodity volatility cycles. |
| Organic and Non-GMO Certification Investment | EFSA's tightened E415 thresholds under EU Regulation 231/2012 lock in premium pricing tiers. |
| Precision Fermentation Platform Development | Cell-free enzymatic synthesis promises cleaner label claims and reduced allergen cross-contamination risk. |
| Direct-to-Foodservice Liquid Concentrate Launch | Bypasses traditional ingredient distributor markups by selling hydration-ready solutions to restaurant chains. |
| African Market Distribution Partnership | Nigeria and South Africa import substitution openings address underpenetrated demand lacking local supply infrastructure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across fermentation plant managers, procurement leads at sauce and dairy processors, distribution channel partners, and technical R&D directors at hydrocolloid specialists. FDA 21 CFR 172.695 submissions, EFSA E415 re-evaluation dossiers, China's GB 1886.41 standards revisions, and import-export statistics from Shandong Province customs authorities supplied quantitative foundations. Bottom-up fermentation capacity modeling and top-down food additive demand estimation were triangulated against industry stakeholder validation.
Data-stream reconciliation across powder and liquid format shipments, organic certification volumes, and end-use application splits generated consistent segmentation outputs across the projection horizon. Modeled dimensions included product type, application, end-user procurement tier, and distribution channel, with strain-specific viscosity performance as an industry-specific overlay. CAGRs were derived from trend extrapolation of clean-label certification adoption rates and plant-based dairy formulation penetration, calibrated against Shandong Province capacity expansion announcements and EFSA enforcement timelines.
Inputs from customs authorities and trade associations were available through the study window; gaps in private-label contract terms and toll manufacturing arrangements introduce uncertainty bands around foodservice channel estimates. Forecasts reflect assumptions on EFSA enforcement consistency, corn syrup price stability, and precision fermentation technology maturation. A small set of named triggers—regulatory divergence between FDA and EFSA thresholds, Shandong Province export policy shifts, and precision fermentation commercialization timelines—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Coating Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market
Food Components and Additives
Food Antioxidant Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Edible Films and Coating Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Astaxanthin Market
Food Components and Additives
Horseradish Peroxidase Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Europe Food Premix Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
Food Antimicrobial Coating Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
Brazil Food Hydrocolloids Market