
 Polyunsaturated Fatty Acids Market | 2026-2036
Polyunsaturated Fatty Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Polyunsaturated Fatty Acids Market Analytics
Multi-source procurement of omega-3 and omega-6 feedstocks is restructuring supply economics for finished PUFA producers. BASF SE leverages backward integration into marine and plant-based raw material streams to sustain margin stability across volatile fish oil cycles. Cargill Incorporated anchors North American oilseed crushing capacity, while Koninklijke DSM N.V. competes through synthetic biology platforms that reduce harvest-season dependency.
Polyunsaturated fatty acids are long-chain hydrocarbons containing two or more carbon-carbon double bonds, typically extracted via cold-pressing, molecular distillation, or enzymatic interesterification, and function primarily as structural lipid precursors for cell membranes and eicosanoid synthesis in nutraceutical and pharmaceutical applications. Omega-3 concentrates command premium positioning in cardiovascular and cognitive health formulations, while algal oil sources represent the fastest-expanding origin category as brands seek to decouple from wild-catch fisheries. Softgel capsules dominate pharmaceutical and dietary supplement delivery, though powdered supplements gain traction in functional food integration where thermal stability and shelf-life extension matter.
EFSA governs health claim substantiation for PUFAs marketed in Europe, while FDA regulates structure-function claims and new dietary ingredient notifications in the United States, and China's NMPA and SAMR jointly oversee functional food and pharmaceutical lipid registrations. These frameworks elevate barriers for unvalidated entrants and redirect R&D spending toward clinical trial infrastructure. Stakeholders must weigh algal oil capital commitments against the regulatory lag in novel source approvals across major jurisdictions.
Market Dynamics
Algal oil fermentation capacity expansion is fragmenting omega-3 supply concentration away from Peruvian anchovy fisheries, forcing finished goods manufacturers to requalify raw material streams under divergent Novel Food and GRAS notification pathways.
Growth Catalysts
- EFSA Article 13.1 health claims framework:Validated cardiovascular and cognitive function claims accelerate premium positioning for EPA/DHA concentrates in European dietary supplements and medical foods.
- China's dual carbon policy alignment:Domestic algal oil producers secure preferential financing and grid access, compressing unit costs against imported fish oil equivalents.
- Precision fermentation platforms:Synthetic biology-derived omega-3 strains achieve titers exceeding 15 grams per liter, reducing harvest-season dependency and stabilizing input pricing for contract manufacturers.
Market Restraints
- Fish oil input volatility:El Niño-Southern Oscillation events compress Peruvian anchovy catch quotas, spiking crude oil prices and compressing gross margins for non-integrated refiners.
- Novel Food approval timelines:EFSA's 12-18 month safety evaluation window for new PUFA sources delays product launches and traps capital in pre-revenue fermentation assets.
- Plant-based omega-3 substitution:ALA-rich chia and flaxseed oils capture price-sensitive functional food applications, displacing DHA/EPA in bakery and beverage fortification.
Strategic Opportunities
- Infant formula premiumization in Southeast Asia:DHA fortification mandates in Vietnam and Indonesia create pull-through for algal oil suppliers with halal certification and traceability documentation.
- Cell-cultured seafood lipid partnerships:Cultivated salmon and tuna producers require exogenous DHA/EPA inputs, opening long-term offtake contracts for fermentation-derived concentrates.
- USDA BioPreferred procurement preferences:Federal purchasing guidelines for biobased products create channel access for domestic algal oil processors in institutional nutrition programs.
Industry Challenges
- Chromatographic purification expertise scarcity:Fewer than twenty contract manufacturers globally operate preparative-scale supercritical fluid chromatography for EPA/DHA enrichment, creating bottlenecks for high-concentrate pharmaceutical-grade output.
- Multi-jurisdiction dossier harmonization:Divergent oxidative stability testing protocols between FDA, EFSA, and NMPA force redundant analytical spending and extend registration timelines for global product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyunsaturated Fatty Acids Market |
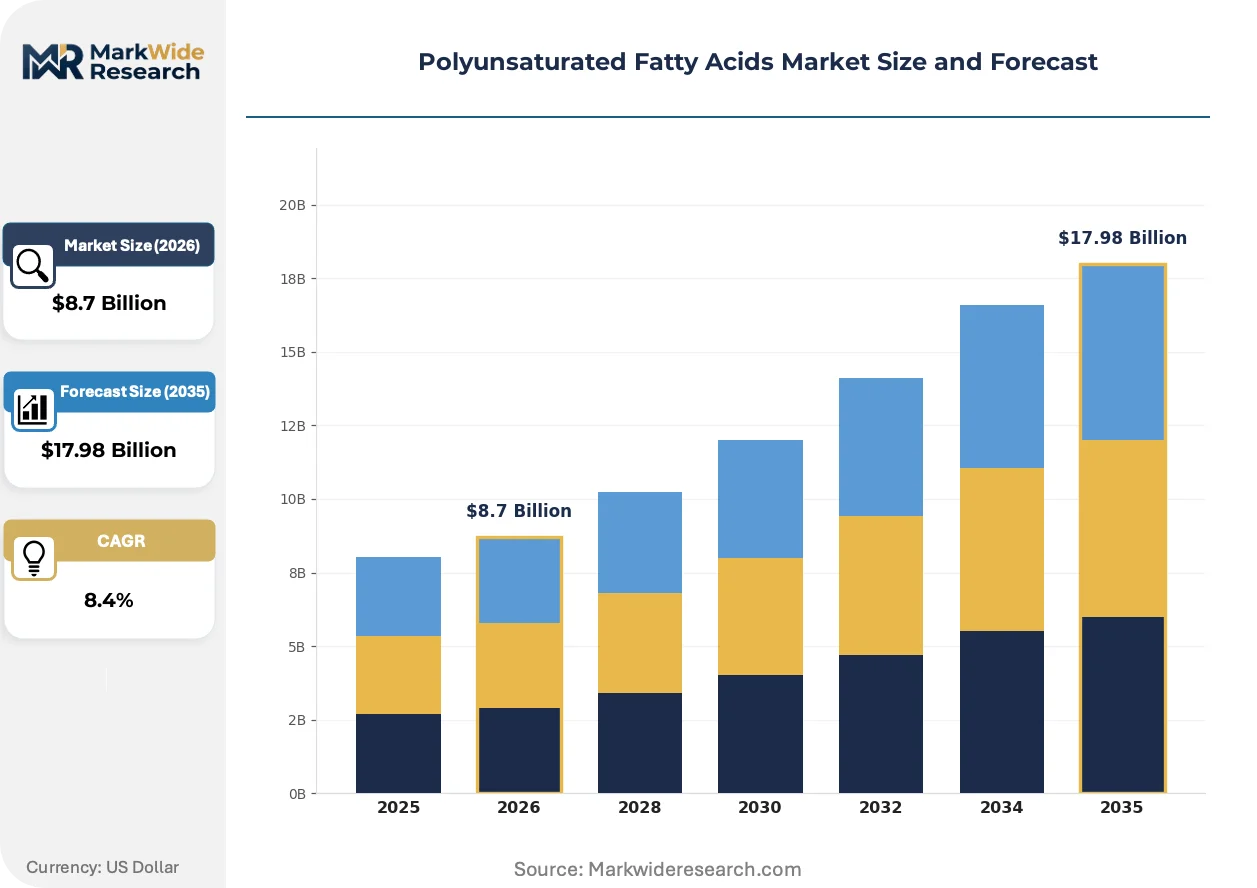
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Omega-3, Omega-6, Alpha-Linolenic Acid, Linoleic Acid End Use Industry: Food & Beverages, Pharmaceuticals, Personal Care, Dietary Supplements Form: Liquid Oils, Softgel Capsules, Powdered Supplements, Emulsions Source: Plant-based, Fish Oil, Algal Oil, Krill Oil |
| Companies Covered | BASF SE, Cargill Incorporated, Koninklijke DSM N.V., Croda International PLC, FMC Corporation, Aker BioMarine AS, Omega Protein Corporation, Polaris Nutritional Lipids, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyunsaturated Fatty Acids Market Evolving Landscape
Bioprocess intensification and regulatory data digitization are compressing development cycles for novel PUFA sources while reshaping how manufacturers demonstrate quality equivalence across marine and fermentation origins.
Continuous fermentation with cell retention is modularizing algal oil production economics. Pharmaceutical-grade DHA manufacturers deploy perfusion bioreactors achieving steady-state operation beyond 60 days. This architecture collapses batch-to-batch variability and enables geographic distribution of production assets closer to formulation customers.
REACH Annex XVII restrictions on persistent organic pollutants in marine lipids tighten testing burdens for fish oil importers into the European Union. Laboratories must demonstrate sub-ppb levels of dioxins and PCBs across every catch season. Concentrate producers respond by accelerating algal oil substitution in premium supplement lines to bypass contamination risk entirely.
Direct-to-practitioner distribution is displacing mass retail for clinical omega-3 formulations. Functional medicine clinics and registered dietitians prescribe condition-specific EPA/DHA ratios, bypassing pharmacy and grocery channels. This pattern concentrates in the United States and Australia where practitioner-only brands build recurring revenue through patient monitoring protocols and subscription replenishment.
Polyunsaturated Fatty Acids Market Segmentation
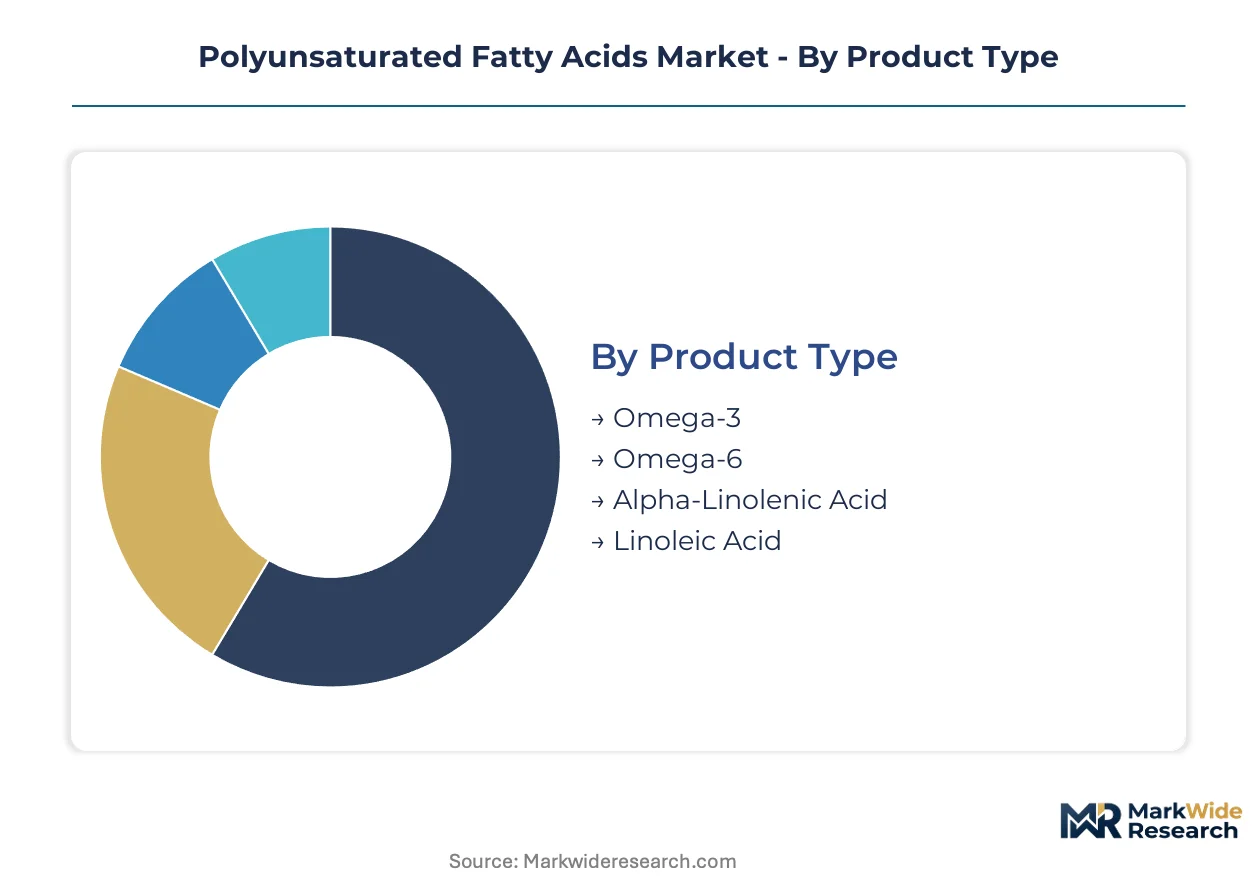
PUFA manufacturers configure production assets around distinct specification tiers that separate pharmaceutical-grade concentrates from commodity food-grade oils. Segmentation discipline determines margin capture and regulatory pathway complexity across marine, plant, and fermentation-derived feedstocks.
Product Type:
Standardization dominates at the commodity end with basic ALA and linoleic acid specifications, while EPA and DHA concentrates demand customized molecular distillation protocols and oxidative stability guarantees.
- Omega-3:EPA and DHA concentrates extracted via molecular distillation or supercritical CO2 fractionation achieve 85%+ purity for cardiovascular therapeutic applications. Demand concentrates in pharmaceutical softgel formulations where EFSA-validated health claims support premium positioning against generic fish oil alternatives.
- Omega-6:Arachidonic acid and gamma-linolenic acid serve as structural precursors for eicosanoid synthesis in infant nutrition and inflammatory condition management. ARA fortification mandates in China and Southeast Asian infant formula markets sustain volume throughput for fermentation-derived sources.
- Alpha-Linolenic Acid:Plant-sourced C18:3 omega-3 from flaxseed and chia functions as a cost-efficient bulk lipid for functional food fortification where conversion efficiency to EPA/DHA remains secondary to label claims.
- Linoleic Acid:Corn and sunflower oil derivatives supply essential fatty acid baseline nutrition in mass-market edible oils and animal feed formulations.
Most installed capacity flows through Omega-6 for feed and food oil applications. Expansion is steepest in Omega-3 concentrates for prescription medical foods and high-potency supplements.
End Use Industry:
Volume scale inverts against margin structure — food applications consume tonnage while pharmaceutical and supplement channels extract value per gram through purity certification and clinical substantiation.
- Food & Beverages:Bakery, dairy, and beverage manufacturers incorporate ALA-rich oils and microencapsulated DHA powders for shelf-stable omega-3 positioning. Thermal degradation constraints limit inclusion rates to 50-200mg per serving in UHT-processed applications.
- Pharmaceuticals:Prescription omega-3 ethyl esters and free fatty acid formulations require USP monograph compliance and batch-level COA documentation for cardiovascular and hypertriglyceridemia indications. Lovaza and Vascepa equivalents drive demand for 90%+ EPA concentrates.
- Personal Care:Cosmetic formulations leverage linoleic acid for barrier repair and anti-inflammatory topical applications, with clean-label positioning favoring plant-derived over marine sources.
- Dietary Supplements:Direct-to-consumer softgels and gummies represent the primary revenue channel for finished PUFA brands, with practitioner-only distribution gaining share for condition-specific EPA/DHA ratio protocols.
Food & Beverages channels process the highest raw tonnage. Dietary Supplements generate the steepest margin expansion through concentration and delivery format differentiation.
Form:
Processing intensity separates commodity liquid oils from value-added delivery systems that address bioavailability, shelf stability, and consumer convenience preferences.
- Liquid Oils:Bulk fish oil and algal oil in drum and tote packaging supply contract manufacturers and food processors with cost-efficient raw material inputs requiring nitrogen flushing and refrigerated storage.
- Softgel Capsules:Gelatin and plant-based capsule shells encapsulate standardized potency oils for retail supplement shelves and clinical trial supply, with enteric coating options for gastric bypass protection.
- Powdered Supplements:Spray-dried and microencapsulated formats enable functional food integration where thermal processing and extended shelf life demand oxidative stability beyond liquid oil limits.
- Emulsions:Water-dispersible omega-3 concentrates serve beverage fortification and parenteral nutrition applications requiring homogenous suspension and enhanced mucosal absorption.
Softgel capacity represents the most installed conversion infrastructure. Powdered Supplements are climbing the fastest as bakery and RTD beverage brands seek clean-label fortification without sensory compromise.
Source:
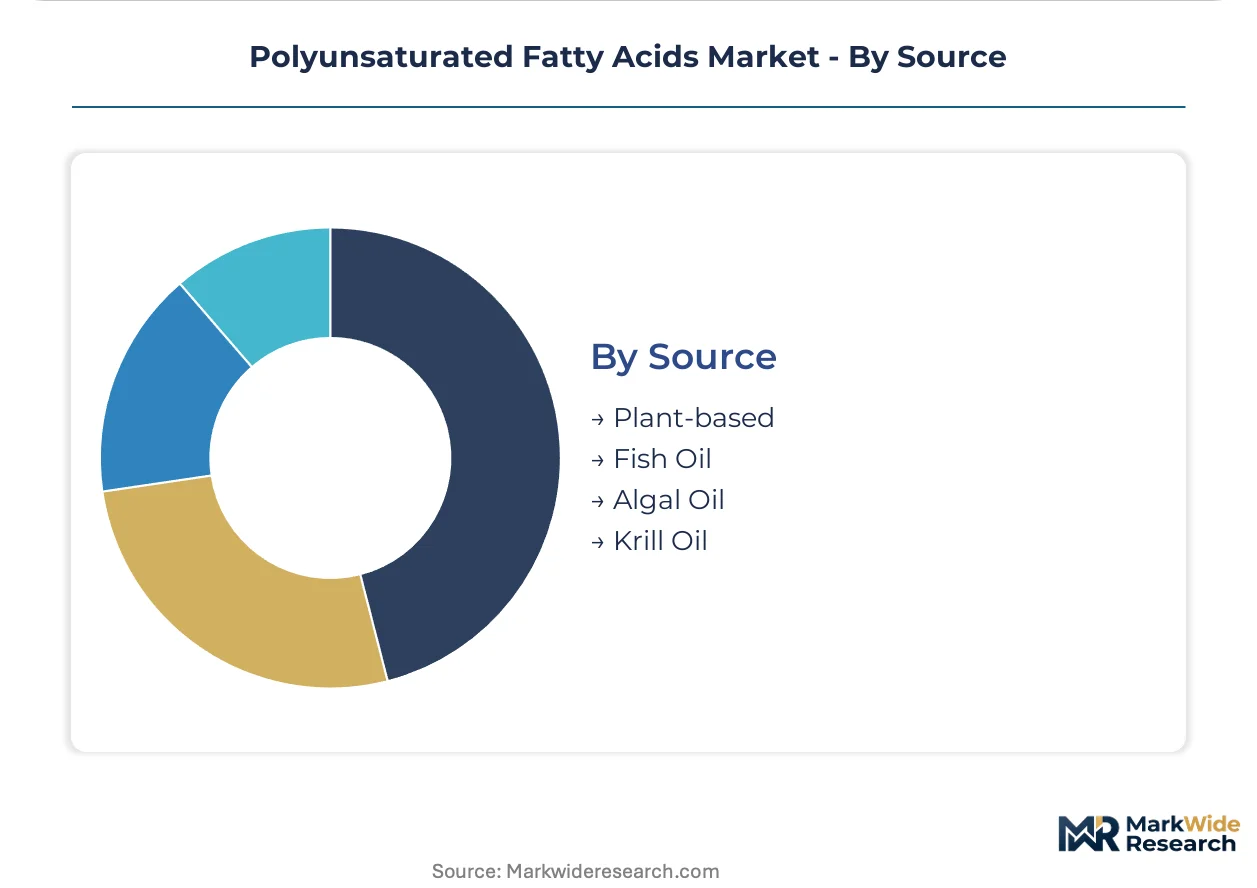
Supply concentration in Peruvian anchovy fisheries is fragmenting toward distributed fermentation assets as brands decouple from harvest volatility and contaminant risk.
- Plant-based:Flaxseed, chia, and echium oils deliver ALA for vegetarian positioning, though metabolic conversion to EPA/DHA limits efficacy claims in premium supplement segments.
- Fish Oil:Peruvian and North Atlantic reduction fisheries supply the majority of crude EPA/DHA raw material, with IFFO RS certification and GOED monograph compliance gating access to major brand supply chains.
- Algal Oil:Fermentation-derived DHA from Schizochytrium and Crypthecodinium strains achieves pharmaceutical-grade purity without marine contaminant burden, with capacity expansion concentrated in China and Singapore.
- Krill Oil:Antarctic krill biomass delivers phospholipid-bound omega-3s with enhanced bioavailability claims, though harvest quota constraints and MSC certification requirements limit scale.
Most installed refining capacity processes Fish Oil through molecular distillation trains. Algal Oil fermentation is gaining share fastest as synthetic biology platforms compress unit costs and EFSA Novel Food pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta concentration anchors fermentation capacity expansion for algal-derived omega-3s. EFSA-validated health claims and FDA structure-function pathways create divergent approval economics across Atlantic markets. Procurement patterns now favor multi-source qualification to buffer El Niño-driven fish oil volatility.
China
Domestic Schizochytrium fermentation scales under dual carbon policy incentives that compress unit costs against Peruvian imports. SAMR and NMPA jointly oversee functional food and pharmaceutical lipid registrations with divergent oxidative stability protocols. Qingdao and Shanghai biotech clusters host the majority of installed algal oil capacity serving Southeast Asian infant formula manufacturers.
United States
FDA structure-function claims and NDIN pathways for novel sources sustain premium positioning for EPA/DHA concentrates. USDA BioPreferred procurement preferences channel institutional nutrition demand toward domestic fermentation processors. Boston and San Diego biotech corridors concentrate precision biology platforms that reduce harvest-season dependency for contract manufacturers.
Germany
REACH Annex XVII contaminant restrictions tighten testing burdens for marine lipid importers, accelerating algal substitution in premium supplement lines. EFSA Article 13.1 cardiovascular claims validate prescription-grade positioning for 85%+ EPA concentrates. Hamburg and Frankfurt house the majority of European molecular distillation capacity for pharmaceutical-grade output.
Japan
PMDA oversight of functional food and pharmaceutical lipid registrations demands batch-level COA documentation that elevates barriers for unvalidated entrants. METI bioprocess intensification grants support continuous fermentation with cell retention beyond 60 days. Osaka and Tokyo clusters specialize in water-dispersible emulsion formats for beverage fortification applications.
Singapore
Halal certification and traceability documentation requirements from Indonesian and Vietnamese DHA fortification mandates concentrate Southeast Asian procurement decisions. The city-state's free trade agreements reduce tariff exposure for fermentation-derived concentrates entering ASEAN markets. Jurong Island hosts the majority of regional algal oil refining capacity serving pharmaceutical softgel contract manufacturers.
Polyunsaturated Fatty Acids Market Competitive Landscape
Global majors compete with regional champions across raw material sourcing and regulatory dossier capabilities. The vendor base stratifies between integrated marine processors, synthetic biology platforms, and specialized concentrate refiners. Three archetypes dominate: backward-integrated chemical conglomerates, fermentation technology licensors, and contract manufacturing organizations with chromatographic purification expertise. Competitive moves concentrate on multi-source procurement partnerships and Novel Food approval acceleration through clinical trial infrastructure.
Among integrated chemical conglomerates, BASF SE and Cargill Incorporated exemplify the backward-integration archetype through captive supply of marine and oilseed feedstocks. Koninklijke DSM N.V. occupies a distinct position within the synthetic biology tier, representing fermentation-derived alternatives that decouple finished goods manufacturers from wild-catch volatility. These three anchors illustrate how margin stability now depends on upstream control over raw material streams rather than downstream formulation differentiation alone.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Incorporated |
| Koninklijke DSM N.V. |
| Croda International PLC |
| FMC Corporation |
| Aker BioMarine AS |
| Omega Protein Corporation |
| Polaris Nutritional Lipids |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade EPA/DHA concentrate premiums diverge sharply from commodity ALA feedstock pricing, with that bifurcation manifesting in dual sourcing strategies and divergent margin protection mechanisms across marine and fermentation origins. EFSA-validated health claims sustain 3-5x price multiples for 85%+ purity concentrates against standard fish oil, while China's dual carbon incentives compress algal oil unit costs toward parity with Peruvian anchovy equivalents.
Pricing Analysis
Input-cost pass-through from fish oil crude volatility dominates pricing dynamics, with El Niño-driven anchovy quota compressions spiking refined EPA/DHA feedstock costs within single harvest cycles. Three-tier pricing structure across pharmaceutical, nutraceutical, and food-grade levels separates USP-monograph compliance from basic GOED-standard oils. Cost compression in commodity omega-3 is intensifying as Chinese fermentation capacity floods mid-tier concentrate supply. Mass-market food fortification buyers exhibit highest price sensitivity, while prescription medical food manufacturers absorb premiums for batch-level COA documentation.
Supply Chain Analysis
Reverse-logistics flows for expired or oxidized marine oils remain underdeveloped, with most degradation losses absorbed at manufacturing rather than recaptured through re-refining. Geographic concentration centers on Peru for crude fish oil, China for algal fermentation, and Germany for molecular distillation refining. Raw material dependencies draw from Antarctic krill biomass, Schizochytrium fermentation strains, and North Atlantic reduction fisheries. Single-source vulnerability in Peruvian anchovy quotas exposes non-integrated refiners to margin collapse. Distribution runs through Rotterdam and Singapore hub terminals for bulk oil, with direct formulation partnerships displacing spot market transactions for pharmaceutical-grade output.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EFSA Article 13.1 cardiovascular claim validations and China's SAMR functional food registrations accelerating premium capture for clinically substantiated concentrates.
For Market Incumbents: Hedge harvest-season dependency by accelerating algal oil fermentation partnerships in China's Yangtze River Delta biotech clusters. Secure backward integration into Schizochytrium strain development to defend margin stability against synthetic biology platform entrants. Prioritize multi-jurisdiction dossier harmonization investments to compress EFSA-FDA-NMPA registration lag. For New Entrants and Emerging Players: USDA BioPreferred procurement preferences in the United States open a window for domestic fermentation processors seeking federal institutional nutrition contracts. Target practitioner-only distribution channels in Australia and the United States where condition-specific EPA/DHA protocols command subscription recurring revenue. Pursue halal certification and traceability documentation to penetrate Southeast Asian infant formula mandates in Vietnam and Indonesia. For Investors and Strategic Acquirers: Consolidation pressure builds where chromatographic purification expertise scarcity concentrates pharmaceutical-grade output among fewer than twenty global contract manufacturers. Five-to-ten year viability favors synthetic biology platforms with continuous fermentation cell retention capabilities over batch-dependent marine processors. Monitor EFSA Novel Food approval timelines for algal oil sources as inflection indicator for fermentation-derived market share acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Synthetic biology platforms achieving 15+ g/L titers collapse harvest-season dependency for contract manufacturers. |
| Multi-Jurisdiction Dossier Harmonization | Unified EFSA-FDA-NMPA submission packages compress registration timelines and reduce redundant analytical spending. |
| Practitioner-Only Distribution Buildout | Direct-to-clinic channels in the United States bypass mass retail margin compression for condition-specific formulations. |
| Halal Certification Investment | Traceability documentation unlocks Southeast Asian infant formula procurement decisions in Indonesia and Vietnam. |
| Continuous Fermentation Technology | Perfusion bioreactors beyond 60 days steady-state operation enable geographic production asset distribution. |
Research Methodology
Bottom-up dietary supplement and pharmaceutical modeling reconciled against top-down fermentation capacity and marine catch tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads at algal oil processors, procurement managers at infant formula manufacturers, technical R&D directors at molecular distillation refiners, and GPO contracts managers at hospital systems combined with secondary validation from EFSA health claim registers, FDA NDIN filings, SAMR functional food approvals, and customs trade data for omega-3 concentrate imports. Triangulation between stakeholder demand signals and supply-side installation capacity ensures cross-verified volume and value estimates.
Historical trendline analysis across EPA/DHA concentrate purity tiers, algal oil fermentation scale trajectories, and regional regulatory approval velocities established baseline growth parameters. Segmentation dimensions modeled include product type concentration level, end-use industry margin structure, delivery format processing intensity, and source origin regulatory pathway. CAGRs derive from fitted trend extrapolation adjusted for policy inflection points and technology cost curves. Industry-specific forecast inputs incorporate El Niño-Southern Oscillation cycle impacts on anchovy quotas and synthetic biology platform yield improvement trajectories.
Revisions become necessary when EFSA Novel Food approval timelines extend beyond standard evaluation windows or when Chinese dual carbon policy incentives shift domestic algal oil financing terms. Forecasts reflect assumptions regarding regulatory pathway maturation and fermentation scale economics. Practitioners should monitor EFSA algal oil safety opinions and SAMR infant formula ARA fortification mandate enforcement for early signals of supply concentration shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Polyphenols Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Food Premix Market
Food Components and Additives
Food Antimicrobial Coating Market
Food Components and Additives
Clean Label Pectin Market
Food Components and Additives
USA Food Premix Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Food-Grade Monopotassium Phosphate Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
Natural Fatty Acids Market