
 Food Can Coatings Market | 2026-2036
Food Can Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Food Can Coatings Market Intelligence
A bundled service model that includes technical support and regulatory compliance is shifting the value proposition beyond mere material supply. This integrated approach helps food manufacturers navigate complex international food safety laws. PPG Industries leverages its global manufacturing footprint to serve multinational food producers. AkzoNobel competes on its portfolio of BPA-free polyester and acrylic coatings, while Altana AG specializes in high-performance solutions for niche applications like beverage ends.
Food can coatings are polymeric films applied to the interior surface of metal cans to prevent interaction between the food product and the container. These coatings, typically applied at thicknesses of 2 to 10 micrometers, must withstand high-temperature sterilization processes while ensuring food safety and preserving taste. While traditional epoxy coatings still hold a significant share, polyester coatings are gaining traction due to regulatory pressures on BPA. The beverage and pet food application segments exhibit strong demand for advanced coating solutions that guarantee product integrity and extended shelf life.
Regulations from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) heavily influence material selection by setting strict migration limits for substances. Compliance with standards like China's GB standards for food contact materials is mandatory for market access, driving research and development in non-BPA alternatives. Material suppliers and can manufacturers must continually assess the evolving landscape of global food safety regulations and consumer preferences for sustainable packaging.
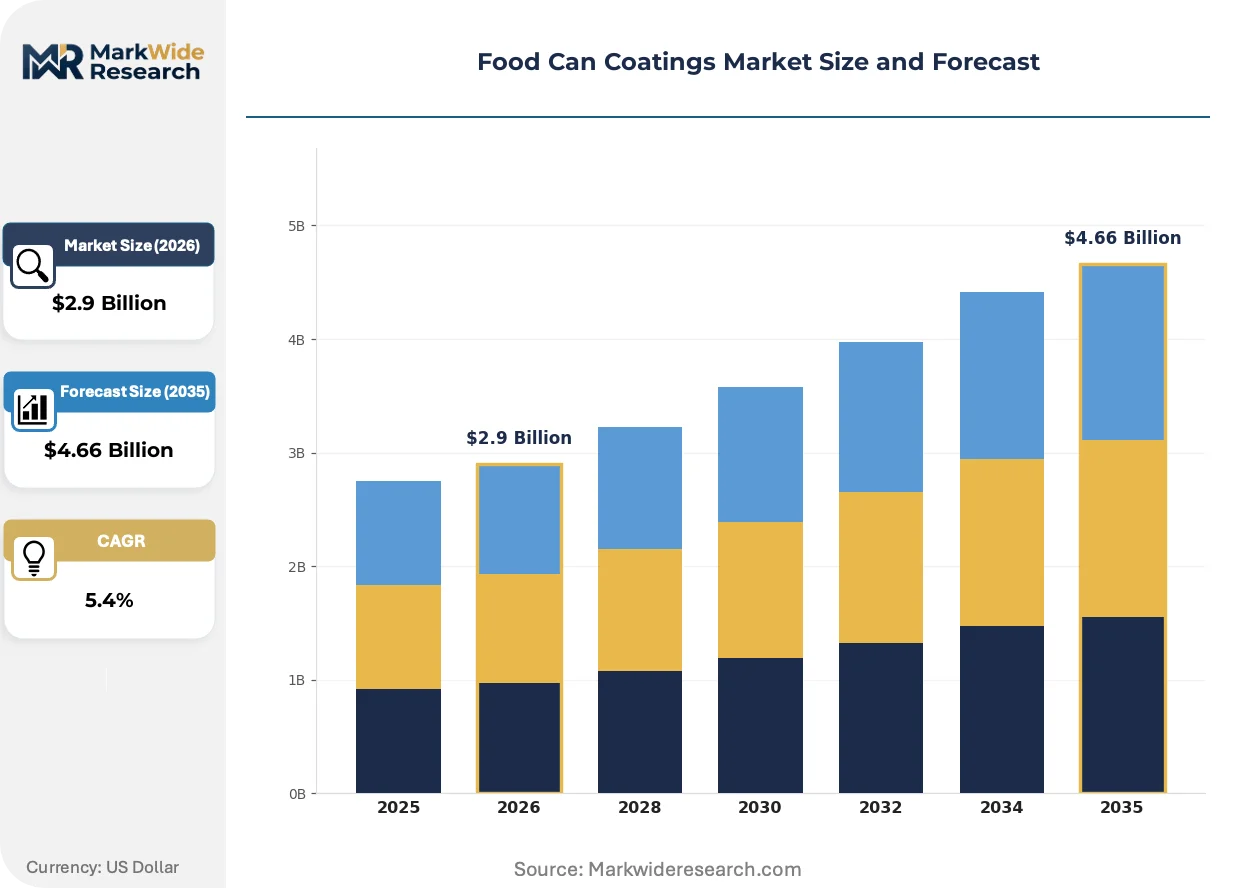
Market Dynamics
The imperative to replace bisphenol-A (BPA) in food contact materials is the central structural force defining the market. This regulatory-driven shift, enforced by authorities like the FDA and EFSA, compels innovation away from traditional epoxies toward alternative polymer systems.
Growth Catalysts
- Regulatory Mandates:Stricter migration limits for substances from authorities like the European Food Safety Authority (EFSA) create a continuous demand for new, compliant coating formulations, particularly next-generation polyesters and acrylics.
- Premiumization in Pet Food:The expansion of the premium pet food segment requires advanced coatings that protect complex formulations and sensitive nutrients, ensuring product integrity and extended shelf life for high-value products.
- Manufacturing Relocation:The concentration of can manufacturing and food processing in Southeast Asian countries necessitates localized coating production and technical support, pulling investment into the region's supply chain infrastructure.
Market Restraints
- Higher Formulation Costs:The research, development, and qualification costs for novel BPA-free coatings are significantly higher than for mature epoxy technologies, creating a cost barrier for adoption, especially in price-sensitive segments.
- Performance Parity Challenges:Some non-epoxy alternatives struggle to match the universal adhesion and chemical resistance of traditional epoxies, particularly when used with highly acidic or aggressive food products like tomatoes.
- Divergent Global Standards:Navigating conflicting or non-harmonized regulations, such as differing substance clearance lists between China's GB standards and US FDA rules, complicates global product rollouts and increases compliance costs.
Strategic Opportunities
- Bio-Based and Renewable Polymers:Developing coatings from bio-based sources presents a significant opportunity to meet brand owner demand for sustainable packaging solutions, creating a new axis of product differentiation beyond BPA-free status.
- Coatings for New Can Formats:The rise of new packaging formats, such as aluminum beverage bottles and shaped cans, creates demand for specialized coatings with unique flexibility, formability, and barrier properties.
- Expansion in Latin America:Growing processed food consumption in markets like Brazil and Mexico, coupled with less-saturated market penetration for advanced coatings, offers a key geographic expansion corridor for suppliers.
Industry Challenges
- Lengthy Certification Cycles:The time and capital required to achieve food contact certification for a new polymer or additive from bodies like the FDA or EFSA can delay market entry and return on investment for innovators. *Raw Material Qualification: Reformulating coatings requires qualifying new sources for monomers and additives, a complex process that involves extensive testing to ensure no adverse impact on final coating performance or safety.
- Application Process Variability:Ensuring consistent film weight and cure performance across diverse can manufacturing lines, which may use different equipment and operating parameters, remains a persistent operational challenge for coating suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Can Coatings Market |
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $4.66 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Epoxy, Acrylic, Vinyl Application: Fruits, Vegetables, Beverages, Pet Food End User: Food Manufacturers, Beverage Producers, Canning Facilities, Retailers Technology: In-Mold Coating, Spray Coating, Electrostatic Coating, Roll Coating |
| Companies Covered | Altana AG, TOYOCHEM, PPG Industries, Kansai Paint, VPL Packaging Coatings, AkzoNobel, Tiger Coatings, Srisol Group, Valspar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Can Coatings Market Strategic Shifts & Innovations
Material science is advancing under a dual mandate of regulatory compliance and enhanced product protection. This dynamic is pushing development beyond simple material substitution toward integrated systems that combine novel polymers with advanced application processes for superior performance.
Next-generation polyester and acrylic chemistries provide a BPA-free barrier that prevents metal migration and flavor scalping. These advanced polymers are seeing rapid adoption in the beverage and sensitive food segments, including infant formula and dairy products. This new generation of material science is converging with advanced application methods like coil coating to enable higher production speeds and greater material efficiency.
The European Union's REACH regulation imposes stringent evaluation requirements on all chemicals used within the bloc, including those in food contact materials. This creates a continuous cycle of risk assessment and potential restriction, forcing coating formulators to maintain a pipeline of compliant alternatives. Legacy epoxy systems are most affected, compelling can makers to accelerate transitions to pre-approved polyester and acrylic solutions to mitigate future supply risks.
Food and beverage brand owners are increasingly adopting bundled service models that extend beyond simple material supply. This approach, which integrates technical application support and regulatory compliance consulting, is displacing purely transactional procurement. The shift is most visible among large multinational food companies that need to ensure product consistency and safety across diverse global markets like the United States, China, and the European Union.
Food Can Coatings Market Segmentation
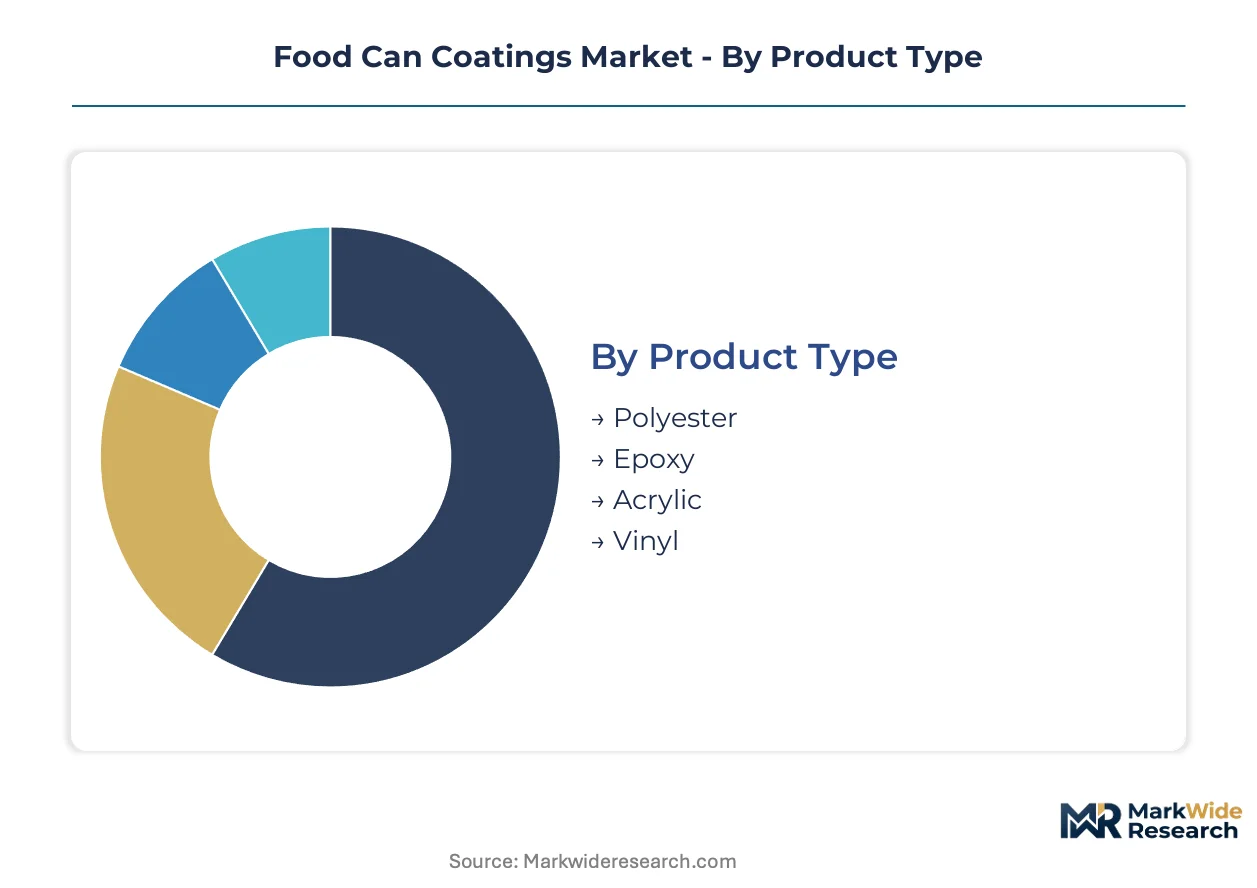
Segmentation in the food can coatings market reveals distinct material preferences and application requirements. Understanding these divisions helps suppliers tailor solutions for diverse end-user needs. This granular view highlights areas of innovation and competitive differentiation.
Product Type:
Buyers in the food can coatings market differentiate based on performance specifications and regulatory compliance.
- Polyester:These BPA-free polymeric films offer excellent flexibility and corrosion resistance, gaining traction as alternatives to epoxy systems due to evolving health regulations. Demand concentrates in beverage and pet food segments, driven by stringent safety standards from EFSA and FDA.
- Epoxy:Traditional coatings based on bisphenol-A (BPA) provide superior adhesion and chemical resistance, historically dominating the market due to their robust performance. However, regulatory scrutiny in regions like the European Union and China compels manufacturers to seek alternatives.
- Acrylic:Acrylic coatings offer good clarity and chemical resistance, finding use in specific food contact applications where transparency and non-BPA status are critical.
- Vinyl:Vinyl-based coatings provide flexibility and good barrier properties, often used for specific food products requiring high formability or specific chemical inertness.
Volume sits with Epoxy; growth tilts toward Polyester.
Application:
Application segments for food can coatings are defined by the specific food product characteristics and required barrier properties.
- Beverages:Coatings for beverage cans require high acid resistance and flavor neutrality, preventing interaction with carbonated drinks and juices. This segment experiences strong demand for advanced BPA-free solutions due to high production volumes and consumer sensitivity to taste.
- Pet Food:Advanced coatings in pet food protect complex formulations, sensitive nutrients, and ensure extended shelf life for premium products. The segment's premiumization trend drives demand for robust barriers against fats and proteins, maintaining product integrity.
- Fruits:Coatings for fruit cans must withstand the acidity of various fruits and high-temperature sterilization processes, ensuring product integrity and preventing metal contamination.
- Vegetables:Coatings for vegetable cans provide a protective barrier against mild acids and salts, maintaining the taste and nutritional value of processed vegetables.
The segment for Beverages drives significant revenue, while Pet Food exhibits the steepest expansion trajectory.
End User:
End-user categories for food can coatings are distinguished by their operational scale, regulatory requirements, and procurement practices.
- Food Manufacturers:These entities directly purchase and apply coatings or procure pre-coated cans for a wide range of food products, prioritizing food safety compliance and product compatibility across diverse formulations. Global food manufacturers require suppliers with strong technical support and regulatory expertise.
- Beverage Producers:High-volume beverage producers demand coatings that ensure flavor integrity, withstand high-speed filling lines, and comply with strict migration limits. Their procurement often involves long-term contracts with specialized coating suppliers.
- Canning Facilities:These facilities apply coatings to metal sheets or pre-formed cans, necessitating efficient application technologies and consistent coating performance for mass production.
- Retailers:Retailers indirectly influence coating selection through packaging specifications and consumer preferences for sustainable and safe food containers.
Food Manufacturers represent the largest customer base, with Beverage Producers showing increasing procurement sophistication.
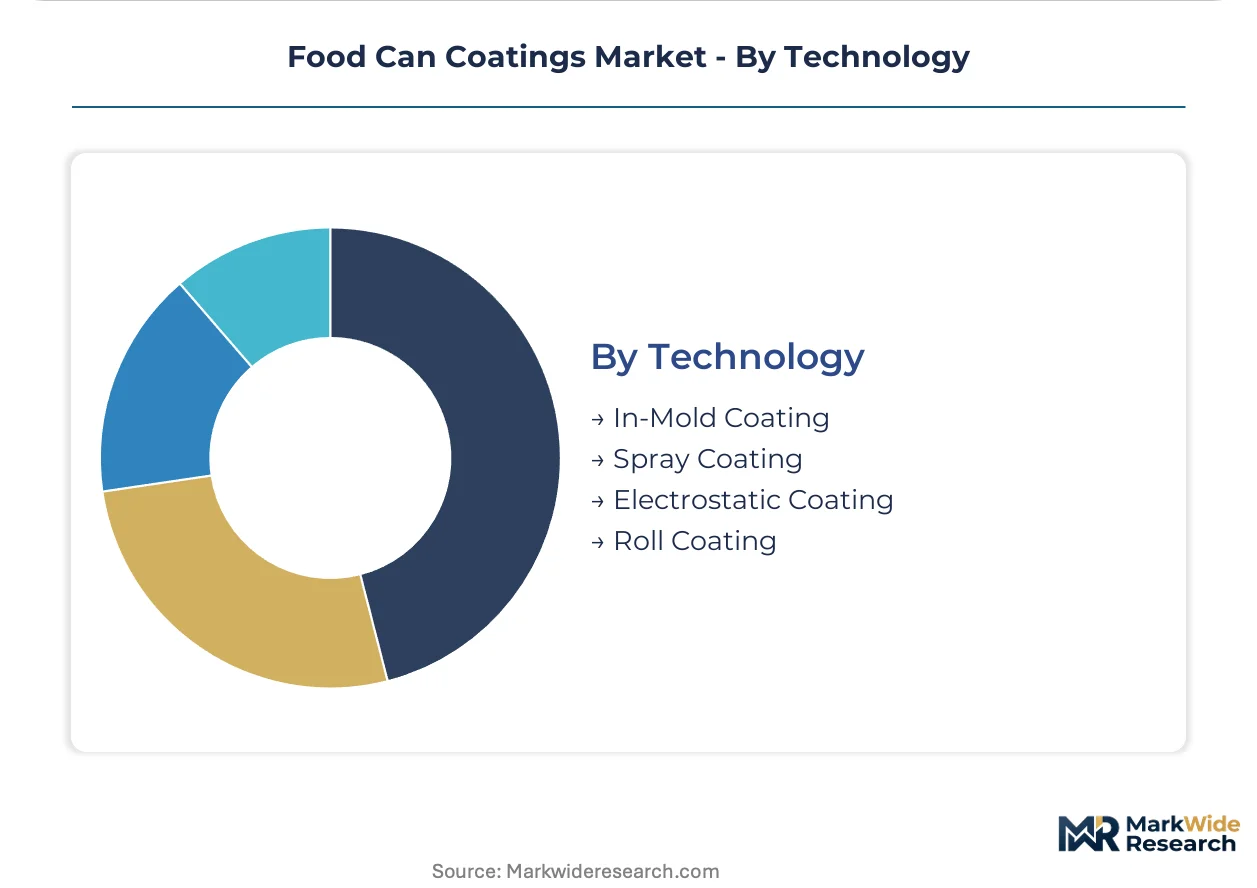
Technology:
Coating technologies are differentiated by their application method, suitability for various can formats, and operational efficiencies.
- Roll Coating:This high-speed process applies liquid coatings to flat metal sheets before can formation, enabling efficient mass production and uniform film thickness. It is widely used for producing two-piece and three-piece food cans.
- Spray Coating:Spray coating applies liquid or powder coatings to the interior of already formed cans, particularly suitable for complex shapes and beverage ends. This method allows for precise, targeted application.
- Electrostatic Coating:Electrostatic coating uses an electric field to apply powdered coating materials, ensuring uniform coverage and minimizing overspray. This technology reduces material waste and offers environmental benefits.
- In-Mold Coating:This emerging technology integrates the coating application directly into the can molding process, offering potential for novel can designs and material savings.
Roll Coating remains critical for high-volume production, while Spray Coating enables diverse can designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global food can coatings market exhibits a notable production-consumption divide, with manufacturing capabilities increasingly consolidating in specific regions while demand for advanced solutions remains widespread across diverse food processing hubs. This dynamic drives localized investment and technical support for food manufacturers.
China
Demand for food can coatings in China is driven by its massive domestic food processing industry and export mandates. Compliance with China's GB standards for food contact materials is mandatory for market access. Coating production and technical service centers in the Yangtze River Delta region support the country's extensive can manufacturing base.
United States
The United States market requires specialized coatings for its large beverage and processed food sectors. US Food and Drug Administration (FDA) regulations heavily influence material selection, particularly for BPA-free alternatives. Food packaging innovation centers in the Midwest focus on developing compliant and high-performance solutions for domestic producers.
Germany
European food safety regulations, particularly from the European Food Safety Authority (EFSA), shape the demand for advanced BPA-free coatings in Germany. The country's strong chemical industry drives research into next-generation polyester and acrylic solutions. Manufacturing clusters in states like North Rhine-Westphalia develop specialized coatings for both domestic and export markets.
Thailand
Southeast Asian countries like Thailand are becoming key manufacturing centers for food and beverage cans, necessitating localized coating production. The Thai industrial standards (TIS) for food contact materials ensure product safety and quality. Investment in coating facilities around Bangkok supports the region's expanding food processing and export activities.
Brazil
Growing processed food consumption in Brazil fuels demand for protective can coatings. ANVISA regulations for food contact materials dictate the adoption of safe and compliant coating technologies. Industrial zones in São Paulo state are expanding their capacity for can manufacturing, requiring efficient and cost-effective coating solutions.
Food Can Coatings Market Key Industry Players
Capital-heavy producers of base polymers compete with specialized formulators who design custom coating solutions for specific applications. The market structure exhibits a tiered consolidation, with a few large chemical companies holding significant material supply capabilities. Strategic archetypes include integrated material suppliers, niche application specialists, and regional coating providers. Dominant competitive moves involve portfolio diversification into BPA-free alternatives and strategic partnerships for technical support.
Among the global chemical giants, PPG Industries exemplifies a diversified player leveraging its extensive manufacturing footprint to serve multinational food producers across various geographies. AkzoNobel, a European-based supplier, occupies a position focused on a broad portfolio of BPA-free polyester and acrylic coatings, catering to evolving regulatory demands. Altana AG, a German specialty chemical company, anchors the high-performance segment, providing specialized solutions for niche applications such as beverage ends. These firms represent distinct approaches to market penetration and value capture, reflecting varied strategies in product development and customer engagement within the evolving food can coatings landscape.
| Leading Market Players |
|---|
| Altana AG |
| TOYOCHEM |
| PPG Industries |
| Kansai Paint |
| VPL Packaging Coatings |
| AkzoNobel |
| Tiger Coatings |
| Srisol Group |
| Valspar |
Cost & Logistics Intelligence
Captive supply chain integration anchors both the supply position and the pricing power for large food can coatings manufacturers. This model allows for greater control over material quality and cost structures, influencing market pricing.
Pricing Analysis
Cost compression in the standard coatings segment stems from intense competition among suppliers, particularly for traditional epoxy systems. Contract-based long-term offtake agreements define the dominant pricing model, offering stability for high-volume buyers. Price differentiation arises from certification levels (e.g., FDA/EFSA compliance) and volume scale, with premium solutions commanding higher rates. Small and medium-sized canners exhibit the highest price sensitivity, often seeking cost-effective alternatives, while large multinational food manufacturers prioritize performance and regulatory compliance.
Supply Chain Analysis
Regional distribution hubs in Southeast Asia and China facilitate localized delivery of food can coatings to manufacturing centers. Geographic supply concentration includes major production in China, Thailand, and Germany, leveraging existing chemical industry infrastructure. Raw material sourcing for polyester resins, acrylic monomers, and specialized pigments often originates from diverse global suppliers. Raw material price volatility represents a structural risk, impacting overall coating production costs. The dominant distribution model involves direct sales supplemented by comprehensive technical support for can manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, driven by the shift from traditional epoxy coatings to advanced polyester and acrylic systems. This evolution necessitates strategic adjustments across the value chain.
For Market Incumbents: Cement market leadership by accelerating investment in next-generation BPA-free coating formulations, particularly bio-based polymers. Diversify product portfolios to mitigate the regulatory threat posed by legacy epoxy systems. Leverage existing global manufacturing footprints to offer localized technical support and ensure compliance with diverse international food safety regulations.
For New Entrants and Emerging Players: Small and medium-sized food manufacturers in emerging markets represent an underserved buyer archetype. Target geographic expansion into regions like Latin America, focusing on niche applications such as specialty pet food coatings. A strong go-to-market angle involves offering bundled technical support and regulatory consulting, simplifying market entry for local producers.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated specialty chemical firms with strong IP portfolios in non-BPA solutions. The long-term viability of the market is strong, driven by continuous regulatory compliance and consumer demand for safer packaging. A key signal to watch is the successful commercialization of novel bio-based coating technologies with proven performance parity.
| Strategic Initiative | Industry Significance |
|---|---|
| BPA-Free Portfolio Diversification | Expands market reach into regulated segments and meets evolving consumer preferences. |
| Localized Technical Support Centers | Enhances customer relationships and ensures application consistency for regional manufacturers. |
| Bio-Based Polymer R&D Investment | Addresses sustainability demands and creates new product differentiation beyond regulatory compliance. |
| Strategic Partnerships for Compliance | Navigates complex global food safety regulations and accelerates market access for new materials. |
| Manufacturing Footprint Optimization | Reduces logistics costs and improves responsiveness to regional demand fluctuations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market intelligence. This secondary research was combined with primary interviews involving R&D directors, procurement managers, regulatory affairs specialists, and can manufacturing engineers. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy and consistency across all segments.
Data-stream reconciliation integrated quantitative market sizing with qualitative insights across the modeling period. Segmentation dimensions modeled included product type, application, end-user, technology, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected adoption rates for new coating technologies. Raw material cost fluctuations and regulatory timelines for new material approvals served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving food safety regulations and raw material supply chain disruptions. These forecasts reflect a comprehensive set of assumptions regarding market dynamics and technological advancements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
Fillings and Toppings Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
Food Grade Xanthan Gum Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Europe Food Premix Market
Food Components and Additives
Asia-Pacific Food Anti Caking Agents Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial Coating Market
Food Components and Additives
Food Antioxidant Market
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market
Food Components and Additives
Germany Food Hydrocolloids Market