
 North America Food Flavor and Enhancer Market | 2026-2036
North America Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Flavor and Enhancer Market Analytics
The premium-commodity split in North America food flavor and enhancer supply is rebalancing around clean-label certification and synthetic cost floors. Sensient Technologies Corporation leverages its botanical extraction infrastructure to dominate natural flavor supply for beverage and dairy manufacturers. Kerry Group anchors its position through backward integration into dairy and meat taste solutions, while International Flavors & Fragrances Inc. competes on biotech-derived flavor molecule platforms.
Food flavors and enhancers comprise volatile aromatic compounds, taste-active peptides, and nucleotide salts formulated to deliver, modify, or intensify sensory perception in processed foods, typically dosed at parts-per-million to percent-level concentrations depending on application heat stability requirements. Natural flavors command margin premiums in beverages and dairy products where label transparency drives procurement decisions, while artificial flavors and flavor enhancers retain volume dominance in savory snacks where cost thresholds constrain reformulation. Powder and liquid forms split demand across bakery and beverage applications respectively, with granular formats gaining traction in seasoning blends for food service channels.
The FDA's GRAS program, USDA organic certification standards, and Health Canada's Food and Drug Regulations collectively govern ingredient approval, labeling claims, and cross-border trade eligibility across the North American bloc. These frameworks compendium testing burdens and documentation requirements directly shape R&D allocation and product launch cadences for flavor houses operating in multiple jurisdictions. Stakeholders must monitor evolving positions on precision-fermented flavor compounds across FDA and Health Canada review queues to anticipate qualification timelines and first-mover advantages.
Market Dynamics
The FDA's GRAS notification framework is compressing ingredient qualification timelines and forcing flavor houses to front-load toxicology documentation before formulation work begins, fundamentally altering R&D capital allocation across the North American bloc.
Growth Catalysts
- Clean-label certification mandates:Beverage manufacturers in California's innovation corridor are demanding botanical extraction documentation for premium bottling lines, pulling natural flavor volumes upward.
- Precision fermentation platforms:Biotech-derived flavor molecules are qualifying under FDA's updated GRAS pathway faster than traditional extraction methods, opening new supply channels for dairy taste solutions.
- USDA organic procurement thresholds:Food service operators serving K-12 and institutional channels are reformulating around certified organic flavor inputs to meet federal nutrition program standards.
Market Restraints
- Vanillin feedstock volatility:Guaiacol and lignin-derived precursor markets swing with pulp mill capacity, squeezing margin predictability for synthetic vanilla substitutes used in savory snacks.
- California agricultural concentration:Botanical extraction infrastructure clusters within a 200-mile radius of Fresno and Salinas, creating single-point-of-failure risk for natural flavor supply security.
- Heat stability technical ceilings:Natural flavor compounds degrade above 180°C, limiting clean-label penetration into high-temperature bakery applications where Maillard-reaction masking is required.
Strategic Opportunities
- Quebec dairy processing corridor:Health Canada's distinct Food and Drug Regulations create a parallel qualification pathway for taste-active peptides in cheese and yogurt applications underserved by US-centric suppliers.
- Direct-to-foodservice granular formats:Seasoning blend manufacturers are bypassing traditional distribution tiers to supply restaurant chains with customized umami nucleotide salts for back-of-house deployment.
- IRA bio-based manufacturing credits:Precision fermentation facilities accessing Department of Energy loan guarantees can undercut extraction-based cost structures for natural-identical molecules.
Industry Challenges
- Flavor chemist talent scarcity:The specialized skill set bridging organic chemistry and sensory science commands compensation premiums that mid-tier houses struggle to match against pharmaceutical recruiters.
- GRAS dossier capex intensity:Building toxicology and exposure assessment capabilities in-house requires multi-million-dollar analytical infrastructure that excludes smaller formulation shops from novel ingredient development.
- Cross-border label harmonization friction:FDA "natural flavor" definitions diverge from Health Canada's "natural extract" nomenclature, forcing dual SKUs for products distributed across the US-Canada corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Flavor and Enhancer Market |
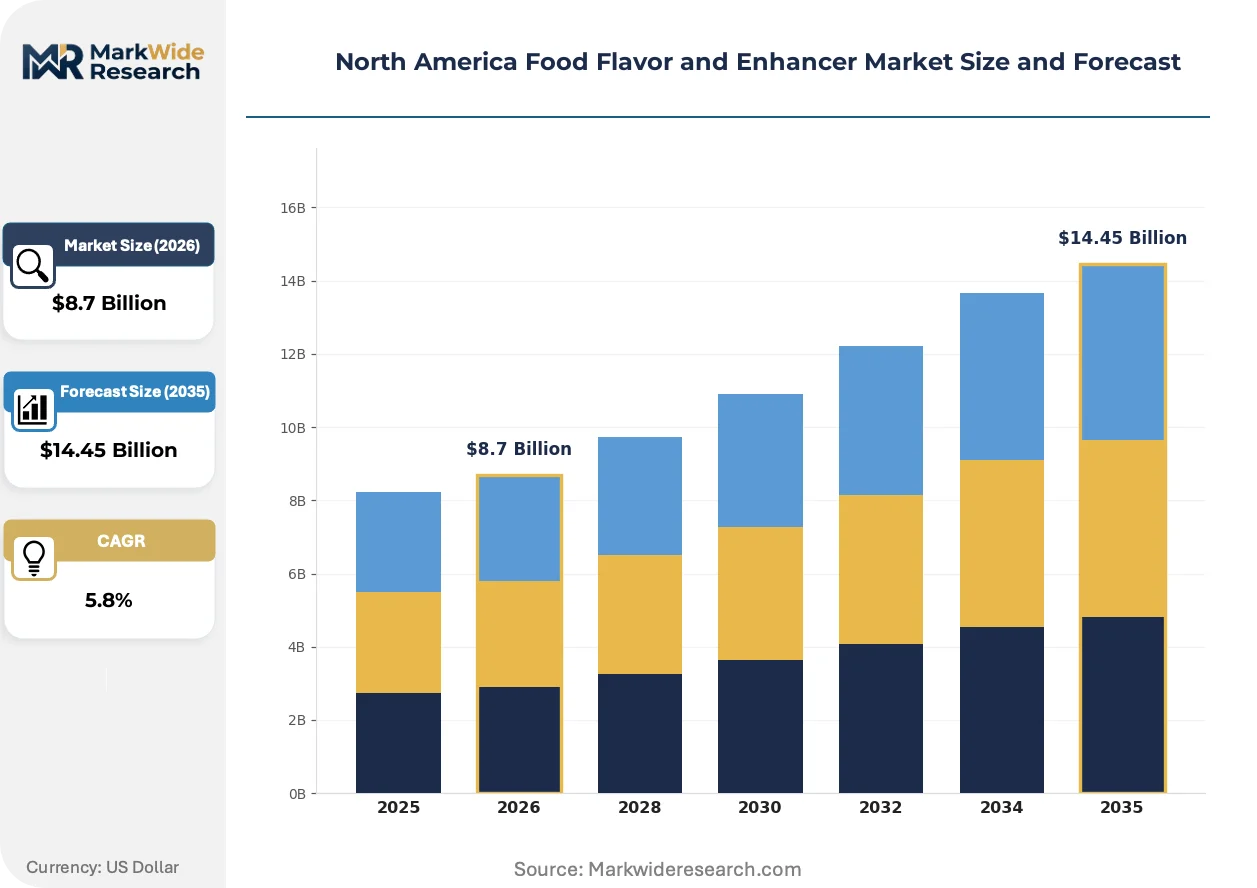
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Flavor Enhancers, Seasonings Application: Beverages, Bakery Products, Savory Snacks, Dairy Products End User: Food Manufacturers, Restaurants, Retailers, Food Service Providers Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Sensient Technologies Corporation, International Flavors & Fragrances Inc., Kerry Group, Givaudan, Archer Daniels Midland Company, Symrise AG, Firmenich SA, McCormick & Company, Inc., Corbion N.V., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Flavor and Enhancer Market Evolving Landscape
Biotechnology platforms are intersecting with traditional extraction infrastructure to create hybrid supply models that redefine cost structures and qualification timelines across flavor manufacturing.
Precision fermentation for natural-identical molecules is converging with botanical extraction certification requirements. Beverage and dairy manufacturers in California and the Pacific Northwest are adopting hybrid sourcing strategies that blend biotech-derived aromatic compounds with documented agricultural provenance. This convergence is compressing the premium pricing window for conventionally extracted natural flavors while expanding the addressable market for clean-label formulations previously constrained by botanical supply limits.
Health Canada's evolving stance on precision-fermented ingredients under the Food and Drug Regulations is creating a secondary approval queue distinct from FDA timelines. Flavor houses maintaining parallel dossier capabilities in Toronto and Montreal are securing first-mover positioning for novel molecules in the Canadian market. The dairy and meat taste solutions segment is most affected, with suppliers accelerating Health Canada submissions to preempt US regulatory synchronization.
Buyer concentration among multinational beverage bottlers is forcing flavor houses to unbundle technical service from compound supply. Procurement teams at three major carbonated soft drink manufacturers are separating sensory panel access, formulation support, and regulatory documentation into discrete contract line items. This unbundling is most visible in Texas and Georgia production hubs, where regional procurement offices now negotiate flavor supply, technical services, and compliance documentation through distinct vendor relationships rather than integrated master agreements.
North America Food Flavor and Enhancer Market Segmentation
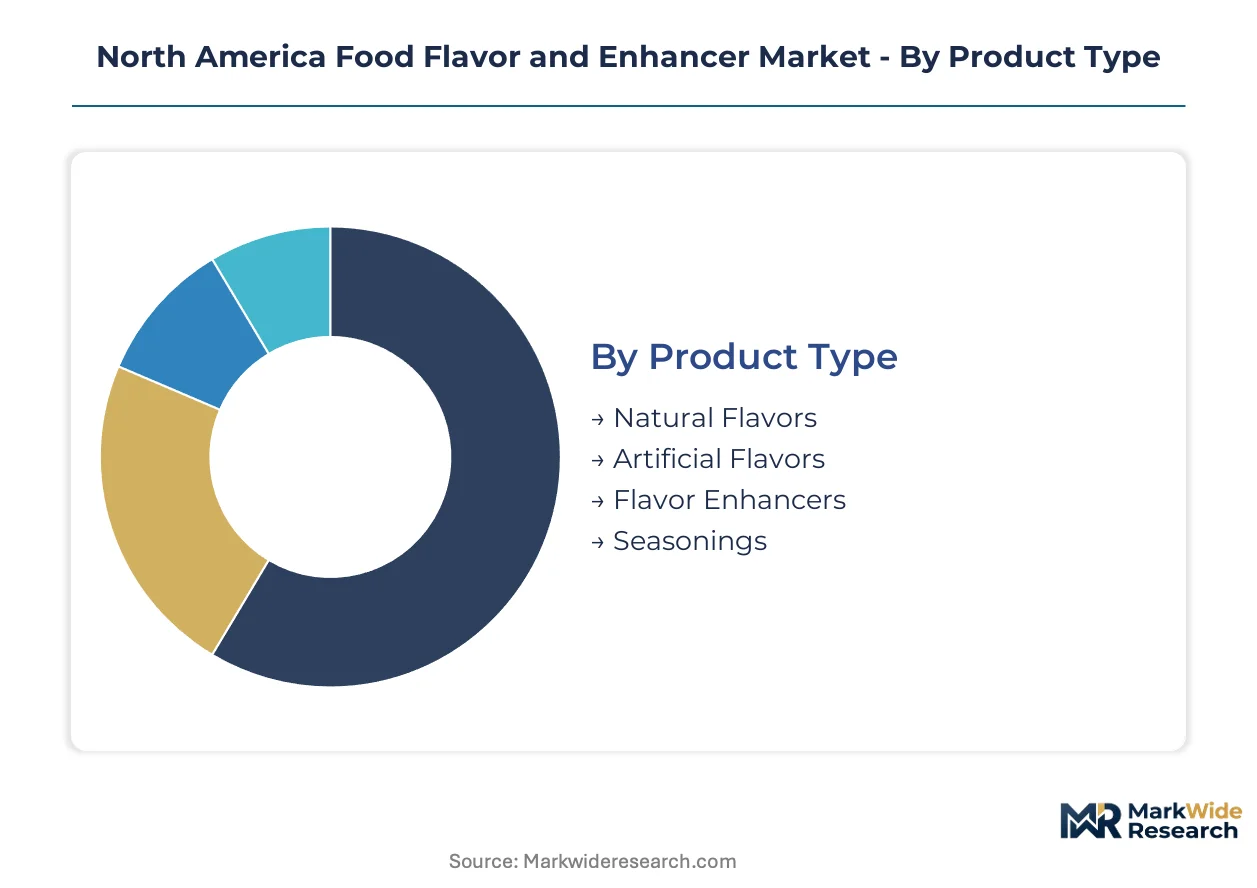
Flavor and enhancer procurement in North America splits sharply between premium clean-label formulations and cost-optimized synthetic alternatives. Segmentation discipline reveals where margin pools concentrate and which technical specifications command procurement priority across beverage, dairy, and savory applications.
Product Type:
Natural flavors capture premium pricing in California's innovation corridor while artificial flavors and enhancers anchor volume in cost-constrained savory segments.
- Natural Flavors:Botanical extraction yields volatile aromatic compounds from agricultural feedstocks with documented provenance. Beverage manufacturers in the Pacific Northwest and California's Central Valley are mandating extraction documentation for premium bottling lines, pulling supply toward Fresno and Salinas processing clusters.
- Artificial Flavors:Synthetic aromatic molecules manufactured from petrochemical or lignin-derived precursors deliver cost-predictable taste replication. Savory snack producers in Texas and Georgia production hubs rely on artificial vanillin and ester compounds where Maillard-reaction masking requirements and heat stability thresholds exclude natural alternatives.
- Flavor Enhancers:Nucleotide salts and glutamate derivatives intensify umami perception at sub-threshold concentrations. Food service seasoning blend manufacturers deploy customized enhancer ratios for back-of-house applications.
- Seasonings:Blended spice and flavor systems formulated for specific protein and starch substrates. Retail private-label programs drive formulation standardization.
Mature deployment sits with artificial flavors. Newer deployment is concentrated in natural flavors.
Application:
Heat stability requirements and label transparency standards segment demand across temperature-sensitive and certification-sensitive use cases.
- Beverages:Liquid flavor systems dosed at parts-per-million concentrations require cold-process compatibility and clarity stability. California beverage innovators are specifying botanical extraction documentation that disqualifies synthetic alternatives for premium positioning.
- Bakery Products:High-temperature applications above 180°C degrade natural aromatic compounds, forcing reliance on heat-stable artificial flavors or encapsulated natural systems. Midwest commercial bakeries balance clean-label marketing claims against technical performance failures in crust browning applications.
- Savory Snacks:Fried and extruded substrates tolerate aggressive flavor loading with cost-optimized artificial compounds. Seasoning adherence and fat-phase distribution drive powder and granular format selection.
- Dairy Products:Fermented and fresh dairy matrices demand flavor systems compatible with live culture activity and pH variation. Quebec cheese processors are accelerating Health Canada submissions for taste-active peptides to secure first-mover positioning in yogurt and fresh cheese applications.
Volume concentration remains in savory snacks. Steepest expansion trajectory is visible in beverages.
End User:
Procurement sophistication and technical service requirements separate integrated manufacturers from distributed food service operators.
- Food Manufacturers:Multinational bottlers and dairy processors unbundle technical service from compound supply, negotiating sensory panel access and regulatory documentation as discrete contract line items. Three major carbonated soft drink manufacturers now separate formulation support from flavor procurement in Texas and Georgia regional offices.
- Restaurants:Chain operators specify back-of-house granular formats for direct seasoning deployment, bypassing traditional distribution tiers. Customized umami nucleotide blends are gaining traction in quick-service kitchen operations.
- Retailers:Private-label programs demand formulation standardization and dual-source supply security for house-brand seasoning and flavor lines.
- Food Service Providers:Institutional channels serving K-12 and federal nutrition programs are reformulating around USDA organic procurement thresholds, pulling certified organic flavor inputs upward.
Contract sophistication sits with food manufacturers. Procurement flexibility is expanding fastest among restaurants.
Form:
Physical state determines distribution economics, dosing precision, and application equipment compatibility across manufacturing environments.
- Liquid:Pumpable concentrates with defined viscosity profiles for metered injection systems. Beverage lines in California and the Pacific Northwest specify liquid formats for homogeneous dispersion in high-speed bottling operations.
- Powder:Spray-dried or plated carriers with controlled particle size for dry blend uniformity. Bakery and seasoning applications dominate powder consumption.
- Granular:Agglomerated formats with enhanced flow properties for food service portion control. Restaurant chain back-of-house deployment is driving granular adoption.
- Paste:High-solids systems for protein and fat-phase incorporation where moisture management is critical. Specialty meat and sauce applications retain paste format preference.
Established infrastructure sits with liquid and powder. Granular deployment is gaining share fastest in food service channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fresno and Salinas anchor North American natural flavor extraction, with botanical processing infrastructure clustering within a 200-mile radius of California's Central Valley agricultural belt.
United States
Beverage manufacturers in California's innovation corridor are mandating documented botanical provenance for premium bottling lines. The FDA's updated GRAS notification framework compresses ingredient qualification timelines, forcing R&D capital reallocation. Texas and Georgia production hubs host regional procurement offices for carbonated soft drink manufacturers negotiating unbundled flavor supply contracts.
Canada
Quebec cheese processors are accelerating Health Canada submissions for taste-active peptides in yogurt and fresh cheese applications. Health Canada's Food and Drug Regulations create distinct qualification pathways parallel to FDA timelines. Toronto and Montreal dossier capabilities secure first-mover positioning for precision-fermented ingredients in the Canadian market.
Mexico
Savory snack producers in northern border states rely on cost-optimized artificial flavor imports for fried and extruded substrates. Mexico's COFEPRIS regulatory alignment with FDA standards facilitates cross-border supply chain integration. Guadalajara and Monterrey industrial corridors concentrate seasoning blend manufacturing for domestic and export markets.
North America Food Flavor and Enhancer Market Competitive Landscape
Capital-heavy extraction infrastructure operators compete with asset-light biotech-derived molecule designers for procurement contracts across beverage and dairy channels. The vendor base stratifies around three strategic archetypes: integrated flavor houses with captive botanical processing, precision fermentation specialists leveraging IRA bio-based manufacturing credits, and regional seasoning blend formulators serving food service channels. Dominant competitive moves include backward integration into agricultural feedstock sourcing and geographic expansion into parallel regulatory jurisdictions.
Within the integrated extraction tier, Sensient Technologies Corporation and Kerry Group exemplify divergent specialization strategies—Sensient leveraging botanical infrastructure dominance while Kerry anchors through upstream control over dairy and meat taste solutions. International Flavors & Fragrances Inc. occupies a distinct position bridging biotech-derived platforms with traditional compound supply.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| International Flavors & Fragrances Inc. |
| Kerry Group |
| Givaudan |
| Archer Daniels Midland Company |
| Symrise AG |
| Firmenich SA |
| McCormick & Company, Inc. |
| Corbion N.V. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap botanical extraction specialists in California's Central Valley anchor natural flavor supply, translating documented agricultural provenance into pricing premiums that commodity synthetic producers cannot match.
Pricing Analysis
Value-based pricing anchored to clean-label certification outcomes dominates procurement negotiations between California beverage bottlers and flavor houses. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified extracts from conventional natural grades and synthetic alternatives. Cost compression in artificial vanillin substitutes is intensifying because guaiacol and lignin feedstock markets swing with pulp mill capacity. Food service seasoning blend manufacturers exhibit highest price sensitivity, while premium beverage innovators in the Pacific Northwest demonstrate lowest sensitivity when botanical documentation is guaranteed.
Supply Chain Analysis
USDA organic certification requirements and California agricultural concentration are reshaping sourcing patterns toward verified domestic feedstock networks. Botanical extraction infrastructure draws from the United States, Mexico, and Canada, with volatile aromatic compound supply tethered to Fresno-Salinas agricultural clusters, Quebec dairy processing corridors, and northern Mexico industrial zones. Guaiacol, lignin derivatives, and nucleotide salts constitute critical input dependencies. Single-source vulnerability concentrates around California's 200-mile extraction radius. Distribution runs through direct-to-manufacturer contracts for multinational bottlers and food service distributors for restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America food flavor and enhancer market operates as a vertical-integration race, with players pursuing upstream control over agricultural feedstock sourcing to defend margin position against biotech-derived molecule competitors.
For Market Incumbents: Anticipate precision fermentation platforms displacing conventional extraction volumes in dairy taste solutions by securing Health Canada parallel dossier capabilities ahead of FDA synchronization. Kerry Group's backward integration into dairy and meat taste solutions demonstrates the defensive value of upstream control over protein-derived peptide supply. Incumbents must add extraction capacity in Quebec to preempt Canadian-first positioning by fermentation specialists.
For New Entrants and Emerging Players: Direct-to-foodservice digital channels offer the most penetrable route for granular umami nucleotide salt suppliers seeking to bypass traditional distribution tiers. Quebec's underserved cheese and yogurt applications present white-space opportunity given Health Canada's distinct regulatory pathway. Food service procurement platforms enable rapid back-of-house seasoning blend deployment without legacy distributor relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precision fermentation specialists with IRA bio-based manufacturing credit access in the US Midwest and Pacific Northwest. Long-term viability centers on hybrid supply models bridging biotech platforms with botanical certification documentation. Watch FDA-Health Canada regulatory synchronization timelines as the inflection signal for platform consolidation versus extraction infrastructure premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstock | Captures botanical provenance documentation required by California beverage innovators for premium positioning. |
| Parallel Regulatory Dossier Capabilities | Toronto and Montreal facilities secure first-mover positioning under Health Canada's distinct Food and Drug Regulations. |
| Precision Fermentation Scale-Up | IRA bio-based manufacturing credits enable cost-competitive natural-identical molecules against extraction-based supply. |
| Direct-to-Foodservice Channel Development | Restaurant chain back-of-house granular format deployment bypasses traditional distribution margin extraction. |
| Clean-Label Certification Investment | USDA organic thresholds for K-12 institutional channels pull certified flavor inputs into defensible premium tiers. |
Research Methodology
Document review covered FDA GRAS notification databases, Health Canada Food and Drug Regulations guidance, and USDA organic certification standards, complemented by interviews with flavor house R&D directors, beverage procurement executives, dairy processing technical leads, and food service distribution channel managers. Secondary validation drew from customs trade data, SEC filings of publicly traded flavor houses, and industry association reports. Bottom-up volume modeling and top-down value triangulation cross-checked segment estimates.
Segment-level outputs across product type, application, end user, and form dimensions were generated over the projection horizon. CAGRs were derived from regression analysis against macroeconomic indicators and industry-specific drivers including clean-label procurement thresholds, precision fermentation platform adoption rates, and cross-border regulatory harmonization progress. Heat stability technical ceilings and botanical supply concentration patterns informed bakery and beverage application forecasts respectively.
Inputs from regulatory filing databases and flavor house technical documentation were available through the study window; gaps in real-time procurement contract terms and precision fermentation facility utilization rates introduce uncertainty bands around volume concentration estimates. Forecasts reflect documented assumptions regarding FDA-Health Canada regulatory synchronization timelines and IRA credit program continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
South Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Asia-Pacific Feed Palatability Enhancers Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Lignans Market
Food Enhancers and Additives
United States Water Enhancer Market
Food Enhancers and Additives
Europe Food Flavor and Enhancer Market
Food Enhancers and Additives
Browning Enhancers Market
Food Enhancers and Additives
Yellow Fats Market
Food Enhancers and Additives
Australia Food Flavor and Enhancer Market
Food Enhancers and Additives
High Ratio Shortening Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Veratrole Market