
 Lignans Market | 2026-2036
Lignans Market Size, Share, and Industry Trends Forecast 2026-2036
Lignans Market Analysis
Modular dosing formats in lignan supplements is hardening as the dominant packaging configuration, with single-serve sachets and blister-pack strips displacing bulk powder jars across European pharmacy channels. Biogin leverages its extraction technology leadership to supply standardized secoisolariciresinol diglucoside to German pharmaceutical contract manufacturers. Prairie Tide Diversified anchors North American supply through vertically integrated flaxseed cultivation in Saskatchewan. ADM competes on manufacturing scale, operating multi-ton extraction capacity that feeds into both human nutraceutical and animal nutrition formulations.
Lignans constitute a class of diphenolic compounds derived from phenylpropanoid metabolism, occurring predominantly as glycosidic conjugates in flaxseed hulls and sesame seeds with molecular weights typically ranging from 358 to 686 daltons depending on substitution patterns; their primary commercial purpose centers on phytoestrogenic activity modulation for applications in hormone-dependent health conditions and oxidative stress management. Secoisolariciresinol dominates volume throughput due to its abundance in flaxseed and established analytical standardization, while pinoresinol from sesame sources occupies a narrower but higher-margin niche in cosmeceutical formulations. The food supplement application channel sustains the broadest revenue base, though pharmaceutical-grade specifications are capturing expanding margin pools as clinical validation accumulates for lignan intervention in prostate and breast health protocols.
EFSA maintains stringent Novel Food safety assessment pathways for lignan concentrates entering EU commerce, while the FDA oversees GRAS self-affirmation processes that determine US market access timelines for new extraction methodologies. Germany's BfR issues specific intake guidance for lignan-containing supplements that directly shapes maximum-per-serving formulations across the bloc. Stakeholders must monitor evolving pharmacovigilance requirements for botanical estrogen modulators as regulatory divergence between European precautionary frameworks and US notification-based systems creates compliance complexity for multi-territory product strategies.
Market Dynamics
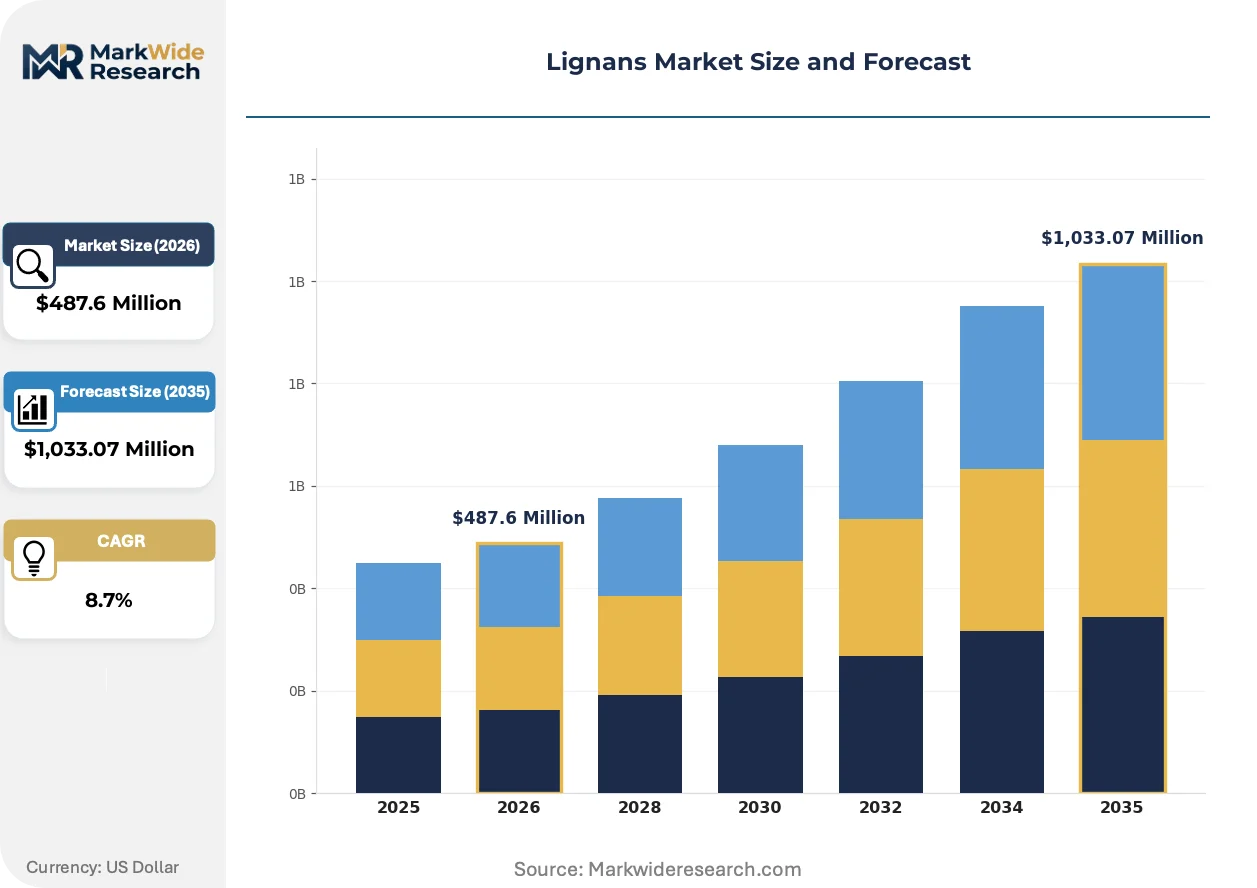
Pharmaceutical formulators are driving lignan demand into menopausal health and oncology adjuvant protocols, while EFSA's tightening Novel Food purity benchmarks force extraction technology upgrades across European supply chains.
Growth Catalysts
- EFSA Novel Food assessments:The European regulator's health claim validation pathway creates premium positioning for standardized secoisolariciresinol diglucoside, rewarding compliant suppliers with pharmacy channel access.
- Menopausal health protocols:Clinicians in Germany and Scandinavia are expanding lignan prescriptions for hormone modulation, building volume throughput in pharmaceutical-grade specifications.
- Modular dosing formats:Single-serve sachets and blister-pack strips are displacing bulk powder jars across European pharmacy channels, improving patient adherence and margin capture.
Market Restraints
- Flaxseed supply concentration:Saskatchewan cultivation anchors North American raw material flows, creating geographic single-point vulnerability for secoisolariciresinol production.
- GRAS affirmation timelines:FDA notification-based approval for new extraction methodologies extends US market entry by 18-24 months versus European equivalents.
- Sesame-derived pinoresinol cost structure:Limited sesame hull availability and complex glycoside hydrolysis requirements constrain cosmeceutical-grade supply expansion.
Strategic Opportunities
- Animal nutrition formulations:Lignan incorporation into ruminant feed for methane reduction aligns with EU Green Deal agricultural targets, opening industrial-scale volume pools.
- Pharmaceutical-grade specifications:Clinical validation accumulation for prostate and breast health interventions enables prescription-channel pricing premiums.
- Cosmeceutical pinoresinol:Sesame-derived lignans command higher margins in topical antioxidant applications, with Japanese and South Korean beauty markets showing formulation interest.
Industry Challenges
- Pharmacovigilance expertise gaps:Botanical estrogen modulators require specialized toxicology assessment capabilities that contract research organizations struggle to staff.
- Multi-territory compliance complexity:Divergent European precautionary frameworks and US notification-based systems force duplicate dossier preparation for identical extraction methodologies.
- Analytical standardization delays:Reference material scarcity for minor lignan glycosides slows method validation for novel concentrate specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lignans Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Secoisolariciresinol, Pinoresinol, Lariciresinol, Matairesinol Source: Flaxseed, Sesame Seed, Whole Grains, Berries Application: Food Supplement, Cosmetics, Pharmaceuticals, Animal Feed Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Shops |
| Companies Covered | Biogin, Prairie Tide Diversified, Hunan NutraMax, Hebei Xinqidian Biotechnology, ADM, TSKG Products, Zebrago Herb, Plamed, Skuny Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lignans Market Emerging Trajectories
Supercritical CO2 extraction systems are reshaping lignan manufacturing economics, while modular bioprocessing units enable distributed production closer to flaxseed cultivation clusters.
Supercritical fluid extraction technology is integrating into commercial lignan production, replacing solvent-based methods with tunable pressure-temperature parameters that preserve glycoside integrity. German pharmaceutical contract manufacturers are adopting these systems to meet EFSA residual solvent limits. The technology is integrating food-grade and pharmaceutical-grade output from shared infrastructure, compressing capital requirements for multi-segment suppliers.
EFSA's evolving Novel Food safety assessment pathways now mandate extended subchronic toxicity studies for lignan concentrates exceeding 50% purity. This regulatory tightening favors established extractors with dedicated toxicology dossiers while excluding smaller suppliers from premium pharmacy channels. German formulators are responding by consolidating supplier relationships around BfR-compliant secoisolariciresinol sources.
Single-serve packaging configurations are displacing bulk formats across European pharmacy and direct-to-consumer channels. German consumers prefer blister-pack strips for travel convenience, while Nordic markets favor sachets for powder-to-liquid preparation. This shift concentrates procurement power with packaging-integrated contract manufacturers in Hamburg and Copenhagen.
Lignans Market Segmentation
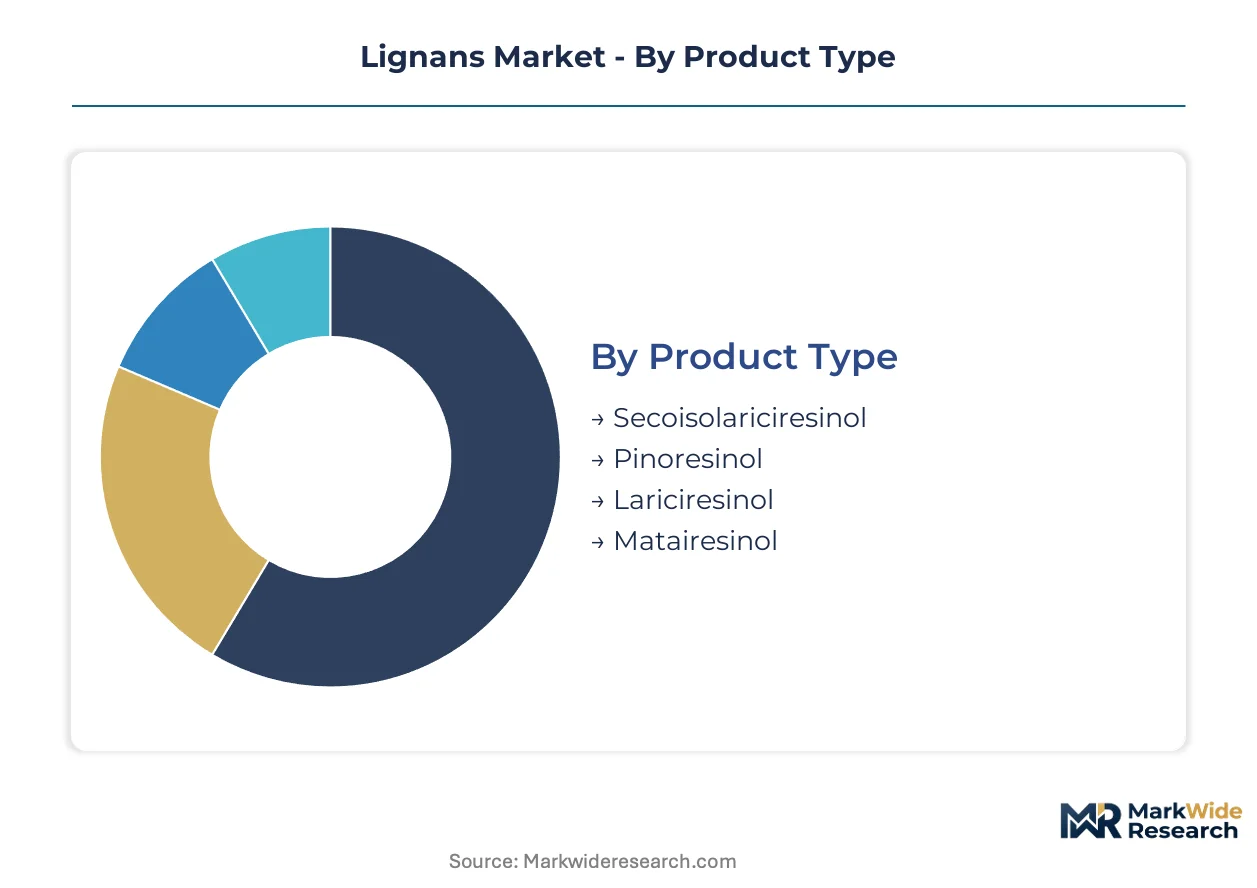
Lignan market segmentation reveals distinct capital requirements across extraction technologies and purity grades. Pharmaceutical-grade specifications demand substantially higher upfront investment than food supplement or animal feed categories.
Product Type:
Capital intensity varies sharply across lignan molecular classes, with glycoside hydrolysis and chromatographic purification driving differential equipment spend.
- Secoisolariciresinol:Flaxseed-derived diglucoside dominates commercial throughput due to established analytical standardization and EFSA-validated health claim pathways. German pharmaceutical contract manufacturers concentrate procurement here, drawn by BfR-compliant intake guidance and pharmacy channel access.
- Pinoresinol:Sesame seed extraction requires complex glycoside hydrolysis and yields lower volumes, positioning this lignan for cosmeceutical applications in Japanese and South Korean beauty markets where antioxidant premiums offset higher production costs.
- Lariciresinol:Minor flaxseed constituent with limited reference material availability constraining method validation for novel concentrate specifications.
- Matairesinol:Gut microbiota metabolite of secoisolariciresinol with emerging analytical interest but minimal dedicated extraction infrastructure.
Secoisolariciresinol absorbs the bulk of installed capacity; pinoresinol is expanding most quickly.
Source:
Raw material geography determines supply security and extraction methodology selection, with cultivation concentration creating divergent risk profiles.
- Flaxseed:Saskatchewan cultivation anchors North American secoisolariciresinol flows. Prairie Tide Diversified maintains vertically integrated control from seed to extract, insulating against commodity price volatility.
- Sesame Seed:Limited hull availability and geographic cultivation dispersion constrain pinoresinol scale-up, restricting supply to premium cosmetic and pharmaceutical niches.
- Whole Grains:Lower lignan concentration versus oilseeds elevates processing volumes required for equivalent extract yield, marginalizing this source outside co-product recovery economics.
- Berries:Lariciresinol and matairesinol presence in trace quantities renders commercial extraction uneconomical without valorization of anthocyanin and polyphenol co-streams.
Flaxseed commands the deepest supplier integration; sesame seed is gaining formulation interest fastest.
Application:
End-use specifications stratify across purity tiers, with pharmaceutical and food supplement channels imposing divergent certification burdens.
- Food Supplement:Broadest revenue base sustained by modular dosing formats—single-serve sachets and blister-pack strips displacing bulk powder jars across European pharmacy channels. EFSA Novel Food assessments reward compliant suppliers with premium positioning.
- Pharmaceuticals:Menopausal health and oncology adjuvant protocols in Germany and Scandinavia drive prescription-channel volume. Clinical validation accumulation for prostate and breast health interventions enables pricing premiums over nutraceutical grades.
- Cosmetics:Sesame-derived pinoresinol serves topical antioxidant formulations, with supercritical CO2 extraction meeting residual solvent limits for dermal application.
- Animal Feed:Ruminant methane reduction applications align with EU Green Deal agricultural targets, opening industrial-scale volume pools distinct from human-grade specifications.
Food supplement applications absorb the bulk of installed capacity; pharmaceuticals are climbing the fastest.
Distribution Channel:
Channel selection determines packaging configuration and margin capture, with pharmacy integration requiring distinct logistics infrastructure.
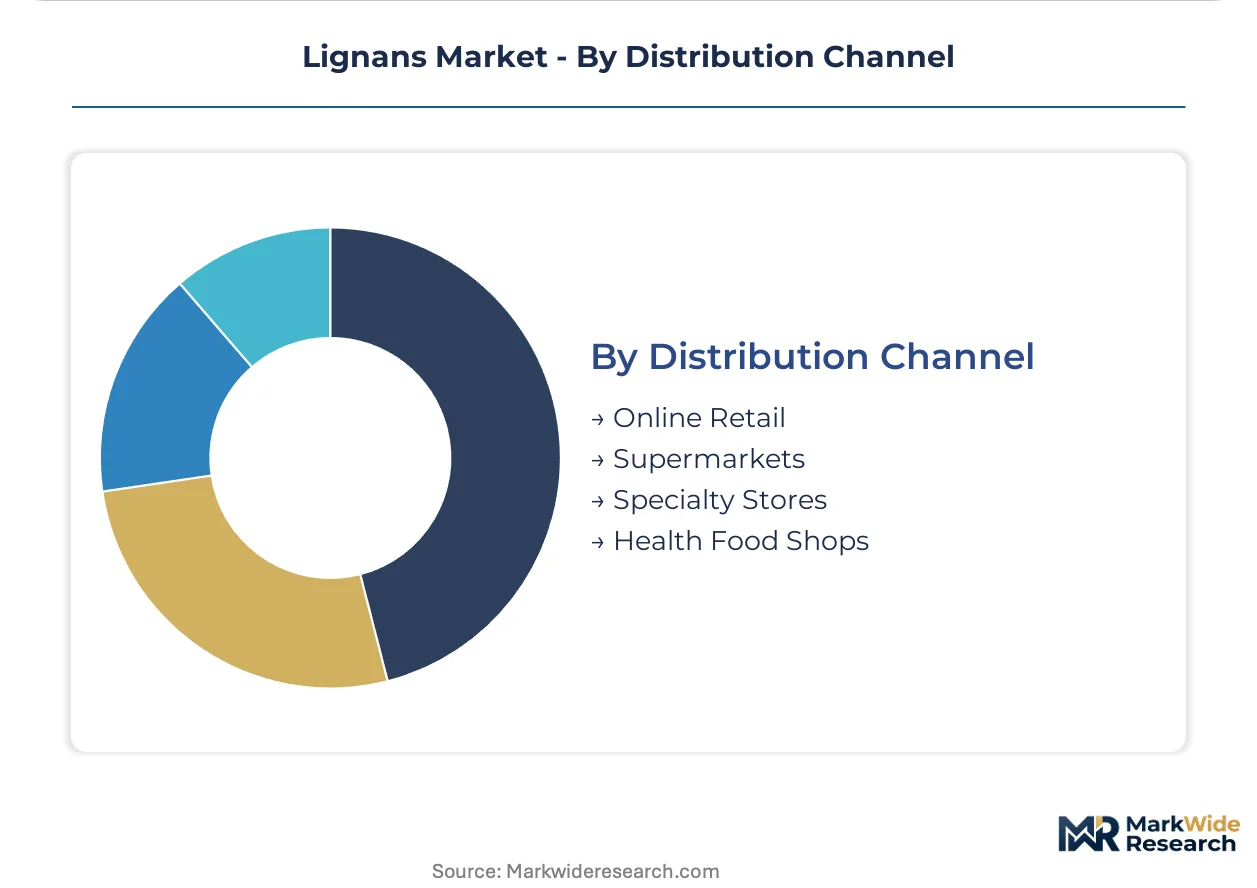
- Specialty Stores:German pharmacy chains consolidate procurement around BfR-compliant secoisolariciresinol sources, with Hamburg and Copenhagen packaging-integrated contract manufacturers capturing value from blister-pack and sachet formats.
- Online Retail:Direct-to-consumer channels favor bulk powder and capsule formats with lower packaging cost ratios, though Nordic markets show rising sachet preference for powder-to-liquid preparation convenience.
- Health Food Shops:Independent retail maintains relevance for flaxseed-derived whole food products and unstandardized hull powders outside pharmaceutical-grade specifications.
- Supermarkets:Mass-market penetration limited by consumer education requirements and price positioning against established phytoestrogen alternatives.
Specialty stores absorb the bulk of installed capacity; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saskatchewan's designated agricultural processing zones concentrate North American lignan extraction capacity, while Germany's Bioeconomy Cluster Mittelhessen anchors European pharmaceutical-grade production.
United States
FDA GRAS self-affirmation processes govern market entry timelines for novel extraction methodologies. The agency's notification-based system extends approval cycles by 18-24 months versus European equivalents. Chicago-based contract manufacturers serve nutraceutical formulators seeking rapid product iteration outside pharmaceutical-grade specifications.
Germany
BfR intake guidance for lignan-containing supplements directly shapes maximum-per-serving formulations across the European bloc. EFSA's Novel Food safety assessments mandate extended subchronic toxicity studies for concentrates exceeding 50% purity. Hamburg packaging-integrated contract manufacturers capture value from blister-pack strip formats displacing bulk powder jars.
China
NMPA oversight of botanical extract imports creates dual registration requirements for domestic and export-facing production lines. The country's national food safety regulator maintains separate dossier standards for novel food ingredients versus traditional medicinal substances. Shandong Province extraction clusters supply standardized secoisolariciresinol diglucoside to German pharmaceutical contract manufacturers.
Japan
METI's positioning of functional foods within national health policy drives lignan incorporation into Foods for Specified Health Uses. The Ministry of Health, Labour and Welfare maintains distinct approval pathways for intestinal health claims versus antioxidant positioning. Osaka-based formulators source sesame-derived pinoresinol for cosmeceutical applications targeting domestic beauty markets.
Canada
Health Canada's Natural and Non-prescription Health Products Directorate oversees site licensing for lignan extraction facilities supplying cross-border flows. The regulator's Good Manufacturing Practices inspection regime aligns with US FDA standards, enabling integrated North American supply strategies. Prairie Provinces cultivation clusters anchor vertically integrated flaxseed-to-extract operations serving pharmaceutical-grade specifications.
Lignans Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across lignan extraction tiers. The supplier base stratifies between multi-ton manufacturing scale operators and boutique glycoside purification houses. Three archetypes dominate: agricultural processors with captive seed supply, pharmaceutical contract manufacturers with EFSA-compliant dossiers, and distributed bioprocessing units near cultivation clusters. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with supercritical CO2 technology licensing accelerating consolidation around compliant extraction infrastructure.
Within the pharmaceutical-grade tier, Biogin and ADM occupy positions representing divergent scale strategies. Biogin anchors European supply through extraction technology leadership serving German contract manufacturers. ADM exemplifies manufacturing scale operations with multi-ton capacity feeding human nutraceutical and animal nutrition channels. Prairie Tide Diversified sits within the agricultural integration archetype, maintaining upstream control over Saskatchewan flaxseed cultivation.
| Leading Market Players |
|---|
| Biogin |
| Prairie Tide Diversified |
| Hunan NutraMax |
| Hebei Xinqidian Biotechnology |
| ADM |
| TSKG Products |
| Zebrago Herb |
| Plamed |
| Skuny Bioscience |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade toxicology dossier specialists in Hamburg and Copenhagen command wage premiums that compress margin spreads between food supplement and pharmaceutical-grade lignan tiers. Labor-cost differentials between EFSA-compliant extraction facilities and standard nutraceutical operations widen pricing spreads as Novel Food assessment requirements harden.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with pharmacy-channel premiums while spot inventory from non-compliant suppliers trades at discounts. Pharmaceutical-grade secoisolariciresinol diglucoside commands three-tier pricing structure across premium, standard, and economy levels based on EFSA dossier completeness and BfR intake guidance alignment. Pricing pressure stems from supercritical CO2 equipment amortization costs compressing mid-tier margins. Contract manufacturers show highest price sensitivity; German pharmaceutical formulators demonstrate lowest sensitivity given prescription-channel pricing power.
Supply Chain Analysis
EFSA Novel Food certification gates pharmacy-channel access, concentrating qualified supply among German and Danish extraction facilities with dedicated toxicology capabilities. Raw material flows draw from Saskatchewan flaxseed cultivation, Shandong Province processing clusters, and dispersed sesame hull sources across East Asia. Supply chain risk centers on single-source vulnerability in secoisolariciresinol feedstock from prairie cultivation zones. Distribution runs through Hamburg and Copenhagen packaging-integrated contract manufacturers serving European pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained extraction story where EFSA-compliant supercritical CO2 capacity bottlenecks prop pharmaceutical-grade pricing premiums. Qualified manufacturing slots carry 18-24 month backlogs.
For Market Incumbents: Cement pharmacy-channel relationships through BfR-aligned intake guidance formulations and dedicated toxicology dossier maintenance. Lock in Saskatchewan flaxseed offtake through cultivation partnerships before Prairie Tide Diversified expands vertical control. Capacity addition in Mittelhessen bioprocessing clusters counters emerging Chinese extraction scale. For New Entrants and Emerging Players: Supercritical CO2 technology licensing offers entry wedge into EFSA-compliant supply tiers currently dominated by Biogin and ADM. Animal nutrition formulations for EU Green Deal methane reduction targets represent the most penetrable white-space segment. Direct-to-consumer sachet formats in Nordic markets provide go-to-market angle outside consolidated pharmacy procurement. For Investors and Strategic Acquirers: Re-rating potential sits with agricultural processors possessing captive Saskatchewan seed supply given flaxseed concentration risk and pharmacy-channel pricing power. Long-term viability frames around 5-10 year clinical validation accumulation for oncology adjuvant protocols. Monitor EFSA subchronic toxicity study mandate expansion as inflection signal for compliance-cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Meets EFSA residual solvent limits for pharmaceutical-grade secoisolariciresinol diglucoside output. |
| Backward Integration into Flaxseed Cultivation | Insulates against Saskatchewan commodity volatility and secures pharmacy-channel supply commitments. |
| Novel Food Dossier Investment | Unlocks premium positioning in German pharmacy chains under BfR intake guidance frameworks. |
| Animal Nutrition Formulation Development | Captures EU Green Deal ruminant methane reduction volume pools outside human-grade competition. |
| Modular Packaging Integration | Concentrates procurement power with Hamburg and Copenhagen contract manufacturers serving blister-pack demand. |
Methodological Framework
Document review covered EFSA Novel Food safety assessments, FDA GRAS notifications, BfR intake guidance documents, and customs trade data, complemented by interviews with extraction technology directors, pharmaceutical contract manufacturing procurement leads, regulatory affairs specialists at botanical extract importers, and flaxseed cultivation operations managers. Secondary validation drew from Health Canada site licensing records, NMPA import registration databases, and EU Green Deal agricultural policy filings. Bottom-up capacity modeling triangulated against top-down pharmacy channel volume estimates.
Cross-referencing historical extraction capacity buildouts against expert panel input on supercritical CO2 adoption timelines anchored the analytical framework. Segmentation modeling spanned lignan molecular class, purity grade tier, end-use application, and regional regulatory cluster. CAGRs derived from pharmacy-channel volume trajectories and animal nutrition penetration curves. Forecast inputs incorporated EFSA toxicity study mandate evolution and Saskatchewan cultivation yield variability.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA Novel Food assessment pathway acceleration or Saskatchewan climate disruption. Model outputs reflect assumptions on clinical validation accumulation for menopausal health protocols and pharmacy-channel pricing power sustainability. A model refresh is warranted upon material change in German BfR intake guidance or EFSA subchronic toxicity purity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
Italy Anti-Caking Market
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market
Food Enhancers and Additives
Brazzein Market
Food Enhancers and Additives
Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Feed Palatability Enhancers Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
United Kingdom Interesterified Fats Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
Germany Water Enhancer Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market