
 Europe Food Flavor and Enhancer Market | 2026-2036
Europe Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Flavor and Enhancer Market Foresight
Flavor chemist shortages across Western Europe is redrawing competitive boundaries for specialty ingredient suppliers. Givaudan leverages its Swiss R&D heritage to sustain leadership in natural extraction technologies. Symrise anchors its position through deep partnerships with German beverage and dairy processors. Kerry Group competes by extending its integrated taste and nutrition platform across multiple European production sites.
Europe food flavor and enhancer products comprise volatile aromatic compounds, taste-active molecules, and savory nucleotides formulated at precise concentrations measured in parts per million to modify or intensify sensory perception in processed foods. These formulations serve industrial food manufacturers seeking to standardize taste profiles across high-volume production runs while meeting clean-label expectations. Natural flavors now command premium positioning as reformulation investments shift away from artificial alternatives under consumer and retailer pressure. Beverage applications show the fastest structural expansion, particularly in functional and low-sugar drinks where masking technologies prove critical. Powder forms dominate manufacturing efficiency for bakery and snack producers, while liquid formats retain importance in dairy processing lines.
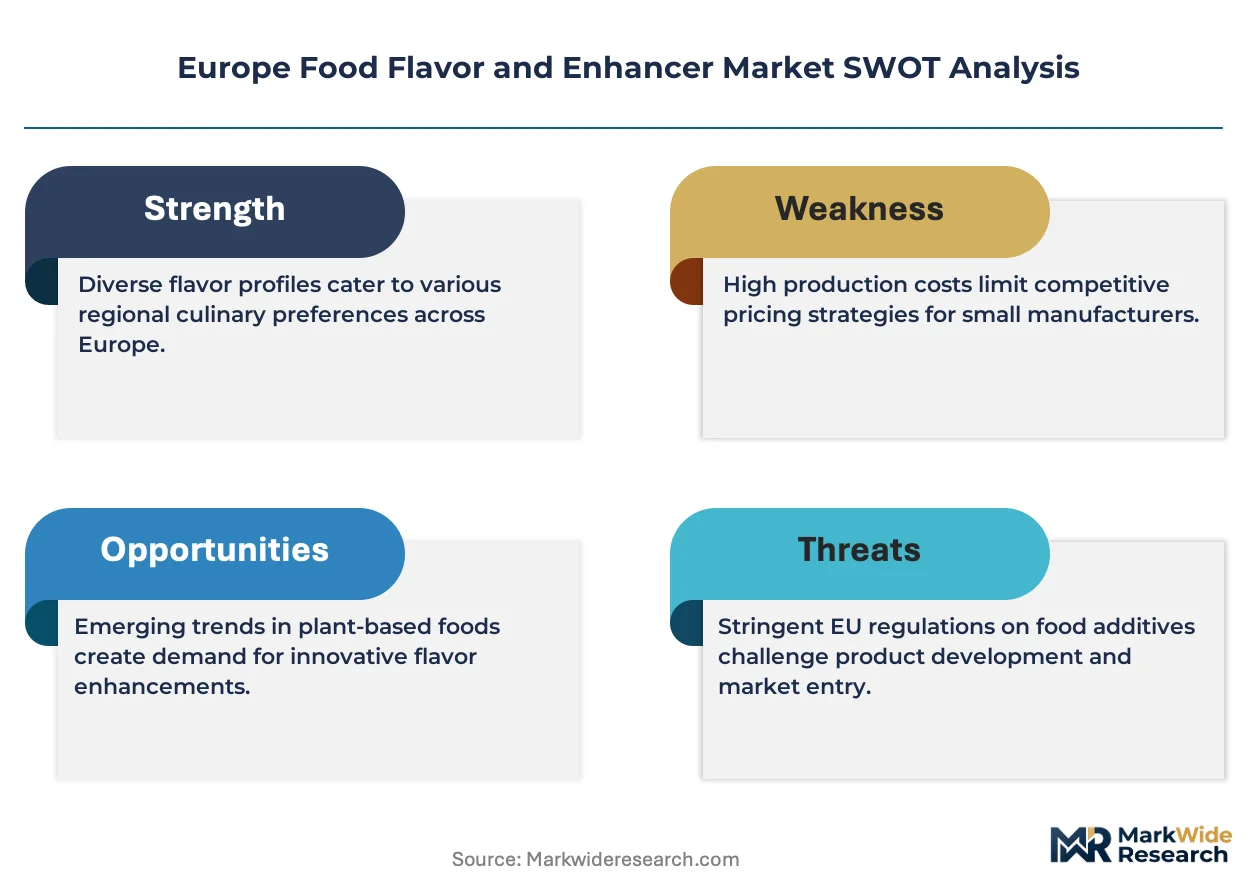
EFSA safety evaluations and EU Flavouring Regulation 1334/2008 govern which substances enter the European food supply, directly constraining innovation pipelines and reformulation timelines for suppliers. REACH chemical registration requirements and the EU Green Deal sustainability disclosures add compliance layers that favor larger players with dedicated regulatory affairs teams. Stakeholders must monitor EFSA's ongoing re-evaluations of authorized flavoring substances, as delistings could force rapid portfolio restructuring across the supplier base.
Market Dynamics
EU Green Deal sustainability disclosures and Farm to Fork Strategy mandates are forcing European food manufacturers to reformulate entire product portfolios, compressing supplier timelines and redrawing sourcing relationships across the flavor value chain.
Growth Catalysts
- Plant-based meat alternatives:European processors are accelerating clean-label flavor investments to mask off-notes in pea and soy protein bases, creating specialized extraction demand.
- REACH chemical registration:The centralized EU framework streamlines cross-border ingredient approvals, reducing regulatory fragmentation for compliant suppliers.
- Beverage masking technologies:Functional and low-sugar drink manufacturers in Germany and France require advanced bitter-blocking solutions to maintain palatability.
Market Restraints
- Natural vanilla supply concentration:Madagascar and Ugandan crop volatility exposes European formulators to price spikes and sourcing interruptions.
- Flavor chemist talent scarcity:Western European universities produce insufficient qualified synthetic and natural extraction specialists.
- EFSA re-evaluation cycles:Ongoing safety reviews of authorized substances force suppliers to maintain parallel formulation pipelines for delisting scenarios.
Strategic Opportunities
- Netherlands biotech clusters:Wageningen University partnerships enable precision fermentation for rare flavor molecules at industrial scale.
- CSRD sustainability reporting:Mandatory Scope 3 disclosures incentivize food manufacturers to source from verified low-carbon flavor suppliers.
- Direct-to-manufacturer digital platforms:Specialty ingredient marketplaces are bypassing traditional distribution layers for mid-sized European processors.
Industry Challenges
- Cross-facility formulation standardization:Multi-site European manufacturers struggle to replicate taste profiles across production lines with varying equipment ages.
- Natural certification timeline compression:EU organic and natural claim verifications extend new product launch windows by 8-14 months.
- Legacy dairy processing integration:Liquid flavor dosing systems require retrofitting for powder-compatible clean-in-place protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Flavor and Enhancer Market |
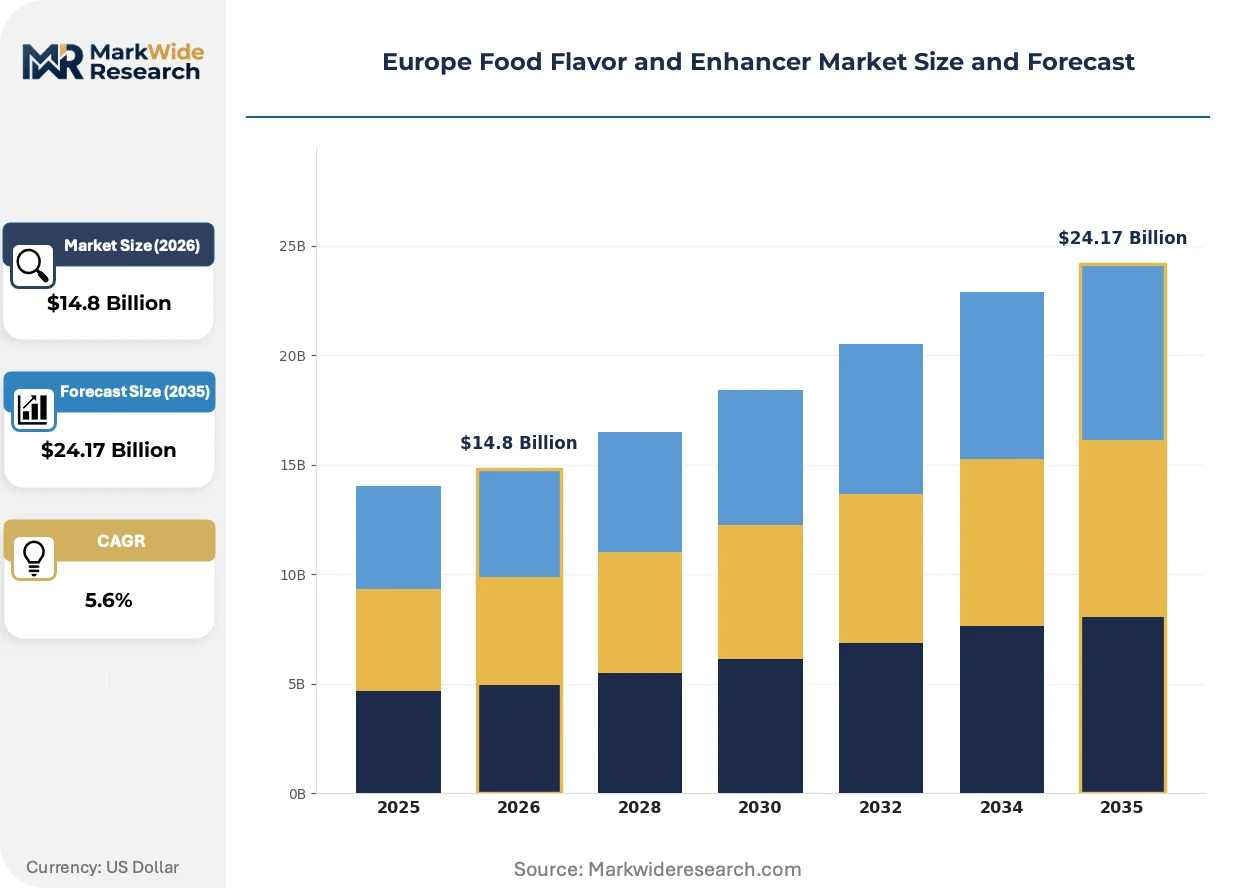
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Flavor Enhancers, Seasonings Application: Beverages, Bakery Products, Dairy Products, Snacks Form: Liquid, Powder, Granular, Paste Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Foodservice |
| Companies Covered | International Flavors & Fragrances, Symrise, Givaudan, European Flavours and Fragrances, DSM-Firmenich, Firmenich, Kerry Group, Bell Flavors & Fragrances, BASF, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Flavor and Enhancer Market Shifts & Advancements
Biotechnology-enabled flavor production and regulatory disclosure requirements are converging to transform how European suppliers design, manufacture, and validate their ingredient portfolios for food processors.
Precision fermentation for rare terpenes and lactones is decomposing traditional agricultural dependency for high-value flavor molecules. Dutch and Danish biotechnology firms are scaling production of heat-stable vanillin and citrus notes without crop cultivation. This technology is decomposing price premiums historically attached to natural-extraction scarcity.
EU Flavouring Regulation 1334/2008 amendment proposals are tightening maximum concentration limits for certain pyrazine and sulfur-containing compounds in savory applications. Food manufacturers face accelerated reformulation costs to maintain product registrations. Snack and ready-meal segments in Germany and Poland are pre-emptively reducing reliance on affected substances.
Clean-label procurement committees at major European retailers now mandate full supply chain disclosure from flavor suppliers, including solvent types and geographic origin of starting materials. This specification cascade forces ingredient houses to document extraction methods previously considered proprietary. French and British supermarket chains are most advanced in enforcing these transparency protocols.
Europe Food Flavor and Enhancer Market Segmentation
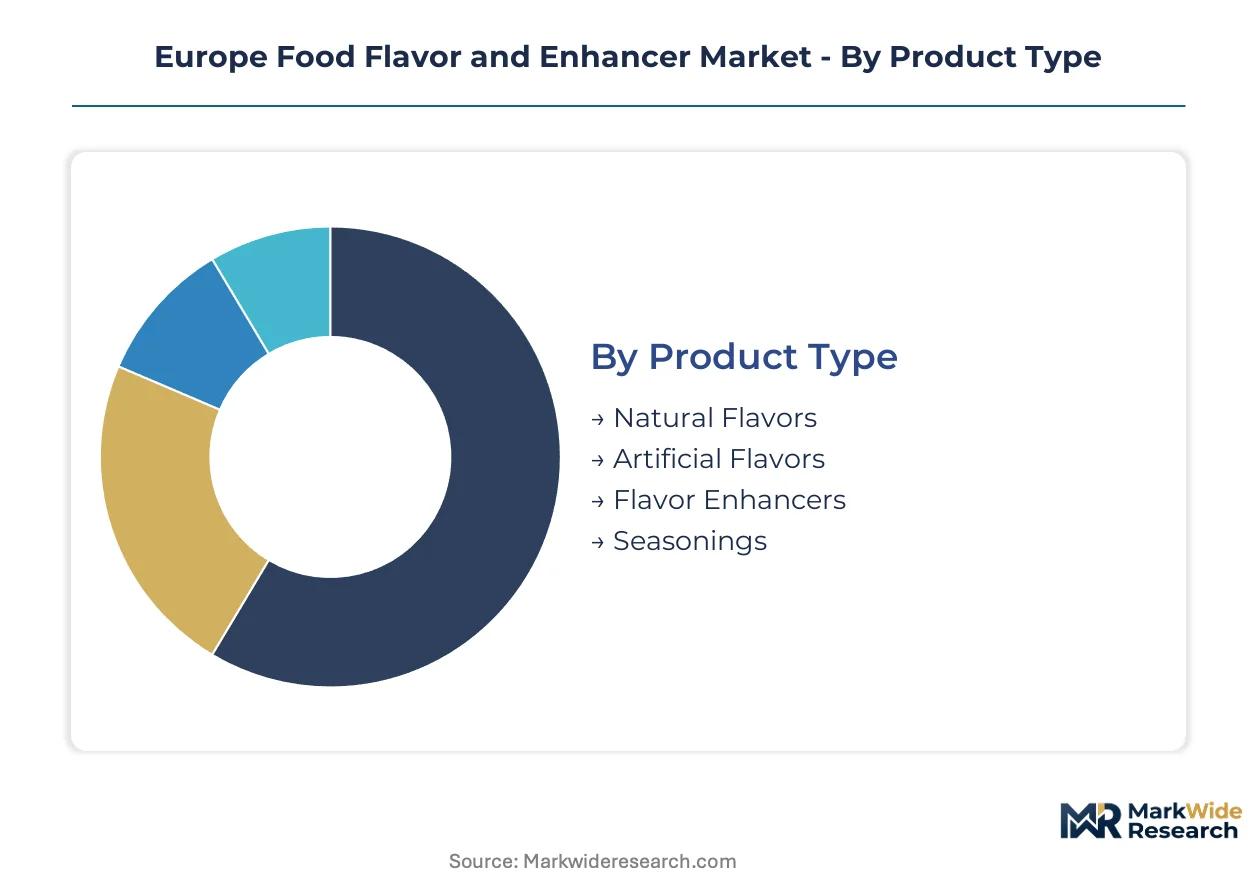
European food manufacturers source flavor inputs through distinct procurement channels that shape supplier relationships and technical specifications. Each segmentation dimension reveals where formulation investments concentrate and which delivery formats align with processing infrastructure.
Product Type:
Natural flavors flow predominantly through direct supplier-manufacturer partnerships, while artificial alternatives and enhancers move through broader distribution networks serving smaller processors.
- Natural Flavors:Derived from plant, animal, or microbial sources through extraction, distillation, or fermentation. German and French beverage manufacturers drive premium extraction demand as clean-label commitments harden across retail chains. EFSA authorization timelines and organic certification requirements extend procurement cycles.
- Artificial Flavors:Synthetically produced aromatic compounds formulated to replicate natural taste profiles at lower cost. Eastern European snack and confectionery producers maintain volume demand despite retail pressure for natural claims.
- Flavor Enhancers:Glutamates, nucleotides, and yeast extracts that amplify existing taste perception without adding distinct flavor notes. Savory applications in Dutch and Polish ready-meal manufacturing anchor consumption.
- Seasonings:Blended spice and flavor preparations incorporating salt carriers and anti-caking agents. Foodservice distributors and industrial meat processors in Spain and Italy represent primary offtake channels.
Natural flavors dominate installed base value. Flavor enhancers are where expansion concentrates as umami-rich product development accelerates.
Application:
Cost tier stratification separates commodity formulations from premium positioning, with masking technologies commanding substantial price premiums in functional beverage segments.
- Beverages:Liquid and emulsion concentrates designed for dissolution stability in aqueous systems. German functional drink manufacturers and French mineral water processors invest heavily in bitter-masking solutions for reduced-sugar lines. Precision dosing equipment requirements favor established supplier relationships.
- Bakery Products:Heat-stable encapsulated flavors resisting thermal degradation during oven processing. Powder formats dominate manufacturing efficiency across automated mixing lines in Belgian and Dutch industrial bakeries.
- Dairy Products:Fat-compatible flavor systems dispersing uniformly in milk matrices. Italian cheese and yogurt processors maintain steady demand for fruit and vanilla profiles despite seasonal variation.
- Snacks:Surface-applied seasoning systems adhering to fried or baked substrates. Seasoning tumble drums and oil-spray application equipment in British and German snack facilities dictate powder and granular format preferences.
Beverages command the steepest expansion trajectory as functional drink portfolios multiply. Bakery products retain the largest established volume base.
Form:
Volume throughput and clean-in-place protocol compatibility determine format selection across European processing facilities of varying equipment vintage.
- Liquid:Pumpable concentrates and emulsions suited to continuous dosing in beverage and dairy processing lines. French and German liquid flavor houses maintain dedicated tanker delivery fleets for large-account service.
- Powder:Spray-dried or plated formulations offering extended shelf stability and automated handling. Dutch and British bakery and snack manufacturers prioritize powder compatibility with pneumatic conveying systems.
- Granular:Agglomerated particles reducing dust generation and improving flow properties. Seasoning applications in meat processing and foodservice distribution favor granular handling characteristics.
- Paste:High-viscosity concentrates for incorporation into doughs, batters, and compound coatings. Italian and Spanish confectionery and bakery specialists source pastes for precise flavor intensity control.
Powder forms dominate installed manufacturing capacity. Liquid formats are where technology investment concentrates as precision dosing systems proliferate.
Distribution Channel:
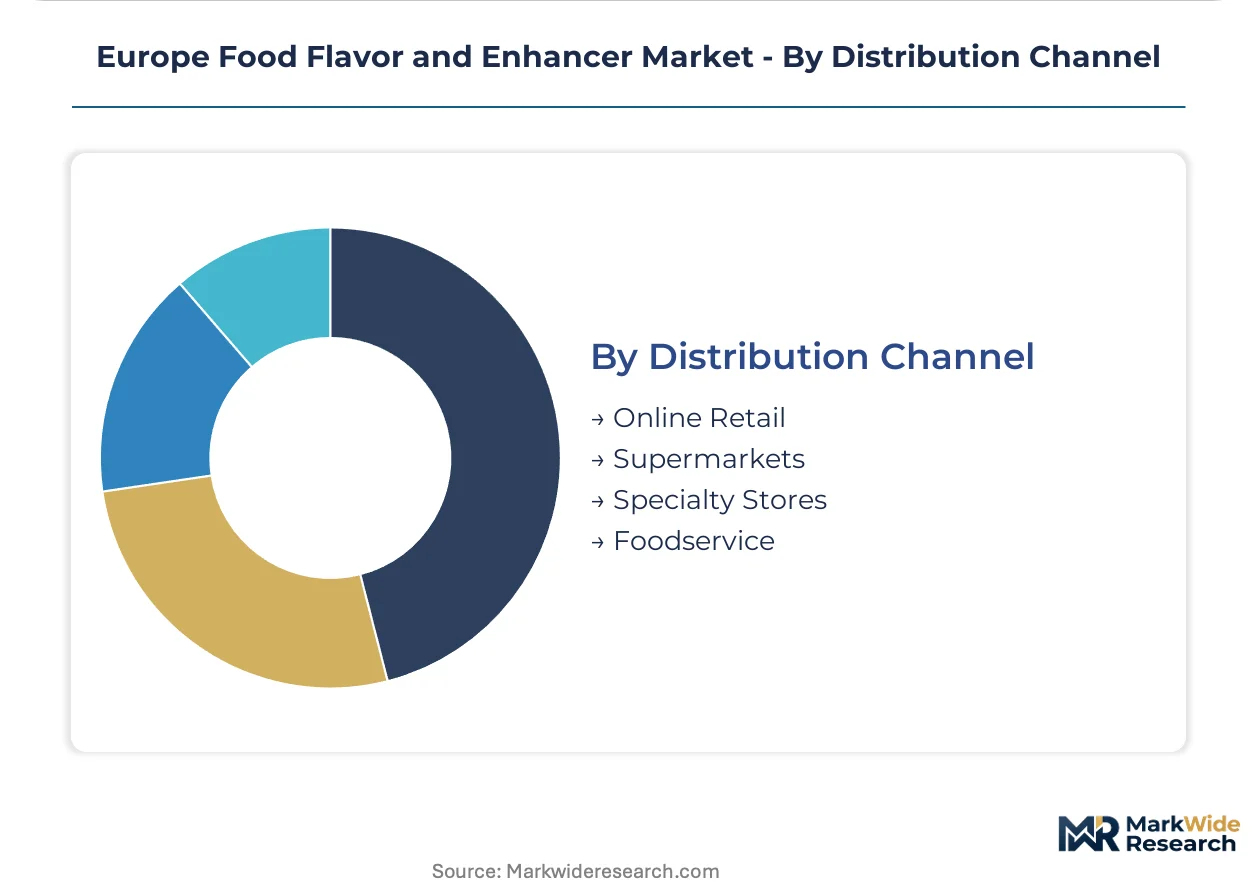
Customer type segmentation separates multinational manufacturers with direct supplier contracts from mid-tier processors purchasing through intermediaries.
- Online Retail:E-commerce platforms serving artisanal food producers and small-batch manufacturers with minimum-order quantities below traditional distributor thresholds. Dutch and German specialty ingredient marketplaces expand geographic reach for regional flavor houses.
- Supermarkets:Retail chains procuring private-label seasonings and flavor systems through centralized buying offices. French and British supermarket technical teams increasingly mandate supply chain transparency documentation.
- Specialty Stores:Independent distributors serving ethnic food manufacturers and traditional processors with customized formulation support. Italian and Spanish regional distributors maintain relationships with family-owned meat and cheese producers.
- Foodservice:Broadline distributors supplying prepared meal manufacturers, restaurant chains, and catering operations with standardized seasoning blends. German and French contract catering consolidation drives volume concentration.
Supermarkets dominate procurement value through private-label concentration. Online retail is where channel experimentation concentrates as digital platforms disintermediate traditional distribution layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German beverage manufacturers drive precision flavor dosing demand while French dairy processors anchor natural extraction requirements, diverging from Dutch and British processors who prioritize powder-format manufacturing efficiency for bakery and snack applications.
Germany
Beverage masking technologies for functional drinks and reduced-sugar lines concentrate procurement spending in Bavaria and North Rhine-Westphalia. The country's national food safety regulator enforces strict additive concentration limits under EU harmonized standards. Cologne and Hamburg host major flavor houses operating dedicated tanker fleets for liquid concentrate delivery to dairy and soft drink facilities.
France
Natural flavor investments for yogurt and cheese applications dominate technical specifications from processors in Île-de-France and Auvergne-Rhône-Alpes. EFSA safety evaluations directly constrain which aromatic compounds receive authorization for dairy matrix incorporation. Paris-based supermarket technical teams mandate supply chain transparency documentation extending to solvent types and geographic origin of starting materials.
Netherlands
Wageningen University partnerships enable precision fermentation scale-up for rare flavor molecules serving plant-based meat alternative manufacturers. The EU Green Deal sustainability disclosure requirements pressure Dutch processors to document Scope 3 emissions from ingredient sourcing. Eindhoven and Rotterdam biotech clusters attract fermentation specialists displacing traditional agricultural extraction dependency.
United Kingdom
Snack seasoning applications and private-label procurement through retail consolidation drive powder-format demand from British manufacturers. British supermarket chains enforce clean-label procurement committees requiring full supply chain disclosure from flavor suppliers. Greater London and Midlands production facilities retrofit liquid dosing systems for powder-compatible clean-in-place protocols.
Italy
High-viscosity paste concentrates for confectionery and traditional bakery applications sustain specialized procurement from family-owned processors in Lombardy and Piedmont. Regional distributors maintain relationships with artisanal meat and cheese producers requiring customized formulation support. Milan and Turin anchor specialty ingredient marketplaces serving small-batch manufacturers below traditional distributor thresholds.
Europe Food Flavor and Enhancer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Swiss and German flavor houses commanding premium positioning through R&D heritage while mid-sized regional suppliers compete on formulation agility and customer proximity. The market structure rewards players with captive extraction capabilities and regulatory affairs teams capable of navigating EFSA authorization timelines. Three archetypes dominate: integrated taste-nutrition platforms, precision fermentation biotechnology firms, and regional specialists with deep vertical relationships in specific applications. Competitive moves concentrate on strategic partnerships with university research clusters and portfolio diversification into masking technologies for plant-based substrates.
Within the integrated leader tier, Givaudan and Symrise exemplify archetypes built on Swiss and German R&D heritage respectively, while Kerry Group occupies a position bridging taste and nutrition integration across multiple production sites. These entities represent the consolidation trajectory reshaping supplier-manufacturer relationships as clean-label mandates harden across European retail chains.
| Leading Market Players |
|---|
| International Flavors & Fragrances |
| Symrise |
| Givaudan |
| European Flavours and Fragrances |
| DSM-Firmenich |
| Firmenich |
| Kerry Group |
| Bell Flavors & Fragrances |
| BASF |
| Others |
Supply & Pricing Matrix
EU Flavouring Regulation 1334/2008 authorization timelines gate both supplier qualification and price stratification across the European flavor value chain, compressing procurement cycles for natural-certified inputs while amplifying premiums for compliant specialty molecules. EFSA safety evaluations and REACH registration requirements simultaneously constrain supply base expansion and validate price positioning for authorized substances.
Pricing Analysis
Long-term offtake agreements dominate procurement between major flavor houses and German beverage manufacturers, insulating volume commitments from Madagascar vanilla crop volatility while spot markets serve smaller Eastern European confectionery processors. Three-tier pricing structure across premium natural-extraction, standard nature-identical, and economy artificial tiers separates clean-label certified inputs from commodity synthetics. Cost compression in standard-tier synthetics is intensifying because Eastern European processors prioritize volume over certification claims. Mid-sized Dutch and Polish ready-meal manufacturers exhibit highest price sensitivity, while French dairy processors anchored in retail private-label chains absorb premium natural extraction costs.
Supply Chain Analysis
Madagascar and Uganda anchor global vanilla bean cultivation, while India and Indonesia concentrate spice extraction for European seasoning applications. Dutch biotechnology clusters and Swiss R&D facilities feed precision-fermentation alternatives decomposing traditional agricultural dependency for high-value terpenes and lactones. Single-source vulnerability in Madagascar vanilla exposes formulators to sourcing interruptions from cyclone damage and political instability. Distribution runs through dedicated tanker fleets for liquid concentrates serving German beverage facilities, with powder-format bulk shipments moving via Rotterdam and Hamburg port clusters to British and Dutch bakery manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation scale-up and EU Green Deal sustainability disclosure mandates are disrupting established extraction economics, creating acquisition opportunities for biotechnology-enabled suppliers capable of bypassing agricultural commodity cycles.
For Market Incumbents: Compound captive fermentation capabilities through Wageningen University partnerships and Danish biotech cluster investments to offset vanilla and citrus extraction dependency. Secure backward integration into rare terpene production before agricultural price spikes erode margin buffers in natural-flavor portfolios. Defend market position by pre-emptively reformulating savory applications ahead of EFSA pyrazine concentration limit amendments. For New Entrants and Emerging Players: Digital procurement platform gaps for mid-sized Italian and Spanish artisanal processors present white-space entry points beneath incumbent minimum-order thresholds. Target Netherlands-based plant-based meat alternative manufacturers requiring specialized off-note masking for pea and soy protein bases. Deploy direct-to-manufacturer sampling programs bypassing traditional distribution layers to capture formulation development relationships early. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision-fermentation sub-segments as Dutch and Danish facilities achieve industrial-scale lactone production. Five-to-ten-year viability favors acquisition targets combining fermentation IP with established EFSA regulatory affairs capabilities. Monitor EFSA re-evaluation delisting announcements as inflection signals forcing rapid portfolio restructuring across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Dutch biotechnology clusters decompose agricultural price volatility for rare flavor molecules. |
| EFSA Pre-Authorization Pipeline | Parallel formulation development buffers against substance delisting scenarios. |
| Direct-to-Manufacturer Digital Platform | Online retail channels bypass distribution layers for mid-sized European processors. |
| University Research Cluster Partnership | Wageningen collaborations accelerate industrial-scale rare terpene production. |
| Scope 3 Emissions Verification | CSRD disclosures incentivize sourcing from verified low-carbon flavor suppliers. |
Research Methodology
Operator-level perspectives from flavor formulation chemists, regulatory affairs directors at major houses, procurement leads at German beverage manufacturers, and Dutch plant-based protein processors anchored the qualitative base. Primary interview insights triangulated against EFSA authorization databases, REACH registration filings, EU customs trade data, and SEC disclosures from listed ingredient suppliers. Bottom-up volume modeling across product type, application, and form segments converged with top-down value validation using macroeconomic indicators.
Sensitivity analysis tested forecast robustness across regulatory delay scenarios, agricultural commodity price shocks, and biotechnology scale-up timelines. Segmentation dimensions modeled include natural versus artificial versus fermented origin, beverage-dairy-bakery-snack application clusters, and liquid-powder-granular format categories. CAGRs derived from segment-level volume trajectories weighted by EFSA authorization status and clean-label procurement intensity. Industry-specific inputs incorporated vanilla crop yield volatility indices and precision-fermentation capacity build-out announcements.
Forecasts assume regulatory continuity in EU Flavouring Regulation 1334/2008 and REACH frameworks; material policy shifts including substance delistings or concentration limit amendments would require re-modeling. Specific risks include EFSA re-evaluation outcomes, Madagascar supply disruptions, and biotechnology scale-up delays. Recalibration cycles align with material shifts in regulatory authorization timelines and agricultural commodity price trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
Fortified Salts Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
Flour Improvers Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market