
 Vegetable Shortening Market | 2026-2036
Vegetable Shortening Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Shortening Market Outlook
Recipe-ready shortening blends with emulsifier packages is expanding as a service layer that locks in bakery customers through formulation consistency guarantees. Cargill, Incorporated leverages its integrated oilseed processing network to control feedstock costs across North American bakery accounts. Bunge Limited anchors South American soybean oil supply into global shortening distribution. Wilmar International Ltd dominates palm-based shortening output from Southeast Asian refineries.
Vegetable shortening is a refined, hydrogenated or interesterified fat derived from plant oils such as soybean, palm, or canola, engineered to achieve specific melting profiles and oxidative stability for high-temperature food processing. Solid shortening leads product type demand in industrial baking for pie crusts and laminated pastries where plastic fat functionality governs flake structure. Emulsified shortening captures margin pools in confectionery coatings where monoglyceride content controls bloom resistance and snap quality.
The U.S. FDA enforces trans-fat disclosure rules that compel reformulation away from partial hydrogenation, while the EU Green Deal and F-Gas Regulation indirectly pressure edible oil processors to decarbonize refinery operations. Indonesia's BIS-aligned national standards and Malaysia's MEE sustainability requirements shape palm oil sourcing protocols for shortening exports. Stakeholders must monitor interesterification capacity buildouts and tropical oil traceability certifications to secure supply positions.
Market Dynamics
Interesterification technology is displacing partial hydrogenation as the dominant fat modification process, driven by FDA trans-fat disclosure mandates that render legacy formulations non-compliant for U.S. retail and foodservice distribution.
Growth Catalysts
- Quick-service bakery chains:Laminated dough applications in quick-service restaurants are scaling procurement of solid shortening with guaranteed plasticity ranges, locking in multi-year supply contracts with reformulated product specifications.
- EU F-Gas Regulation:Refinery decarbonization requirements under the EU Green Deal are accelerating capital deployment into heat-recovery systems at edible oil processing facilities, improving energy efficiency credentials for European shortening exports.
- Interesterification:Enzymatic and chemical interesterification processes are achieving equivalent functionality to partially hydrogenated fats without trans-fat generation, enabling clean-label positioning in North American retail channels.
Market Restraints
- Palm oil price volatility:Indonesian and Malaysian crude palm oil supply fluctuations transmit directly into industrial shortening input costs, compressing margin predictability for regional food manufacturers dependent on tropical feedstocks.
- Refinery concentration:Southeast Asian palm oil refining capacity concentrates in Johor and Riau provinces, creating single-source vulnerability for shortening exporters serving ASEAN bakery and confectionery markets.
- Butter and lard substitution:Clean-label bakery segments in Western Europe are reverting to animal fats where supply chain traceability exceeds vegetable shortening certification complexity, eroding share in premium positioned applications.
Strategic Opportunities
- Vietnam bakery sector:Industrial bread and pastry production in Vietnam remains underpenetrated by formulated shortening suppliers, with local mills relying on unrefined palm olein that delivers inconsistent functionality.
- Emulsifier-blend service contracts:Recipe-ready shortening with pre-incorporated monoglyceride packages is creating a service-layer moat that binds bakery customers through formulation consistency guarantees and technical support integration.
- India PLI scheme:Production-linked incentives for food processing infrastructure are attracting shortening manufacturers to establish domestic blending operations serving North Indian biscuit and namkeen clusters.
Industry Challenges
- Interesterification technician shortage:Specialized process engineers capable of optimizing enzymatic fat modification remain scarce in Southeast Asian refining hubs, constraining capacity expansion timelines.
- RSPO certification lag:Mass balance and segregated supply chain documentation for sustainable palm oil creates 12-18 month compliance timelines that delay customer conversions in European and North American premium channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Shortening Market |
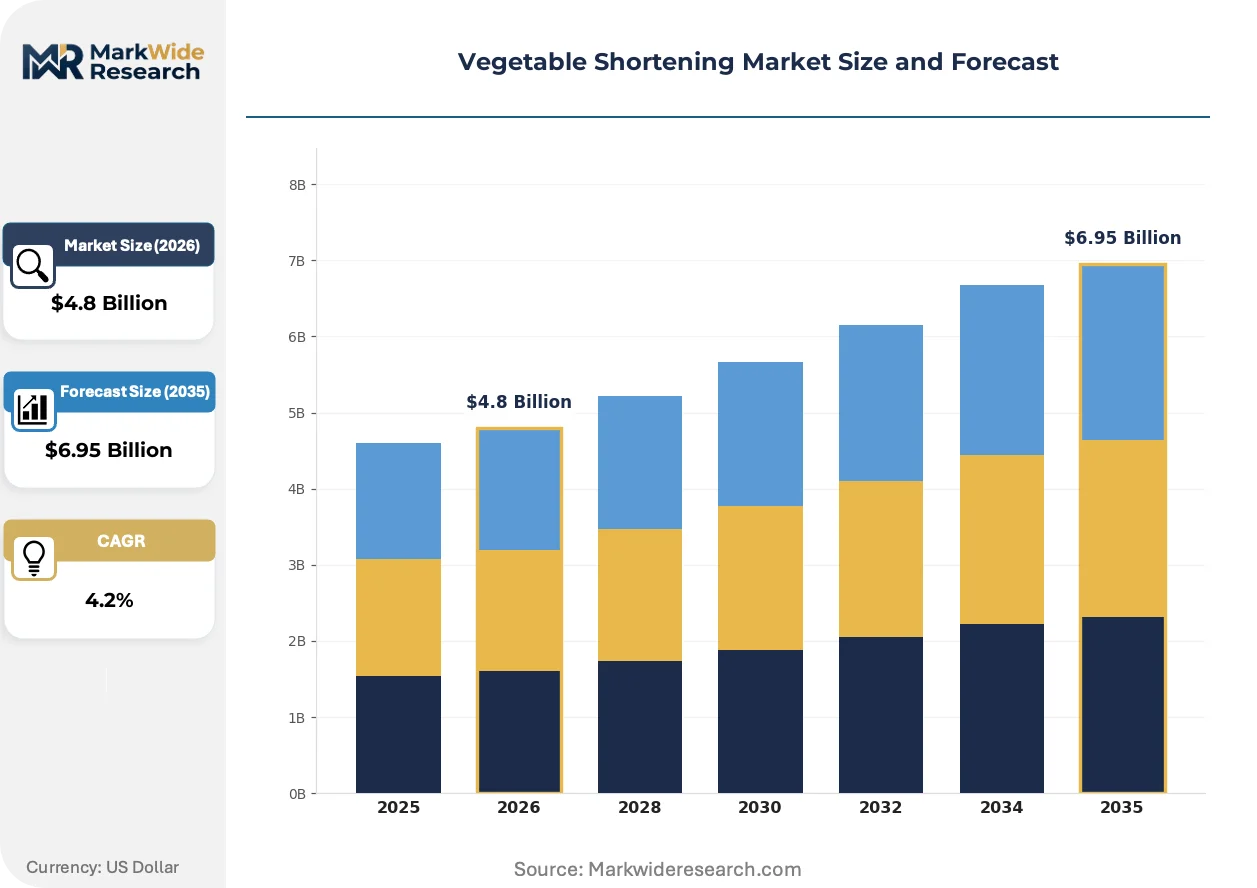
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid, Liquid, Plastic, Emulsified End Use: Baking, Frying, Confectionery, Sauces Packaging Type: Cans, Tubs, Pouches, Bulk Containers Distribution Channel: Wholesale, Retail, E-Commerce, Food Service |
| Companies Covered | Cargill, Incorporated, Bunge Limited, Wilmar International Ltd, Archer Daniels Midland Company, Conagra Brands, Inc., Fuji Oil Co., Ltd., Ventura Foods, Associated British Foods plc, The J.M. Smucker Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Shortening Market Strategic Shifts
Enzymatic processing and clean-label formulation are converging to redefine shortening functionality standards, while regulatory pressure on trans fats and carbon intensity forces simultaneous reformulation of both product chemistry and refinery operations.
Enzymatic interesterification is integrating into mainstream shortening production as the preferred alternative to chemical interesterification and partial hydrogenation. Bakery manufacturers in North America and Western Europe are specifying enzymatically processed fats for their cleaner label positioning and superior oxidative stability profiles. This technology is integrating process efficiency gains with regulatory compliance, compressing the competitive window for producers still reliant on legacy hydrogenation assets.
The EU F-Gas Regulation and companion EU Green Deal decarbonization mandates are imposing emissions caps on edible oil refinery operations that process palm and soybean feedstocks into shortening. European processors are retrofitting deodorization and fractionation units with heat integration systems to maintain export competitiveness. Southeast Asian exporters serving EU markets are responding by accelerating MEE sustainability certification and renewable energy procurement at origin refineries.
Consolidated procurement by multinational bakery chains is displacing fragmented distributor purchasing across key accounts in North America and Western Europe. Direct supplier relationships with technical service attachments are replacing traditional ingredient distributor intermediation, particularly for laminated dough and confectionery coating applications. This pattern is most visible in the U.S. quick-service restaurant sector and German industrial bakery clusters, where formulation consistency requirements override cost-minimization purchasing logic.
Vegetable Shortening Market Segmentation
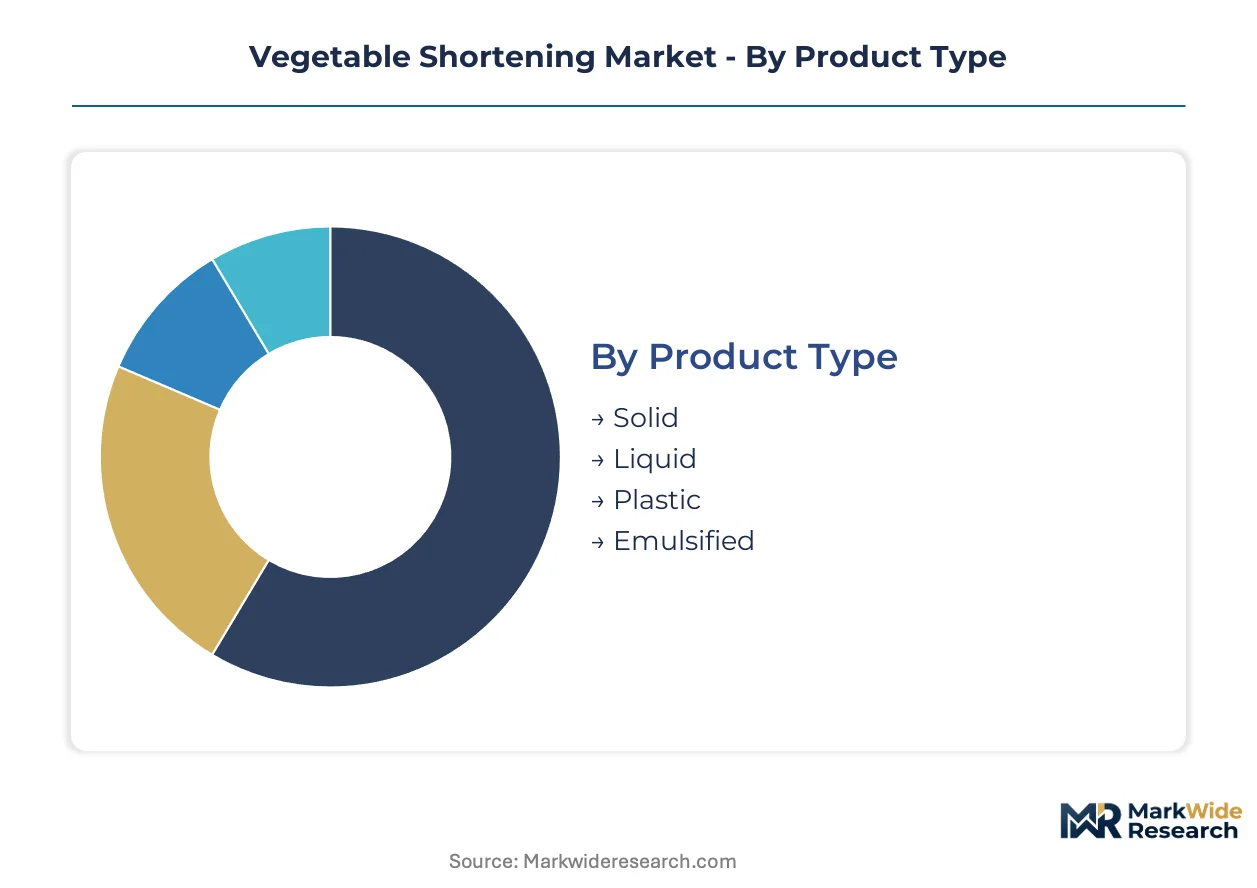
Segmentation in vegetable shortening reveals how formulation chemistry, packaging logistics, and channel economics partition margin capture across industrial and retail value chains. Certification burdens vary sharply by end-use and geography, with bakery applications demanding RSPO traceability while foodservice prioritizes cost-efficient bulk formats.
Product Type:
FDA trans-fat disclosure rules and EU Green Deal carbon accounting impose divergent compliance loads across product categories, with enzymatic processing certifications required for retail-facing segments.
- Solid:Hydrogenated or interesterified fats with plastic crystal structures engineered for lamination and flake formation in pie crusts. Quick-service restaurant chains in the United States specify guaranteed plasticity ranges, locking in multi-year supply contracts with reformulated specifications. Solid shortening sits at the top of the volume ranking, with emulsified shortening climbing the fastest.
- Emulsified:Shortening pre-blended with monoglyceride emulsifiers to control fat bloom and snap quality in confectionery coatings. Western European chocolate manufacturers specify these grades for clean-label positioning, though RSPO mass balance documentation creates 12-18 month compliance timelines.
- Liquid:Pourable vegetable oils fractionated for high-temperature frying applications, common in Southeast Asian street food vendors and institutional kitchens.
- Plastic:Semi-solid shortenings with tunable melting profiles for industrial bread production, prevalent in Indian biscuit and namkeen clusters.
Cost tiering separates commodity liquid grades from premium emulsified formulations with integrated technical service attachments.
End Use:
Application-specific functionality requirements dictate formulation complexity, with laminated dough demanding precise plastic fat behavior that commodity grades cannot replicate.
- Baking:Laminated pastries, pie crusts, and industrial bread production requiring controlled fat crystallization for texture engineering. German industrial bakery clusters and U.S. quick-service chains specify direct supplier relationships with formulation consistency guarantees.
- Confectionery:Coatings and fillings where fat bloom resistance and snap quality depend on emulsifier content and tempering behavior. Clean-label segments in Western Europe are reverting to butter where supply chain traceability exceeds vegetable shortening certification complexity.
- Frying:High-temperature stability applications in quick-service restaurants and street food operations, concentrated in Indonesia and Malaysia.
- Sauces:Cream-style emulsions and gravies requiring oxidative stability, common in institutional food manufacturing.
Baking commands the largest volume position, while confectionery delivers the steepest margin expansion trajectory.
Packaging Type:
Packaging economics align with customer scale and inventory velocity, with industrial accounts minimizing unit costs through bulk formats while retail channels prioritize shelf-ready presentation.
- Bulk Containers:Tote bins and tanker deliveries serving industrial bakeries and food manufacturers with high-volume, rapid-turn requirements. Southeast Asian refineries in Johor and Riau provinces concentrate supply for ASEAN bakery markets.
- Cans:Metal packaging for retail grocery and traditional trade channels requiring extended shelf stability and tamper evidence.
- Tubs:Consumer-sized polyethylene containers for household baking, prevalent in North American mass retail.
- Pouches:Flexible film packaging for economy-tier retail and emerging market penetration, gaining share in Vietnam's underpenetrated bakery sector.
Bulk containers dominate tonnage, with pouches expanding most quickly in price-sensitive developing markets.
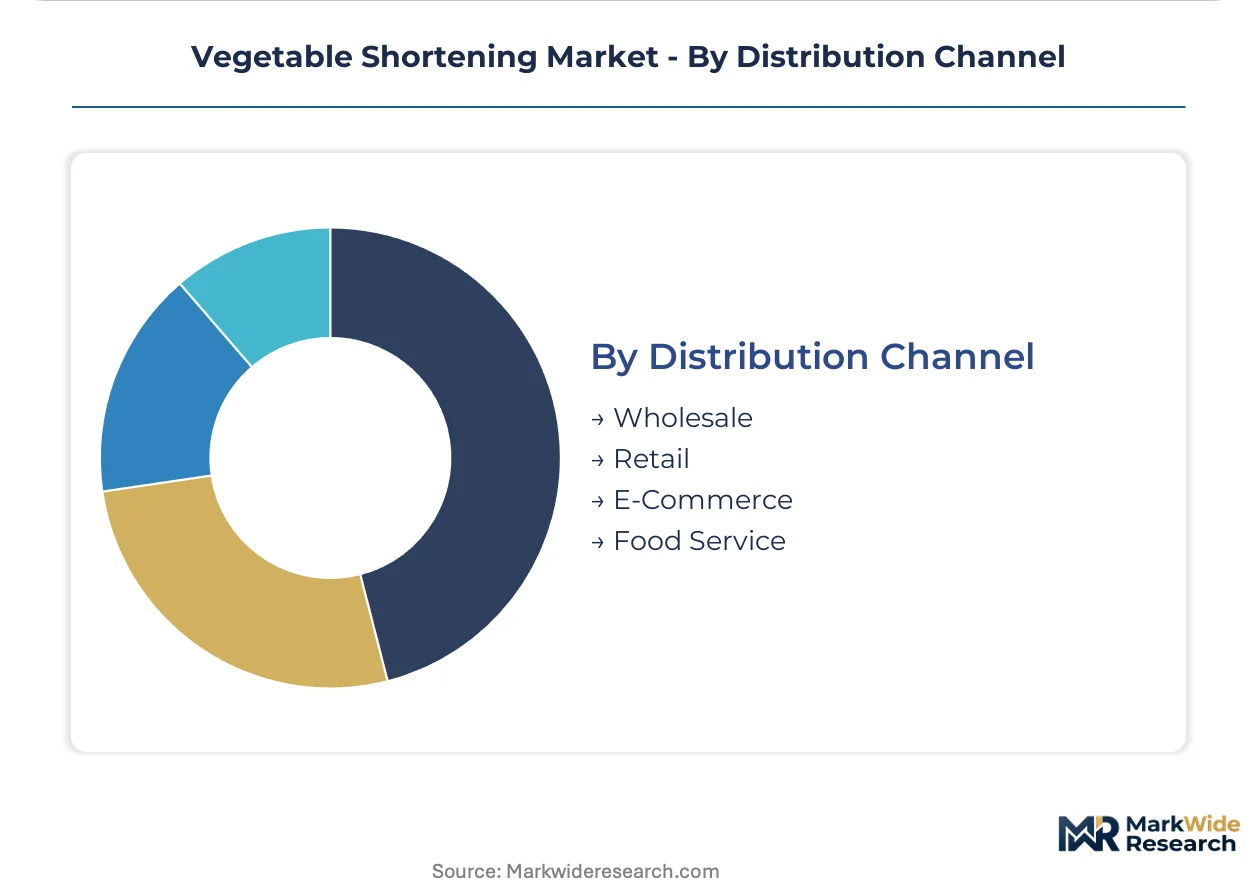
Distribution Channel:
Channel structure reflects customer consolidation patterns, with multinational bakery chains displacing fragmented distributor purchasing through direct technical service relationships.
- Food Service:Direct supply to quick-service restaurants, institutional kitchens, and bakery chains with attached formulation support and consistency guarantees. U.S. laminated dough applications are scaling procurement through multi-year contracts with reformulated specifications.
- Wholesale:Traditional distributor intermediation serving regional bakeries and smaller food manufacturers, losing share to direct supplier relationships in premium segments.
- Retail:Supermarket and grocery channels for household consumers, concentrated in private-label and branded packaged goods.
- E-Commerce:Digital procurement platforms for specialty and small-batch shortening grades, still nascent but expanding in ingredient-forward consumer segments.
Food service captures the highest volume flow, with e-commerce gaining share fastest among artisanal and clean-label buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting vegetable shortening production toward jurisdictions with lower compliance costs for trans-fat reformulation and carbon accounting. Southeast Asian refineries capture cost advantages from integrated palm oil supply chains, while North American and European processors absorb higher regulatory burdens.
United States
Quick-service restaurant chains dominate laminated dough procurement, locking in multi-year supply contracts with guaranteed plasticity specifications. FDA trans-fat disclosure rules compel reformulation toward interesterified alternatives, eliminating legacy partially hydrogenated formulations from retail channels. Chicago and Minneapolis industrial bakery clusters anchor North American demand for solid shortening grades.
Indonesia
Palm oil refining capacity concentrates in Riau province, supplying regional food manufacturers with industrial shortening at cost-competitive input prices. BIS-aligned national standards shape export protocols for shortening destined for ASEAN bakery markets. Jakarta and Surabaya food processing corridors drive domestic absorption of locally refined palm-based fats.
Germany
Industrial bakery clusters specify direct supplier relationships with attached technical service for formulation consistency in laminated pastry production. EU F-Gas Regulation and Green Deal decarbonization mandates accelerate heat-recovery retrofits at edible oil processing facilities. Hamburg and Berlin metropolitan areas concentrate confectionery coating demand for emulsified shortening grades.
India
Production-linked incentive schemes for food processing infrastructure attract shortening manufacturers to establish domestic blending operations. FSSAI regulations govern fat labeling and quality standards for biscuit and namkeen cluster supply. Maharashtra and Gujarat industrial corridors concentrate North Indian bakery demand for plastic shortening formulations.
Malaysia
Johor province refining hubs face single-source vulnerability concerns as regional exporters serve ASEAN confectionery and bakery markets. MEE sustainability requirements and RSPO certification protocols shape palm oil sourcing for premium channel access. Port Klang logistics infrastructure enables bulk container distribution to Southeast Asian food manufacturers.
Vegetable Shortening Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated oilseed processors commanding industrial bakery accounts while regional blenders serve price-sensitive institutional channels. The vendor base organizes around three archetypes: multinational agribusinesses with captive feedstock supply, Southeast Asian palm oil refiners with integrated fractionation assets, and regional compounders with formulation service capabilities. Capacity expansion and backward integration into oilseed crushing represent the dominant competitive moves, as margin compression in commodity grades forces upstream control over input costs.
Among integrated agribusinesses, Cargill Incorporated, Bunge Limited, and Wilmar International Ltd exemplify the feedstock-integrated archetype. Cargill leverages its North American oilseed processing network to secure cost positions across bakery accounts. Bunge anchors South American soybean oil supply into global distribution channels. Wilmar dominates palm-based shortening output from Southeast Asian refineries with integrated plantation-to-port supply chains.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Bunge Limited |
| Wilmar International Ltd |
| Archer Daniels Midland Company |
| Conagra Brands, Inc. |
| Fuji Oil Co., Ltd. |
| Ventura Foods |
| Associated British Foods plc |
| The J.M. Smucker Company |
| Others |
Value Chain & Pricing Dynamics
Captive plantation-to-refinery integration across Indonesian and Malaysian palm oil networks anchors cost positions for tropical feedstock processors while compressing margin capture for non-integrated compounders dependent on spot olein purchases. This structural asymmetry concentrates pricing power among Wilmar International Ltd and integrated Southeast Asian refiners serving ASEAN bakery manufacturers.
Pricing Analysis
Distributor margin compression in North American foodservice channels is accelerating direct supplier relationships between shortening manufacturers and quick-service restaurant chains. Three-tier pricing structure across premium enzymatic grades, standard interesterified formulations, and economy hydrogenated alternatives separates RSPO-certified emulsified shortening for European confectionery from commodity liquid grades for Southeast Asian frying applications. Pricing pressure stems from Indonesian crude palm oil supply fluctuations transmitting directly into input cost volatility. Institutional bakery accounts in India exhibit highest price sensitivity due to unrefined palm olein substitution options, while German industrial clusters prioritize formulation consistency over cost minimization.
Supply Chain Analysis
Ocean freight cost differentials between Riau province export terminals and Port Klang distribution hubs influence regional competitiveness for ASEAN bakery market supply. Raw material flows draw from Indonesian plantation estates, Malaysian fractionation facilities, and South American soybean crushing operations. Single-source vulnerability concentrates in Johor and Riau refining corridors where tropical palm oil processing capacity aggregates. Distribution runs through bulk tanker deliveries to industrial bakeries, with technical service attachments replacing traditional wholesale intermediation in North American laminated dough applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in vegetable shortening rests on enzymatic processing premiums capturing reformulation demand from FDA trans-fat compliance deadlines, while captive feedstock supply insulates integrated processors from palm oil price volatility.
For Market Incumbents: Cement multi-year supply contracts with quick-service restaurant chains by embedding formulation technical service teams that guarantee plasticity ranges for laminated dough applications. Deepen backward integration into oilseed crushing or plantation assets to offset palm olein price swings eroding commodity-grade margins. Defend against butter substitution in Western European clean-label segments through accelerated RSPO mass balance certification timelines. For New Entrants and Emerging Players: Launch via direct-to-bakery technical service models targeting Vietnam's underpenetrated industrial bread sector, where local mills currently tolerate inconsistent unrefined palm olein functionality. Prioritize emulsifier-blend service contracts in Indian biscuit and namkeen clusters benefiting from PLI scheme infrastructure incentives. Establish enzymatic processing partnerships with Southeast Asian refiners lacking in-house fat modification expertise to bypass technician shortage constraints. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with formulation service capabilities because multinational bakery chains are consolidating procurement away from fragmented distributor networks. Mid-term viability hinges on interesterification capacity buildouts capturing FDA-driven reformulation demand. Monitor RSPO certification completion rates as inflection indicator for premium channel access velocity in European and North American markets.| Strategic Initiative | Industry Significance |
|---|---|
| Interesterification Capacity Expansion | Enzymatic processing assets capture FDA trans-fat reformulation mandates across North American retail channels. |
| Backward Integration into Palm Plantations | Captive feedstock supply insulates margin positions from Indonesian and Malaysian crude palm oil volatility. |
| RSPO Certification Acceleration | Mass balance documentation unlocks premium confectionery coating contracts with Western European chocolate manufacturers. |
| Direct Technical Service Deployment | Embedded formulation support binds quick-service restaurant chains through multi-year plasticity guarantees. |
| Emulsifier-Blend Service Contracts | Pre-incorporated monoglyceride packages create switching costs for bakery customers dependent on consistency. |
Study Parameters
Bottom-up bakery and confectionery end-use modeling reconciled against top-down oilseed processing and refinery capacity tracking forms the analytical core of this study. Primary interviews with procurement directors at quick-service restaurant chains, technical R&D managers at industrial bakeries, refinery operations heads in Southeast Asia, and shortening distribution channel partners combined with secondary validation from FDA labeling guidance documents, EU F-Gas Regulation filings, RSPO certification databases, and Indonesian BIS standards publications. Triangulation between demand-side volume build-ups and supply-side capacity assessments ensures cross-verified output integrity.
Historical trendline analysis of shortening procurement patterns across laminated dough applications, confectionery coating specifications, and frying stability requirements established baseline trajectory assumptions. Segmentation dimensions modeled include product type chemistry, end-use functionality requirements, packaging format economics, and distribution channel structure across the projection horizon. CAGRs derived from fitted growth curves incorporate palm oil price cycle assumptions, regulatory compliance timeline accelerations, and bakery sector consolidation rates as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt Indonesian export policy shifts or enzymatic enzyme supply disruptions. Model outputs reflect documented assumptions regarding interesterification adoption curves and RSPO certification penetration timelines. A model refresh is warranted upon material change in FDA enforcement posture or EU Green Deal carbon accounting implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
United Kingdom Water Enhancer Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
Germany Food Flavor and Enhancer Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
Germany Water Enhancer Market
Food Enhancers and Additives
Flour Improvers Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
North America Feed Palatability Enhancers Market
Food Enhancers and Additives
Lignans Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
North America Food Flavor and Enhancer Market