
 Asia-Pacific Feed Palatability Enhancers Market | 2026-2036
Asia-Pacific Feed Palatability Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Feed Palatability Enhancers Market Outlook
ISO 22000 certification for feed safety management is unwinding competitive access across the Asia-Pacific feed palatability enhancers market, forcing regional formulators to upgrade hazard control systems. Symrise AG leverages its flavor science heritage to dominate premium pet food palatability segments. Kerry Group anchors its position through integrated taste and nutrition platforms serving multinational feed manufacturers. Cargill controls raw material procurement corridors from Southeast Asian spice and extract sources.
Feed palatability enhancers comprise sensory-active compounds—amino acids, flavor enhancers, sweeteners, and texture modifiers—formulated to stimulate voluntary feed intake and mask anti-nutritional factors in compound feeds. These additives typically incorporate nucleotides, hydrolyzed proteins, or high-intensity sweeteners at inclusion rates between 0.01% and 0.5% by weight, manufactured through spray-drying, extrusion, or micro-encapsulation processes to preserve volatile active compounds during pelleting and storage. Flavor enhancers command the largest revenue pool due to established use in pet food and poultry applications, while amino acid-based palatants represent the fastest-expanding category as precision livestock farming advances in Australia and New Zealand. Texture modifiers retain niche status concentrated in aquaculture feed for crustacean species with specific mouthpart mechanics.
China's SAMR enforces GB standards for feed additive safety and labeling, while Australia's TGA-equivalent agricultural regulator oversees import permits for novel palatability compounds. India's FSSAI and BIS jointly govern feed-grade ingredient specifications, creating multi-layer compliance requirements for cross-border suppliers. Stakeholders must monitor how ASEAN harmonization of feed additive registration procedures reshapes market entry timelines and testing cost structures.
Market Dynamics
ISO 22000 certification requirements are forcing Southeast Asian feed compounders to rebuild hazard control systems from the ground up, compressing margins for unaccredited suppliers while locking in procurement relationships with certified ingredient vendors.
Growth Catalysts
- Thailand's agricultural modernization programs:Government subsidies for industrial livestock operations are accelerating adoption of precision-formulated palatability enhancers in automated feeding systems across the country's central plains.
- Flavor enhancement in crustacean aquaculture:Texture-modified palatants targeting specific mouthpart mechanics of black tiger shrimp are opening premium export channels to Japanese and South Korean processors.
- China's eastern coastal industrialization:Concentration of large-scale pork and poultry operations in Jiangsu and Shandong provinces is generating concentrated demand for high-inclusion-rate flavor enhancers.
Market Restraints
- Raw material supply concentration:Cargill's control over Southeast Asian spice and extract procurement corridors limits independent formulators' access to cost-competitive botanical precursors.
- Novel compound registration timelines:India's FSSAI and BIS joint governance creates multi-layer testing requirements that extend product launch cycles by 18-24 months for cross-border suppliers.
- Natural extract price volatility:Weather-dependent yields of vanilla and citrus extracts in Indonesia and Vietnam destabilize input cost structures for premium palatant formulations.
Strategic Opportunities
- Underpenetrated Vietnamese aquaculture:Mekong Delta shrimp and pangasius producers remain reliant on unformulated attractants, creating white space for nucleotide-based precision palatants.
- ASEAN harmonization of feed additive registration:Streamlined cross-border approval procedures will reduce testing cost burdens for regional suppliers operating across multiple member states.
- Micro-encapsulation and precision delivery convergence:Combining spray-drying technologies with species-specific release profiles enables premium pricing in Australian and New Zealand precision livestock farming segments.
Industry Challenges
- Flavor chemist talent scarcity:Formulation expertise combining feed science with volatile compound stability engineering concentrates in Symrise AG and Kerry Group research centers, constraining regional competitor R&D pipelines.
- ISO 22000 certification capex intensity:Hazard analysis and critical control point infrastructure upgrades require substantial capital outlay for mid-scale Thai and Indonesian compound feed manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Feed Palatability Enhancers Market |
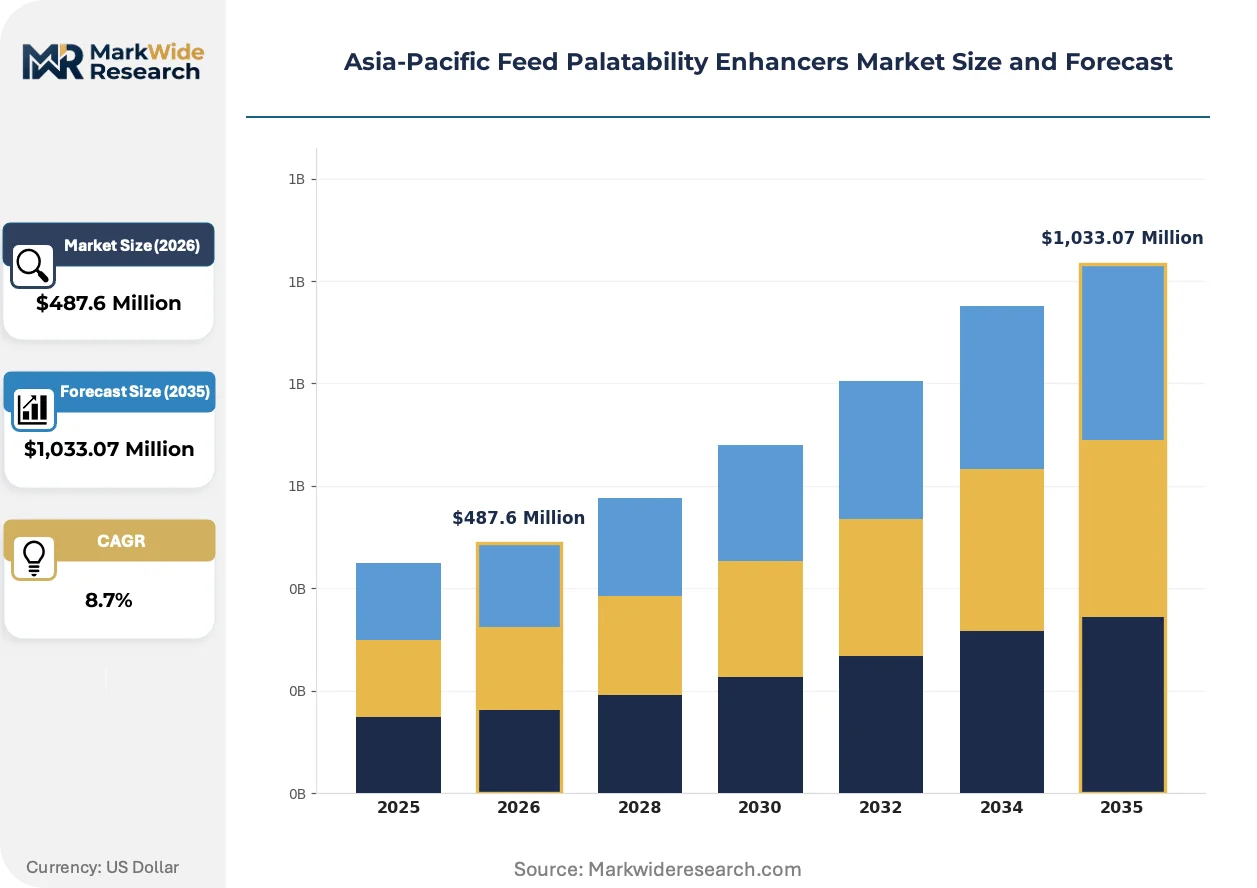
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Flavor Enhancers, Sweeteners, Texture Modifiers Application: Pet Food, Livestock, Aquaculture, Poultry Distribution Channel: Online Retail, Distributors, Direct Sales, Supermarkets End User: Farmers, Pet Owners, Feed Manufacturers, Aquatic Farmers |
| Companies Covered | Symrise AG, DuPont, Kerry Group, Associated British Foods, Adisseo, Kemin Industries, Pancosma, Cargill, Nutriad, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Feed Palatability Enhancers Market Strategic Shifts
Active ingredient delivery systems are fragmenting into species-specialized formats, while regulatory pressure on label transparency and residue testing accelerates substitution of synthetic compounds with verified natural alternatives across the Asia-Pacific region.
Micro-encapsulation via spray-drying and extrusion is bifurcating the palatability enhancer market into volatile-preservation and controlled-release technology tiers. Australian and New Zealand precision livestock operators are adopting high-specification micro-capsules at triple the rate of Southeast Asian commodity feed producers. This technology split is compressing margins for generic spray-dried formulations while enabling 40-60% price premiums for species-targeted release profiles in crustacean and monogastric applications.
China's SAMR enforcement of GB standards for feed additive safety and labeling is mandating full traceability documentation for nucleotide and hydrolyzed protein sources. Industrial compounders in Shandong and Guangdong provinces are restructuring supplier qualification protocols to pre-empt audit failures. The regulatory pressure falls most heavily on flavor enhancer categories, where ingredient complexity complicates origin verification and forces reformulation of legacy products containing unspecified hydrolyzed protein fractions.
Direct procurement relationships between Vietnamese livestock cooperatives and specialty palatant formulators are displacing traditional distributor-mediated supply chains in the Mekong Delta. Large integrated pork producers in Dong Nai and Long An provinces now negotiate annual volume contracts for customized amino acid-based palatants, bypassing regional feed additive traders. This channel compression is most visible in poultry operations, where feed conversion ratio improvements of 3-5% justify the administrative burden of direct supplier management.
Asia-Pacific Feed Palatability Enhancers Market Segmentation
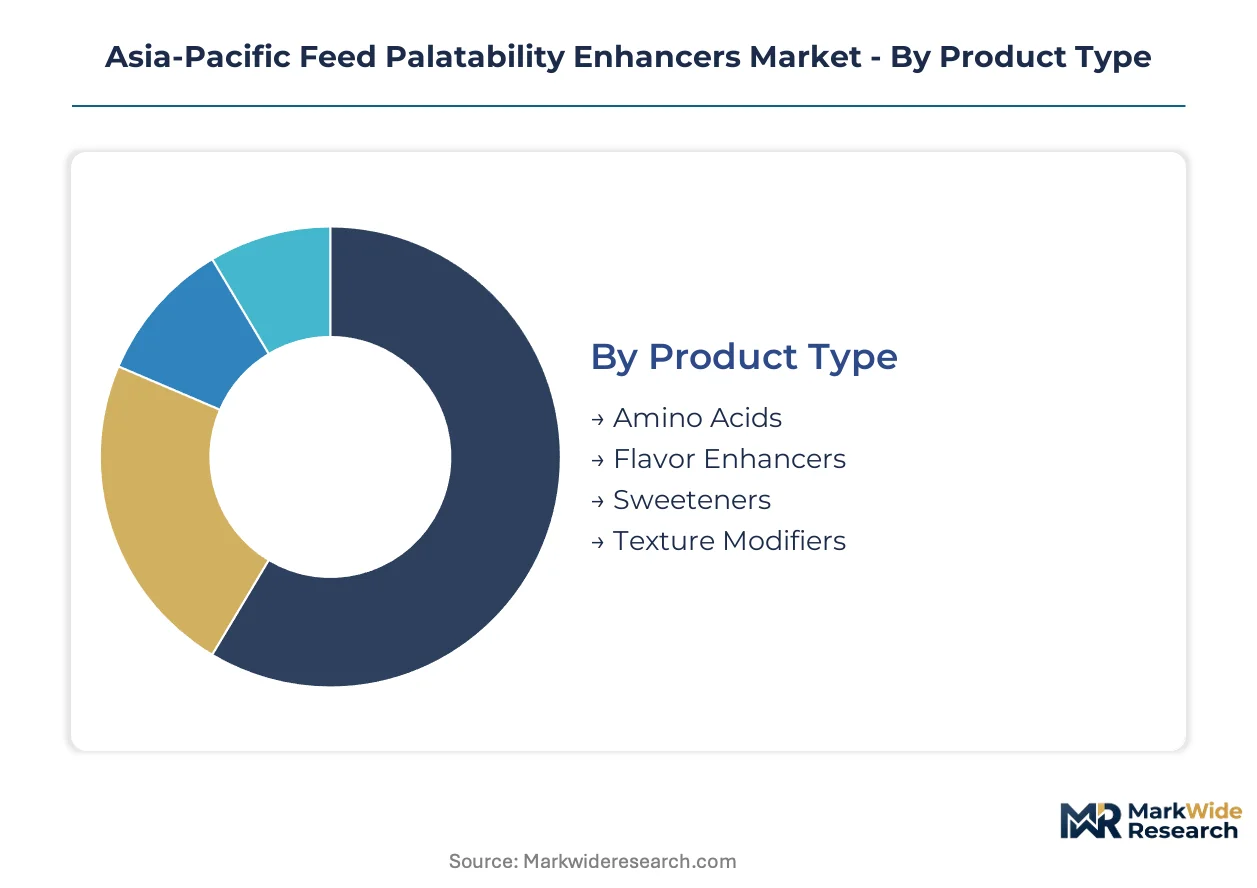
Segmentation in the Asia-Pacific feed palatability enhancers market reveals how substitution pressures and regulatory complexity reshape procurement patterns across product categories. Understanding these divisions exposes where formulators must defend margin position against natural extract volatility and where precision livestock farming creates premium pricing power.
Product Type:
Sweeteners and synthetic high-intensity compounds face the strongest displacement threat from natural extract alternatives as China's SAMR tightens label transparency requirements.
- Flavor Enhancers:These sensory-active formulations incorporate nucleotides, hydrolyzed proteins, and volatile compound blends at inclusion rates between 0.01% and 0.5% by weight. Demand concentrates in China's eastern coastal provinces where industrialized pork and poultry operations in Jiangsu and Shandong require high-inclusion-rate formulations to mask anti-nutritional factors in compound feeds.
- Amino Acids:Precision-formulated palatants based on lysine, methionine, and threonine derivatives stimulate voluntary feed intake through specific receptor activation. Australian and New Zealand precision livestock farming segments are adopting these compounds fastest as automated feeding systems enable gram-level inclusion accuracy.
- Sweeteners:High-intensity compounds including neohesperidin dihydrochalcone and stevia derivatives serve monogastric applications.
- Texture Modifiers:Specialized formulations targeting crustacean mouthpart mechanics retain niche concentration in Vietnamese and Thai aquaculture.
Flavor enhancers retain volume leadership; amino acids hold the steepest expansion curve.
Application:
Cost tier differentiation separates premium-specification pet food formulations from commodity livestock applications where price sensitivity dominates procurement decisions.
- Livestock:Industrial pork and cattle operations across Vietnam's Dong Nai province and Indonesia's Java heartland drive bulk demand for cost-optimized palatability systems. Feed conversion ratio improvements of 3-5% justify annual volume contracts with specialty formulators, displacing traditional distributor channels.
- Pet Food:Premium dry and wet formulations command specification thresholds exceeding livestock applications by an order of magnitude. Symrise AG and Kerry Group concentrate R&D investment here, leveraging flavor science heritage to capture value from multinational pet food manufacturers operating in Thailand and Australia.
- Poultry:Broiler and layer operations in China's Guangdong province require rapid intake stimulation to maximize growth rates.
- Aquaculture:Black tiger shrimp and pangasius producers in Vietnam's Mekong Delta remain underpenetrated relative to crustacean potential.
Livestock dominates absolute volume; pet food captures the highest margin per kilogram.
Distribution Channel:
Customer type fragmentation between industrial compounders and smallholder cooperatives determines channel viability across Southeast Asian markets.
- Direct Sales:Large integrated producers in Vietnam and Thailand negotiate customized amino acid-based palatant formulations through annual contracts, bypassing regional feed additive traders entirely. This channel compression accelerates fastest in poultry operations where administrative burden justification is strongest.
- Distributors:Traditional trader networks retain relevance for mid-scale Indonesian and Filipino compound feed manufacturers lacking procurement scale for direct supplier relationships.
- Online Retail:Specialty palatant sampling and small-volume procurement platforms emerge for aquaculture cooperatives.
- Supermarkets:Consumer-facing pet food palatability products move through retail channels in Australian and New Zealand urban centers.
Direct sales expand most quickly; distributors defend position in fragmented supply bases.
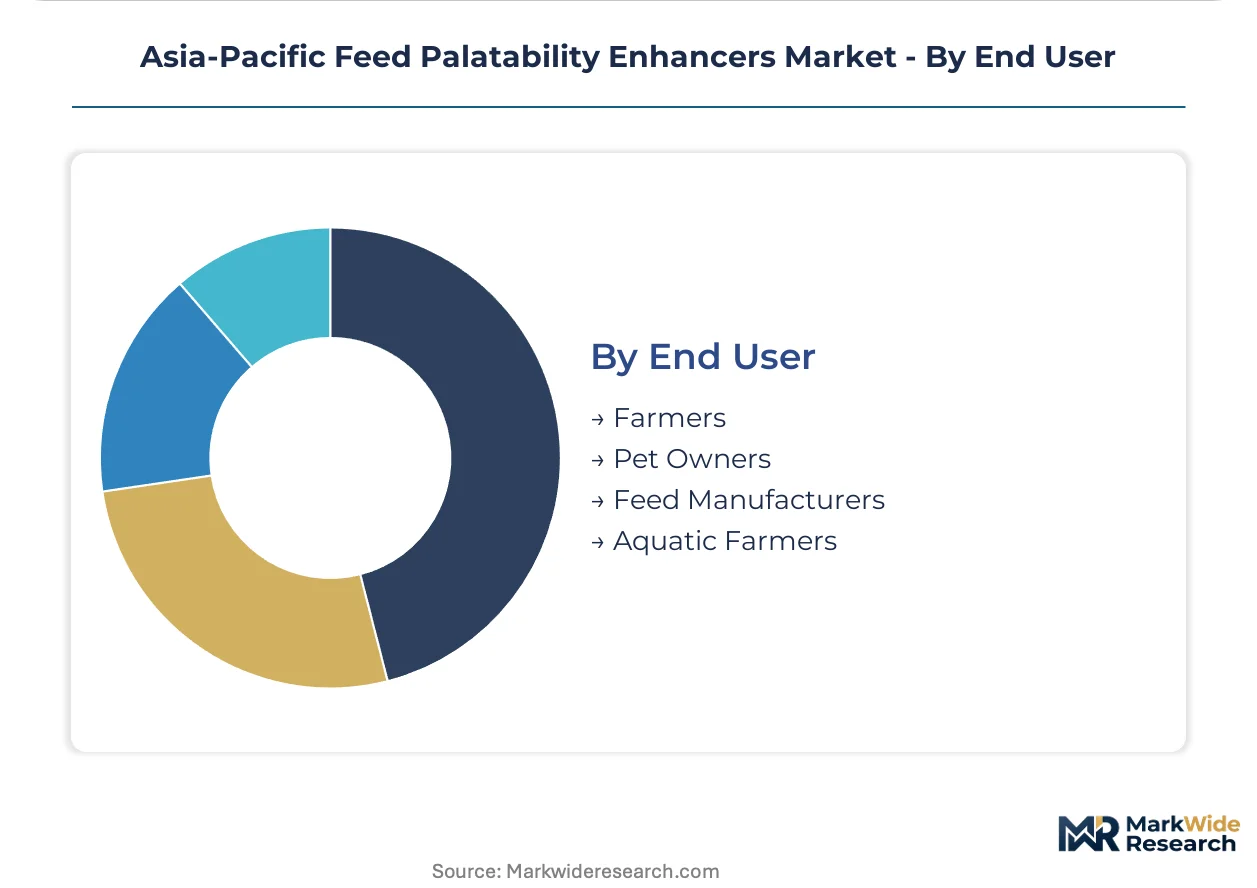
End User:
Supply concentration among feed manufacturers creates procurement leverage that squeezes independent formulator margins.
- Feed Manufacturers:Industrial compounders in Shandong and Guangdong provinces restructure supplier qualification protocols to pre-empt SAMR audit failures, consolidating procurement relationships with ISO 22000-certified ingredient vendors. Cargill's control over Southeast Asian spice corridors locks in cost advantages for integrated players.
- Farmers:Vietnamese livestock cooperatives in Long An province increasingly source directly from specialty formulators, fragmenting traditional channel structures.
- Aquatic Farmers:Mekong Delta shrimp producers remain reliant on unformulated attractants.
- Pet Owners:Premium pet food consumers in Australian metropolitan markets drive specification intensity for natural-label palatants.
Feed manufacturers concentrate procurement volume; farmers gain negotiating power fastest through channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial compounders and integrated livestock operations concentrate procurement volume in coastal manufacturing belts, while aquaculture cooperatives in river delta systems fragment traditional distribution channels through direct supplier relationships.
China
Jiangsu and Shandong provinces host dense clusters of pork and poultry operations driving concentrated demand for high-inclusion-rate flavor enhancers. SAMR enforcement of GB standards for feed additive safety forces industrial compounders to restructure supplier qualification protocols with full traceability documentation. Guangdong province compounders pre-empt audit failures by consolidating procurement with ISO 22000-certified ingredient vendors.
Vietnam
Dong Nai and Long An province pork producers negotiate annual volume contracts for customized amino acid-based palatants, bypassing regional feed additive traders entirely. The country's agricultural modernization programs accelerate adoption of precision-formulated enhancers in automated feeding systems across the Mekong Delta. Mekong Delta shrimp and pangasius producers remain underpenetrated relative to crustacean potential, creating white space for nucleotide-based precision palatants.
Thailand
Government subsidies for industrial livestock operations drive adoption of precision-formulated palatability enhancers across the central plains. The country's agricultural modernization programs compress margins for unaccredited suppliers while locking in procurement relationships with certified ingredient vendors. Bangkok-based feed compounders face substantial capital outlay for hazard analysis and critical control point infrastructure upgrades.
Indonesia
Java heartland cattle operations drive bulk demand for cost-optimized palatability systems where feed conversion ratio improvements justify direct supplier relationships. Weather-dependent yields of vanilla and citrus extracts in Indonesian growing regions destabilize input cost structures for premium palatant formulations. Mid-scale compound feed manufacturers lacking procurement scale retain reliance on traditional distributor networks.
Australia
Precision livestock farming segments adopt amino acid-based palatants fastest as automated feeding systems enable gram-level inclusion accuracy. TGA-equivalent agricultural regulators oversee import permits for novel palatability compounds, creating compliance requirements for cross-border suppliers. New South Wales and Victoria operators adopt high-specification micro-capsules at triple the rate of Southeast Asian commodity feed producers.
Asia-Pacific Feed Palatability Enhancers Market Competitive Environment
Player mix skews toward integrated multinational ingredient suppliers with captive raw material procurement and specialized flavor science heritage houses with deep volatile compound stability expertise. Tiered competitive structure separates premium specification formulators serving pet food and precision livestock segments from commodity suppliers competing on cost in bulk livestock applications. Two dominant strategic archetypes emerge: integrated agricultural conglomerates controlling upstream botanical extract corridors, and specialized sensory science companies leveraging flavor chemistry R&D platforms. Competitive moves concentrate on backward integration into Southeast Asian spice sourcing and technology licensing partnerships for micro-encapsulation delivery systems.
Within the integrated supplier tier, Cargill anchors its position through upstream control over Southeast Asian spice and extract procurement corridors. Symrise AG and Kerry Group occupy the specialized sensory science tier, with Symrise leveraging flavor science heritage and Kerry anchoring through integrated taste and nutrition platforms. These three companies exemplify the bifurcation between raw material security and formulation expertise that defines competitive positioning across the region.
| Leading Market Players |
|---|
| Symrise AG |
| DuPont |
| Kerry Group |
| Associated British Foods |
| Adisseo |
| Kemin Industries |
| Pancosma |
| Cargill |
| Nutriad |
| Others |
Value Chain & Pricing Dynamics
ISO 22000 certification gates supply qualification and price differentiation simultaneously, locking unaccredited Southeast Asian compounders out of premium procurement tiers while forcing certified vendors to absorb hazard control infrastructure costs. Buyers in Vietnam's Dong Nai province and China's Shandong province now tier supplier relationships by certification status, compressing margins for non-compliant formulators.
Pricing Analysis
Cost-plus contracts with vanilla and citrus extract indexation dominate procurement agreements for premium palatant formulations. Price differentiation rests on ISO 22000 certification tier and volume scale, with large integrated pork producers in Vietnam's Long An province commanding 15-20% discounts over mid-scale Indonesian compounders. Pricing pressure stems from weather-driven volatility in Indonesian and Vietnamese botanical yields, squeezing input cost predictability for natural-extract formulations. Smallholder cooperatives in the Mekong Delta exhibit highest price sensitivity, while Australian precision livestock operators accept premium positioning for species-targeted micro-encapsulated delivery systems.
Supply Chain Analysis
Southeast Asian spice corridor control by integrated agricultural conglomerates creates a chokepoint constraining independent formulator access to cost-competitive botanical precursors. Supply concentrates in Indonesia, Vietnam, and Thailand for vanilla and citrus extracts, with hydrolyzed protein sourcing anchored in China's Shandong and Guangdong provinces. Raw material dependencies on weather-sensitive crop yields and nucleotide fermentation capacity expose formulators to commodity price volatility. Distribution runs through direct annual contracts for large integrated producers, while traditional trader networks retain relevance for fragmented Indonesian and Filipino mid-scale compounders lacking procurement scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across species-specific delivery formats and certification tiers creates niche entry points, as precision livestock farming in Australia and New Zealand and aquaculture modernization in Vietnam generate demand for specialized formulations unmatched by commodity suppliers.
For Market Incumbents: Secure captive supply arrangements for Southeast Asian spice corridors to defend margin position against Cargill's upstream control, while accelerating ISO 22000 certification investments to pre-empt SAMR audit enforcement in China's eastern coastal provinces. Channel consolidation toward direct annual contracts with Vietnamese livestock cooperatives locks out distributor-dependent competitors. For New Entrants and Emerging Players: ASEAN harmonization of feed additive registration procedures offers a certification fast-track for regional suppliers seeking multi-country market access without redundant testing cycles. Target Vietnam's underpenetrated Mekong Delta aquaculture segment with nucleotide-based precision palatants, displacing unformulated attractants through direct technical sales to shrimp producer cooperatives. For Investors and Strategic Acquirers: SAMR enforcement of GB standards for full traceability documentation reshapes the acquisition landscape toward ISO 22000-certified formulators with established nucleotide and hydrolyzed protein supplier qualification protocols. Five-to-ten-year viability favors specialized sensory science houses with flavor chemistry R&D platforms over commodity suppliers exposed to natural extract price volatility. Monitor ASEAN registration harmonization implementation timelines as inflection indicator for regional supplier consolidation activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Southeast Asian Spice Sourcing | Cargill's corridor control forces competitors to secure captive vanilla and citrus extract supply from Indonesian and Vietnamese growing regions. |
| ISO 22000 Certification Acceleration | SAMR audit enforcement in Jiangsu and Shandong provinces disqualifies non-compliant suppliers from industrial compounder procurement. |
| Micro-Encapsulation Technology Licensing | Australian precision livestock operators adopt species-targeted release profiles at triple Southeast Asian commodity rates. |
| Direct Channel Development in Vietnam | Dong Nai and Long An province pork producers bypass regional traders through annual volume contracts for customized amino acid palatants. |
| ASEAN Registration Harmonization Compliance | Streamlined cross-border approval procedures reduce testing cost burdens for suppliers operating across multiple member states. |
Study Parameters
Cross-validation between primary interviews with feed formulator technical directors, procurement leads at Thai industrial compounders, Vietnamese livestock cooperative managers, and Australian precision livestock operators anchors the qualitative findings against secondary validation from SAMR GB standard filings, ASEAN feed additive registration databases, customs trade data for Southeast Asian spice and extract flows, and SEC disclosures from listed ingredient suppliers. Bottom-up demand modeling from species-specific inclusion rate assumptions triangulates against top-down market sizing from regional feed production volumes.
Sensitivity analysis around vanilla and citrus extract price volatility, ISO 22000 certification adoption curves, and ASEAN harmonization implementation timelines informs projection robustness across the analysis window. Segmentation dimensions modeled include product type, application, distribution channel, and end user, with additional granularity on species-specific delivery format specifications. CAGRs derive from compound growth assumptions applied to baseline demand calibrated against industrial livestock operation expansion in Vietnam and China, precision farming adoption in Australia and New Zealand, and aquaculture modernization in Thailand.
Decision-makers should treat outputs as directional under assumptions of continued SAMR enforcement intensity and ASEAN regulatory convergence; material deviation in certification adoption rates or harmonization timelines would warrant model refresh. Revision becomes warranted when weather-driven botanical yield volatility or trade corridor disruptions cross thresholds that alter input cost structures for premium natural-extract formulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
North America Feed Palatability Enhancers Market
Food Enhancers and Additives
Emulsifier Alternatives Market
Food Enhancers and Additives
Italy Anti-Caking Market
Food Enhancers and Additives
South America Feed Palatability Enhancers Market
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
North America Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
Mexico Water Enhancer Market
Food Enhancers and Additives
Yellow Fats Market
Food Enhancers and Additives
Dysphagia Diet Thickening Agents Market
Food Enhancers and Additives
Browning Enhancers Market
Food Enhancers and Additives
South Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market