
 United States Water Enhancer Market | 2026-2036
United States Water Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Water Enhancer Market Analytics
Fitness-oriented consumption is restructuring the United States water enhancer demand profile, pulling volume away from traditional family-centric formats toward electrolyte-enhanced and zero-sugar variants. PepsiCo Inc. leverages its Gatorade brand ecosystem to cross-sell enhancer formats into athletic channels. The Coca-Cola Company competes through its Vitaminwater portfolio, sustaining shelf presence across convenience and club retail. Nestlé S.A. specializes in functional wellness positioning, anchoring premium price tiers with mineral-fortified liquid concentrates.
Water enhancers comprise concentrated flavoring and functional additive systems—typically delivered as liquid concentrates, powders, drops, or effervescent tablets—that consumers dilute into plain water to alter taste, nutritional content, or physiological performance. Liquid formats dominate current production volume due to manufacturing simplicity and dosing precision, though powder segments claim faster velocity in direct-to-consumer channels where shipping weight drives margin. Berry flavor profiles occupy the broadest household penetration, while exotic and herbal variants capture expanding space in health store and online retail assortments where trial-driven purchasing behavior supports premium positioning.
FDA food additive regulations and USDA organic certification standards govern ingredient permissibility and label claims, directly constraining formulation freedom and marketing vocabulary for health-focused SKUs. The FTC monitors advertising substantiation for performance claims, particularly around electrolyte replacement and energy benefits that target fitness enthusiasts. Stakeholders must track evolving EPA water quality advisories and state-level extended producer responsibility frameworks that could reshape packaging material specifications and disposal cost allocation across the value chain.
Market Dynamics
Fitness-oriented consumption patterns are restructuring the United States water enhancer demand profile, pulling volume away from traditional family-centric formats toward electrolyte-enhanced and zero-sugar variants. This shift concentrates purchasing power among athletic channels and premium retail clusters.
Growth Catalysts
- FDA Food Additive Modernization:Updated safety evaluations for novel sweeteners and natural flavor compounds accelerate clean-label product pipelines.
- California Health Infrastructure:Dense networks of specialty fitness studios and premium grocery chains create concentrated trial environments for functional enhancer formats.
- Electrolyte Formulation Advances:Precision mineral dosing technologies enable shelf-stable concentrates that match sports drink performance without refrigeration.
Market Restraints
- Stevia Supply Volatility:Price fluctuations in high-purity Reb M extract constrain margin stability for zero-sugar product lines.
- Midwest Distribution Gaps:Limited cold-chain independent retail penetration outside coastal metropolitan zones restricts geographic expansion.
- FTC Substantiation Burden:Performance claims around hydration efficacy and energy enhancement require costly clinical documentation.
Strategic Opportunities
- Texas Sun Belt Expansion:Underdeveloped functional beverage penetration in Dallas-Fort Worth and Houston suburban corridors offers whitespace for athletic-positioned SKUs.
- USDA Organic Certification Pipeline:Federal cost-share programs for organic transition reduce barrier-to-entry for premium mineral-fortified lines.
- Direct-to-Consumer Powder Velocity:E-commerce subscription models bypass shelf-space competition while capturing repeat purchase data.
Industry Challenges
- Flavor Chemist Talent Scarcity:Shortage of specialists capable of masking off-notes from functional actives delays new product cycles.
- EPR Compliance Fragmentation:Evolving state-level extended producer responsibility frameworks create packaging specification uncertainty across multi-state distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Water Enhancer Market |
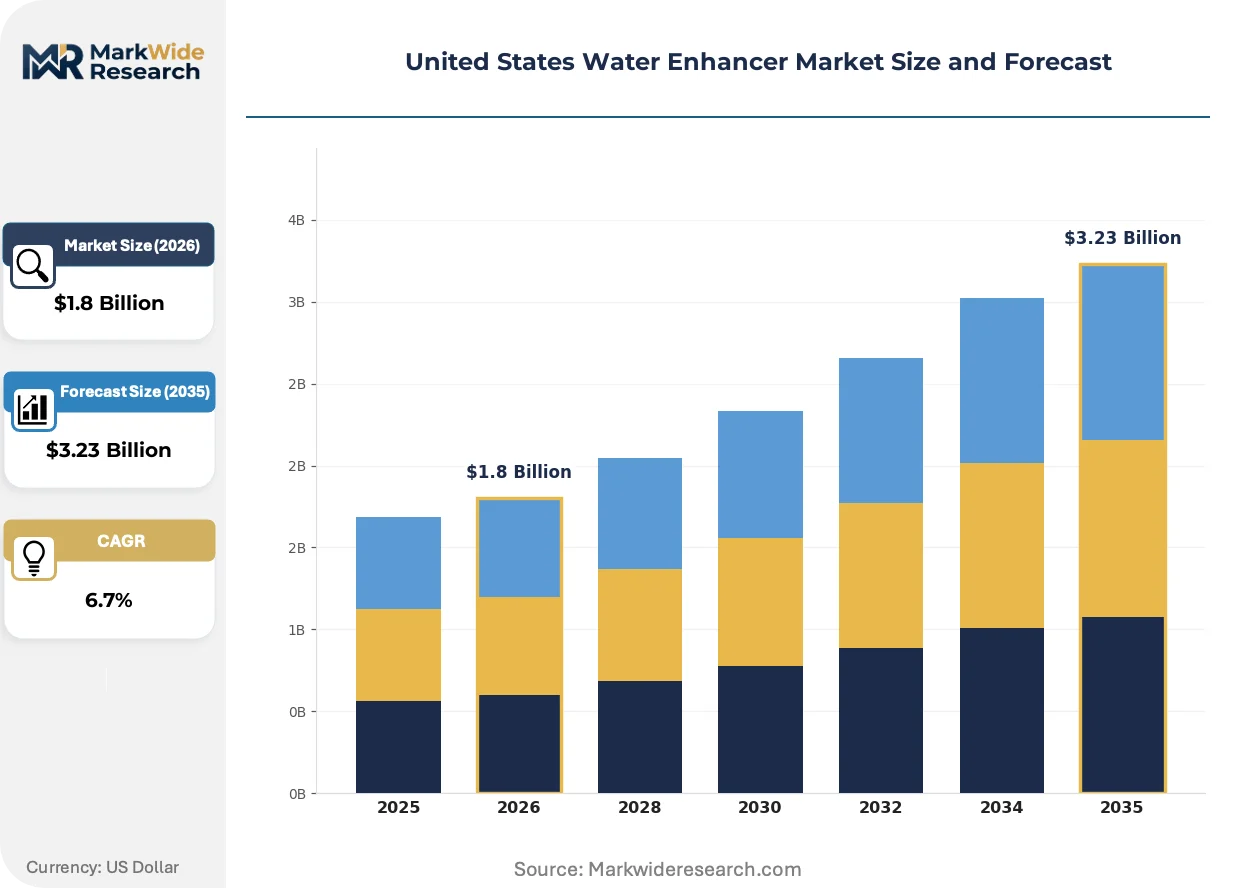
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Drops, Tablets Flavor Profile: Citrus, Berry, Exotic, Herbal Target Audience: Fitness Enthusiasts, Families, Health-Conscious Consumers, Seniors Sales Channel: Online Retail, Supermarkets, Health Stores, Convenience Stores |
| Companies Covered | PepsiCo Inc., The Coca-Cola Company, Nestlé S.A., The Kraft Heinz Company, Arizona Beverages USA, 4C Foods Corp., The Jel Sert Company, Stur Drinks LLC, Hydrant Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Water Enhancer Market Evolving Landscape
Reformulation priorities are pivoting around bioactive ingredient stability and clean-label positioning. Manufacturers invest in processing infrastructure that preserves functional potency through ambient distribution while satisfying ingredient transparency demands.
Microencapsulation technology for heat-sensitive vitamins and probiotics is expanding into liquid concentrate formats previously limited to simple flavoring systems. Athletic consumers now expect effervescent and drop formats to deliver clinically relevant electrolyte loads without refrigeration dependency. This capability compression enables club retail placement alongside ambient sports nutrition categories.
USDA organic certification standards are tightening enforcement of synthetic processing aid prohibitions in flavor extraction. Manufacturers face reformulation costs or alternative supplier qualification timelines. Premium-positioned brands absorb compliance investments to defend shelf price tiers against conventional competitors.
Bulk purchasing behavior among CrossFit affiliates and boutique studio networks is displacing individual bottle sales with multi-serve concentrate systems. These B2B channels command volume discounts that compress per-unit margins while securing predictable offtake. Florida and Arizona fitness markets exhibit the strongest concentration of this procurement pattern.
United States Water Enhancer Market Segmentation
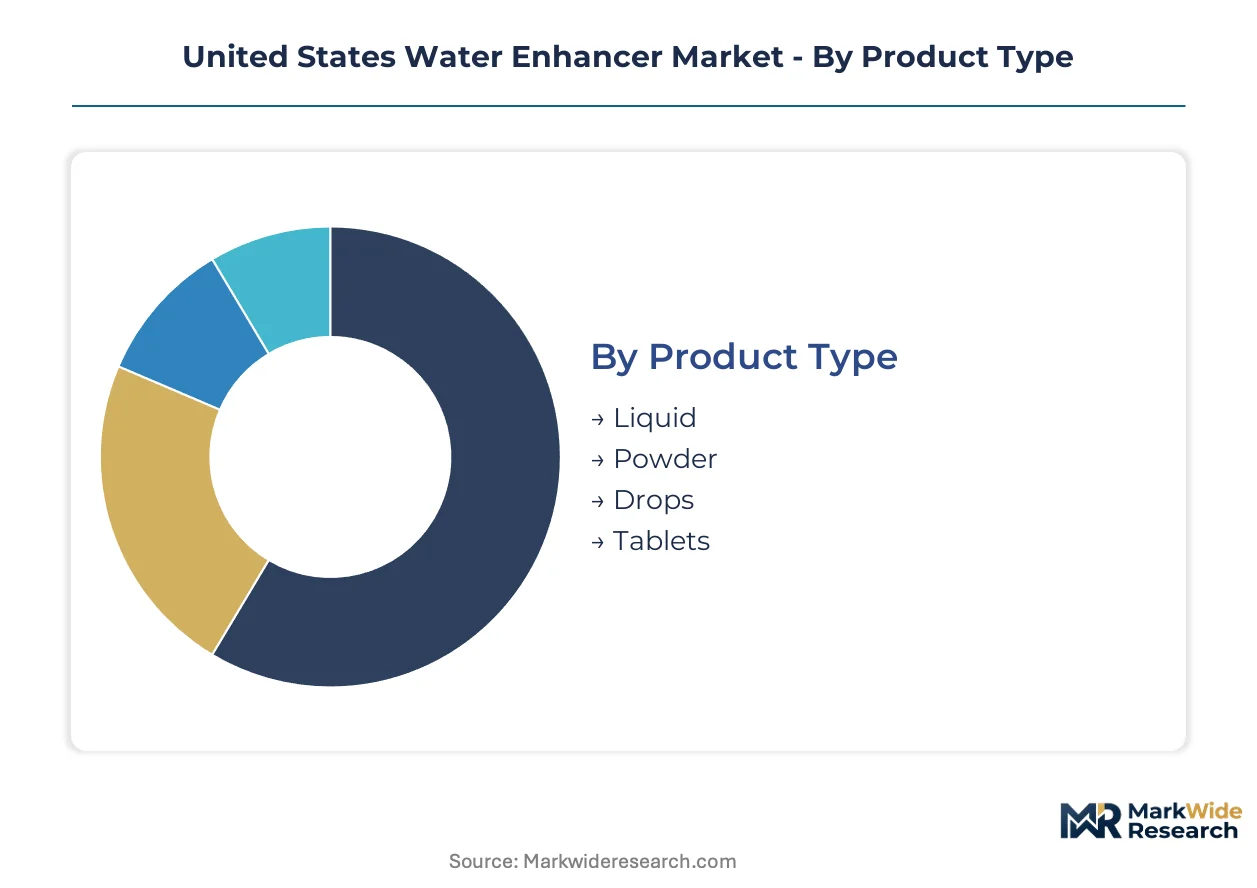
Water enhancer segmentation reveals how formulation technology, flavor chemistry, and channel economics partition demand across distinct consumer missions. Understanding these axes enables precise resource allocation between mass-market scale and premium positioning strategies.
Product Type:
Liquid concentrate manufacturing dominates current capacity investment due to dosing precision and ambient stability advantages.
- Liquid:Shelf-stable concentrates utilize propylene glycol carriers and preservative systems to maintain flavor integrity across temperature excursions. California health-conscious consumers drive premium liquid adoption through specialty grocery channels where unit economics support higher price points.
- Powder:Dehydrated formulations reduce shipping weight and enable single-serve sachet formats. E-commerce subscription velocity concentrates in powder segments where fulfillment cost advantages compound with fitness enthusiast bulk purchasing behavior.
- Drops:Ultra-concentrated pipette delivery systems offer micro-dosing control for mineral fortification applications. Health store retail placement favors drop formats for premium positioning.
- Tablets:Effervescent and slow-dissolve compressed formats require specialized compaction equipment and humidity-controlled packaging. Convenience store distribution remains limited due to higher unit cost and slower consumer education cycles.
Mature deployment sits with Liquid. Newer deployment is concentrated in Powder.
Flavor Profile:
Flavor chemistry investment correlates directly with repeat purchase rates and subscription retention metrics.
- Citrus:Limonene and citral-based formulations deliver immediate refreshment cues with established consumer acceptance. Mass-market supermarket placement anchors citrus SKUs as trial entry points for family segment conversion.
- Berry:Anthocyanin-stable natural color systems and polyphenol masking technologies enable clean-label berry positioning. Berry profiles capture the broadest household penetration across all sales channels and age demographics.
- Exotic:Dragon fruit, yuzu, and passionfruit extracts require specialized supplier relationships and extended stability testing. Exotic variants gain share fastest in health store and online retail assortments where novelty-seeking behavior supports premium pricing.
- Herbal:Botanical extracts including lavender, chamomile, and adaptogenic compounds demand sophisticated off-note masking from flavor chemists. Senior-targeted formulations leverage herbal positioning for relaxation and sleep support claims.
Volume leadership belongs to Berry. Margin expansion concentrates in Exotic.
Target Audience:
Consumer mission segmentation determines formulation complexity, packaging format, and channel investment priorities.
- Fitness Enthusiasts:Electrolyte precision dosing and branched-chain amino acid fortification define performance-oriented SKUs. Athletic channel placement in specialty fitness studios and CrossFit affiliates drives concentrated demand in Texas Sun Belt expansion corridors.
- Families:Multi-serve packaging economies and simplified flavor profiles prioritize cost efficiency over functional complexity. Supermarket promotional calendars and back-to-school seasonal programming anchor family segment volume.
- Health-Conscious Consumers:USDA organic certification and non-GMO verification command price premiums in premium grocery channels. California consumer density supports specialized retail infrastructure for this segment.
- Seniors:Vitamin D, B-complex, and hydration monitoring formulations address age-specific nutritional gaps. Pharmacy and assisted living channel development remains underpenetrated relative to demographic growth.
Current revenue concentration favors Fitness Enthusiasts. Emerging expansion opportunity sits with Seniors.
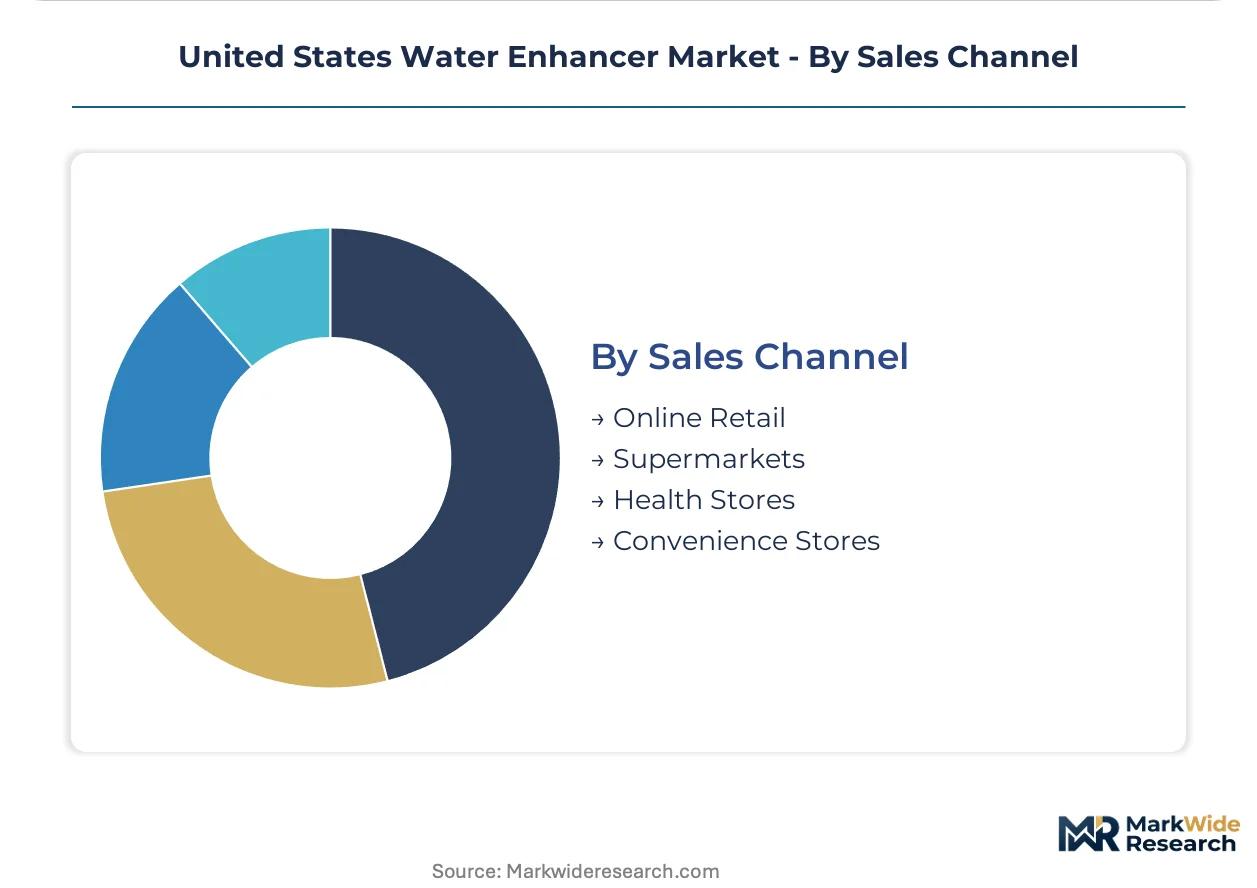
Sales Channel:
Channel economics dictate packaging format, promotional intensity, and trade spend allocation across the portfolio.
- Online Retail:Direct-to-consumer subscription models capture repeat purchase data and bypass slotting fee competition. Powder segment velocity advantages compound with digital-native fitness brand partnerships.
- Supermarkets:Mass-market scale demands promotional calendar discipline and seasonal programming investment. Citrus and berry flavor profiles dominate shelf placement due to household penetration metrics.
- Health Stores:Curation-driven assortments favor exotic and herbal variants with premium positioning and ingredient transparency claims. Staff education requirements limit brand count and favor concentrated supplier relationships.
- Convenience Stores:Impulse purchase dynamics favor single-serve liquid formats with immediate consumption cues. Cold-chain independent retail gaps in Midwest metropolitan zones constrain geographic coverage.
Margin optimization centers on Health Stores. Volume scale depends on Supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Opportunity Zones and state-level clean-label manufacturing incentives concentrate water enhancer production capacity along the Pacific Coast. Texas Enterprise Fund awards and Arizona's targeted beverage sector tax credits are pulling secondary investment into Sun Belt corridors.
California
Specialty fitness studio density and premium grocery chain expansion drive concentrated demand for electrolyte-enhanced liquid concentrates. FDA food additive safety evaluations govern novel sweetener approvals for clean-label formulations. Los Angeles and San Francisco Bay Area retail clusters anchor the highest per-capita consumption rates nationally.
Texas
Dallas-Fort Worth and Houston suburban corridors present underdeveloped whitespace for athletic-positioned SKUs targeting CrossFit affiliates. State agriculture department organic certification cost-share programs reduce barrier-to-entry for premium mineral-fortified lines. Austin's boutique fitness network is accelerating bulk concentrate procurement from regional distributors.
Florida
Retirement community density and humidity-driven hydration awareness support senior-targeted vitamin-fortified formulations. USDA organic certification enforcement tightens processing aid prohibitions in flavor extraction. Miami and Tampa health store clusters favor exotic and herbal variant placement with premium positioning.
New York
Direct-to-consumer subscription velocity concentrates in powder segments where digital-native fitness brand partnerships drive repeat purchase data capture. FTC advertising substantiation requirements impose documentation burdens for performance claims around hydration efficacy. New York City metro area e-commerce fulfillment infrastructure supports same-day delivery models.
Illinois
Midwest distribution gaps in cold-chain independent retail constrain geographic expansion for refrigerated-dependent formats. EPA water quality advisories influence regional formulation adjustments for mineral content claims. Chicago metropolitan retail consolidation favors mass-market berry and citrus profile placement through supermarket promotional calendars.
United States Water Enhancer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with beverage conglomerates commanding athletic channel placement while private-label fabricators serve supermarket value tiers. The vendor base organizes around three archetypes: diversified beverage holding companies with cross-brand ecosystem leverage, functional wellness specialists anchoring premium price tiers, and agile direct-to-consumer entrants exploiting e-commerce subscription mechanics. Consolidation pressure manifests through strategic partnerships between flavor houses and mineral suppliers, alongside capacity expansion into ambient-stable electrolyte processing infrastructure.
Among diversified beverage holding companies, PepsiCo Inc. and The Coca-Cola Company exemplify ecosystem-driven competitive positioning, leveraging existing brand equity and distribution infrastructure to secure shelf presence across convenience and club retail channels. Nestlé S.A. occupies a position within the functional wellness specialist tier, anchoring premium mineral-fortified liquid concentrates through specialized retail relationships. These three entities represent contrasting strategic postures: scale-driven cross-selling, mass-market volume capture, and premium-tier wellness positioning respectively.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| The Coca-Cola Company |
| Nestlé S.A. |
| The Kraft Heinz Company |
| Arizona Beverages USA |
| 4C Foods Corp. |
| The Jel Sert Company |
| Stur Drinks LLC |
| Hydrant Inc. |
| Others |
Value Network & Pricing Analysis
Clean-label certification divergence between USDA organic and conventional formulations splits the United States water enhancer market into distinct pricing echelons and sourcing configurations. Premium organic SKUs command shelf price premiums through California health store networks while conventional concentrates compete on unit economics in Midwest supermarket promotional calendars, with supply chain investments clustering around Pacific Coast flavor extraction infrastructure versus inland powder compaction facilities.
Pricing Analysis
Short lead-time premiums for refrigerated liquid concentrates versus ambient-stable formats drive price stratification across distribution channels. Three-tier pricing structure across premium organic, standard clean-label, and economy conventional levels segments buyer willingness-to-pay by certification grade and channel type. Cost compression in economy tiers is intensifying because stevia supply volatility and Reb M extract price fluctuations squeeze margin stability for zero-sugar product lines. Family segment buyers exhibit highest price sensitivity through supermarket promotional dependency, while fitness enthusiasts in specialty athletic channels accept premium positioning for electrolyte precision dosing.
Supply Chain Analysis
Domestic-content mandates in California Opportunity Zones and Texas Enterprise Fund qualification requirements are reshaping sourcing patterns toward US-based flavor extraction and mineral fortification processing. Supply concentration centers on California for liquid concentrate manufacturing, Texas for powder compaction serving Sun Belt expansion corridors, and Illinois for Midwest distribution hub consolidation. Raw material dependencies span high-purity Reb M stevia extracts from domestic agricultural processors, propylene glycol carriers from Gulf Coast petrochemical complexes, and anthocyanin-stable natural color systems from specialty botanical suppliers. Single-source vulnerability in high-purity natural sweetener supply creates structural risk exposure. Distribution runs through direct-to-consumer subscription models bypassing traditional retail slotting fee competition alongside conventional supermarket and health store wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States water enhancer market is becoming a vertical-integration race as players pursue captive supply of high-purity natural sweeteners and in-house flavor extraction capabilities to defend margin structure against input cost volatility.
For Market Incumbents: Anchor shelf position through exclusive CrossFit affiliate and boutique studio network partnerships that lock in bulk concentrate procurement commitments. Deepen backward integration into stevia agricultural processing and Reb M extraction to insulate zero-sugar product lines from supply price volatility. Defend against direct-to-consumer powder entrants by accelerating ambient-stable electrolyte formulation R&D that matches sports drink performance without refrigeration dependency. For New Entrants and Emerging Players: Specialty fitness studio distributors in Texas Sun Belt expansion corridors offer the most penetrable channel whitespace for athletic-positioned SKUs. Target senior-targeted vitamin-fortified formulations for Florida retirement community pharmacy and assisted living channel development, where demographic growth outpaces current product availability. Pursue USDA organic certification cost-share programs through state agriculture departments to reduce barrier-to-entry for premium mineral-fortified lines competing in California health store clusters. For Investors and Strategic Acquirers: Re-rating potential sits with functional wellness specialists possessing captive mineral supplier relationships and established health store retail placement given tightening FDA enforcement of synthetic processing aid prohibitions in flavor extraction. Long-term viability over the next decade favors players with integrated organic certification pipelines and direct-to-consumer subscription data assets. Monitor stevia supply contract renegotiation cycles as an inflection indicator for margin compression timing across zero-sugar product portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Sweetener Supply | Captive Reb M extraction capacity insulates margin structure from stevia price volatility affecting zero-sugar SKUs. |
| Direct-to-Consumer Subscription Launch | Powder segment velocity advantages compound with fitness enthusiast bulk purchasing behavior in e-commerce channels. |
| USDA Organic Certification Investment | Federal and state cost-share programs reduce compliance barrier-to-entry for premium mineral-fortified positioning. |
| Texas Sun Belt Distribution Expansion | Dallas-Fort Worth and Houston suburban corridors present underdeveloped whitespace for athletic-positioned SKU placement. |
| Ambient-Stable Electrolyte Formulation R&D | Precision mineral dosing technologies enable club retail placement alongside ambient sports nutrition categories. |
Research Methodology
Independent corroboration across flavor house technical directors, mineral supplier account managers, and CrossFit affiliate procurement coordinators underwrites the qualitative findings in this study. Primary interviews with category buyers at premium grocery chains, regulatory affairs specialists navigating FDA food additive evaluations, and e-commerce operations heads at direct-to-consumer brands combined with secondary validation from FDA GRAS notifications, USDA organic certification databases, Nielsen retail audit data, and state-level extended producer responsibility framework filings. Bottom-up demand modeling across product type, flavor profile, target audience, and sales channel dimensions triangulated against top-down market sizing from trade flow analysis.
Comparable historical reference periods spanning pre-pandemic baseline, supply disruption interval, and normalization phase anchored the forecast window across the analysis window. Segmentation dimensions modeled include liquid versus powder versus drop versus tablet formats, berry versus citrus versus exotic versus herbal flavor chemistry, fitness enthusiast versus family versus health-conscious versus senior consumer missions, and online retail versus supermarket versus health store versus convenience store channel economics. CAGRs were derived from elasticity-adjusted demand projections incorporating electrolyte formulation technology adoption curves and clean-label certification penetration rates.
Caveats apply where FDA food additive safety evaluation delays, stevia supply price shocks, or state-level EPR packaging specification changes could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and input cost stabilization trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
South Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
North America Feed Palatability Enhancers Market
Food Enhancers and Additives
Browning Enhancers Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
Canada Food Flavor and Enhancer Market
Food Enhancers and Additives
Flavonoid Phytogenic Feed Additive Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
Food Thickening Agents Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Thaumatin Market