
 Yellow Fats Market | 2026-2036
Yellow Fats Market Size, Share, and Industry Trends Forecast 2026-2036
Yellow Fats Market Analytics
Consolidation among quick-service restaurant chains and institutional caterers is realigning procurement volumes toward long-term supply contracts with verified fat suppliers. Unilever Group leverages its global sourcing infrastructure to secure cost-advantaged positions across multiple geographies. FrieslandCampina N.V. anchors its competitiveness through backward integration into dairy farming cooperatives in Northwestern Europe. Kraft Heinz Company differentiates via brand equity in North American retail butter and margarine segments.
Yellow fats encompass spreadable and cookable lipid products derived from animal milk, vegetable oils, or blended formulations, typically containing 80-82% fat content with emulsifiers and water phases engineered for specific functional performance in baking, frying, and table use. The product type dimension shows butter commanding premium positioning in retail and food service channels, while plant-based margarine competes aggressively on price in industrial applications. Within the application category, baked goods and confectionery absorb the largest volume flows, though sauces represent a faster-growing niche as global cuisine adoption broadens.
The EU Green Deal and REACH frameworks mandate traceable, sustainable sourcing for palm-derived inputs entering European food manufacturing, directly elevating compliance costs for blend-dependent margarine producers. The FDA's standards of identity for butter and the USDA's dairy grading system shape product labeling and interstate commerce rules in the United States. India's FSSAI enforces fortification and adulteration controls that determine which ghee and butter formulations reach organized retail. Stakeholders must monitor evolving trans-fat restrictions and carbon-border adjustments to anticipate which ingredient sources and product formats will retain market access.
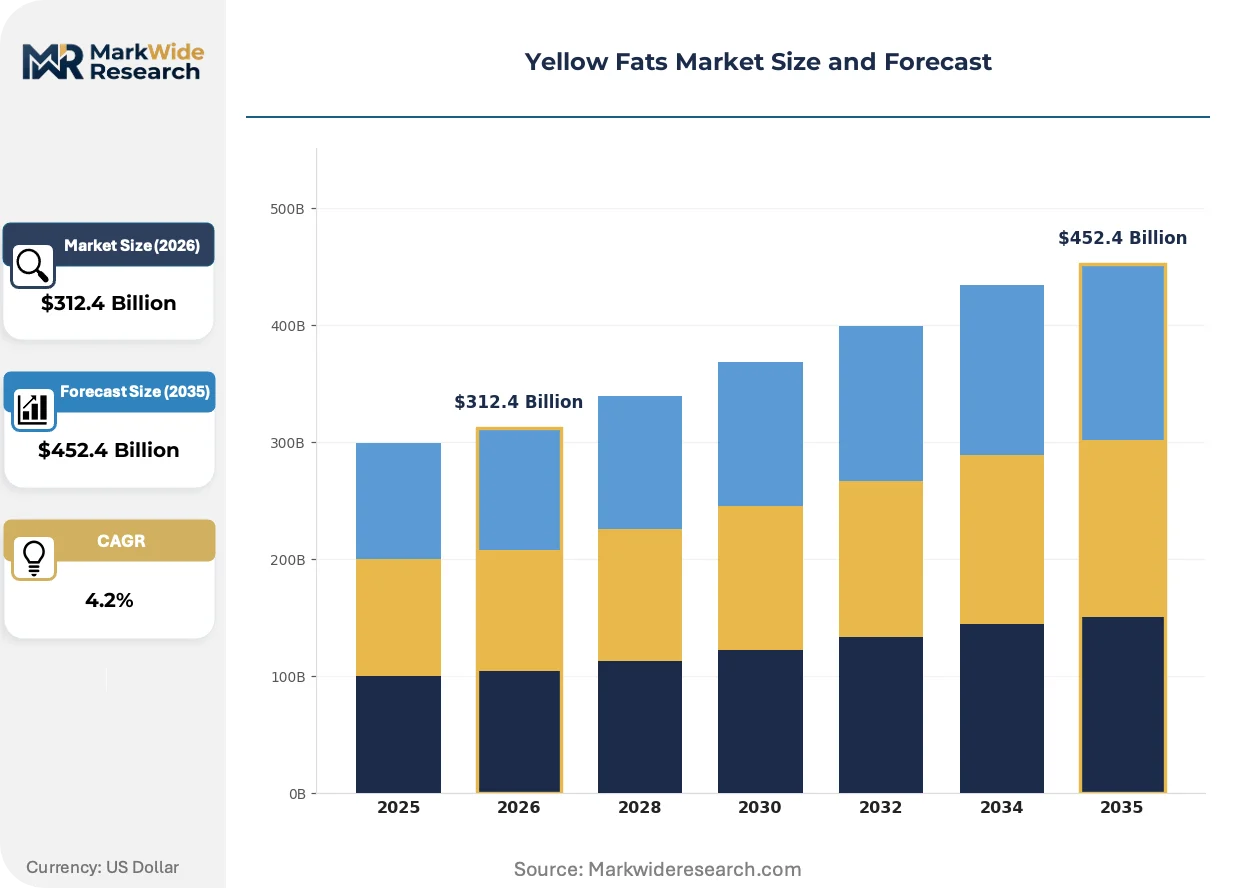
Market Dynamics
EU Green Deal deforestation-free supply chain mandates are forcing reformulation investments across margarine portfolios while concentrating procurement power among verified suppliers.
Growth Catalysts
- Urban household consumption in India:Organized retail penetration in tier-2 and tier-3 cities is pulling branded ghee and butter volumes into formal channels, with FSSAI fortification standards accelerating product standardization.
- REACH traceability requirements:European food manufacturers are locking in long-term palm oil contracts with RSPO-certified suppliers, creating premium positioning for compliant blenders.
- Food service channel expansion:Quick-service restaurant chains across Southeast Asia are specifying butter and ghee for authentic cuisine preparation, consolidating volumes toward institutional suppliers.
Market Restraints
- Palm oil price volatility:El Niño-driven supply disruptions in Indonesian and Malaysian plantations are compressing margins for blend-dependent margarine producers.
- Dairy input cost concentration:Northwestern European cooperative structures control fluid milk pricing, limiting margin flexibility for butter processors outside integrated farming networks.
- Trans-fat regulatory compression:WHO elimination targets and national bans on partially hydrogenated oils are rendering legacy formulation assets obsolete across multiple jurisdictions.
Strategic Opportunities
- Carbon-border adjustment alignment:EU CBAM phase-in creates first-mover advantage for dairy and oilseed suppliers with verified Scope 3 emissions data.
- Plant-based butter convergence:Precision fermentation-derived fats and high-oleic sunflower oil blends are opening clean-label positioning in premium retail segments.
- E-commerce direct-to-household channels:Cold-chain logistics investments are enabling subscription-based ghee and cultured butter delivery in Indian metropolitan clusters.
Industry Challenges
- Reformulation technical debt:Removing trans-fats while maintaining shelf stability and mouthfeel requires expensive emulsifier system redevelopment and sensory retesting protocols.
- Certification timeline compression:RSPO, Rainforest Alliance, and EU Deforestation Regulation compliance audits are creating 12-18 month supplier onboarding bottlenecks.
- Legacy equipment retrofit requirements:Shifting from batch to continuous processing for spreadable blends demands capital outlays that mid-scale processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yellow Fats Market |
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $452.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Margarine, Ghee, Shortening Application: Baked Goods, Confectionery, Dairy Products, Sauces End User: Food Service, Retail, Industrial, Household Ingredient Source: Plant-Based, Animal-Based, Blends, Others |
| Companies Covered | Arla Foods, Nestle SA, Unilever Group, Kraft Heinz Company, Land O'Lakes Inc., Bunge Limited, Danone SA, FrieslandCampina N.V., Amul, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yellow Fats Market Evolving Landscape
Novel lipid structuring technologies are redefining functional performance benchmarks while regulatory chemistry restrictions and procurement consolidation reshape competitive requirements.
High-pressure processing and enzymatic interesterification are electrifying texture engineering in reduced-fat spreads. Industrial bakeries in Germany and France are adopting these enzymatic blends at accelerated rates to meet clean-label demands without sacrificing lamination performance. The technology is compressing the performance gap between premium butter and modified margarine in laminated dough applications.
REACH Annex XIV authorization procedures for food-contact substances are tightening emulsifier approval pathways. ECHA's evolving restrictions on specific glycerol esters are forcing reformulators toward enzymatically produced alternatives with cleaner toxicological profiles. Margarine producers serving Northern European retail are responding by accelerating GRAS self-determination dossiers for novel emulsifier systems.
Buyer consolidation among institutional caterers is compressing supplier rosters and lengthening contract tenures. Multi-year supply agreements with verified sustainability credentials are displacing spot-market purchasing in French and Dutch food service procurement. This pattern is most visible in contract catering for corporate campuses and healthcare facilities where ESG reporting requirements dominate vendor selection criteria.
Yellow Fats Market Segmentation
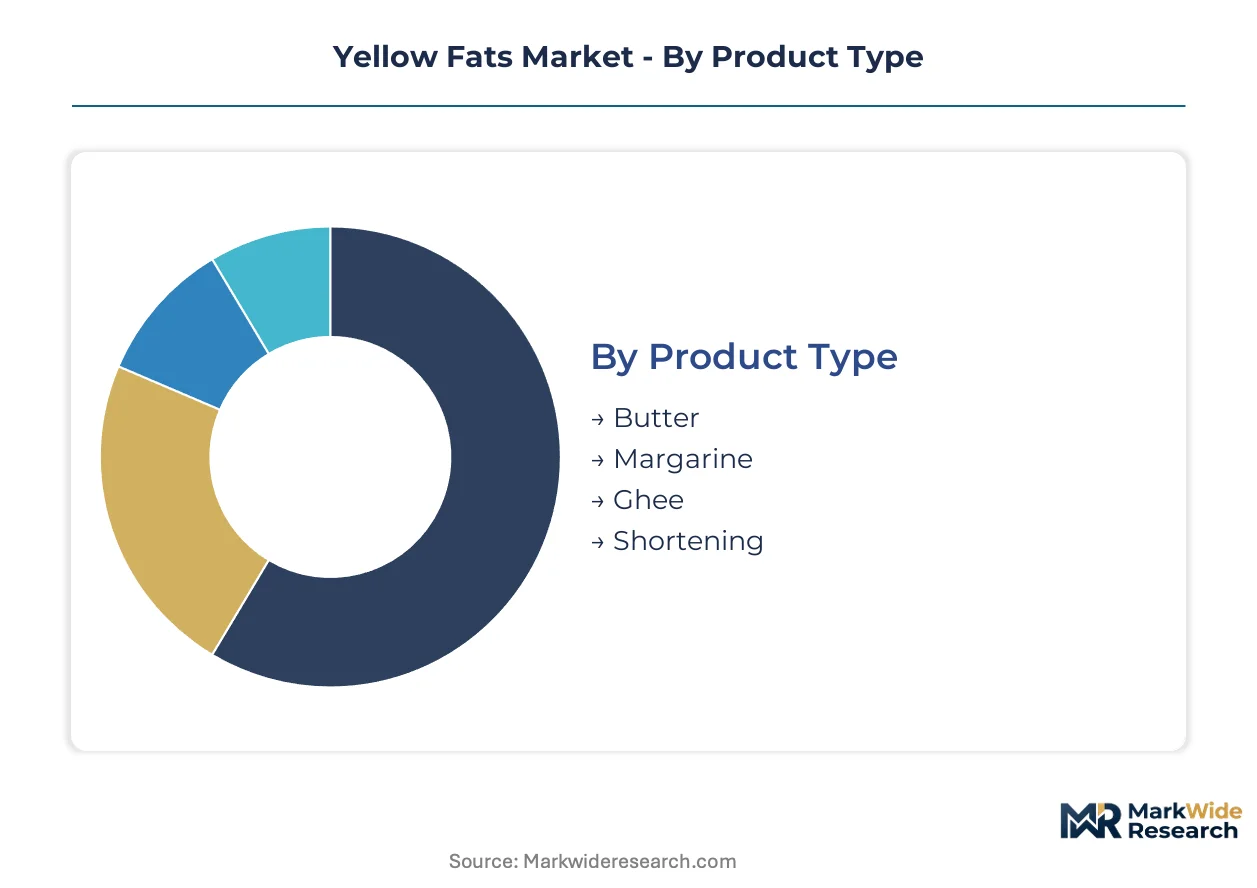
Yellow fats procurement decisions hinge on functional performance requirements, regulatory compliance burdens, and supply chain verification standards. Distinct buyer archetypes—industrial formulators, food service operators, and household consumers—prioritize different attribute bundles across fat content, emulsifier systems, and provenance credentials.
Product Type:
Buyers select product types based on price-positioning strategy and end-use performance specifications rather than ingredient origin alone.
- Butter:Anhydrous milk fat formulations deliver 80-82% lipid content with distinctive dairy flavor profiles and superior lamination performance in croissant and puff pastry production. Premium retail positioning in French and German supermarkets concentrates demand for PDO-certified churned varieties, though fluid milk cost volatility compresses processor margins outside cooperative structures.
- Margarine:Vegetable oil-based spreads with engineered water-in-oil emulsions compete aggressively on unit cost in industrial baking and frying applications. Southeast Asian quick-service restaurant chains specify high-oleic sunflower and palm olein blends for extended fry life, with RSPO certification now mandatory for EU-facing export volumes.
- Ghee:Clarified butter with moisture removal exceeding 99% offers high smoke points and extended ambient shelf stability for South Asian cuisine preparation. Organized retail penetration in Indian tier-2 cities is pulling branded cow and buffalo ghee into formal channels under FSSAI fortification mandates.
- Shortening:Fully hydrogenated vegetable oil formulations provide plastic fat functionality for pie crusts and cookies without water phase interference. North American industrial bakeries favor interesterified alternatives to meet trans-fat elimination targets while maintaining creaming performance.
Volume sits with margarine in industrial procurement; growth tilts toward ghee as Indian urban household formalization accelerates.
Application:
Application selection follows processing temperature requirements and finished product texture specifications that dictate fat crystallization behavior.
- Baked Goods:Laminated doughs, cookies, and cakes demand precise solid fat content curves across temperature ranges to control spread and mouthfeel. German industrial bakeries are adopting enzymatically interesterified margarines to meet clean-label demands without sacrificing volume yield in layer cakes.
- Confectionery:Chocolate and compound coatings require tempered fat systems with sharp melting profiles and bloom resistance. Cocoa butter equivalents from palm mid-fraction and shea stearin blends face EU Deforestation Regulation traceability requirements that extend to plantation-level geolocation data.
- Dairy Products:Ice cream, cream cheese, and recombined milk applications utilize anhydrous milk fat and butteroil for standardized fat content and flavor consistency.
- Sauces:Emulsified dressings and cooking sauces require stable water-in-oil or oil-in-water systems that resist freeze-thaw breakdown. Southeast Asian food manufacturers specify ghee and butter for authentic curry and béchamel preparations in export-oriented production.
Revenue concentrates in baked goods manufacturing; sauces represent the steepest expansion trajectory as global cuisine adoption broadens.
End User:
End user category determines contract structure, certification burden, and price sensitivity through procurement scale and ESG reporting obligations.
- Food Service:Institutional caterers and quick-service chains consolidate volumes toward multi-year supply agreements with verified sustainability credentials. French and Dutch contract catering for corporate campuses prioritizes RSPO-certified and carbon-footprint-documented fat supplies for Scope 3 emission reporting.
- Retail:Supermarket and convenience store channels demand differentiated positioning through PDO designations, organic certification, and clean-label emulsifier declarations.
- Industrial:Food manufacturers and ingredient suppliers prioritize functional consistency and long-term price hedging over brand equity, with formulation flexibility enabling rapid reformulation for regulatory compliance.
- Household:Direct consumer purchases concentrate in Indian metropolitan clusters where cold-chain e-commerce subscriptions enable cultured butter and artisanal ghee delivery.
Procurement scale favors industrial buyers; margin expansion tilts toward food service as ESG-linked vendor selection hardens.
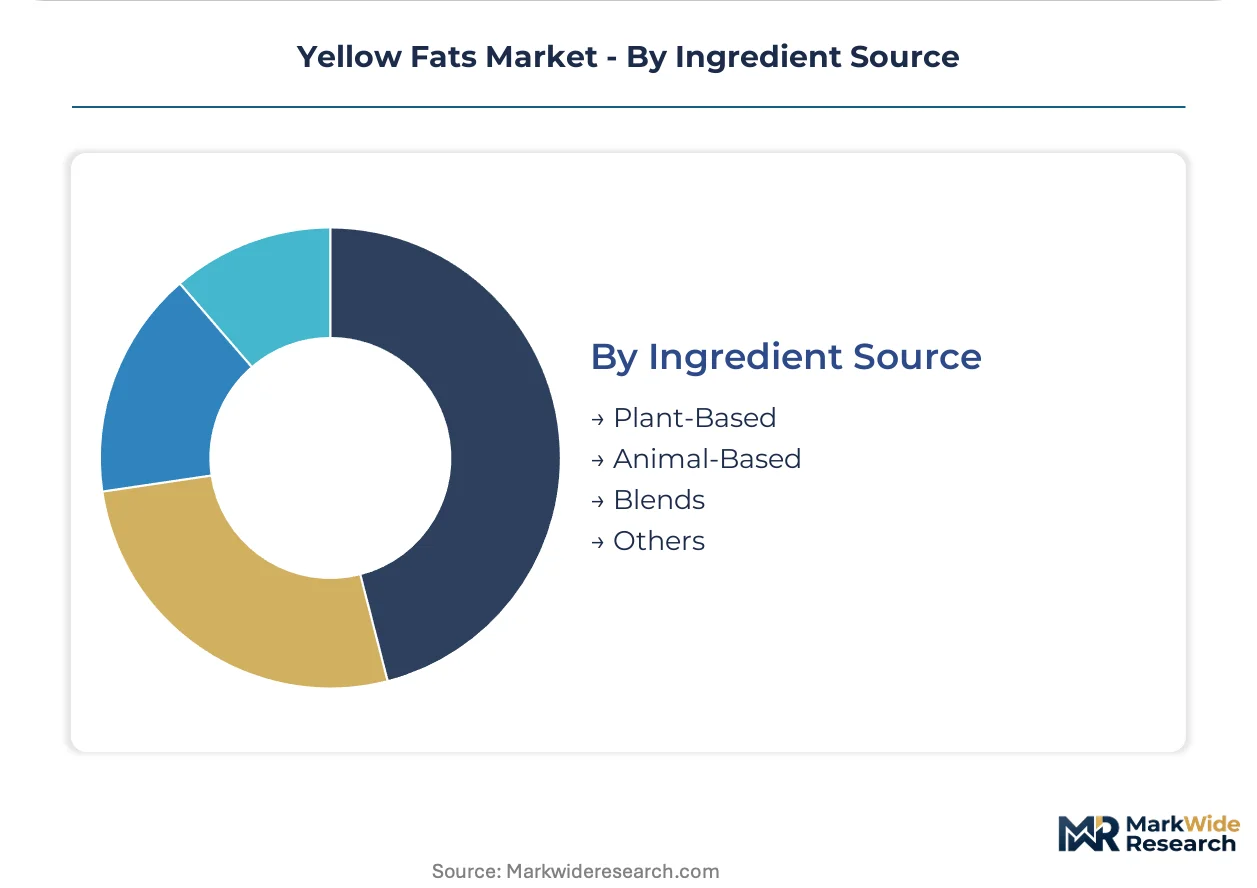
Ingredient Source:
Source selection increasingly reflects regulatory compliance timelines and carbon-border adjustment positioning rather than traditional cost optimization.
- Plant-Based:Palm, sunflower, rapeseed, and coconut oil derivatives dominate volume through cost efficiency and supply security, though EU Deforestation Regulation and REACH traceability mandates elevate compliance overhead for palm-dependent formulations.
- Animal-Based:Milk fat from bovine sources delivers irreplaceable flavor and texture performance in premium applications, with Northwestern European cooperative structures controlling fluid milk pricing and limiting non-integrated processor flexibility.
- Blends:Hybrid formulations balance cost and functionality through precise ratio engineering of dairy and vegetable components, requiring sophisticated emulsifier systems that face tightening ECHA authorization procedures.
- Others:Precision fermentation-derived fats and cultivated animal lipids occupy nascent premium positioning with clean-label appeal but face scale-up economics and novel food approval pathways.
Volume concentrates in plant-based sourcing; investment flow tilts toward precision fermentation as carbon-border alignment creates first-mover premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates household demand for branded ghee and butter as urban retail formalization accelerates. Procurement power shifts toward long-term supply contracts with verified sustainability credentials. Regulatory divergence across major producing regions is fragmenting sourcing protocols and compliance burdens.
India
Tier-2 and tier-3 cities drive organized retail penetration for cow and buffalo ghee. FSSAI fortification mandates standardize product formulations entering formal channels. Mumbai and Delhi metropolitan clusters anchor cold-chain e-commerce subscriptions for cultured butter delivery.
Germany
Industrial bakeries adopt enzymatically interesterified margarines for clean-label laminated dough production. EU Green Deal deforestation-free requirements reshape palm oil procurement protocols. The Rhine-Ruhr industrial corridor concentrates margarine blending capacity serving export-oriented food manufacturers.
United States
North American retail butter segments concentrate brand equity value in premium positioning. FDA standards of identity and USDA dairy grading systems govern interstate commerce rules. Wisconsin and California dairy cooperatives control fluid milk pricing for butter processors.
Indonesia
El Niño-driven supply disruptions in palm plantations create input cost volatility for margarine blenders. RSPO certification requirements for EU-facing exports elevate compliance overhead. Sumatra and Kalimantan plantation clusters face EU Deforestation Regulation traceability mandates.
France
PDO-certified churned butter varieties command premium retail positioning in supermarket channels. ECHA REACH Annex XIV procedures tighten emulsifier approval pathways for food-contact substances. The Brittany dairy basin anchors cooperative-controlled butter production for export markets.
Yellow Fats Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and plant-based convergence. Market structure consolidates around integrated dairy cooperatives and diversified consumer goods conglomerates with global sourcing infrastructure. Two strategic archetypes dominate: backward-integrated dairy cooperatives controlling fluid milk supply, and multinational blenders leveraging palm oil procurement scale. Competitive moves concentrate on multi-year supply agreements with verified sustainability credentials and enzymatic interesterification technology licensing.
Within the cooperative archetype, FrieslandCampina N.V. and Land O'Lakes Inc. exemplify structures with captive dairy farming networks. Among diversified consumer goods groups, Unilever Group and Kraft Heinz Company occupy positions spanning retail brand equity and industrial supply contracts. Arla Foods represents the European dairy cooperative model with integrated milk sourcing.
| Leading Market Players |
|---|
| Arla Foods |
| Nestle SA |
| Unilever Group |
| Kraft Heinz Company |
| Land O'Lakes Inc. |
| Bunge Limited |
| Danone SA |
| FrieslandCampina N.V. |
| Amul |
| Others |
Value Network & Pricing Analysis
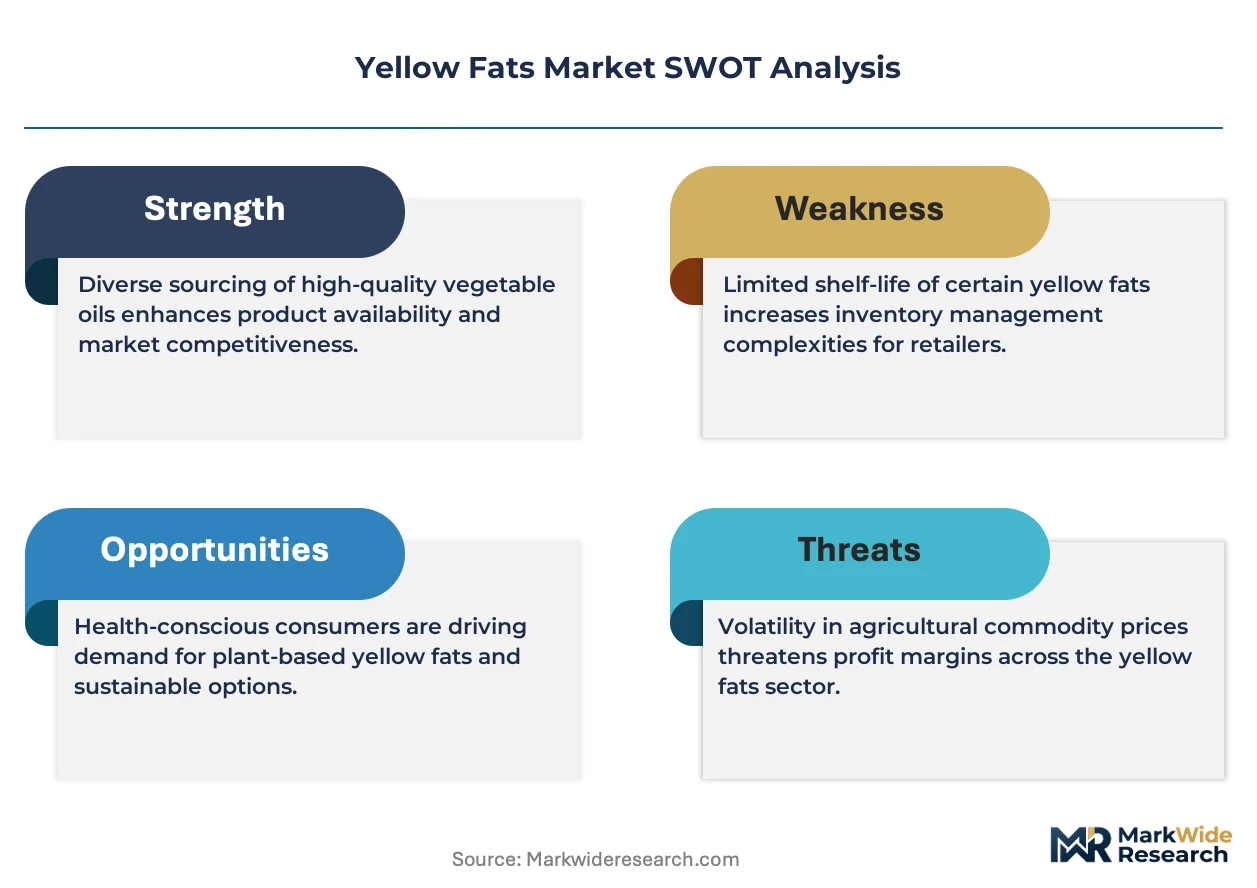
EU Green Deal deforestation-free mandates are forcing food manufacturers to lock in RSPO-certified palm oil contracts, concentrating procurement power among verified suppliers and compressing margins for non-compliant blenders. This specification-driven consolidation is reshaping how margarine producers negotiate input costs and pass compliance premiums downstream.
Pricing Analysis
Volume sits with commodity margarine in industrial baking, while margins concentrate in PDO-certified butter and premium ghee. Price differentiation rests on RSPO certification tier and cooperative-backed dairy integration. Pricing pressure stems from El Niño-driven palm oil volatility squeezing blend-dependent producers. Industrial buyers exhibit highest price sensitivity; food service operators with ESG reporting obligations absorb certification premiums.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for palm oil and dairy fat redistribution. Supply concentrates in Indonesia, Malaysia, and Northwestern European dairy cooperatives. Raw material flows draw from crude palm oil, fluid milk, and high-oleic sunflower feedstocks. Single-source vulnerability runs through Indonesian plantation clusters facing EU Deforestation Regulation traceability mandates. Distribution runs through institutional catering procurement with multi-year verified supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with players pursuing captive dairy farming networks and plantation-level sourcing control to secure margin insulation against regulatory compliance costs.
For Market Incumbents: Hedge against palm oil volatility by securing long-term RSPO-certified supply agreements with geolocation-verified Indonesian and Malaysian plantations. Deepen backward integration into dairy cooperatives in Northwestern Europe to control fluid milk pricing. Invest in enzymatic interesterification licensing to defend formulation flexibility as ECHA tightens emulsifier approvals. For New Entrants and Emerging Players: Launch via cold-chain e-commerce subscriptions targeting Indian metropolitan clusters for cultured butter and artisanal ghee delivery. Exploit underpenetrated tier-2 and tier-3 Indian cities where organized retail formalization is accelerating. Partner with quick-service restaurant chains in Southeast Asia specifying authentic ghee and butter for cuisine preparation. For Investors and Strategic Acquirers: The window for entry favors precision fermentation specialists with clean-label fat platforms and verified Scope 3 emissions data. Acquisition targets should demonstrate carbon-border adjustment alignment capability. Watch for EU CBAM phase-in acceleration as the inflection signal for first-mover premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Cooperatives | FrieslandCampina and Land O'Lakes structures demonstrate margin protection through captive milk supply. |
| RSPO Certification Investment | EU Deforestation Regulation compliance creates supplier onboarding bottlenecks favoring early certifiers. |
| Enzymatic Interesterification Licensing | German industrial bakeries adopt clean-label texture engineering to meet trans-fat elimination targets. |
| Cold-Chain E-Commerce Launch | Mumbai and Delhi clusters enable subscription-based cultured butter delivery outside traditional retail. |
| Precision Fermentation Scale-Up | Carbon-border adjustment alignment creates first-mover premiums for verified low-emission fat production. |
Research Methodology
Independent corroboration across procurement directors at quick-service restaurant chains, sustainability officers at margarine blenders, and category managers at Indian organized retailers underwrites the qualitative findings. Primary interviews with food service operators, dairy cooperative representatives, and palm oil traders combined with secondary validation from FSSAI fortification records, EU Deforestation Regulation implementation documents, and RSPO certification databases. Bottom-up volume triangulation against top-down value estimates anchored the market sizing.
Comparable historical periods spanning pre-pandemic baseline, supply disruption windows, and regulatory implementation phases anchored the projection framework. The analysis modeled product type, application, end user, and ingredient source dimensions across the analysis window. CAGRs derived from segment-level growth trajectories weighted by India urbanization rates, EU compliance timeline acceleration, and palm oil price cycle positioning. Forecast inputs incorporated FSSAI fortification mandate penetration curves and REACH Annex XIV emulsifier restriction schedules.
El Niño recurrence patterns, EU CBAM expansion scope, and precision fermentation scale-up economics are the dominant revision risks. Forecasts reflect assumptions around regulatory enforcement consistency and cooperative pricing power persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
Europe Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
United Kingdom Interesterified Fats Market
Food Enhancers and Additives
Mexico Water Enhancer Market
Food Enhancers and Additives
UK Food Flavor and Enhancer Market
Food Enhancers and Additives
Lignans Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
South Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
Browning Enhancers Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
Liquid Smoke Market