
 North America Food Thickeners Market | 2026-2036
North America Food Thickeners Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Thickeners Market Analytics
Plant-based hydrocolloid innovation is narrowing the performance gap between conventional starch systems and premium gum alternatives in texture-modified foods. Ingredion Incorporated leverages its potato and tapioca starch verticals to anchor supply security for dysphagia-focused product lines. Cargill Inc competes through its broad oilseed and grain processing footprint, sustaining cost advantages across modified starch categories. CP Kelco specializes in microbial fermentation-derived gellan and xanthan systems, differentiating on label-friendly positioning for beverage suspension applications.
Food thickeners are hydrocolloid or polysaccharide additives that increase viscosity in liquid and semi-liquid matrices, typically functioning at concentrations between 0.5% and 5.0% by weight depending on target rheology and base composition. Their primary commercial purpose centers on enabling safe swallowing for dysphagia patients, stabilizing emulsions in processed foods, and controlling syneresis in dairy matrices. The starch segment dominates volume throughput due to its cost structure and familiarity among institutional foodservice operators, while gum systems capture disproportionate margin pools in clinical nutrition and premium beverage applications. Dairy Products represents the fastest-growing application channel as Greek-style yogurt and protein-fortified drink formulations demand enhanced mouthfeel and suspension stability.
FDA oversight of food additive safety under 21 CFR, USDA FSIS labeling requirements for meat and poultry containing binders, and Health Canada’s Food and Drug Regulations collectively shape product approval pathways and label claims across North American jurisdictions. These frameworks compel manufacturers to maintain granular documentation on GRAS status, allergen cross-contact controls, and substantiated texture-modification efficacy. Stakeholders must monitor evolving dysphagia diet standardization initiatives from the International Dysphagia Diet Standardisation Initiative and their adoption trajectory within Medicare-reimbursed long-term care settings.
Market Dynamics
FDA guidance on modified food textures under 21 CFR is compressing formulation cycles for dysphagia-targeted thickeners, forcing manufacturers to validate viscosity stability across institutional reheating protocols before securing long-term care contracts.
Growth Catalysts
- IDDSI Adoption:The International Dysphagia Diet Standardisation Initiative framework is embedding standardized texture levels into Medicare-reimbursed facility menus across the United States, creating procurement pull for pre-calibrated thickener systems.
- Clinical Nutrition Expansion:Pediatric feeding disorder clinics are integrating texture-modified protocols into early intervention programs, widening the prescriber base beyond geriatric specialists.
- Clean-Label Hydrocolloids:Microbial fermentation-derived gellan and xanthan systems are displacing modified starch in premium beverage applications where ingredient transparency commands shelf placement.
Market Restraints
- Input Cost Volatility:Tapioca starch supply from Southeast Asian processing clusters faces weather-driven crop fluctuations, compressing margin predictability for cost-anchored product lines.
- Technical Performance Ceilings:Native starch systems exhibit retrogradation and syneresis under freeze-thaw cycling, limiting their utility in prepared meal distribution channels requiring extended cold chain holding.
- Regulatory Documentation Burden:Health Canada's Food and Drug Regulations mandate granular allergen cross-contact protocols that extend approval timelines for novel hydrocolloid introductions.
Strategic Opportunities
- Underpenetrated Sub-Regions:Canadian long-term care networks outside Ontario and Quebec show lower IDDSI compliance rates, creating first-mover positioning for education-supported thickener suppliers.
- Protein Beverage Suspension:Greek-style yogurt and plant-protein drink matrices require enhanced mouthfeel stabilization, opening formulation partnerships with dairy alternative processors.
- USDA FSIS Labeling Alignment:Meat and poultry binder regulations are evolving to permit cleaner hydrocolloid declarations, enabling texture-modified pureed protein products in institutional foodservice.
Industry Challenges
- Rheology Specialist Scarcity:Formulation teams with combined food science and clinical dysphagia expertise remain concentrated in academic medical centers, constraining product development bandwidth.
- Legacy Equipment Integration:Institutional kitchens operating on batch-scale mixing infrastructure face viscosity inconsistency when transitioning to pre-thickened liquid concentrates requiring precise hydration protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Thickeners Market |
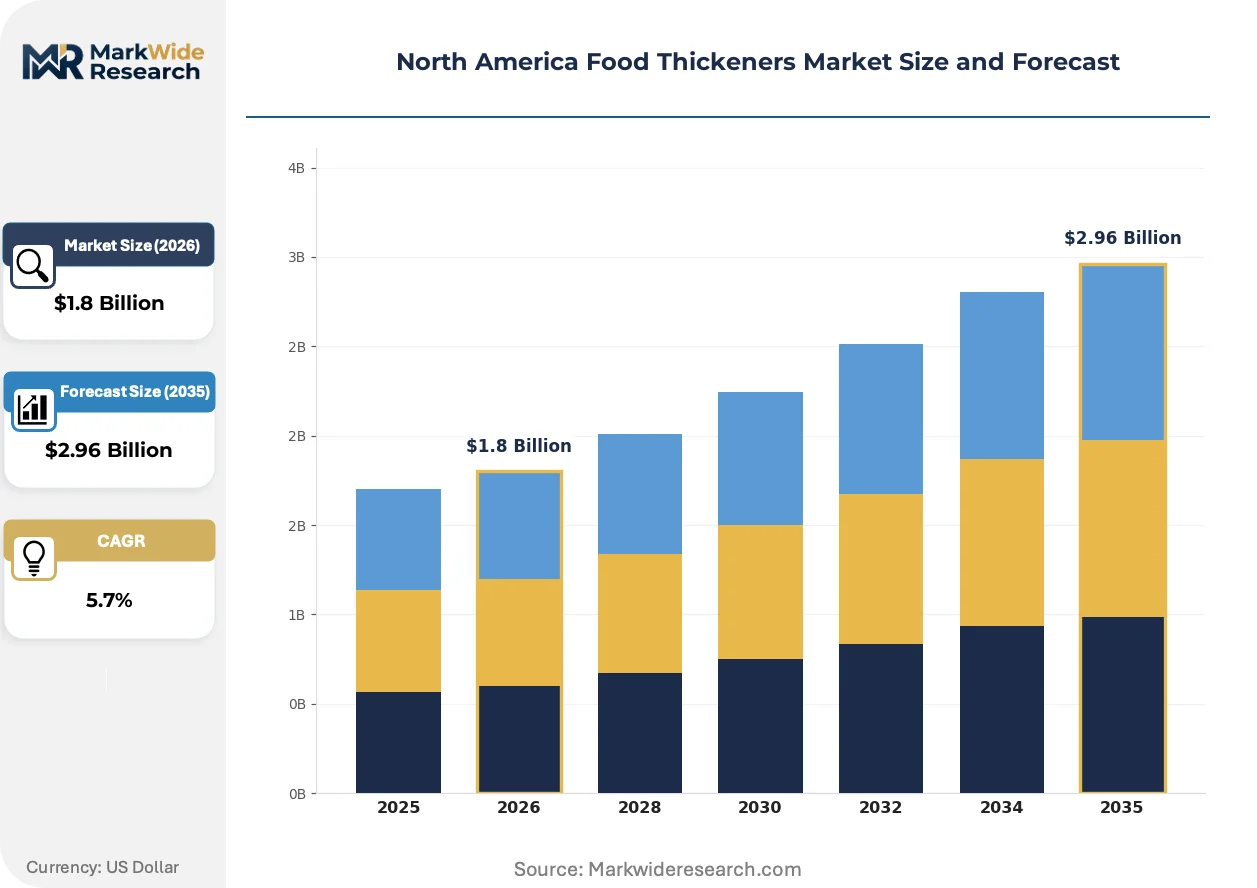
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch, Gum, Pectin, Protein Application: Soups, Sauces, Beverages, Dairy Products End User: Food Manufacturers, Retailers, Restaurants, Home Cooks Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Tate & Lyle PLC, Kerry Group PLC, Archer Daniels Midland Company, DuPont de Nemours Inc, Ingredion Incorporated, Cargill Inc, CP Kelco, Ashland Inc, Darling Ingredients Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Thickeners Market Evolving Landscape
Formulation science is pivoting toward label-friendly hydrocolloids that replicate the viscosity stability of chemically modified starches without triggering clean-label penalties in retail and clinical channels.
Enzymatically modified tapioca starch is migrating from conventional dysphagia management into pediatric nutrition and sports hydration segments where mouthfeel precision and rapid dispersion matter. Manufacturers serving neonatal intensive care units are adopting these systems for enteral feeding tube compatibility. The shift is compressing demand for pre-gelatinized corn starch in premium clinical applications.
FDA oversight under 21 CFR Part 170 is tightening substantiation requirements for GRAS self-determinations on novel hydrocolloid sources, particularly fermentation-derived biomass. Manufacturers must now submit expanded toxicity datasets before commercializing microbial polysaccharides. Beverage suspension applications face the steepest compliance ramps as FDA scrutinizes label claims linking viscosity to swallowing safety.
Institutional procurement in United States senior care networks is consolidating around pre-thickened liquid contracts with guaranteed viscosity ranges, displacing traditional powder-based thickener dispensing. Group purchasing organizations are negotiating multi-year supply agreements that lock in IDDSI Level 2 and Level 3 specifications. This pattern concentrates most visibly in Florida and Arizona retirement community clusters where managed care penetration is deepest.
North America Food Thickeners Market Segmentation
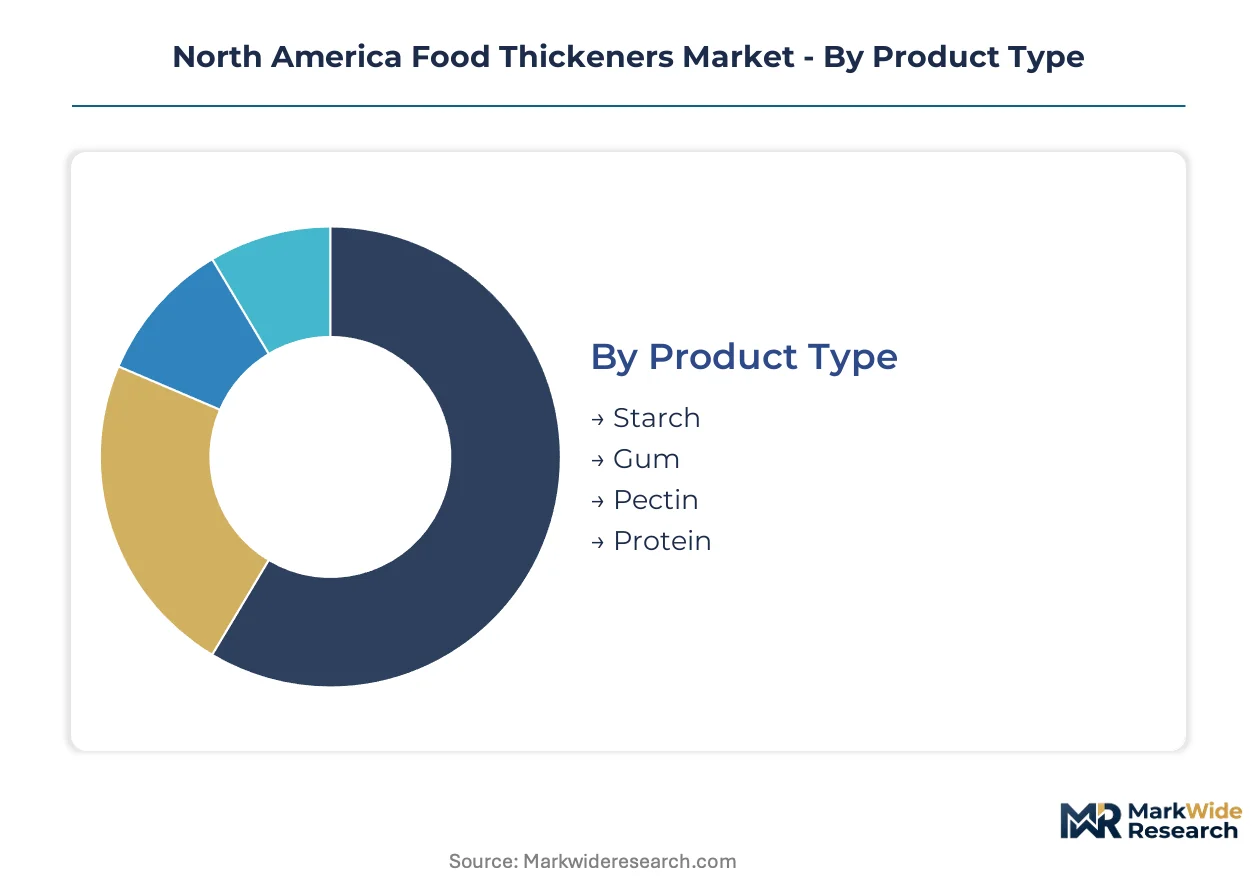
Segmentation in the North America Food Thickeners Market reveals how formulation requirements diverge across clinical nutrition, institutional foodservice, and consumer retail channels. Each dimension—product chemistry, application matrix, end-user sophistication, and procurement pathway—creates distinct performance specifications and margin structures.
Product Type:
Mature modified starches dominate volume throughput while microbial fermentation-derived hydrocolloids represent the emerging premium tier.
- Starch:Modified corn, tapioca, and potato starches deliver cost-anchored viscosity at 0.5-5.0% inclusion rates. Institutional foodservice operators in United States senior care networks specify these systems for IDDSI-compliant texture modification under Medicare-reimbursed procurement contracts.
- Gum:Xanthan, guar, and locust bean derivatives achieve superior freeze-thaw stability and suspension clarity. Premium beverage formulators in California and New York dairy alternative clusters specify gum systems where label transparency commands shelf placement.
- Pectin:Citrus and apple-derived high-methoxyl pectins function across acid-stable gel matrices. Jam and jelly processors in Florida and Michigan fruit belt regions specify these for clean-label positioning.
- Protein:Whey and egg white albumen systems provide dual functionality as nutritional fortifiers and texture modifiers. Sports nutrition manufacturers in Colorado and Utah protein processing corridors integrate these for mouthfeel in ready-to-drink formulations.
Starch retains volume leadership; gum holds the steepest expansion curve.
Application:
Application segmentation tracks how rheology requirements shift across thermal processing intensity and serving temperature protocols.
- Soups:Heat-stable hydrocolloids prevent viscosity breakdown during retort sterilization. United States prepared meal distributors specify these for extended shelf-life pureed diets in long-term care.
- Sauces:Emulsion-stabilizing starches and gums control syneresis through freeze-thaw cycles. Canadian institutional foodservice operators in Ontario and Quebec demand these for bulk sauce concentrates.
- Beverages:Rapid-dispersion modified starches and gellan systems enable swallowing safety without clumping. Pediatric feeding clinics in Texas and Illinois early intervention programs specify these for texture-modified oral nutrition.
- Dairy Products:Protein-fortified drink matrices require enhanced suspension stability. Greek-style yogurt processors in New York and Wisconsin dairy corridors drive specification intensity here.
Dairy Products captures the most rapid specification evolution; soups maintain the deepest procurement volume.
End User:
End-user segmentation distinguishes between formulation sophistication and regulatory documentation requirements.
- Food Manufacturers:Industrial-scale processors demand batch-to-batch viscosity consistency with full GRAS documentation. FDA 21 CFR compliance mandates drive supplier qualification protocols.
- Retailers:Private-label brands specify clean-label hydrocolloids for shelf differentiation. United States mass-market chains negotiate multi-year thickener supply agreements with guaranteed IDDSI calibration.
- Restaurants:Foodservice operators prioritize instant dispersion and holding stability. Quick-service chains in Florida and Arizona retirement community clusters specify pre-thickened concentrates.
- Home Cooks:Consumer-packaged powder thickeners target dysphagia patients and caregivers. Online retail channels in dispersed rural United States sub-regions serve this segment.
Food Manufacturers concentrate procurement volume; retailers are expanding most quickly into private-label positioning.
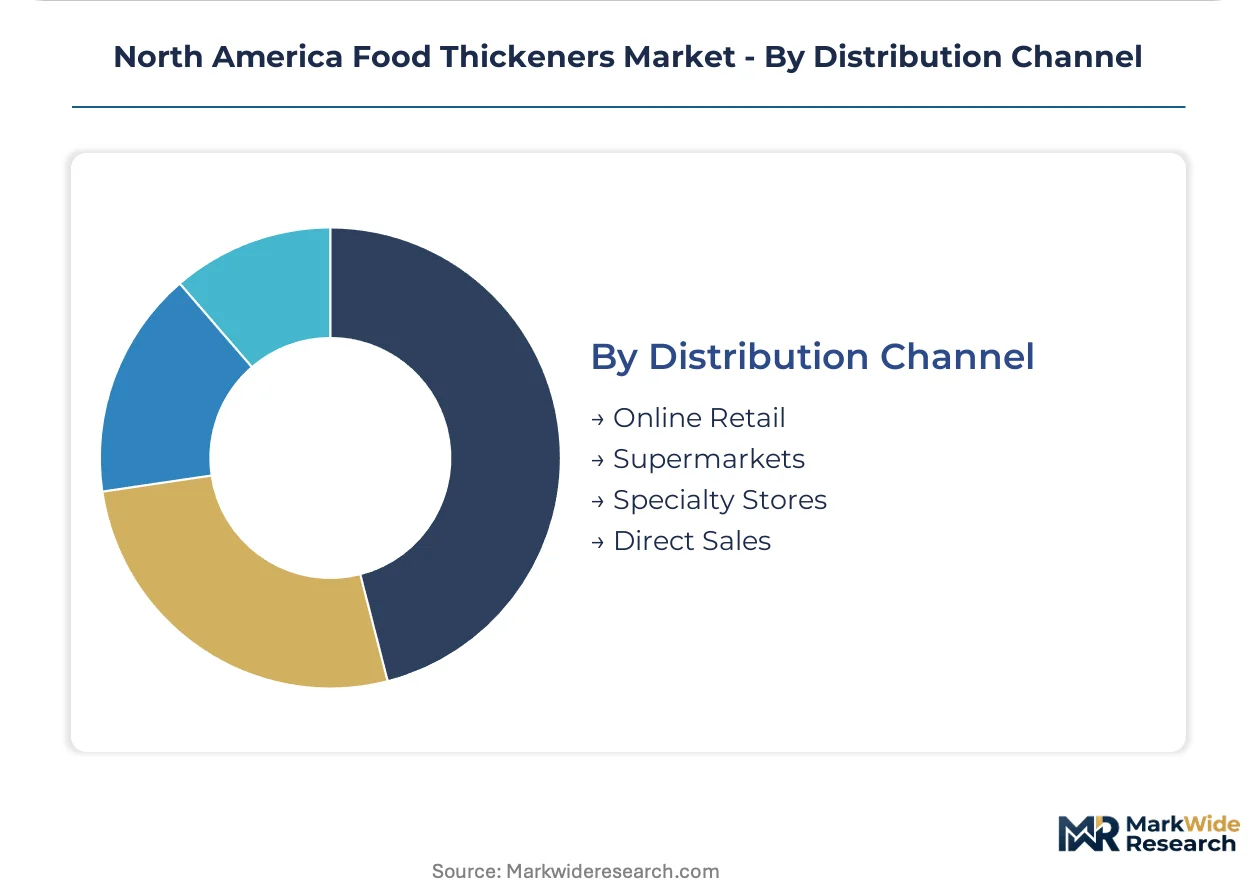
Distribution Channel:
Channel segmentation reflects how procurement centralization and technical service requirements shape supplier access.
- Online Retail:Direct-to-consumer platforms serve home caregivers and small clinical practices. United States rural and exurban geographies with limited specialty store access depend on this channel.
- Supermarkets:Mass-market retail chains stock consumer-format thickeners near pharmacy and nutrition aisles. Group purchasing organizations negotiate regional distribution contracts.
- Specialty Stores:Medical supply retailers and dysphagia-focused distributors provide clinical consultation. Canadian long-term care networks outside Ontario and Quebec source through these channels.
- Direct Sales:Manufacturer field representatives service institutional accounts with technical formulation support. United States senior care facility networks rely on direct relationships for IDDSI compliance verification.
Direct Sales anchors institutional procurement; online retail gains share fastest in home-use segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of tapioca and potato starch into North American processing hubs outpace regional export volumes of finished hydrocolloid formulations, creating persistent trade deficits in raw material inputs. Canada and Mexico supply specialty gum extracts and fermentation-derived polysaccharides back into United States distribution channels. Cross-border regulatory alignment under USMCA facilitates ingredient transit while preserving distinct national approval pathways.
United States
Florida and Arizona retirement community clusters drive procurement consolidation for IDDSI-compliant pre-thickened liquids under Medicare-reimbursed managed care contracts. FDA 21 CFR Part 170 oversight tightens GRAS substantiation requirements for novel microbial polysaccharides entering beverage suspension applications. Chicago and Dallas institutional foodservice corridors anchor bulk modified starch distribution networks serving long-term care facility chains.
Canada
Ontario and Quebec long-term care networks maintain higher IDDSI compliance rates than Prairie Provinces or Atlantic Canada, generating uneven demand distribution for clinical nutrition thickeners. Health Canada's Food and Drug Regulations mandate granular allergen cross-contact documentation that extends novel hydrocolloid approval timelines. Toronto and Montreal dairy processing clusters specify clean-label pectin and gum systems for Greek-style yogurt mouthfeel stabilization.
Mexico
Jalisco and Bajío Region fruit processing belts supply citrus and apple-derived pectin feedstocks for North American jam and jelly manufacturers. Mexico's national health regulator COFEPRIS maintains distinct additive safety protocols that diverge from FDA harmonization efforts. Guadalajara and Querétaro industrial corridors concentrate starch modification capacity serving both domestic food manufacturers and United States export contracts.
North America Food Thickeners Market Competitive Landscape
On the supply side, the industry is consolidating around multi-hydrocolloid portfolios that span starch, gum, and fermentation-derived categories. Tier-one suppliers anchor procurement relationships with institutional foodservice operators through multi-year IDDSI specification contracts. Three strategic archetypes dominate: integrated agribusiness processors with captive starch supply, specialized fermentation houses with microbial polysaccharide expertise, and regional distributors with clinical nutrition technical service capabilities. Competitive moves concentrate on backward integration into tropical starch sourcing and formulation partnerships with dairy alternative processors.
Within the integrated agribusiness tier, Ingredion Incorporated and Cargill Inc occupy positions that exemplify supply security strategies anchored in potato and tapioca starch verticals. CP Kelco represents the specialized fermentation archetype, with its San Diego-based operations focusing on gellan and xanthan systems derived from microbial biomass. These three companies illustrate how competitive positioning diverges between cost-anchored commodity throughput and premium label-friendly positioning.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Kerry Group PLC |
| Archer Daniels Midland Company |
| DuPont de Nemours Inc |
| Ingredion Incorporated |
| Cargill Inc |
| CP Kelco |
| Ashland Inc |
| Darling Ingredients Inc |
| Others |
Value Network & Pricing Analysis
Guadalajara and Querétaro industrial corridors anchor North American starch modification capacity, concentrating upstream supply leverage among integrated processors who dictate contract terms to downstream formulators seeking IDDSI-compliant hydrocolloid systems.
Pricing Analysis
Modified starch versus microbial fermentation-derived hydrocolloids versus enzymatically processed tapioca systems define the three-tier pricing structure across the market. Premium-mid-economy pricing differentiation rests on IDDSI certification tier, clean-label positioning, and guaranteed viscosity stability across institutional reheating protocols. Cost compression in native starch tiers is intensifying because Southeast Asian tapioca crop volatility feeds raw material uncertainty into contract negotiations. Food manufacturers with multi-year procurement agreements exhibit lowest price sensitivity; home caregivers purchasing consumer-format powder thickeners through online retail channels show highest elasticity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Thai and Vietnamese tapioca processors have become standard for North American starch importers managing working capital through volatile harvest cycles. Geographic supply concentration centers on Thailand, Vietnam, and Indonesia for cassava feedstocks; the United States and Canada for microbial fermentation infrastructure; and Mexico for citrus pectin extraction. Raw material dependencies include cassava root, potato tubers, and fermentation biomass substrates. Tariff exposure on Southeast Asian starch imports creates structural risk as USMCA rules of origin complicate transshipment strategies. Distribution runs through direct sales teams for institutional accounts, specialty medical distributors for Canadian long-term care networks, and group purchasing organizations consolidating United States senior care procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IDDSI framework adoption functions as a platform-economics inflection, where interoperability between thickener specifications and institutional procurement systems creates winner-take-most dynamics for suppliers achieving first-mover certification lock-in.
For Market Incumbents: Harden IDDSI specification control by embedding guaranteed viscosity ranges into multi-year group purchasing organization contracts before emerging fermentation houses achieve GRAS substantiation for novel microbial polysaccharides. Deepen backward integration into Thai tapioca processing clusters to anchor cost position against weather-driven supply volatility threatening margin predictability in modified starch product lines. For New Entrants and Emerging Players: Canadian long-term care networks outside Ontario and Quebec represent the most penetrable entry point, where lower IDDSI compliance rates create education-supported thickener supplier opportunities without incumbent contract lock-in. Pediatric feeding disorder clinics integrating texture-modified protocols into early intervention programs offer a second white-space channel. A go-to-market angle emphasizing rapid-dispersion enzymatic starch systems for neonatal intensive care enteral feeding compatibility bypasses established geriatric-focused distribution relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized fermentation houses with validated microbial polysaccharide pipelines over integrated agribusiness processors facing commodity starch margin compression. Long-term viability over the coming decade hinges on clean-label hydrocolloid substitution trajectories displacing modified starch in premium beverage and clinical nutrition applications. The signal to watch is FDA 21 CFR Part 170 enforcement intensity on GRAS self-determinations, which would accelerate consolidation toward suppliers with pre-submitted toxicity datasets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Starch Sourcing | Captive tapioca supply from Thai processing clusters insulates margin predictability against weather-driven crop fluctuations. |
| IDDSI Certification Investment | Pre-calibrated thickener systems lock in multi-year procurement contracts with Medicare-reimbursed United States senior care networks. |
| Microbial Fermentation Capacity Expansion | Gellan and xanthan production scale-up enables label-friendly positioning in premium California and New York beverage clusters. |
| Formulation Partnership with Dairy Alternative Processors | Protein beverage suspension expertise opens Greek-style yogurt and plant-protein drink specification channels. |
| Direct Sales Force Expansion in Canadian Prairie Provinces | Technical service capabilities penetrate underpenetrated long-term care networks with education-supported IDDSI compliance programs. |
Research Methodology
Cross-validation between regulatory filing analysis and trade flow databases anchors the qualitative findings on hydrocolloid approval pathways and raw material import patterns. Primary interviews with formulation scientists at clinical nutrition manufacturers, procurement directors at United States senior care facility networks, regulatory affairs specialists navigating FDA 21 CFR Part 170 submissions, and group purchasing organization contract managers combined with secondary validation against FDA GRAS notices, Health Canada Food and Drug Regulations, USMCA customs documentation, and SEC 10-K disclosures from listed ingredient suppliers. Bottom-up demand modeling across end-use segments triangulates with top-down trade flow analysis.
Calibration against historical viscosity specification adoption curves and institutional procurement contract tenors shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include hydrocolloid chemistry tier, application matrix thermal processing intensity, end-user formulation sophistication, and procurement channel centralization. CAGRs derive from fitted adoption curves for IDDSI compliance penetration and clean-label substitution elasticities. Industry-specific forecast inputs include Medicare reimbursement policy trajectories for texture-modified diets and FDA enforcement intensity on novel microbial polysaccharide substantiation.
Practitioners should monitor IDDSI adoption velocity in Canadian provincial long-term care networks, FDA GRAS substantiation backlog clearance rates, and Southeast Asian cassava harvest yields for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
United States Water Enhancer Market
Food Enhancers and Additives
UK Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Feed Palatability Enhancers Market
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
Veratrole Market
Food Enhancers and Additives
South Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
North America Water Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Yellow Fats Market
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market