
 Australia Food Flavor and Enhancer Market | 2026-2036
Australia Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Food Flavor and Enhancer Market Outlook
Queensland's expanding food manufacturing corridor is reshaping supply dynamics for flavor houses serving Australasia. Givaudan leverages its technical application labs in Sydney to anchor premium natural flavor development for local beverage clients. Sensient Technologies Corporation competes through specialized color-flavor integration systems targeting bakery and confectionery channels. Kerry Group dominates clean-label enhancer supply to protein processors, sustaining volume through long-term manufacturing agreements.
Food flavors and enhancers comprise aromatic compounds, taste-active molecules, and savory potentiators formulated to intensify or modify sensory perception in finished foods. These inputs typically undergo solvent extraction, enzymatic modification, or controlled Maillard reaction processing to achieve targeted flavor profiles, stability thresholds, and dose efficiency in industrial food production. Natural flavors command premium positioning as FSANZ-aligned clean-label requirements tighten across retail-facing applications, while flavor enhancers gain traction in reduced-sodium product reformulations. The bakery application segment occupies mature volume pools, whereas beverages represent the fastest-growing application as functional and flavored water categories expand.
FSANZ governs flavor additive approvals and maximum permitted levels under the Australia New Zealand Food Standards Code, directly determining which novel enhancers achieve market access. The ACCC monitors labeling accuracy and anti-competitive conduct among concentrated supplier bases, while state-level food safety regulators enforce Good Manufacturing Practice compliance across production facilities. Stakeholders must track pending FSANZ novel food determinations and emerging state-based sustainability mandates that will reshape ingredient sourcing specifications.
Market Dynamics
FSANZ's updated food additive labeling requirements are compressing formulation lead times and forcing flavor houses to revalidate entire product portfolios for compliance, creating a structural bottleneck that favors suppliers with captive regulatory affairs capabilities.
Growth Catalysts
- Clean-label mandates:FSANZ-aligned natural flavor specifications are pulling reformulation investment across retail-facing applications, with beverage processors accelerating substitution timelines for synthetic alternatives.
- Queensland manufacturing corridor:The state's expanding food processing clusters are generating localized demand spikes that flavor houses must service through dedicated technical service presence.
- Reduced-sodium formulations:Savory enhancer technologies are capturing reformulation budgets as protein processors seek to maintain taste intensity while cutting sodium content.
Market Restraints
- Natural extract input volatility:Vanilla, citrus, and botanical raw material prices swing with climate-exposed harvest cycles, compressing margin predictability for natural flavor specialists.
- Supplier concentration in New South Wales:Technical application infrastructure clusters around Sydney, creating geographic dependency for national coverage and service responsiveness.
- FSANZ novel food determination timelines:Extended approval windows for innovative enhancer molecules delay commercialization by 18-36 months versus benchmark jurisdictions.
Strategic Opportunities
- Western Australia expansion:Underpenetrated food manufacturing base offers first-mover positioning for flavor houses establishing Perth technical service capabilities.
- Functional water categories:Emerging beverage applications in vitamin-fortified and adaptogenic formulations require specialized flavor masking and stability expertise.
- State-based sustainability mandates:Victoria's packaging and sourcing regulations are creating compliant-ingredient premiums that certified suppliers can capture.
Industry Challenges
- Regulatory affairs talent scarcity:FSANZ submission expertise concentrates among senior consultants, creating hiring bottlenecks for expanding flavor houses.
- Clean-label certification timelines:Third-party natural certification audits require 12-18 month validation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Food Flavor and Enhancer Market |
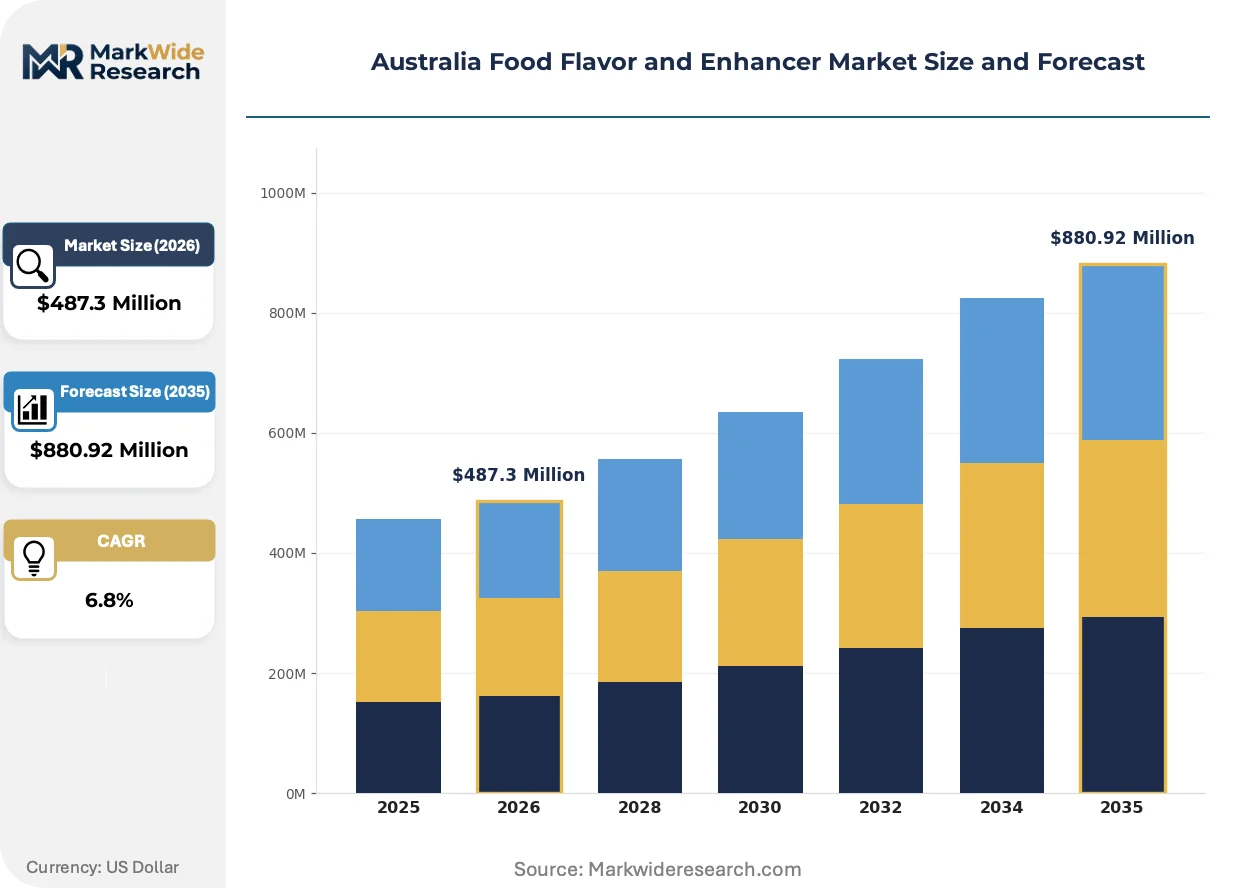
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Flavor Enhancers, Seasonings Application: Bakery, Beverages, Sauces, Snacks End User: Food Manufacturers, Restaurants, Retailers, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | International Flavors & Fragrances, Symrise AG, Givaudan, Firmenich, Takasago International Corporation, DSM-Firmenich, Sensient Technologies Corporation, Sensate Pty Ltd, Kerry Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Food Flavor and Enhancer Market Strategic Shifts
Digital formulation platforms and accelerated regulatory feedback loops are compressing product development cycles, while demand-side fragmentation forces flavor suppliers to modularize their service architectures.
Artificial intelligence-driven flavor molecule prediction is digitizing the traditional trial-and-error formulation process. Beverage and snack manufacturers in Victoria and New South Wales are piloting these platforms to cut development cycles from months to weeks. The technology is digitizing how sensory targets translate to ingredient specifications, reducing reliance on master flavorist intuition.
FSANZ's pending updates to the Australia New Zealand Food Standards Code are tightening maximum permitted levels for certain synthetic enhancers. Reformulation costs are diverting R&D budgets toward natural alternatives and clean-label positioning. Bakery and confectionery channels face the steepest compliance cliffs, with manufacturers accelerating supplier qualification processes.
Direct technical service engagement is displacing traditional distributor-mediated relationships for mid-size food processors. Flavor houses are embedding application scientists within client manufacturing facilities to co-develop formulations, compressing iteration cycles. This pattern is most visible in Queensland's emerging food corridor, where processor scale does not yet justify full in-house flavor development teams.
Australia Food Flavor and Enhancer Market Segmentation
Segmentation in the Australia Food Flavor and Enhancer Market reveals how regulatory pressure, clean-label migration, and channel fragmentation reshape supplier priorities. Understanding where volume concentrates versus where margins expand allows flavor houses to allocate technical resources and compliance investment strategically.
Product Type:
Maturity varies sharply across this dimension, with legacy synthetic formulations facing accelerated substitution while novel natural extraction methods capture reformulation budgets.
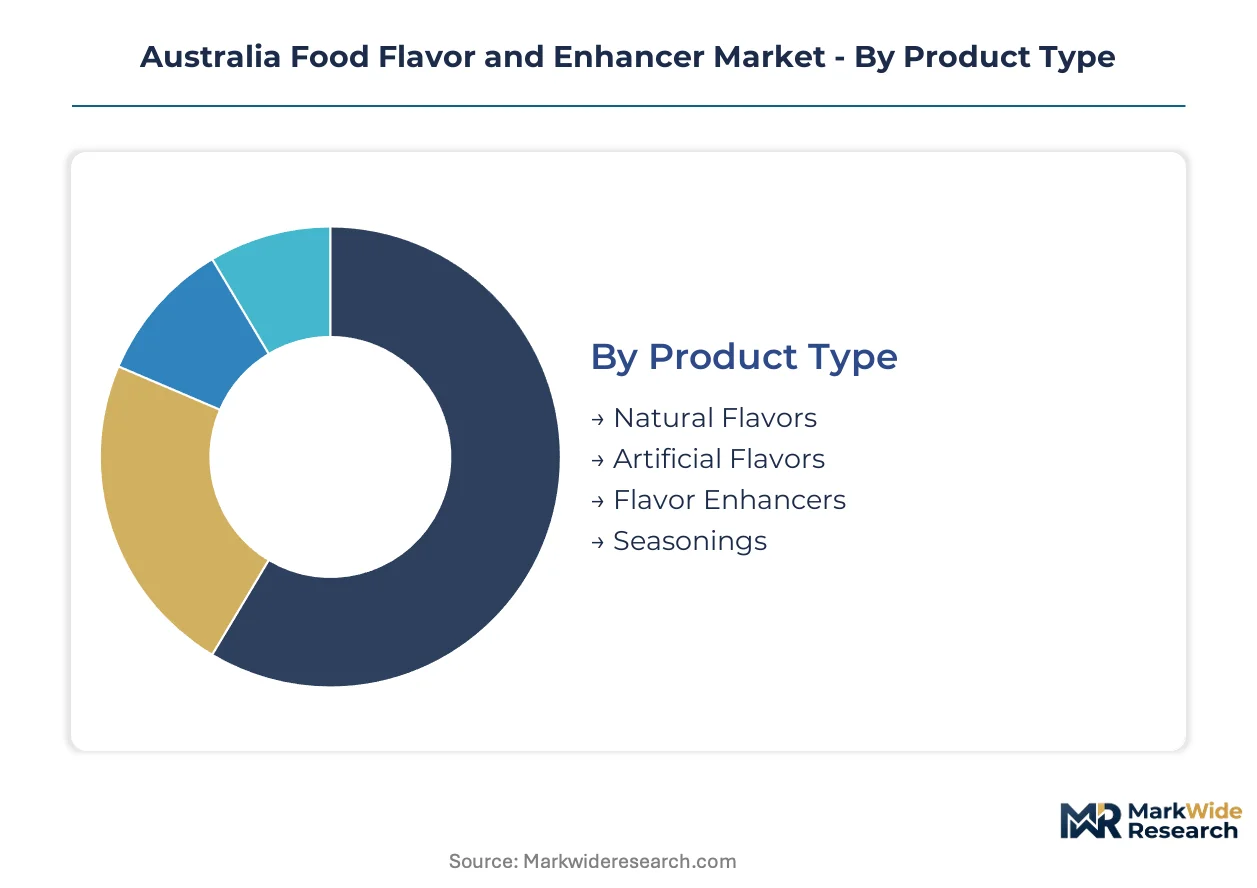
- Natural Flavors:These comprise solvent-extracted, enzymatically modified, or fermented aromatic compounds meeting FSANZ clean-label specifications. New South Wales and Victoria beverage processors are driving substitution timelines as retail-facing applications face tightened additive disclosure requirements.
- Flavor Enhancers:Taste-active molecules including nucleotides and amino acid derivatives that intensify savory perception without adding sodium. Protein processors across Queensland's expanding manufacturing corridor are capturing these technologies for reduced-sodium reformulations.
- Artificial Flavors:Synthetic aromatic compounds produced through chemical synthesis, now concentrated in industrial and foodservice channels where cost sensitivity dominates procurement decisions.
- Seasonings:Blended spice and flavor systems incorporating both natural and enhanced components, serving ready-meal manufacturers seeking single-ingredient solutions.
Natural Flavors handles the majority of throughput; Flavor Enhancers is the fastest mover on share.
Application:
Volume concentration tracks food processing cluster geography, with established manufacturing bases anchoring mature segments and emerging corridors driving expansion.
- Beverages:Functional waters, flavored sparkling drinks, and adaptogenic formulations requiring specialized masking and stability expertise. Victoria's beverage innovation hubs are expanding fastest as health-positioned products capture shelf space.
- Snacks:Processed savory applications where clean-label enhancers replace sodium-heavy seasoning systems. New South Wales snack manufacturers are accelerating natural flavor adoption under retailer sustainability mandates.
- Bakery:Mature volume pool where reformulation costs and thermal stability requirements slow substitution timelines for synthetic alternatives.
- Sauces:Condiment and dressing applications balancing flavor intensity with label simplicity, concentrated in Queensland's emerging food processing corridor.
Bakery maintains the largest installed volume base; Beverages is climbing the fastest as functional categories expand.
End User:
Procurement sophistication separates segments, with scale determining whether flavor development stays in-house or relies on supplier technical partnerships.
- Food Manufacturers:Industrial-scale processors with dedicated R&D functions, concentrated in New South Wales and Victoria, driving long-term supply agreements and co-development partnerships.
- Restaurants:Foodservice operators prioritizing consistency and cost control, increasingly sourcing through consolidated distribution rather than direct supplier relationships.
- Retailers:Private-label developers seeking differentiated flavor profiles for store-brand positioning, demanding shorter lead times than industrial clients.
- Catering Services:Volume-driven operators with limited technical capability, dependent on distributor-mediated supply and standardized product ranges.
Food Manufacturers commands the deepest supplier relationships; Retailers is gaining share fastest as private-label innovation accelerates.
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements, with direct engagement displacing intermediaries for sophisticated processors.
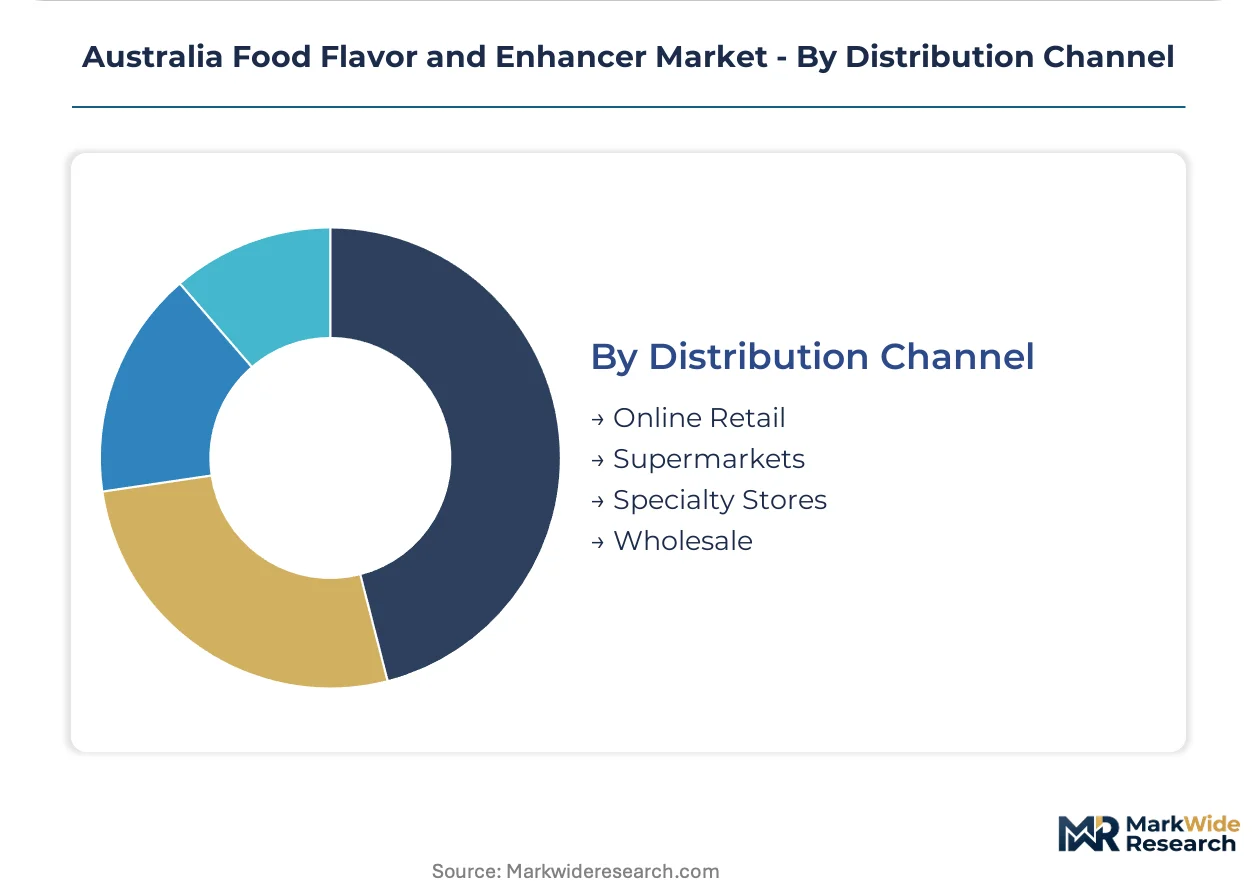
- Wholesale:Bulk supply relationships serving large-scale manufacturers with predictable volume requirements and dedicated technical service support.
- Online Retail:Digital procurement platforms capturing small-to-mid-size processors seeking sample access and rapid order fulfillment without distributor markup.
- Supermarkets:Retail-facing packaged goods channels where clean-label certification and FSANZ compliance documentation determine listing eligibility.
- Specialty Stores:Niche channels for artisan and premium-positioned products, requiring smaller batch sizes and higher per-unit service intensity.
Wholesale moves the largest absolute volume; Online Retail is expanding most quickly as digital procurement platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Australian states diverge sharply based on manufacturing density and regulatory enforcement intensity. New South Wales and Victoria dominate absolute volume through established food processing clusters, while Queensland and Western Australia present divergent growth trajectories shaped by infrastructure investment and import dependency.
New South Wales
Sydney anchors the nation's largest flavor application infrastructure, with beverage and snack manufacturers driving concentrated demand for natural flavor reformulations. FSANZ compliance documentation requirements compress supplier qualification timelines for processors based in the city's western industrial corridor. Parramatta and Blacktown manufacturing zones host dedicated technical service labs from major flavor houses serving Australasian clients.
Victoria
Melbourne's food innovation hubs generate accelerating demand for functional water and adaptogenic beverage flavor systems. State-level sustainability mandates on packaging and ingredient sourcing create compliant-ingredient premiums that certified suppliers capture. The city's northern suburbs concentrate bakery and confectionery processors facing steep FSANZ compliance cliffs for synthetic enhancer phase-outs.
Queensland
Brisbane and the state's expanding food manufacturing corridor generate localized demand spikes for savory enhancers in protein processing applications. The region's emerging processor scale does not yet justify full in-house flavor development teams, creating openings for embedded technical service partnerships. Direct supplier engagement is displacing distributor-mediated relationships for mid-size operators.
Western Australia
Perth's underpenetrated food manufacturing base offers first-mover positioning for flavor houses establishing technical service capabilities. Geographic isolation from eastern supply chains elevates inventory carrying costs for processors dependent on interstate distribution. Local seafood and protein processors represent untapped demand pools for clean-label enhancer technologies.
South Australia
Adelaide's wine and beverage processing heritage translates into specialized demand for natural extraction expertise and stability-focused formulations. Smaller industrial scale limits absolute volume compared to eastern states, though premium-positioned artisan producers command higher per-unit service intensity. Regional supply chain fragmentation creates procurement inefficiencies for processors seeking national-grade technical support.
Australia Food Flavor and Enhancer Market Competitive Environment
Capability concentration sits with specialized natural flavor developers; scale advantage sits with diversified ingredient conglomerates. The market structures around a tiered supplier base where regulatory affairs expertise and captive technical service infrastructure determine competitive viability. Three archetypes dominate: global flavor houses with Sydney application labs, regional specialists in color-flavor integration, and clean-label enhancer suppliers with long-term manufacturing agreements. Competitive moves center on embedded technical service deployment and portfolio diversification toward natural extraction capabilities.
Among global flavor houses with Australian technical presence, Givaudan and International Flavors & Fragrances anchor premium natural flavor development for beverage clients. Sensient Technologies Corporation exemplifies the specialized integration tier competing through color-flavor systems targeting bakery channels. Kerry Group occupies the clean-label enhancer segment, sustaining volume through manufacturing agreements with protein processors. Sensate Pty Ltd represents regional specialist positioning within the national supplier ecosystem.
| Leading Market Players |
|---|
| International Flavors & Fragrances |
| Symrise AG |
| Givaudan |
| Firmenich |
| Takasago International Corporation |
| DSM-Firmenich |
| Sensient Technologies Corporation |
| Sensate Pty Ltd |
| Kerry Group |
| Others |
Value Chain & Pricing Dynamics
Indonesian vanilla and Madagascar botanical harvests anchor raw material cost structures for Australian natural flavor houses, concentrating margin volatility upstream while downstream pricing power fragments across processor tiers and retail-facing applications.
Pricing Analysis
Long-term offtake contracts dominate procurement between major flavor houses and protein processors, insulating volume buyers from spot volatility in citrus and botanical extracts. Three-tier pricing structure across premium natural-certified, standard clean-label, and economy synthetic tiers reflects FSANZ compliance grade and volume scale. Pricing pressure stems from climate-driven harvest variability compressing margin predictability for natural specialists. Food manufacturers with captive regulatory affairs capabilities exhibit lowest price sensitivity, while mid-size Queensland processors remain most exposed to spot market swings.
Supply Chain Analysis
Australian biosecurity controls and import permit requirements for novel flavor molecules restrict supply chain flexibility, extending lead times for innovative enhancers seeking FSANZ approval. Raw material sourcing draws from Indonesian vanilla estates, Chinese amino acid derivative producers, and Indian botanical extract houses. Single-source vulnerability concentrates in certified natural supply tiers where FSANZ-aligned audit requirements limit qualified suppliers. Distribution runs through wholesale technical service relationships for large manufacturers, with digital platforms capturing emerging mid-tier demand in underpenetrated states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic-to-natural flavor substitution threatens incumbent positioning as FSANZ disclosure requirements tighten and retail-facing applications accelerate reformulation timelines.
For Market Incumbents: Build captive regulatory affairs capabilities as a moat against FSANZ submission bottlenecks that delay competitor commercialization. Deepen backward integration into Australian-native botanical extraction to secure climate-resilient supply pools. Anchor long-term manufacturing agreements with Queensland's expanding protein processors before technical service infrastructure saturates the corridor.
For New Entrants and Emerging Players: Establish a beachhead in Western Australia's underpenetrated seafood and protein processing base, where geographic isolation from eastern supply chains elevates procurement costs for incumbents. Target functional water flavor masking as a specialized entry point, leveraging AI-driven formulation platforms to compress development cycles versus established flavor houses. Pursue direct technical service engagement to displace distributor-mediated relationships for mid-size processors lacking in-house R&D.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists possessing FSANZ-aligned clean-label certification infrastructure but limited geographic coverage. Five-to-ten year viability hinges on natural extraction capability depth and regulatory submission track records. Watch Queensland manufacturing corridor density as an inflection signal—accelerated processor clustering will trigger consolidation demand for technical service scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capability Buildout | FSANZ submission expertise compresses novel enhancer commercialization timelines versus competitors. |
| Native Botanical Extraction Investment | Australian-sourced natural inputs reduce climate-exposed import dependency for premium flavor tiers. |
| Embedded Technical Service Deployment | Application scientists co-located in Queensland manufacturing facilities accelerate formulation iteration cycles. |
| AI-Driven Formulation Platform Adoption | Predictive flavor molecule modeling cuts development cycles from months to weeks for beverage clients. |
| Clean-Label Certification Infrastructure | Third-party natural validation capabilities capture compliant-ingredient premiums under tightening FSANZ requirements. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with flavor house regulatory affairs directors, protein processor procurement leads, and FSANZ compliance consultants; and secondary validation through Food Standards Australia New Zealand determinations, customs import records, and state-level food manufacturing investment disclosures. Bottom-up volume estimates triangulated against top-down category spending patterns across beverage, snack, and protein processing channels.
Forecast inputs incorporated product type segmentation by natural versus synthetic versus enhancer categories, application segmentation across beverage and bakery channels, and end-user procurement sophistication tiers. CAGRs derived from regression analysis of historical substitution rates and regulatory-driven reformulation timelines, with cross-checks against Queensland manufacturing corridor investment pipelines and Victoria sustainability mandate implementation schedules across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in Australian dollar exchange rates against Indonesian rupiah and euro would shift raw material cost trajectories. Forecasts reflect assumptions of stable FSANZ approval timelines and continued clean-label retail mandate expansion. Material shifts in biosecurity import restrictions or novel food determination frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Australia Water Enhancer Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Crumb Softener Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market
Food Enhancers and Additives
Brazzein Market
Food Enhancers and Additives
Used Cooking Oil Market
Food Enhancers and Additives
Flour Improvers Market