
 Africa Food Flavor and Enhancer Market | 2026-2036
Africa Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Food Flavor and Enhancer Market Outlook
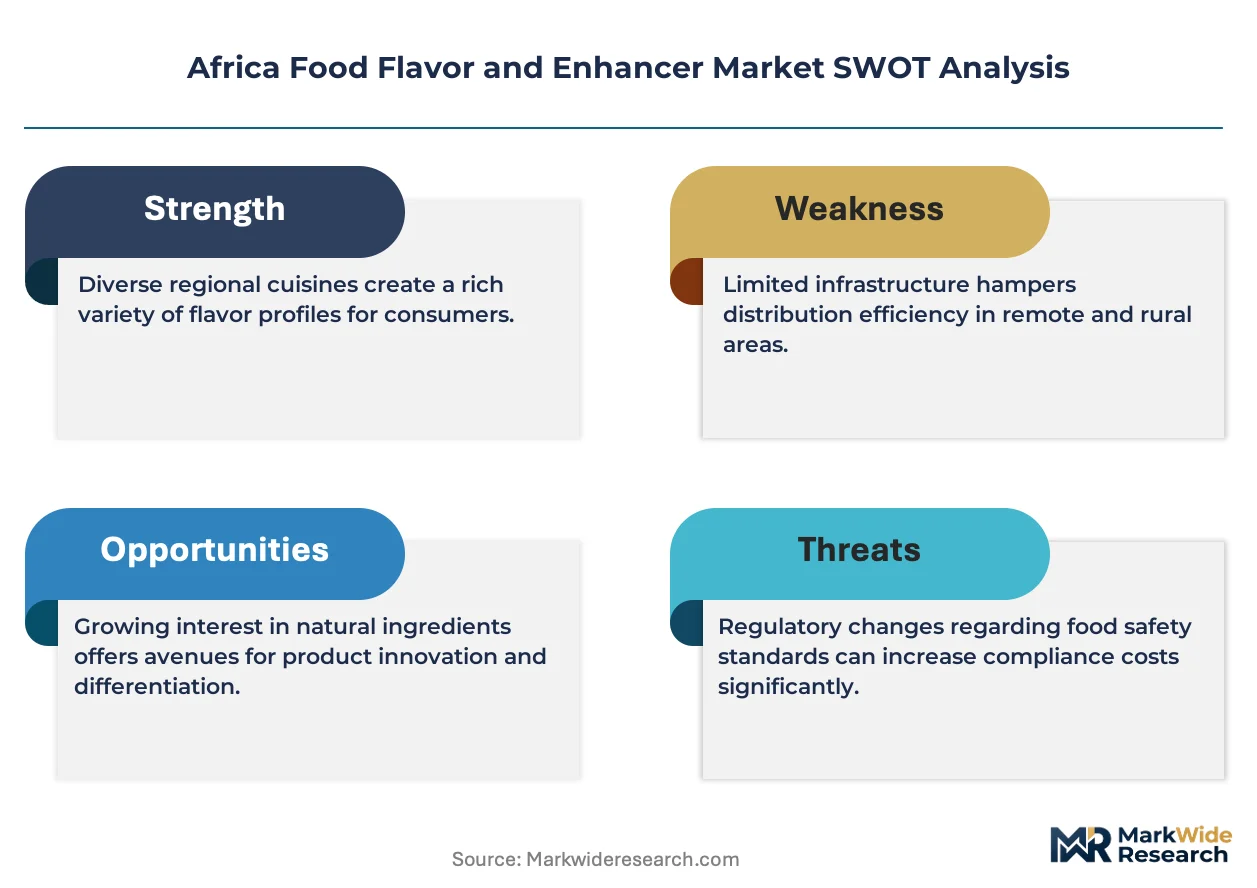
ISO 22000 certification is redrawing competitive boundaries across the Africa Food Flavor and Enhancer Market, filtering out suppliers lacking documented food safety management systems. Givaudan leverages its Swiss-origin technical protocols to anchor premium positioning in North and West African markets. Sensient Technologies Corporation competes through specialized natural color and flavor extraction capabilities tailored to local botanical feedstocks. Kerry Group dominates dairy and savory application development with region-specific formulation labs.
Food flavor and enhancer systems comprise volatile aromatic compounds, taste-active molecules, and carrier substrates engineered to modify or intensify sensory perception in processed foods; manufacturing involves solvent extraction, steam distillation, or enzymatic biotransformation of plant, microbial, or synthetic precursors, with stability parameters such as heat resistance and pH tolerance determining application suitability. Natural Extracts command margin premiums due to clean-label positioning among African health-conscious consumers, while Artificial Flavors sustain volume leadership in cost-sensitive mass-market categories like carbonated beverages and instant noodles. Spice Mixes occupy a mature growth trajectory rooted in indigenous culinary traditions, whereas Flavoring Agents for Meat Processing represent the fastest-expanding application segment as formalized protein processing scales across the continent.
FSSAI-equivalent national food safety agencies in South Africa, Kenya, and Nigeria enforce additive maximum limits and labeling transparency that shape product registration timelines and reformulation costs. The country's national pharmaceutical regulator and central bank frameworks in key economies indirectly influence investment flows into food ingredient manufacturing capacity. Stakeholders must monitor evolving harmonization between CODEX Alimentarius guidelines and national standards to anticipate compliance burdens and first-mover certification advantages.
Market Dynamics
ISO 22000 certification requirements are restructuring supplier eligibility across the Africa Food Flavor and Enhancer Market, forcing documented food safety management systems as a baseline for commercial relationships with multinational processed food manufacturers.
Growth Catalysts
- Urban Consumer Preference Shift:Nigeria's Lagos-Ibadan manufacturing corridor concentrates snack producers and beverage bottlers driving bulk procurement of flavoring agents for convenience food portfolios.
- Clean-Label Regulatory Tailwind:Kenya's national food safety framework is accelerating adoption of natural extracts through tightened additive disclosure standards that favor botanical-derived alternatives.
- Formalized Protein Processing:Flavoring agents for meat processing represent the fastest-expanding application segment as industrial slaughterhouses and cold-chain facilities scale across South Africa, Egypt, and Morocco.
Market Restraints
- Feedstock Price Volatility:Vanilla bean, citrus peel, and spice crop yields in Madagascar, Tanzania, and Uganda fluctuate with rainfall patterns, compressing margin predictability for natural extract suppliers.
- Import Dependency Concentration:Synthetic aroma chemical precursors and specialized extraction equipment flow through Durban, Mombasa, and Lagos ports, creating single-point vulnerability in supply security.
- Reformulation Cost Burden:South Africa's Department of Health additive maximum limits trigger product registration timelines exceeding eighteen months for reformulated flavor systems.
Strategic Opportunities
- Ethiopian Manufacturing Greenfield:Underdeveloped flavor compounding infrastructure in Addis Ababa's industrial zones offers first-mover positioning as the country's pharmaceutical and food processing sectors formalize.
- Enzymatic Biotransformation Convergence:Microbial fermentation platforms combined with solvent extraction are enabling novel taste-active molecules from indigenous botanicals previously uneconomical to process.
- CODEX Harmonization Window:Alignment between national standards and CODEX Alimentarius guidelines in Kenya and Nigeria is compressing compliance burdens for suppliers holding dual certifications.
Industry Challenges
- Food Safety Auditor Scarcity:ISO 22000 lead auditor certification programs remain limited to Johannesburg, Nairobi, and Lagos, creating inspection bottlenecks for upcountry manufacturing facilities.
- Legacy Equipment Integration:Steam distillation units installed in Moroccan and Tunisian flavor houses during the 1990s require retrofitting for heat-sensitive natural extract processing without full replacement capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Food Flavor and Enhancer Market |
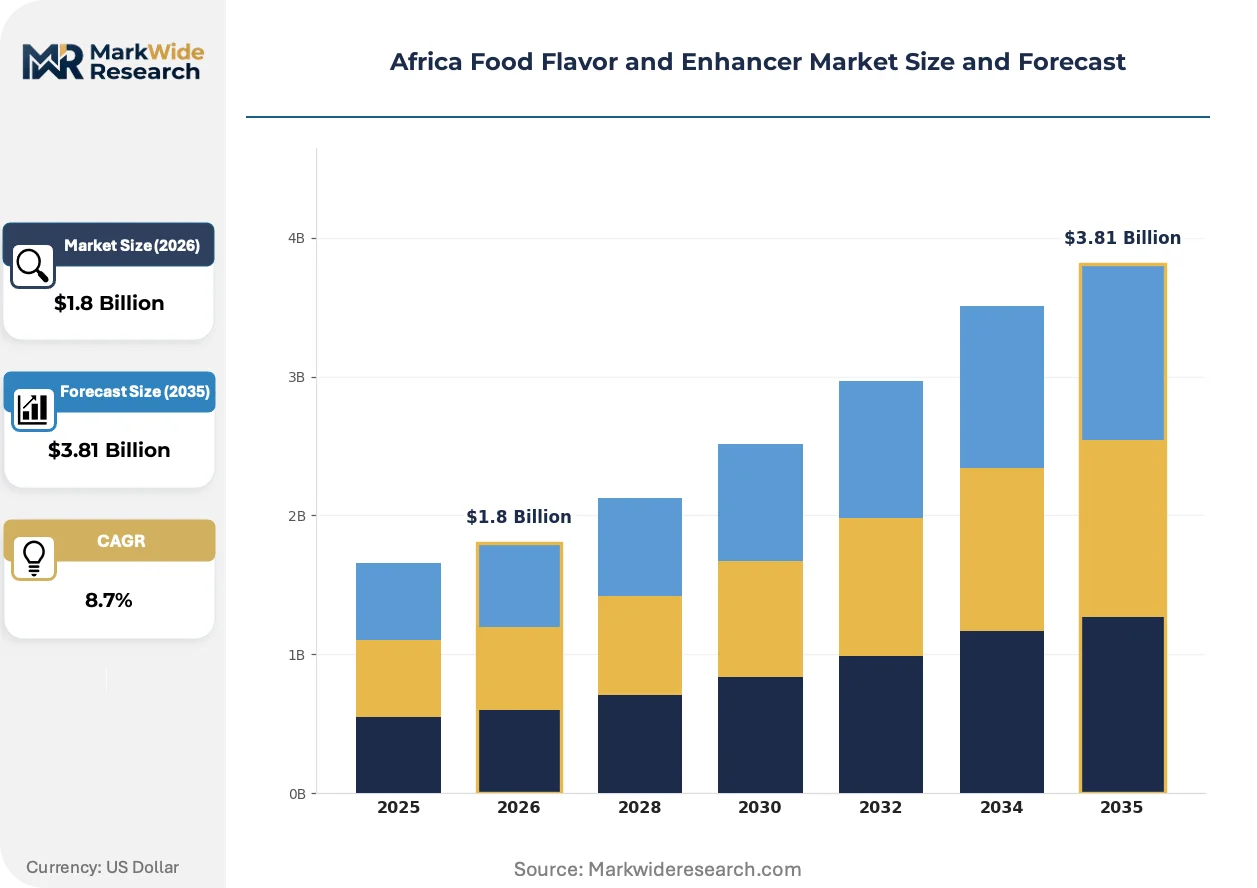
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extracts, Artificial Flavors, Spice Mixes, Flavoring Agents End User: Food Manufacturers, Beverage Companies, Restaurants, Snack Producers Application: Baking, Dairy Products, Sauces, Meat Processing Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores |
| Companies Covered | Givaudan, Sensient Technologies Corporation, International Flavors & Fragrances Inc., Firmenich SA, Kerry Group, Koninklijke DSM N.V., Fruition, Symrise AG, Teubes Oils Out of Africa, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Food Flavor and Enhancer Market Strategic Shifts
Biotechnology-derived flavor precursors and clean-label extraction methods are redrawing technical boundaries between natural and artificial positioning, while regulatory harmonization efforts compress compliance fragmentation across national markets.
Enzymatic biotransformation of plant feedstocks into volatile aromatic compounds is supplanting traditional solvent extraction in premium natural flavor production. South African dairy and savory manufacturers are adopting these processes at pilot scale. The technology is compressing extraction yield variability and enabling consistent supply of heat-labile botanical notes previously restricted to seasonal harvest windows.
South Africa's Department of Health food additive regulations are tightening maximum permissible limits for synthetic colorants and preservatives in flavored beverages. Industrial consequence includes mandatory reformulation cycles for carbonated drink portfolios. Nigerian and Ghanaian bottlers are responding by accelerating natural extract sourcing partnerships to preempt compliance deadlines.
Direct procurement relationships between snack manufacturers and flavor houses are displacing traditional distributor intermediaries in West African supply chains. Lagos-based processors are negotiating volume commitments with Givaudan and Sensient facilities rather than regional chemical traders. Kenya's supermarket retail consolidation is amplifying this pattern as private-label snack lines demand customized flavor development cycles incompatible with stock-catalog distribution.
Africa Food Flavor and Enhancer Market Segmentation
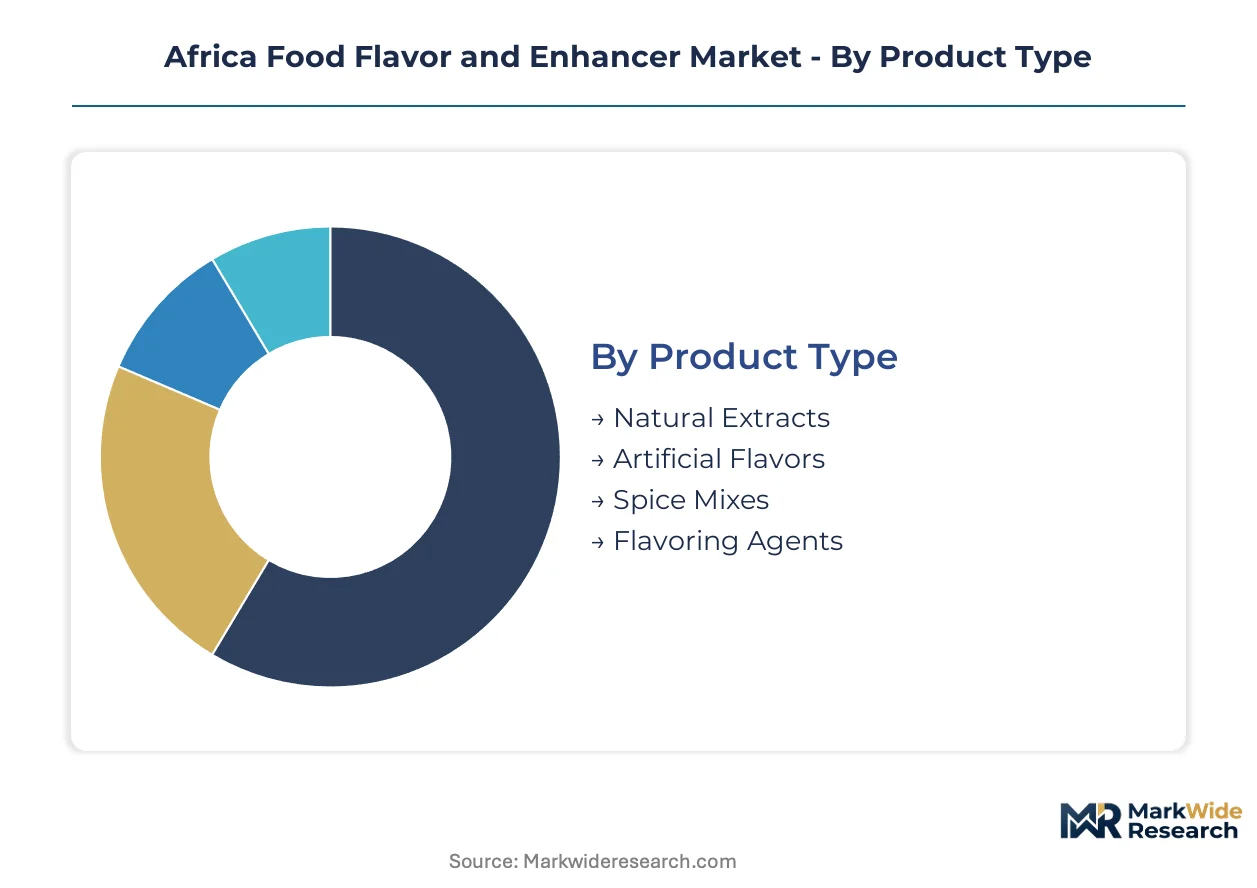
Flavor and enhancer procurement patterns diverge sharply across Africa's fragmented distribution infrastructure. Urban manufacturing corridors favor bulk direct sourcing while informal retail channels sustain spice mix volumes in peri-urban zones.
Product Type:
Natural Extracts and Artificial Flavors flow predominantly through multinational food manufacturer direct contracts, while Spice Mixes and regional Flavoring Agents reach end-users via wholesale spice markets and specialty retail networks.
- Natural Extracts:Botanical-derived volatile compounds and oleoresins extracted through steam distillation or cold-pressing methods. Lagos-Ibadan beverage bottlers and Nairobi dairy processors are driving procurement of vanilla and citrus extracts as Kenya's clean-label disclosure standards tighten.
- Artificial Flavors:Synthetic aroma chemicals including esters, aldehydes, and ketones formulated for heat stability and cost efficiency. Nigerian instant noodle manufacturers and Ghanaian carbonated drink bottlers anchor volume demand despite South Africa's Department of Health maximum limit pressures.
- Spice Mixes:Indigenous blends of dried herbs, peppers, and aromatics rooted in West and North African culinary traditions. Moroccan and Tunisian food service distributors sustain mature wholesale channels.
- Flavoring Agents:Application-specific taste modulators and enhancers including nucleotides and amino acid derivatives. Egyptian and South African industrial meat processors are scaling procurement as cold-chain infrastructure formalizes.
Artificial Flavors dominate installed base. Natural Extracts is where expansion concentrates.
End User:
Cost tier stratification separates multinational manufacturers demanding ISO 22000-certified supply from price-sensitive informal processors operating outside formal regulatory frameworks.
- Food Manufacturers:Industrial bakeries, confectioners, and ready-meal producers requiring documented batch consistency and regulatory compliance. South African and Egyptian facilities are consolidating supplier panels around certified flavor houses.
- Beverage Companies:Carbonated soft drink, juice, and dairy beverage bottlers with specialized flavor emulsion requirements. Nigerian and Ghanaian bottlers are accelerating natural extract partnerships to preempt reformulation deadlines.
- Restaurants:Quick-service chains and institutional catering operations sourcing standardized seasoning systems. Kenyan supermarket retail consolidation is amplifying private-label flavor development demand.
- Snack Producers:Extruded, fried, and baked snack manufacturers requiring topical flavor coatings and seasonings. Lagos-based processors are negotiating direct volume commitments with international flavor houses.
Food Manufacturers command premium pricing tiers. Snack Producers are climbing the fastest as West African convenience food consumption accelerates.
Application:
Volume concentration tracks protein processing formalization and dairy sector expansion across North and West African manufacturing zones.
- Baking:Yeast-raised and chemically leavened products requiring heat-stable vanilla, butter, and fruit flavor systems. Egyptian and Moroccan industrial bakeries sustain established procurement channels.
- Dairy Products:Fermented milk, cheese, and ice cream applications demanding clean-label fruit and savory flavor profiles. Kerry Group's regional formulation labs are anchoring technical service relationships with East African processors.
- Sauces:Tomato-based, emulsified, and oil-based condiments requiring acid-stable flavor systems. Nigerian and Ghanaian table sauce manufacturers drive regional blending facility investment.
- Meat Processing:Cured, smoked, and comminuted protein applications with specialized smoke, spice, and umami enhancement requirements. South African, Egyptian, and Moroccan industrial slaughterhouses are scaling flavor agent procurement most steeply.
Dairy Products anchor mature revenue streams. Meat Processing is where technology investment and capacity expansion concentrate.
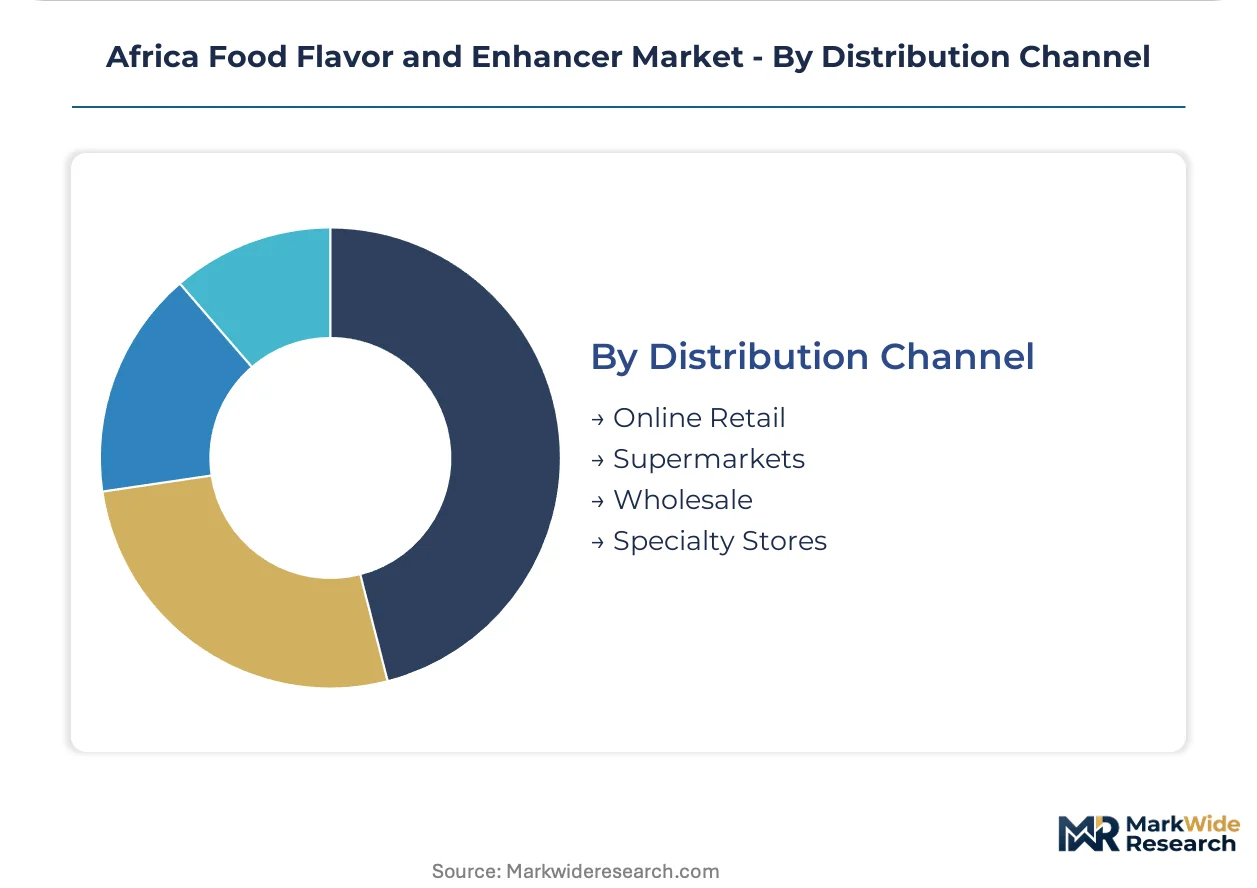
Distribution Channel:
Geographic reach and customer scale determine channel selection, with urban manufacturing clusters bypassing traditional intermediaries.
- Online Retail:E-commerce platforms serving small-batch artisan producers and remote food service operators. Limited penetration outside South African and Kenyan urban centers due to logistics infrastructure gaps.
- Supermarkets:Formal retail chains consolidating private-label snack and sauce flavor development. Kenya's supermarket consolidation is compressing supplier diversity requirements.
- Wholesale:Open-air markets and dedicated spice trading hubs serving informal processors and restaurants. Durban, Mombasa, and Lagos ports concentrate import-dependent synthetic precursor flows.
- Specialty Stores:Dedicated ingredient suppliers and food service distributors offering technical formulation support. Moroccan and Tunisian legacy flavor houses maintain regional presence through this channel.
Wholesale dominates transaction volume. Supermarkets are where margin expansion and direct manufacturer relationships concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational food manufacturers and regional bottlers concentrate procurement in coastal manufacturing corridors, with ISO 22000 certification filtering supplier eligibility across Nigeria, South Africa, Kenya, Egypt, and Morocco.
Nigeria
Lagos-Ibadan snack producers and beverage bottlers drive bulk procurement of flavoring agents for convenience food portfolios. The country's national food safety agency enforces additive maximum limits and labeling transparency that shape product registration timelines. Lagos-based processors negotiate direct volume commitments with international flavor houses, displacing traditional distributor intermediaries.
South Africa
Dairy and savory application development anchors demand, with industrial meat processors scaling procurement as cold-chain infrastructure formalizes. The Department of Health food additive regulations tighten maximum permissible limits for synthetic colorants and preservatives in flavored beverages. Johannesburg concentrates ISO 22000 lead auditor certification programs, creating inspection bottlenecks for upcountry manufacturing facilities.
Kenya
Supermarket retail consolidation amplifies private-label snack lines demanding customized flavor development cycles. The national food safety framework accelerates adoption of natural extracts through tightened additive disclosure standards. Nairobi dairy processors drive procurement of vanilla and citrus extracts as clean-label positioning strengthens among health-conscious consumers.
Egypt
Industrial bakeries sustain established procurement channels for yeast-raised and chemically leavened products requiring heat-stable flavor systems. The country's central bank frameworks indirectly influence investment flows into food ingredient manufacturing capacity. Cairo and Alexandria industrial zones anchor formalized protein processing expansion, with industrial slaughterhouses scaling flavor agent procurement.
Morocco
Indigenous spice blends rooted in North African culinary traditions sustain mature wholesale channels through food service distributors. Legacy steam distillation units installed during the 1990s require retrofitting for heat-sensitive natural extract processing. Casablanca and Tunisian flavor houses maintain regional presence through specialty stores offering technical formulation support.
Africa Food Flavor and Enhancer Market Competitive Environment
Player mix skews toward multinational flavor houses with documented food safety management systems and regional specialists leveraging local botanical feedstocks. Tiered competitive structure separates ISO 22000-certified suppliers serving multinational manufacturers from price-sensitive traders supplying informal processors. Strategic archetypes include Swiss-origin technical protocol leaders, specialized natural extraction capability holders, and dairy-savory application development specialists. Dominant competitive moves encompass direct procurement relationship cultivation with Lagos-based processors and enzymatic biotransformation platform investments for novel taste-active molecules.
Within the premium-tier vector, Givaudan represents Swiss-origin technical protocol leadership anchoring positioning in North and West African markets. Sensient Technologies Corporation exemplifies specialized natural color and flavor extraction capabilities tailored to local botanical feedstocks. Kerry Group occupies a position in dairy and savory application development with region-specific formulation labs.
| Leading Market Players |
|---|
| Givaudan |
| Sensient Technologies Corporation |
| International Flavors & Fragrances Inc. |
| Firmenich SA |
| Kerry Group |
| Koninklijke DSM N.V. |
| Fruition |
| Symrise AG |
| Teubes Oils Out of Africa |
| Others |
Value Chain & Pricing Dynamics
ISO 22000 certification gates both supplier qualification and price differentiation across African flavor markets, separating documented food safety management systems from informal traders and enabling premium positioning for audited facilities serving multinational manufacturers.
Pricing Analysis
Cost-plus contracts with vanilla bean and citrus peel indexation dominate natural extract procurement, while synthetic aroma chemicals trade on spot-equivalent terms. Three-tier pricing structure across ISO-certified premium, documented-standard, and informal-economy levels tracks certification grade and batch consistency guarantees. Price differentiation hinges on food safety documentation depth and volume commitment scale. Cost compression in natural extracts is intensifying because Madagascar and Tanzania crop yields fluctuate with rainfall patterns. Informal spice traders in Lagos open-air markets exhibit highest price sensitivity; multinational dairy processors in Nairobi and Johannesburg demonstrate lowest.
Supply Chain Analysis
Inventory cycles for steam distillation equipment and specialized extraction solvents extend eighteen to twenty-four months, forcing advance procurement commitments from flavor houses. Madagascar, Tanzania, and Uganda concentrate botanical feedstock cultivation; China and India supply synthetic aroma chemical precursors. Raw material dependencies encompass vanilla beans, citrus peel oleoresins, and specialized enzymatic biotransformation catalysts. Single-source vulnerability concentrates in Durban, Mombasa, and Lagos port chokepoints for imported extraction equipment. Distribution runs through direct manufacturer relationships with Lagos-Ibadan processors, displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical formulation services and regulatory compliance consulting attach to flavor compound sales at margins expanding faster than base ingredient volumes, as Kenyan supermarket consolidation and South African additive tightening demand customized development cycles.
For Market Incumbents: Consolidate supplier panels around ISO 22000-certified facilities to preempt disqualification from multinational procurement tenders as Kenya's disclosure standards tighten. Deepen captive supply of indigenous botanical feedstocks through backward integration into Ethiopian and Tanzanian cultivation zones to buffer Madagascar vanilla price volatility. Anchor technical service relationships with Nairobi dairy processors through dedicated formulation labs. For New Entrants and Emerging Players: Anchor in Ethiopian manufacturing greenfields where flavor compounding infrastructure remains underdeveloped and pharmaceutical sector formalization creates first-mover positioning. Target enzymatic biotransformation platforms for novel taste-active molecules from previously uneconomical indigenous botanicals. Pursue direct procurement relationships with Lagos-based snack producers bypassing regional chemical traders. For Investors and Strategic Acquirers: Kenya's clean-label regulatory alignment with CODEX Alimentarius guidelines reshapes the acquisition landscape toward natural extraction capability holders with dual certification positioning. Five-to-ten year viability favors specialists with documented food safety systems and regional formulation lab networks. Watch for Ethiopian industrial zone development announcements as inflection signal for manufacturing capacity deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Biotransformation Platform Investment | South African dairy processors adopt pilot-scale microbial fermentation for heat-labile botanical notes. |
| Direct Procurement Relationship Cultivation | Lagos-based snack manufacturers negotiate volume commitments with international flavor houses. |
| ISO 22000 Certification Acceleration | Kenyan natural extract suppliers preempt reformulation deadlines through documented safety systems. |
| Indigenous Botanical Feedstock Integration | Moroccan legacy flavor houses retrofit 1990s steam distillation for seasonal harvest windows. |
| Regional Formulation Lab Expansion | Kerry Group anchors technical service relationships with East African dairy processors. |
Study Parameters
A standing panel of flavor house technical directors, food manufacturer procurement leads, national food safety agency regulators, and port logistics specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from customs trade records, national pharmaceutical regulator filings, central bank investment flow data, and CODEX Alimentarius guideline repositories. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including industrial slaughterhouse capacity expansion filings and beverage bottler procurement disclosures. The analytical framework modeled product type, end user category, application segment, and distribution channel dimensions throughout the forecast period. CAGRs derived from segment-level growth trajectory analysis incorporating protein processing formalization rates and clean-label regulatory adoption curves.
Decision-makers should treat outputs as directional under assumptions of continued urban consumer preference shift and regulatory harmonization progress; material deviation in crop yield patterns or port logistics disruptions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
Germany Water Enhancer Market
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
Resveratrol Market
Food Enhancers and Additives
Flour Improvers Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
United Kingdom Water Enhancer Market
Food Enhancers and Additives
Australia Food Flavor and Enhancer Market
Food Enhancers and Additives
North America Water Enhancer Market
Food Enhancers and Additives
Mexico Water Enhancer Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market