
 Liquid Smoke Market | 2026-2036
Liquid Smoke Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Smoke Market Outlook
Plant-based protein manufacturers is redrawing demand patterns in the liquid smoke category as alt-meat formulators seek authentic smoke notes without traditional combustion. Kerry Group leverages its flavor science infrastructure to supply tailored smoke extracts for extruded protein matrices. B&G Foods anchors the retail segment through shelf-stable sauce and marinade portfolios stocked across North American grocery chains. Colgin specializes in hickory and mesquite varietals that dominate American barbecue culture.
Liquid smoke is a water-soluble condensate produced by capturing and condensing smoke vapors from controlled wood combustion, typically filtered to remove tar and particulates while retaining phenolic and carbonyl flavor compounds. Food processors deploy it to impart smoked sensory attributes without installing costly onsite smoking chambers or managing combustion emissions. Natural liquid smoke leads product type value contribution as clean-label formulations displace artificial alternatives in premium meat and snack applications. Sauces and marinades represent the fastest-growing application segment as ready-to-cook meal kits and bottled condiment lines expand SKU counts.
The U.S. FDA maintains GRAS oversight for smoke-derived flavorings, while the USDA enforces labeling integrity for smoke-flavored meat products sold interstate. The EU's EFSA evaluates pyroligneous acid derivatives under flavoring regulation standards, affecting import eligibility for non-European extract suppliers. Stakeholders must monitor evolving clean-label certification thresholds and regional combustion-emission regulations that could restrict traditional smoking capacity and redirect volume toward liquid smoke alternatives.
Market Dynamics
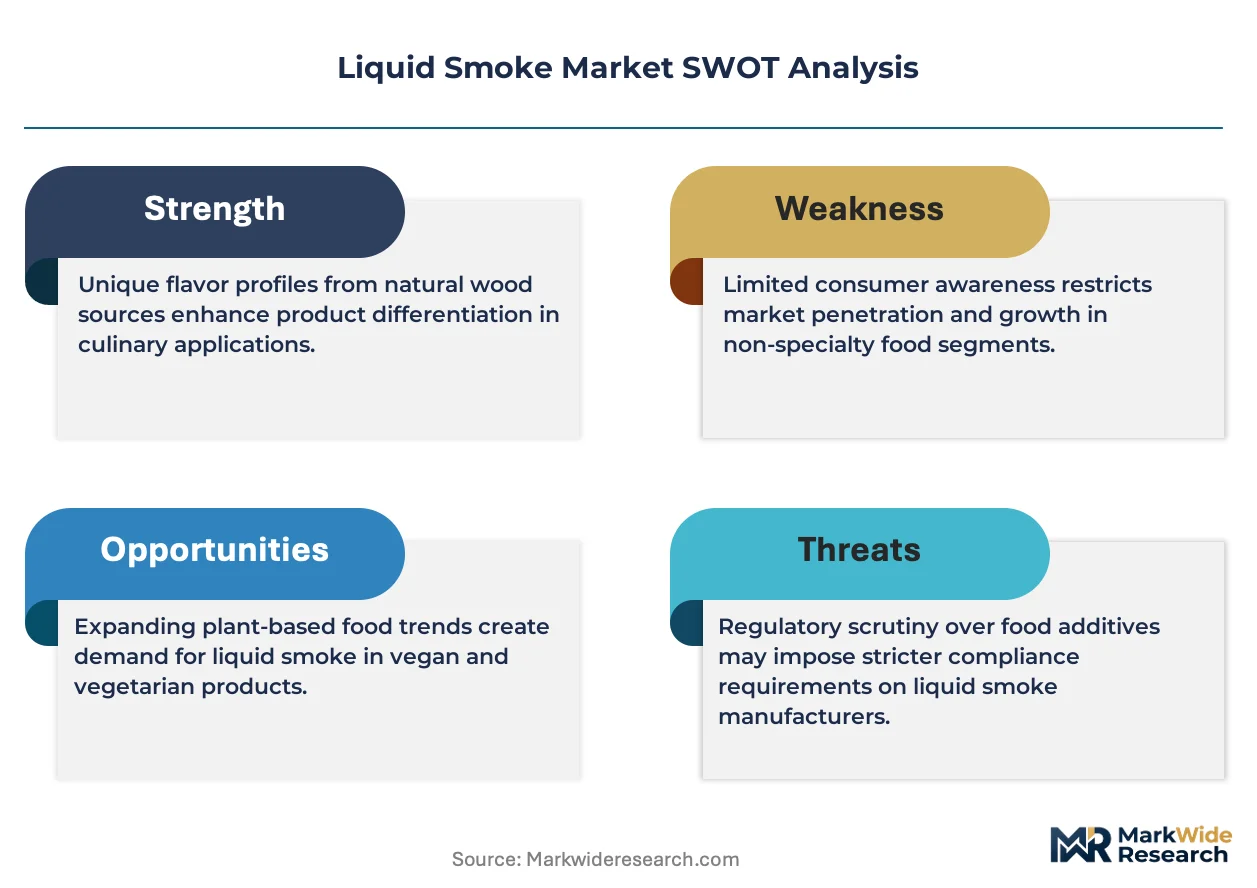
Clean-label meat processors are eliminating onsite combustion chambers in favor of water-soluble smoke condensates that bypass emissions compliance while delivering consistent phenolic flavor profiles.
Growth Catalysts
- FDA GRAS Streamlining:The U.S. FDA's GRAS designation for natural smoke flavorings accelerates ingredient approval timelines for meat processors expanding smoke-labeled product lines.
- Plant-Based Protein Formulation:Alt-meat manufacturers deploy liquid smoke to replicate authentic barbecue notes in extruded protein matrices without combustion infrastructure.
- Netherlands Sausage Tradition:Dutch and German processed meat clusters sustain concentrated demand for pyroligneous acid derivatives in traditional curing applications.
Market Restraints
- Hardwood Feedstock Volatility:Hickory and mesquite wood supply fluctuations in the southeastern United States create input cost instability for phenolic extract production.
- EFSA Import Friction:The EU's EFSA evaluation of pyroligneous acid derivatives under flavoring regulation standards restricts non-European extract supplier eligibility.
- Cold Smoking Substitution:Premium artisan meat producers retain preference for traditional cold-smoking chambers in heritage product positioning.
Strategic Opportunities
- Meal Kit Channel Expansion:Ready-to-cook subscription services create concentrated demand for pre-marinated proteins with standardized smoke flavor dosing.
- Snack Application White Space:Extruded savory snack manufacturers represent underpenetrated end-users for hickory and mesquite flavor concentrates.
- USDA Label Integrity Enforcement:Stricter interstate labeling requirements for smoke-flavored meat products redirect volume toward certified liquid smoke suppliers.
Industry Challenges
- Flavor Chemist Talent Scarcity:Formulation expertise at the intersection of pyrolysis chemistry and food safety compliance remains concentrated among legacy smoke houses.
- Clean-Label Certification Timelines:Third-party non-GMO and organic smoke extract certifications extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Smoke Market |
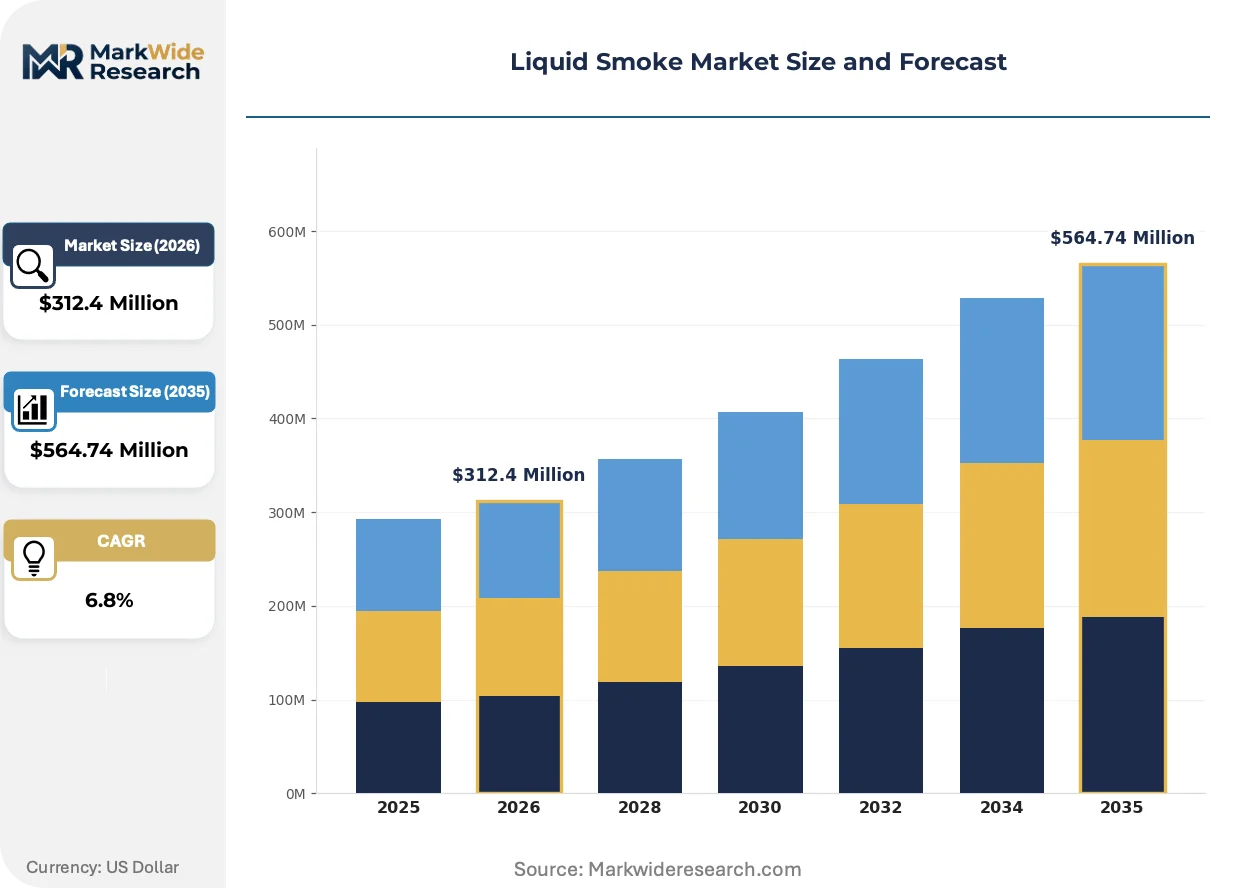
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Liquid Smoke, Artificial Liquid Smoke, Wood Smoke Extract, Concentrated Liquid Smoke End User: Food Processing, Restaurant, Retail, Household Application: Meat Products, Sauces & Marinades, Seasonings, Snacks Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Azelis, B&G Foods, Kerry Group, MSK Ingredients, Ruitenberg Ingredients, Red Arrow International, Baumer Foods, QST Smoke Flavors, Colgin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Smoke Market Strategic Shifts
Smoke flavor delivery is fragmenting across three vectors: condensed vapor chemistry, regulatory arbitrage between combustion and condensate pathways, and procurement consolidation among contract meat processors.
Fractional distillation of pyroligneous acid is supplanting crude filtration methods in premium extract production. Clean-label meat processors in the United States and Germany adopt refined phenolic concentrates to achieve batch-to-batch consistency impossible with traditional smoking. This technology is compressing the competitive advantage of artisan smokehouse operators who rely on variable combustion conditions.
REACH registration requirements for wood-derived flavoring substances are tightening documentation burdens on European extract importers. The European Chemicals Agency now mandates full toxicological dossiers for pyrolysis-derived carbonyl compounds entering the EU food chain. German sausage manufacturers are responding by qualifying captive domestic distillation capacity to shorten supply chains.
Direct-procurement contracts between meat processors and smoke extract laboratories are displacing traditional flavor house intermediaries. Large North American protein packers now negotiate volume commitments directly with pyroligneous acid specialists, bypassing multi-ingredient distributors. This pattern is most visible in the U.S. Midwest, where vertically integrated pork processors consolidate ingredient sourcing under centralized procurement functions.
Liquid Smoke Market Segmentation
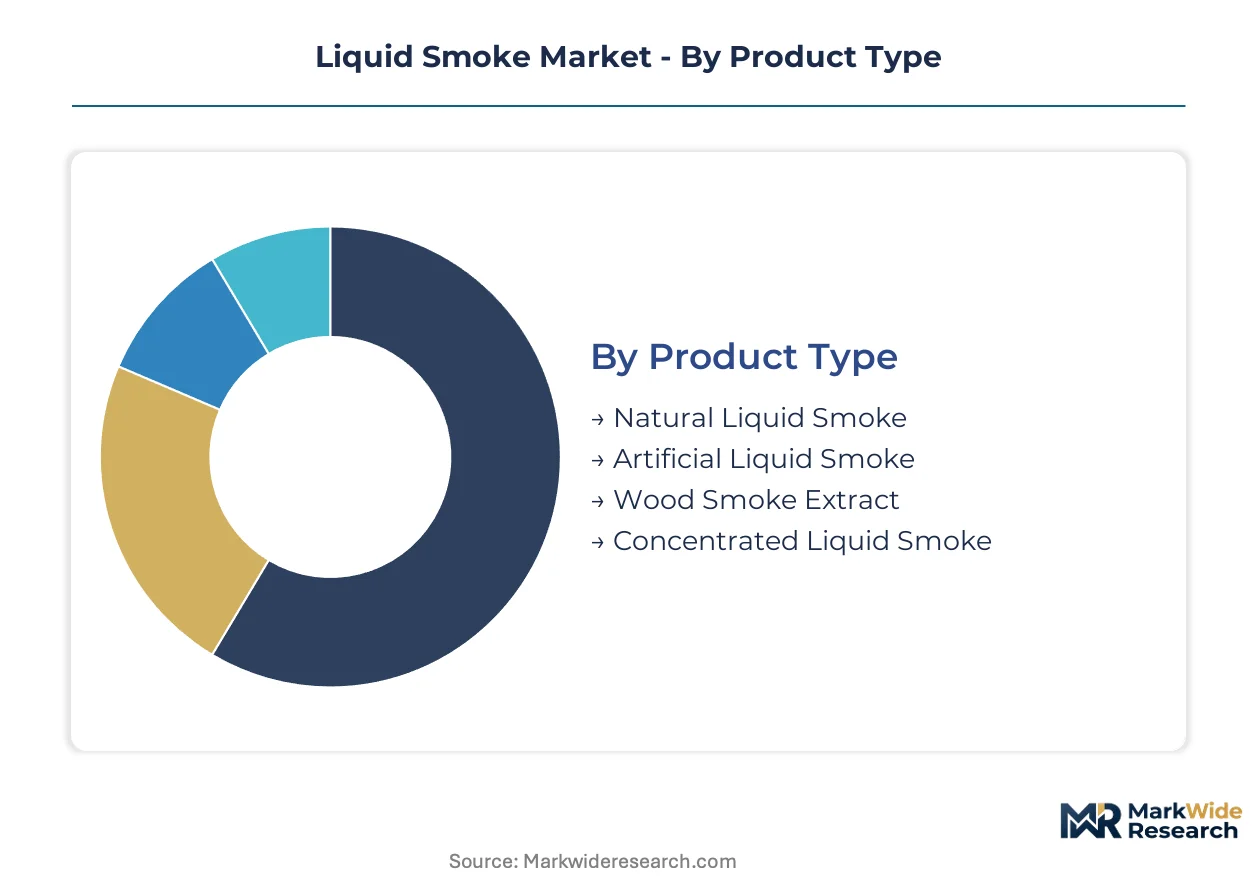
Liquid smoke manufacturers prioritize margin capture through product type differentiation and application-specific formulation. Segmentation reveals where phenolic extract suppliers command pricing power versus commodity positioning.
Product Type:
Margin pools concentrate in refined extracts that bypass crude filtration costs while meeting clean-label certification thresholds.
- Natural Liquid Smoke:Produced through controlled wood combustion and condensation with tar filtration, retaining authentic phenolic and carbonyl compounds. Food processors in Germany and the Netherlands specify this grade for traditional sausage curing applications where EFSA compliance is mandatory. Clean-label meat manufacturers eliminate artificial alternatives entirely from premium product lines.
- Concentrated Liquid Smoke:Fractionally distilled pyroligneous acid with standardized phenol content enabling precise dosing in extruded protein matrices. Alt-meat formulators in the United States specify concentrated grades for batch consistency impossible with traditional smoking infrastructure.
- Artificial Liquid Smoke:Synthetic phenolic compound blends mimicking hickory and mesquite profiles at lower input cost. Budget sauce manufacturers in retail channels specify artificial grades where label disclosure requirements remain permissive.
- Wood Smoke Extract:Solvent-extracted resinous compounds from specific hardwood species, typically reserved for fragrance and non-food applications with limited food-grade certification.
The dominant share belongs to Natural Liquid Smoke, while Concentrated Liquid Smoke is closing the gap fastest.
End User:
Volume concentration tracks with procurement scale and formulation expertise requirements.
- Food Processing:Contract meat packers and extruded snack manufacturers deploy liquid smoke for emission-compliant smoke flavoring at industrial scale. USDA labeling enforcement redirects volume toward certified suppliers with documented GRAS status.
- Restaurant:Commercial kitchen operators specify liquid smoke for sauce consistency and labor reduction in barbecue and smoked protein preparation. Chain restaurant procurement functions consolidate supplier qualification under centralized food safety protocols.
- Retail:Branded sauce and marinade portfolios stocked across North American grocery chains anchor shelf-stable consumer demand. B&G Foods and comparable suppliers dominate this channel through established retail distribution relationships.
- Household:Small-format bottles and spray applications serve home barbecue enthusiasts seeking authentic smoke notes without outdoor smoking equipment.
Food Processing commands the volume base, though Restaurant procurement is expanding most quickly through chain consolidation.
Application:
Formulation complexity and certification burden vary sharply across end-use categories.
- Sauces & Marinades:Ready-to-cook meal kits and bottled condiment lines drive SKU expansion with standardized smoke flavor dosing. Kerry Group supplies tailored extracts for sauce matrices requiring thermal stability and shelf-life compatibility.
- Meat Products:Cured sausages, bacon, and smoked poultry retain the traditional application base with stringent USDA interstate labeling requirements. Dutch and German processors specify pyroligneous acid derivatives for heritage product positioning.
- Snacks:Extruded savory manufacturers represent underpenetrated demand for hickory and mesquite concentrates in flavored chip and puff applications.
- Seasonings:Dry rub and spice blend applications require spray-dried or plated smoke flavor systems with moisture stability specifications.
Sauces & Marinades holds the steepest expansion trajectory, while Meat Products retains the revenue foundation.
Distribution Channel:
Channel selection determines margin capture through pricing transparency and service requirements.
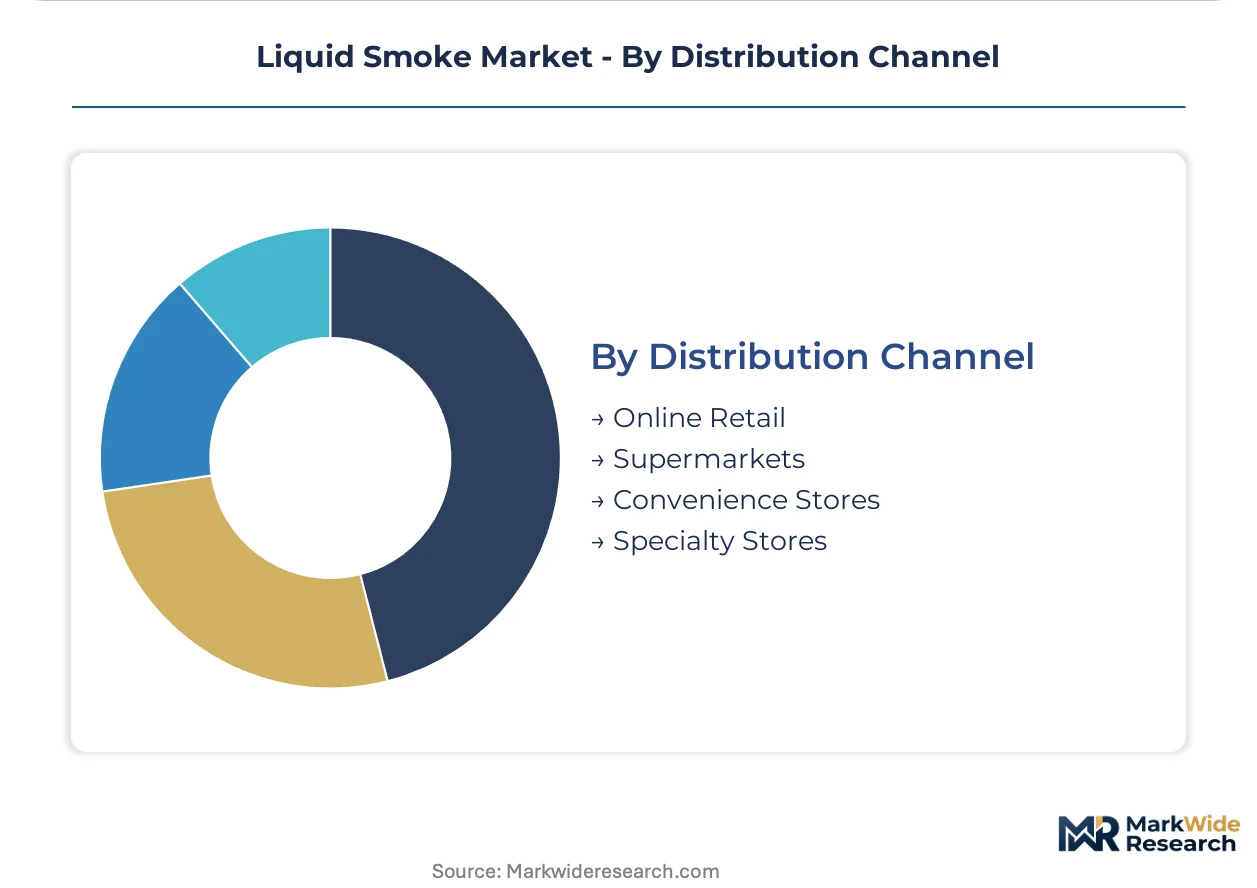
- Supermarkets:Mass retail placement for shelf-stable sauces and marinades with established brand recognition and promotional calendar coordination.
- Online Retail:Direct-to-consumer and B2B procurement platforms serving specialty food manufacturers and restaurant operators with technical documentation access.
- Specialty Stores:Premium and organic-certified smoke extracts targeting artisan meat producers and clean-label formulators with certification requirements.
- Convenience Stores:Limited SKU presence for single-serve sauce packets and impulse-format liquid smoke products.
Supermarkets anchor the volume base, though Online Retail is gaining share fastest through procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Meat processors in Germany and the Netherlands drive concentrated European procurement, while U.S. alt-meat startups and barbecue sauce manufacturers anchor transatlantic demand. Brazilian sausage exporters and Australian smoked seafood producers represent emerging volume pockets.
United States
Alt-meat formulators in Chicago and Austin deploy liquid smoke for extruded protein matrices lacking combustion infrastructure. The FDA's GRAS designation for natural smoke flavorings accelerates ingredient approval timelines for expanding smoke-labeled product lines. Vertically integrated pork processors in Iowa and North Carolina now negotiate direct procurement contracts with pyroligneous acid specialists.
Germany
Heritage sausage manufacturers in Bavaria and Lower Saxony specify pyroligneous acid derivatives for traditional curing applications. ECHA's REACH registration requirements for wood-derived flavoring substances tighten documentation burdens on extract importers. German processors are qualifying captive domestic distillation capacity to shorten supply chains and ensure EFSA compliance.
Netherlands
Dutch processed meat clusters in Gelderland sustain concentrated demand for phenolic extracts in smoked sausage and bacon applications. The country's national food safety authority enforces strict labeling integrity for smoke-flavored products sold across EU member states. Rotterdam-based ingredient distributors serve as consolidation points for pyroligneous acid shipments entering northwestern Europe.
Brazil
Sausage exporters in São Paulo and Rio Grande do Sul adopt liquid smoke to meet international clean-label certification thresholds. The country's national agricultural regulator monitors additive compliance for processed meat exports to European and North American markets. Brazilian processors leverage liquid smoke to bypass costly onsite smoking infrastructure while maintaining authentic sensory profiles.
Australia
Smoked seafood manufacturers in Tasmania and South Australia deploy water-soluble condensates for emission-compliant flavoring. Food Standards Australia New Zealand (FSANZ) maintains oversight of smoke-derived flavorings in interstate commerce. Australian processors supply Asian export markets with certified smoke-flavored products meeting diverse regulatory requirements.
Liquid Smoke Market Competitive Environment
Player mix skews toward specialty flavor houses and diversified food ingredient conglomerates with pyrolysis chemistry capabilities. The vendor base separates into three strategic archetypes: legacy smoke houses with captive distillation expertise, multi-ingredient distributors leveraging established retail relationships, and alt-meat-focused extract laboratories serving protein formulation. Dominant competitive moves include direct-procurement contract negotiation with meat processors and backward integration into hardwood feedstock sourcing.
Among diversified ingredient conglomerates, Kerry Group and B&G Foods exemplify scale-driven positioning across food service and retail channels. Kerry Group leverages flavor science infrastructure to supply tailored smoke extracts, while B&G Foods anchors shelf-stable sauce portfolios across North American grocery chains. Within the specialty extract tier, Colgin occupies a position tied to American barbecue culture through hickory and mesquite varietals. These three represent the competitive anchors around which procurement consolidation patterns are forming.
| Leading Market Players |
|---|
| Azelis |
| B&G Foods |
| Kerry Group |
| MSK Ingredients |
| Ruitenberg Ingredients |
| Red Arrow International |
| Baumer Foods |
| QST Smoke Flavors |
| Colgin |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between North American pork processors and pyroligneous acid specialists lock in multi-year supply access while providing cost predictability against hardwood feedstock volatility. These contracts tie pricing to regional hickory and mesquite lumber indices, insulating meat packers from spot market swings in the southeastern United States.
Pricing Analysis
Cost-plus contracts with lumber indexation dominate procurement between large processors and extract suppliers. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified natural extracts from concentrated grades and artificial alternatives. Price differentiation centers on clean-label certification burden and phenolic compound standardization. Cost compression in artificial grades is intensifying because budget sauce manufacturers face retail margin pressure. Food processing buyers exhibit highest price sensitivity, while specialty stores serving artisan producers accept premium positioning.
Supply Chain Analysis
Container availability fluctuations on transatlantic trade lanes from Rotterdam to Savannah elevate inbound logistics costs for European extract shipments. Geographic supply concentrates in the United States, Germany, and the Netherlands, with Brazilian capacity expanding for export markets. Raw material dependencies include hickory and mesquite hardwoods, fractionation equipment, and filtration membranes. Single-source vulnerability persists for EFSA-compliant phenolic concentrates qualified by Dutch sausage manufacturers. Distribution runs through direct-procurement contracts displacing traditional flavor house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across application segments creates entry points for specialized suppliers as plant-based protein formulators demand tailored smoke extracts incompatible with commodity grades.
For Market Incumbents: Consolidate backward integration into hardwood feedstock sourcing in the southeastern United States to secure hickory supply against climate-driven harvest variability. Deepen captive distillation capacity in Germany to circumvent ECHA REACH documentation burdens on imported pyroligneous acid derivatives. For New Entrants and Emerging Players: Technical documentation gaps in online retail channels present white-space opportunities for extract laboratories offering batch-specific phenolic certificates and GRAS dossier access. Target extruded savory snack manufacturers in North America with hickory and mesquite concentrates formulated for high-temperature processing. Lead with direct technical service teams rather than distributor relationships. For Investors and Strategic Acquirers: Boutique smoke extract laboratories with proprietary fractionation IP represent acquisition targets as direct-procurement trends concentrate volume among qualified suppliers. Long-term viability hinges on clean-label certification infrastructure and regulatory dossier depth rather than commodity scale. Watch EFSA evaluation timelines for pyroligneous acid derivatives as inflection indicators for European import eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardwood Feedstock | Captive hickory and mesquite supply in the southeastern United States insulates against lumber price volatility. |
| Captive Domestic Distillation Capacity | German processors qualify in-house pyroligneous acid production to satisfy ECHA REACH registration requirements. |
| Direct-Procurement Contract Negotiation | Vertically integrated pork processors in Iowa and North Carolina bypass flavor house intermediaries for volume commitments. |
| Clean-Label Certification Investment | Third-party non-GMO and organic smoke extract credentials extend product launch cycles but secure premium positioning. |
| Meal Kit Channel Partnership | Ready-to-cook subscription services create concentrated demand for pre-marinated proteins with standardized smoke dosing. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the liquid smoke value chain, including procurement directors at contract meat packers, flavor chemists at extract laboratories, regulatory affairs leads managing EFSA and FDA submissions, and category buyers at North American grocery chains. Secondary validation drew from USDA labeling enforcement records, EFSA flavoring regulation evaluations, SEC filings of diversified ingredient conglomerates, and customs data tracking pyroligneous acid trade flows. Bottom-up volume estimates from application-specific consumption rates were triangulated against top-down market sizing from producer revenue disclosures.
Across the analysis window, the forecasting framework modeled demand trajectories by product type tier, end-user procurement scale, application formulation complexity, and regional regulatory cluster. CAGRs were derived from segment-level growth rate distributions weighted by current revenue contribution. Key inputs included hardwood feedstock harvest forecasts, clean-label certification adoption curves, and alt-meat production capacity expansion plans.
Forecasts assume regulatory continuity in FDA GRAS oversight and EFSA pyroligneous acid evaluation standards; material policy shifts would require re-modeling of import eligibility and labeling integrity requirements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
Food Thickening Agents Market
Food Enhancers and Additives
Asia-Pacific Feed Palatability Enhancers Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
Lignans Market
Food Enhancers and Additives
Yellow Fats Market
Food Enhancers and Additives
Germany Food Flavor and Enhancer Market
Food Enhancers and Additives
Fortified Salts Market
Food Enhancers and Additives
Europe Food Flavor and Enhancer Market
Food Enhancers and Additives
Veratrole Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Used Cooking Oil Market
Food Enhancers and Additives
Food Raising Agents Market