
 North America Vinegar Market | 2026-2036
North America Vinegar Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vinegar Market Intelligence
Asset-light contract manufacturing and co-packing arrangements are reconfiguring competitive entry barriers for mid-sized vinegar brands in North America. Kraft Heinz Company leverages its refrigerated distribution network to dominate retail shelf placement across mass-market channels. Mizkan Holdings anchors its position through backward integration into rice vinegar fermentation, securing supply consistency for food service clients. Bragg Live Food Products differentiates via organic certification depth, commanding loyalty in the natural-products segment.
Vinegar is a dilute solution of acetic acid, typically containing 4–7% acetic acid by volume, produced through bacterial oxidation of ethanol derived from grains, fruits, or other fermentable substrates; its primary commercial purpose spans food preservation, flavor modulation, and pH control in industrial food processing. Apple cider vinegar occupies the fastest-expanding product category, propelled by functional-food positioning and wellness-oriented household buyers. The food services end-user segment sustains the largest volume absorption, with white and red wine varieties standardizing procurement for commercial kitchen operations. Bottles retain dominance in packaging, though pouches are gaining traction in food processing bulk purchasing.
The FDA's Food Safety Modernization Act and the USDA's National Organic Program collectively shape compliance costs and label-claim legitimacy for vinegar marketed across the United States. Health Canada's Food and Drug Regulations and the Safe Food for Canadians Act impose parallel acidification standards that govern cross-border product movement. Stakeholders must monitor evolving organic certification stringency and acidified-food rulemaking to preempt supply chain disruption and maintain market access.
Market Dynamics
Clean-label food processing is compressing formulation cycles across North America's vinegar supply base, forcing producers to accelerate organic certification timelines and acidification compliance documentation to maintain shelf placement in premium retail channels.
Growth Catalysts
- California's food manufacturing corridor:Specialty vinegar blends command premium placement in natural-products retail, amplifying demand for apple cider and balsamic varieties among wellness-oriented household buyers.
- FDA's Food Safety Modernization Act:Updated acidified foods requirements tighten compliance thresholds for imported products, advantaging domestic producers with established laboratory validation protocols.
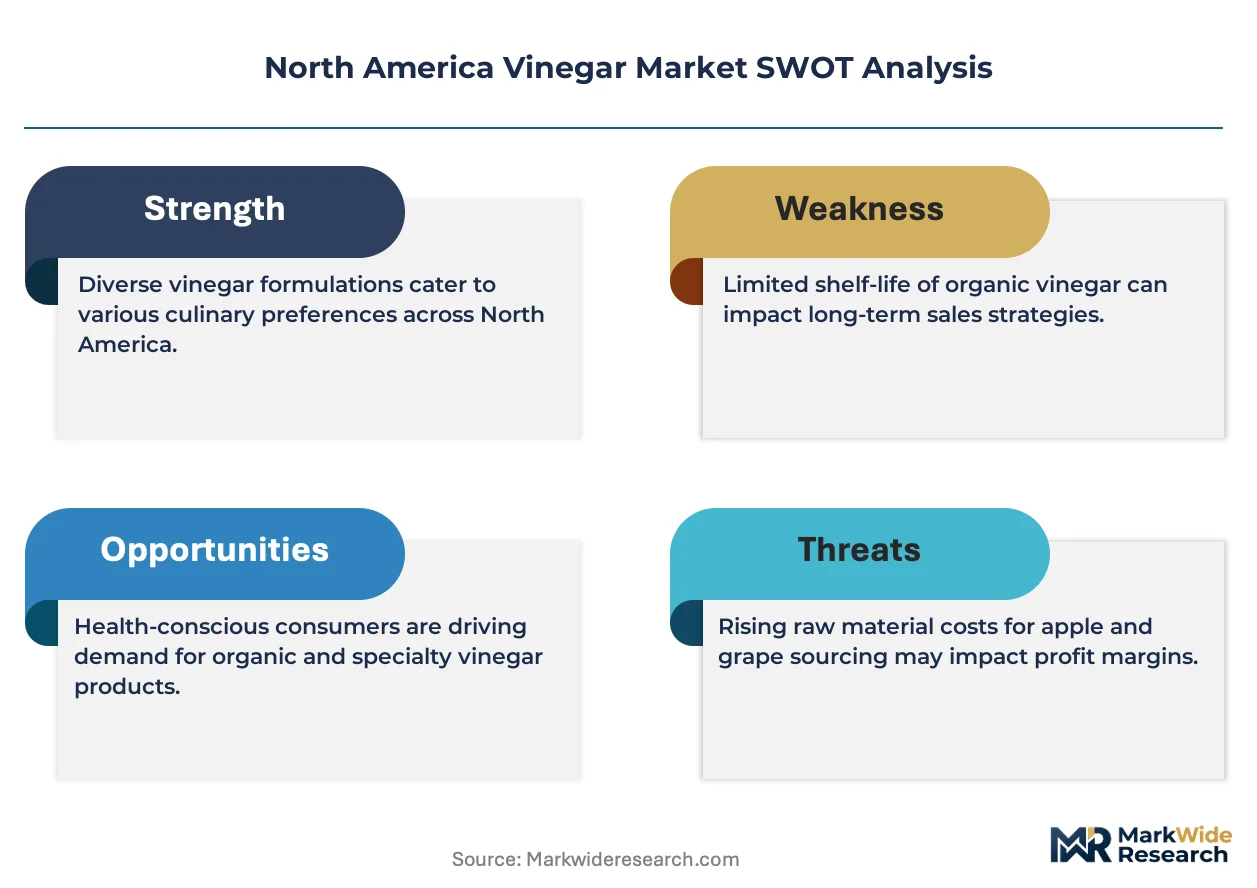
- Functional-food positioning:Apple cider vinegar occupies the fastest-expanding product category, propelled by wellness-oriented consumption patterns in food service and retail channels.
Market Restraints
- Grain and fruit substrate volatility:Input costs for ethanol feedstocks fluctuate with agricultural commodity cycles, compressing margin buffers for mid-sized fermentation operations.
- Import compliance concentration:Cross-border acidification documentation burdens concentrate on smaller foreign suppliers lacking in-house regulatory affairs capacity.
- pH control technical limitation:Precise acidification standardization remains difficult at commercial scale for artisanal producers seeking organic certification depth.
Strategic Opportunities
- Canadian cross-border expansion:Health Canada's Food and Drug Regulations and the Safe Food for Canadians Act impose parallel acidification standards, creating regulatory alignment for US producers with existing FDA compliance infrastructure.
- Pouch packaging in food processing bulk purchasing:Alternative formats gain traction among industrial buyers seeking reduced freight costs and improved handling efficiency in high-volume kitchen operations.
- USDA National Organic Program stringency:Evolving certification requirements create competitive moats for early adopters of comprehensive organic supply chain documentation.
Industry Challenges
- Acidified-food rulemaking uncertainty:FDA guidance document revisions create timeline risk for product reformulation and label-claim validation cycles.
- Laboratory validation capex:In-house pH testing and microbial screening equipment requires capital deployment that strains smaller fermentation operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vinegar Market |
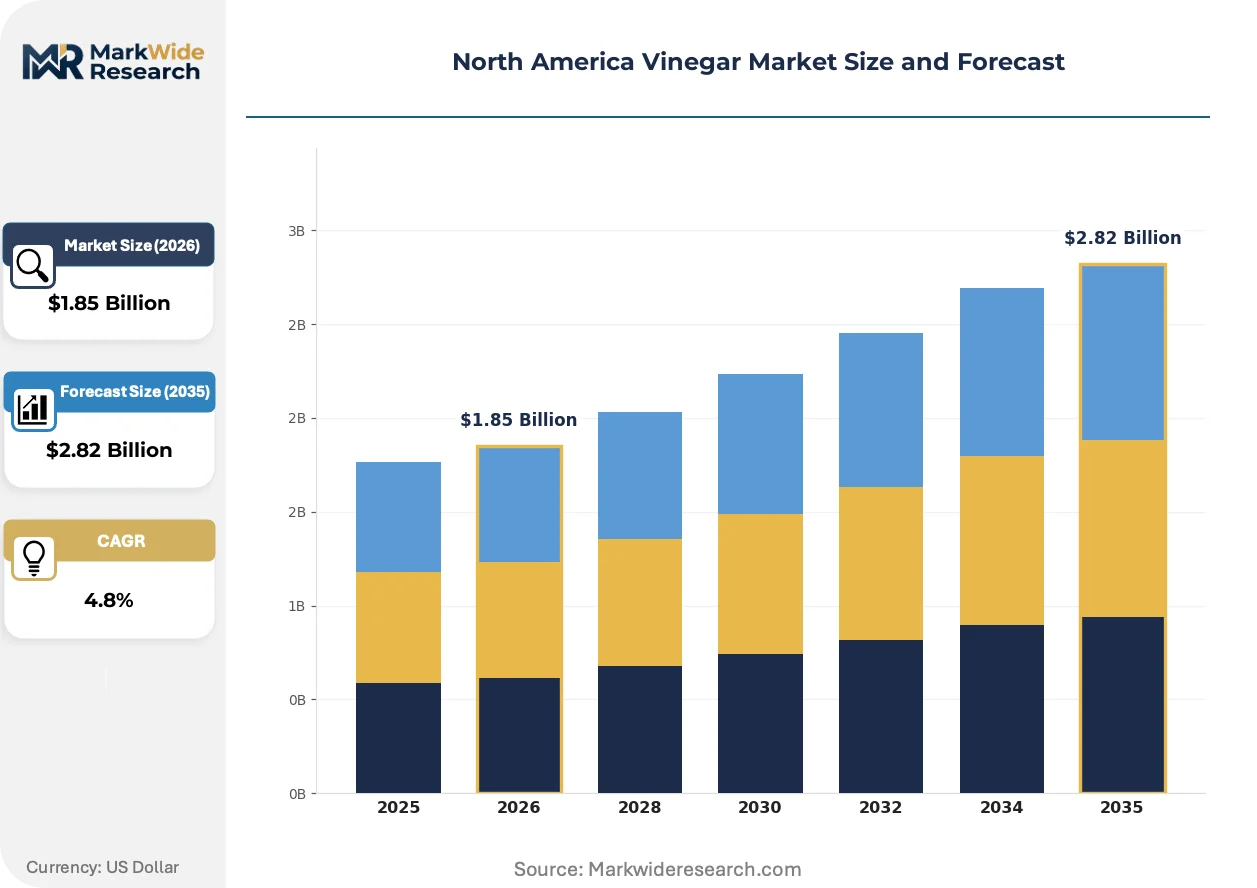
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balsamic, Apple Cider, White, Red Wine Packaging Type: Bottles, Jars, Pouches, Tetra Packs Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale End User: Household, Food Services, Food Processing, Retail |
| Companies Covered | Kraft Heinz Company, Mizkan Holdings, Carl Kühne KG, Australian Vinegar, Bragg Live Food Products, Marukan Vinegar, Eden Foods, Burg Groep, Aspall Cyder, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vinegar Market Strategic Shifts & Innovations
Technology convergence and regulatory stringency are simultaneously compressing production timelines and expanding certification requirements across North American vinegar manufacturing.
Continuous fermentation monitoring systems are hybridizing traditional batch oxidation processes with real-time acetic acid concentration tracking. Food service distributors and large-scale commercial kitchen operators are adopting these sensor arrays to ensure pH consistency in white and red wine vinegar procurement. The technology is hybridizing quality assurance protocols, enabling outcome-based supplier contracts that tie payment to documented acidification compliance rather than volume delivery.
The FDA's Food Safety Modernization Act acidified foods rulemaking is tightening documentation requirements for imported ethanol-derived substrates. Domestic producers with captive laboratory validation capacity are securing preferential placement in mass-market retail channels previously accessible to lower-cost foreign competitors. California's food manufacturing corridor exhibits the most pronounced supply base restructuring, with specialty blend producers investing in preventive control qualified individual certification.
Wellness-oriented household buyers are compressing switching cycles between vinegar categories, rotating purchases based on functional-food positioning rather than brand loyalty. Natural-products retail channels are capturing this behavioral shift through end-cap placement of apple cider vinegar adjacent to supplement aisles. The pattern concentrates most visibly in California and Pacific Northwest metropolitan markets, where clean-label preference intensity exceeds national benchmarks.
North America Vinegar Market Segmentation
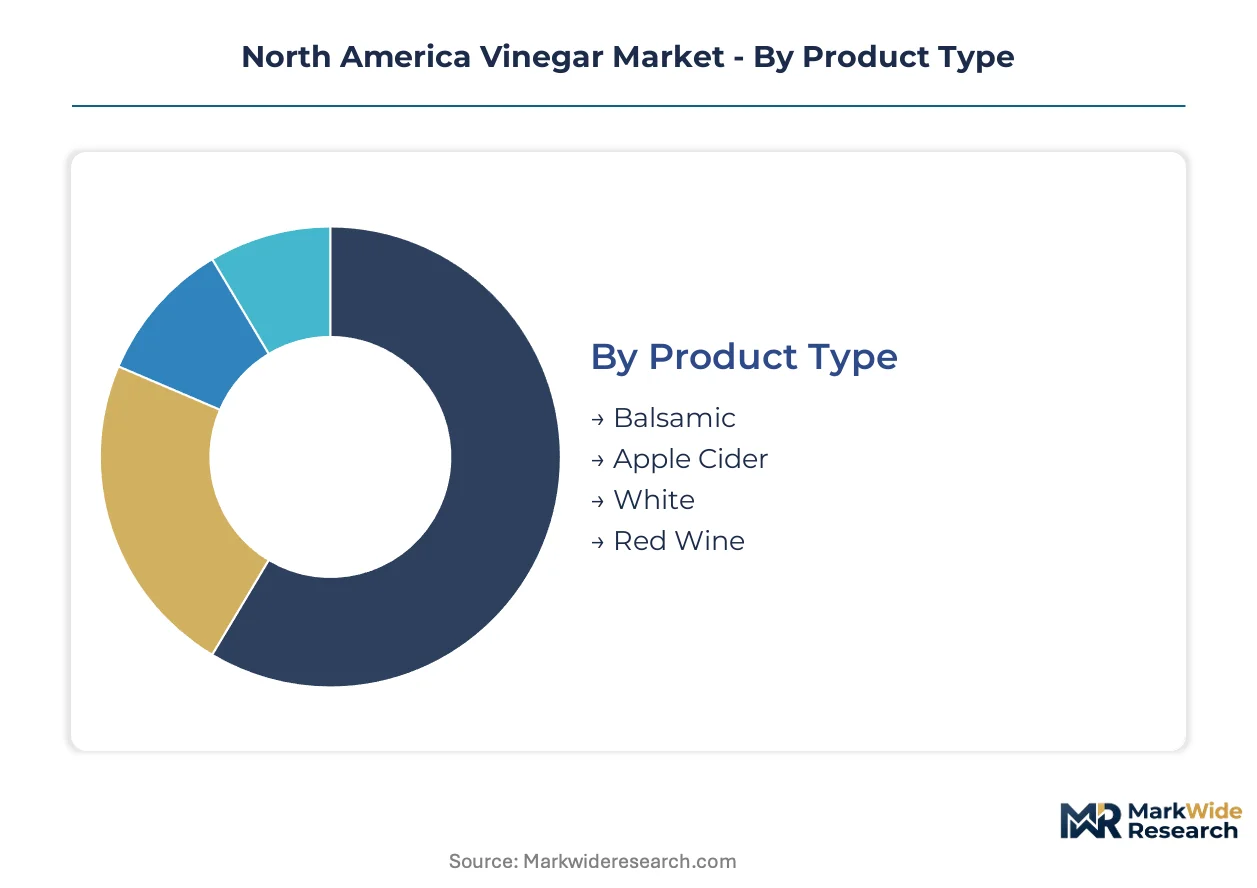
Vinegar segmentation in North America reflects divergent velocity patterns across consumption contexts. Product categories cycle at different speeds depending on wellness trends and food service procurement rhythms. Packaging and channel choices further stratify turnover rates based on handling economics and buyer sophistication.
Product Type:
Apple cider vinegar turns over fastest in retail channels driven by wellness-oriented purchasing, while balsamic maintains slower rotation in premium placement. White and red wine varieties exhibit intermediate velocity tied to food service contract renewal cycles.
- Apple Cider:Fermented from crushed apples with 5-6% acetic acid concentration and cloudy unfiltered presentation. Demand concentrates in California's natural-products retail corridor where wellness-oriented household buyers rotate purchases based on functional-food positioning adjacent to supplement aisles.
- Balsamic:Aged grape must reduction with complex sugar-acid balance and protected origin specifications for traditional grades. Procurement concentrates in specialty retail channels where premium placement commands slower inventory turns and higher margin retention.
- White:Grain-ethanol fermentation yielding neutral flavor profile and consistent 5% acidity standardization. Food service distributors standardize procurement for commercial kitchen pH control applications.
- Red Wine:Grape-derived fermentation retaining phenolic compounds and characteristic color stability. Mediterranean restaurant chains specify this variety for dressing and marinade formulations.
White vinegar anchors the volume base while apple cider gains share at the steepest rate.
Packaging Type:
Cost tier differentiation separates premium glass presentation from economy bulk formats. Material choice directly shapes freight economics and shelf-life performance across distribution distances.
- Bottles:Glass or PET containers with tamper-evident closures dominate retail shelf presence. Mass-market channels prioritize this format for brand visibility and consumer handling familiarity.
- Jars:Wide-mouth glass packaging facilitates scooping access for paste and thick varieties. Specialty retail segments favor this presentation for artisanal positioning.
- Pouches:Flexible multilayer film reduces freight weight and improves cube utilization. Food processing bulk purchasing adopts this format for reduced handling costs in high-volume kitchen operations.
- Tetra Packs:Aseptic carton technology extends ambient shelf stability without refrigeration. Institutional food service channels specify this format for storage efficiency.
Bottles retain the installed base while pouches are climbing the fastest in food service adoption.
Distribution Channel:
Customer type stratification separates household impulse purchasing from institutional procurement discipline. Channel selection determines promotional intensity and compliance documentation requirements.
- Supermarkets:Mass-market retail with high-velocity shelf rotation and promotional calendar dependency. End-cap placement drives trial conversion for wellness-positioned varieties.
- Online Retailers:Direct-to-consumer fulfillment with subscription model potential and review-driven discovery. Pacific Northwest metropolitan markets show elevated penetration in this channel.
- Specialty Stores:Curated assortment with educated staff and premium price acceptance. Natural-products retail captures rotation-based purchasing from clean-label seekers.
- Wholesale:Volume contracting with food service distributors and institutional buyers. pH documentation and acidification compliance certificates determine supplier qualification.
Supermarkets anchor volume throughput while online retailers are expanding most quickly in subscription segments.
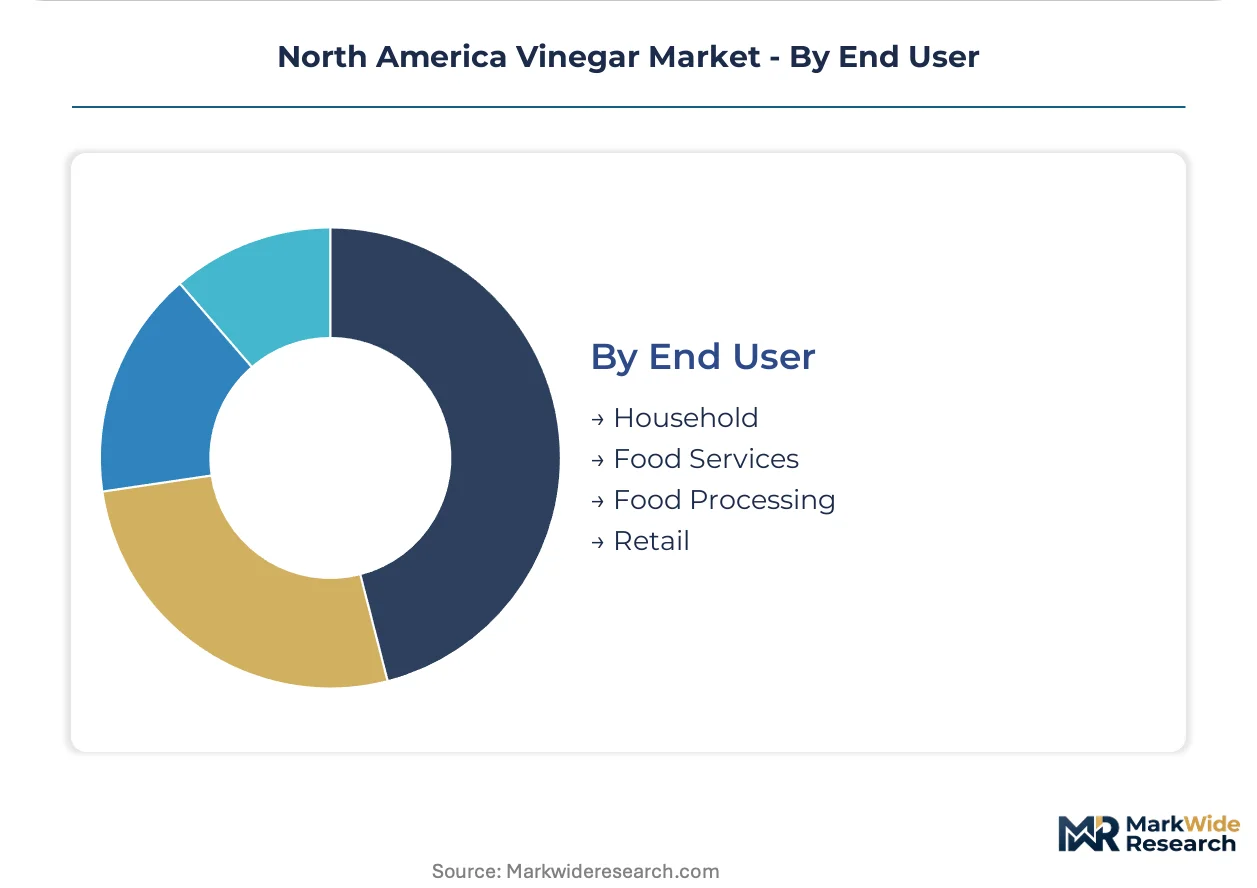
End User:
Application maturity separates established industrial processing from emerging functional consumption patterns. User type dictates specification stringency and certification depth requirements.
- Food Services:Commercial kitchen operations with standardized procurement and pH compliance documentation. White and red wine varieties dominate this segment for dressing and marinade production.
- Food Processing:Industrial acidification applications with preventive control requirements and laboratory validation protocols. FDA acidified foods compliance determines supplier eligibility.
- Household:Wellness-oriented buyers rotating between categories based on functional positioning rather than brand loyalty. Apple cider captures the steepest share gain in this segment.
- Retail:Resale-oriented purchasing with private-label development and shelf placement negotiation. Premium blend producers invest in organic certification depth for natural-products channel access.
Food services commands the largest volume absorption while household consumption is gaining share fastest on wellness positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds Canadian benchmarks by roughly one-third, reflecting California's premium-channel concentration and Mexico's cost-advantaged fermentation base. This asymmetry shapes cross-border investment flows and supply chain configuration across the tri-national vinegar production footprint.
United States
California's food manufacturing corridor drives specialty vinegar demand through wellness-oriented retail placement. The FDA's Food Safety Modernization Act acidified foods requirements tighten compliance documentation for domestic and imported products alike. Los Angeles and San Francisco metropolitan markets exhibit the steepest clean-label preference intensity, commanding premium shelf positioning for organic-certified varieties.
Canada
Health Canada's Food and Drug Regulations impose parallel acidification standards that facilitate regulatory alignment for US suppliers. The Safe Food for Canadians Act governs cross-border product movement through preventive control requirements. Ontario and Quebec food processing clusters absorb bulk white vinegar volumes for industrial acidification applications in condiment manufacturing.
Mexico
Cost-advantaged grain ethanol feedstock availability supports fermentation operations serving North American mass-market channels. Mexican agricultural substrate cycles influence regional input cost structures for white vinegar production. Baja California and central Mexico fermentation facilities supply contract manufacturing arrangements for US private-label brands seeking margin compression.
North America Vinegar Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in substrate cultivation and captive acetic acid production. The North American vinegar market exhibits consolidated mass-market retail placement alongside fragmented specialty fermentation operations. Three archetypes dominate: diversified food conglomerates with refrigerated distribution networks, vertically integrated Asian fermentation houses with rice vinegar expertise, and organic-certified specialists with natural-products channel depth. Competitive moves concentrate on backward integration into ethanol feedstock security and co-packing arrangements that lower capital barriers for mid-sized brand expansion.
Among diversified food conglomerates, Kraft Heinz Company occupies a position exemplifying mass-market shelf dominance through established retail relationships. Mizkan Holdings anchors the Asian fermentation specialist archetype with demonstrated rice vinegar supply consistency. Bragg Live Food Products represents the organic-certified specialist tier, sitting within natural-products retail channels where certification depth commands buyer loyalty. These three players illustrate the strategic segmentation between scale-driven distribution, upstream substrate control, and premium-channel positioning that defines competitive structure in this market.
| Leading Market Players |
|---|
| Kraft Heinz Company |
| Mizkan Holdings |
| Carl Kühne KG |
| Australian Vinegar |
| Bragg Live Food Products |
| Marukan Vinegar |
| Eden Foods |
| Burg Groep |
| Aspall Cyder |
| Others |
Cost & Logistics Intelligence
Commodity ethanol feedstock volatility compresses margin buffers across fermentation operations while simultaneously widening spreads between premium organic-certified and economy white vinegar tiers, forcing supply chain reconfiguration toward captive grain sourcing and regional acidification hubs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the North America vinegar market. Price differentiation hinges on organic certification depth under the USDA National Organic Program and volume scale commitments in food service contracting. Cost compression in the economy tier is intensifying because Mexican grain-ethanol substrate advantages attract contract manufacturing migration. Household wellness buyers show the least price sensitivity, while food processing bulk purchasers drive the hardest volume-based negotiations.
Supply Chain Analysis
FDA acidified foods documentation requirements function as de facto export controls limiting cross-border substrate flows from smaller foreign suppliers lacking laboratory validation capacity. Supply concentrates in the United States, Canada, and Mexico, with California's food manufacturing corridor and central Mexico fermentation facilities anchoring regional production. Raw material dependencies center on grain ethanol, apple pomace, and grape must from agricultural commodity markets. Single-source vulnerability concentrates in specialty balsamic aged stock reserves. Distribution runs through refrigerated food service networks and mass-market retail shelf placement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable barriers—FDA acidified foods compliance costs and organic certification timelines lock in incumbent positioning while raising entry costs for challengers.
For Market Incumbents: Build certification moats by accelerating preventive control qualified individual staffing and in-house pH testing laboratory deployment. Kraft Heinz Company and Mizkan Holdings should deepen backward integration into grain and rice ethanol feedstock security to defend against Mexican contract manufacturing erosion. Channel control through refrigerated distribution network exclusivity agreements protects mass-market shelf placement against private-label encroachment. For New Entrants and Emerging Players: Pacific Northwest metropolitan markets exhibit underpenetration in subscription-model apple cider vinegar direct-to-consumer channels. Clean-label seekers in this geography rotate purchases based on functional positioning rather than brand loyalty, creating white-space for organic-certified specialists. Pouch packaging adoption in food processing bulk purchasing offers a second entry vector with reduced capital requirements versus glass bottling infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors organic-certified specialists with natural-products channel depth. Long-term viability over the next decade rests on regulatory compliance infrastructure rather than brand equity alone. Acquisition targets should demonstrate existing FDA laboratory validation protocols and USDA organic supply chain documentation. The signal to watch is Health Canada alignment with evolving FDA acidified foods rulemaking, which would trigger cross-border supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Feedstock | Captive grain supply secures margin buffers against agricultural commodity cycles. |
| Preventive Control Laboratory Certification | FDA acidified foods compliance creates preferential retail placement for domestic producers. |
| Pouch Packaging Format Expansion | Food service distributors adopt flexible film for reduced freight weight in bulk purchasing. |
| Organic Certification Depth Investment | USDA National Organic Program stringency builds competitive moats in natural-products retail. |
| Canadian Cross-Border Regulatory Alignment | Health Canada parallel standards enable US producers to leverage existing FDA infrastructure. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with fermentation operations managers, regulatory affairs leads at acidified food processors, category buyers at food service distributors, and organic certification specialists; and secondary validation through FDA guidance document archives, USDA National Organic Program standards, Health Canada Food and Drug Regulations, customs trade flow records, and SEC filings from diversified food conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across product type, packaging format, distribution channel, and end-user segmentation dimensions.
Forecast inputs considered grain and fruit substrate price cycles, wellness-oriented household buyer behavioral shifts, food service contract renewal patterns, and regulatory compliance cost trajectories across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. The analytical framework modeled acidification standardization technology adoption curves and organic certification penetration rates as industry-specific demand shapers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-label contract manufacturers or Asian fermentation houses with rice vinegar expertise would shift outcomes. Material shifts in FDA acidified foods rulemaking timelines or USDA organic certification stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Australia Water Enhancer Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
Resveratrol Market
Food Enhancers and Additives
Emulsifier Alternatives Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
Australia Food Flavor and Enhancer Market
Food Enhancers and Additives
North America Feed Palatability Enhancers Market
Food Enhancers and Additives
Food Thickening Agents Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Yellow Fats Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Germany Food Flavor and Enhancer Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market
Food Enhancers and Additives
Gut Modifiers Market