
 Global Citrus Aurantium Extract Market | 2026-2036
Global Citrus Aurantium Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Global Citrus Aurantium Extract Market Analysis
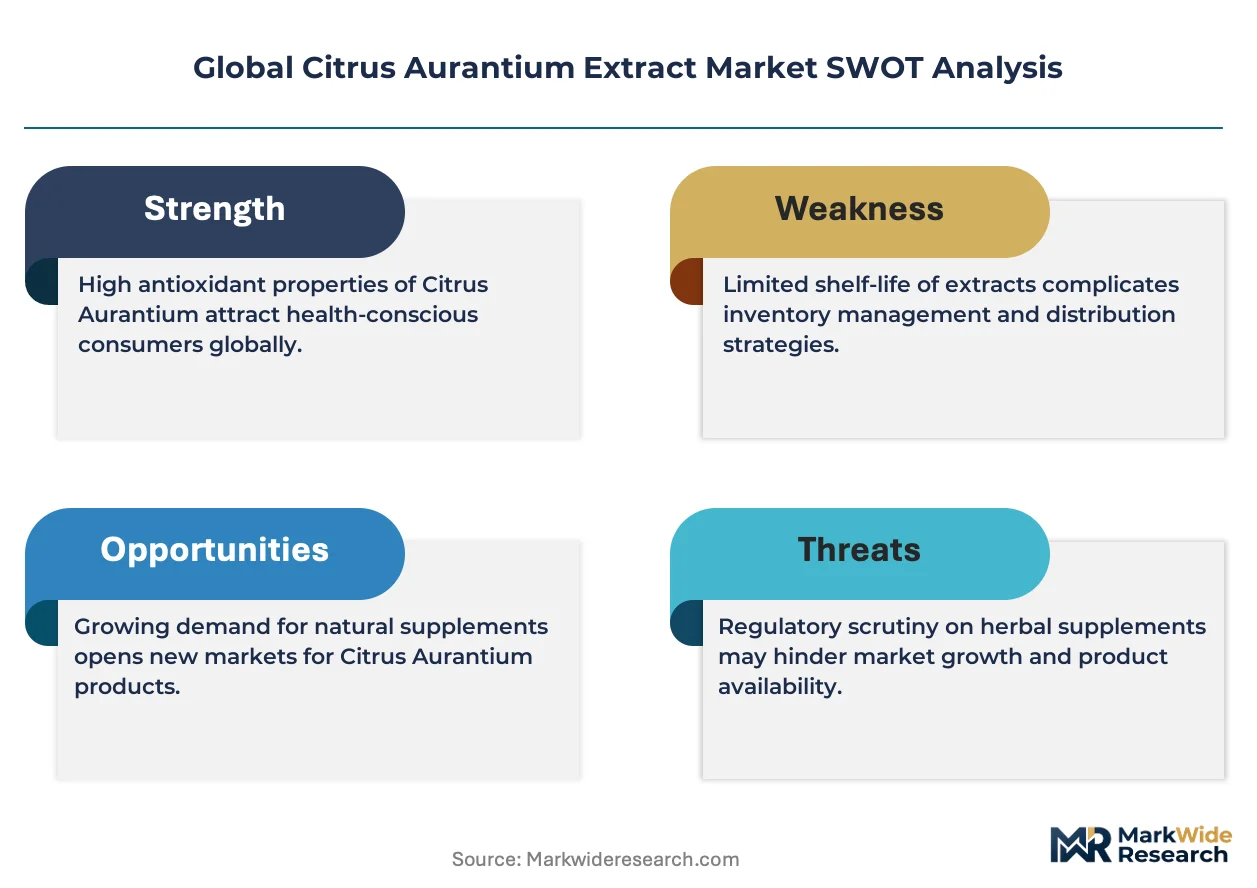
Subscription-based raw material sourcing is hardening as the dominant commercial model in citrus aurantium extract supply. Sabinsa Corporation leverages its vertically integrated botanical extraction infrastructure to secure consistent alkaloid profiles for pharmaceutical clients. Layn Natural Ingredients Corp. anchors its position through captive citrus cultivation in subtropical growing regions. Bio Biotinica competes on specialized organic certification tiers that command premium positioning in European specialty channels.
Citrus aurantium extract comprises bioactive compounds derived from the bitter orange fruit, principally synephrine, flavonoids, and volatile terpenes recovered through hydrodistillation or supercritical CO2 extraction; manufacturers standardize these markers to between 4% and 10% synephrine content for pharmaceutical and nutraceutical applications. Powder formats dominate volume throughput due to stability advantages in blending operations and extended shelf life under ambient storage conditions. Liquid extract sales accelerate fastest through online retail channels serving small-batch dietary supplement manufacturers who require flexible dosing integration. Essential oil segments occupy concentrated margin pools in cosmetics applications where fragrance houses value terpene complexity for natural positioning.
FDA oversight of dietary supplement New Dietary Ingredient notifications constrains rapid market entry for novel bitter orange alkaloid ratios in the United States. EFSA's evolving stance on synephrine safety thresholds shapes permissible dosage claims across European member states, while China's NMPA and GB standards govern import quality specifications for botanical raw materials entering pharmaceutical supply chains. Stakeholders must monitor regulatory divergence between pharmacopeial-grade and food-grade specifications as classification decisions determine accessible distribution channels and labeling permissions.
Market Dynamics
Subscription-based raw material sourcing is hardening as the dominant commercial model in citrus aurantium extract supply, with vertically integrated botanical extraction infrastructure reshaping competitive positioning across pharmaceutical and nutraceutical procurement channels.
Growth Catalysts
- EFSA Health Claim Pathways:The European Food Safety Authority's evolving assessments on synephrine safety are creating clearer registration frameworks for weight management formulations, enabling faster product launches across EU member states.
- Supercritical CO2 Extraction:This solvent-free recovery method is displacing conventional hydrodistillation in premium pharmaceutical applications, yielding higher flavonoid retention and cleaner alkaloid profiles for standardized extracts.
- Dietary Supplement Concentration:Germany and the United States are anchoring procurement volumes as manufacturers expand bitter orange extract integration into plant-based metabolic support portfolios.
Market Restraints
- FDA NDI Notification Burden:New Dietary Ingredient pre-market notifications for novel synephrine ratios impose 75-120 day review timelines that constrain rapid formulation innovation in the United States.
- Captive Cultivation Concentration:Subtropical citrus growing regions in China and India concentrate raw material supply, exposing processors to climate volatility and geopolitical trade friction.
- Pharmacopeial-Grade Specification Divergence:Inconsistent purity standards between USP, EP, and ChP monographs force dual-certification investments that elevate working capital requirements for cross-border suppliers.
Strategic Opportunities
- Essential Oil Cosmetics Penetration:Fragrance houses in France and Switzerland are expanding terpene complexity specifications for natural positioning in clean beauty formulations, opening premium margin pools outside traditional nutraceutical channels.
- Organic Certification Tiers:EU 2018/848 organic regulation alignment is creating definitional clarity that specialty European distributors exploit for 15-30% price premiums in pharmacy and apothecary channels.
- Liquid Extract E-Commerce:Small-batch dietary supplement manufacturers are migrating procurement to online retail platforms that offer flexible dosing integration and reduced minimum order quantities.
Industry Challenges
- Alkaloid Standardization Expertise:Chromatographic assay proficiency for 4-10% synephrine consistency remains concentrated among analytical chemists in Basel and Hyderabad, creating talent scarcity for new market entrants.
- Dual-Grade Inventory Management:Pharmaceutical and food-grade specification divergence forces parallel stock-keeping unit systems that complicate demand forecasting and elevate obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Citrus Aurantium Extract Market |
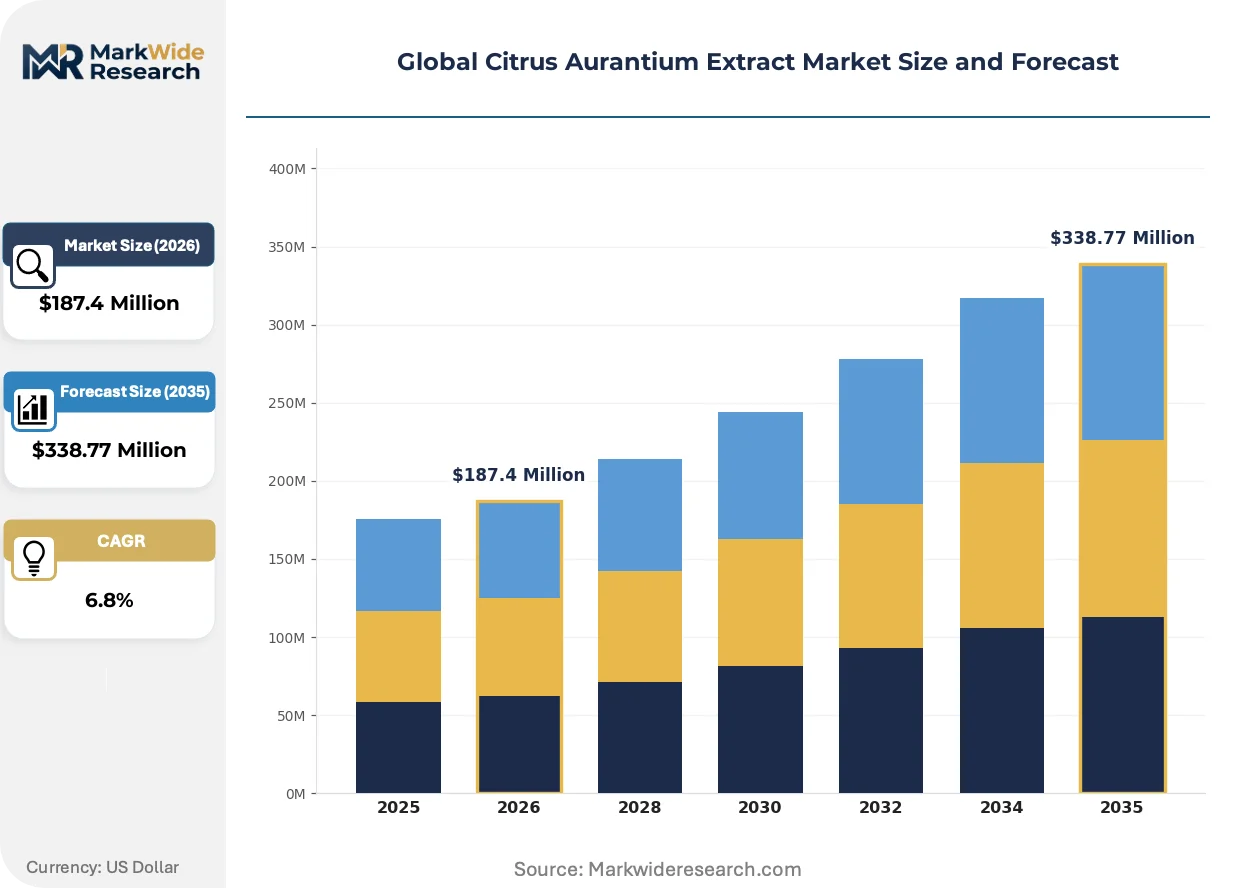
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Powder, Liquid Extract, Capsules Application: Pharmaceuticals, Food & Beverages, Cosmetics, Dietary Supplements Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Manufacturers, Retailers, Wholesalers, Consumers |
| Companies Covered | Bio Biotinica, Sabinsa Corporation, Innophos Inc., Layn Natural Ingredients Corp., Organic Herb Inc., Synthite Industries Ltd., BI Nutraceuticals, Naturalin Bio-Resources Co. Ltd., Kalsec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Citrus Aurantium Extract Market Emerging Trajectories
Extraction technology convergence and regulatory clarity initiatives are reshaping value capture in citrus aurantium derivatives, with downstream buyers demanding traceable alkaloid provenance and flexible format integration.
Supercritical CO2 extraction systems paired with inline chromatographic monitoring are electrifying quality assurance protocols in pharmaceutical-grade production. European contract manufacturers are adopting these integrated platforms at 20-25% annual investment rates. This technology compression is enabling real-time standardization adjustments that reduce batch rejection rates and accelerate release timelines for time-sensitive nutraceutical contracts.
China's NMPA implementation of revised GB standards for botanical raw materials is tightening import quality specifications entering pharmaceutical supply chains. Domestic extractors must now demonstrate heavy metal and pesticide residue compliance at stricter thresholds than previous administrative measures required. This regulatory tightening most affects powder format exporters serving Chinese finished dose manufacturers, who are responding by qualifying secondary suppliers in Vietnam and Indonesia.
Small-batch dietary supplement manufacturers are unbundling traditional distributor relationships in favor of direct platform procurement. Online retail channels serving North American and Western European formulators are replacing regional ingredient distributors for liquid extract purchases under 500 kilograms annually. This channel disintermediation is most visible in California and Bavaria, where startup supplement brands prioritize formulation agility over volume discounts.
Global Citrus Aurantium Extract Market Segmentation
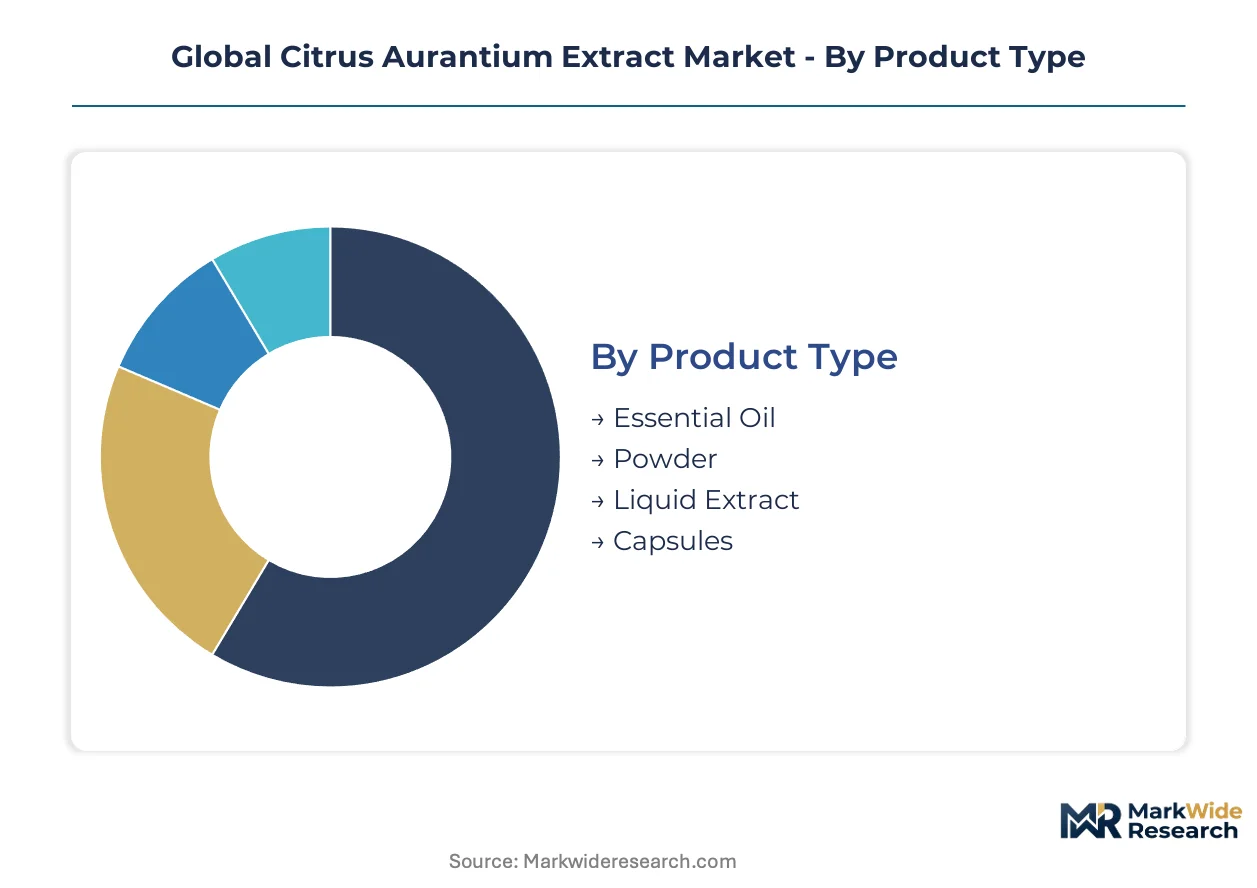
Alkaloid standardization requirements and extraction technology choices fragment the citrus aurantium extract landscape into distinct commercial tiers. Procurement patterns diverge sharply between pharmaceutical-grade specifications and commodity food-grade volumes, with each segment demanding specialized certification and inventory management.
Product Type:
Capital intensity escalates from solvent-based extraction through supercritical CO2 systems to pharmaceutical-grade chromatographic finishing, concentrating manufacturing investment in powder and essential oil segments.
- Powder:Spray-dried extracts standardized to 4-10% synephrine content dominate pharmaceutical and nutraceutical procurement due to stability under ambient storage and seamless blending integration. German dietary supplement manufacturers anchor volume demand as they expand bitter orange integration into metabolic support portfolios.
- Liquid Extract:Hydroalcoholic or glycerin-based solutions enable flexible dosing for small-batch formulators. California and Bavaria-based startup supplement brands are migrating procurement to online platforms, prioritizing formulation agility over volume discounts.
- Essential Oil:Steam-distilled terpene fractions command premium positioning in fragrance applications.
- Capsules:Pre-dosed finished formats serve direct-to-consumer channels with minimal processing requirements.
Most installed capacity flows through Powder. Expansion is steepest in Liquid Extract.
Application:
Regulatory pathway complexity separates pharmaceutical registrations from food-grade self-affirmation, with EFSA and FDA diverging on synephrine safety thresholds.
- Dietary Supplements:Weight management formulations drive procurement volumes as consumers shift toward plant-based metabolic support. United States and German manufacturers are expanding standardized bitter orange sourcing for thermogenic and appetite-modulation claims.
- Pharmaceuticals:Pharmacopeial-grade extracts require USP, EP, or ChP certification with heavy metal and pesticide residue documentation. China's NMPA revised GB standards are tightening import specifications, forcing dual-certification investments from cross-border suppliers.
- Cosmetics:Essential oil terpene complexity attracts fragrance houses in France and Switzerland seeking natural positioning.
- Food & Beverages:Flavoring applications face Novel Food regulatory barriers in the European Union.
Dietary Supplements concentrate the highest procurement volumes. Pharmaceuticals deliver the steepest margin expansion trajectory.
Distribution Channel:
Channel disintermediation is compressing traditional distributor margins as digital procurement platforms capture small-batch volume.
- Online Retail:Direct platform procurement is displacing regional distributors for purchases under 500 kilograms annually, particularly visible in North American and Western European formulator clusters.
- Direct Sales:Long-term contracts between extractors and pharmaceutical manufacturers secure alkaloid supply consistency through subscription-based sourcing models.
- Specialty Stores:Pharmacy and apothecary channels in the European Union exploit EU 2018/848 organic certification for 15-30% price premiums.
- Supermarkets:Mass-market retail carries limited SKUs due to regulatory complexity and consumer education requirements.
Direct Sales channels lock in the majority of pharmaceutical-grade volume. Online Retail is gaining share fastest among small-batch manufacturers.
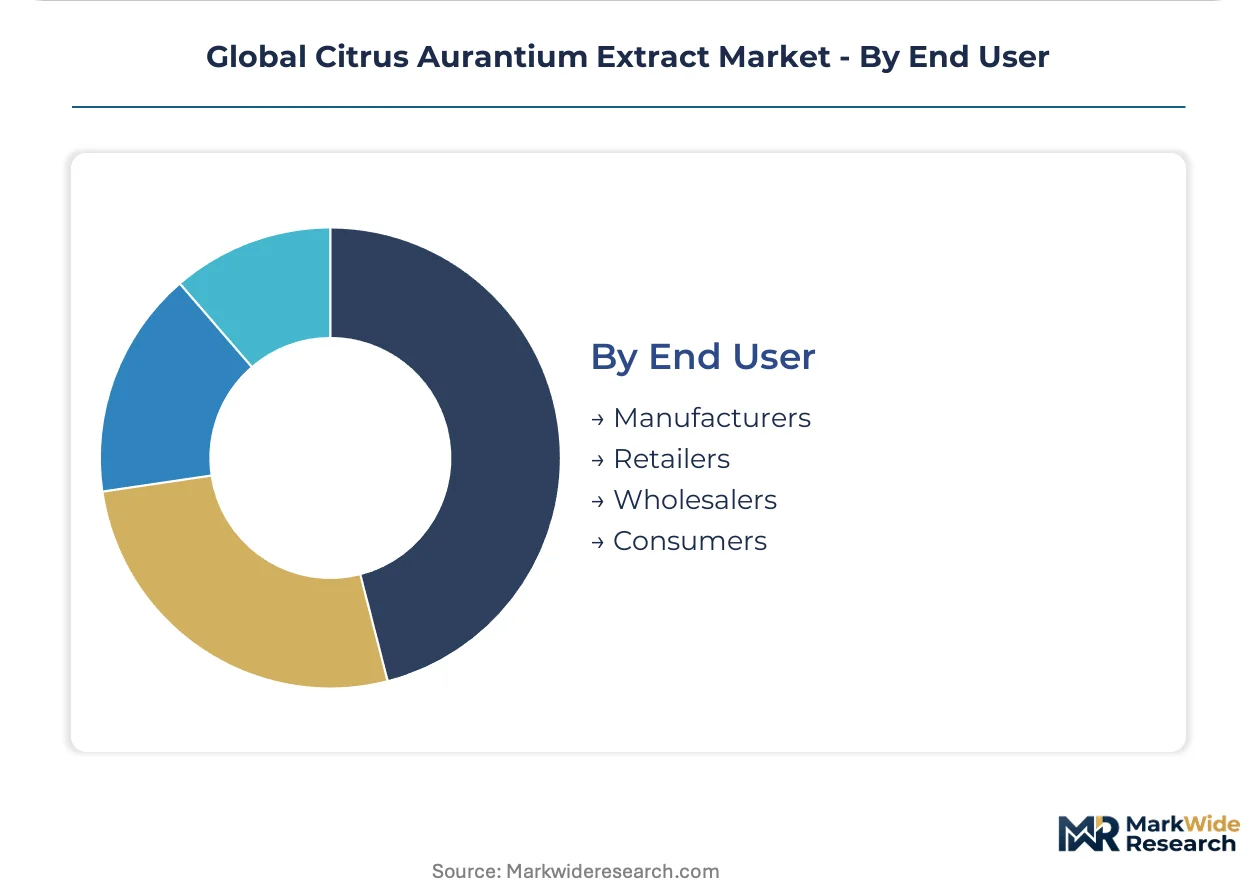
End User:
Specification divergence between pharmacopeial-grade and food-grade requirements forces parallel inventory systems that complicate demand forecasting.
- Manufacturers:Finished dose and supplement formulators in Germany, the United States, and China drive procurement with exacting alkaloid consistency requirements. Chromatographic assay proficiency remains concentrated among analytical chemists in Basel and Hyderabad, creating talent scarcity for new supplier qualification.
- Wholesalers:Inventory aggregation functions face margin pressure from channel disintermediation and direct platform procurement trends.
- Retailers:Pharmacy chains and natural product stores in the European Union navigate evolving EFSA health claim assessments.
- Consumers:Direct purchases concentrate in online channels with educational content requirements around synephrine safety profiles.
Manufacturers absorb the dominant share of extraction output. Wholesalers are experiencing the steepest volume compression from platform disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dietary supplement manufacturers procure standardized bitter orange extracts at volumes exceeding French fragrance houses, while Chinese pharmaceutical raw material imports face tightening GB standards that redirect sourcing toward Southeast Asian alternatives.
United States
California and Florida-based formulators drive liquid extract demand through direct platform procurement for small-batch metabolic support products. FDA New Dietary Ingredient notifications impose 75-120 day review timelines that constrain rapid alkaloid ratio innovation. Austin and San Diego startup clusters prioritize formulation agility over volume discounts in subscription-based sourcing arrangements.
Germany
Bavarian and North Rhine-Westphalia supplement manufacturers anchor European procurement volumes for 4-10% synephrine standardized powders. EFSA health claim assessments on synephrine safety thresholds shape permissible dosage frameworks across EU member states. Frankfurt and Munich industrial zones concentrate chromatographic assay proficiency for alkaloid consistency verification.
China
NMPA revised GB standards for botanical raw materials tighten heavy metal and pesticide residue thresholds for pharmaceutical supply chain entry. Yangtze River Delta and Pearl River Delta extractors face qualification pressure as domestic finished dose manufacturers diversify toward Vietnamese and Indonesian secondary suppliers. Sichuan-Chongqing citrus cultivation regions supply captive raw material to provincial processing facilities.
France
Grasse and Paris fragrance houses command premium terpene complexity specifications for essential oil segments in clean beauty formulations. ANSM oversight of cosmetic ingredient safety intersects with EU 2018/848 organic regulation alignment for pharmacy channel positioning. Provence-Alpes-Côte d'Azur clusters specialize in steam-distilled volatile fraction recovery for natural fragrance applications.
Switzerland
Basel pharmaceutical analytical chemists concentrate chromatographic standardization expertise that new market entrants struggle to replicate. Swissmedic pharmacopeial-grade specifications require dual-certification investments from cross-border suppliers seeking European distribution access. Geneva and Zurich headquarters anchor contract manufacturing relationships with subscription-based raw material sourcing models.
Global Citrus Aurantium Extract Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with powder format suppliers commanding consolidated positions in pharmaceutical-grade procurement while liquid extract channels fragment among platform-enabled small-batch formulators. Three archetypes dominate: vertically integrated botanical extractors with captive cultivation assets, specialized organic certification holders targeting EU pharmacy premiums, and regional contract manufacturers leveraging supercritical CO2 infrastructure. Competitive moves concentrate on backward integration into subtropical citrus growing regions and technology licensing for inline chromatographic monitoring systems.
Among the named participants, Sabinsa Corporation exemplifies the vertically integrated archetype through its established botanical extraction infrastructure, while Layn Natural Ingredients Corp. represents cultivation-anchored positioning with subtropical growing region assets. Bio Biotinica occupies the specialized certification tier that European specialty channels reward with price premiums. These three illustrate how competitive differentiation fragments across supply chain control, geographic sourcing, and regulatory compliance capabilities rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| Bio Biotinica |
| Sabinsa Corporation |
| Innophos Inc. |
| Layn Natural Ingredients Corp. |
| Organic Herb Inc. |
| Synthite Industries Ltd. |
| BI Nutraceuticals |
| Naturalin Bio-Resources Co. Ltd. |
| Kalsec Inc. |
| Others |
Supply Flow & Price Mechanics
EFSA's tightening synephrine safety thresholds are forcing German and United States manufacturers to demand certified organic powder grades with full alkaloid traceability, compelling extractors to absorb dual-certification costs and pass selective premiums downstream.
Pricing Analysis
Capacity additions in China's Sichuan-Chongqing corridor are reshaping price floors for standard-grade powders while supercritical CO2-equipped European facilities command 15-30% premiums for pharmaceutical-grade consistency. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and chromatographic assay documentation. Cost compression in commodity food-grade extracts is intensifying because Vietnamese and Indonesian suppliers are qualifying under revised NMPA GB standards. Small-batch dietary supplement manufacturers in California and Bavaria show highest price sensitivity, while Swiss pharmaceutical contract manufacturers demonstrate lowest sensitivity due to subscription-based sourcing commitments.
Supply Chain Analysis
Dual-sourcing mandates from Basel-based pharmaceutical contract manufacturers are proliferating across European procurement desks, requiring parallel qualification of Indian and Chinese extractors to mitigate single-source vulnerability. Raw material supply draws from subtropical citrus cultivation belts in China, India, and Vietnam, with volatile monsoon patterns and geopolitical trade friction posing structural risks. Downstream distribution runs through subscription-based direct sales for pharmaceutical volumes, while platform-enabled online retail captures small-batch liquid extract demand from North American and Western European formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EFSA health claim clarity and FDA NDI pathway maturation are concentrating procurement among suppliers with demonstrable alkaloid standardization expertise.
For Market Incumbents: Anchor pharmaceutical-grade market share through captive cultivation investments in subtropical growing regions and inline chromatographic monitoring technology licensing. Defend against emerging Vietnamese and Indonesian entrants by accelerating USP-EP dual-certification completion before NMPA GB standard enforcement tightens. Prioritize subscription-based sourcing contract renewals with Basel and Frankfurt manufacturing clusters. For New Entrants and Emerging Players: Enter via liquid extract e-commerce platforms serving California and Bavaria startup supplement brands with flexible minimum order quantities below 500 kilograms annually. Target essential oil cosmetics penetration in French fragrance houses seeking terpene complexity for clean beauty positioning. Pursue organic certification under EU 2018/848 alignment to capture pharmacy channel premiums. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized organic certification holders commanding 15-30% price premiums in European apothecary channels. Long-term viability hinges on backward integration into subtropical citrus cultivation assets and supercritical CO2 extraction infrastructure ownership. Watch for NMPA GB standard enforcement acceleration as the inflection signal triggering consolidation among non-compliant Chinese extractors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Subtropical Cultivation | Captive citrus supply in China and India secures raw material consistency against climate volatility. |
| Supercritical CO2 Technology Licensing | Inline chromatographic monitoring adoption in Basel pharmaceutical zones reduces batch rejection rates. |
| Dual-Certification Investment (USP-EP-ChP) | Cross-border supplier qualification unlocks pharmaceutical procurement channels in Germany and Switzerland. |
| Organic Certification Alignment (EU 2018/848) | Pharmacy channel positioning in France and Germany commands tiered price premiums. |
| Platform-Enabled E-Commerce Expansion | Direct procurement relationships with California and Bavaria small-batch formulators replace distributor margins. |
Methodological Framework
Direct dialogue with extraction plant managers, pharmaceutical procurement leads at German and Swiss contract manufacturers, dietary supplement formulators in California and Bavaria, and EFSA regulatory affairs specialists grounded this analysis. Secondary validation drew from NMPA GB standard filings, EFSA health claim assessment documentation, FDA NDI notification databases, and customs trade records for bitter orange extract flows. Bottom-up volume modeling triangulated with top-down market sizing across product type, application, and distribution channel dimensions.
Bottom-up demand aggregation by segment combined with top-down macro constraint analysis shaped the projection framework across the analysis window. Segmentation modeling incorporated product format stability requirements, pharmacopeial-grade versus food-grade specification divergence, and regional regulatory pathway complexity. CAGRs were derived from installed capacity expansion rates, extraction technology adoption curves, and procurement pattern shifts among pharmaceutical and nutraceutical end-users. Forecast inputs included EFSA health claim timeline assumptions and NMPA enforcement trajectory indicators.
Inputs from NMPA administrative measures and EFSA scientific opinion releases were available through the study window; gaps in real-time FDA NDI review timeline data introduce uncertainty bands around United States market entry assumptions. Forecasts reflect documented assumptions regarding regulatory pathway maturation and extraction technology diffusion rates. Deviation in EFSA synephrine safety threshold finalization or NMPA GB standard enforcement acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
South America Feed Palatability Enhancers Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
UK Food Flavor and Enhancer Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
Europe Food Flavor and Enhancer Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
United Kingdom Interesterified Fats Market
Food Enhancers and Additives
Asia-Pacific Feed Palatability Enhancers Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
Flour Conditioner Market
Food Enhancers and Additives
High Ratio Shortening Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market