
 South Africa Food Flavor and Enhancer Market | 2026-2036
South Africa Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Food Flavor and Enhancer Market Analytics
A shift from single-source imports toward multi-source local blending is hardening across South Africa's flavor supply base. Givaudan leverages its Johannesburg technical center to anchor regional formulation services for beverage and dairy clients. Sensient Technologies competes through specialized natural color-flavor combinations tailored to local fruit profiles. Afriplex (Pty) Ltd occupies a distinctive position by sourcing indigenous botanicals such as buchu and rooibos for premium extract lines.
Food flavor and enhancer systems comprise volatile aromatic compounds, taste-active peptides, nucleotides, and Maillard reaction products engineered to deliver targeted sensory profiles at parts-per-million concentrations. Their primary commercial purpose is to restore flavor intensity lost during thermal processing, extended shelf-life packaging, or sodium-fat reduction in mass-market foods. Natural flavors and extracts command premium positioning as clean-label momentum shifts procurement budgets away from artificial alternatives. Powder and liquid forms dominate industrial throughput, with powder formats preferred for dry seasoning blends and liquid concentrates optimized for beverage manufacturing lines.
South Africa's Department of Health enforces sodium reduction targets under the Foodstuffs, Cosmetics and Disinfectants Act, pushing manufacturers toward potassium chloride blends and yeast extract-based umami solutions. The country's national standards body, the South African Bureau of Standards (SBS), mandates label compliance for flavor declarations and allergen thresholds that determine market access for imported additive packages. Local producers must also navigate Department of Agriculture, Land Reform and Rural Development biosecurity protocols for botanical raw material imports. Stakeholders should monitor how pending amendments to labeling regulations will redefine permissible clean-label claims and reshape competitive positioning between synthetic and natural flavor portfolios.
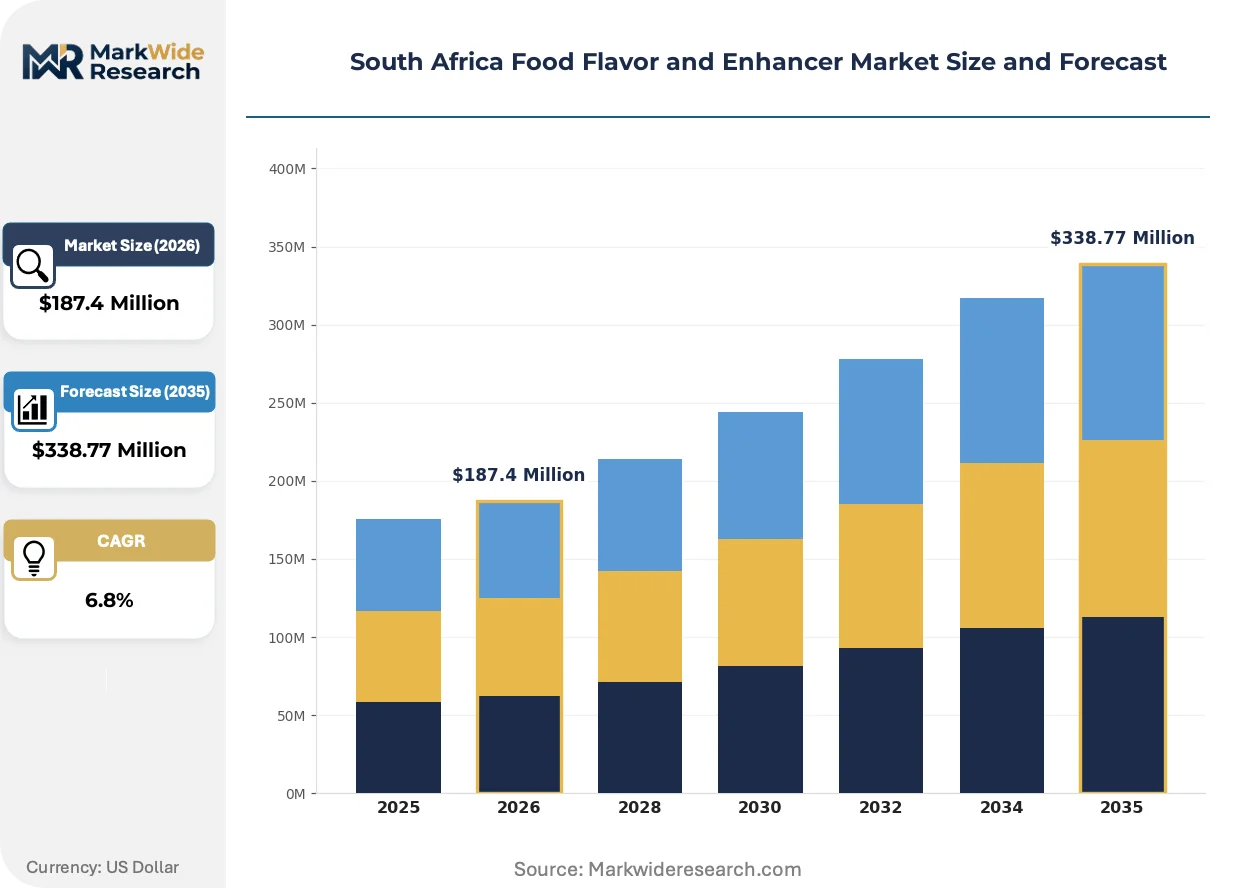
Market Dynamics
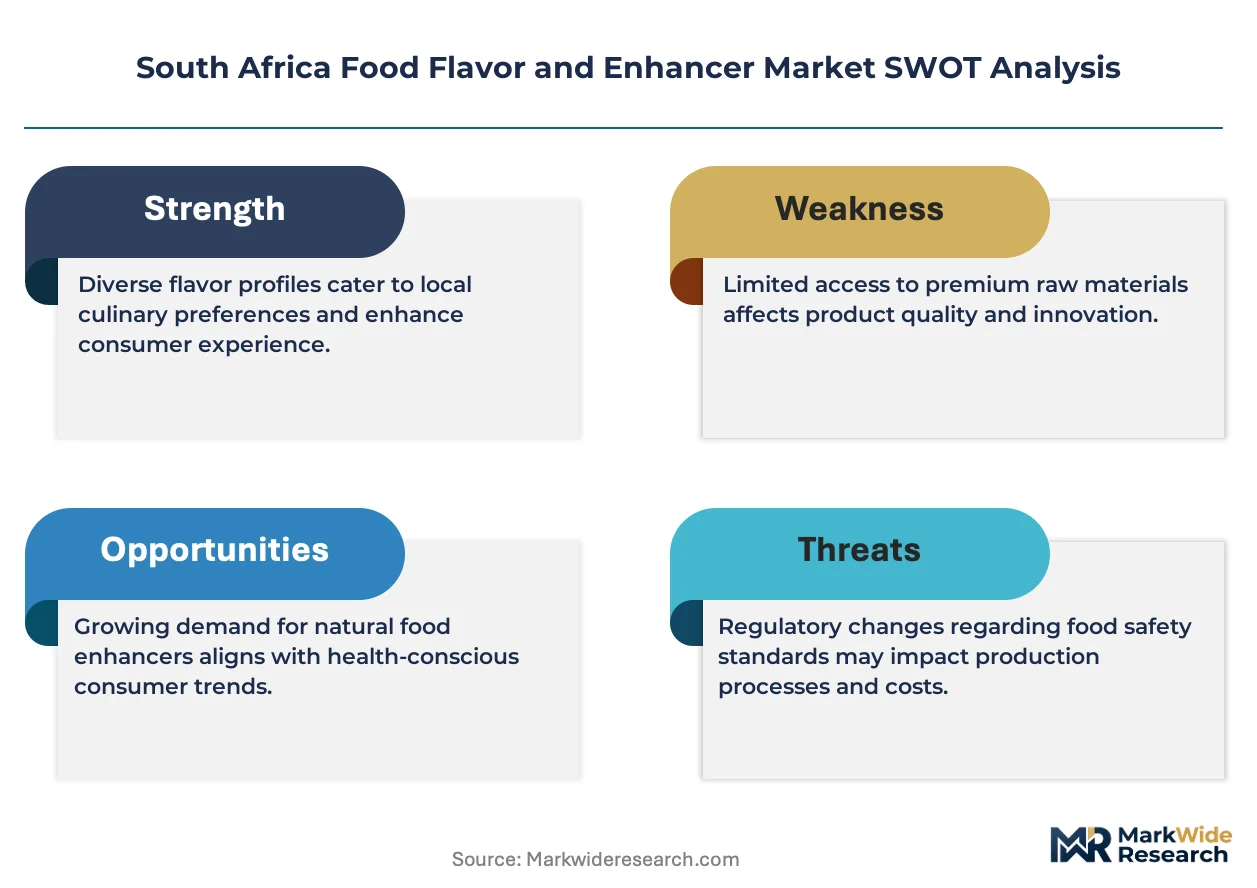
Sodium reduction mandates from South Africa's Department of Health are forcing mass-market reformulation across processed food categories, redirecting procurement budgets toward yeast extract-based umami systems and natural flavor blends that restore taste intensity without salt.
Growth Catalysts
- Clean-label procurement:Beverage and snack manufacturers in Johannesburg's industrial corridor are expanding bulk purchasing of natural extracts to meet retailer clean-label requirements.
- Regulatory sodium targets:The Foodstuffs, Cosmetics and Disinfectants Act mandates progressive sodium reduction, accelerating adoption of potassium chloride blends and nucleotide-based enhancers.
- Indigenous botanical commercialization:Buchu and rooibos extraction capabilities are creating premium positioning for local flavor houses serving export-oriented organic brands.
Market Restraints
- Import dependency for specialty inputs:Botanical raw materials not native to the Western Cape require biosecurity clearance under Department of Agriculture protocols, creating lead time volatility.
- Technical substitution limits:Yeast extracts cannot fully replicate the temporal flavor release of sodium chloride in certain thermal-processed meat applications.
- Cost structure pressure:Natural flavor concentrations command 3-5x the unit cost of synthetic alternatives, compressing margins in mass-market categories.
Strategic Opportunities
- Underpenetrated rural retail:Independent grocers in Limpopo and Mpumalanga represent unserved demand for affordable clean-label seasoning sachets.
- Regulatory tailwind for indigenous claims:Pending amendments to South African Bureau of Standards labeling rules may permit "locally sourced" certifications that differentiate premium portfolios.
- Technology convergence:Encapsulation technologies paired with indigenous botanicals are enabling controlled-release flavor systems for extended-shelf-life products.
Industry Challenges
- Formulation talent scarcity:Competent flavor chemists familiar with Maillard reaction optimization for reduced-salt matrices remain concentrated in Gauteng.
- Certification timeline compression:South African Bureau of Standards flavor declaration reviews are extending market entry timelines for imported additive packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Food Flavor and Enhancer Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Seasonings, Extracts End User: Food Processing, Bakeries, Beverage Manufacturers, Restaurants Application: Dairy Products, Snacks, Sauces, Confectionery Form: Liquid, Powder, Granulated, Paste |
| Companies Covered | International Flavors & Fragrances (IFF), Sensient Technologies, Givaudan, Mane SA, Takasago International, DSM-Firmenich, Symrise AG, Afriplex (Pty) Ltd, Kerry Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Food Flavor and Enhancer Market Evolving Landscape
Digital formulation platforms and precision fermentation are compressing development cycles for natural flavor alternatives, while regulatory pressure on sodium and synthetic additives redirects R&D investment toward clean-label systems.
Precision fermentation for bio-identical flavor molecules is automating the production of volatile aromatic compounds previously extracted from scarce botanical sources. Mid-sized dairy and beverage manufacturers in the Western Cape are adopting these inputs at pilot scale. This technology is automating quality consistency in natural flavor supply chains that previously suffered from agricultural harvest variation.
South Africa's Department of Health amendments to sodium reduction targets under the Foodstuffs, Cosmetics and Disinfectants Act are mandating reformulation timelines that compress product development schedules. Manufacturers must now validate taste-equivalent reduced-salt formulations within 18-month windows. Snack and processed meat categories face the steepest compliance curves, driving co-development partnerships with technical service laboratories.
Direct technical service relationships are displacing traditional distributor-mediated flavor procurement in Gauteng's beverage corridor. Large-scale manufacturers now contract Johannesburg-based technical centers for bespoke formulation support rather than purchasing standard catalogs. This pattern concentrates in carbonated soft drink and flavored water segments where rapid flavor rotation demands responsive customization.
South Africa Food Flavor and Enhancer Market Segmentation
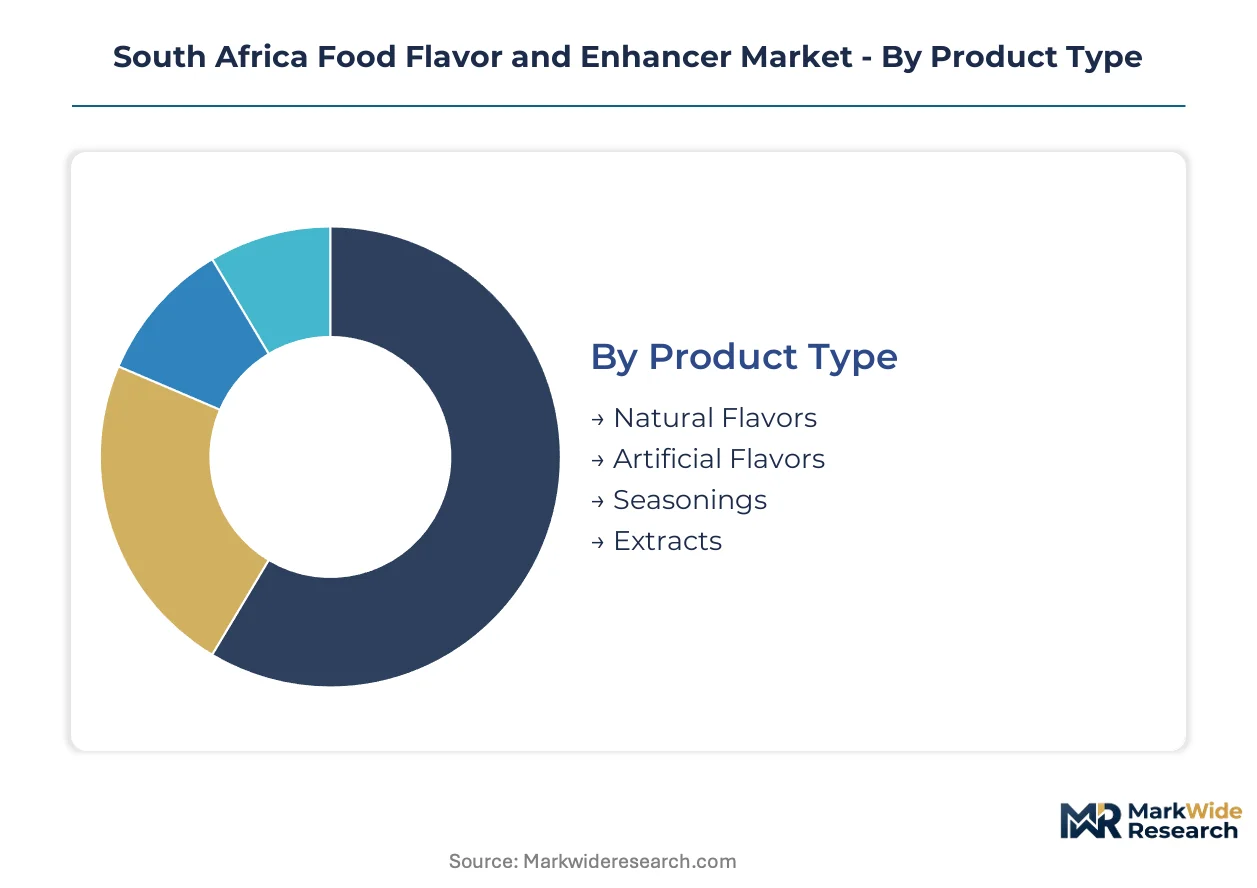
Flavor and enhancer procurement in South Africa diverges sharply between standardized commodity inputs and tailored formulation services. Understanding where each segment sits on this spectrum reveals margin concentration and technical differentiation strategies across Gauteng's industrial corridor and the Western Cape.
Product Type:
Customization intensity spans from fully synthetic standardization to botanical extraction requiring harvest-to-bottle traceability.
- Natural Flavors:Volatile aromatic compounds and oleoresins extracted from indigenous rooibos, buchu, and imported vanilla and citrus sources. Demand concentrates in premium beverage lines manufactured in Stellenbosch and Paarl, where clean-label positioning commands shelf-space premiums at Woolworths and Pick n Pay.
- Artificial Flavors:Chemically synthesized esters, aldehydes, and ketones delivering consistent sensory profiles at unit costs 60-80% below natural equivalents. Mass-market snack producers in Johannesburg's industrial corridor standardize procurement on these inputs to maintain price competitiveness in township retail.
- Seasonings:Pre-blended salt-spice-herb matrices for ready-meal and processed meat applications.
- Extracts:Concentrated botanical preparations including yeast-derived nucleotides for umami enhancement in sodium-reduced formulations.
Most installed capacity flows through Artificial Flavors. Expansion is steepest in Natural Flavors.
End User:
Volume scale inversely correlates with formulation sophistication across South Africa's customer base.
- Food Processing:Large-scale thermal processing operations producing canned goods, frozen meals, and shelf-stable proteins. Procurement concentrates in Germiston and Pretoria industrial parks, where sodium reduction mandates under the Foodstuffs, Cosmetics and Disinfectants Act are forcing yeast extract adoption at pilot scale.
- Beverage Manufacturers:Carbonated soft drink, flavored water, and dairy beverage producers. Technical service relationships with Johannesburg formulation centers are displacing catalog purchasing as flavor rotation cycles compress to under 12 months.
- Bakeries:Industrial and artisanal bread, pastry, and biscuit operations.
- Restaurants:Chain and independent food service operations sourcing bulk seasonings and finishing flavors.
Food Processing absorbs the highest absolute tonnage. Beverage Manufacturers are gaining share fastest.
Application:
Regulatory pressure and thermal processing intensity determine enhancer selection across food categories.
- Snacks:Extruded and fried products where Maillard reaction products and yeast extracts restore flavor intensity lost to sodium reduction. Manufacturers in the Western Cape are trialing encapsulated salt systems to manage temporal release in extended-shelf-life packaging.
- Dairy Products:Yogurt, cheese, and flavored milk applications requiring heat-stable flavor systems. Precision fermentation inputs for bio-identical vanillin are entering pilot production for premium ice cream lines.
- Sauces:Table and cooking sauces demanding balanced umami-sweet-acid profiles.
- Confectionery:Chocolate, candy, and gum applications requiring fat-compatible flavor delivery.
Snacks dominate current enhancer consumption. Dairy Products show the steepest clean-label conversion trajectory.
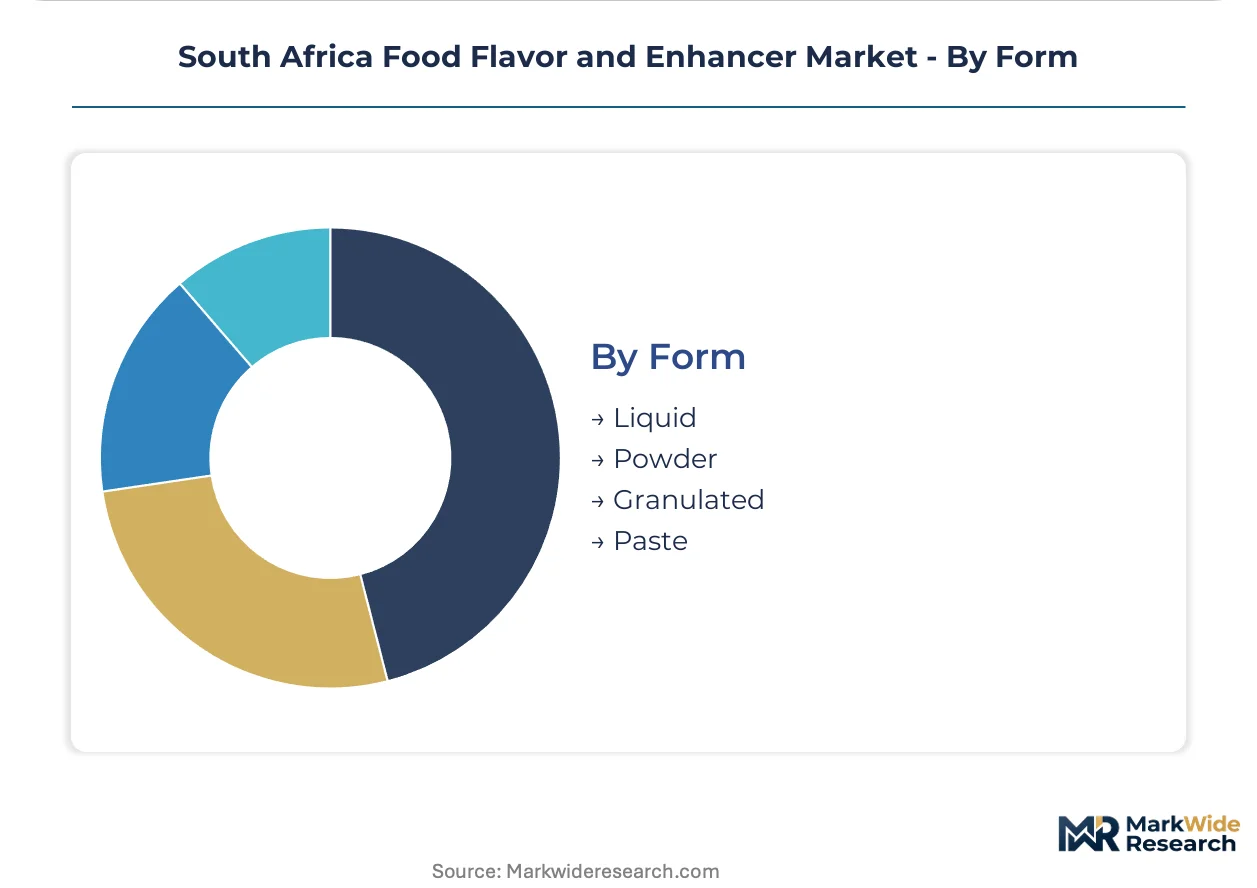
Form:
Manufacturing line configuration and shelf-life requirements lock in format selection.
- Liquid:Concentrated aqueous or solvent-based solutions metered directly into beverage and sauce production lines. Preferred by Coca-Cola Beverages South Africa and Pioneer Foods operations in Johannesburg for rapid flavor rotation and minimal handling.
- Powder:Spray-dried or plated flavors for dry seasoning blends and bakery premixes. Dominates procurement from Tiger Brands and RCL Foods facilities where pneumatic conveying systems integrate with existing ingredient handling infrastructure.
- Granulated:Free-flowing crystals for tabletop and industrial seasoning.
- Paste:High-viscosity concentrates for meat marinades and concentrated sauce bases.
Powder formats command the largest installed base. Liquid concentrates are climbing the fastest as beverage capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johannesburg's industrial corridor anchors South Africa's flavor procurement, with Gauteng and Western Cape manufacturing clusters driving divergent sourcing patterns across the national market.
Gauteng
Beverage and snack manufacturers in Germiston and Pretoria industrial parks are expanding bulk purchasing of yeast extract-based umami systems. The Department of Health's sodium reduction mandates under the Foodstuffs, Cosmetics and Disinfectants Act are forcing reformulation partnerships with technical service laboratories. Johannesburg's formulation centers are displacing catalog purchasing through direct technical service relationships for carbonated soft drink producers.
Western Cape
Stellenbosch and Paarl premium beverage lines command shelf-space premiums at Woolworths and Pick n Pay through clean-label positioning. The South African Bureau of Standards mandates label compliance for flavor declarations that determine market access for imported additive packages. Precision fermentation inputs for bio-identical vanillin are entering pilot production for ice cream manufacturers clustered around Cape Town's dairy processing infrastructure.
KwaZulu-Natal
Processed meat and ready-meal facilities in Durban's harbor industrial zone are trialing encapsulated salt systems for extended-shelf-life packaging. Department of Agriculture biosecurity protocols for botanical raw material imports create lead time volatility for seasoning blend manufacturers. The province's sugar processing heritage is driving demand for natural flavor masking systems in reduced-sugar confectionery applications.
Eastern Cape
Independent grocers in Port Elizabeth and surrounding townships represent unserved demand for affordable clean-label seasoning sachets. Pending amendments to South African Bureau of Standards labeling rules may permit locally sourced certifications that differentiate premium portfolios. The region's citrus cultivation base is supplying extraction feedstock for regional flavor houses serving export-oriented organic brands.
Limpopo and Mpumalanga
Rural retail penetration remains underdeveloped for mass-market snack seasoning distribution networks. The Department of Health regulations on sodium reduction are accelerating adoption of potassium chloride blends among emerging processed food entrepreneurs. Agricultural processing cooperatives in these provinces are exploring indigenous botanical commercialization for buchu and rooibos extraction capabilities.
South Africa Food Flavor and Enhancer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue indigenous botanical specialization and precision fermentation capabilities. The market structures around three distinct tiers: multinational technical service providers, regional natural extract specialists, and local commodity seasoning blenders. Strategic differentiation concentrates on formulation partnerships versus catalog supply, clean-label certification speed, and sodium-reduction technical support. Dominant competitive moves include technical center establishment for direct manufacturer relationships and backward integration into indigenous raw material sourcing.
Within the multinational technical service tier, Givaudan leverages its Johannesburg technical center to anchor regional formulation services, while Sensient Technologies competes through specialized natural color-flavor combinations. Afriplex (Pty) Ltd occupies a distinctive position by sourcing indigenous botanicals for premium extract lines, exemplifying the emerging archetype of local natural specialists. These three players represent the competitive spectrum from global technical service depth to indigenous supply chain control.
| Leading Market Players |
|---|
| International Flavors & Fragrances (IFF) |
| Sensient Technologies |
| Givaudan |
| Mane SA |
| Takasago International |
| DSM-Firmenich |
| Symrise AG |
| Afriplex (Pty) Ltd |
| Kerry Group |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap flavor houses in South Africa's Western Cape exercise pricing discipline through captive cultivation of rooibos and buchu, insulating premium extract lines from commodity volatility while forcing multinational competitors to absorb margin compression on standard catalog offerings.
Pricing Analysis
Input-cost pass-through from botanical harvest variation and biosecurity clearance delays anchors pricing volatility in natural flavor tiers. Three-tier pricing structure across premium certified-organic, standard natural, and economy synthetic levels separates Woolworths shelf-space contenders from township retail suppliers. Pricing pressure stems from yeast extract substitution mandates under Department of Health sodium targets, squeezing mass-market seasoning margins. Mass-market snack producers in Johannesburg's industrial corridor exhibit highest price sensitivity, while Stellenbosch premium beverage lines accept 3-5x unit premiums for indigenous botanical provenance.
Supply Chain Analysis
Reverse-logistics flows for expired or non-conforming botanical batches feed secondary extraction streams and agricultural composting cooperatives, reducing raw material waste rates for Western Cape flavor houses. Supply concentrates in Madagascar for vanilla, India for oleoresins, and domestic Western Cape for rooibos and buchu. Raw material dependencies rest on citrus peel, yeast biomass, and indigenous botanical biomass. Single-source vulnerability for imported vanilla and citrus extracts creates lead time volatility under Department of Agriculture biosecurity protocols. Distribution runs through Johannesburg technical centers for direct manufacturer relationships, displacing traditional distributor networks in Gauteng's beverage corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory sodium reduction mandates force perpetual reformulation cycles, embedding flavor suppliers into manufacturer R&D workflows across South Africa's processed food sector.
For Market Incumbents: Anchor technical service relationships through Johannesburg formulation centers to defend against precision fermentation entrants displacing botanical extraction. Deepen backward integration into Western Cape rooibos and buchu cultivation to secure clean-label supply and margin control. Accelerate South African Bureau of Standards certification pipelines to outpace regulatory label claim amendments. For New Entrants and Emerging Players: The Foodstuffs, Cosmetics and Disinfectants Act amendments in South Africa open a window for indigenous botanical specialists to claim "locally sourced" certifications before incumbent reformulation cycles conclude. Target underpenetrated rural retail in Limpopo and Mpumalanga with affordable clean-label seasoning sachets. Pursue co-development partnerships with emerging processed food entrepreneurs in sodium-reduced meat applications. For Investors and Strategic Acquirers: Valuations sit cheapest among regional natural extract specialists with indigenous supply chain control but limited technical service depth. Five-to-ten-year viability hinges on regulatory tailwinds for clean-label claims persisting through sodium reduction enforcement phases. Monitor South African Bureau of Standards labeling rule amendments as the signal for premium portfolio repricing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indigenous Cultivation | Captive rooibos and buchu supply secures Western Cape premium extract margins against import volatility. |
| Technical Center Establishment | Johannesburg formulation partnerships displace catalog purchasing among Coca-Cola Beverages South Africa and Pioneer Foods. |
| Precision Fermentation Pilot Scale-Up | Bio-identical vanillin production reduces dependency on Madagascar vanilla harvest variation for dairy clients. |
| Encapsulation Technology Deployment | Controlled-release salt systems enable Durban processed meat manufacturers to meet extended-shelf-life requirements. |
| Rural Distribution Channel Expansion | Independent grocer networks in Limpopo and Mpumalanga unlock mass-market clean-label seasoning penetration. |
Research Methodology
Bottom-up beverage and snack manufacturer modeling reconciled against top-down botanical import tracking forms the analytical core of this study. Primary interviews with flavor chemists, procurement leads at Tiger Brands and RCL Foods, technical service directors at Johannesburg formulation centers, and Department of Health regulatory affairs officers combined with secondary validation from South African Bureau of Standards filing records, customs import data, and Foodstuffs, Cosmetics and Disinfectants Act amendment drafts. Triangulation between manufacturer demand signals and raw material supply flows anchors volume estimates.
Input-output matrix framing maps flavor and enhancer consumption across product type, end user, application, and form dimensions over the projection horizon. Segmentation modeling captures natural versus artificial flavor splits, beverage versus food processing demand patterns, and powder versus liquid format preferences. CAGRs derive from slope analysis of procurement budget trajectories and regulatory compliance timeline compression. Industry-specific forecast inputs include Department of Health sodium reduction phase-in schedules and precision fermentation pilot production announcements from Western Cape dairy processors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under biosecurity protocol disruptions or accelerated synthetic additive bans. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and manufacturer reformulation capacity constraints. Practitioners should monitor South African Bureau of Standards labeling rule amendments and Department of Agriculture import clearance timelines for early signals of supply chain stress or competitive repositioning opportunities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Canada Food Flavor and Enhancer Market
Food Enhancers and Additives
Brazzein Market
Food Enhancers and Additives
Germany Water Enhancer Market
Food Enhancers and Additives
North America Feed Palatability Enhancers Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
Mexico Water Enhancer Market
Food Enhancers and Additives
United States Water Enhancer Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
North America Water Enhancer Market
Food Enhancers and Additives
Food Thickening Agents Market