
 Middle East and Africa Glassware Market | 2026-2036
Middle East and Africa Glassware Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Glassware Market Foresight
Modular drinkware bundling is expanding across hotel and restaurant supply contracts, replacing single-item purchasing with coordinated tableware sets. Emirates Glass LLC leverages its Jebel Ali manufacturing base to anchor regional distribution networks. Saudi Arabian Glass Company dominates domestic production capacity through its Riyadh and Jeddah facilities. Frigoglass Jebel Ali FZE sustains technical leadership in tempered and heat-resistant glass configurations for commercial foodservice.
Middle East and Africa glassware encompasses vessels and containers fabricated from soda-lime, borosilicate, or crystal compositions, formed through blow-molding, pressing, or hand-blowing techniques, serving foodservice, hospitality, and residential consumption with thermal and chemical resistance specifications. Soda-lime glass occupies the volume base due to cost efficiency in mass-produced tableware and storage containers, while borosilicate segments command premium positioning in bakeware and specialty drinkware for temperature shock resistance. Crystal material categories concentrate margin pools in luxury hotel and ceremonial applications, though their growth remains constrained by price sensitivity across mainstream retail channels.
SFDA material safety protocols in Saudi Arabia and UAE product conformity schemes administered by the Emirates Authority for Standardization and Metrology shape import clearance and local manufacturing compliance costs for glassware producers. Egypt's EOS quality markings and South Africa's NRCS safety requirements add layer complexity for pan-regional suppliers seeking multi-country market access. Stakeholders must monitor evolving mandatory certification timelines and align production specifications with the strictest jurisdiction in their target footprint.
Market Dynamics
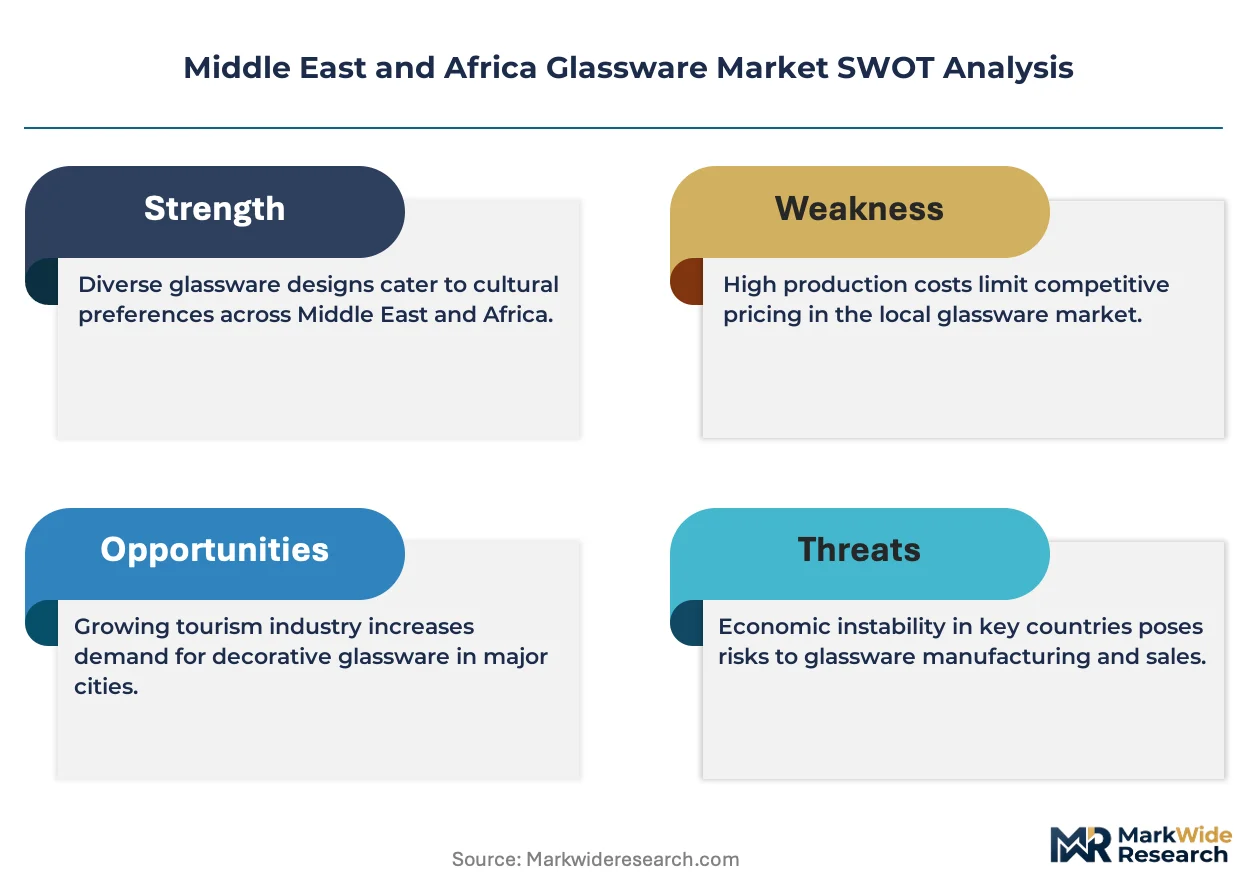
Hospitality procurement consolidation across the Gulf Cooperation Council is compressing supplier margins while elevating technical compliance burdens. SFDA food-contact protocols and UAE conformity mandates now function as market entry filters rather than post-hoc quality checks.
Growth Catalysts
- SFDA Material Safety Standards:Saudi Arabia's tightening food-contact regulations are eliminating substandard imports and creating protected demand corridors for certified domestic and regional producers.
- Luxury Hospitality Expansion:Premium hotel developments in Dubai, Riyadh, and Jeddah are specifying coordinated drinkware sets rather than commodity glassware, pulling volume toward higher-margin borosilicate and crystal categories.
- Modular Tableware Contracts:Foodservice operators are bundling glassware procurement with ceramics and flatware, reducing supplier count and locking in multi-year volume commitments.
Market Restraints
- Natural Gas Price Volatility:Soda-lime glass production depends on consistent energy input costs, and GCC electricity pricing fluctuations compress furnace operating margins unpredictably.
- Import Dependency for Borosilicate Feedstock:Regional manufacturers lack captive boron sourcing, exposing specialty glassware producers to supply concentration risks from Turkish and Chinese chemical suppliers.
- Technical Limitation in Thin-Wall Tempering:Local heat-treatment capabilities max out at 4mm wall thickness, excluding regional producers from ultra-lightweight stemware segments dominated by European imports.
Strategic Opportunities
- Underpenetrated East African Foodservice:Kenya and Ethiopia's expanding airline catering and conference hospitality sectors lack established glassware supply relationships, creating first-mover positioning for GCC-based distributors.
- Emirates Authority for Standardization and Metrology Incentives:UAE product conformity certification subsidies reduce compliance cost burdens for manufacturers establishing Jebel Ali production bases.
- Digital Spec-to-Fulfillment Platforms:Hospitality procurement teams are migrating to B2B marketplaces that aggregate supplier catalogs, compressing traditional distributor markups and rewarding direct manufacturer relationships.
Industry Challenges
- Artisanal Glassblowing Skill Attrition:Hand-blown crystal and decorative segments face workforce aging, with master craftsman training programs failing to replace retiring Egyptian and Syrian expatriate technicians in UAE and Saudi facilities.
- Multi-Jurisdiction Certification Timelines:Pan-regional suppliers must sequence SFDA, EOS, and NRCS approvals sequentially rather than in parallel, extending product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Glassware Market |
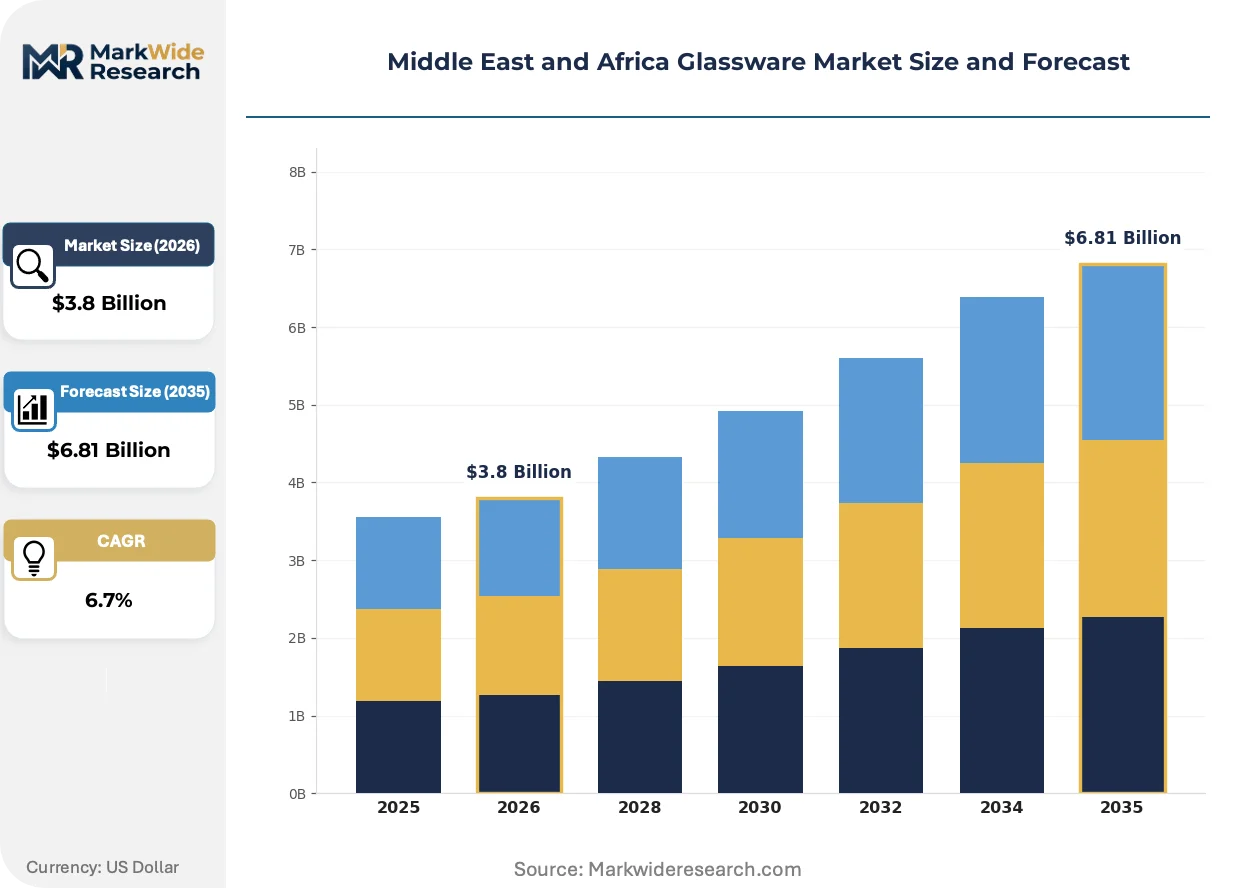
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tableware, Drinkware, Bakeware, Storage Containers Material: Ceramic, Borosilicate, Soda-Lime, Crystal End User: Households, Restaurants, Hotels, Retailers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Department Stores |
| Companies Covered | Frigoglass Jebel Ali FZE, Emirates Glass LLC, Saudi Arabian Glass Company, Jeddah Glass Company, Misr Glass Manufacturing Company, Gulf Glass Industries, O-I Jebel Ali, Kandil Glass, National Company for Glass Industries, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Glassware Market Shifts & Advancements
Digital specification tools and automated quality verification are compressing traditional procurement cycles across hospitality and foodservice channels. Material science advances in thermal shock resistance are opening application boundaries previously closed to regional suppliers.
Advanced tempering automation is decentralizing production economics for heat-resistant glassware. Mid-scale manufacturers in Sharjah and Riyadh are adopting continuous thermal processing lines previously exclusive to European capital-intensive facilities. This technology diffusion is enabling regional producers to bid competitively on commercial bakeware and oven-to-table contracts previously ceded to imports.
SFDA's 2024 food-contact material notification requirements are restructuring import clearance workflows. Pre-shipment laboratory testing at accredited GCC facilities is becoming mandatory, adding documentation layers but reducing port-of-entry rejection rates. Egyptian and South African suppliers are establishing Riyadh-based certification liaisons to compress approval timelines.
Spec-driven procurement through digital platforms is fragmentizing traditional distributor relationships. Hotel procurement teams in Dubai and Jeddah are bypassing layered supply chains, issuing RFQs directly to manufacturers via specialized B2B portals. This channel compression is most visible in the four- and five-star hospitality segment, where technical specification transparency outweighs distributor service bundling.
Middle East and Africa Glassware Market Segmentation
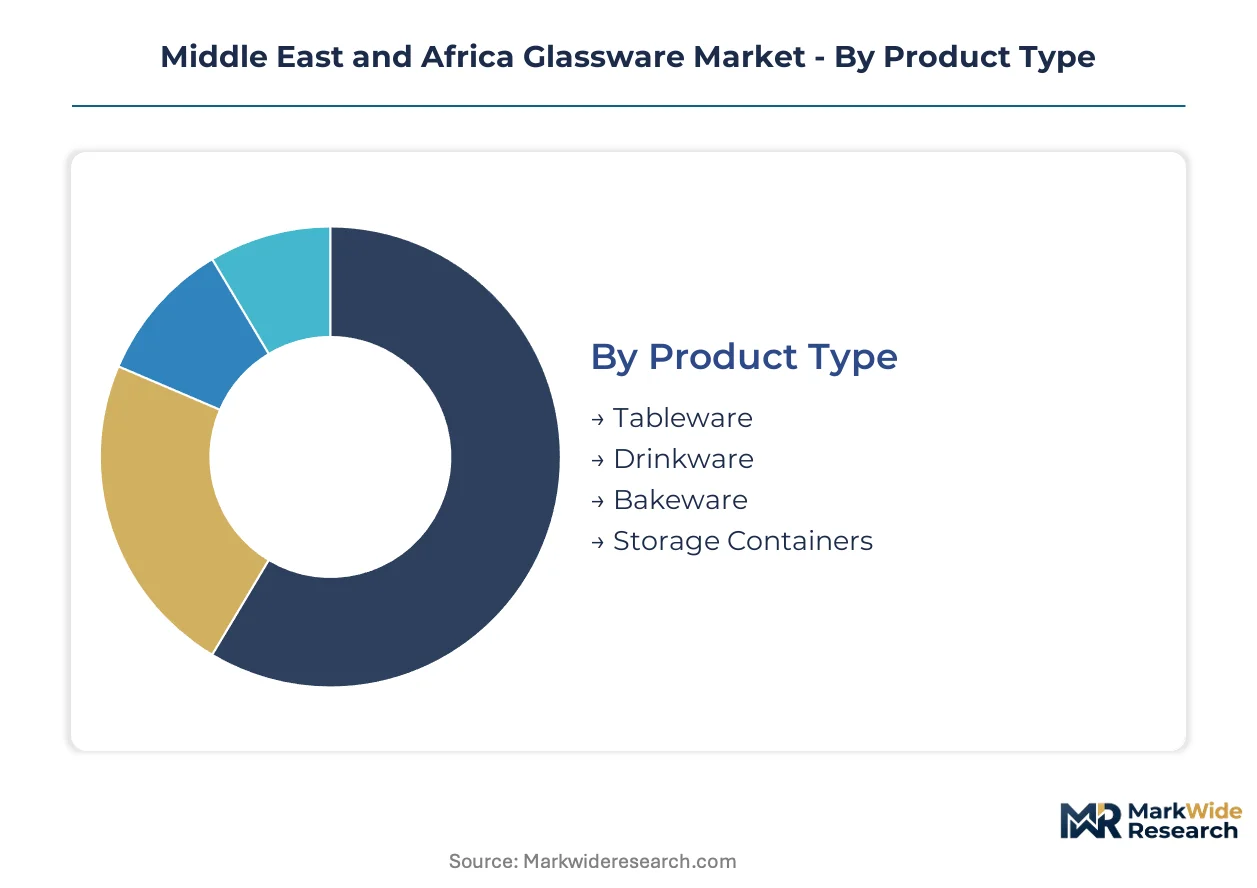
Glassware procurement in the Middle East and Africa fragments across material specifications, thermal performance requirements, and channel economics. Procurement officers in Dubai and Riyadh hospitality clusters weight segments differently than mass-market retailers in Cairo or Lagos.
Product Type:
Integration depth varies sharply: drinkware and tableware function as standalone purchase decisions, while bakeware and storage containers embed within broader kitchenware procurement bundles.
- Tableware:Comprises plates, serving dishes, and decorative centerpieces in soda-lime and crystal compositions. Saudi luxury hotel developments in Riyadh and Jeddah specify coordinated tableware sets with matching drinkware, pulling volume toward premium borosilicate blends that withstand thermal cycling from kitchen to table.
- Drinkware:Encompasses stemware, tumblers, and beverage service vessels across all material grades. Dubai's fine-dining sector concentrates demand here, with procurement teams specifying 3-5mm wall thickness for durability against commercial dishwasher cycles.
- Bakeware:Oven-to-table dishes and baking trays requiring thermal shock resistance. Egyptian and South African household segments drive volume through retail channels.
- Storage Containers:Food-grade jars and canisters with sealing mechanisms. Mass-market penetration concentrates in Nigerian and Kenyan supermarket chains.
Tableware leads volumes today; drinkware is gaining share fastest.
Material:
Cost tier stratification dominates supplier positioning, with furnace economics and feedstock sourcing determining which materials capture margin versus volume.
- Soda-Lime:Standard silicate glass with sodium and calcium oxide additives, formed through automated blow-molding. Emirates Glass LLC and Saudi Arabian Glass Company anchor regional production here, serving mass-market tableware and storage demand across GCC retail networks.
- Borosilicate:Thermal shock-resistant glass with boron trioxide content enabling direct flame and oven exposure. Frigoglass Jebel Ali FZE specializes here, capturing commercial bakeware contracts from Dubai hotel procurement consortia.
- Crystal:Lead or lead-free high-refractive glass for luxury ceremonial and hospitality applications. Syrian and Egyptian master craftsmen supply hand-blown pieces to UAE and Saudi luxury segments.
- Ceramic:Non-glass alternative in glazed porcelain and stoneware, competing at tableware price points. South African and Moroccan producers dominate this adjacent category.
Soda-lime commands volume dominance; borosilicate shows the steepest expansion trajectory.
End User:
Customer type determines specification stringency, with commercial hospitality imposing thermal performance and certification requirements absent in residential procurement.
- Hotels:Four- and five-star properties across Dubai, Riyadh, and Jeddah mandate coordinated glassware sets with documented SFDA or Emirates Authority for Standardization and Metrology compliance. Procurement consolidation here favors regional manufacturers with captive certification capabilities.
- Restaurants:Fine-dining and casual foodservice operators prioritizing dishwasher durability and replacement cost predictability. Kenyan and Ethiopian airline catering segments represent emerging demand pockets.
- Households:Residential consumers purchasing through retail channels, price-sensitive with limited specification requirements. Nigerian and Egyptian mass markets concentrate here.
- Retailers:Supermarket and department store private-label programs sourcing commodity glassware. South African chains extend procurement reach into neighboring SADC markets.
Households anchor volume today; hotels are climbing the fastest.
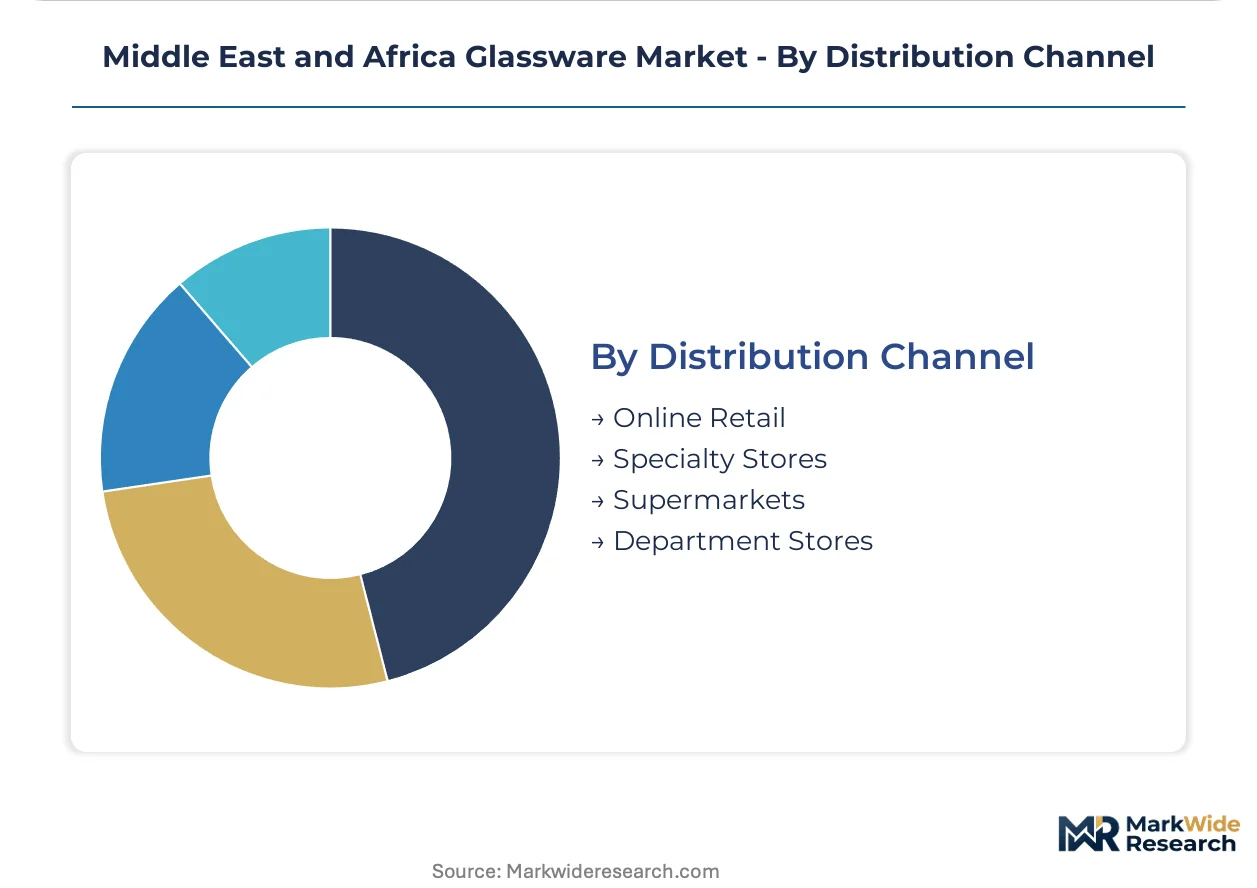
Distribution Channel:
Channel concentration shapes margin capture, with direct manufacturer relationships compressing traditional distributor economics in hospitality segments.
- Specialty Stores:Dedicated kitchenware and home goods retailers offering curated glassware selections. Dubai's design districts and Riyadh's upscale retail clusters concentrate premium inventory here.
- Supermarkets:Mass-market retail chains with high-volume, low-margin tableware and storage container sales. Shoprite and Spar networks across South Africa and Nigeria dominate.
- Online Retail:B2B procurement portals and B2C marketplaces fragmenting traditional distribution. Jumia and noon.com aggregate regional glassware catalogs for hospitality and residential buyers.
- Department Stores:Full-line retailers with dedicated housewares sections, declining share as specialty and online channels capture specification-driven buyers.
Supermarkets retain volume leadership; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glassware manufacturing in the Middle East and Africa traces its modern foundation to Egyptian artisanal workshops that supplied ceremonial vessels to Levantine markets, with industrial-scale production emerging later through state-backed ventures in Saudi Arabia and the UAE during the 1970s oil boom.
United Arab Emirates
Dubai's hospitality procurement consortia and Abu Dhabi's luxury hotel developments drive specification-grade demand for borosilicate and crystal tableware. The Emirates Authority for Standardization and Metrology administers product conformity schemes that filter import clearance workflows. Jebel Ali industrial zones anchor regional distribution networks, with manufacturers leveraging the port's free zone status for pan-GCC re-export.
Saudi Arabia
SFDA food-contact material standards are eliminating substandard imports and creating protected corridors for certified domestic producers. Riyadh and Jeddah facilities dominate domestic production capacity, serving both local hospitality procurement and neighboring Gulf markets. The kingdom's Vision 2030 hospitality expansion is pulling volume toward coordinated premium tableware sets.
Egypt
Misr Glass Manufacturing Company and artisanal workshops in Cairo and Alexandria sustain regional supply of hand-blown crystal and decorative segments. EOS quality markings add compliance complexity for exporters seeking multi-country market access. The Nile Delta corridor retains skilled glassblowing craft traditions despite workforce aging challenges.
South Africa
NRCS safety requirements govern import and local manufacturing compliance for foodservice and residential glassware. Shoprite and Spar retail networks extend procurement reach into neighboring SADC markets. Gauteng and Western Cape provinces concentrate distribution infrastructure serving sub-Saharan demand.
Kenya
Expanding airline catering and conference hospitality sectors in Nairobi lack established glassware supply relationships, creating positioning opportunities for GCC-based distributors. Kenyan supermarket chains are developing private-label programs for mass-market tableware. Mombasa port facilities enable regional re-export into East African Community markets.
Middle East and Africa Glassware Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material specialization and certification capability, with borosilicate and crystal specialists commanding pricing power over soda-lime mass producers. The vendor base organizes into three archetypes: integrated manufacturers with captive furnace operations, specialist tempering houses focused on heat-resistant configurations, and artisanal ateliers supplying hand-blown ceremonial pieces. Dominant competitive moves include backward integration into raw material sourcing and strategic partnerships with hospitality procurement platforms.
Among UAE-based fabricators, Emirates Glass LLC and Frigoglass Jebel Ali FZE exemplify the integrated manufacturing archetype, while Saudi Arabian Glass Company anchors the scale-driven domestic production tier. These three entities occupy positions that reflect the region's bifurcation between mass-market soda-lime supply and premium thermal-resistant specialties.
| Leading Market Players |
|---|
| Frigoglass Jebel Ali FZE |
| Emirates Glass LLC |
| Saudi Arabian Glass Company |
| Jeddah Glass Company |
| Misr Glass Manufacturing Company |
| Gulf Glass Industries |
| O-I Jebel Ali |
| Kandil Glass |
| National Company for Glass Industries |
| Others |
Supply & Pricing Matrix
Continuous tempering line adoption across Sharjah and Riyadh manufacturing clusters compresses unit economics for heat-resistant glassware while redistributing furnace capacity toward mid-scale producers previously excluded from commercial bakeware contracts. This equipment transition simultaneously lowers marginal production costs and fragments supply concentration away from Jebel Ali-dominant incumbents.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts, with SFDA certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from hospitality procurement consolidation across Dubai and Riyadh, where bundled tableware contracts compress supplier margins. Mass-market retailers in Cairo and Lagos exhibit highest price sensitivity, while five-star hotel procurement teams prioritize thermal performance specifications over unit cost.
Supply Chain Analysis
Regional distribution centers in Jebel Ali, Riyadh, and Jeddah anchor hub-and-spoke fulfillment patterns serving GCC hospitality clusters. Manufacturing concentrates in the UAE, Saudi Arabia, and Egypt, with borosilicate feedstock drawing from Turkish and Chinese chemical suppliers. Single-source vulnerability for boron trioxide inputs creates exposure to supply disruption. Distribution runs through manufacturer-direct relationships in premium hospitality segments and layered wholesale networks in mass-market retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Dubai and Riyadh hospitality procurement shifts toward coordinated premium tableware sets with documented thermal performance specifications.
For Market Incumbents: Extend certification capabilities across SFDA, EOS, and NRCS jurisdictions to compress multi-approval timelines that currently delay product launches. Add captive tempering capacity in Riyadh to defend against Sharjah-based mid-scale competitors adopting continuous thermal processing lines. Channel control through direct B2B platform relationships offsets distributor margin compression. For New Entrants and Emerging Players: Enter via Kenyan airline catering and conference hospitality segments in Nairobi, where established supply relationships remain underdeveloped. Target Ethiopian foodservice operators through Mombasa port re-export arrangements. A GCC-based certification liaison office accelerates SFDA approval timelines for Egyptian and South African manufacturing origins. For Investors and Strategic Acquirers: Valuations sit cheapest among borosilicate specialists with captive tempering automation and Emirates Authority for Standardization and Metrology conformity infrastructure. Long-term viability favors integrated manufacturers with backward integration into soda-lime furnace operations and upstream chemical sourcing relationships. Watch for SFDA notification requirement enforcement intensity as inflection signal for import clearance cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Investment | Pre-shipment laboratory testing at accredited GCC facilities reduces port-of-entry rejection rates for Riyadh-bound shipments. |
| Continuous Tempering Line Adoption | Mid-scale Sharjah manufacturers now bid competitively on Dubai hotel procurement contracts previously ceded to European imports. |
| Direct B2B Platform Relationships | Procurement teams at Jeddah five-star properties bypass layered distributors via specialized hospitality marketplaces. |
| East African Distribution Partnership | Mombasa port facilities enable GCC-based suppliers to reach Kenyan and Ethiopian airline catering segments. |
| Artisanal Craftsmanship Preservation | Master glassblower training programs in Cairo and Alexandria address workforce aging in hand-blown crystal segments. |
Research Methodology
Bottom-up hospitality procurement modeling reconciled against top-down furnace capacity tracking forms the analytical core of this study. Primary interviews with hotel procurement managers, foodservice supply directors, glassware manufacturing plant managers, and Emirates Authority for Standardization and Metrology certification specialists combined with secondary validation from customs trade records, SFDA notification filings, and hospitality development pipeline databases. Triangulation between demand-side specification tracking and supply-side production capacity verification ensures cross-dimensional consistency.
Historical trendline analysis of soda-lime and borosilicate furnace operating rates across the UAE, Saudi Arabia, and Egypt established baseline capacity utilization patterns. The forecast framework models material type, end-user segment, thermal performance tier, and distribution channel dynamics across the projection horizon. CAGRs derive from segmented demand elasticity coefficients and regulatory compliance cost trajectories, with particular weighting applied to Vision 2030 hospitality expansion timelines and SFDA enforcement intensity assumptions.
Inputs from hospitality procurement consortia and manufacturing plant operators were available through the study window; gaps in artisanal workshop production data and informal channel volume estimates introduce uncertainty bands around hand-blown crystal segment projections. Forecasts reflect documented assumptions regarding regulatory timeline adherence and energy pricing stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Global Flat Glass Market
Glass
Glass Mason Jars Market
Glass
East Africa Flat Glass Market
Glass
Cellular Glass Market
Glass
Global Energy Efficient Glass Market
Glass
Impact Resistant Glass Market
Glass
Europe Sapphire Glass Market
Glass
Glass Lens Market
Glass
Flexible Glass Market
Glass
Foam Glass Market
Glass
Dynamic Glazing Market
Glass
Glass Block Market
Glass
China Flat Glass Market
Glass
North America Flat Glass Market
Glass
Ultra Violet Glass Bottles Market
Glass
Glass Mat Market