
 Porous Glass Market | 2026-2036
Porous Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Porous Glass Market Analysis
The split between high-purity nano-pore grades and standard construction-grade macro-pore material is realigning procurement patterns across buyer categories. Schott leverages its German manufacturing base to dominate premium healthcare and laboratory segments. REFAGLASS competes on thermal insulation specialization, anchoring its position in Eastern European construction markets.
Porous glass consists of a sintered silicate matrix with controlled interconnected void structures, typically engineered to porosity ranges between 15% and 85% and pore diameters spanning nanometers to millimeters depending on thermal processing parameters. Its primary commercial purpose centers on selective permeability, thermal insulation, and structural lightweighting across industrial systems. Open-pore configurations capture the dominant margin pool in filtration and catalysis applications, while closed-pore grades sustain volume leadership in building insulation where thermal performance requirements dominate specification sheets. Nano-pore segments occupy the fastest expansion trajectory as semiconductor and pharmaceutical end users tighten purity tolerances.
REACH registration requirements in Europe, FDA device material guidelines in the United States, and China's GB standards for construction materials collectively shape product certification burdens and market access conditions for porous glass suppliers. ECHA substance evaluations force reformulation of certain borosilicate precursors, redirecting R&D spending toward compliant alternative chemistries. Stakeholders must monitor evolving certification fragmentation between ISO 9001, ASTM C857, and CE Mark pathways to avoid specification mismatches in cross-border tendering.
Market Dynamics
REACH substance evaluations are forcing reformulation of borosilicate precursors across European supply chains, redirecting R&D budgets toward compliant alternative chemistries while tightening purity benchmarks for healthcare and semiconductor applications.
Growth Catalysts
- Healthcare filtration expansion:Hospitals and biopharma manufacturers specify nano-pore grades for sterile processing, tightening tolerance requirements that favor premium suppliers with certified cleanroom production.
- REACH compliance premiums:ECHA registration mandates create competitive moats for producers with pre-authorized chemistries, squeezing non-compliant regional competitors out of tender processes.
- Semiconductor cleanroom demand:Wafer fabrication facilities in Germany and South Korea specify ultra-high-purity porous glass for chemical handling systems, anchoring volume commitments for specialized grades.
Market Restraints
- Boron raw material volatility:Concentrated Turkish and U.S. boron mining operations expose precursor costs to supply disruptions and export quota fluctuations.
- Sintering energy intensity:Thermal processing requires sustained furnace temperatures exceeding 600°C, locking producers into natural gas-dependent cost structures vulnerable to European energy pricing.
- Ceramic foam substitution:Aluminum oxide and silicon carbide alternatives capture construction insulation specifications where thermal performance tolerances permit lower-cost materials.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO quality mandates and PLI scheme incentives attract contract manufacturing organizations seeking qualified filtration component suppliers.
- Carbon capture membrane integration:Porous glass substrates paired with amine-functionalized coatings enter pilot testing for post-combustion CO2 separation systems.
- Direct-to-laboratory distribution:Research institutions bypass traditional chemical distributors through specialized e-procurement platforms, compressing channel margins and accelerating specification feedback loops.
Industry Challenges
- Specialized furnace engineering talent:Sintering process optimization requires expertise spanning glass chemistry, thermal engineering, and statistical quality control that pools in Germany and Japan.
- Multi-jurisdiction certification timelines:Simultaneous FDA device material reviews, CE Mark conformity assessments, and GB standard testing extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Porous Glass Market |
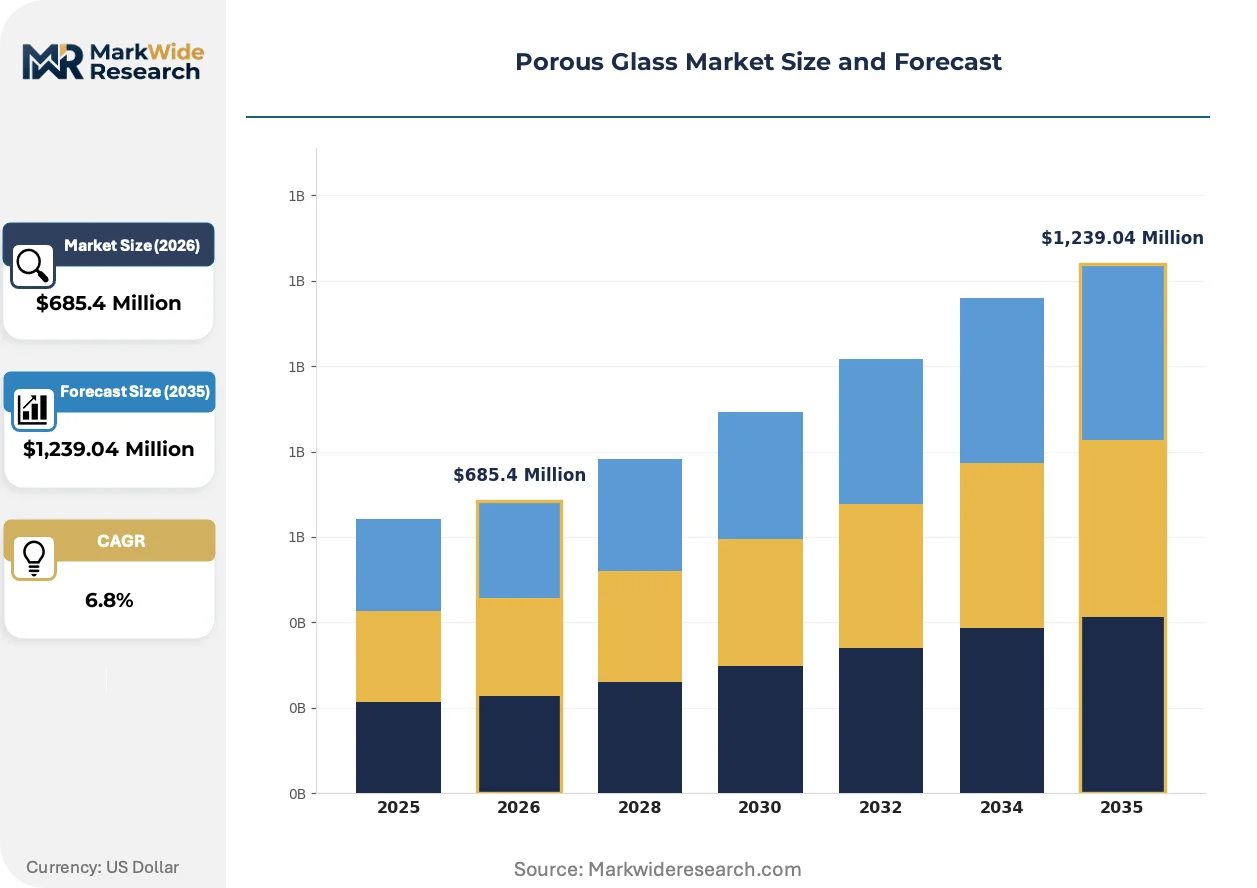
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open-Pore, Closed-Pore, Nano-Pore, Macro-Pore End Use: Construction, Aerospace, Healthcare, Filtration Manufacturing Stage: Raw Material Processing, Shaping, Surface Treatment, Final Machining Certification: ISO 9001, ASTM C857, CE Mark, FDA Compliance |
| Companies Covered | Earthstone, REFAGLASS, Schott, Corning Inc., Zhejiang DEHO, Pittsburgh Corning, JSC Gomelglass, Huichang New Material, GLAPOR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Porous Glass Market Emerging Trajectories
Process intensification and regulatory convergence are compressing product development cycles while elevating material traceability requirements across buyer segments.
Additive manufacturing of porous glass structures is unifying complex geometries previously requiring assembly of multiple sintered components. Aerospace and medical device manufacturers adopt topology-optimized lattice structures for lightweight thermal management. This technology is unifying design and production workflows that previously separated prototyping from scale manufacturing.
EU F-Gas Regulation phase-down schedules are accelerating adoption of porous glass insulation in commercial refrigeration systems as hydrofluorocarbon alternatives face supply constraints. Equipment OEMs in Italy and Poland redesign compressor housings around vacuum-insulated panels. Cold chain logistics operators in the Netherlands retrofit transport containers to maintain compliance with evolving carbon footprint disclosure requirements.
Specification-driven consolidation concentrates procurement authority among centralized technical buying teams at multinational pharmaceutical and semiconductor firms. Regional distributors lose influence as direct vendor relationships and long-term supply agreements replace spot purchasing. Germany's precision manufacturing corridor exhibits the most pronounced shift, with Schott and specialty competitors negotiating multi-year framework contracts with locked volume commitments.
Porous Glass Market Segmentation
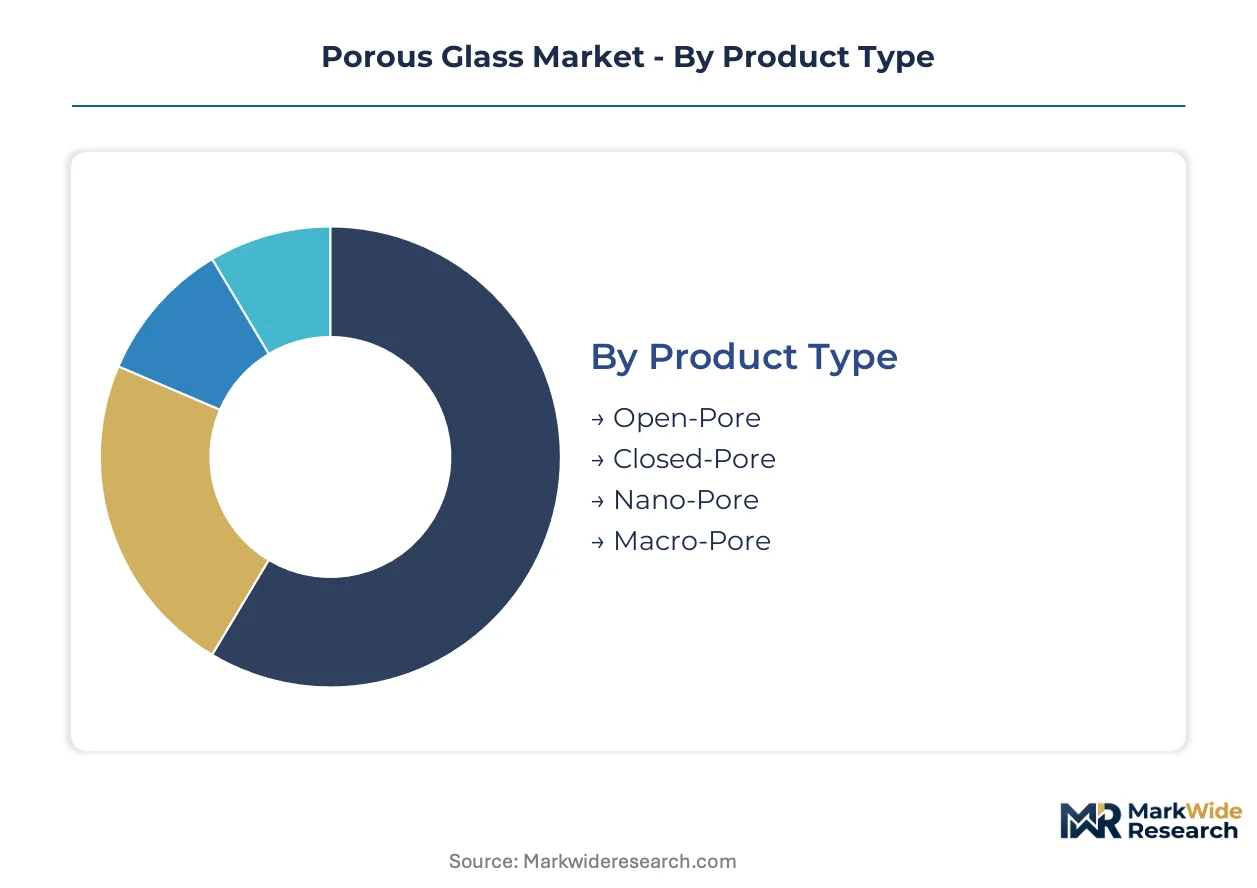
Specification requirements diverge sharply across buyer categories in porous glass. Nano-pore grades command certification premiums in semiconductor and pharmaceutical applications. Construction-grade macro-pore material competes on thermal performance metrics and installed cost.
Product Type:
Pore architecture determines functional performance and manufacturing complexity. Thermal processing parameters lock in structural characteristics that resist post-production modification.
- Nano-Pore:Engineered void structures below 100 nanometers deliver selective permeability for sterile filtration and chemical separation. Wafer fabrication facilities in Germany and South Korea specify these grades for ultra-high-purity chemical handling systems, anchoring volume commitments for certified cleanroom production.
- Open-Pore:Interconnected void networks enable fluid transport and catalytic surface exposure. Biopharma manufacturers in Switzerland and the United States specify open-pore configurations for chromatography columns and bioreactor supports, tightening tolerance requirements that favor premium suppliers with validated production.
- Closed-Pore:Isolated void cells trap gas for thermal insulation without moisture absorption. Building envelope specifications in Poland and the Czech Republic favor closed-pore grades where thermal bridging resistance dominates performance criteria.
- Macro-Pore:Millimeter-scale void structures reduce structural weight in non-load-bearing applications. Lightweight concrete additives in Turkey and Spain absorb volume in construction markets where cost sensitivity limits specification upgrades.
Mature deployment sits with closed-pore grades in European building insulation. Newer deployment is concentrated in nano-pore segments for semiconductor and pharmaceutical end uses.
End Use:
Application environments dictate purity thresholds and mechanical property requirements. Certification burdens scale with patient safety exposure and process criticality.
- Healthcare:Sterile processing applications demand validated bio-compatibility and extractables testing. FDA device material guidelines and EMA quality standards force dual-track certification for suppliers serving transatlantic markets.
- Filtration:Chemical separation and air purification systems specify graded porosity for particle retention efficiency. REACH registration requirements in Europe redirect formulation choices toward pre-authorized borosilicate chemistries.
- Aerospace:Lightweight thermal management structures require topology-optimized lattice geometries. Additive manufacturing adoption unifies design and production workflows for engine components and satellite systems.
- Construction:Thermal insulation and acoustic dampening specifications prioritize installed cost over purity metrics. EU F-Gas Regulation phase-down schedules accelerate porous glass substitution for hydrofluorocarbon insulation in commercial refrigeration.
Volume leadership belongs to construction applications. Steepest expansion trajectory runs through healthcare filtration as hospitals and biopharma manufacturers tighten sterile processing standards.
Manufacturing Stage:
Process control requirements intensify downstream as value accumulates. Energy-intensive thermal operations concentrate in regions with favorable natural gas pricing.
- Surface Treatment:Functionalization coatings enable selective chemical affinity for catalysis and separation membranes. Amine-functionalized layers enter pilot testing for post-combustion carbon capture systems in the Netherlands.
- Shaping:Sintering furnaces operating above 600°C lock in porosity structures through controlled thermal profiles. German and Japanese engineering talent pools dominate process optimization expertise spanning glass chemistry and statistical quality control.
- Raw Material Processing:Boron precursor purification establishes baseline chemistry for downstream consistency. Turkish and U.S. mining concentration exposes supply chains to export quota disruptions.
- Final Machining:Dimensional tolerancing and edge finishing prepare components for assembly integration. Precision grinding requirements concentrate in Germany's manufacturing corridor.
Capital intensity peaks at shaping stage with furnace infrastructure. Surface treatment commands expanding R&D allocation for functional coating development.
Certification:
Regulatory fragmentation extends product launch timelines and elevates compliance spending. Multi-jurisdiction approval strategies separate multinational suppliers from regional competitors.
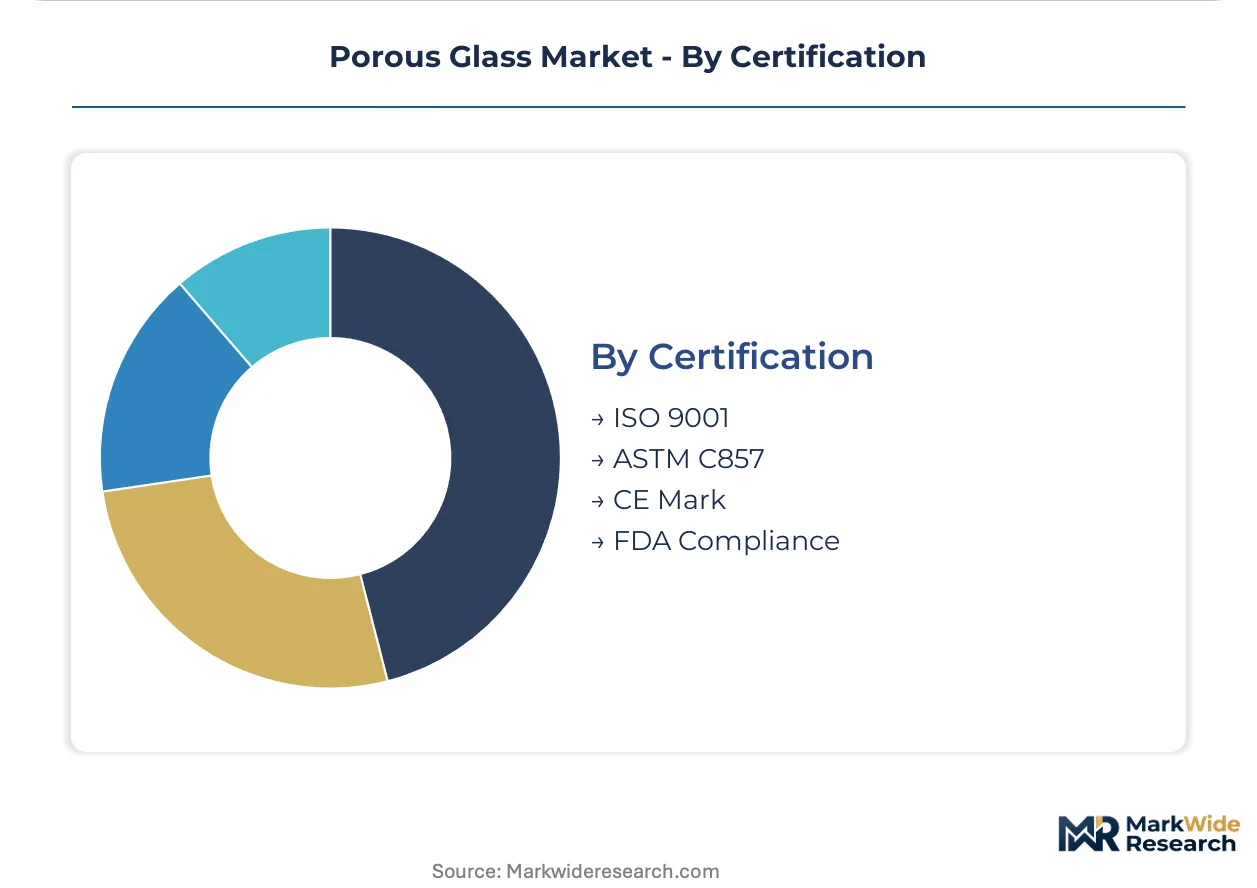
- FDA Compliance:Device material guidelines govern bio-compatibility and sterilization validation for healthcare applications. Pre-market notification pathways extend certification cycles by 12-18 months for novel formulations.
- CE Mark:European conformity assessments cover construction products and medical devices under separate regulatory frameworks. ECHA substance evaluations force reformulation of certain borosilicate precursors.
- ISO 9001:Quality management system certification provides baseline supplier qualification for industrial procurement. Multinational pharmaceutical firms mandate ISO certification as table stakes for vendor qualification.
- ASTM C857:Standard specification for rigid porous glass covers dimensional tolerances and thermal properties. North American construction specifications reference ASTM protocols for material acceptance testing.
Widest geographic recognition attaches to ISO 9001. Most stringent technical requirements flow from FDA compliance for implantable and sterile processing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing corridor concentrates the highest-value porous glass activity, with Schott anchoring production in Mainz and supplier networks radiating through Baden-Württemberg and Bavaria.
Germany
Wafer fabrication facilities in Dresden and Munich specify ultra-high-purity nano-pore grades for chemical handling systems. REACH registration requirements through ECHA create competitive moats for producers with pre-authorized borosilicate chemistries. The Rhine-Main cluster integrates sintering expertise with pharmaceutical cleanroom demand from Frankfurt's biopharma corridor.
United States
Biopharma manufacturers in Massachusetts and North Carolina tighten sterile processing standards for filtration components. FDA device material guidelines extend certification cycles for healthcare-grade porous glass. Corning's New York manufacturing base supplies semiconductor fabrication facilities across the Southwest and Pacific Northwest.
China
Construction-grade macro-pore material absorbs volume in building insulation across the Yangtze River Delta. GB standards for construction materials shape product certification burdens for domestic suppliers. Zhejiang province hosts shaping operations serving both domestic refrigeration OEMs and export markets.
South Korea
Memory and logic chip foundries in Pyeongtaek and Hwaseong drive specification-grade demand for chemical handling systems. The national semiconductor regulator enforces purity tolerances that favor certified cleanroom production. The Gyeonggi-do corridor anchors volume commitments for specialized nano-pore grades.
India
Contract manufacturing organizations in Hyderabad and Ahmedabad seek qualified filtration component suppliers for pharmaceutical exports. CDSCO quality mandates and PLI scheme incentives redirect procurement toward certified producers. The Gujarat pharmaceutical cluster exhibits accelerating specification feedback loops through direct vendor relationships.
Porous Glass Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across distinct value chain positions. Sintering furnace infrastructure concentrates among integrated manufacturers with captive boron precursor supply, while surface treatment specialists license coating technologies without thermal processing assets. Three archetypes dominate: German precision manufacturers with healthcare certification depth, Chinese scale players serving construction insulation, and Eastern European thermal insulation specialists. Competitive moves center on multi-year framework contracts with locked volume commitments and backward integration into boron precursor purification.
Among German-based fabricators, Schott AG and GLAPOR occupy positions anchored in the Rhine-Main industrial corridor, exemplifying the premium-tier archetype through healthcare and laboratory certification depth. REFAGLASS represents the Eastern European specialization vector, with its geographic origin signaling thermal insulation focus. Chinese scale players including Zhejiang DEHO and Huichang New Material sit within the construction-grade volume tier, their corporate structures reflecting limited liability manufacturing entities serving domestic building markets.
| Leading Market Players |
|---|
| Earthstone |
| REFAGLASS |
| Schott |
| Corning Inc. |
| Zhejiang DEHO |
| Pittsburgh Corning |
| JSC Gomelglass |
| Huichang New Material |
| GLAPOR |
| Others |
Supply Flow & Price Mechanics
Boron precursor costs originating in Turkish and U.S. mining operations cascade through three distinct pricing tiers before reaching downstream buyers, with purification intensity and certification depth determining final contract values across healthcare, semiconductor, and construction segments.
Pricing Analysis
Yield-guaranteed uptime clauses anchor premium nano-pore contracts for wafer fabrication facilities, where contamination tolerance failures trigger penalty structures. Pricing stratifies across certified cleanroom production, validated pharmaceutical grades, and standard construction specifications, with REACH-compliant borosilicate chemistries commanding 15-40% premiums over baseline formulations. Cost compression in macro-pore construction grades intensifies as Chinese scale players absorb margin through volume commitments. Pharmaceutical and semiconductor buyers exhibit lowest price sensitivity due to process criticality, while building insulation procurement teams in Eastern Europe prioritize installed cost over purity metrics.
Supply Chain Analysis
Refurbished sintering furnace components flow back through German and Japanese engineering networks, extending asset lifecycles for thermal processing infrastructure. Production gravity centers on Germany, China, and the United States, with boron precursor purification drawing from concentrated Turkish mining operations and U.S. desert deposits. Supply chain vulnerability rests on single-source dependency for high-purity boron trioxide, where export quota disruptions in Ankara propagate through six-month procurement cycles. Distribution runs through direct vendor relationships with multinational pharmaceutical and semiconductor firms, displacing regional distributor influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance evaluations and ECHA registration mandates are consolidating procurement authority among pre-authorized chemistry holders, forcing non-compliant regional competitors into exit or acquisition pathways.
For Market Incumbents: To counter ceramic foam substitution in construction insulation, Schott and GLAPOR should deepen captive boron precursor supply through backward integration into Turkish purification assets, while simultaneously locking multi-year framework contracts with Dresden and Munich wafer fabrication facilities to anchor volume commitments against emerging Chinese entrants. For New Entrants and Emerging Players: Capture underserved demand from Indian contract manufacturing organizations in Hyderabad and Ahmedabad by qualifying nano-pore grades under CDSCO mandates, leveraging PLI scheme incentives to offset certification costs, and establishing direct e-procurement relationships that bypass traditional chemical distribution channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor Eastern European thermal insulation specialists with established REFAGLASS-like positions in Polish and Czech building markets, where energy price volatility squeezes furnace-dependent producers; watch for ECHA authorization list updates as inflection signals for chemistry-compliant acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Precursor Purification | Captive supply from Turkish mining operations insulates margin from export quota volatility. |
| Multi-Year Framework Contract Negotiation | Locked volume commitments with Frankfurt biopharma corridor defend position against spot-market competitors. |
| REACH Pre-Authorization Chemistry Investment | ECHA-compliant formulations create competitive moats in European tender processes. |
| Direct-to-Laboratory E-Procurement Platform Launch | Bypassing chemical distributors compresses channel margins and accelerates specification feedback loops. |
| Amine-Functionalized Coating Development | Carbon capture membrane integration opens pilot testing revenue with Dutch climate technology operators. |
Methodological Framework
Independent corroboration across sintering furnace operators, pharmaceutical procurement directors, and semiconductor facility engineers underwrites the qualitative findings, with secondary validation drawing from ECHA substance evaluation databases, FDA device material guidance documents, SEC filings of listed glass manufacturers, and customs trade records for boron precursor flows. Bottom-up demand modeling from end-use segments triangulates against top-down supply capacity assessments across German, Chinese, and U.S. production hubs.
Comparable-period anchoring to historical REACH implementation phases and F-Gas Regulation adoption curves shapes the projection horizon, with segmentation modeling spanning pore architecture tiers, end-use criticality levels, certification burden categories, and regional manufacturing cluster density. CAGRs derive from elasticity-adjusted volume trajectories incorporating semiconductor capital expenditure cycles, pharmaceutical cleanroom buildout rates, and European building insulation retrofit mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to boron export policy shifts in Turkey, European natural gas pricing volatility affecting sintering economics, and ceramic foam substitution thresholds in construction specifications. Material deviation in ECHA authorization timelines or CDSCO enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Double Glazing Glass Market
Glass
Asia Pacific Flexible Glass Market
Glass
Asia-Pacific Glassware Market
Glass
Low Temperature Laminated Glass Market
Glass
Recycled Glass Aggregates Market
Glass
Foam Glass Market
Glass
Low-E Glass Market
Glass
North America Flat Glass Market
Glass
Float Glass Market
Glass
Europe Sapphire Glass Market
Glass
Glass Prepreg Market
Glass
Optical Materials Market
Glass
Spherical Silica Market
Glass
Latin America Flat Glass Market
Glass
Laboratory Glassware Market
Glass
Europe Silica Sand for Glass Making Market