
 Food Grade Vitamin C Market | 2026-2036
Food Grade Vitamin C Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Vitamin C Market Insights
Buyer concentration among dietary supplement producers is repositioning procurement leverage toward large-scale contract manufacturers with backward integration into fermentation feedstocks. DSM-Firmenich N.V. leverages its integrated biotechnology platform to secure long-term supply agreements with multinational nutrition brands. BASF SE anchors European demand through certified ascorbic acid production aligned with REACH compliance protocols. CSPC Pharmaceutical Group dominates bulk powder output from Hebei province, competing on fermentation yield efficiency and captive citric acid supply.
Food grade vitamin C comprises purified L-ascorbic acid and mineral ascorbates meeting FCC and USP monograph specifications for residual solvents, heavy metals, and microbial limits, synthesized primarily via the Reichstein-Grüssner two-step fermentation process or the more efficient two-stage bacterial fermentation route developed in China. The ingredient functions as an antioxidant preservative, nutrient fortifier, and pH control agent across processed food matrices. Ascorbic acid powder leads volume demand due to cost efficiency in industrial bakery and beverage applications, while calcium ascorbate commands premium positioning in buffered supplement formulations for gastric-sensitive consumers. Tablet and granule forms are capturing share from raw powder as contract manufacturers seek downstream processing efficiencies and reduced dust exposure compliance.
EFSA purity standards, FDA 21 CFR 182.3013 GRAS affirmation, and China's GB 14754 national food additive standard collectively govern market access and product specification tiers across major trade corridors. The EU F-Gas Regulation indirectly shapes fermentation economics through refrigerant cost pass-through in ascorbic acid production facilities. India's FSSAI fortification guidelines for edible oils and wheat flour are expanding import demand for FCC-grade ascorbic acid from Chinese and European suppliers. Stakeholders must monitor regulatory divergence between EFSA's evolving additive re-evaluation timelines and China's GB standards revision cycle to anticipate specification-driven supply chain reconfigurations.
Market Dynamics
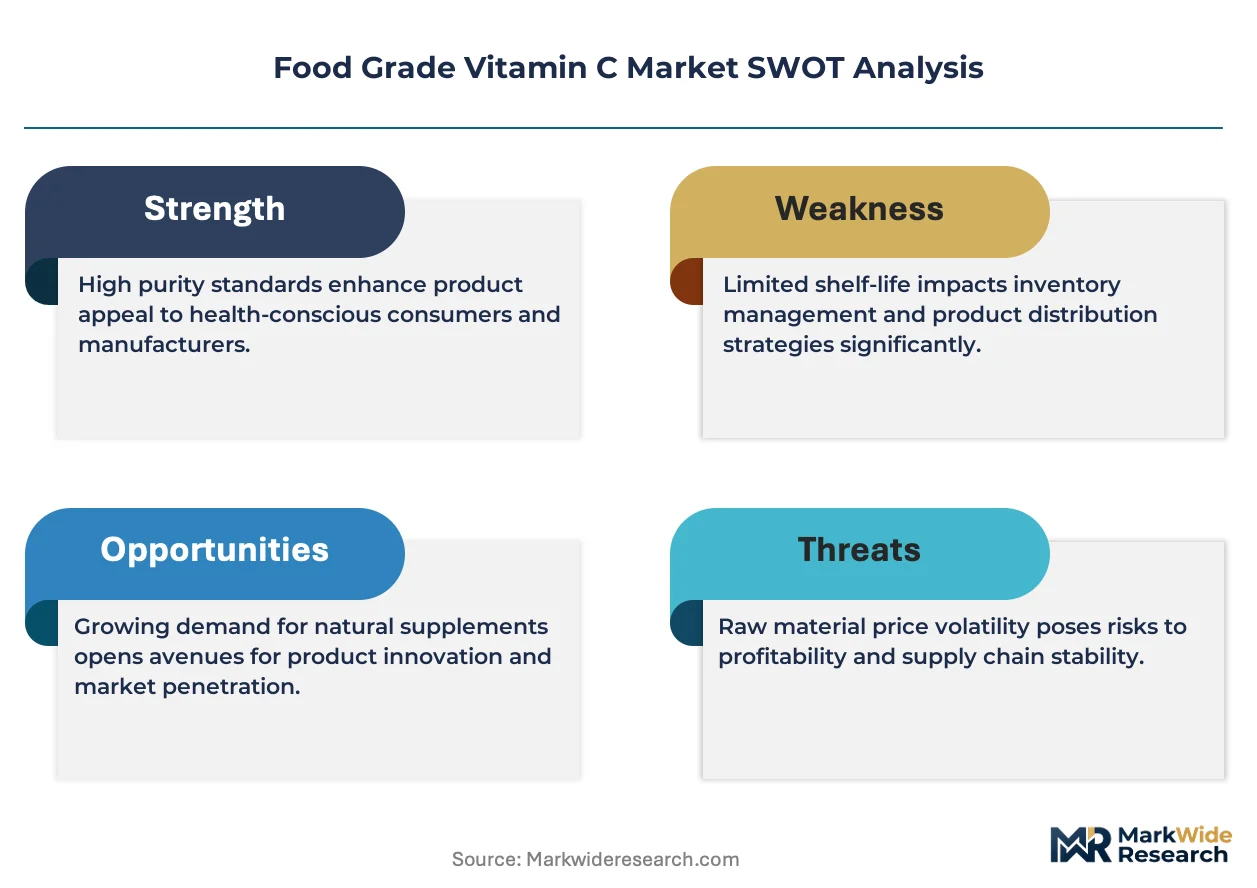
Fermentation yield efficiency differentials between Hebei province clusters and European pharmaceutical-grade facilities are compressing margin structures for non-integrated processors. Contract manufacturers now prioritize suppliers with captive citric acid feedstock security over spot-market sourcing flexibility.
Growth Catalysts
- FSSAI Oil Fortification Mandates:India's mandatory wheat flour and edible oil vitamin enrichment programs are expanding import demand for FCC-grade ascorbic acid from certified Chinese suppliers.
- Two-Stage Bacterial Fermentation:China's optimized fermentation route achieves superior conversion efficiency versus the legacy Reichstein-Grüssner process, lowering unit production costs for bulk powder output.
- EFSA Novel Food Pathway:Streamlined safety assessments for mineral ascorbate derivatives are accelerating new product introductions across EU dietary supplement channels.
Market Restraints
- Hebei Production Concentration:Overreliance on CSPC Pharmaceutical Group and Shandong Luwei Pharmaceutical creates geographic supply vulnerability to regional environmental enforcement actions.
- Citric Acid Price Volatility:Fermentation economics remain exposed to molasses and corn-derived substrate cost swings, compressing margins for non-backward-integrated processors.
- EU F-Gas Refrigerant Costs:The F-Gas Regulation's phasedown schedule elevates cooling expenses in fermentation facilities, disproportionately impacting smaller European producers.
Strategic Opportunities
- Buffered Supplement Formulations:Calcium ascorbate's gastric-tolerant positioning commands premium pricing in aging-population markets, with Japan's PMDA creating favorable classification pathways.
- Granule Form Conversion:Contract manufacturers are substituting raw powder with pre-processed granules to reduce dust exposure compliance burdens and downstream processing costs.
- Clean-Label Preservation:Ascorbic acid's antioxidant functionality in minimally processed foods aligns with WHO sodium reduction guidelines and clean-label positioning in North American retail channels.
Industry Challenges
- GB 14754-EFSA Specification Divergence:Misaligned heavy metal and residual solvent thresholds between Chinese national standards and EU purity requirements force dual-certification investments for export-oriented processors.
- Fermentation Specialist Scarcity:Industrial microbiology talent pools capable of optimizing two-stage bacterial yields remain concentrated in Shijiazhuang and Shandong corridor facilities, limiting technology transfer to new production sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Vitamin C Market |
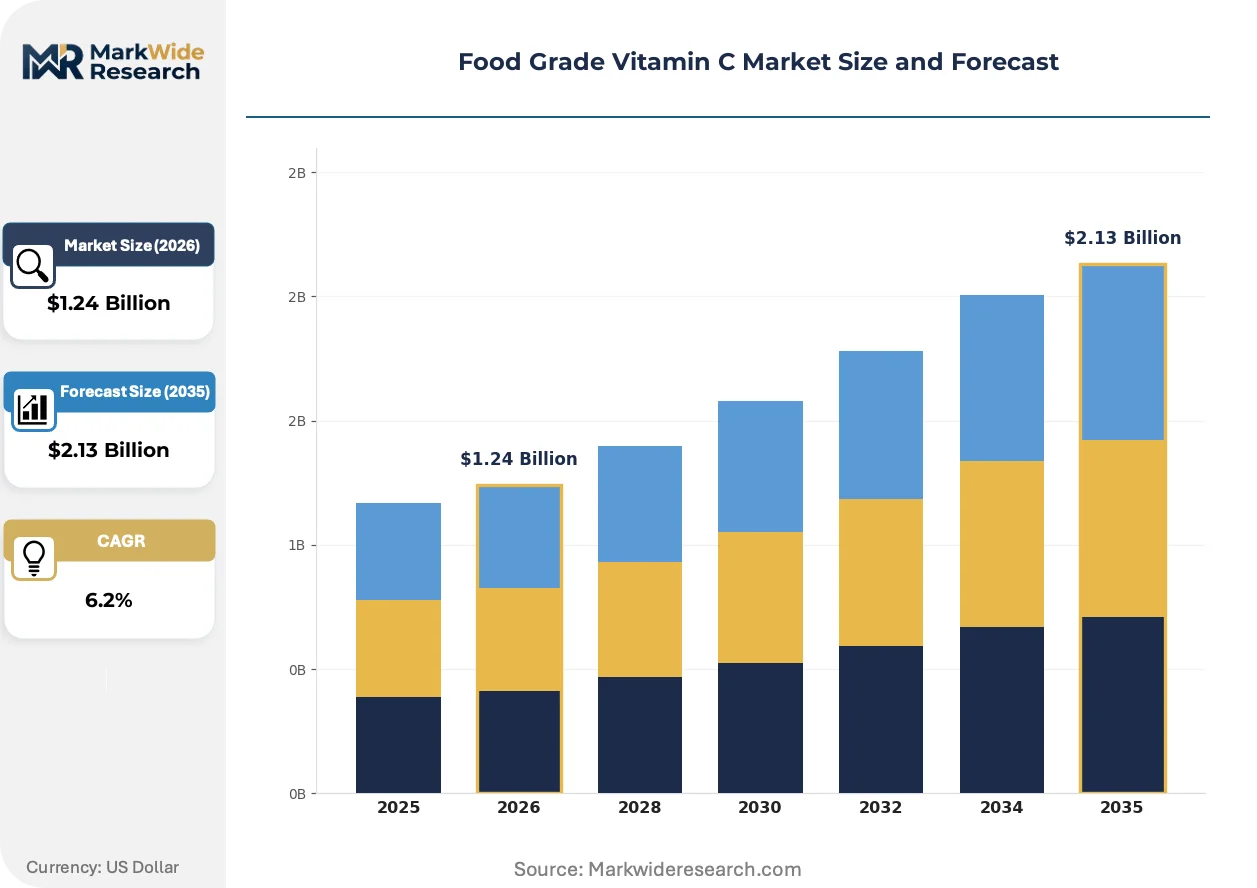
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Ascorbate, Calcium Ascorbate, Ascorbic Acid, Magnesium Ascorbate Form: Powder, Granule, Tablet, Liquid End User: Food Industry, Beverage Manufacturers, Dietary Supplement Producers, Cosmetics Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale |
| Companies Covered | DSM-Firmenich N.V., BASF SE, CSPC Pharmaceutical Group Ltd, Northeast Pharmaceutical Group Co., Ltd, Shandong Luwei Pharmaceutical Co., Ltd., Anhui BBCA Group, Zhejiang NHU Co., Ltd, Lonza Group Ltd, Foodchem International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Vitamin C Market Trends and Innovations
Biotechnology platforms and regulatory harmonization efforts are restructuring how ascorbic acid derivatives reach end-use markets. Process efficiency gains and specification convergence are compressing traditional competitive advantages.
Continuous fermentation systems with real-time metabolite monitoring are overtaking batch processing in new Chinese capacity installations. Industrial bakery and beverage manufacturers are prioritizing suppliers with validated continuous output consistency. This technology is enabling 24-hour production cycles that compress per-kilogram labor and energy costs versus conventional batch methods.
REACH compliance protocols for residual solvent documentation are tightening specification requirements across European import channels. ECHA's updated substance evaluation timelines are forcing third-party testing investments from Asian exporters. FCC-grade ascorbate shipments to Germany and the Netherlands now require expanded analytical certification packages, favoring producers with in-house chromatography capabilities.
Direct sourcing agreements between multinational nutrition brands and fermentation facilities are displacing traditional distributor intermediaries. Large-scale contract manufacturers in the United States are negotiating multi-year offtake contracts with specified volume floors and quality audits. This consolidation is most visible in California and New Jersey supplement manufacturing clusters, where backward-integrated suppliers secure preferential allocation during feedstock constraints.
Food Grade Vitamin C Market Segmentation
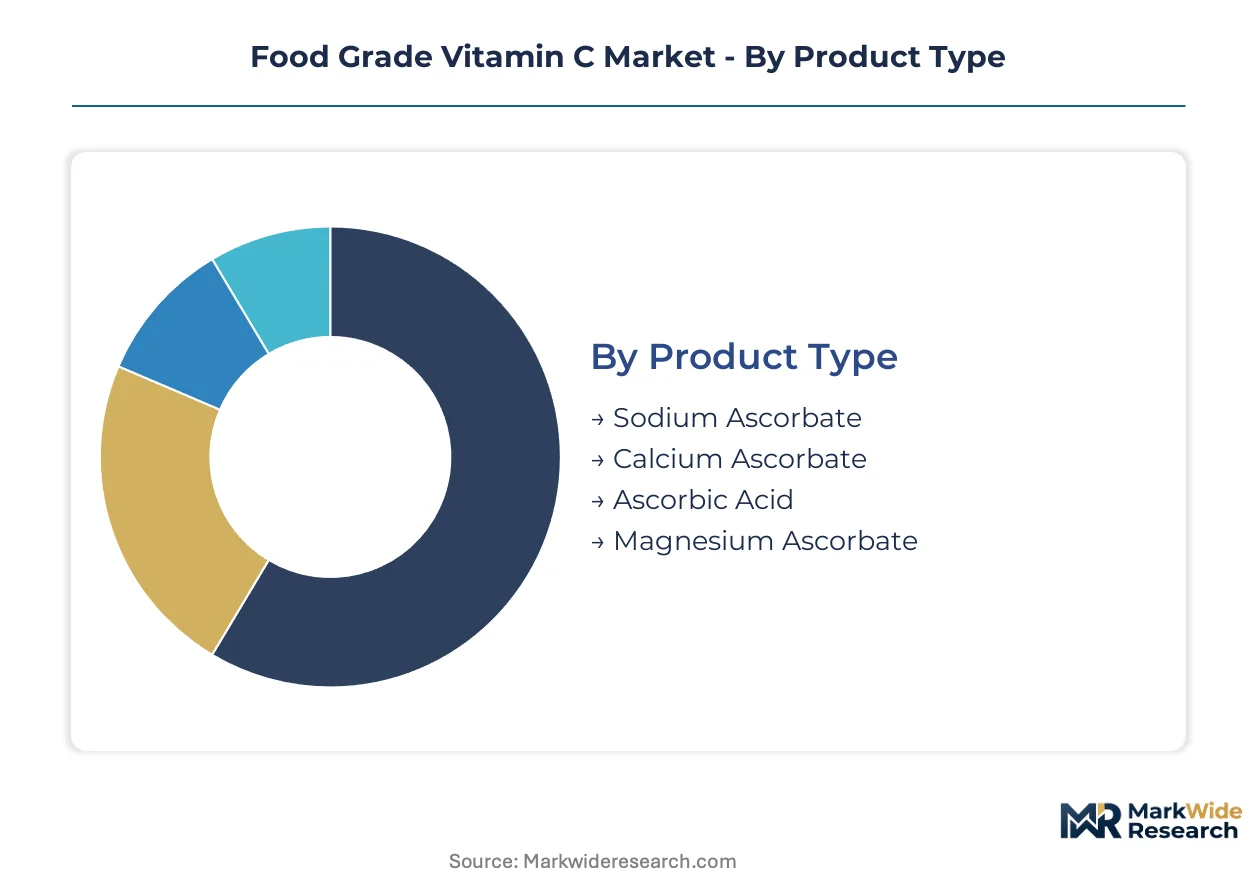
Segmentation in food grade vitamin C reveals divergent specification requirements across pharmaceutical-grade dietary supplements and industrial food preservation. Procurement patterns split between cost-sensitive bulk powder buyers and premium mineral ascorbate formulators seeking gastric-tolerant positioning.
Product Type:
Volume concentration favors commodity ascorbic acid while premium mineral ascorbates capture higher-margin supplement channels.
- Ascorbic Acid:Purified L-ascorbic acid meeting FCC and USP monograph specifications serves as the baseline antioxidant preservative across industrial bakery and beverage matrices. Demand concentrates in China where Hebei province fermentation clusters achieve superior yield efficiency through two-stage bacterial processing.
- Calcium Ascorbate:Buffered mineral ascorbate with neutral pH positioning commands premium pricing in gastric-sensitive supplement formulations. Japan's PMDA classification pathways and aging-population markets in Germany and the United States drive specialized procurement volumes.
- Sodium Ascorbate:Water-soluble salt derivative finds application in liquid fortification systems and pH-sensitive food matrices requiring sodium-compatible buffering.
- Magnesium Ascorbate:Dual-function mineral ascorbate combining nutrient delivery with magnesium supplementation targets premium wellness positioning in North American and European specialty channels.
Mature deployment sits with Ascorbic Acid. Newer deployment is concentrated in Calcium Ascorbate.
Form:
Industrial processors prioritize handling efficiency while supplement manufacturers seek downstream processing advantages.
- Powder:Crystalline ascorbic acid powder dominates volume throughput in industrial-scale bakery and beverage manufacturing. Cost efficiency and established handling infrastructure in China and India sustain procurement concentration despite dust exposure compliance burdens.
- Granule:Pre-processed granular forms reduce airborne particle exposure and downstream processing costs for contract manufacturers. California and New Jersey supplement manufacturing clusters are substituting raw powder with validated granule supply to streamline OSHA compliance protocols.
- Tablet:Direct-compression ready formats eliminate intermediate processing steps for finished dietary supplement producers seeking formulation consistency.
- Liquid:Pre-dissolved ascorbate solutions serve beverage fortification and injectable nutrient applications requiring immediate bioavailability.
Volume leadership remains with Powder. Granule forms are climbing the fastest as regulatory pressure on workplace exposure intensifies.
End User:
Application specifications diverge between industrial preservation requirements and pharmaceutical-grade nutrient delivery standards.
- Dietary Supplement Producers:Pharmaceutical-grade mineral ascorbate demand concentrates in contract manufacturers serving multinational nutrition brands. Direct sourcing agreements with fermentation facilities are displacing traditional distributor intermediaries in California and New Jersey clusters.
- Food Industry:Industrial bakery and processed meat applications drive bulk ascorbic acid procurement for antioxidant preservation and color stabilization. India's FSSAI fortification mandates for wheat flour and edible oils are expanding import demand from certified Chinese suppliers.
- Beverage Manufacturers:Liquid fortification and pH control applications in carbonated and functional beverages require consistent solubility specifications.
- Cosmetics:Topical antioxidant formulations utilize ultra-pure ascorbic acid derivatives with stringent heavy metal limits for dermal application.
Established penetration sits with Food Industry. Accelerating deployment is concentrated in Dietary Supplement Producers.
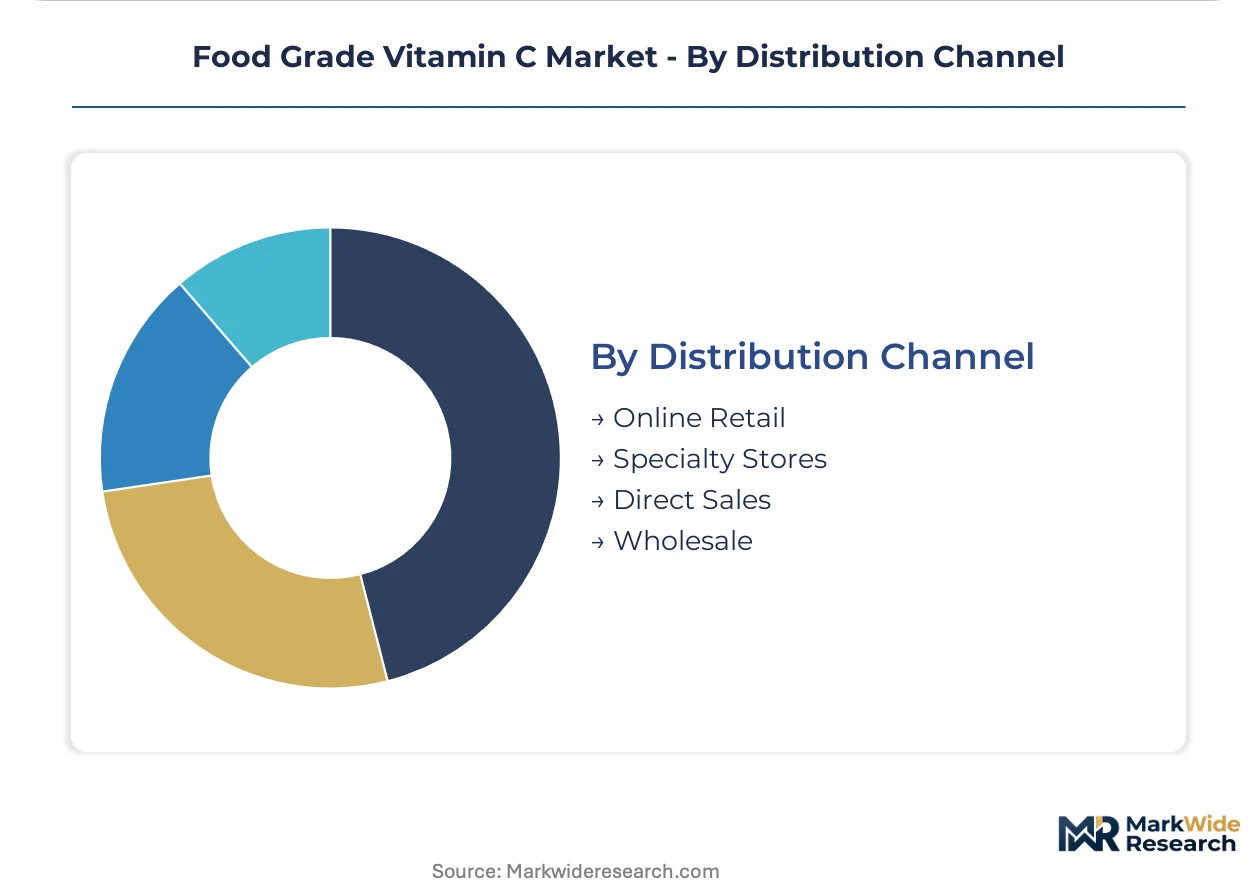
Distribution Channel:
Supply chain configuration reflects scale differentiation between institutional procurement and fragmented retail access.
- Direct Sales:Multi-year offtake contracts with specified volume floors and quality audits dominate large-scale procurement. Multinational nutrition brands negotiate directly with CSPC Pharmaceutical Group and Shandong Luwei Pharmaceutical to secure preferential allocation during feedstock constraints.
- Wholesale:Traditional distributor networks serve mid-tier processors requiring flexible spot-market sourcing without backward integration capabilities.
- Online Retail:E-commerce platforms capture small-batch specialty and research-grade ascorbate demand from independent formulators and regional supplement manufacturers.
- Specialty Stores:Niche channels serve cosmetic and pharmaceutical compounders requiring certified pharmacopeia grades with expanded analytical documentation.
Procurement concentration sits with Direct Sales. Emerging volume is concentrating in Online Retail for specialty and small-batch requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hebei province's corn belt supplies the fermentation feedstock that anchors China's dominance in bulk ascorbic acid output. Regional demand patterns split between industrial preservation markets in Asia and pharmaceutical-grade supplement channels in North America and Europe.
China
Shijiazhuang and Shandong corridor facilities process two-stage bacterial fermentation at unmatched yield efficiency. GB 14754 national food additive standards govern domestic purity specifications while export-oriented plants pursue dual-certification for EFSA-aligned heavy metal thresholds. Hebei province clusters concentrate over half of global fermentation capacity, with environmental enforcement actions periodically disrupting regional output.
United States
California and New Jersey supplement manufacturing clusters drive pharmaceutical-grade mineral ascorbate procurement. FDA 21 CFR 182.3013 GRAS affirmation structures import documentation requirements for FCC-grade powder. Direct sourcing agreements between contract manufacturers and Chinese fermentation facilities are displacing traditional distributor networks in these coastal manufacturing zones.
Germany
BASF SE anchors European demand through REACH-compliant ascorbic acid production serving industrial bakery and beverage preservation. ECHA substance evaluation timelines tighten residual solvent documentation for Asian imports entering Rotterdam and Hamburg ports. Bavaria-based pharmaceutical compounders prioritize suppliers with in-house chromatography capabilities for expanded analytical certification.
India
FSSAI mandatory wheat flour and edible oil fortification programs expand import demand for FCC-grade ascorbic acid from certified Chinese suppliers. Mumbai and Ahmedabad processing hubs distribute bulk powder to regional bakery and oil-refining operations. BIS quality mark requirements create specification barriers for uncertified Asian exporters seeking direct market access.
Japan
PMDA classification pathways for buffered mineral ascorbates support premium supplement positioning in aging-population markets. Osaka and Tokyo formulation clusters source ultra-pure derivatives for gastric-tolerant tablet and granule production. METI industrial standards differentiate food-grade from pharmaceutical-grade import channels, with stricter microbial limits applied to finished supplement ingredients.
Food Grade Vitamin C Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty mineral ascorbate formulations and clean-label preservation positioning. Market structure concentrates around fermentation-based bulk suppliers with captive citric acid feedstock security and downstream formulators with direct brand relationships. Three archetypes dominate: backward-integrated Chinese fermentation clusters, European REACH-compliant chemical processors, and North American contract manufacturers with formulation IP. Competitive moves center on multi-year offtake contracting with volume floors and geographic expansion through distributor displacement.
Within the fermentation-integrated tier, CSPC Pharmaceutical Group Ltd and Shandong Luwei Pharmaceutical Co., Ltd. exemplify scale-driven positioning anchored in Hebei province feedstock access. DSM-Firmenich N.V. represents the biotechnology-platform archetype securing long-term supply agreements through integrated fermentation capabilities. BASF SE occupies the European compliance-specialist position, aligning certified production with REACH documentation protocols for German industrial demand.
| Leading Market Players |
|---|
| DSM-Firmenich N.V. |
| BASF SE |
| CSPC Pharmaceutical Group Ltd |
| Northeast Pharmaceutical Group Co., Ltd |
| Shandong Luwei Pharmaceutical Co., Ltd. |
| Anhui BBCA Group |
| Zhejiang NHU Co., Ltd |
| Lonza Group Ltd |
| Foodchem International Corporation |
| Others |
Pricing and Supply Chain Analysis
Corn-derived fermentation feedstock costs cascade through three distinct pricing tiers, with Hebei province's captive citric acid supply anchoring economy-grade powder quotations while REACH-compliant European production commands premium positioning for pharmaceutical-grade mineral ascorbates. Contract manufacturers in California and New Jersey clusters negotiate multi-year offtake agreements with specified volume floors, compressing spot-market flexibility for non-integrated processors.
Pricing Analysis
Certificate-of-analysis bundling separates premium mineral ascorbate quotations from unbundled bulk powder transactions, with EFSA-aligned heavy metal documentation adding cost layers for EU-bound shipments. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and captive feedstock security. Pricing pressure stems from two-stage bacterial fermentation yield improvements in Shijiazhuang corridor facilities, eroding legacy Reichstein-Grüssner process margins. Dietary supplement producers exhibit lowest price sensitivity, prioritizing gastric-tolerant calcium ascorbate positioning over unit cost minimization.
Supply Chain Analysis
Industrial microbiology talent scarcity in Shandong and Hebei provinces constrains technology transfer to new fermentation sites, preserving incumbent yield advantages. Production gravity centers on China, Germany, and India, with raw material dependencies spanning corn-derived substrates, molasses feedstocks, and specialized bacterial culture strains. Single-source vulnerability concentrates in CSPC Pharmaceutical Group and Shandong Luwei Pharmaceutical capacity, exposing buyers to regional environmental enforcement disruptions. Distribution runs through direct sales channels displacing traditional wholesale intermediaries among large-scale contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into fermentation feedstocks defines competitive survival, with citric acid supply security and bacterial culture optimization emerging as the decisive upstream levers separating margin-sustainable producers from spot-market casualties.
For Market Incumbents: To counter yield-efficiency compression from two-stage bacterial fermentation advances in Hebei province, DSM-Firmenich N.V. and BASF SE should deepen captive citric acid supply through long-term molasses offtake contracts and accelerate continuous fermentation system deployment. Certification investment in expanded analytical documentation packages for ECHA substance evaluation timelines will defend European channel access against lower-cost Chinese exporters. For New Entrants and Emerging Players: Capture white-space opportunity in granule-form conversion for California and New Jersey supplement manufacturing clusters seeking OSHA dust exposure compliance solutions. Target India's FSSAI fortification-driven import demand with certified FCC-grade powder positioning, leveraging Mumbai and Ahmedabad distribution hubs for regional bakery and oil-refining penetration. For Investors and Strategic Acquirers: EFSA Novel Food pathway acceleration for mineral ascorbate derivatives is the leading indicator that premium supplement formulation capacity will command scarcity premiums. Five-to-ten year viability favors acquisition targets with validated continuous fermentation installations and in-house chromatography capabilities for REACH-compliant documentation, with dual-certification investments for GB 14754-EFSA specification convergence serving as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Deployment | 24-hour production cycles compress labor and energy costs versus batch methods for Hebei province operators. |
| Dual-Certification Investment | GB 14754 and EFSA alignment enables export flexibility across Chinese domestic and European import channels. |
| Granule Form Capacity Addition | Pre-processed formats reduce OSHA compliance burdens for New Jersey and California supplement manufacturers. |
| Captive Citric Acid Integration | Molasses supply security insulates fermentation economics from commodity substrate volatility. |
| Direct Sourcing Agreement Expansion | Multi-year offtake contracts with volume floors displace distributor intermediaries in multinational nutrition brand procurement. |
Research Methodology
Multi-period observation of fermentation yield differentials, regulatory re-evaluation timelines, and contract manufacturing procurement patterns anchored the trend analysis, supplemented by interviews with fermentation plant managers, dietary supplement procurement leads, EFSA regulatory affairs specialists, and Indian FSSAI compliance officers. Secondary validation drew from customs trade data, ECHA substance evaluation disclosures, SEC 10-K filings by listed chemical producers, and GB standards revision bulletins. Bottom-up volume modeling triangulated against top-down market sizing across product type, form, end user, and distribution channel dimensions.
Segment-weighting approaches applied differential growth assumptions to pharmaceutical-grade mineral ascorbates versus industrial preservation powder, with calcium ascorbate premium positioning and granule form conversion receiving accelerated trajectory coefficients. CAGRs derived from regression analysis of historical procurement volumes against FSSAI mandate implementation schedules and PMDA classification pathway progressions. Industry-specific inputs incorporated two-stage bacterial fermentation yield curves and REACH documentation cost pass-through estimates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Hebei province environmental enforcement intensity, EU F-Gas Regulation refrigerant phasedown cost trajectories, and corn-molasses feedstock price volatility. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Global Vitamin Tonics Market
Vitamin Fortified
Vitamin E Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Food Grade Vitamin B1 Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
Delta-Tocopherol Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
Vitamin B Market
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
Feed Grade Vitamin D Market