
 Fortified Beverages Market | 2026-2036
Fortified Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Fortified Beverages Market Foresight
Single-serve functional shot formats is consolidating shelf space away from multi-liter family bottles in mainstream retail. PepsiCo leverages its direct-store-delivery infrastructure to dominate convenience channel placement for protein-based shakes. Danone sustains competitive positioning in pediatric and elderly nutrition through specialized fortification protocols. Nestle anchors premium mineral-enriched juice offerings in European pharmacy networks with clinical-grade positioning.
Fortified beverages are non-alcoholic drinks engineered with added micronutrients, bioactive compounds, or functional ingredients at specified concentrations, typically processed through aseptic cold-filling or hot-fill pasteurization to preserve nutrient stability. These products serve commercial purposes ranging from targeted dietary supplementation to performance optimization and clinical nutrition support. Vitamin-enhanced water and protein-based shakes command the largest current revenue pools, while mineral-enriched juices and herbal infusions represent faster-expanding categories as consumers prioritize clean-label botanical sourcing. Energy drinks maintain mature volume bases in North American convenience retail but face margin compression from ingredient cost volatility and caffeine regulatory scrutiny.
The FDA nutrition labeling overhaul and EFSA health claims framework govern permissible fortification levels and marketing language across their respective jurisdictions, directly constraining product development pipelines and cross-border formulation strategies. China's SAMR national food safety standards for nutrient fortification impose additional testing and registration burdens on imported functional beverages seeking mainland market access. Stakeholders must monitor evolving micronutrient ceilings and permissible health claim inventories to preempt reformulation cycles and avoid distribution holds.
Market Dynamics
The FDA's updated nutrition labeling requirements for added sugars and micronutrient disclosures are compelling manufacturers to reformulate portfolios at scale, compressing development cycles and reshaping competitive positioning across retail channels.
Growth Catalysts
- Collegiate athletic procurement:Sports nutrition applications draw heightened procurement from collegiate athletic programs and professional training facilities, expanding institutional volume commitments.
- SAMR registration pathways:China's national food safety standards for nutrient fortification, while imposing testing burdens, create structured entry mechanisms for compliant imported functional beverages.
- Pharmacy channel penetration:Functional beverage distribution through pharmacy and convenience store channels in Brazil deepens market access in lower-tier cities previously underserved by mainstream retail.
Market Restraints
- Ingredient cost volatility:Caffeine sourcing and botanical extract supply face price instability from climate-affected harvests in Southeast Asia and East Africa.
- Regulatory friction:EFSA's health claims framework constrains permissible fortification levels and marketing language, forcing cross-border formulation divergence.
- Substitution pressure:Whole-food nutrition bars and fresh functional foods capture consumer preference shifts away from processed liquid formats in premium segments.
Strategic Opportunities
- Clean-label botanical expansion:Mineral-enriched juices and herbal infusions with transparent sourcing protocols capture consumer prioritization of traceable ingredient chains.
- Direct-store-delivery optimization:Convenience channel placement for protein-based shakes benefits from infrastructure investments in cold-chain last-mile capabilities.
- Clinical-grade positioning:European pharmacy networks anchor premium mineral-enriched juice offerings with medical-channel credibility and reimbursement adjacency.
Industry Challenges
- Nutrient stability engineering:Aseptic cold-filling and hot-fill pasteurization processes require specialized equipment and technical expertise to preserve bioactive compound integrity through shelf life.
- Reformulation cycle compression:Evolving micronutrient ceilings across FDA, EFSA, and SAMR jurisdictions force simultaneous multi-market compliance updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Beverages Market |
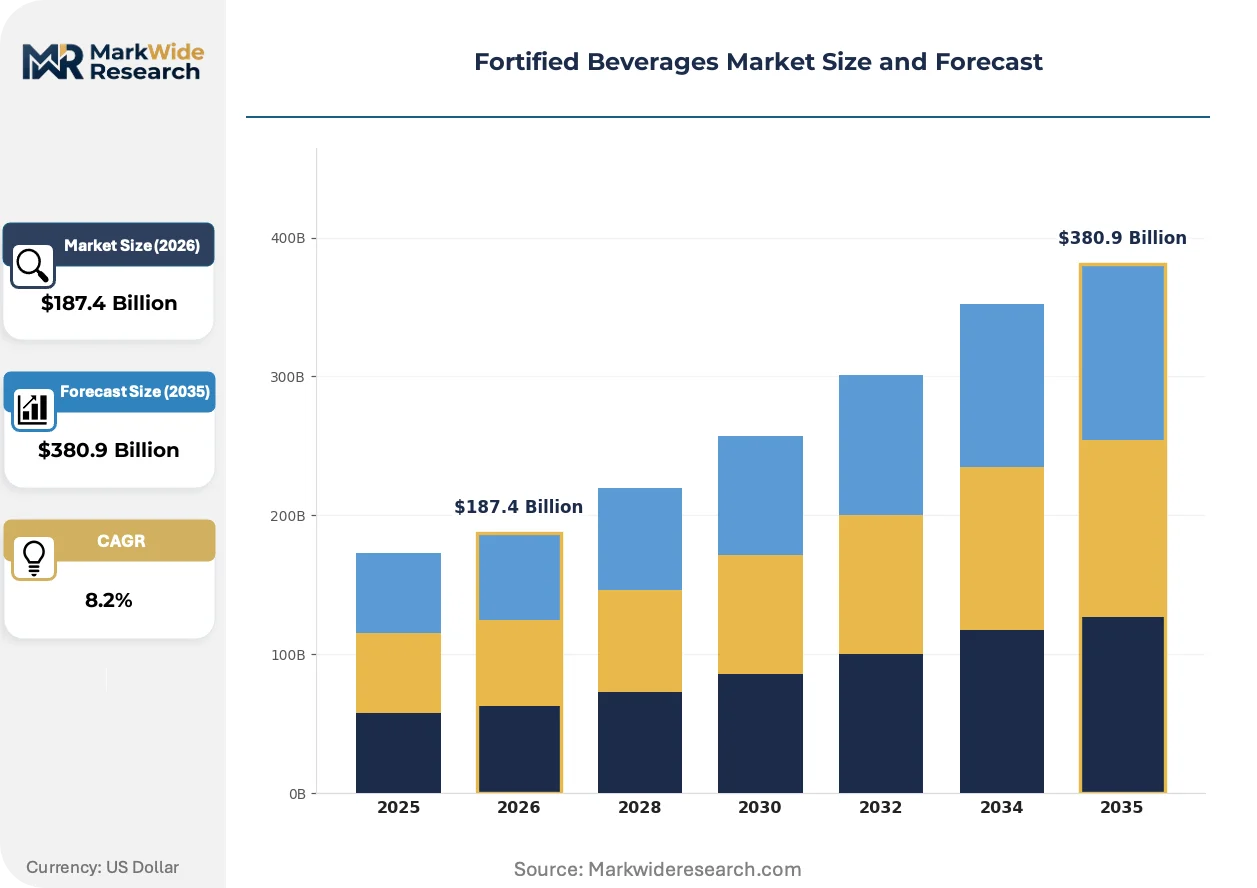
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $380.9 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Drinks, Vitamin-Enhanced Water, Mineral-Enriched Juices, Herbal Infusions, Protein-Based Shakes Fortifying Ingredient: Vitamins, Minerals, Amino Acids, Antioxidants, Probiotics Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops, Pharmacies End User: Athletes, Children, Elderly, Fitness Enthusiasts, Pregnant Women |
| Companies Covered | Nestle, PepsiCo, Coca-Cola, Danone, Mondelez International, Unilever, Kraft Heinz, Reed's Inc., Hain Celestial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Beverages Market Shifts & Advancements
Single-serve functional shot formats are consolidating shelf space away from multi-liter family bottles, while cold-chain infrastructure investments and clinical-channel positioning are rewriting how fortified beverages reach end consumers.
Microencapsulation technology for heat-sensitive vitamins and probiotics is rewriting stability benchmarks for ambient-distribution functional beverages. Pediatric and elderly nutrition segments adopt these formats most aggressively, enabling shelf-stable claims previously restricted to refrigerated products. This capability compression is collapsing the traditional refrigerated-ambient boundary in retail beverage planning.
EFSA's evolving health claims inventory and the FDA's added-sugar disclosure mandates are forcing parallel reformulation tracks for multinational portfolios. Manufacturers must maintain distinct SKUs or universal compliant recipes, each imposing cost and complexity trade-offs. European pharmacy networks and US mainstream retail channels now demand divergent documentation and labeling protocols from shared production lines.
Buyer concentration among institutional sports programs and healthcare procurement coalitions is shortening contract renewal cycles and tightening performance specifications. Volume commitments now hinge on clinical validation or athletic outcome data rather than brand recognition alone. Brazil's pharmacy channel expansion and US collegiate athletic programs exemplify this specification-driven purchasing shift.
Fortified Beverages Market Segmentation
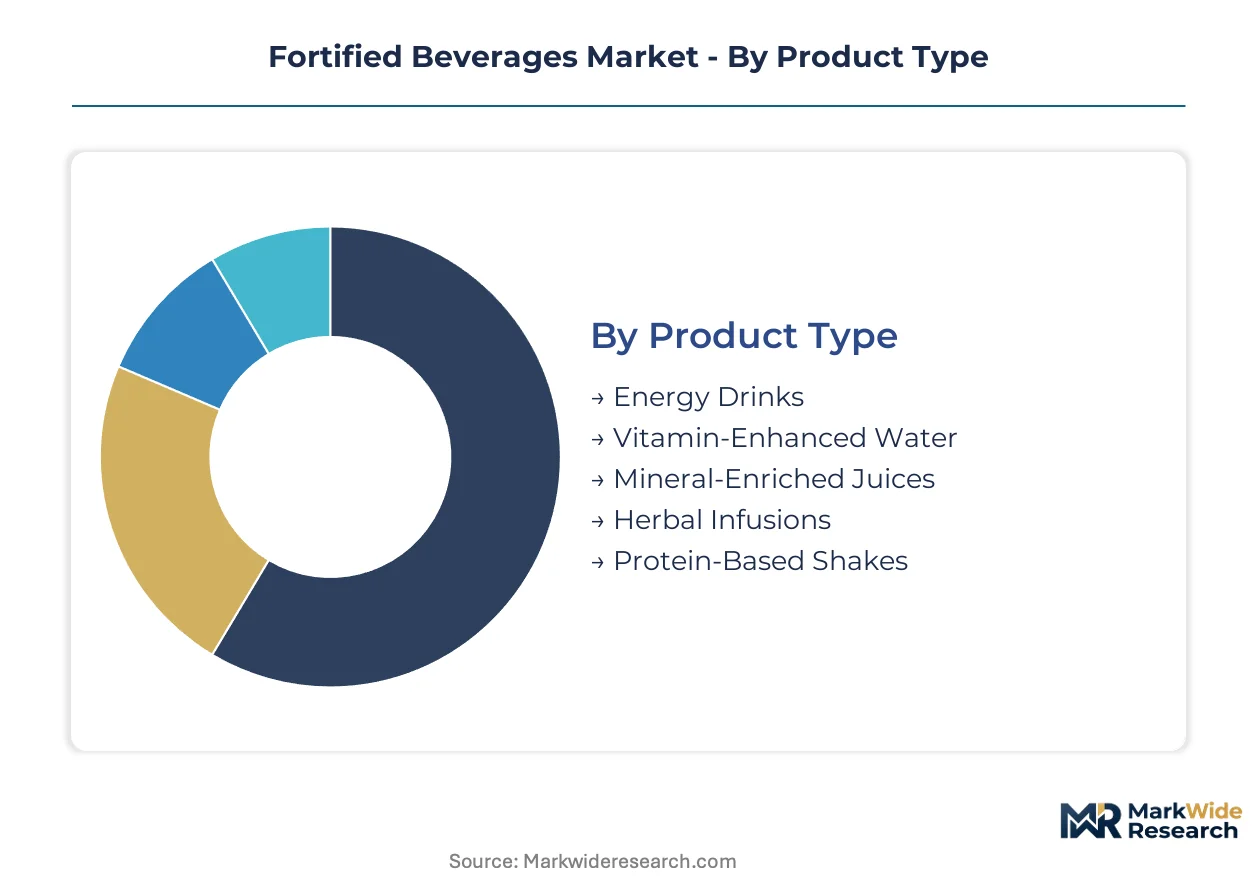
Fortified beverages fragment across formulation technology, distribution infrastructure, and physiological targeting. Manufacturers must align production capabilities with channel-specific stability requirements and end-user nutritional specifications to capture value.
Product Type:
Processing technology and shelf-stability requirements differentiate competitive positioning across liquid formats.
- Protein-Based Shakes:Cold-chain distribution and aseptic filling preserve amino acid integrity through extended shelf life. Collegiate athletic programs and professional training facilities in the United States drive institutional procurement volumes for post-workout recovery formulations.
- Vitamin-Enhanced Water:Hot-fill pasteurization enables ambient distribution while maintaining micronutrient concentrations above label claims. Brazil's pharmacy and convenience store channels in lower-tier cities deepen penetration for functional hydration products.
- Energy Drinks:Mature convenience retail presence in North America faces margin pressure from caffeine sourcing volatility.
- Mineral-Enriched Juices:Clinical-grade positioning in European pharmacy networks commands premium pricing through medical-channel credibility.
- Herbal Infusions:Clean-label botanical sourcing protocols attract traceability-focused consumers seeking transparent supply chains.
Protein-based shakes lead on scale; mineral-enriched juices lead on momentum.
Fortifying Ingredient:
Ingredient stability profiles and regulatory ceiling constraints shape formulation strategies across jurisdictions.
- Vitamins:Microencapsulation technology protects heat-sensitive compounds during pasteurization, enabling shelf-stable claims previously restricted to refrigerated distribution. Pediatric and elderly nutrition segments in Japan adopt these formats aggressively.
- Minerals:Bioavailability enhancement through chelation chemistry drives absorption efficacy in clinical nutrition applications. China's SAMR registration pathways impose testing burdens while creating structured entry mechanisms for compliant imports.
- Amino Acids:Sports performance positioning requires precise leucine-isoleucine-valine ratios for muscle protein synthesis claims.
- Antioxidants:Botanical extract sourcing from Southeast Asia faces climate-affected harvest volatility.
- Probiotics:Ambient-stable strain development collapses traditional refrigerated-ambient boundaries in retail beverage planning.
Vitamins dominate current revenue pools; probiotics command the steepest expansion trajectory.
Distribution Channel:
Cold-chain infrastructure investment and last-mile capabilities determine placement economics.
- Convenience Stores:Direct-store-delivery networks optimize protein shake placement through refrigerated merchandising. PepsiCo's infrastructure dominance in the United States secures prime shelf positioning for functional beverages.
- Pharmacies:Clinical-grade mineral juices anchor premium positioning with reimbursement adjacency in Germany and Switzerland. Nestle leverages European pharmacy network relationships for medical-channel credibility.
- Supermarkets:Single-serve functional shots consolidate shelf space away from multi-liter family bottles.
- Online Retail:Subscription models capture repeat purchase loyalty for specialized pediatric and elderly nutrition.
- Specialty Shops:Premium botanical infusions target traceability-focused consumers seeking artisanal sourcing narratives.
Convenience stores concentrate volume; pharmacies capture margin expansion.
End User:
Physiological requirements and consumption occasions drive formulation specificity and channel selection.
- Athletes:Collegiate and professional procurement specifications now demand clinical validation or athletic outcome data rather than brand recognition alone. Danone sustains positioning through specialized fortification protocols for performance optimization.
- Elderly:Micronutrient density and texture modification address sarcopenia and hydration challenges in aging populations. European pharmacy networks prioritize geriatric nutrition with medical-channel documentation.
- Children:Pediatric fortification protocols require stringent safety testing and age-appropriate dosing.
- Fitness Enthusiasts:Protein timing and recovery positioning drives post-workout consumption occasions.
- Pregnant Women:Folate and iron fortification addresses specific gestational nutritional requirements.
Athletes anchor institutional volume commitments; elderly nutrition segments gain share fastest through clinical-channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The fortified beverages industry traces its commercial origins to Swiss pharmaceutical-nutrition laboratories and American convenience retail networks, with European pharmacy channels and U.S. mass-market distribution establishing the dual-track regulatory and commercial templates now replicated worldwide.
United States
Collegiate athletic programs and professional training facilities drive institutional procurement volumes for protein-based recovery formulations. The FDA's updated nutrition labeling requirements for added sugars and micronutrient disclosures compel manufacturers to maintain parallel formulation tracks for domestic and export markets. Greater Los Angeles and the Northeast Corridor concentrate cold-chain logistics infrastructure for direct-store-delivery optimization.
Germany
Clinical-grade mineral-enriched juices command premium positioning through pharmacy network credibility and reimbursement adjacency. EFSA's health claims framework constrains permissible fortification levels and marketing language, forcing documentation protocols distinct from North American standards. The Rhine-Ruhr and Bavarian industrial clusters anchor aseptic filling equipment manufacturing and technical expertise for nutrient stability engineering.
Brazil
Functional beverage penetration deepens in lower-tier cities through pharmacy and convenience store channels previously underserved by mainstream retail. ANVISA registration pathways impose testing burdens while creating structured entry mechanisms for compliant imported products. São Paulo and Rio de Janeiro metropolitan areas concentrate distribution infrastructure for ambient-stable vitamin-enhanced water formats.
China
SAMR national food safety standards for nutrient fortification drive registration and testing requirements for imported functional beverages seeking mainland market access. The country's dual carbon goals accelerate cold-chain infrastructure investment for refrigerated protein shake distribution. Yangtze River Delta manufacturing clusters produce microencapsulation technology for heat-sensitive vitamin stabilization.
Japan
Pediatric and elderly nutrition segments adopt ambient-stable fortification formats aggressively, collapsing traditional refrigerated-ambient boundaries in retail beverage planning. METI industrial standards guide probiotic strain development for shelf-stable claims. Kanto and Kansai metropolitan areas concentrate specialized fortification protocol R&D for aging-population micronutrient density requirements.
Fortified Beverages Market Competitive Landscape
The competitive structure tilts toward multinational diversified beverage conglomerates with established cold-chain distribution infrastructure and pharmaceutical-nutrition specialists with clinical-channel credibility. Three archetypes dominate: scale-driven mass-market operators leveraging direct-store-delivery networks, premium-tier clinical-grade formulators anchoring pharmacy relationships, and clean-label botanical specialists targeting traceability-focused consumers. Consolidation pressure operates through strategic partnerships for geographic expansion and technology licensing for microencapsulation capabilities.
Among Swiss and French nutrition specialists, Nestle and Danone exemplify the clinical-grade positioning archetype through European pharmacy network relationships. PepsiCo occupies the mass-market infrastructure tier with convenience channel dominance for protein-based shake distribution. These three entities represent the strategic spectrum from medical-channel credibility to retail-scale penetration.
| Leading Market Players |
|---|
| Nestle |
| PepsiCo |
| Coca-Cola |
| Danone |
| Mondelez International |
| Unilever |
| Kraft Heinz |
| Reed's Inc. |
| Hain Celestial Group |
| Others |
Supply & Pricing Matrix
Aseptic filling technician concentrations in the Rhine-Ruhr industrial cluster and Bavarian manufacturing zones create labor-cost differentials that widen pricing-tier spreads between clinical-grade pharmacy products and mass-market convenience formats. European technical expertise commands premium wage structures that feed into mineral-enriched juice positioning, while automated hot-fill lines in lower-cost geographies compress standard-tier price points.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies fortified beverages by clinical validation depth and cold-chain dependency. Price differentiation separates medical-channel mineral juices with reimbursement adjacency from ambient-stable vitamin waters and economy protein shakes. Cost compression in the standard tier intensifies because caffeine sourcing volatility and botanical extract supply instability from Southeast Asian harvests squeeze manufacturer margins. Institutional sports programs exhibit lowest price sensitivity due to specification-driven procurement, while fitness enthusiasts in direct-to-consumer channels demonstrate highest elasticity.
Supply Chain Analysis
Workforce availability for microencapsulation R&D concentrates in Japan's Kanto and Kansai metropolitan areas and China's Yangtze River Delta manufacturing clusters. Supply draws from German aseptic equipment engineering, Brazilian ambient distribution infrastructure, and Japanese probiotic strain development capabilities. Raw material dependencies include climate-vulnerable botanical extracts from East Africa, chelated mineral compounds from European chemical processors, and heat-sensitive vitamin precursors requiring specialized stabilization. Single-source vulnerability in Southeast Asian caffeine harvesting creates supply chain risk. Distribution runs through direct-store-delivery networks for refrigerated protein shakes and pharmacy wholesale for clinical-grade positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fortified beverages market functions as a geographic-arbitrage play where SAMR registration burdens in China create compliance cost differentials against Brazil's ANVISA pathways, rewarding manufacturers with multi-jurisdictional regulatory expertise.
For Market Incumbents: Acquire cold-chain last-mile capabilities in underserved Brazilian lower-tier cities to preempt pharmacy channel consolidation. Nestle and Danone anchor positions through European pharmacy network relationships; PepsiCo's infrastructure dominance secures US convenience placement. Defensive consolidation demands backward integration into botanical extract sourcing to mitigate climate-driven supply volatility, paired with microencapsulation technology licensing to collapse refrigerated-ambient boundaries. For New Entrants and Emerging Players: Enter via pediatric and elderly nutrition subscription models in Japan's aging demographic, where ambient-stable fortification formats displace traditional refrigerated products. White-space targets include clean-label herbal infusions with transparent supply chain documentation and clinical-grade mineral juices in German pharmacy networks seeking reimbursement adjacency. Go-to-market positioning emphasizes traceable botanical sourcing narratives over brand recognition. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale clean-label botanical specialists lacking direct-store-delivery infrastructure but commanding traceability premiums. Long-term viability across the analysis window favors clinical-channel credibility over mass-market scale as procurement shifts toward specification-driven purchasing. Acquisition target archetype: European pharmacy-network formulators with EFSA-compliant documentation protocols. Watch for FDA micronutrient ceiling revisions as inflection indicators forcing portfolio-wide reformulation.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Enables shelf-stable probiotic claims previously restricted to refrigerated distribution in pediatric segments. |
| Pharmacy Channel Expansion | Deepens functional beverage penetration in Brazil's lower-tier cities through ANVISA-compliant distribution infrastructure. |
| Clinical Validation Investment | Secures institutional procurement from collegiate athletic programs demanding athletic outcome data over brand recognition. |
| Botanical Supply Chain Integration | Reduces caffeine and extract cost volatility exposure from climate-affected Southeast Asian harvests. |
| Multi-Jurisdictional Registration | Creates structured SAMR and EFSA compliance pathways for cross-border formulation standardization. |
Research Methodology
Direct dialogue with beverage formulation scientists, pharmacy procurement managers, collegiate athletic program nutrition directors, and cold-chain logistics operators grounded qualitative insights. Secondary validation drew from FDA nutrition labeling filings, EFSA health claims registers, SAMR food safety standard publications, and ANVISA registration databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation outputs modeled product type, fortifying ingredient stability profile, distribution channel infrastructure requirement, and end-user physiological targeting throughout the forecast period. CAGRs derived from historical trajectory analysis adjusted for regulatory reformulation cycle compression and channel penetration rate differentials. Forecast inputs incorporated institutional procurement contract renewal patterns and microencapsulation technology adoption curves.
The model holds under stable regulatory ceiling assumptions across FDA, EFSA, and SAMR jurisdictions; deviation in micronutrient disclosure mandates or botanical extract import restrictions would shift manufacturer reformulation timelines and cross-border portfolio strategies. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
Retinyl Linoleate Market
Vitamin Fortified
Vitamin K Market
Vitamin Fortified
Essential Micronutrients Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Food Grade Vitamin B1 Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Vitamin Yeast Market
Vitamin Fortified
Global Vitamin Tonics Market
Vitamin Fortified
Middle East Feed Vitamins Market