
 Europe Food Fortifying Agents Market | 2026-2036
Europe Food Fortifying Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Fortifying Agents Market Foresight
Precision fermentation and enzymatic synthesis is rewriting the cost structure for bioactive fortifying compounds across European food manufacturing. BASF SE leverages its Ludwigshafen R&D complex to sustain leadership in lipid-soluble vitamin production. Kerry Group plc anchors its position through dairy-specific premix formulations that dominate Irish and UK processing channels. DSM Nutritional Products differentiates via microbial strain libraries that accelerate probiotic stability in ambient beverages.
Food fortifying agents comprise vitamins, minerals, amino acids, and probiotics added to processed foods to restore nutrients lost in refining or to enhance nutritional profiles beyond baseline composition; these compounds typically require encapsulation or spray-drying to survive thermal processing and gastric transit. Vitamins retain the largest volume share due to mandatory fortification in flour and dairy across EU member states, though probiotics generate superior margins through clinical-strain differentiation and refrigerated supply chain premiums. Powder formulations lead in industrial procurement for bakery and dairy integration, while liquid fortification concentrates gain traction in beverage lines seeking clean-label dissolution.
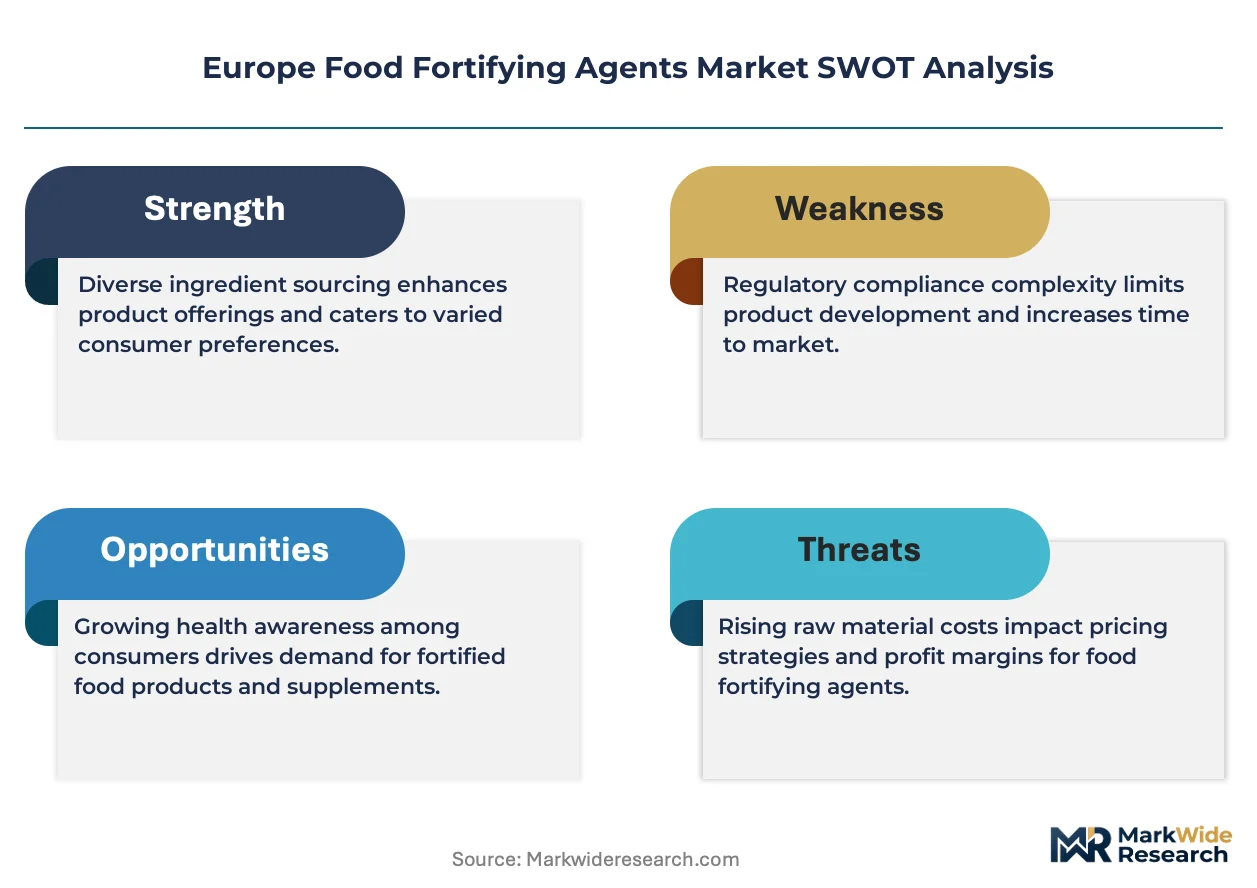
EFSA establishes maximum permitted levels for vitamins and minerals in fortified foods under the Food Supplements Directive, while the EU Green Deal's Farm to Fork strategy pressures formulators to eliminate synthetic additives in favor of bio-sourced alternatives. REACH compliance adds toxicity-testing burdens for novel amino acid derivatives entering the European market. Stakeholders must monitor EFSA's ongoing re-evaluation of additive safety panels and position supply chains for probable tightening of probiotic health claim substantiation requirements.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing timelines for synthetic-to-bio-sourced ingredient transitions, forcing reformulators to rebuild supply chains around precision fermentation and enzymatic synthesis platforms.
Growth Catalysts
- Mandatory Fortification Mandates:EU-wide flour and dairy fortification requirements under the Food Supplements Directive sustain baseline vitamin demand. Member states enforce compliance through national food safety authorities.
- Precision Fermentation Scale-Up:Bioactive compound production costs are collapsing as enzymatic synthesis replaces petrochemical routes. Contract manufacturers in the Netherlands and Denmark are expanding capacity.
- Clean-Label Premium Positioning:Western European retail channels reward transparent ingredient decks with preferential shelf placement. Bakery and beverage processors reformulate to capture this margin expansion.
Market Restraints
- REACH Toxicity Testing Burdens:Novel amino acid derivatives face extended safety evaluation timelines. ECHA compliance costs deter smaller innovators from European market entry.
- Probiotic Supply Concentration:Clinical-strain libraries remain concentrated among three dominant suppliers. Dairy processors face limited alternatives for ambient-stable probiotic formulations.
- Refrigerated Cold Chain Dependency:Probiotic viability requires temperature-controlled logistics. Energy cost volatility in Germany and France compresses margins on premium-positioned products.
Strategic Opportunities
- Central European Processing Expansion:Poland and Czech Republic dairy capacity is underpenetrated for micronutrient premix integration. Local processors seek technical partnerships with established premix suppliers.
- Sports Nutrition Fortification:Branched-chain amino acid and mineral blends for recovery beverages represent whitespace beyond traditional dairy. German fitness-focused retailers are expanding functional beverage SKUs.
- EFSA Health Claim Substantiation:Stricter probiotic claim requirements favor companies with clinical trial infrastructure. Early movers in strain-specific research secure defensible positioning.
Industry Challenges
- Encapsulation Engineering Talent Scarcity:Thermal-stable delivery systems for lipid-soluble vitamins require specialized formulation expertise. Food science programs produce insufficient graduates in this niche.
- Spray-Drying Equipment Lead Times:Industrial-scale drying capacity for heat-sensitive bioactives faces 18-month procurement backlogs. Capex commitments strain mid-tier processor balance sheets.
- Cross-Border Regulatory Divergence:National interpretations of EU directives create compliance fragmentation. Irish and UK post-Brexit regulatory misalignment complicates premix formulation standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Fortifying Agents Market |
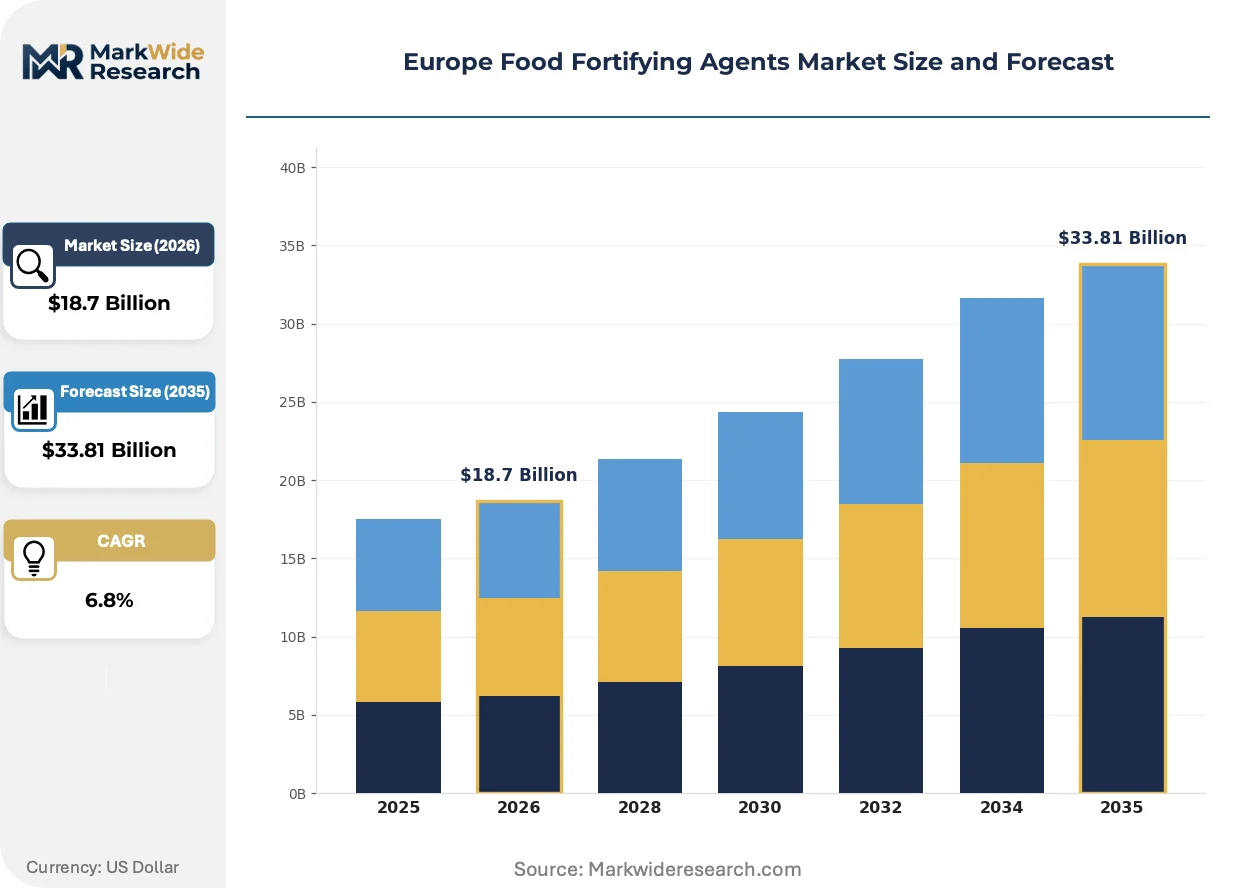
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Probiotics Formulation: Powder, Liquid, Granules, Capsules Application: Beverages, Dairy, Bakery, Snacks Distribution Channel: Online, Supermarkets, Health Stores, Convenience Stores |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, BASF SE, Kerry Group plc, Tate & Lyle PLC, Glanbia PLC, Ingredion Incorporated, Chr. Hansen Holding AS, DSM Nutritional Products, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Fortifying Agents Market Shifts & Advancements
Digital integration of fermentation monitoring and predictive quality control is compressing development cycles for next-generation fortifying agents. Three distinct vectors are reshaping competitive positioning.
Inline spectroscopy coupled with machine learning algorithms is digitizing real-time metabolite tracking during precision fermentation runs. Dutch contract manufacturers deploy these systems to reduce batch-to-batch variability in vitamin K2 production. Quality assurance teams now intercept deviations hours earlier than manual sampling permits, compressing time-to-certificate for EFSA submissions.
EFSA's ongoing re-evaluation of additive safety panels is tightening purity thresholds for synthetic vitamin carriers. The 2024 draft guidance on mineral bioavailability testing imposes additional clinical endpoint requirements. Italian and Spanish premix suppliers are restructuring analytical capabilities to meet accelerated substantiation timelines.
Direct-procurement platforms connecting dairy processors with fermentation specialists are disintermediating traditional ingredient distributors. Large cooperatives in France and Germany now contract bioactive production through dedicated supply agreements. This channel shift concentrates volume with vertically integrated suppliers capable of strain development through finished premix delivery.
Europe Food Fortifying Agents Market Segmentation
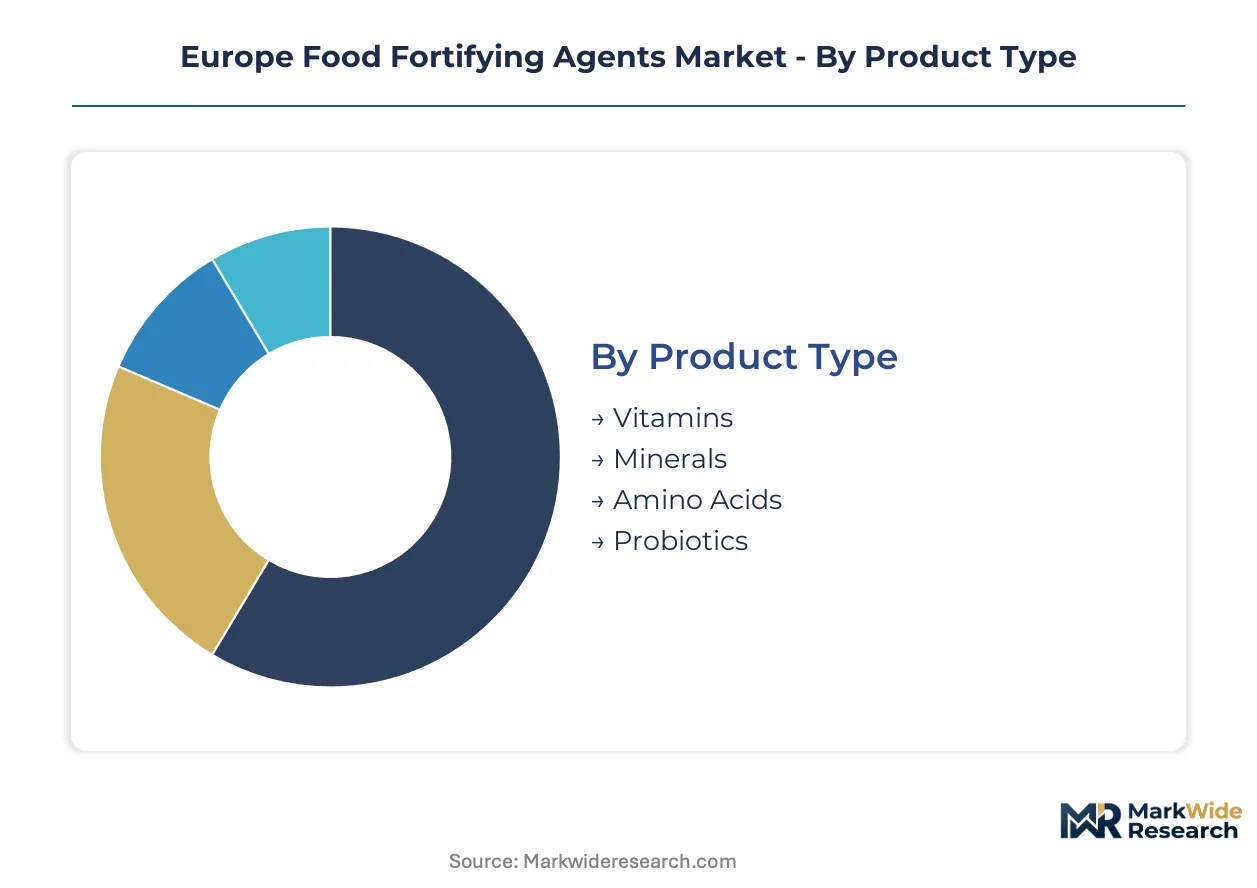
Segmentation in the Europe Food Fortifying Agents Market reveals how formulation chemistry, delivery mechanics, and channel economics create distinct competitive battlegrounds. Each dimension carries unique margin profiles and regulatory burdens that reshape supplier priorities across EU member states.
Product Type:
Product type segmentation tracks the use-case spectrum from mass fortification mandates to premium clinical positioning.
- Vitamins:Lipid-soluble (A, D, E, K) and water-soluble (B-complex, C) compounds dominate industrial procurement for flour and dairy fortification. German and French processors absorb the largest volumes under EU mandatory enrichment laws. Powder premixes for bakery integration sustain baseline demand despite margin compression from commodity pricing.
- Probiotics:Live microbial strains requiring refrigerated supply chains and clinical substantiation for health claims. Ambient-stable formulations from DSM and Kerry command premium positioning in Irish and UK beverage channels. Strain-specific intellectual property creates defensible margin pools that vitamin commodities cannot match.
- Minerals:Iron, zinc, calcium, and selenium compounds address deficiency correction in Central European processed foods.
- Amino Acids:Branched-chain and essential amino acid derivatives target sports nutrition and clinical nutrition applications.
The dominant share belongs to Vitamins, while Probiotics is closing the gap fastest.
Formulation:
Form choice reflects cost tier differentiation between industrial-scale processing and precision dosing requirements.
- Powder:Spray-dried and agglomerated formats integrate seamlessly into bakery doughs and dairy powders. Dutch contract manufacturers operate the largest European capacity for heat-sensitive bioactive drying. German dairy cooperatives specify powder premixes for standardized nutrient distribution across production batches.
- Liquid:Concentrates and emulsions dissolve rapidly in beverage matrices without sedimentation. French functional drink brands prefer liquid vitamin D and B12 for clean-label dissolution transparency. Precision fermentation-derived compounds increasingly enter market as liquid intermediates before downstream drying.
- Granules:Intermediate particle size for controlled-release applications in nutritional bars.
- Capsules:Unit-dose formats for direct-to-consumer supplement channels and clinical nutrition.
Powder formulations capture the volume base, yet Liquid concentrates are expanding most quickly in beverage applications.
Application:
Application segmentation follows customer type priorities from commodity food manufacturing to premium positioning.
- Dairy:Fluid milk, yogurt, and cheese fortification represents the most mature application with established premix supply relationships. Irish and UK processors lead probiotic integration for ambient drinkable yogurt. EFSA health claim substantiation requirements favor suppliers with clinical trial infrastructure serving this segment.
- Beverages:Functional waters, juices, and plant-based milks demand rapid-dissolution formats and transparent ingredient decks. German fitness-focused retailers are expanding branched-chain amino acid and mineral blend SKUs for recovery positioning. Clean-label premiums in Western European channels reward reformulation investments.
- Bakery:Mandatory flour fortification sustains baseline vitamin demand across EU member states.
- Snacks:Nutritional bars and fortified cereals target on-the-go consumption occasions.
Dairy retains the largest installed premix base, though Beverages is gaining share fastest through functional positioning.
Distribution Channel:
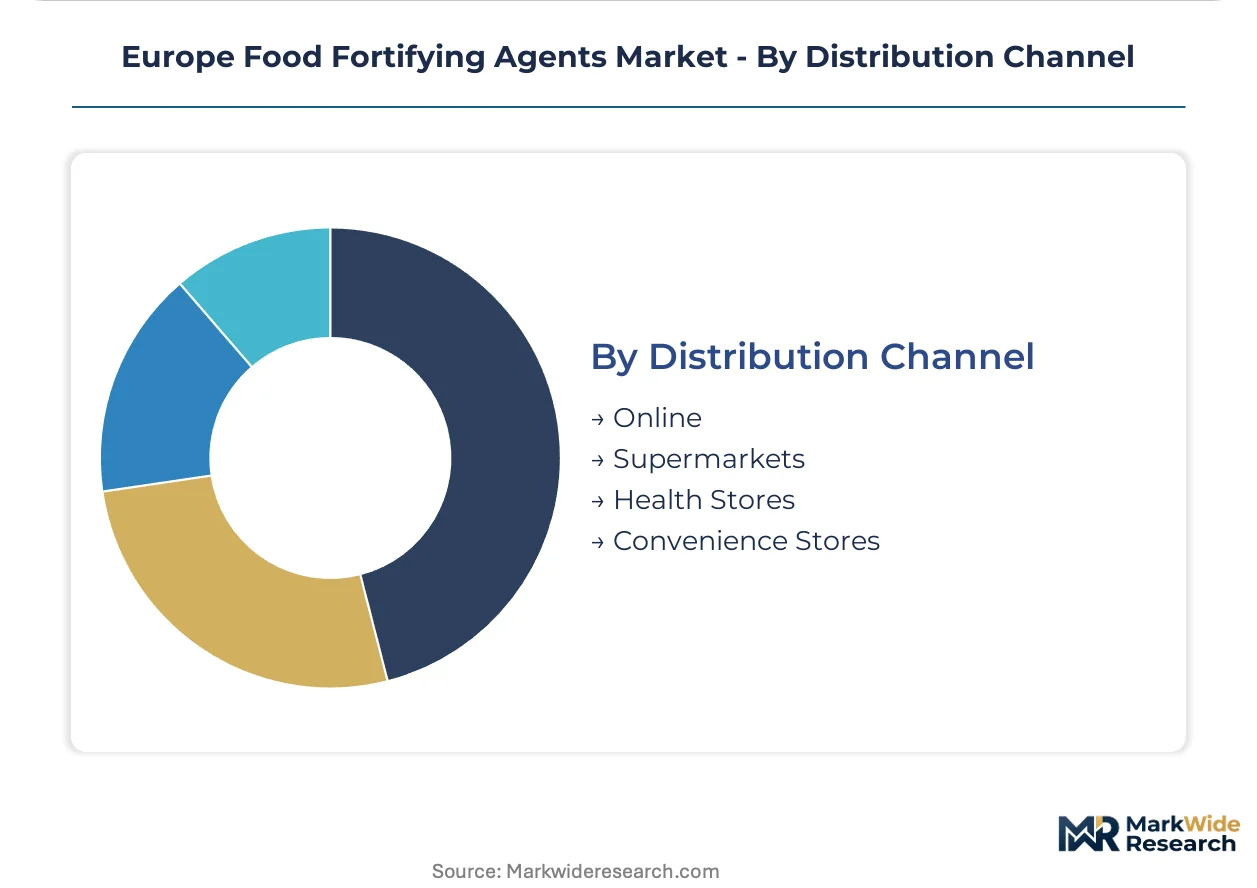
Channel segmentation maps supply concentration from direct procurement platforms to fragmented retail access.
- Supermarkets:Mass-market retail chains in France and Germany consolidate volume for standard fortification SKUs. Private-label expansion by Aldi and Lidl compresses branded premix margins while expanding total addressable volume. Shelf placement negotiations favor suppliers with EFSA-compliant health claim portfolios.
- Online:Direct-procurement platforms and B2B marketplaces are disintermediating traditional ingredient distributors. Large cooperatives now contract fermentation specialists through dedicated supply agreements. This channel shift concentrates volume with vertically integrated suppliers capable of strain development through finished premix delivery.
- Health Stores:Specialized retail for premium and clinical-grade fortification products.
- Convenience Stores:Impulse and single-serve fortified snack and beverage access.
Supermarkets command the current volume leadership, while Online channels are climbing the fastest through platform disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German premix exports supply dairy processors across Poland and the Czech Republic, establishing a north-south trade corridor that concentrates technical expertise in the Rhine-Ruhr industrial cluster while distributing formulated products into Central European manufacturing expansion zones.
Germany
Dairy cooperatives in Lower Saxony and Bavaria absorb the largest vitamin premix volumes under EU mandatory fortification laws. The Federal Office of Consumer Protection and Food Safety enforces BVL purity standards that exceed baseline EFSA thresholds. Ludwigshafen's chemical processing corridor anchors lipid-soluble vitamin production for export to neighboring member states.
France
Fluid milk and yogurt fortification drives sustained demand for ambient-stable probiotic formulations in the Île-de-France dairy belt. ANSM monitors health claim substantiation for clinical-grade strains entering the French market. Large cooperatives in Brittany and Normandy negotiate direct-procurement agreements that bypass traditional ingredient distributors.
United Kingdom
Irish Sea logistics connect UK beverage processors to DSM's strain development facilities for drinkable yogurt applications. Post-Brexit regulatory divergence from EFSA frameworks complicates premix standardization across the Irish border. Greater Manchester and West Midlands manufacturing zones concentrate functional beverage production capacity.
Netherlands
Contract fermentation specialists in the Randstad region operate Europe's largest precision fermentation capacity for bioactive vitamin K2 and novel amino acid derivatives. ECHA REACH compliance infrastructure in Rotterdam supports accelerated toxicity testing for innovators. Eindhoven's bioprocessing corridor attracts enzymatic synthesis scale-up investments from dairy-focused premix suppliers.
Poland
Central European dairy capacity expansion in Masovian and Greater Poland voivodeships creates underpenetrated demand for micronutrient premix technical partnerships. Polish Chief Sanitary Inspectorate alignment with EU Food Supplements Directive enables rapid regulatory clearance for imported formulations. Local processors seek knowledge-transfer agreements with established German and Dutch suppliers.
Europe Food Fortifying Agents Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a moderately consolidated structure where three to four integrated chemical-nutrition conglomerates anchor volume supply while mid-tier premix formulators capture margin through application-specific expertise. Strategic archetypes separate into precision fermentation platform operators, dairy-focused premix specialists, and diversified agricultural processors extending into nutritional ingredients. Dominant competitive moves include backward integration into strain development capabilities and geographic expansion through technical partnership structures rather than asset-heavy acquisitions.
Within the integrated chemical-nutrition tier, BASF SE and DSM Nutritional Products exemplify platform operators with captive fermentation infrastructure spanning vitamin and probiotic production. Kerry Group plc occupies a position as the dairy-specialist archetype, leveraging Irish processing channel relationships that concentrate premix formulation expertise for fluid milk and yogurt applications. These three entities collectively represent the supply concentration that limits alternative sourcing for ambient-stable clinical strains and lipid-soluble vitamin carriers.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| BASF SE |
| Kerry Group plc |
| Tate & Lyle PLC |
| Glanbia PLC |
| Ingredion Incorporated |
| Chr. Hansen Holding AS |
| DSM Nutritional Products |
| Others |
Supply & Pricing Matrix
Overcapacity in Dutch precision fermentation facilities is compressing contract manufacturing margins while simultaneously expanding pricing leverage for integrated vitamin suppliers with captive strain libraries. This utilization asymmetry rewards backward-integrated players like BASF SE and DSM Nutritional Products with premium capture on lipid-soluble vitamin carriers, while forcing toll manufacturers toward volume-based commodity positioning.
Pricing Analysis
Next-generation enzymatic synthesis platforms command 15-25% premiums over legacy petrochemical-derived bioactives, while first-generation precision fermentation outputs face margin erosion from capacity gluts in the Randstad region. Three-tier pricing structure across premium clinical-strain probiotics, standard vitamin premixes, and economy-grade mineral blends reflects certification-grade differentiation and EFSA health claim substantiation depth. Pricing pressure stems from energy cost volatility in German and French refrigerated logistics compressing probiotic viability premiums. Dairy cooperatives in Lower Saxony exhibit highest price sensitivity on commodity vitamin premixes, while Irish beverage processors absorb premium positioning for ambient-stable strain formulations.
Supply Chain Analysis
Upstream feedstock dependencies center on corn-derived dextrose for fermentation media and specialized nitrogen sources for microbial strain cultivation. Supply concentrates in the Netherlands, Germany, and Denmark for precision fermentation capacity, with lipid-soluble vitamin precursor chemicals anchored in the Ludwigshafen chemical corridor. Raw material exposures include energy-intensive spray-drying operations, clinical-strain master cell bank maintenance, and REACH-compliant encapsulation polymer supplies. Single-source vulnerability persists for ambient-stable probiotic strains controlled by three dominant suppliers. Distribution runs through direct-procurement platforms disintermediating traditional ingredient distributors, with large French and German cooperatives negotiating dedicated supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for premix formulation optimization and EFSA submission support are expanding faster than base ingredient sales, creating recurring-revenue attachment opportunities that reshape supplier economics. This service layer now represents the primary margin expansion vector for integrated players with regulatory affairs infrastructure.
For Market Incumbents: Pre-empt encroachment from enzymatic synthesis specialists by securing exclusive strain development partnerships with Dutch contract manufacturers. Lock in multi-year offtake agreements with Polish dairy processors before Central European capacity expansion matures. Prioritize EFSA health claim substantiation investment to defend premium positioning against commodity vitamin suppliers. For New Entrants and Emerging Players: Pursue technical partnership structures with Masovian and Greater Poland voivodeship dairy cooperatives seeking knowledge transfer on micronutrient integration. Target sports nutrition branched-chain amino acid blends for German fitness-focused retail channels as the most penetrable whitespace beyond traditional dairy applications. Lead with direct-procurement platform positioning to bypass established distributor relationships concentrated in Western European markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation platform operators as enzymatic synthesis achieves scale economies. Long-term viability favors vertically integrated suppliers with captive strain libraries through finished premix delivery capability. Acquisition target archetype: mid-tier premix formulators with EFSA submission track records and established dairy processor relationships. Signal to watch: EFSA draft guidance finalization on mineral bioavailability testing requirements as inflection indicator for analytical capability valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captive microbial libraries from DSM Nutritional Products reduce dependency on external clinical-strain suppliers. |
| EFSA Health Claim Substantiation Investment | Clinical trial infrastructure enables premium positioning for probiotic formulations in Irish and UK beverage channels. |
| Central European Technical Partnership Expansion | Knowledge-transfer agreements with Polish processors unlock underpenetrated dairy capacity in Masovian voivodeships. |
| Direct-Procurement Platform Deployment | Disintermediation of traditional distributors concentrates volume with vertically integrated fermentation-to-premix suppliers. |
| Precision Fermentation Capacity Scale-Up | Enzymatic synthesis investments in Eindhoven's bioprocessing corridor collapse bioactive compound production costs. |
Research Methodology
Cross-validation between executive interviews at premix formulators and customs data on vitamin and probiotic ingredient flows anchors the qualitative findings. Primary fieldwork engaged fermentation platform operators, dairy cooperative procurement directors, EFSA regulatory affairs consultants, and Dutch contract manufacturing executives. Secondary validation drew from REACH registration databases, EU Food Supplements Directive implementation reports, and Cefic chemical industry statistics. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the European food manufacturing sector.
Calibration against historical premix adoption curves in mature dairy markets and emerging Central European processing zones shaped the analytical framework. Segmentation dimensions modeled include product type chemistry, formulation mechanics, application end-use, and distribution channel structure across the projection horizon. CAGRs derived from elasticity-adjusted volume projections incorporating EFSA regulatory timeline assumptions and precision fermentation cost curve trajectories. Industry-specific forecast inputs encompassed energy cost volatility scenarios for refrigerated logistics and ECHA toxicity testing backlog estimates.
Sensitivities concentrate around EFSA health claim substantiation timeline delays, REACH compliance cost escalations for novel amino acid derivatives, and probiotic cold chain disruption events. Forecasts embed assumptions on Farm to Fork synthetic-to-bio-sourced transition pace and precision fermentation scale-up economics. Cross-checking against Cefic chemical production statistics and national food safety authority enforcement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin D Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Asia-Pacific Food Fortifying Agent Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Fortified Breakfast Spreads Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Retinyl Linoleate Market
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
Vitamin Yeast Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Vitamin B Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Fortified Cereal Market