
 Retinyl Linoleate Market | 2026-2036
Retinyl Linoleate Market Size, Share, and Industry Trends Forecast 2026-2036
Retinyl Linoleate Market Analytics
Modular formulation kits that separate active retinyl linoleate from carrier emollients are restructuring how cosmetic manufacturers evaluate supplier partnerships. Eastman leverages its backward integration into specialty ester chemistry to sustain formulation consistency across North American and Asian accounts. BASF SE differentiates through pharmaceutical-grade certification pipelines that anchor its position in regulated dermal therapeutic markets.
Retinyl linoleate constitutes an ester conjugate of retinol and linoleic acid, typically synthesized through enzymatic or chemical esterification to yield a lipid-soluble vitamin A derivative with enhanced oxidative stability and cutaneous penetration profiles. The compound serves primarily as an active ingredient in topical dermatological preparations and nutricosmetic formulations targeting photoaging and barrier repair. Cosmetic-grade supply chains occupy the largest volume position, though pharmaceutical-grade segments command superior margin pools due to compendial testing burdens and GMP documentation requirements. Anti-aging applications lead value contribution within the application taxonomy, while dietary supplement channels represent the fastest-growing demand vector as ingestible beauty protocols gain traction in Asia-Pacific markets.
EU REACH restrictions on retinoid concentration limits in cosmetic preparations, coupled with FDA oversight of retinoid labeling in over-the-counter dermatological products, shape product development thresholds and regional market access conditions. South Korea's MFDS and China's NMPA maintain distinct filing pathways for retinoid-containing cosmeceuticals that fragment registration strategies for multinational suppliers. Stakeholders must monitor divergence between pharmaceutical and cosmetic regulatory classifications as this boundary increasingly determines pricing power and channel eligibility across major consumption markets.
Market Dynamics
EU REACH concentration limits on cosmetic retinoids are forcing formulators to recalibrate active ingredient sourcing strategies, while South Korean cosmetic manufacturers accelerate pharmaceutical-grade certification to access premium dermal therapeutic channels.
Growth Catalysts
- MFDS cosmeceutical pathways:South Korea's distinct filing routes for retinoid-containing products enable faster market entry for compliant suppliers targeting K-beauty export channels.
- Enzymatic esterification advances:Biocatalytic synthesis methods reduce oxidative degradation during production, improving batch consistency for pharmaceutical-grade specifications.
- Nutricosmetic protocols:Ingestible beauty applications across Asia-Pacific markets expand addressable demand beyond topical dermatology into dietary supplement formulations.
Market Restraints
- Linoleic acid feedstock volatility:Fluctuations in safflower and sunflower oil commodity markets compress margin predictability for ester manufacturers.
- GMP documentation burdens:Pharmaceutical-grade segments require extensive compendial testing that extends qualification timelines and raises capital barriers.
- Retinol derivative substitution:Retinyl palmitate and retinyl acetate alternatives compete on cost in mass-market cosmetic applications where penetration speed matters less.
Strategic Opportunities
- Modular formulation architectures:Kit-based systems separating active retinyl linoleate from carrier emollients enable just-in-time compounding and reduce stability risk during distribution.
- China NMPA dual-track registration:Cosmetic and pharmaceutical classification flexibility allows positioning arbitrage between regulated dermal therapeutic and premium cosmeceutical channels.
- Barrier repair indications:Ceramide-retinoid combination therapies for atopic dermatitis and post-procedure recovery expand clinical prescription potential beyond photoaging.
Industry Challenges
- Analytical method standardization:Inconsistent HPLC assay protocols across compendia complicate multi-jurisdictional product registration and batch release procedures.
- Cold chain integrity:Temperature-sensitive ester stability requires validated logistics infrastructure that many regional distributors lack, limiting market access in emerging consumption clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinyl Linoleate Market |
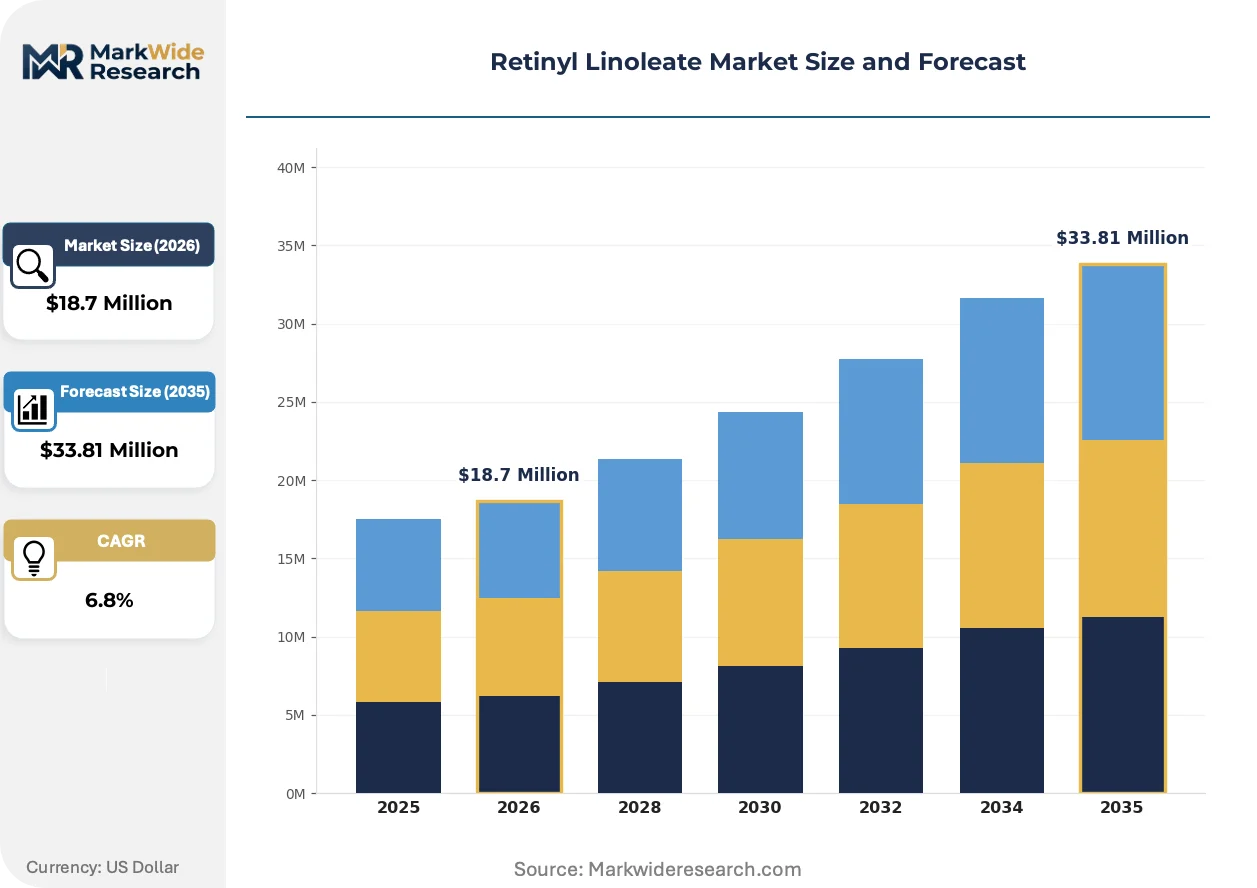
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $33.81 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Pharmaceutical Grade, Industrial Grade, Nutraceutical Grade Application: Skin Care, Hair Care, Dietary Supplements, Anti-Aging Distribution Channel: Online Retail, Specialty Stores, Pharmacy Chains, Direct Sales End User: Cosmetic Manufacturers, Pharmaceutical Companies, Dietary Supplement Providers, Research Institutions |
| Companies Covered | Eastman, Nikkol, Macrocare Tech, BASF SE, DSM, Archer Daniels Midland Company, Tri-K Industries Inc., Mitsubishi Chemical Foods Corporation, Guangzhou ZIO Chemical Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinyl Linoleate Market Evolving Landscape
Active ingredient delivery systems are undergoing functional redesign as oxidative stability requirements clash with consumer preference for minimalist ingredient lists, forcing innovation at the formulation architecture level.
Liposomal encapsulation technology is converging with solid lipid nanoparticle platforms to create hybrid delivery vehicles that protect retinyl linoleate from degradation while enabling controlled release kinetics. Pharmaceutical-grade manufacturers in Germany and Switzerland are adopting these systems for dermal therapeutic applications where bioavailability thresholds determine reimbursement eligibility. The convergence is compressing competitive differentiation around shelf-life extension claims and shifting procurement criteria toward validated stability data packages.
EU REACH Annex XVII restrictions on retinoid concentrations in leave-on cosmetic products are narrowing formulation flexibility for European brands and redirecting R&D investment toward rinse-off and encapsulated formats. The regulation's 2025 enforcement timeline has triggered reformulation cycles across mass-market skincare lines previously reliant on higher active loadings. Compliance costs are concentrating volume among suppliers with dedicated regulatory affairs capabilities and existing pharmaceutical-grade infrastructure.
Ingredient sourcing decisions now prioritize backward-integrated ester manufacturers with captive retinol and fatty acid production, reflecting buyer risk aversion to multi-tier supply chains. Cosmetic formulators in Japan and South Korea are consolidating supplier panels and demanding direct access to synthesis records and stability studies. This consolidation is most visible in premium anti-aging segments where brand equity depends on traceable quality credentials rather than commodity pricing.
Retinyl Linoleate Market Segmentation
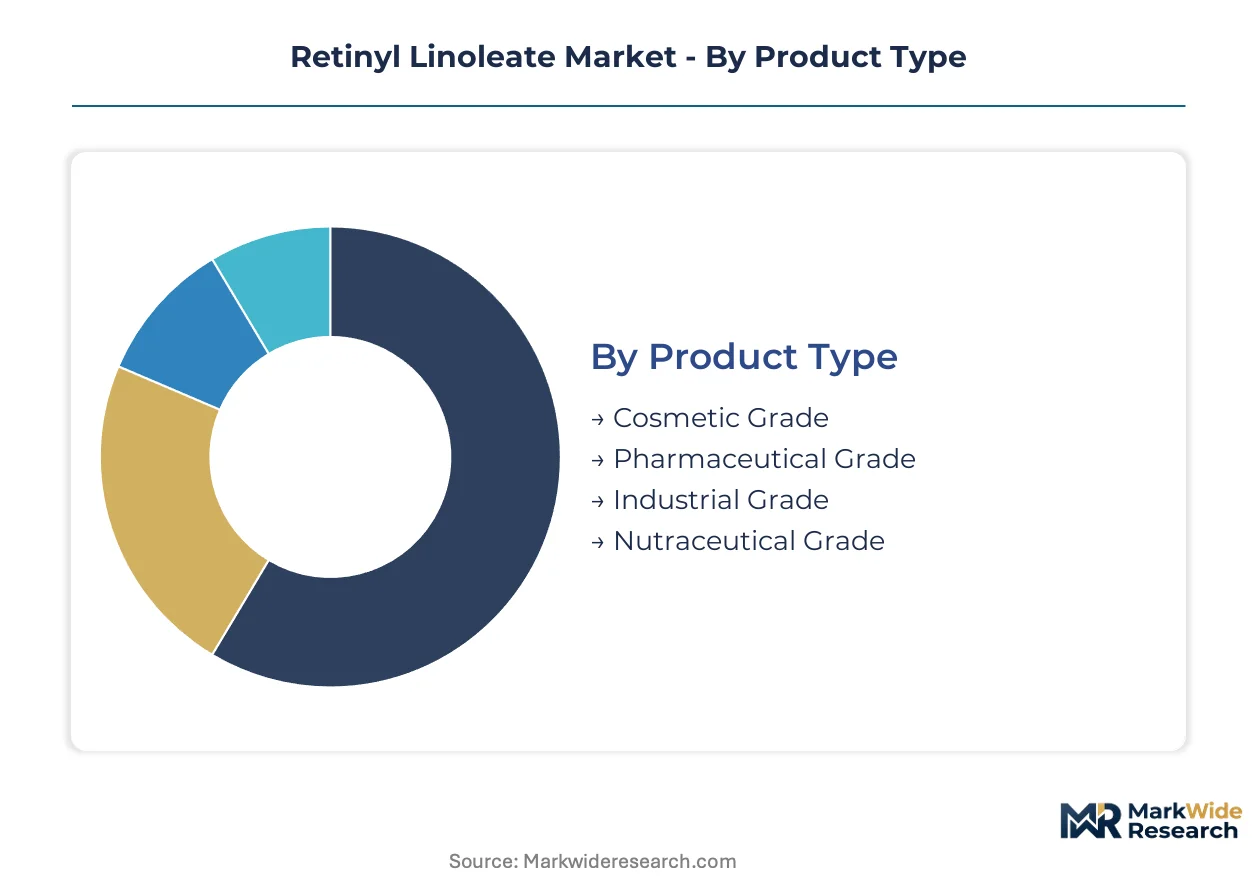
Retinyl linoleate procurement patterns diverge sharply across certification tiers, with pharmaceutical-grade specifications commanding distinct supplier qualification protocols. Channel selection and end-user sophistication further fragment addressable demand pools.
Product Type:
Customization intensity spans from commodity industrial esters to fully documented pharmaceutical batches requiring GMP compliance.
- Cosmetic Grade:Standardized ester concentrations between 0.1-2.0% serve mass-market skincare formulations. South Korean manufacturers drive volume through K-beauty export channels, though EU REACH concentration ceilings are compressing formulation flexibility.
- Pharmaceutical Grade:Compendial-grade material meets USP/EP monographs with full batch documentation and stability validation. German and Swiss dermal therapeutic manufacturers anchor demand as reimbursement eligibility hinges on bioavailability thresholds.
- Industrial Grade:Bulk ester intermediates for non-dermatological chemical synthesis.
- Nutraceutical Grade:Ingestible-specification retinyl linoleate for Asia-Pacific beauty-from-within formulations.
Most installed capacity flows through cosmetic-grade specifications. Expansion is steepest in pharmaceutical-grade segments.
Application:
Functional performance requirements separate rinse-off formats from leave-on therapeutic protocols demanding extended stability windows.
- Anti-Aging:High-potency retinoid serums and targeted wrinkle treatments utilize 0.3-1.0% active loadings. Japanese prestige brands sustain premium positioning through encapsulated delivery systems that extend shelf life beyond 24 months.
- Skin Care:Broad-category moisturizers and cleansers incorporate lower retinoid concentrations for daily use tolerance. Chinese domestic brands are gaining share fastest through e-commerce direct-to-consumer distribution.
- Hair Care:Scalp treatments and follicle-stimulating formulations.
- Dietary Supplements:Softgel and liquid nutricosmetic preparations.
Anti-aging applications command the highest value per kilogram. Dietary supplements are climbing the fastest as ingestible protocols proliferate.
Distribution Channel:
Cold-chain capabilities and regulatory documentation depth determine channel viability across temperature-sensitive ester shipments.
- Pharmacy Chains:Regulated dermal therapeutic products require pharmacist-mediated distribution with prescription or pharmacy-only classification. German and French pharmacy networks maintain strict cold-storage protocols for retinoid stability.
- Specialty Stores:Prestige beauty retailers and dermatology clinics stock professional-grade formulations. South Korean duty-free channels and Japanese department store beauty halls concentrate high-margin transactions.
- Online Retail:Direct-to-consumer platforms with temperature-controlled logistics.
- Direct Sales:Manufacturer-to-formulator bulk contracts with technical support.
Pharmacy chains handle the most regulated volume. Online retail is expanding most quickly through subscription replenishment models.
End User:
Technical sophistication and quality documentation requirements stratify procurement behavior across buyer categories.
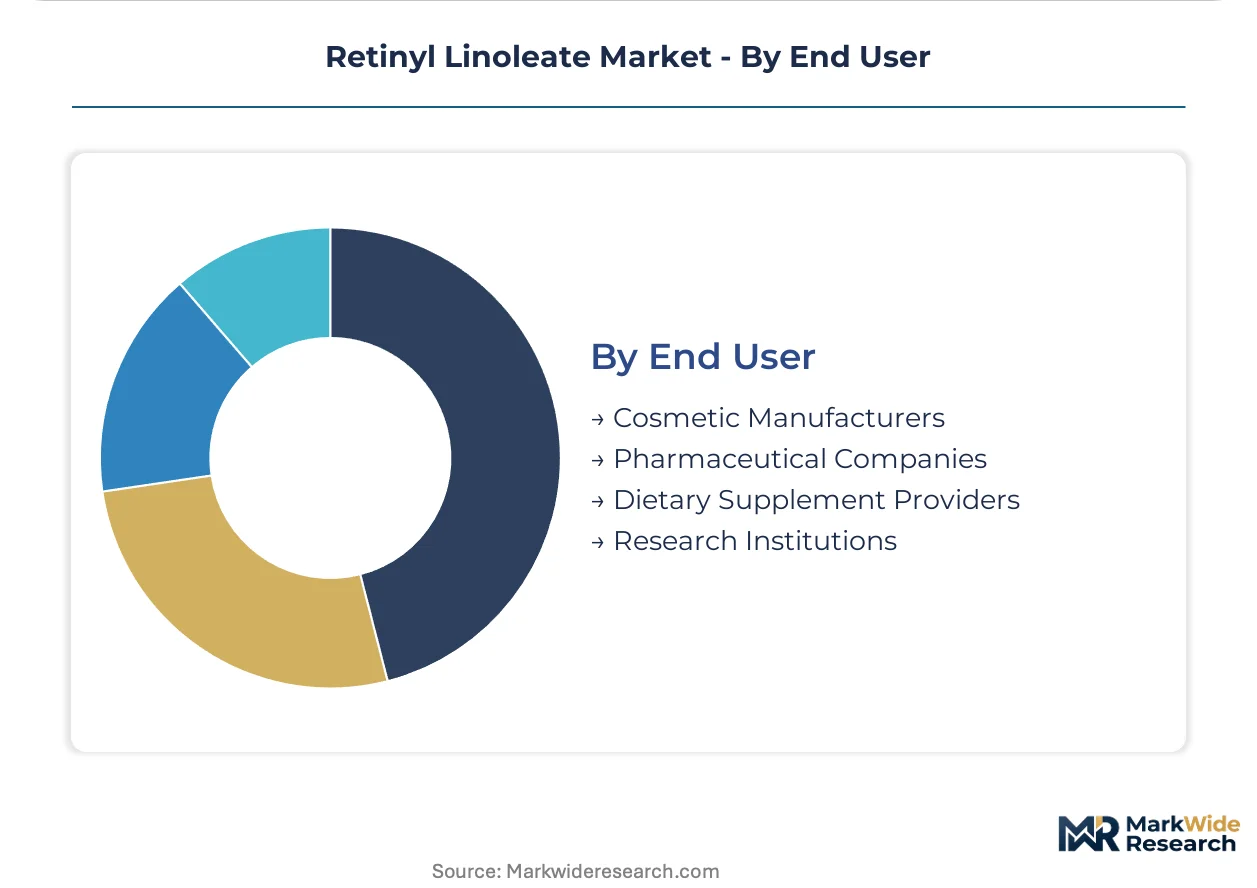
- Cosmetic Manufacturers:Brand owners and contract manufacturers formulate finished skincare products. Large South Korean and Japanese houses consolidate supplier panels and demand direct synthesis record access.
- Pharmaceutical Companies:Dermal therapeutic developers require full CMC documentation and stability data packages. Swiss and German firms lead in ceramide-retinoid combination therapies for atopic dermatitis.
- Dietary Supplement Providers:Nutricosmetic formulators seeking ingestible-grade supply.
- Research Institutions:Academic and clinical trial material sourcing.
Cosmetic manufacturers absorb the largest volume share. Pharmaceutical companies are gaining share fastest as prescription retinoid therapies expand indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered pharmaceutical-grade retinoid ester synthesis during the post-war chemical industry expansion. Swiss dermal therapeutic manufacturers later refined GMP-compliant production protocols. South Korean cosmetic houses now drive volume growth through K-beauty export channels.
Germany
Dermal therapeutic developers in Baden-Württemberg and North Rhine-Westphalia anchor pharmaceutical-grade demand for ceramide-retinoid combinations. EMA oversight of retinoid-containing medicinal products shapes registration timelines and bioavailability documentation requirements. The Basel-Ludwigshafen chemical corridor concentrates backward-integrated ester manufacturers with captive fatty acid supply.
South Korea
Seoul-based cosmetic conglomerates and Busan-Ulsan contract manufacturers absorb the largest cosmetic-grade volumes for anti-aging export formulations. MFDS cosmeceutical filing pathways enable faster market entry for retinoid-containing products than pharmaceutical routes. Incheon's free economic zone hosts temperature-controlled logistics hubs serving duty-free retail channels across Asia-Pacific.
United States
New Jersey and California formulation houses drive demand for modular retinyl linoleate kits separating actives from carrier emollients. FDA labeling requirements for over-the-counter retinoid dermatological products dictate concentration disclosures and stability testing burdens. The Boston-Cambridge biotech cluster incubates barrier repair therapies combining retinoids with ceramide analogues.
Switzerland
Basel and Zurich pharmaceutical developers command premium pricing for USP/EP-grade retinyl linoleate in prescription dermal indications. Swissmedic maintains distinct quality documentation requirements that exceed standard cosmetic-grade specifications. The Lake Geneva region concentrates nutricosmetic innovators developing ingestible retinoid-linoleic acid complexes.
Japan
Tokyo and Osaka prestige beauty brands sustain encapsulated retinyl linoleate demand through 24-month shelf-life positioning. METI oversight of quasi-drug classifications creates regulatory arbitrage between cosmetic and mild therapeutic retinoid claims. The Kansai industrial belt houses specialty ester fabricators serving domestic pharmaceutical and export cosmetic channels.
Retinyl Linoleate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade segmentation, with pharmaceutical-grade specifications commanding three-to-four-fold price multiples over cosmetic-grade equivalents. The vendor base stratifies into three tiers: backward-integrated chemical conglomerates with captive retinol supply, specialist ester houses focused on cosmetic-grade volume, and pharmaceutical-certified manufacturers with full GMP documentation capabilities. Capacity expansion and regulatory certification acceleration represent the dominant competitive moves as EU REACH enforcement compresses formulation flexibility.
Among the backward-integrated chemical conglomerates, Eastman and BASF SE exemplify archetypes with in-house specialty ester chemistry capabilities. DSM occupies a position bridging pharmaceutical-grade certification and nutricosmetic-grade supply for Asia-Pacific ingestible beauty protocols. These three entities anchor the premium-tier competitive vector where formulation consistency and batch documentation determine supplier selection.
| Leading Market Players |
|---|
| Eastman |
| Nikkol |
| Macrocare Tech |
| BASF SE |
| DSM |
| Archer Daniels Midland Company |
| Tri-K Industries Inc. |
| Mitsubishi Chemical Foods Corporation |
| Guangzhou ZIO Chemical Co., Ltd |
| Others |
Value Network & Pricing Analysis
EU REACH Annex XVII enforcement on retinoid concentration limits gates qualified supply access and premium-tier pricing power, forcing cosmetic formulators toward pharmaceutical-certified suppliers with validated stability documentation. Buyers lacking backward-integrated ester chemistry face margin compression as GMP-compliant batches command three-to-four-fold multiples over commodity cosmetic grades.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades separates value pools by certification burden and documentation depth. Price differentiation hinges on USP/EP monograph compliance and captive retinol supply, with pharmaceutical-grade manufacturers in Germany and Switzerland extracting premiums through batch validation services. Pricing pressure stems from retinyl palmitate substitution in mass-market applications where penetration speed matters less. Contract manufacturers in South Korea exhibit highest price sensitivity, while Swiss dermal therapeutic developers prioritize stability data over unit cost.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for cosmetic formulators in Japan and South Korea, reducing single-source dependency on German and Chinese ester houses. Geographic supply concentrates in Germany, China, and South Korea, with the Basel-Ludwigshafen corridor anchoring pharmaceutical-grade capacity. Raw material dependencies center on safflower oil, sunflower oil, and retinol feedstocks vulnerable to agricultural commodity swings. Supply chain risk manifests in cold-chain integrity failures during Asia-Pacific distribution. Distribution runs through direct manufacturer-to-formulator contracts with technical support, bypassing commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through enzymatic esterification cost-downs and pharmaceutical-grade certification premiums that displace commodity cosmetic supply.
For Market Incumbents: Deploy backward integration into specialty ester chemistry to defend against retinyl palmitate substitution in mass-market channels. Eastman and BASF SE anchor this strategy through captive retinol production. Capacity expansion in South Korea's Busan-Ulsan corridor captures K-beauty export volume. Pharmaceutical-grade certification investment insulates pricing power as EU REACH enforcement compresses formulation flexibility for uncertified competitors. For New Entrants and Emerging Players: Biocatalytic synthesis methods offer technology-first entry into pharmaceutical-grade segments where batch consistency determines supplier qualification. Nutricosmetic-grade supply for Asia-Pacific ingestible beauty protocols represents the most penetrable white space, with Chinese domestic brands gaining share fastest through e-commerce direct-to-consumer distribution. Target modular formulation kit architectures that separate active retinyl linoleate from carrier emollients, enabling just-in-time compounding services. For Investors and Strategic Acquirers: Roll-up economics work for pharmaceutical-certified ester manufacturers because regulatory documentation burdens create insurmountable capital barriers for greenfield entrants. The five-to-ten-year viability window favors acquisition of Swiss and German GMP-compliant facilities with existing USP/EP monograph coverage. Watch for MFDS cosmeceutical filing acceleration as the signal indicating premium channel access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | EMA and FDA documentation requirements anchor pricing power in regulated dermal therapeutic channels. |
| Backward Integration into Retinol Supply | Captive production of vitamin A feedstock insulates margin from agricultural commodity volatility. |
| Enzymatic Esterification Scale-Up | Biocatalytic methods reduce oxidative degradation during synthesis, improving batch consistency for pharmaceutical specifications. |
| Modular Formulation Kit Development | Kit-based systems enable just-in-time compounding for cosmetic manufacturers seeking stability risk reduction. |
| Asia-Pacific Nutricosmetic Channel Entry | MFDS and NMPA pathways for ingestible retinoid formulations expand addressable demand beyond topical applications. |
Research Methodology
Coverage spans Germany, South Korea, Switzerland, the United States, and Japan, with primary inputs from each market cluster combined with secondary validation. Interviews engaged cosmetic formulation chemists, pharmaceutical regulatory affairs directors, ester plant operations managers, and duty-free retail procurement heads. Secondary sources included EMA retinoid guidance documents, MFDS cosmeceutical filing databases, SEC 10-K disclosures from chemical conglomerates, and customs trade records for retinol derivative flows. Bottom-up capacity modeling triangulated against top-down consumption estimates across certification tiers.
Rate-of-change decomposition structured the analytical framework across the projection horizon, segmenting by grade tier, application function, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating substitution effects from retinyl palmitate and retinyl acetate alternatives. Forecast inputs captured enzymatic esterification yield improvements, EU REACH enforcement timelines, and K-beauty export channel expansion rates.
The model holds under stable linoleic acid feedstock availability and sustained pharmaceutical-grade certification demand; deviation in safflower or sunflower oil commodity spikes, or accelerated retinoid derivative substitution in mass-market cosmetics, would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin E Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Global Quercetin Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Food Grade Vitamin B1 Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Europe Food Fortifying Agents Market
Vitamin Fortified
Calcium-Fortified Food Market
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
Food Fortification Market
Vitamin Fortified
High Calcium Fortified Food Market
Vitamin Fortified
Calcium-Fortified Cereals Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Global Fortified Yogurt Market
Vitamin Fortified
Multivitamin Gummies Market