
 Food Grade Retinol (Retinene) Market | 2026-2036
Food Grade Retinol (Retinene) Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Retinol (Retinene) Market Insights
Skilled organic synthesis chemists familiar with stereospecific isomerization protocols is collapsing across Western Europe and coastal China, constraining batch consistency at multi-ton food-grade retinol facilities. BASF SE leverages its Ludwigshafen integrated vitamin A complex to sustain captive supply of crystalline retinol acetate for fortification premixes. DSM Nutritional Products anchors its competitive position through biotechnology-derived beta-carotene conversion routes that reduce petrochemical feedstock exposure. Zhejiang Medicine Co. Ltd competes on fermentation-scale economics while navigating stricter export certification requirements for food-active compounds.
Food grade retinol denotes all-trans-retinol and its pro-vitamin A esters manufactured under food additive purity specifications, typically achieving minimum assay values of 1.0 million IU per gram through controlled alkali saponification of fish liver oils or synthetic beta-ionone cyclization. The compound functions primarily as a micronutrient fortificant in edible oils, dairy analogs, and meal replacement beverages targeting vitamin A deficiency intervention programs. Powder formulations dominate institutional procurement channels due to superior flowability in high-speed blending equipment and extended shelf stability under nitrogen flushing. Liquid retinol concentrates command premium positioning within dietary supplements where dose precision and bioavailability enhancement through emulsification technology differentiate finished products.
The European Food Safety Authority establishes maximum permitted levels for retinol in fortified foods under Regulation 1925/2006, while the FDA governs GRAS notifications for synthetic vitamin A additions through its Office of Food Additive Safety. China's National Health Commission mandates GB 14880 compliance for vitamin A fortification in domestic food matrices, creating divergent specification requirements for exporters. India's FSSAI recently aligned with Codex Alimentarius retinol potency standards, reducing technical barriers for premix imports but intensifying local testing obligations. Stakeholders must monitor evolving maximum level harmonization between EFSA and FDA frameworks while building dual-certified manufacturing lines capable of serving both regulatory jurisdictions without reformulation delays.
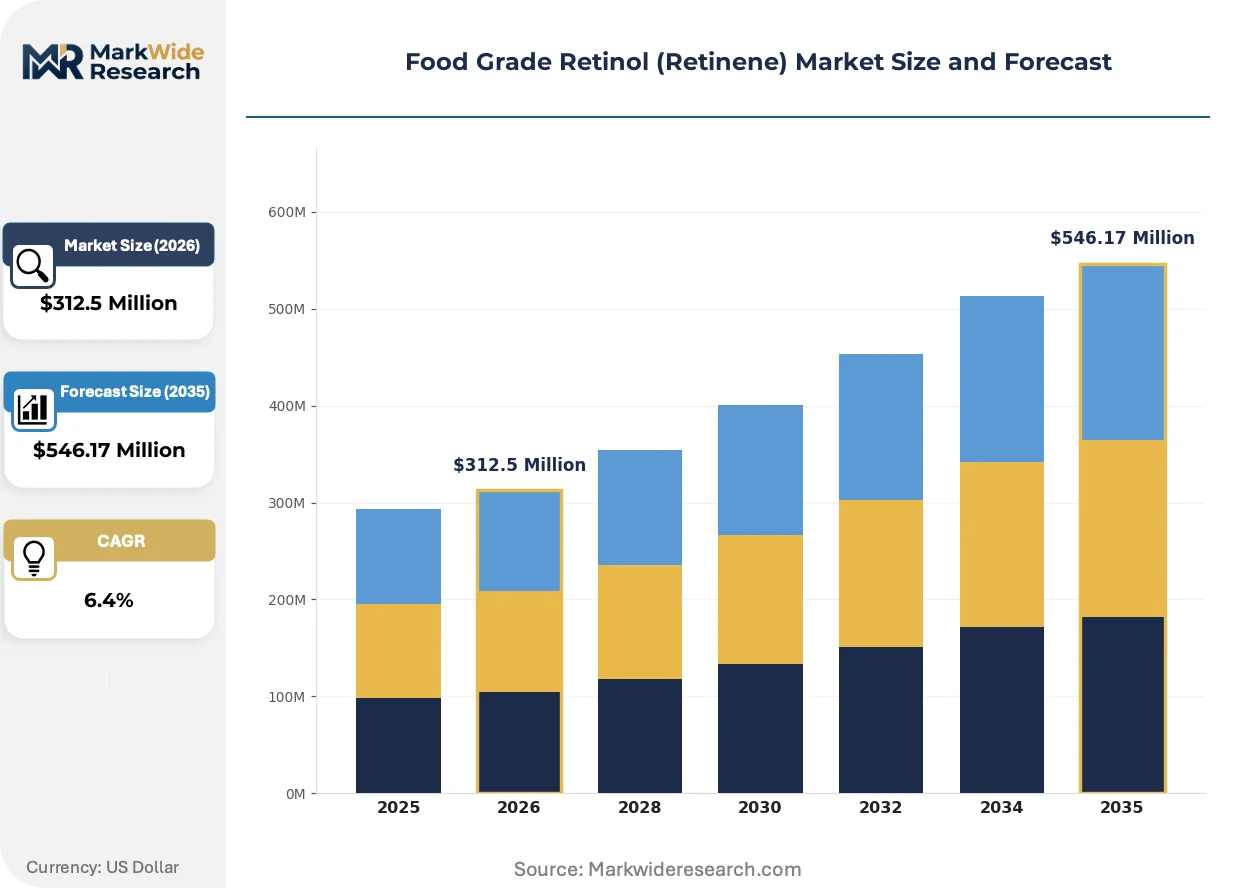
Market Dynamics
Food-grade retinol production is tightening around stereospecific synthesis capabilities as EFSA purity thresholds eliminate marginal producers and concentrate supply among integrated chemical complexes with captive beta-ionone supply chains.
Growth Catalysts
- Vitamin A deficiency intervention mandates:National fortification programs in sub-Saharan Africa and South Asia are expanding procurement of high-potency retinol premixes for edible oil fortification, with WHO guidelines driving institutional purchasing volumes.
- Geriatric nutrition formulation expansion:Functional food manufacturers in Germany and the United States are accelerating retinol fortification in meal replacement beverages targeting sarcopenia and immune function in aging populations.
- Biotechnology conversion efficiency gains:Fermentation-derived beta-carotene isomerization routes are reducing petrochemical feedstock dependency and improving batch-to-batch potency consistency for food-active vitamin A.
Market Restraints
- Stereospecific chemist scarcity:The collapsing pipeline of organic synthesis specialists trained in controlled isomerization protocols is constraining multi-ton batch consistency at Western European and coastal Chinese production facilities.
- Dual certification cost burden:Divergent EFSA and FDA maximum permitted level frameworks force manufacturers to maintain separate formulation lines or absorb reformulation delays, elevating compliance overhead.
- Natural carotenoid substitution pressure:Food marketers in premium positioning segments are displacing synthetic retinol with beta-carotene and mixed carotenoid complexes in clean-label formulations.
Strategic Opportunities
- India FSSAI alignment with Codex:Reduced technical barriers for premix imports are opening institutional procurement channels for exporters with dual-certified manufacturing infrastructure.
- Powder-to-liquid formulation pivot:Emulsification technology advances are enabling dose-precision liquid concentrates for dietary supplement channels, commanding premium positioning beyond institutional powder markets.
- China GB 14880 compliance arbitrage:Domestic fortification mandates are creating demand for food-grade retinol premixes that meet both Chinese and export-market specifications simultaneously.
Industry Challenges
- Alkali saponification scale-up complexity:Controlled hydrolysis of fish liver oils to achieve 1.0 million IU per gram assay values requires capital-intensive reactor infrastructure that smaller producers cannot finance.
- Novel food ingredient dossier timelines:EFSA's tightened purity documentation requirements are extending approval cycles for new retinol derivative formats, compressing first-mover advantage windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Retinol (Retinene) Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Gel, Capsule Application: Dietary Supplements, Skincare Products, Nutraceuticals, Food Additives Grade: Pharmaceutical Grade, Cosmetic Grade, Food Grade, Industrial Grade Distribution Channel: Online Retail, Wholesale, Pharmacy, Supermarket |
| Companies Covered | BASF SE, DSM Nutritional Products, Archer Daniels Midland Company, Eastman Chemical Company, Adisseo, Merck KGaA, Zhejiang Medicine Co. Ltd, Kingdomway Nutrition Inc., Nutraceutical International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Retinol (Retinene) Market Trends and Innovations
Biotechnology-derived production routes and emulsification delivery systems are restructuring competitive positioning in food-grade retinol, while regulatory divergence between major jurisdictions is forcing manufacturing architecture decisions that will persist through the forecast window.
Microencapsulation via spray-drying with modified starch or gelatin matrices is supplanting traditional cold-water-dispersible powder formulations in high-speed blending applications. Dairy analog manufacturers in Germany and the Netherlands are adopting these stabilized formats to extend shelf life under ambient storage conditions. The technology is compressing working capital requirements by reducing nitrogen-flushed packaging dependency and enabling just-in-time premix delivery models.
EFSA's updated novel food ingredient guidelines under Regulation 1925/2006 are tightening purity thresholds for vitamin A derivatives entering the European food chain. Manufacturers must now demonstrate sub-ppm contaminant profiles that exceed previous pharmaceutical-grade specifications, forcing capital expenditure on analytical infrastructure. The German market, anchored by BASF SE's Ludwigshafen complex, is absorbing these compliance costs through integrated production economics that marginal producers cannot replicate.
Institutional procurement for vitamin A deficiency programs is consolidating around pre-qualified supplier registries that certify manufacturing audit trails and batch documentation. UNICEF and WHO procurement channels are displacing spot-market purchasing with multi-year framework agreements that lock in supply security. This concentration is most visible in sub-Saharan Africa, where national fortification programs are standardizing on three to four approved premix suppliers per territory.
Food Grade Retinol (Retinene) Market Segmentation
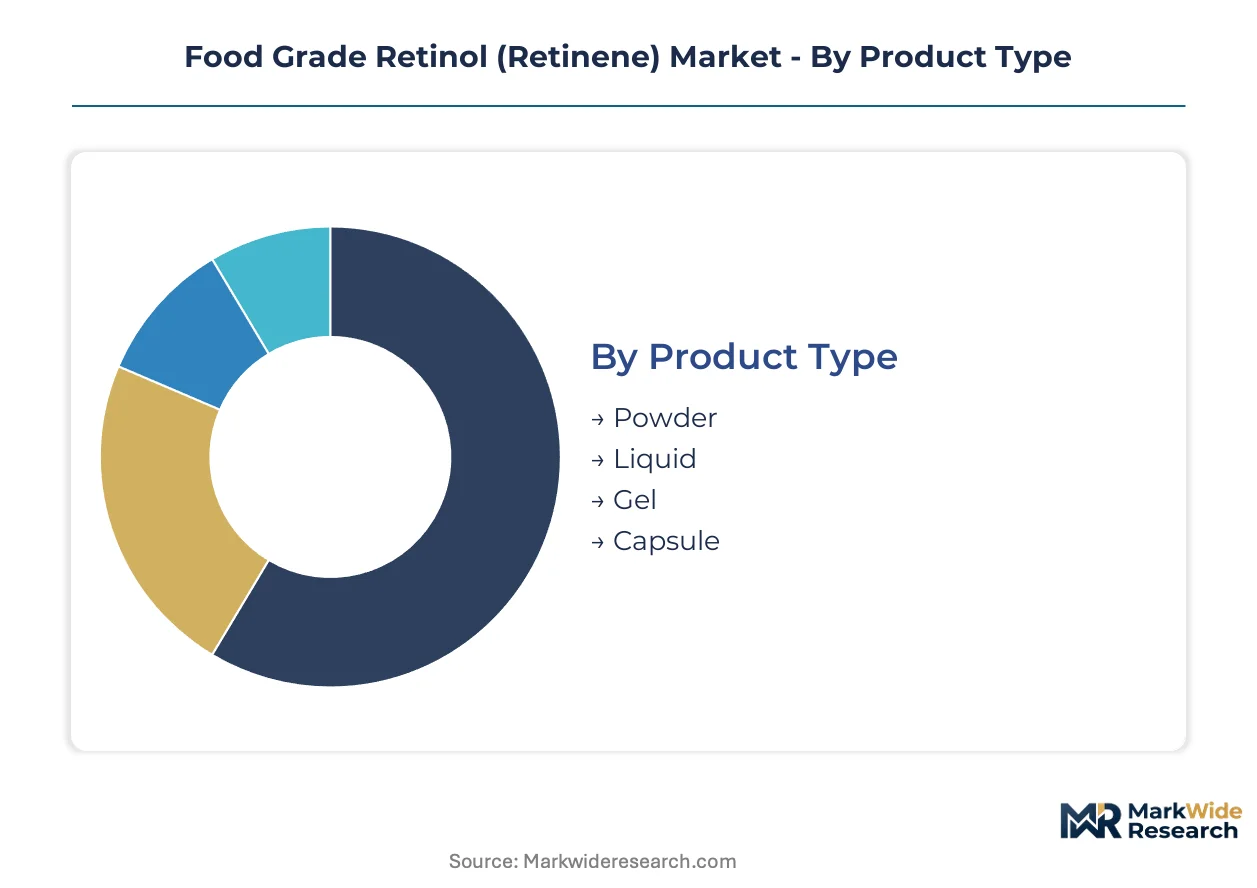
Food-grade retinol segmentation reflects divergent purity requirements and delivery-system economics across fortification channels. Each dimension carries distinct substitution vulnerabilities and regulatory exposure that reshape supplier priorities.
Product Type:
Powder and liquid formats face divergent substitution pressures from natural carotenoid complexes in premium positioning segments.
- Powder:Cold-water-dispersible crystalline retinol acetate achieves 1.0 million IU per gram through spray-dried modified starch encapsulation. Institutional procurement for edible oil fortification in sub-Saharan Africa concentrates here, driven by WHO-guided national deficiency programs requiring nitrogen-flushed shelf stability.
- Liquid:Emulsified retinol concentrates in oil-based carriers enable dose-precision formulation for dietary supplement channels. Germany's geriatric nutrition manufacturers are accelerating adoption for sarcopenia-targeting meal replacement beverages.
- Gel:Hydrogel matrices for topical nutraceutical delivery. Limited food-active adoption outside Japan's functional food sector.
- Capsule:Soft-gel and hard-shell formats dominate direct-to-consumer supplement positioning. EFSA's tightened novel food dossier timelines compress first-mover windows for new encapsulation technologies.
Powder anchors the volume base while liquid gains share at the steepest rate.
Application:
Cost tier stratification separates institutional procurement from premium supplement positioning.
- Dietary Supplements:Precision-dose retinol in soft-gel and emulsified liquid formats commands premium pricing through bioavailability claims. US FDA GRAS notification requirements govern synthetic vitamin A additions, with manufacturers absorbing dual-certification overhead to serve both American and European channels.
- Skincare Products:Retinol and retinyl palmitate in topical cosmeceuticals face ECHA scrutiny under REACH cosmetic ingredient frameworks. Food-grade specifications rarely penetrate this application.
- Nutraceuticals:Functional food and beverage fortification targeting immune function and aging populations. BASF SE's Ludwigshafen complex supplies crystalline acetate for German dairy analog manufacturers.
- Food Additives:Edible oil and flour fortification for vitamin A deficiency intervention. India's FSSAI Codex alignment is reducing technical barriers for premix imports into institutional procurement channels.
Food additives anchor the volume base while dietary supplements gain share at the steepest rate.
Grade:
Supply concentration around integrated chemical complexes favors food-grade and pharmaceutical-grade producers with captive beta-ionone supply chains.
- Pharmaceutical Grade:USP-specification retinol for clinical nutrition and parenteral applications. EMA's impurity profiling requirements exceed food-additive thresholds.
- Cosmetic Grade:Retinol and retinyl esters for topical formulation. REACH registration dossiers dominate compliance burden.
- Food Grade:All-trans-retinol and pro-vitamin A esters manufactured under EFSA Regulation 1925/2006 and FDA GRAS frameworks. DSM Nutritional Products anchors competitive position through biotechnology-derived beta-carotene conversion routes.
- Industrial Grade:Feed-additive retinol for animal nutrition. Lower purity tolerances exclude human food chain entry.
Food grade anchors the volume base while pharmaceutical grade gains share at the steepest rate.
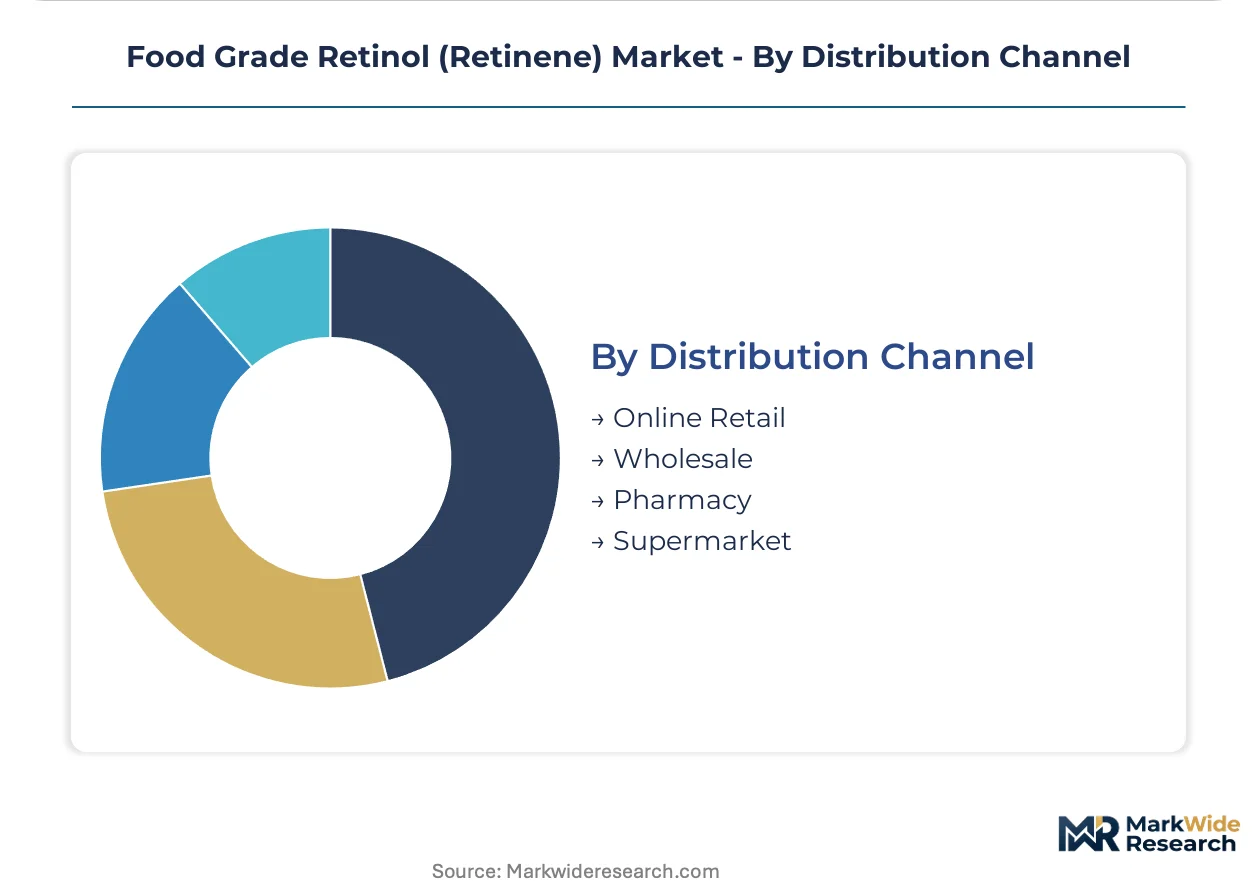
Distribution Channel:
Customer type fragmentation separates institutional framework agreements from spot-market retail procurement.
- Online Retail:Direct-to-consumer supplement sales with dose-precision positioning. China's SAMR e-commerce regulations for food-active compounds create compliance friction for cross-border sellers.
- Wholesale:Bulk premix supply to food manufacturers and fortification programs. UNICEF and WHO procurement channels are consolidating around pre-qualified supplier registries with multi-year framework agreements.
- Pharmacy:Clinical and wellness-oriented retinol supplementation. Germany's pharmacy-dominant distribution structure concentrates high-margin liquid concentrate sales.
- Supermarket:Mass-market fortified food and beverage placement. Clean-label substitution pressure from natural carotenoid complexes constrains synthetic retinol penetration.
Wholesale anchors the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's tightened purity thresholds under Regulation 1925/2006 have concentrated food-grade retinol production in jurisdictions with integrated chemical manufacturing infrastructure. National fortification programs and geriatric nutrition expansion are reshaping demand geography across four dominant markets.
Germany
Geriatric nutrition manufacturers in Bavaria and North Rhine-Westphalia are accelerating retinol fortification for sarcopenia-targeting meal replacements. EFSA's Ludwigshafen-adjacent enforcement cluster maintains the strictest contaminant profiling requirements in Europe. BASF SE's integrated vitamin A complex anchors supply security for dairy analog producers across the Rhine-Neckar metropolitan region.
United States
FDA GRAS notification requirements govern synthetic vitamin A additions for aging-population dietary supplements. Dual-certification overhead burdens manufacturers serving both American and European channels without dedicated formulation lines. DSM Nutritional Products' biotechnology-derived conversion routes reduce petrochemical feedstock exposure for domestic nutraceutical channels.
China
GB 14880 compliance mandates for domestic vitamin A fortification are creating demand for export-certified premixes. SAMR's tightened e-commerce regulations for food-active compounds create compliance friction for cross-border supplement sellers. Zhejiang Medicine Co. Ltd competes on fermentation-scale economics from coastal production clusters while navigating stricter export certification requirements.
India
FSSAI's recent Codex Alimentarius alignment is reducing technical barriers for premix imports into institutional procurement channels. National edible oil fortification programs are expanding procurement volumes for high-potency retinol under WHO guidelines. Maharashtra and Gujarat-based food manufacturers are standardizing on pre-qualified supplier registries with multi-year framework agreements.
Food Grade Retinol (Retinene) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with supply consolidating around chemical complexes possessing captive beta-ionone supply chains. The upper tier commands formulation expertise for stereospecific isomerization protocols that marginal producers cannot replicate. Two strategic archetypes dominate: integrated chemical conglomerates with backward control over petrochemical feedstocks, and biotechnology specialists leveraging fermentation-derived conversion routes. Competitive moves center on dual-certification manufacturing architecture and microencapsulation technology licensing for extended shelf stability.
Within the integrated chemical tier, BASF SE and DSM Nutritional Products exemplify divergent feedstock strategies. Zhejiang Medicine Co. Ltd occupies a position among coastal Chinese fermentation-scale specialists navigating export certification complexity. These three anchors represent the geographic and technological bifurcation structuring competitive positioning: European petrochemical integration against Asian biotechnology economics.
| Leading Market Players |
|---|
| BASF SE |
| DSM Nutritional Products |
| Archer Daniels Midland Company |
| Eastman Chemical Company |
| Adisseo |
| Merck KGaA |
| Zhejiang Medicine Co. Ltd |
| Kingdomway Nutrition Inc. |
| Nutraceutical International Corporation |
| Others |
Pricing and Supply Chain Analysis
Fermentation-derived beta-carotene isomerization routes are displacing petrochemical-based synthetic retinol in premium nutraceutical formulations, simultaneously shifting production gravity toward coastal Chinese biotechnology clusters and compressing price premiums for European petrochemical-integrated supply.
Pricing Analysis
Geographic price spreads between German petrochemical-integrated supply and Chinese fermentation-scale output exceed 15-20% at equivalent purity grades, reflecting divergent feedstock economics and EFSA compliance overhead. Three-tier pricing structure across pharmaceutical-grade crystalline acetate, food-grade encapsulated powder, and feed-grade concentrates separates institutional procurement channels from premium dietary supplement positioning. Cost compression in standard-grade powder formats is intensifying because Zhejiang Medicine Co. Ltd and coastal competitors are expanding fermentation capacity. Institutional buyers in sub-Saharan Africa exhibit highest price sensitivity due to WHO-guided budget constraints, while German geriatric nutrition manufacturers demonstrate lowest sensitivity given sarcopenia-targeting premium positioning.
Supply Chain Analysis
Just-in-time premix delivery models are supplanting strategic stockpiles as microencapsulation technology extends shelf stability under ambient storage, reducing nitrogen-flushed packaging dependency for dairy analog manufacturers. Supply concentrates in Germany's Ludwigshafen chemical complex, China's Zhejiang coastal production clusters, and DSM's Dutch biotechnology facilities. Raw material dependencies center on beta-ionone cyclization feedstocks, fish liver oil saponification inputs, and fermentation-grade glucose substrates. Single-source vulnerability around stereospecific isomerization chemist expertise constrains batch consistency at multi-ton facilities. Distribution runs through UNICEF and WHO pre-qualified supplier registries with multi-year framework agreements displacing spot-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
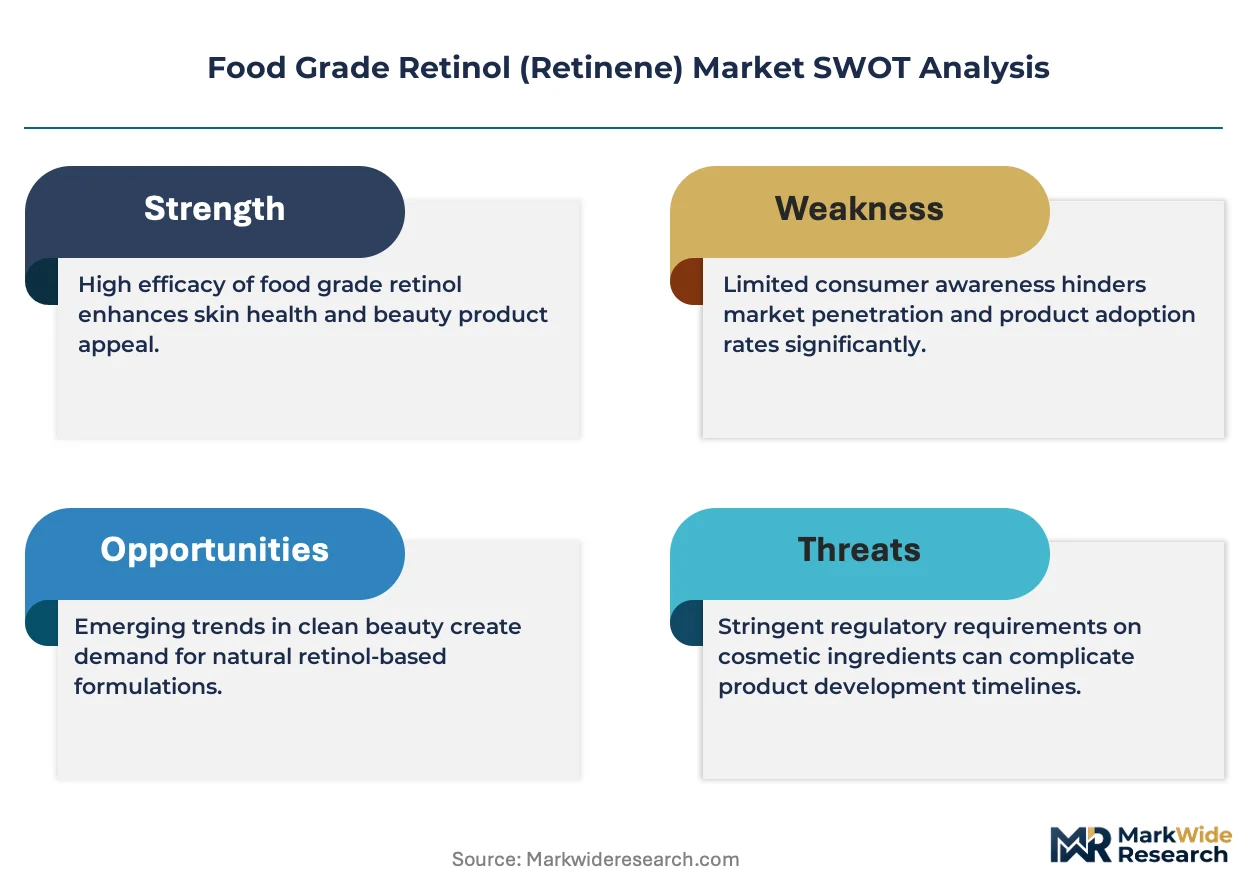
Regulatory entrenchment around EFSA's tightened purity thresholds under Regulation 1925/2006 creates formidable defensive moats for incumbent producers with integrated analytical infrastructure and captive beta-ionone supply chains.
For Market Incumbents: Consolidate formulation expertise in stereospecific isomerization protocols through targeted retention programs for organic synthesis chemists, addressing the collapsing talent pipeline constraining batch consistency. Deepen backward integration into biotechnology-derived beta-carotene conversion routes to reduce petrochemical feedstock exposure and neutralize Zhejiang Medicine Co. Ltd's fermentation-scale cost advantage. Expand dual-certified manufacturing lines serving both EFSA and FDA jurisdictions without reformulation delays. For New Entrants and Emerging Players: Anchor in India's FSSAI-aligned institutional procurement channels where Codex Alimentarius harmonization has reduced technical barriers for premix imports and national edible oil fortification programs are expanding. Target Maharashtra and Gujarat-based food manufacturers standardizing on pre-qualified supplier registries with multi-year framework agreements. Pursue emulsification technology licensing for dose-precision liquid concentrates in dietary supplement channels, commanding premium positioning beyond commoditized powder markets. For Investors and Strategic Acquirers: EFSA's updated novel food ingredient guidelines reshape the acquisition landscape by extending approval timelines and compressing first-mover advantage windows for new retinol derivative formats. Long-term viability favors integrated chemical complexes with captive beta-ionone supply chains and established dual-certification infrastructure over standalone fermentation specialists exposed to export certification volatility. The signal to watch is consolidation velocity among coastal Chinese producers as stricter SAMR e-commerce regulations for food-active compounds create compliance friction for cross-border sellers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beta-Ionone Supply | BASF SE's Ludwigshafen complex secures captive feedstock for crystalline retinol acetate production. |
| Biotechnology Conversion Route Expansion | DSM Nutritional Products reduces petrochemical dependency through fermentation-derived beta-carotene isomerization. |
| Dual-Certification Manufacturing Architecture | Simultaneous EFSA and FDA compliance eliminates reformulation delays for exporters serving both jurisdictions. |
| Microencapsulation Technology Licensing | Spray-dried modified starch matrices extend shelf stability for dairy analog manufacturers in Germany. |
| Pre-Qualified Supplier Registry Positioning | UNICEF and WHO framework agreements lock in multi-year supply security for sub-Saharan Africa fortification programs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA regulatory filings, FDA GRAS notification databases, and trade customs data covering vitamin A derivative flows. Primary interviews engaged plant managers at integrated chemical complexes, procurement leads at German dairy analog manufacturers, regulatory affairs directors navigating dual-certification requirements, and UNICEF supply officers overseeing national fortification programs. Secondary validation drew from SEC 10-K disclosures of listed nutritional ingredient suppliers, WHO guideline documentation for deficiency intervention programs, and GB 14880 compliance records from China's National Health Commission. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Segmentation dimensions modeled span product type hierarchy, application tier stratification, grade certification levels, and distribution channel fragmentation across the projection horizon. Analytical framework incorporated powder versus liquid format substitution elasticities, institutional versus premium supplement demand drivers, and geographic regulatory cluster divergence. CAGRs were derived through exponential smoothing of historical volume trajectories adjusted for policy-driven procurement shifts. Industry-specific forecast inputs included EFSA novel food dossier approval timelines and WHO-guided national fortification program expansion rates.
Material uncertainties — stereospecific chemist scarcity acceleration, EFSA-FDA maximum level harmonization delays, natural carotenoid substitution velocity in clean-label segments — sit outside the modeled envelope. Forecasts reflect assumptions around sustained biotechnology conversion efficiency gains and stable regulatory enforcement intensity. Revision becomes warranted when dual-certification cost burden thresholds trigger supplier consolidation waves or clean-label displacement crosses 25% penetration in premium positioning segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
Global Antioxidant Vitamins Market
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Prenatal Vitamin Preparation Market