
 Feed Grade Vitamin D Market | 2026-2036
Feed Grade Vitamin D Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Grade Vitamin D Market Insights
Pharmaceutical-grade chemist availability is bifurcating the competitive landscape between integrated Chinese manufacturers and Western formulation specialists. Zhejiang Garden Biochemical High-tech leverages captive cholesterol feedstock to sustain cost leadership in cholecalciferol synthesis. DSM-Firmenich anchors premium positioning through microencapsulation technology that extends vitamin D3 stability in pelleted feeds.
Feed grade vitamin D denotes cholecalciferol and ergocalciferol preparations meeting specified purity thresholds for animal nutrition, typically formulated at international units per gram concentrations compatible with premix integration and thermal processing resilience. The compound prevents rickets in young stock and optimizes calcium-phosphorus metabolism across monogastric and ruminant species. Vitamin D3 dominates volume flows due to superior bioavailability in poultry and swine, while liquid emulsion forms capture expanding share in automated aquaculture feeding systems where homogeneity requirements exceed granular dispersion limits. Powder formulations retain entrenched positions in ruminant mineral supplements where on-farm blending persists.
EFSA feed additive evaluations, FDA Center for Veterinary Medicine oversight, and China's Ministry of Agriculture and Rural Affairs registration requirements collectively determine market access trajectories and product specification floors. EFSA's tightened maximum residue limits for vitamin D metabolites in edible tissues are forcing reformulation investments among European suppliers. China's GB standard harmonization with Codex Alimentarius specifications is reshaping export qualification protocols for domestic manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions where asynchronous approval timelines create supply arbitrage opportunities and compliance cost asymmetries.
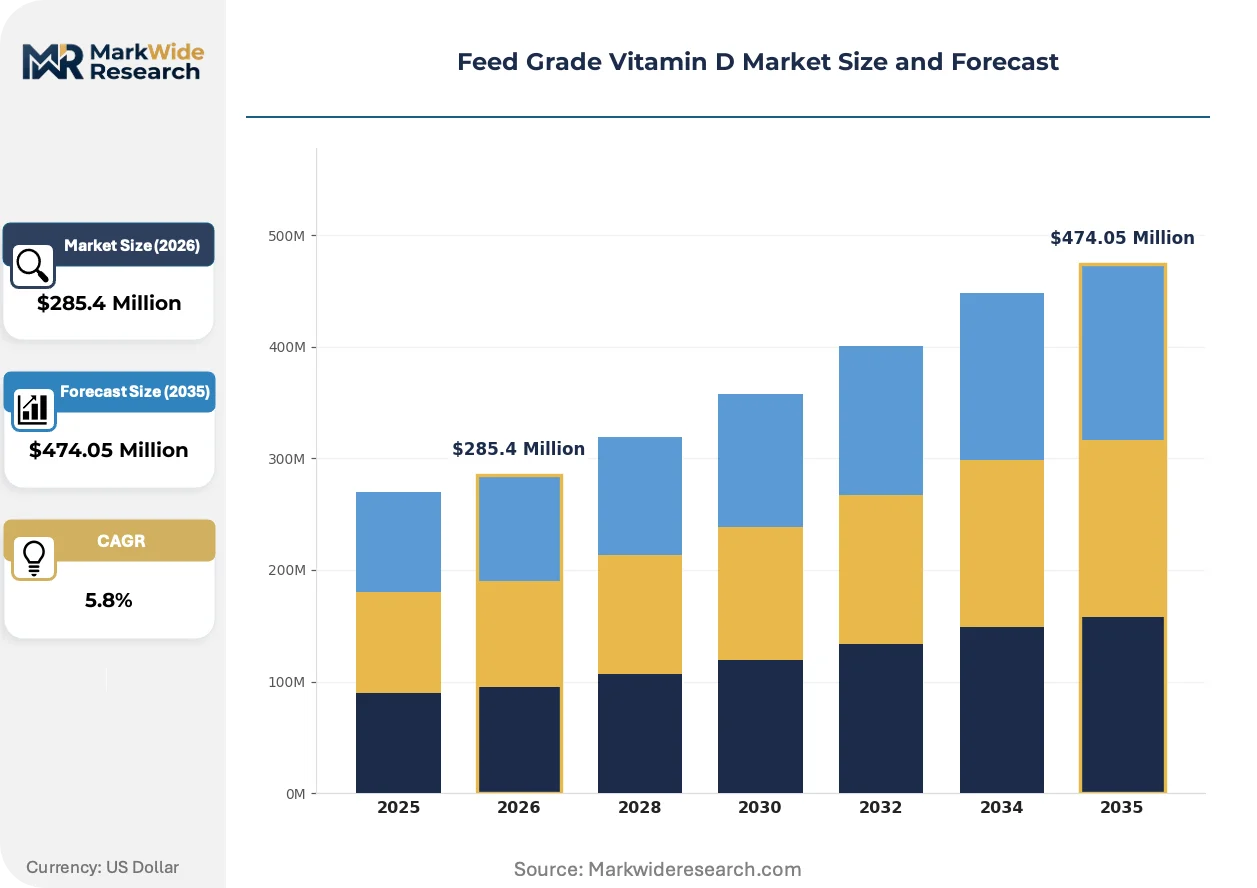
Market Dynamics
EFSA's tightened purity specifications for cholecalciferol are forcing European suppliers into costly reformulation investments while creating compliance arbitrage windows for Chinese manufacturers operating under GB standard harmonization with Codex Alimentarius.
Growth Catalysts
- Aquaculture automation:Liquid emulsion vitamin D3 formulations are displacing granular premixes in Southeast Asian shrimp and finfish operations where feeding system precision demands exceed powder dispersion limits.
- EFSA re-authorization timelines:Extended evaluation periods for feed additive renewals are concentrating procurement among suppliers with established dossier track records, locking out marginal entrants.
- Poultry bone density protocols:Vietnamese and Indonesian integrators are expanding vitamin D fortification programs to reduce skeletal defects and improve feed conversion ratios in broiler operations.
Market Restraints
- Cholesterol feedstock volatility:Captive cholesterol supply constraints in integrated Chinese manufacturing are creating input cost asymmetries against Western formulation specialists dependent on spot market sourcing.
- Regulatory fragmentation:Asynchronous approval timelines between EFSA, FDA Center for Veterinary Medicine, and China's Ministry of Agriculture and Rural Affairs are generating compliance cost burdens that favor multi-jurisdictional incumbents.
- Thermal degradation limits:Standard cholecalciferol preparations exhibit stability failures above 85°C pelleting temperatures, restricting formulation options for high-temperature feed processing applications.
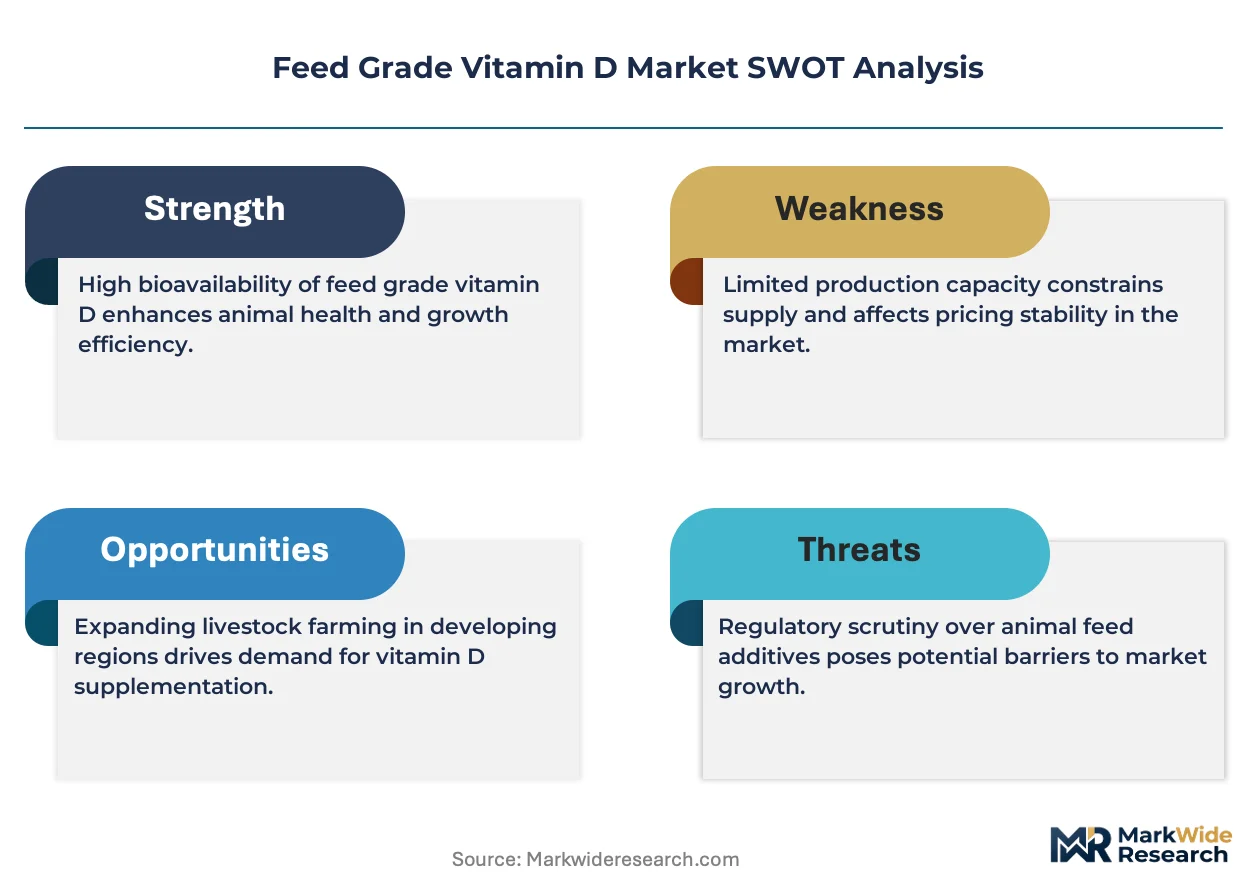
Strategic Opportunities
- Microencapsulation premium tier:Extended-release vitamin D3 technologies command price multiples in European compound feed manufacturing where thermal resilience specifications exceed commodity-grade thresholds.
- Ruminant mineral supplement channels:On-farm blending persistence in Brazilian and Argentine cattle operations creates direct-to-producer distribution openings bypassing integrated premix intermediaries.
- Residue limit compliance services:EFSA's tightened maximum vitamin D metabolite limits in edible tissues are generating advisory revenue streams around formulation optimization and withdrawal period management.
Industry Challenges
- Analytical chemistry capacity gaps:Specialized HPLC-MS competency for vitamin D metabolite quantification remains concentrated among contract laboratories, creating testing bottlenecks for reformulation validation.
- Legacy premix integration friction:Automated aquaculture feeding systems require homogeneity specifications that exceed dispersion capabilities of established powder formulation infrastructure, forcing capital-intensive liquid handling retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Grade Vitamin D Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin D2, Vitamin D3, Ergocalciferol, Cholecalciferol Form: Granular, Powder, Liquid, Emulsion Application: Poultry, Swine, Ruminants, Aquaculture Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Zhejiang Garden Biochemical High-tech, Taizhou Hisound Pharmaceutical, Kingdomway, Zhejiang NHU, DSM, Zhejiang Medicine, DSM-Firmenich, BASF, Adisseo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Grade Vitamin D Market Trends and Innovations
Active pharmaceutical ingredient manufacturing techniques are migrating into feed-grade vitamin production, compressing quality differentials between human and animal nutrition supply chains while elevating specification floors across both segments.
Spray-dried microencapsulation technology is decomposing the traditional tradeoff between thermal stability and bioavailability in cholecalciferol formulations. Poultry integrators in Vietnam and Thailand are adopting these preparations at accelerated procurement cycles. The technology is decomposing incumbent cost structures built around commodity-grade powder production, forcing reformulation investments among suppliers lacking captive encapsulation capabilities.
REACH-aligned substance registration requirements are extending compliance obligations to vitamin D3 precursor chemicals previously exempt from full dossier submission. European compound feed manufacturers face expanded documentation burdens for supply chain traceability. Aquaculture premix specialists operating across EU and non-EU jurisdictions are consolidating procurement around dual-registered suppliers to avoid formulation discontinuities.
Integrated poultry and aquaculture operators are consolidating micronutrient procurement through direct manufacturer relationships, disintermediating traditional premix distributors. Vietnamese integrators are negotiating multi-year cholecalciferol supply agreements with fixed-unit pricing indexed to feed production volumes rather than spot commodity terms. This concentration is most visible in Mekong Delta shrimp farming clusters where three processors account for majority vitamin D3 offtake.
Feed Grade Vitamin D Market Segmentation
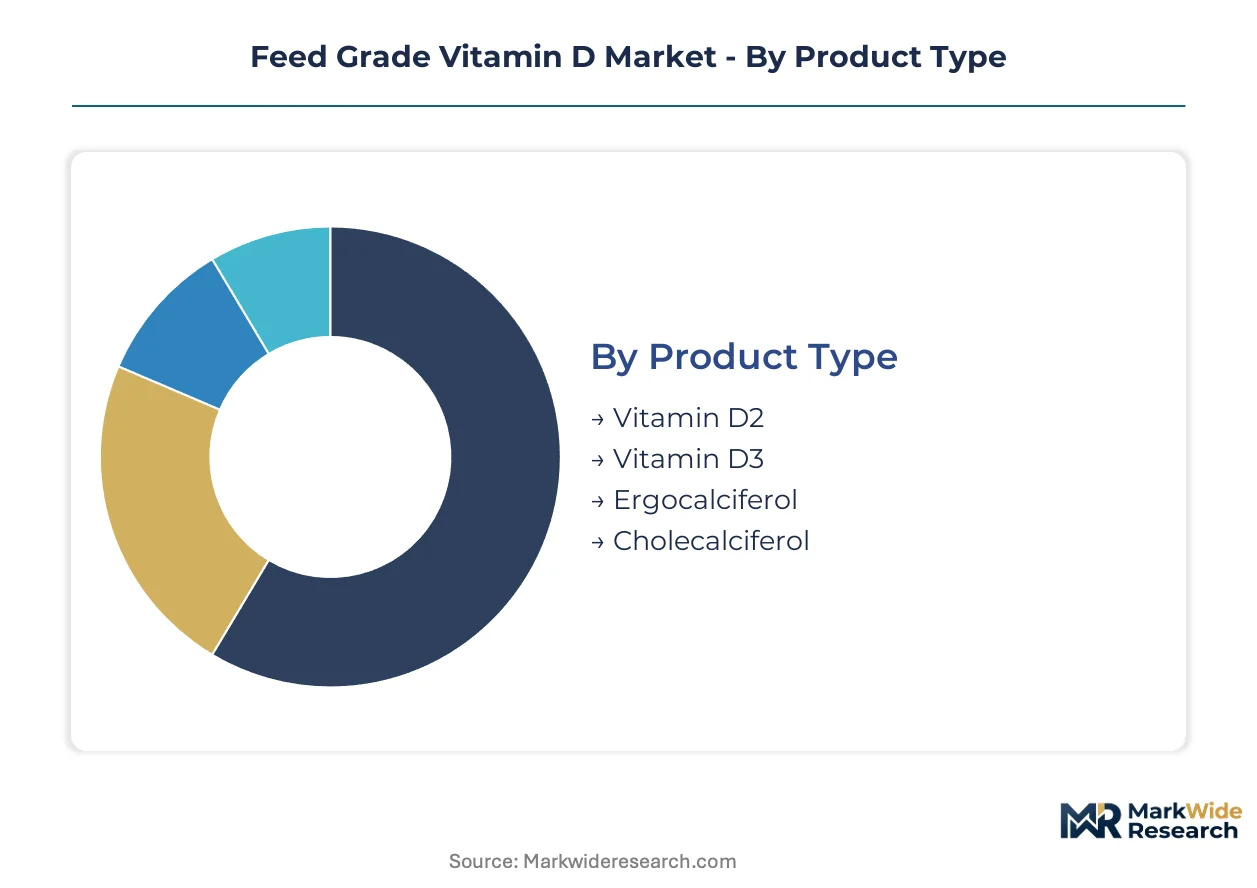
Feed grade vitamin D procurement patterns diverge sharply across product chemistry, physical form, and species application. Each segmentation axis carries distinct margin profiles, regulatory burdens, and geographic concentration that reshape competitive positioning.
Product Type:
Geographic demand spreads unevenly across vitamin D chemistries, with export-led volumes concentrating in cholecalciferol while ergocalciferol retains domestic anchoring in European ruminant markets.
- Vitamin D3:Cholecalciferol preparations dominate poultry and swine formulations across Southeast Asian integrator operations. Vietnamese broiler producers are expanding D3 fortification programs to reduce skeletal defects and improve feed conversion ratios.
- Cholecalciferol:Synthetic and natural-source variants command premium positioning in automated aquaculture feeding systems where bioavailability specifications exceed standard premix thresholds. Mekong Delta shrimp processors account for concentrated offtake through direct manufacturer relationships.
- Vitamin D2:Ergocalciferol retains entrenched positions in European ruminant mineral supplements where on-farm blending persists and regulatory familiarity reduces reformulation friction.
- Ergocalciferol:Plant-derived D2 captures niche demand in organic-certified livestock operations facing synthetic additive restrictions under EFSA organic livestock guidelines.
Cholecalciferol commands the established base. The steepest expansion runs through vitamin D3 aquaculture applications.
Form:
Cost tier stratification separates thermal-resilient microencapsulated powders from commodity-grade liquids, with margin capture concentrating in spray-dried technologies.
- Liquid:Emulsion formulations displace granular premixes in Southeast Asian shrimp and finfish operations where feeding system precision demands exceed powder dispersion limits. Indonesian aquaculture automation is accelerating procurement cycles for homogenous liquid delivery.
- Emulsion:Oil-based vitamin D3 emulsions integrate directly into extruded aquafeeds without thermal degradation, capturing share in high-temperature pelleting applications where standard preparations fail above 85°C.
- Powder:Spray-dried preparations retain dominance in Brazilian and Argentine cattle mineral supplements where on-farm blending infrastructure resists liquid handling retrofits.
- Granular:Beadlet technologies serve legacy premix manufacturers lacking encapsulation capabilities, facing displacement pressure from microencapsulated alternatives in European compound feed manufacturing.
Powder forms anchor the existing installed base. Liquid emulsions are climbing the fastest as aquaculture automation spreads.
Application:
Volume concentration varies by species metabolism requirements, with monogastric applications driving unit economics through higher inclusion rates per ton of feed.
- Poultry:Broiler integrators in Vietnam and Indonesia deploy elevated vitamin D3 protocols to optimize bone density and reduce lamination-related culling. Skeletal defect reduction programs are expanding across Southeast Asian contract farming operations.
- Aquaculture:Shrimp and finfish operations in the Mekong Delta and Indonesian archipelago are consolidating micronutrient procurement through direct manufacturer relationships, disintermediating traditional premix distributors.
- Swine:Sow and grower-finisher formulations maintain steady demand in Chinese integrated pork operations, though calcium-phosphorus optimization receives less technical attention than in poultry.
- Ruminants:Dairy and beef cattle applications in Brazil and Argentina persist in on-farm blending channels, creating direct-to-producer distribution openings that bypass integrated premix intermediaries.
Poultry holds the volume anchor. Aquaculture represents the steepest expansion trajectory as automation penetrates Southeast Asian production clusters.
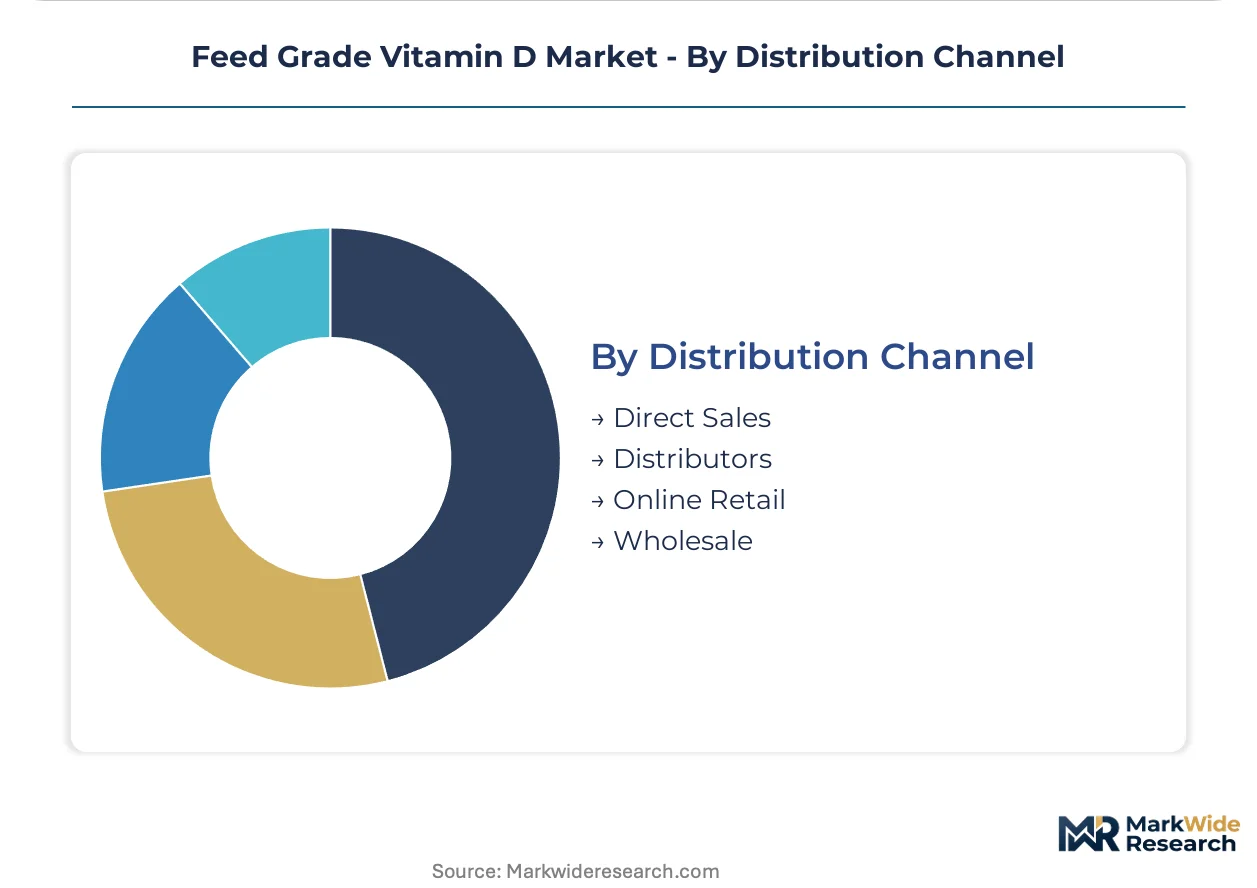
Distribution Channel:
Customer type fragmentation separates large integrator direct procurement from fragmented farm-level purchasing, with channel strategy determining working capital intensity and technical service requirements.
- Direct Sales:Vietnamese poultry and aquaculture integrators negotiate multi-year cholecalciferol supply agreements with fixed-unit pricing indexed to feed production volumes rather than spot commodity terms.
- Distributors:Regional premix specialists aggregate demand from mid-scale livestock operations across Indonesia and the Philippines, absorbing inventory risk and providing formulation technical support.
- Wholesale:Commodity-grade vitamin D3 moves through feed ingredient traders serving Brazilian and Argentine cattle operations with price-sensitive, specification-flexible purchasing patterns.
- Online Retail:Digital procurement channels capture emerging share among smallholder poultry operations in India, though quality verification and cold-chain logistics constrain penetration.
Direct sales command the established integrator base. Distributor networks are expanding most quickly as mid-scale aquaculture operations professionalize procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA feed additive re-authorization timelines are reshaping procurement patterns across European compound feed manufacturing while Chinese GB standard harmonization creates export qualification asymmetries for integrated manufacturers.
China
Captive cholesterol feedstock integration sustains cost leadership in Zhejiang and Jiangsu manufacturing clusters where synthetic cholecalciferol production concentrates. SAMR registration requirements under harmonized GB standards are tightening export documentation burdens for domestic suppliers serving Southeast Asian markets. Ningbo and Hangzhou chemical parks anchor the majority of feed-grade vitamin D3 precursor synthesis.
Vietnam
Mekong Delta shrimp processors and broiler integrators are consolidating micronutrient procurement through direct manufacturer relationships indexed to feed production volumes. The Ministry of Agriculture and Rural Affairs feed additive registration process is accelerating as domestic aquaculture automation expands. Ho Chi Minh City and Can Tho serve as distribution hubs for liquid emulsion formulations displacing legacy powder premixes.
Indonesia
Archipelago aquaculture operations and poultry contract farming networks are driving accelerated procurement cycles for homogenous liquid vitamin D3 delivery systems. National Agency of Drug and Food Control feed supplement regulations are tightening import inspection protocols for premix additives. Surabaya and Medan clusters concentrate integrator demand for automated feeding system compatibility.
Germany
REACH-aligned substance registration requirements are extending compliance obligations to vitamin D3 precursor chemicals previously exempt from full dossier submission. EFSA maximum residue limit enforcement for vitamin D metabolites in edible tissues is forcing reformulation investments among compound feed manufacturers. Lower Saxony and Bavaria host the majority of ruminant premix formulation operations.
Brazil
On-farm mineral supplement blending persistence in cattle operations creates direct-to-producer distribution openings bypassing integrated premix intermediaries. Ministry of Agriculture, Livestock and Supply feed additive quality standards are elevating specification floors for imported vitamin D3 preparations. São Paulo and Rio Grande do Sul states anchor demand for powder formulations resistant to tropical storage conditions.
Feed Grade Vitamin D Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated structure where microencapsulation specialists command premium positioning against integrated feedstock manufacturers. The vendor base separates into three strategic tiers: captive-cholesterol synthesizers with upstream chemical integration, formulation technology specialists with encapsulation capabilities, and regional premix distributors absorbing inventory risk. Competitive moves concentrate around multi-year supply agreements with volume-indexed pricing and direct procurement relationships disintermediating traditional distribution channels.
Within the integrated manufacturing tier, Zhejiang Garden Biochemical High-tech and Zhejiang NHU occupy positions anchored by precursor chemical capabilities. DSM-Firmenich represents the formulation technology archetype where stability-enhancement expertise commands price multiples. These three entities exemplify the competitive tension between cost-driven synthesis and performance-driven delivery systems reshaping procurement patterns across Southeast Asian integrator operations.
| Leading Market Players |
|---|
| Zhejiang Garden Biochemical High-tech |
| Taizhou Hisound Pharmaceutical |
| Kingdomway |
| Zhejiang NHU |
| DSM |
| Zhejiang Medicine |
| DSM-Firmenich |
| BASF |
| Adisseo |
| Others |
Pricing and Supply Chain Analysis
Liquid emulsion formulations displacing legacy powder premixes in Southeast Asian aquaculture are simultaneously redrawing procurement geography toward Ningbo and Hangzhou chemical clusters and compressing margin capture for Western formulation specialists lacking thermal-stability technology. This substitution dynamic concentrates pricing power among integrated Chinese manufacturers with captive cholesterol feedstock while forcing premium-tier positioning for microencapsulation specialists serving European compound feed operations.
Pricing Analysis
Price spreads between Zhejiang-sourced commodity cholecalciferol and DSM-Firmenich microencapsulated preparations exceed three-to-one multiples across European procurement channels. Three-tier pricing structure across microencapsulated premium, spray-dried standard, and liquid economy levels stratifies by thermal resilience certification and volume commitment scale. Cost compression in commodity-grade powder segments is intensifying because captive cholesterol integration among Jiangsu manufacturers eliminates Western spot-market sourcing premiums. Mid-scale Vietnamese aquaculture integrators exhibit highest price sensitivity through volume-indexed multi-year agreements, while European ruminant premix specialists demonstrate lowest sensitivity due to EFSA-mandated reformulation compliance costs.
Supply Chain Analysis
Inventory lead times for cholecalciferol precursors stretch six to eight weeks from Ningbo chemical parks to Ho Chi Minh City distribution hubs, creating working capital intensity for Vietnamese integrators operating just-in-time automated feeding systems. Supply concentrates in China, Vietnam, and Germany, with precursor synthesis anchored in Zhejiang and Jiangsu provinces, formulation and blending in Mekong Delta processing clusters, and regulatory dossier compilation in Lower Saxony. Raw material dependencies center on lanolin-derived cholesterol, pharmaceutical-grade solvents, and spray-drying encapsulation polymers. Single-source vulnerability runs through cholesterol feedstock integration at three dominant Chinese manufacturers. Distribution runs through direct manufacturer relationships for large integrators and regional premix specialists for mid-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where residue limit compliance advisory and withdrawal period management expand faster than commodity vitamin D3 tonnage, creating recurring revenue layers around formulation optimization that exceed hardware margins in traditional premix supply.
For Market Incumbents: Compound defensive positioning through backward integration into microencapsulation technology and captive cholesterol supply agreements that lock in cost asymmetries against Western formulation specialists. EFSA's tightened maximum residue limits for vitamin D metabolites threaten margin compression for suppliers lacking analytical chemistry partnerships; certification investment in HPLC-MS testing capabilities represents the critical lever for preserving European market access. For New Entrants and Emerging Players: Service-layer gaps in automated aquaculture feeding system integration—where legacy premix manufacturers lack liquid handling retrofit expertise—present white-space openings for technology-focused entrants. Brazilian and Argentine ruminant mineral supplement channels, with persistent on-farm blending infrastructure resistant to liquid conversion, offer the most penetrable geography for powder formulation specialists. A direct-to-producer distribution model bypassing integrated premix intermediaries captures margin otherwise absorbed by distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward formulation technology specialists with proven microencapsulation capabilities and established EFSA dossier track records, as regulatory re-authorization timelines concentrate procurement among incumbents with compliance infrastructure. The five-to-ten year viability window favors acquisition targets combining thermal-stability IP with Southeast Asian direct sales relationships. The signal to watch is EFSA re-authorization outcome timing for cholecalciferol additives, which will determine whether compliance cost asymmetries persist or Chinese GB-standard harmonization erodes Western premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cholesterol Feedstock | Zhejiang and Jiangsu chemical parks anchor cost leadership through captive precursor supply. |
| Microencapsulation Technology Licensing | Spray-dried thermal stability commands price multiples in European compound feed manufacturing. |
| Direct Manufacturer Relationship Expansion | Vietnamese integrators consolidate procurement through volume-indexed multi-year supply agreements. |
| Residue Limit Compliance Service Development | EFSA metabolite enforcement generates advisory revenue around withdrawal period management. |
| Aquaculture Liquid Emulsion Capacity Buildout | Mekong Delta automation demands homogenous delivery systems exceeding powder dispersion limits. |
Research Methodology
Cross-validation between primary interviews with feed additive procurement managers, regulatory affairs directors at premix manufacturers, and aquaculture operations executives anchors the qualitative findings against secondary validation from EFSA feed additive opinions, FDA Center for Veterinary Medicine guidance documents, SAMR registration databases, and customs trade flow records. Bottom-up triangulation across Vietnamese integrator offtake data and top-down reconciliation with Chinese export statistics ensures dimensional consistency.
Sensitivity analysis across the projection horizon tests demand elasticity for cholecalciferol against aquaculture automation penetration rates and EFSA re-authorization timeline scenarios. Segmentation dimensions modeled include product chemistry tier, physical form specification, species application, and distribution channel structure, with CAGRs derived from slope-intercept fitting against historical premix integration rates and forward-looking integrator capacity announcements. Cholesterol feedstock cost curves and thermal degradation threshold specifications constitute industry-specific forecast inputs.
Forecasts assume regulatory continuity in EFSA, FDA Center for Veterinary Medicine, and SAMR regimes; material policy shifts around maximum residue limits or GB standard harmonization would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Vitamin B Complex Market
Vitamin Fortified
Global Vitamins Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
Retinyl Linoleate Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Global Antioxidant Vitamins Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
Vitamin Premix Market