
 Solar Air Conditioning Market | 2026-2036
Solar Air Conditioning Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Air Conditioning Market Outlook
The EU Green Deal's building renovation targets and F-Gas Regulation phase-down is broadening addressable demand for low-carbon cooling across member states. Carrier Global Corporation leverages its chiller engineering heritage to anchor premium project pipelines in Mediterranean climates. Daikin Industries, Ltd. competes through photovoltaic-integrated mini-split architectures optimized for residential retrofit markets. Lennox International Inc. specializes in hybrid gas-electric-solar systems that sustain margins in North American new construction segments.
Solar air conditioning integrates photovoltaic arrays, solar thermal collectors, or absorption refrigeration cycles with conventional vapor-compression or desiccant dehumidification hardware to deliver space cooling without sole reliance on grid electricity. Systems typically achieve coefficient of performance ratings between 0.7 and 1.2 for absorption chillers, with photovoltaic-driven units scaling from 3 kW residential mini-splits to 500 kW commercial rooftop configurations. Hybrid systems command the largest installed base due to operational redundancy during intermittent solar generation, while absorption cooling technology captures concentrated demand in industrial process cooling and hospitality applications where waste heat recovery improves overall energy economics.
The US Department of Energy's appliance efficiency standards and EPA SNAP program restrictions on high-GWP refrigerants are reshaping product development roadmaps for solar-thermal and absorption-based equipment. India's BIS certification requirements for solar thermal collectors and state-level net metering caps determine viable system sizing for commercial rooftop installations. China's GB standards for solar-powered appliances and MIIT industrial efficiency mandates filter market access for imported absorption chiller components. Stakeholders must weigh technology-specific regulatory exposure against regional incentive durability when committing manufacturing capacity or project development capital.
Market Dynamics
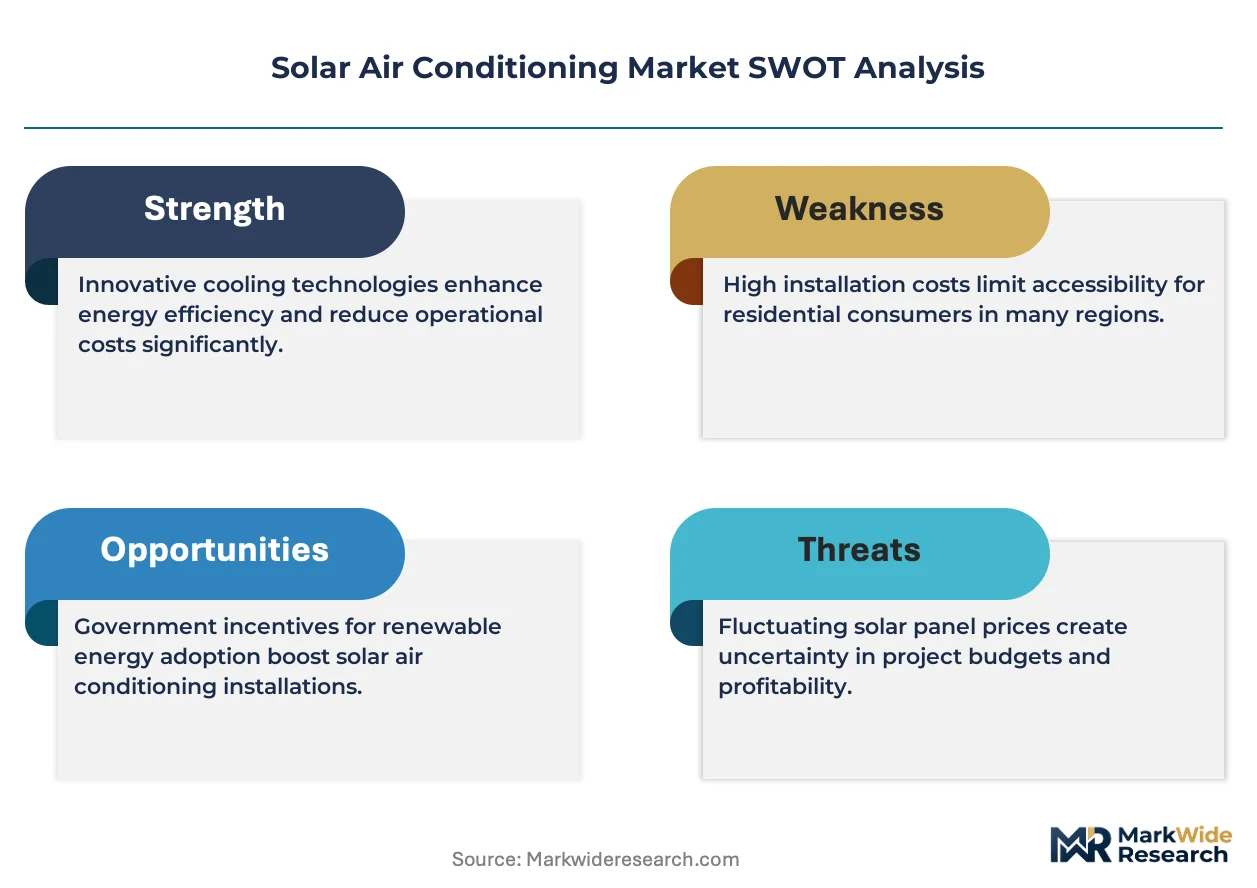
The Solar Air Conditioning Market is being fundamentally restructured by the collision of volatile grid electricity pricing with mandatory clean energy procurement clauses in commercial offtake agreements, forcing building operators to reconsider capital allocation toward on-site generation-integrated cooling.
Growth Catalysts
- EU F-Gas Regulation phase-down:The progressive refrigerant restriction timeline is eliminating high-GWP vapor-compression systems from renovation pipelines, redirecting capital toward absorption and solar-thermal alternatives in Mediterranean commercial portfolios.
- India's solar rooftop obligations:State-level mandates in Gujarat, Maharashtra, and Tamil Nadu require commercial buildings above specified floor areas to install photovoltaic capacity, creating captive power for absorption chiller retrofits.
- Absorption chiller waste heat recovery:Industrial process cooling installations in Vietnam's export manufacturing zones capture exhaust heat from cogeneration systems, improving overall plant efficiency and accelerating payback periods.
Market Restraints
- Lithium-ion battery cost volatility:Photovoltaic-driven cooling systems require substantial storage for evening operation, and input material price swings compress project IRRs for commercial developers.
- Absorption chiller supply concentration:Manufacturing of lithium bromide absorption equipment clusters in East Asian industrial corridors, creating single-source vulnerability for European and North American project pipelines.
- Coefficient of performance ceiling:Solar-thermal absorption systems plateau at performance ratings below vapor-compression alternatives, limiting addressable share in space-constrained urban retrofits.
Strategic Opportunities
- Indonesia's commercial building stock:Jakarta and Surabaya office markets remain underpenetrated by solar cooling despite high grid tariffs and tropical cooling loads, presenting first-mover positioning for hybrid system providers.
- Desiccant-evaporative hybrid convergence:Combining liquid desiccant dehumidification with indirect evaporative cooling addresses latent loads in humid subtropical climates without compression equipment.
- US Inflation Reduction Act commercial credits:Investment tax credit structures for solar-thermal and photovoltaic installations improve project economics for hospitality and healthcare verticals seeking resilience against peak demand charges.
Industry Challenges
- Absorption chiller technician scarcity:The specialized knowledge required for lithium bromide solution maintenance and crystallization prevention is concentrated among aging workforce cohorts in Japan and Germany.
- Multi-vector system integration complexity:Hybrid photovoltaic-thermal-gas configurations require coordination across electrical, plumbing, and HVAC trades, extending commissioning timelines and defect liability periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Air Conditioning Market |
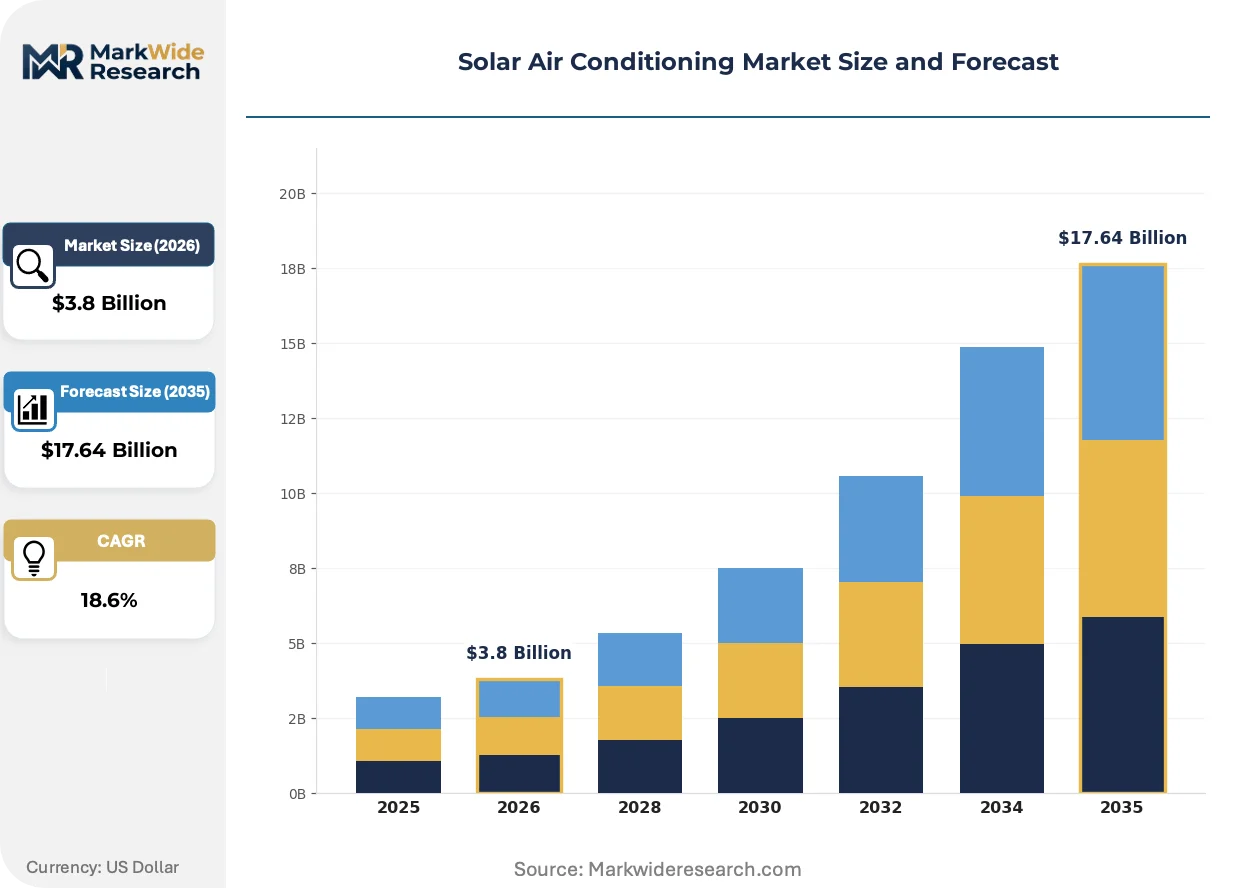
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Hybrid Systems, Chiller Systems, Mini-Splits Technology: Photovoltaic, Solar Thermal, Absorption Cooling, Desiccant Cooling End User: Residential, Commercial, Industrial, Hospitality Installation Type: Rooftop, Ground-Mounted, Building-Integrated, Modular |
| Companies Covered | Lennox International Inc., Gree Electric Appliances Inc., HotSpot Energy, Solair World International, Daikin Industries, Ltd., Midea Group, Carrier Global Corporation, Trane Technologies, Haier Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Air Conditioning Market Strategic Shifts
Equipment architectures are converging around modularity and predictive control systems that optimize across variable solar generation, thermal storage, and grid electricity pricing in real time.
Photovoltaic-integrated mini-split systems with DC-native compressors are rewriting deployment economics for residential and light-commercial retrofits. These units eliminate inverter losses by operating directly from panel output. Installers in Australia's high-solar-penetration suburbs report accelerated customer acquisition where net metering tariffs have compressed. The technology is rewriting the traditional split between residential solar installers and HVAC contractors, forcing consolidation of service capabilities.
The EU Green Deal's building renovation targets and F-Gas Regulation phase-down are compressing the viable product mix for European chiller replacements. Member states must achieve specific renovation rates for non-residential building stock by mandated deadlines. Mediterranean climate zones face the most acute equipment transition pressure, with Spain and Italy accelerating absorption chiller specification in public procurement frameworks.
Commercial building operators are unbundling cooling service contracts from capital equipment ownership, favoring energy-as-a-service arrangements where providers retain asset risk. This shift displaces traditional equipment sale-and-installation revenue pools with long-term performance guarantees. The model is most visible in Singapore's data center and precision manufacturing verticals, where uptime requirements dominate capex minimization priorities.
Solar Air Conditioning Market Segmentation
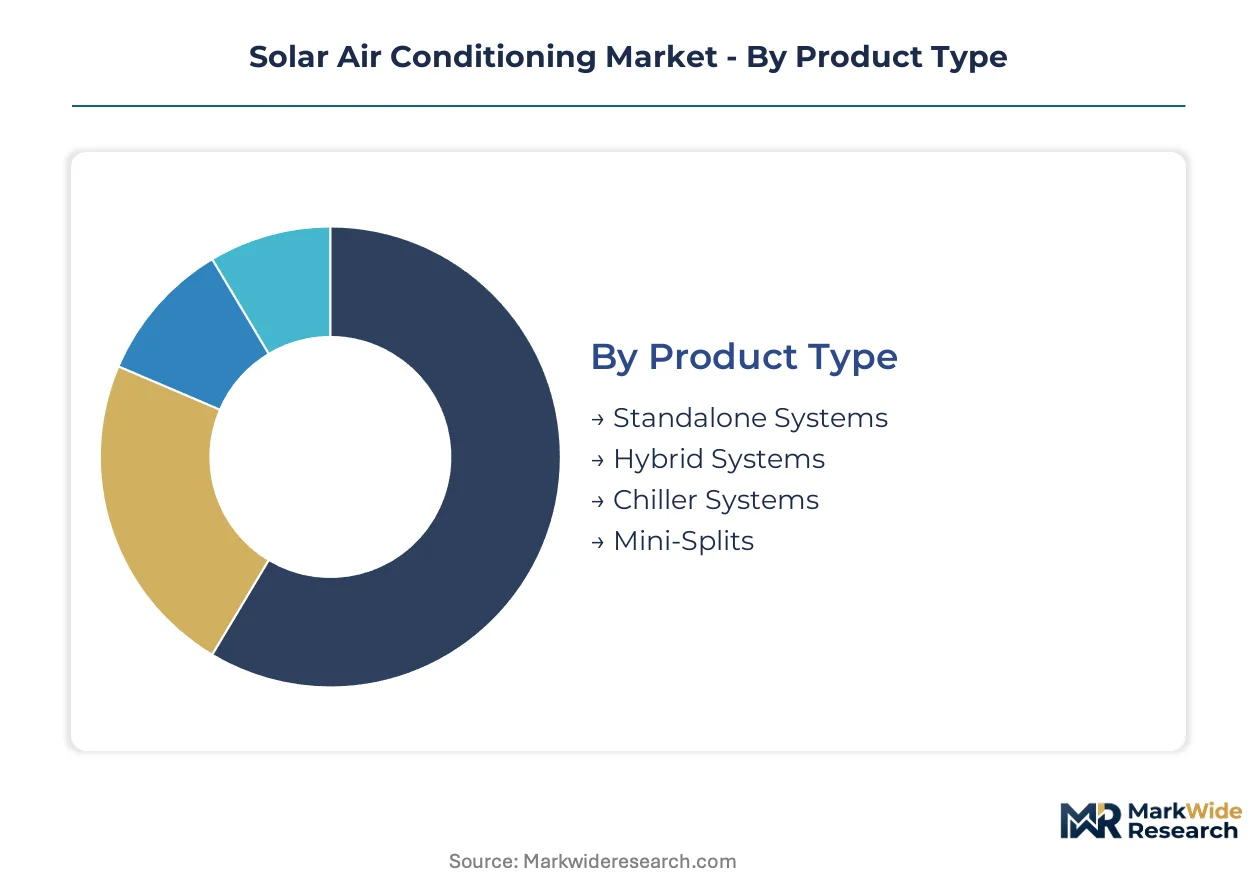
Solar air conditioning equipment fragments across multiple technical axes that determine project economics, regulatory compliance, and operational resilience. Understanding where volume concentrates versus where premiums persist clarifies capital allocation for manufacturers and developers alike.
Product Type:
Hybrid systems dominate installed capacity while standalone photovoltaic units capture the steepest expansion trajectory in residential retrofit channels.
- Standalone Systems:Photovoltaic-driven units operate independently of grid electricity, requiring lithium-ion storage for evening cooling cycles. Demand concentrates in Australian suburbs where net metering tariff compression has eliminated export economics, forcing self-consumption architectures.
- Hybrid Systems:Configurations blending solar-thermal, photovoltaic, and conventional vapor-compression hardware provide operational redundancy during intermittent generation. Commercial building operators in Vietnam's export manufacturing zones specify these for binding clean energy procurement clauses from European buyers.
- Chiller Systems:Absorption chillers from 100kW to 500kW serve centralized cooling plants in Mediterranean hospitality portfolios facing EU F-Gas Regulation phase-down deadlines.
- Mini-Splits:DC-native compressor architectures eliminate inverter losses in residential and light-commercial deployments across India's state-level solar rooftop obligation markets.
Today's leader: Hybrid Systems. Tomorrow's challenger: Mini-Splits.
Technology:
Photovoltaic integration scales fastest where net metering policy shifts force self-consumption, while absorption cooling defends industrial process applications.
- Photovoltaic:Direct-current compressor technologies bypass inverter losses, rewriting deployment economics for distributed cooling. Installers in Gujarat and Maharashtra report accelerated customer acquisition under India's Bureau of Energy Efficiency mandates.
- Solar Thermal:Flat-plate and evacuated-tube collectors drive absorption cycles with coefficient of performance ratings between 0.7 and 1.2, concentrating in Spanish and Italian public procurement frameworks.
- Absorption Cooling:Lithium bromide systems capture waste heat from cogeneration plants in Vietnam's industrial corridors, improving overall plant efficiency.
- Desiccant Cooling:Liquid desiccant dehumidification paired with indirect evaporative cooling addresses latent loads in humid subtropical climates without compression equipment.
Photovoltaic holds volume leadership. Absorption Cooling retains margin defense in industrial verticals.
End User:
Commercial building portfolios generate the largest project pipelines while industrial process cooling commands the highest per-kilowatt system values.
- Residential:Retrofit demand concentrates where photovoltaic-integrated mini-splits displace conventional split-system replacements, particularly in Australian high-solar-penetration suburbs.
- Commercial:Office and retail building operators across Southeast Asia accelerate adoption as grid instability and peak demand charges erode conventional HVAC economics.
- Industrial:Process cooling installations in Vietnam capture exhaust heat from cogeneration systems, accelerating payback through waste heat recovery.
- Hospitality:Hotels and resorts in Mediterranean climate zones face acute equipment transition pressure from EU F-Gas Regulation timelines, redirecting renovation capital toward absorption alternatives.
Commercial commands current deployment scale. Industrial offers the steepest expansion trajectory through waste heat integration.
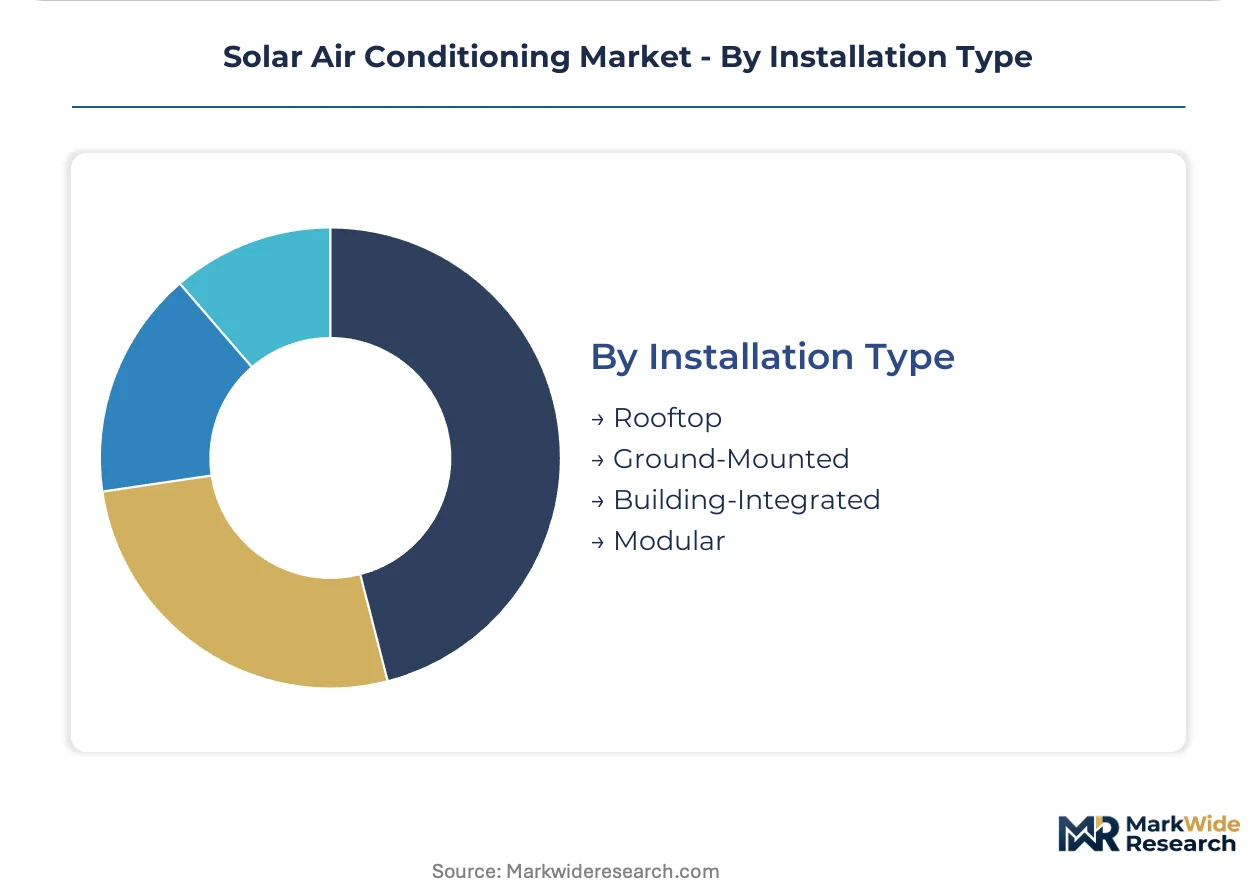
Installation Type:
Rooftop configurations dominate commercial retrofit activity while building-integrated photovoltaics reshape new construction specifications.
- Rooftop:Elevated mounting preserves ground area while maximizing solar exposure for absorption chiller retrofits in India's state-mandated commercial building portfolios.
- Ground-Mounted:Large-scale photovoltaic arrays serve centralized chiller plants in industrial zones where land availability permits optimized panel orientation.
- Building-Integrated:Façade-embedded photovoltaics replace conventional cladding materials, capturing Singapore's data center verticals where uptime requirements dominate capex minimization priorities.
- Modular:Prefabricated skid-mounted systems compress commissioning timelines for hospitality and healthcare verticals seeking resilience against peak demand charges under US Inflation Reduction Act credit structures.
Rooftop anchors near-term volume. Building-Integrated gains share fastest as new construction codes tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools concentrated in Japan's HVAC heritage centers and Germany's thermal systems corridors anchor technical development capacity for absorption chiller maintenance and crystallization prevention protocols.
United States
Commercial building operators in Arizona and Texas accelerate photovoltaic-integrated cooling retrofits as ERCOT grid instability and summer peak demand charges erode conventional HVAC economics. The EPA SNAP program restricts high-GWP refrigerants while the Inflation Reduction Act's investment tax credits improve project returns for hospitality and healthcare verticals. Installers in Phoenix and Dallas report compressed commissioning timelines for modular skid-mounted systems.
India
State-level solar rooftop obligations in Gujarat, Maharashtra, and Tamil Nadu mandate photovoltaic capacity for commercial buildings above specified floor areas. The Bureau of Energy Efficiency compresses payback periods for absorption chiller installations through efficiency mandates. Engineering procurement concentrates in Ahmedabad and Mumbai industrial corridors where export manufacturing zones face binding clean energy requirements.
Germany
Specialized technician knowledge for lithium bromide solution maintenance clusters among aging workforce cohorts in Stuttgart and Munich thermal engineering centers. The EU F-Gas Regulation phase-down eliminates high-GWP vapor-compression systems from renovation pipelines. Mediterranean-facing project developers specify absorption alternatives in public procurement frameworks across Bavaria and Baden-Württemberg.
Vietnam
Export manufacturing zones in Ho Chi Minh City and Binh Duong industrial corridors face binding clean energy procurement requirements from European buyers. Absorption chillers capture waste heat from cogeneration systems, improving overall plant efficiency and accelerating payback periods. Grid instability in southern provinces drives hybrid system specification for operational redundancy.
Australia
Photovoltaic-integrated mini-split systems with DC-native compressors rewrite deployment economics in Queensland and New South Wales suburbs where net metering tariff compression has eliminated export economics. Installers report accelerated customer acquisition as self-consumption architectures displace conventional split-system replacements. Sydney and Melbourne commercial portfolios favor energy-as-a-service arrangements over capital equipment ownership.
Solar Air Conditioning Market Competitive Environment
Capital-heavy producers compete with asset-light designers across technology vectors that demand divergent manufacturing footprints. The vendor base clusters around three strategic archetypes: diversified HVAC conglomerates with chiller engineering heritage, photovoltaic-integrated equipment specialists, and hybrid system fabricators blending thermal and electrical generation. Consolidation pressures intensify as energy-as-a-service business models displace traditional equipment sale-and-installation revenue pools. Dominant competitive moves include strategic partnerships between solar installers and HVAC contractors, plus geographic expansion into underpenetrated Southeast Asian commercial building markets.
Among diversified HVAC conglomerates, Carrier Global Corporation and Daikin Industries, Ltd. exemplify contrasting technology anchoring strategies. Lennox International Inc. occupies a position within the North American hybrid system segment. These three entities represent the tiered competitive structure where engineering heritage, photovoltaic integration capability, and regional regulatory familiarity determine project pipeline access. Their collective positioning illustrates how technology-specific regulatory exposure shapes manufacturing capacity commitments across Mediterranean, Indian, and Southeast Asian demand corridors.
| Leading Market Players |
|---|
| Lennox International Inc. |
| Gree Electric Appliances Inc. |
| HotSpot Energy |
| Solair World International |
| Daikin Industries, Ltd. |
| Midea Group |
| Carrier Global Corporation |
| Trane Technologies |
| Haier Group Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between EU F-Gas-compliant absorption chillers and conventional vapor-compression units manifests in both pricing premiums and supply chain sourcing patterns. Mediterranean project developers pay substantial markups for lithium bromide equipment meeting CE marking and EU Green Deal renovation criteria, while procurement teams source from concentrated East Asian manufacturing corridors to secure compliant components.
Pricing Analysis
Bundled energy-as-a-service contracts versus unbundled equipment sales split the market into divergent pricing architectures. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling, with EU F-Gas-compliant absorption systems commanding substantial premiums over commodity alternatives. Pricing pressure stems from lithium-ion battery cost volatility compressing project IRRs for photovoltaic-driven configurations. Commercial building operators in Southeast Asia exhibit highest price sensitivity due to capex minimization priorities, while Singapore data center verticals prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Freight cost escalation from East Asian industrial corridors to European project sites amplifies landed costs for lithium bromide absorption equipment. Manufacturing concentrates in China, Japan, and South Korea, with lithium bromide solution and evacuated-tube collectors drawing from concentrated chemical processing hubs. Single-source vulnerability pervades European and North American pipelines due to absorption chiller production clustering. Distribution runs through specialized HVAC contractors consolidating with solar installers to deliver integrated photovoltaic-thermal-gas configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where binding clean energy procurement requirements from European buyers force Vietnamese export manufacturers toward premium absorption chiller specifications with waste heat recovery capabilities.
For Market Incumbents: Anchor defensive positioning through captive supply of lithium bromide solutions and crystallization prevention protocols, countering technician scarcity that threatens service revenue pools. Deepen backward integration into photovoltaic-integrated mini-split compressor technologies to capture residential retrofit acceleration in India's state-mandated markets. Prioritize certification investment for EU F-Gas Regulation compliance to defend Mediterranean hospitality renovation pipelines against emerging Asian competitors. For New Entrants and Emerging Players: Indonesia's commercial building stock presents first-mover positioning where Jakarta and Surabaya office markets remain underpenetrated despite high grid tariffs and tropical cooling loads. Target desiccant-evaporative hybrid convergence for humid subtropical climates, addressing latent loads without compression equipment where absorption alternatives face coefficient-of-performance ceilings. Deploy energy-as-a-service business models to displace traditional equipment sale-and-installation revenue pools in Singapore's precision manufacturing verticals. For Investors and Strategic Acquirers: Consolidation pressure builds where energy-as-a-service business models displace traditional equipment sale-and-installation revenue pools, compressing standalone component manufacturers into strategic acquisition targets. Long-term viability favors vertically integrated platforms spanning photovoltaic generation, thermal storage, and predictive control systems. Watch for inflection where India's Bureau of Energy Efficiency mandates accelerate beyond Gujarat and Maharashtra into additional state-level solar rooftop obligation markets.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic-Thermal Hybrid Integration | Combines DC-native compressors with absorption cycles to eliminate inverter losses in Indian state-mandated markets. |
| Energy-as-a-Service Platform Launch | Retains asset risk while guaranteeing performance for Singapore data centers prioritizing uptime over capex. |
| EU F-Gas Compliance Certification | Unlocks Mediterranean hospitality renovation pipelines facing mandated equipment transition deadlines. |
| Waste Heat Recovery Partnership | Captures exhaust heat from Vietnam cogeneration systems to accelerate absorption chiller payback periods. |
| Technician Training Network Expansion | Addresses lithium bromide maintenance scarcity concentrated among aging workforce cohorts in Germany and Japan. |
Study Parameters
Direct dialogue with HVAC engineering directors, solar installer network heads, commercial building procurement officers, and absorption chiller maintenance technicians grounded qualitative findings in operational reality. Secondary validation drew from India's Bureau of Energy Efficiency mandate filings, EU F-Gas Regulation implementation timelines, Vietnam export manufacturing zone clean energy procurement contracts, and US Inflation Reduction Act credit structure documentation. Bottom-up project pipeline assessments across Gujarat, Maharashtra, Tamil Nadu, Ho Chi Minh City, and Mediterranean member states triangulated with top-down market sizing from equipment shipment data and installation permit records.
Bottom-up modeling tracked individual project economics across photovoltaic-driven, solar-thermal, and hybrid system configurations throughout the forecast period. Segmentation dimensions spanned product type, technology vector, end-user vertical, and installation architecture, with regulatory framework intensity and grid tariff structure serving as additional industry-specific forecast inputs. CAGRs derived from installed capacity build rates, payback period compression trajectories under evolving incentive structures, and substitution elasticities between absorption and vapor-compression alternatives.
Underlying measurement precision varies by segment; EU F-Gas-compliant absorption chiller pipelines carry tighter precision than emerging desiccant-evaporative hybrid deployments where technology convergence remains nascent. Forecasts reflect assumptions regarding lithium-ion battery cost trajectories, state-level mandate expansion timelines, and European buyer clean energy procurement clause enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Solar Cooling Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Global Air Coolers Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
Middle East and Africa Cooling Systems Market
Cooling Systems
Solar Fan Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Process Chillers Market
Cooling Systems
Global Condensing Unit Market
Cooling Systems
Cooling Tower Rental Market