
 Asia-Pacific Hot-Melt Adhesives Market | 2026-2036
Asia-Pacific Hot-Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hot-Melt Adhesives Market Outlook
The Asia-Pacific hot-melt adhesives market is pivoting on a widening split between premium specialty grades and commodity EVA formulations. Henkel AG & Co. KGaA leverages its European formulation heritage to dominate high-performance automotive and electronics segments across Japan and South Korea. H.B. Fuller Company anchors its position through deep distribution networks in Southeast Asian packaging hubs, while Pidilite Industries Ltd competes aggressively on cost-optimized woodworking and construction grades for India's domestic market.
Asia-Pacific hot-melt adhesives are thermoplastic polymer systems, typically formulated from ethylene vinyl acetate or styrenic block copolymers, that achieve bond strength upon cooling from a molten state applied between 120°C and 180°C. These adhesives serve primarily as fast-setting, solvent-free bonding agents in high-speed manufacturing environments where clamping time and environmental compliance constrain conventional alternatives. Styrenic block copolymers command the strongest margin pools in pressure-sensitive and elastic bonding applications for hygiene products and medical tapes. Polyurethane hot-melts capture the fastest growth trajectory in automotive interior assembly and electronics encapsulation where thermal and moisture resistance justify premium positioning over standard EVA grades.
Japan's METI enforces chemical substance reporting under its Industrial Safety and Health Act, while China's MEE implements VOC emission ceilings through its GB standards framework for adhesive manufacturing facilities. South Korea's MFDS maintains strict migration limits for food-contact adhesives, directly shaping formulation choices among packaging suppliers serving export markets. Stakeholders must monitor how India's BIS certification expansion and China's dual carbon enforcement timelines will reshape cost structures and regional supply qualifications.
Market Dynamics
The Asia-Pacific hot-melt adhesives market is bifurcating under pressure from China's dual carbon enforcement, which compresses EVA commodity margins while accelerating polyurethane and bio-based formulation premiums. MEE emission ceilings force facility upgrades across Shandong and Jiangsu provinces, reshaping regional supply qualifications.
Growth Catalysts
- E-commerce fulfillment acceleration:Packaging converters in Vietnam and Indonesia deploy high-speed hot-melt lines to match same-day delivery SLAs from regional logistics platforms.
- Automotive lightweighting mandates:India's PLI scheme for advanced chemistry cell batteries drives demand for thermally stable adhesives in electric vehicle battery pack assembly.
- GB standards compliance:China's VOC emission ceilings under MEE oversight push manufacturers toward low-odor formulations qualifying for green procurement tenders.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and vinyl acetate monomer prices track naphtha cracks, compressing formulation margins for EVA-based producers.
- Specialty resin import dependence:Styrenic block copolymer supply concentrates in South Korean and Japanese petrochemical complexes, exposing buyers to freight and forex risks.
- Polyurethane moisture-cure limitations:Ambient humidity requirements restrict application in Southeast Asian monsoon-season outdoor construction.
Strategic Opportunities
- Bio-based feedstock integration:Malaysian and Indonesian palm-derived polyol streams enable renewable-content positioning for EU-destined exports under EUDR traceability rules.
- Medical-grade certification:MFDS migration limits for food-contact and dermal applications create premium tiers for hygiene product adhesives in South Korean export manufacturing.
- Reverse logistics packaging:Returnable e-commerce parcel designs in Japan's metropolitan corridors specify removable hot-melt bonds enabling box reuse.
Industry Challenges
- Formulation chemist scarcity:Polyurethane reactive hot-melt expertise concentrates in Japanese and German technical centers, constraining localized R&D scale-up.
- BIS certification timelines:India's standards body expansion into adhesive grades delays product launches by 8-14 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hot-Melt Adhesives Market |
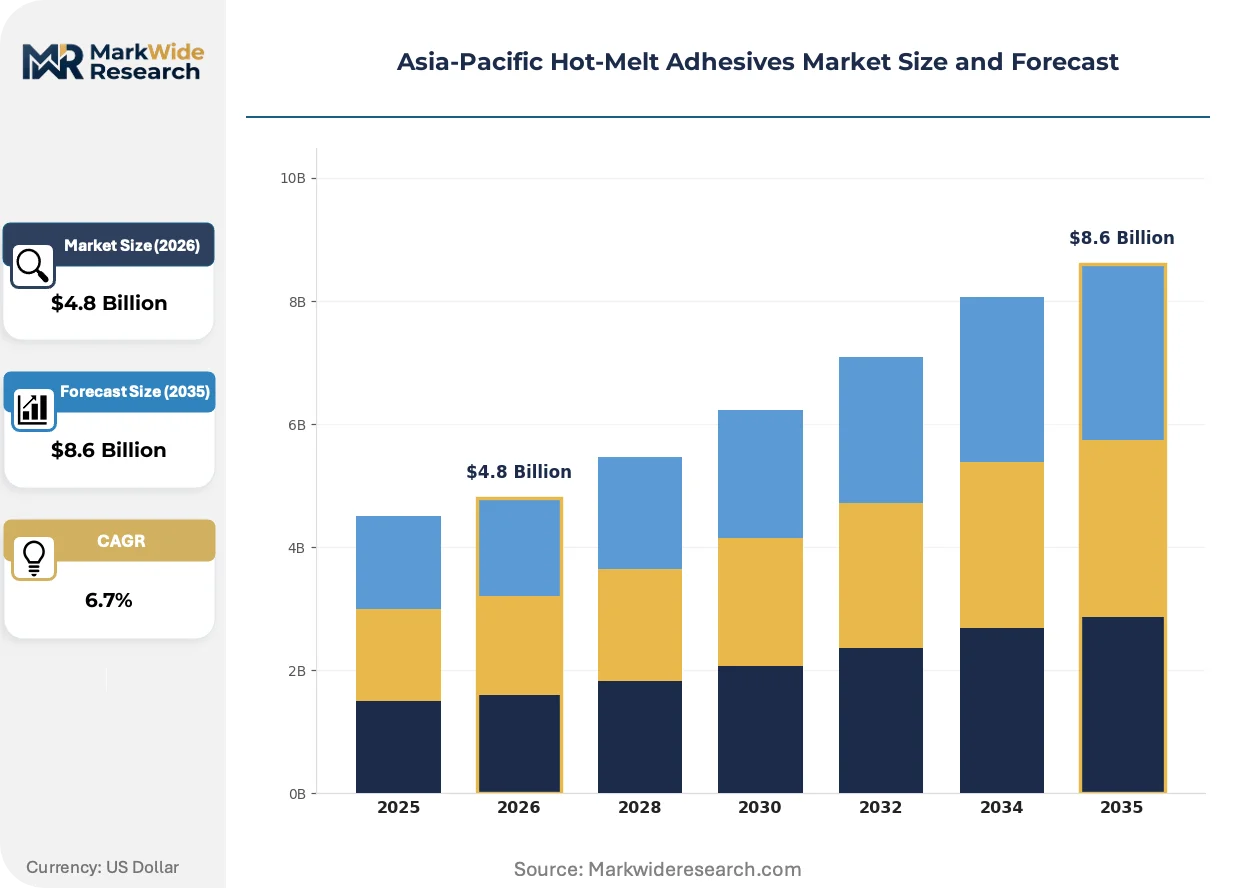
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Vinyl Acetate, Styrenic Block Copolymers, Polyurethane, Polyester End User: Packaging, Automotive, Electronics, Woodworking Application: Labeling, Bookbinding, Construction, Furniture Assembly Formulation: Water-Based, Solvent-Based, Hot-Melt, Reactive |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, Arkema Group, Dow, H.B. Fuller Company, Avery Dennison Corporation, Jowat, Pidilite Industries Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hot-Melt Adhesives Market Strategic Shifts
Reactive polyurethane hot-melt technology is compressing the performance gap between solvent-based structural adhesives and conventional thermoplastic systems. Formulation advances now enable moisture-cure chemistry to penetrate segments previously locked into two-part epoxies.
Polyurethane reactive hot-melts deliver structural bonding strength alongside thermal resistance exceeding 120°C. Automotive seating suppliers in Japan and South Korea adopt these systems for instrument panel and headliner assembly. The technology is expanding into electronics encapsulation where miniaturization demands thinner bond lines than EVA can achieve.
China's MEE implements GB 33372-2020 VOC content limits for adhesive manufacturing facilities, with provincial enforcement intensifying through 2025. Formulators face capital expenditure requirements for thermal oxidizers and solvent recovery systems. Small and mid-scale producers in Hebei and Zhejiang provinces consolidate or exit rather than upgrade, concentrating supply among MEE-compliant facilities.
Packaging buyers in Southeast Asia compress supplier rosters from five-plus vendors to two or three qualified partners. Centralized procurement teams at regional e-commerce platforms demand ISO 9001 and FSSC 22000 certification as baseline qualifications. This consolidation concentrates volume with Henkel, H.B. Fuller, and Pidilite distribution networks while marginalizing local blenders lacking audit documentation.
Asia-Pacific Hot-Melt Adhesives Market Segmentation
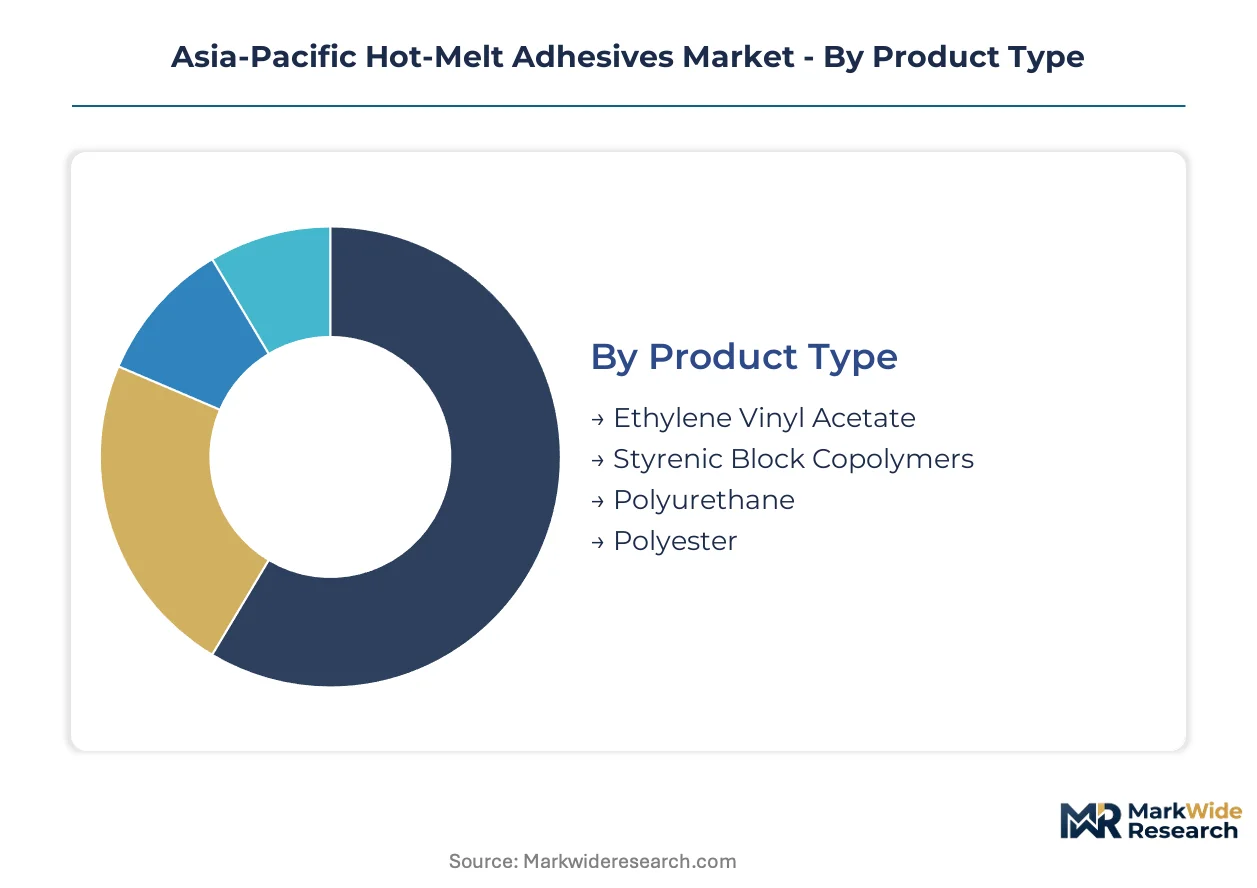
Asia-Pacific hot-melt adhesive buyers select formulations through divergent technical and commercial filters. Automotive engineers prioritize thermal stability and moisture resistance. Packaging converters optimize for set speed and total applied cost per thousand units.
Product Type:
Buyers in this category separate by performance tier versus cost sensitivity, with premium specifications commanding substantial formulation premiums over commodity grades.
- Ethylene Vinyl Acetate:The workhorse thermoplastic formulation blends ethylene and vinyl acetate monomers in ratios from 18% to 40% VA content. Packaging converters across Vietnam and Indonesia deploy EVA systems for high-speed carton sealing where sub-three-second set times match same-day delivery SLAs. MEE emission enforcement compresses margins for producers lacking thermal oxidizer upgrades.
- Styrenic Block Copolymers:SBC formulations combine styrene end-blocks with rubbery mid-blocks to deliver elastic recovery and pressure-sensitive tack. Hygiene product manufacturers in Japan and South Korea specify these grades for diaper construction and medical tape applications where skin-contact compliance under MFDS migration limits creates qualification barriers. Supply concentrates in South Korean and Japanese petrochemical complexes.
- Polyurethane:Moisture-cure reactive systems achieve structural bond strength exceeding 120°C thermal resistance. Automotive seating suppliers specify these for instrument panel assembly.
- Polyester:High-polarity formulations bond to engineered plastics and metalized films. Electronics encapsulation applications in India's Pune corridor drive specification.
Ethylene vinyl acetate leads volumes today; polyurethane is gaining share fastest.
End User:
Volume concentration varies sharply by end user, with e-commerce logistics platforms driving procurement consolidation toward qualified multinational suppliers.
- Packaging:Corrugated carton sealing and case erection consume the largest adhesive volumes regionally. Centralized procurement at Southeast Asian e-commerce platforms compresses supplier rosters to ISO 9001 and FSSC 22000 certified partners.
- Automotive:Interior trim assembly and battery pack bonding demand thermally stable formulations. India's PLI scheme for advanced chemistry cell batteries accelerates specification of polyurethane reactive systems in Pune and Ahmedabad manufacturing corridors.
- Electronics:Miniaturized devices require thinner bond lines than conventional thermoplastics achieve. Japan's METI chemical substance reporting shapes formulation choices.
- Woodworking:Furniture assembly and panel lamination in India's domestic market prioritize cost-optimized EVA grades. Pidilite Industries anchors distribution through construction chemical retail networks.
Packaging commands the greatest volume concentration; automotive applications are climbing the fastest.
Application:
Application selection tracks manufacturing line speed requirements and finished product durability specifications.
- Labeling:Pressure-sensitive adhesive coatings for beverage and logistics labels demand clean die-cutting and repositionability. Southeast Asian bottling plants specify SBC-based formulations for tropical climate adhesion.
- Bookbinding:Spine gluing and case-making operations in Japan's printing industry utilize EVA and PUR systems. Reactive polyurethane enables lay-flat binding for premium publications.
- Construction:Flooring installation and insulation bonding face seasonal humidity constraints. Monsoon conditions in Southeast Asia restrict moisture-cure polyurethane outdoor application.
- Furniture Assembly:Edge-banding and veneer lamination prioritize heat resistance for post-forming operations. China's GB 33372-2020 VOC limits reshape formulation availability.
Labeling generates the highest throughput volumes; construction applications face the steepest seasonal volatility.
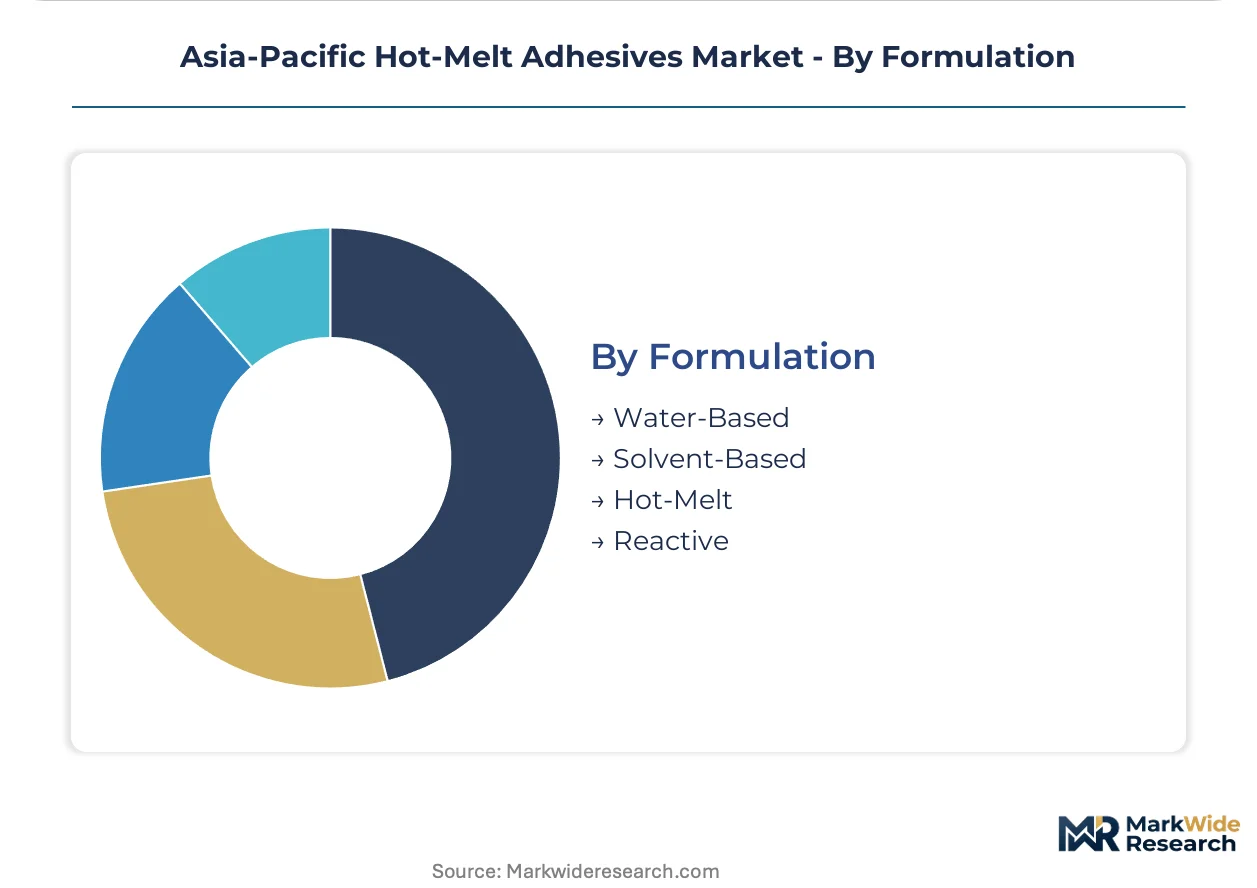
Formulation:
Formulation chemistry determines regulatory compliance pathway and capital intensity for manufacturing facilities.
- Water-Based:Acrylic emulsion systems carry lower VOC profiles but extended drying times limit high-speed applications. China's MEE enforcement accelerates interest for green procurement tenders.
- Solvent-Based:Traditional solutions face mounting regulatory pressure across the region. Facility upgrades for thermal oxidizer installation concentrate supply among capitalized producers.
- Hot-Melt:Thermoplastic systems dominate the regional market by volume. Instant bonding upon cooling eliminates drying infrastructure requirements.
- Reactive:Two-part epoxies and moisture-cure polyurethanes achieve structural performance. Formulation chemist expertise concentrates in Japanese and German technical centers.
Hot-melt formulations anchor regional supply today; reactive systems are expanding most quickly in automotive and electronics specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polyurethane formulation chemists cluster in Japanese technical centers and German research hubs, creating expertise scarcity that shapes regional competitive dynamics. This talent concentration limits localized R&D scale-up across emerging manufacturing corridors.
China
Dual carbon enforcement under MEE oversight compresses EVA commodity margins while accelerating premium polyurethane adoption. GB 33372-2020 VOC emission ceilings force thermal oxidizer upgrades across Shandong and Jiangsu provinces. Manufacturing gravity concentrates in the Yangtze River Delta where compliant facilities absorb volume from exiting small-scale producers.
Japan
Automotive seating and electronics encapsulation demand thermally stable adhesives exceeding 120°C resistance. METI enforces chemical substance reporting under the Industrial Safety and Health Act, shaping formulation disclosure requirements. Industrial activity clusters in the Chubu region around Nagoya, where instrument panel assembly operations specify moisture-cure reactive systems.
India
PLI scheme incentives for advanced chemistry cell batteries drive specification of thermally stable adhesives in electric vehicle battery pack assembly. BIS certification expansion into adhesive grades delays product launches by 8-14 months for new entrants. Manufacturing corridors around Pune and Ahmedabad anchor automotive seating and electronics assembly capacity expansion.
South Korea
Hygiene product and medical tape applications require skin-contact compliance under strict migration limits. MFDS maintains direct oversight of food-contact adhesive specifications, shaping export-oriented formulation choices. Petrochemical complexes in the Ulsan-Busan corridor concentrate styrenic block copolymer supply, exposing buyers to freight and forex exposure.
Vietnam
Packaging converters deploy high-speed hot-melt lines to match same-day delivery SLAs from regional e-commerce logistics platforms. General environmental enforcement follows ASEAN framework guidelines with increasing stringency. Manufacturing activity concentrates in northern industrial zones around Hanoi and Hai Phong, where carton sealing operations serve cross-border fulfillment networks.
Asia-Pacific Hot-Melt Adhesives Market Competitive Environment
Top-tier vendors anchor premium specialty grades, while mid-scale regional blenders compete on cost-optimized commodity EVA formulations. The market structure reflects a bifurcation between MEE-compliant facilities with thermal oxidizer investments and unupgraded producers facing consolidation pressure. Three strategic archetypes dominate: European heritage formulators leveraging technical reputation, Southeast Asian distribution network operators, and India-focused cost-optimized suppliers. Competitive moves center on certification acquisition for green procurement tenders and geographic expansion into industrial corridor clusters.
Among European-heritage multinationals, Henkel AG & Co. KGaA and H.B. Fuller Company occupy positions exemplifying premium-tier formulation capabilities and deep distribution architecture respectively. Pidilite Industries Ltd represents the India-focused archetype, anchoring cost-competitive positioning through construction chemical retail networks. These three entities illustrate how competitive advantage separates across technical specialization, channel control, and domestic market penetration vectors.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema Group |
| Dow |
| H.B. Fuller Company |
| Avery Dennison Corporation |
| Jowat |
| Pidilite Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
Regional e-commerce procurement teams at Shopee, Lazada, and Tokopedia platforms concentrate volume with ISO 9001-certified multinational suppliers, forcing three-tier pricing stratification across premium polyurethane, standard styrenic block copolymer, and economy EVA grades. This buyer consolidation rewards MEE-compliant facilities with thermal oxidizer investments while marginalizing unupgraded local blenders.
Pricing Analysis
Service bundling separates formulation supply from technical application support, with Japanese automotive OEMs paying premiums for on-site dispensing system integration alongside reactive polyurethane grades. Price differentiation rests on GB 33372-2020 compliance certification and thermal resistance specifications exceeding 120°C. Cost compression in commodity EVA tiers intensifies because MEE emission enforcement forces facility upgrades. Packaging converters in Vietnam and Indonesia exhibit highest price sensitivity, while Japanese automotive seating suppliers accept substantial premiums for METI-compliant formulation disclosure.
Supply Chain Analysis
Direct-to-automotive-OEM channels handle specification-grade polyurethane demand, while packaged goods distribution serves woodworking and construction segments across India. Feedstock supply concentrates in South Korea, Japan, and Thailand where petrochemical complexes produce styrenic block copolymers and EVA resins. Raw material sourcing draws from ethylene and vinyl acetate monomer streams tracking naphtha crack spreads, plus palm-derived polyol feedstocks from Malaysia and Indonesia. Single-source vulnerability runs through South Korean SBC supply exposing buyers to freight and forex exposure. Distribution runs through authorized distributor networks with technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific hot-melt adhesives market functions as a geographic-arbitrage play where MEE compliance costs in China's Yangtze River Delta exceed India's BIS certification timelines by 6-10 months, creating manufacturing relocation incentives.
For Market Incumbents: Deepen backward integration into palm-derived polyol supply from Malaysian and Indonesian feedstock streams to secure EUDR-qualifying renewable content positioning. Acquire thermal oxidizer-equipped facilities in Shandong and Jiangsu provinces to absorb volume from exiting small-scale competitors. Certification investment in MFDS food-contact migration compliance creates defensive moats against emerging regional blenders. For New Entrants and Emerging Players: E-commerce platform direct procurement portals offer the lowest barrier entry path for qualified specialty grade suppliers seeking to bypass established distributor networks. Target India's woodworking and furniture assembly segments where Pidilite's construction chemical retail concentration leaves technical-grade polyurethane penetration gaps. Pursue white-label manufacturing partnerships with Vietnamese packaging converters serving cross-border fulfillment networks. For Investors and Strategic Acquirers: Japanese automotive chemical suppliers are the most active acquirer in this space, seeking reactive hot-melt formulation expertise for battery pack assembly applications. Five-to-ten year viability favors MEE-compliant facilities with captive thermal oxidizer infrastructure and established green procurement tender qualifications. Monitor India's BIS certification expansion timelines as inflection indicator for market entry window viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Captive palm-derived polyol supply secures EUDR traceability for EU-destined exports. |
| Thermal Oxidizer Facility Upgrades | MEE GB 33372-2020 compliance qualifies producers for China's green procurement tenders. |
| MFDS Medical-Grade Certification | Migration limit compliance unlocks premium hygiene product adhesive tiers in South Korea. |
| Direct E-Commerce Platform Procurement | Centralized purchasing at Shopee and Lazada concentrates volume with certified multinational suppliers. |
| Polyurethane Reactive R&D Scale-Up | Moisture-cure expertise scarcity in Southeast Asia creates localized technical service differentiation. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with adhesive formulation chemists, automotive Tier 1 procurement managers, packaging converter operations directors, and MEE regional enforcement officers combined with secondary validation from customs trade data, China GB standards filings, SEC 10-K chemical segment disclosures, and ASEAN environmental enforcement reports. Triangulation between consumption-side volume estimates and production capacity tracking across Shandong, Jiangsu, and Ulsan-Busan corridor facilities ensures consistency.
Historical trendline analysis of ethylene-vinyl acetate and styrenic block copolymer consumption patterns informs projection modeling across the analysis window. Segmentation dimensions include product chemistry tier, end-use industry vertical, application line speed requirements, and regional regulatory compliance cluster. CAGRs derive from elasticity-adjusted demand curves incorporating automotive lightweighting mandates, e-commerce fulfillment acceleration, and dual carbon enforcement intensity. Forecast inputs incorporate PLI scheme incentive timelines for India's advanced chemistry cell battery manufacturing and MEE provincial enforcement escalation patterns.
Feedstock price volatility, regulatory enforcement acceleration, and formulation chemist availability constraints are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding MEE compliance penetration rates and BIS certification expansion scope. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global EVA Adhesives Market
Adhesives & Sealants
Mexico Adhesives Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Asia-Pacific Waterborne Adhesives Market
Adhesives & Sealants
Middle-East and Africa Cyanoacrylate Adhesives Market
Adhesives & Sealants
Rubber Repair Adhesives Market
Adhesives & Sealants
Gelatin Bone Glue Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Curing Agents Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Polyurethane Sealant Market
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
India Construction Chemicals Market