
 Global Bone Glue Market | 2026-2036
Global Bone Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bone Glue Market Foresight
A shift from single-source to multi-source procurement is consolidating among tier-one orthopedic supply chains. Stryker leverages its integrated hospital contracting networks to lock in volume commitments across major health systems. Zimmer Biomet anchors its position through dedicated R&D facilities focused on next-generation adhesive platforms. DePuy Synthes competes by controlling proprietary applicator designs that pair with its bone glue formulations.
Bone glue comprises synthetic or biological adhesive systems formulated to achieve rapid polymerization under physiological conditions, typically setting within 30–120 seconds at 37°C with tensile shear strengths exceeding 2 MPa for load-bearing orthopedic applications. The product serves to stabilize bone fragments, secure implants, and eliminate the morbidity associated with mechanical fixation hardware. Cyanoacrylate adhesives dominate current revenue due to their instant bonding profile and broad surgical acceptance, while polyurethane adhesives represent the fastest-expanding category owing to superior elasticity and osteoconductive additive compatibility. Orthopedic surgery commands the largest application share as arthroplasty and spinal fusion volumes rise, with maxillofacial surgery emerging as a concentrated margin pool where aesthetic outcomes justify premium pricing.
FDA 510(k) clearance requirements and the EU MDR's reinforced clinical evidence mandates are reshaping product development timelines and barrier to entry for new adhesive platforms. ISO 10993 biocompatibility testing series governs cytotoxicity and sensitization thresholds that all commercial formulations must satisfy. Stakeholders must monitor how FDA breakthrough device designations for novel hemostatic bone adhesives alter competitive dynamics and reimbursement pathways.
Market Dynamics
EU MDR's reinforced clinical evidence mandates and FDA 510(k) biocompatibility tightening are compressing product development timelines while elevating capital requirements for adhesive platform commercialization. Manufacturers now face dual-track regulatory navigation that favors incumbents with established ISO 10993 testing infrastructure.
Growth Catalysts
- EU MDR Clinical Evidence Mandates:Stricter biocompatibility documentation requirements under the Medical Device Regulation are filtering out marginal formulations and consolidating demand around validated suppliers with robust ISO 10993 testing capabilities.
- Spinal Fusion Volumes:Rising procedural counts in degenerative disc disease intervention are expanding the addressable patient pool for load-bearing adhesive applications requiring tensile shear strengths above 2 MPa.
- Cyanoacrylate Instant Bonding:The sub-30-second polymerization profile of current cyanoacrylate systems addresses operative time pressures in high-throughput orthopedic suites, sustaining surgical preference.
Market Restraints
- Polyol Feedstock Volatility:Polyurethane adhesive manufacturers face margin pressure from fluctuating isocyanate and polyether polyol input costs tied to petrochemical supply chains.
- German Notified Body Concentration:EU MDR certification capacity bottlenecks concentrate among a shrinking pool of designated conformity assessment bodies, extending time-to-market for new entrants.
- Mechanical Fixation Substitution:Locked plating systems and intramedullary nails retain surgeon preference in high-load fracture scenarios, capping adhesive penetration in trauma applications.
Strategic Opportunities
- India Orthopedic Infrastructure:Underpenetrated arthroplasty capacity in tier-2 and tier-3 cities under CDSCO jurisdiction offers whitespace for adhesive platforms compatible with cost-constrained surgical environments.
- Maxillofacial Aesthetic Premium:Craniofacial reconstruction applications command pricing multiples due to visible outcome sensitivity, attracting formulation investments in color-matched and low-exotherm systems.
- 3D-Printed Implant Convergence:Patient-specific additive manufacturing workflows create demand for adhesives engineered to bond with titanium lattice structures and PEEK substrates.
Industry Challenges
- Biomaterials Toxicology Expertise:ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization testing require specialized in-house capabilities or contracted laboratory relationships that extend development cycles.
- Legacy Applicator Integration:Surgical workflow compatibility demands that novel adhesive delivery systems interface with existing instrument sterilization protocols and operating room supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bone Glue Market |
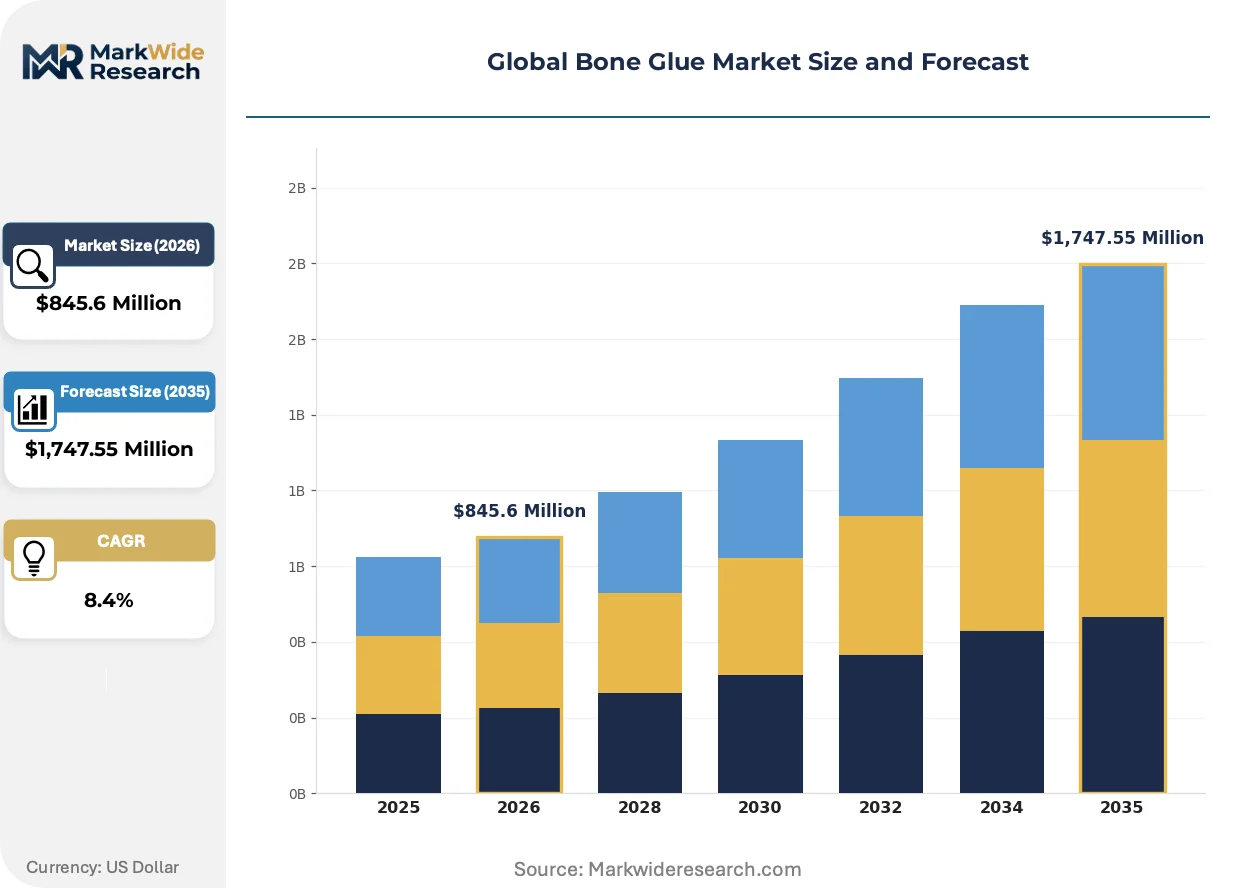
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,747.55 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyanoacrylate Adhesives, Epoxy Resins, Polyurethane Adhesives, Acrylic Adhesives, Silicone Adhesives Application: Orthopedic Surgery, Dental Procedures, Trauma Repair, Veterinary Use, Maxillofacial Surgery End User: Hospitals, Specialty Clinics, Research Institutions, Veterinary Clinics, Dental Laboratories Packaging Type: Syringes, Bottles, Tubes, Blister Packs, Single-use Ampoules |
| Companies Covered | Stryker, Zimmer Biomet, DePuy Synthes, Johnson & Johnson, Integra Lifesciences, B. Braun Melsungen, Baxter International, CryoLife, Luna Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bone Glue Market Shifts & Advancements
Osteoconductive additive integration and regulatory harmonization pressures are redefining competitive differentiation in bone adhesive platforms. Formulation science now converges with digital surgical planning tools.
Photocurable polyurethane systems incorporating hydroxyapatite and beta-tricalcium phosphate fillers are rewriting the performance envelope for load-bearing spinal applications. Academic medical centers in Germany and Japan are piloting these platforms in deformity correction cases. The technology is compressing the historical trade-off between setting speed and mechanical resilience.
FDA breakthrough device designation pathways for hemostatic bone adhesives are accelerating evidentiary requirements while opening priority review channels. The agency's orthopedics panel has issued draft guidance on weight-bearing adhesive claims that demands prospective clinical data. Small and mid-sized manufacturers are responding by pre-submission engagement to clarify predicate device strategies.
Health system procurement consolidation in the United States is disintermediating traditional distributor relationships. Integrated delivery networks now negotiate directly with adhesive manufacturers for multi-hospital contracts tied to arthroplasty volume commitments. This behavior is most visible in the southeastern and midwestern states where hospital merger activity has concentrated buying power among three to five dominant systems per metropolitan area.
Global Bone Glue Market Segmentation
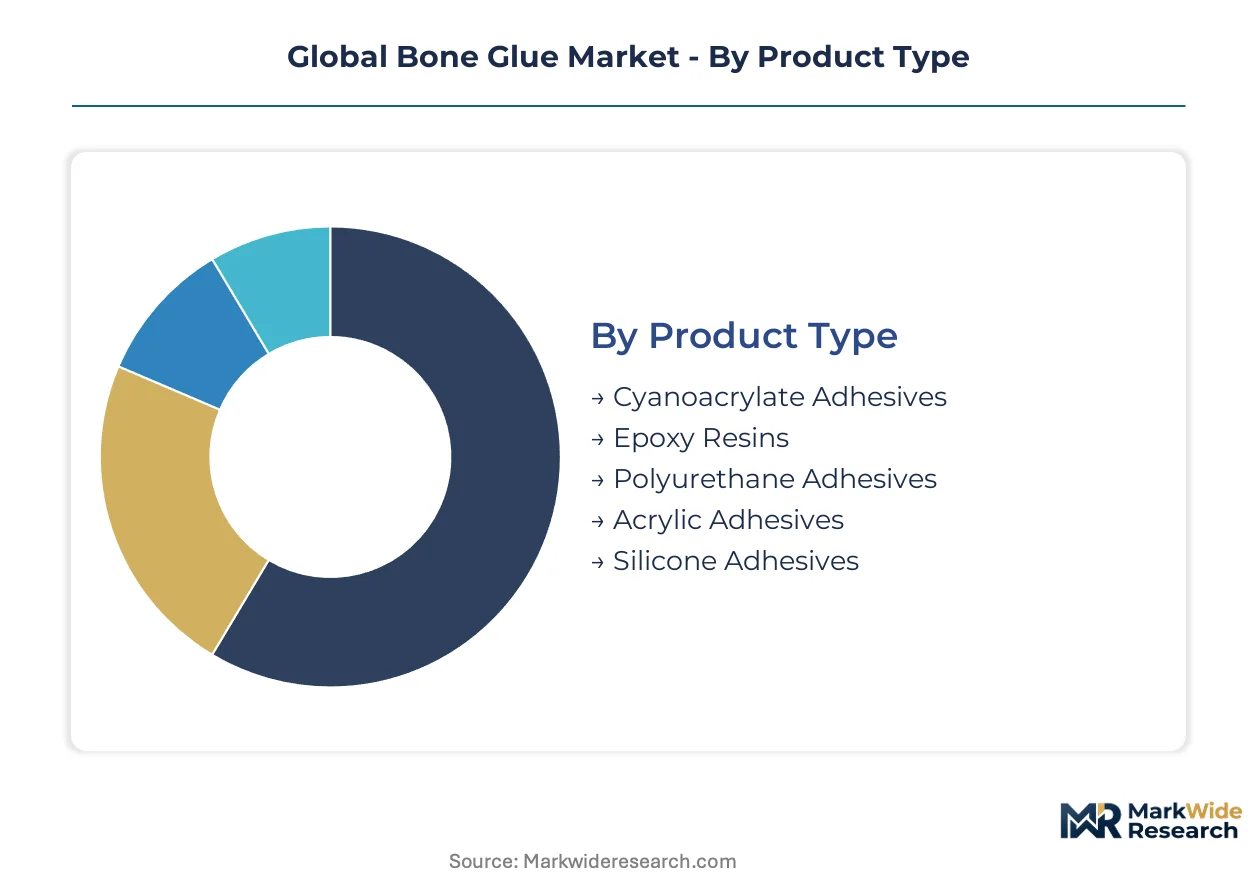
Bone glue segmentation reveals divergent regulatory pathways and technical specifications that shape supplier positioning. Product chemistry determines ISO 10993 testing burden, while application setting dictates whether FDA 510(k) or EU MDR clinical evidence thresholds apply.
Product Type:
Cyanoacrylate and polyurethane platforms carry the heaviest FDA biocompatibility documentation loads, while silicone and acrylic alternatives navigate lighter predicate device pathways.
- Cyanoacrylate Adhesives:N-alkyl and 2-octyl formulations polymerize through anionic chain reaction upon contact with tissue moisture, achieving tensile shear strengths exceeding 2 MPa within 30 seconds. Demand concentrates in United States arthroplasty suites where operative throughput pressures favor instant bonding profiles, though exotherm limitations restrict use near neural structures.
- Polyurethane Adhesives:Isocyanate-terminated prepolymers crosslink with tissue moisture to form elastomeric bonds with superior elasticity and hydroxyapatite filler compatibility. German and Japanese academic medical centers are piloting these systems in spinal deformity correction where load-bearing resilience trumps setting speed.
- Epoxy Resins:Two-part systems requiring manual mixing prior to application, primarily deployed in maxillofacial reconstruction where working time flexibility outweighs rapid polymerization needs.
- Acrylic Adhesives:PMMA-based formulations leveraging existing bone cement regulatory pathways, common in dental implant fixation where radiopacity requirements dominate specification sheets.
- Silicone Adhesives:Room-temperature vulcanizing elastomers offering biostability and minimal tissue reaction, finding niche use in veterinary soft-tissue adhesion where long-term implantation tolerance varies by species.
Cyanoacrylate Adhesives sits at the top of the volume ranking, with Polyurethane Adhesives climbing the fastest.
Application:
Procedure reimbursement codes and surgical volume economics segment the addressable market into high-throughput hospital settings versus premium-margin specialized interventions.
- Orthopedic Surgery:Arthroplasty and spinal fusion procedures in United States integrated delivery networks drive the largest adhesive consumption, with health system procurement consolidation favoring suppliers offering multi-hospital contracting leverage.
- Maxillofacial Surgery:Craniofacial reconstruction commands pricing multiples due to visible outcome sensitivity, attracting investments in color-matched and low-exotherm systems from manufacturers targeting aesthetic-conscious patient populations.
- Dental Procedures:Implant fixation and periodontal applications in German and Japanese dental laboratories emphasize radiopacity and handling characteristics over load-bearing performance.
- Trauma Repair:Emergency department applications face substitution pressure from locked plating systems in high-load fracture scenarios, capping adhesive penetration despite setting speed advantages.
- Veterinary Use:Cost-constrained companion animal and livestock applications in India tier-2 cities under CDSCO jurisdiction prioritize unit economics over advanced formulation features.
Orthopedic Surgery dominates procedure volumes, with Maxillofacial Surgery expanding most quickly on margin expansion.
End User:
Facility type determines sterilization protocol compatibility and inventory management requirements that shape packaging and applicator design priorities.
- Hospitals:Central sterile processing departments in United States southeastern and midwestern health systems demand adhesives compatible with standard autoclave cycles and existing orthopedic instrument trays.
- Specialty Clinics:Ambulatory surgery centers in Germany concentrate outpatient arthroplasty volumes, requiring just-in-time delivery logistics and compact storage footprints.
- Dental Laboratories:Japanese prosthodontic workshops prioritize precision dispensing and working time control for implant-supported restoration fabrication.
- Veterinary Clinics:Mixed-animal practices in India seek multi-species labeling and simplified storage conditions for field deployment.
- Research Institutions:Academic medical centers in Germany and Japan pilot photocurable polyurethane platforms, generating clinical evidence for regulatory submissions.
Hospitals anchor procurement volumes, with Specialty Clinics gaining share fastest through outpatient migration.
Packaging Type:
Delivery system design intersects with surgical workflow integration and waste reduction mandates across United States, German, and Japanese health systems.
- Syringes:Luer-lock compatible barrels dominate orthopedic suites for controlled extrusion and mixing of two-part systems, with United States health systems negotiating direct manufacturer contracts for volume commitments.
- Single-use Ampoules:Pre-measured unit doses eliminate mixing errors and reduce waste in German outpatient settings where regulatory scrutiny of sterile field maintenance intensifies under EU MDR.
- Bottles:Bulk containers serve dental laboratory workflows with high daily consumption and established repackaging protocols.
- Tubes:Collapsible aluminum or plastic tubes accommodate veterinary field applications requiring portability and extended shelf stability.
- Blister Packs:Individual cavity packaging supports inventory tracking requirements in Japanese hospital pharmacies with automated dispensing systems.
Syringes hold the volume lead, with Single-use Ampoules ascending fastest on sterility assurance priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warsaw's orthopedic manufacturing corridor anchors European adhesive production, with German notified bodies and Japanese academic medical centers completing the dominant geographic triangle for bone glue commercialization.
United States
Integrated delivery networks in the Southeast and Midwest negotiate multi-hospital volume contracts tied to arthroplasty procedures. FDA 510(k) clearance pathways govern cyanoacrylate and polyurethane platform submissions, with breakthrough device designations accelerating novel hemostatic adhesive reviews. Memphis and Warsaw, Indiana host concentrated orthopedic instrument manufacturing clusters where applicator-sterilization compatibility drives packaging specifications.
Germany
Academic medical centers in Berlin and Munich pilot photocurable polyurethane systems for spinal deformity correction cases. EU MDR clinical evidence mandates filter marginal formulations, with TÜV SÜD and BSI Group dominating notified body certification capacity. Baden-Württemberg's medical technology corridor integrates adhesive R&D with precision instrument fabrication.
Japan
Prosthodontic workshops in Osaka and Nagoya prioritize radiopacity and handling precision for dental implant fixation applications. PMDA consultation procedures align with FDA pre-submission engagement patterns for predicate device strategies. Tokyo's university hospitals generate clinical evidence supporting load-bearing adhesive claims in deformity correction.
India
Tier-2 and tier-3 cities under CDSCO jurisdiction present whitespace for cost-constrained adhesive platforms compatible with emerging arthroplasty capacity. Maharashtra and Gujarat host contract manufacturing organizations serving multinational orthopedic supply chains. Delhi-NCR research institutions collaborate on biocompatibility testing protocols adapted to tropical storage conditions.
Switzerland
Swissmedic's streamlined device registration attracts formulation specialists seeking EU MDR parallel certification efficiency. Basel's pharmaceutical-industrial complex supports biomaterials toxicology expertise for ISO 10993 testing series compliance. Zurich's university hospitals evaluate osteoconductive additive integration in maxillofacial reconstruction applications.
Global Bone Glue Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue photocurable polyurethane and 3D-printed implant convergence spaces. Market structure concentrates among integrated orthopedic conglomerates with hospital contracting networks, diversified medical device portfolios, and dedicated biocompatibility testing infrastructure. Three archetypes dominate: diversified orthopedic multinationals with applicator-sterilization integration capabilities, mid-cap adhesive specialists with ISO 10993-5 and ISO 10993-10 testing relationships, and research-stage platform developers targeting breakthrough device designation pathways. Competitive moves center on multi-source procurement consolidation and direct health system contracting disintermediation.
Within the diversified multinational tier, Stryker, Zimmer Biomet, and DePuy Synthes exemplify integrated orthopedic supply chain positioning. Stryker represents hospital contracting network leverage; Zimmer Biomet anchors dedicated R&D facility investment patterns; DePuy Synthes exemplifies proprietary applicator design control. These entities occupy positions where ISO 10993 testing infrastructure and regulatory submission experience create incumbent advantages under tightening FDA and EU MDR evidentiary requirements.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| DePuy Synthes |
| Johnson & Johnson |
| Integra Lifesciences |
| B. Braun Melsungen |
| Baxter International |
| CryoLife |
| Luna Innovations |
| Others |
Supply & Pricing Matrix
ISO 10993 certification tiers bifurcate bone glue procurement into validated premium suppliers versus marginal commodity players, with FDA 510(k) and EU MDR evidentiary burdens concentrating pricing power among incumbents while compressing margins for entrants lacking established biocompatibility testing infrastructure.
Pricing Analysis
Polyol feedstock volatility in isocyanate and polyether polyol markets passes directly into polyurethane adhesive pricing, with petrochemical-linked input costs forcing contract renegotiations annually. Three-tier pricing structure across premium, standard, and economy levels separates validated ISO 10993-5/10 compliant formulations from predicate-device alternatives and unbranded veterinary substitutes. Pricing pressure stems from German notified body certification bottlenecks extending time-to-market for new entrants. Tier-one orthopedic supply chains demonstrate lowest price sensitivity due to multi-hospital volume commitments, while India tier-2 veterinary clinics face acute cost constraints.
Supply Chain Analysis
Dual-sourcing mandates from United States integrated delivery networks and German hospital procurement committees require adhesive manufacturers to qualify secondary suppliers for cyanoacrylate monomers and hydroxyapatite fillers. Manufacturing concentrates in the United States, Germany, and Switzerland, with Warsaw's orthopedic corridor and Baden-Württemberg's medical technology cluster anchoring European production. Raw material dependencies center on petrochemical-derived polyols, pharmaceutical-grade cyanoacrylate monomers, and ceramic osteoconductive additives. Single-source vulnerability in German notified body certification capacity creates regulatory chokepoint risk. Distribution runs through direct manufacturer contracts with health systems, disintermediating traditional orthopedic distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EU MDR's clinical evidence burdens and India's CDSCO cost-constrained pathways, where tropical-adapted biocompatibility testing and contract manufacturing infrastructure enable margin capture absent in saturated Western markets.
For Market Incumbents: Deepen ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization testing capabilities to defend against emerging photocurable polyurethane platforms seeking FDA breakthrough device designation. Lock in multi-year volume commitments with southeastern and midwestern United States health systems before procurement consolidation peaks. Prioritize backward integration into polyol supply chains to offset petrochemical feedstock volatility eroding polyurethane margins.
For New Entrants and Emerging Players: Begin with maxillofacial surgery applications in Swissmedic and PMDA jurisdictions, where aesthetic outcome sensitivity justifies premium pricing without competing against Stryker's hospital contracting networks. Target India tier-2 arthroplasty capacity under CDSCO jurisdiction with cost-optimized cyanoacrylate formulations. Pursue white-label manufacturing partnerships with Maharashtra and Gujarat contract organizations to bypass capital-intensive ISO 10993 infrastructure.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 10993 testing infrastructure scarcity meets tightening FDA evidentiary requirements, favoring acquisition of mid-cap adhesive specialists with established notified body relationships over research-stage platform developers. Long-term viability hinges on photocurable polyurethane convergence with 3D-printed implant workflows. Watch for FDA draft guidance finalization on weight-bearing adhesive claims as inflection signal for clinical data investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Parallel Certification | Swissmedic streamlined registration accelerates dual-market access for osteoconductive formulations. |
| Hospital System Partnership | Direct contracting with United States integrated delivery networks locks in arthroplasty volume commitments. |
| Photocurable Platform Development | Hydroxyapatite-integrated polyurethane systems address spinal deformity correction load-bearing requirements. |
| Backward Integration | In-house polyol production mitigates isocyanate feedstock volatility compressing polyurethane margins. |
| CDSCO Market Entry | Tropical-adapted biocompatibility protocols enable cost-competitive positioning in India tier-2 cities. |
Research Methodology
Direct dialogue with orthopedic surgeons, hospital procurement committee members, biomedical engineers, and GPO contracts managers grounded qualitative insights, cross-referenced against FDA 510(k) filings, EU MDR notified body certification databases, CMS Medicare procedure volume data, and hospital procurement contract repositories. Secondary validation drew from SEC 10-K disclosures of diversified orthopedic multinationals and trade flow records for cyanoacrylate and polyurethane raw material inputs. Bottom-up procedure volume modeling and top-down adhesive consumption estimates were triangulated to constrain forecast variance.
Segment-level projections across product chemistry, application setting, and end-user facility type were generated across the analysis window, with CAGRs derived from historical procedure volume elasticities and adhesive penetration rate assumptions. Inputs included arthroplasty and spinal fusion procedural forecasts, health system merger activity tracking, and regulatory submission pipeline monitoring for novel hemostatic platforms.
Caveats apply where FDA breakthrough device designation pathways or EU MDR notified body capacity constraints could materially shift the outlook for new entrant commercialization timelines. Deviation in polyol feedstock pricing or German certification bottlenecks would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Moisture Curing Adhesives Market
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Polysulfide Sealants Market
Adhesives & Sealants
Wood Repair Epoxy Market
Adhesives & Sealants
Global Construction Adhesives Market
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
2-Octyl Cyanoacrylate Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
Flexible Packaging Adhesive Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Wearable Skin Adhesives Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Thailand Adhesives and Sealants Market