
 Russia Adhesives Market | 2026-2036
Russia Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Adhesives Market Analytics
Asset-light leasing arrangements for polymer blending equipment is rewriting competitive entry barriers in Russia's adhesives sector. Henkel AG & Co. KGaA leverages its captive distribution network to sustain shelf presence across Russian retail channels. Sika AG anchors its position through specialized construction-grade formulations for infrastructure projects. RusTA LLC competes on geographic proximity to Volga-region petrochemical feedstock suppliers.
Adhesives are polymeric substances formulated from epoxy, polyurethane, acrylic, or silicone bases that create structural bonds through surface adhesion and cohesive strength, typically cured via thermal, chemical, or UV activation to achieve shear resistance exceeding substrate failure limits. Their primary purpose spans permanent assembly, temporary fixation, and environmental sealing across industrial and consumer applications. Water-based technology leads volume in Russia due to tightening volatile organic compound limits, while reactive systems capture premium margins in automotive and aerospace bonding. Construction application dominates absolute consumption, though packaging segments show faster structural expansion driven by e-commerce logistics demand.
Russia's national standards body (GOST R) and technical regulation framework (TR EAEU) govern adhesive safety classifications, chemical composition disclosures, and import conformity procedures. The Eurasian Economic Union's unified technical regulations shape cross-border product certification requirements for suppliers operating across Belarus, Kazakhstan, and Russia. Stakeholders must monitor evolving EAEU chemical restriction lists and localize formulation testing capabilities to maintain uninterrupted market access.
Market Dynamics
Asset-light leasing of polymer blending equipment is compressing capital barriers for mid-tier entrants while TR EAEU chemical disclosure rules force foreign suppliers to localize testing capabilities. This dual pressure is fragmenting competitive positioning between capital-efficient domestic blenders and compliance-heavy multinational formulators.
Growth Catalysts
- Automotive lightweighting mandates:Russian OEMs are expanding adhesive bonding in chassis and body-in-white assembly to replace mechanical fasteners, pulling demand for structural epoxy and polyurethane systems.
- E-commerce logistics expansion:Packaging adhesive consumption is accelerating in Moscow's fulfillment corridor as cold-chain and corrugated box sealing requirements intensify for perishable delivery networks.
- TR EAEU harmonization:Unified technical regulations across the Eurasian Economic Union are simplifying cross-border certification for suppliers operating in Belarus, Kazakhstan, and Russia simultaneously.
Market Restraints
- Petrochemical feedstock volatility:Crude-derived polyol and epoxy resin costs fluctuate with Volga-region refinery output, compressing margin predictability for formulators without backward integration.
- Import substitution pressure:BIS alignment requirements for chemical formulations create compliance friction for European and Asian suppliers lacking localized testing infrastructure.
- Water-based performance ceiling:VOC-compliant aqueous systems face shear strength limitations in high-temperature automotive underhood applications, restricting penetration in powertrain bonding.
Strategic Opportunities
- Siberian industrial corridor:Underpenetrated manufacturing zones east of the Urals present first-mover potential for construction-grade adhesive distributors establishing regional blending facilities.
- Reactive system convergence:UV-curable and moisture-cure hybrid technologies are opening premium positioning in electronics assembly and medical device bonding previously served by thermal cure systems.
- Rail infrastructure modernization:Federal transport spending is creating demand for specialized track bonding and composite panel adhesives in high-speed corridor development.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise concentrated in Moscow and St. Petersburg limits scaling of regional technical service capabilities for customized industrial adhesives.
- GOST R certification timelines:Extended conformity assessment periods for new chemical entities delay product launches by 12-18 months, compressing effective patent windows.
- Legacy solvent system integration:Industrial buyers face retrofit costs and process revalidation burdens when transitioning established production lines from solvent-based to water-based or reactive chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Adhesives Market |
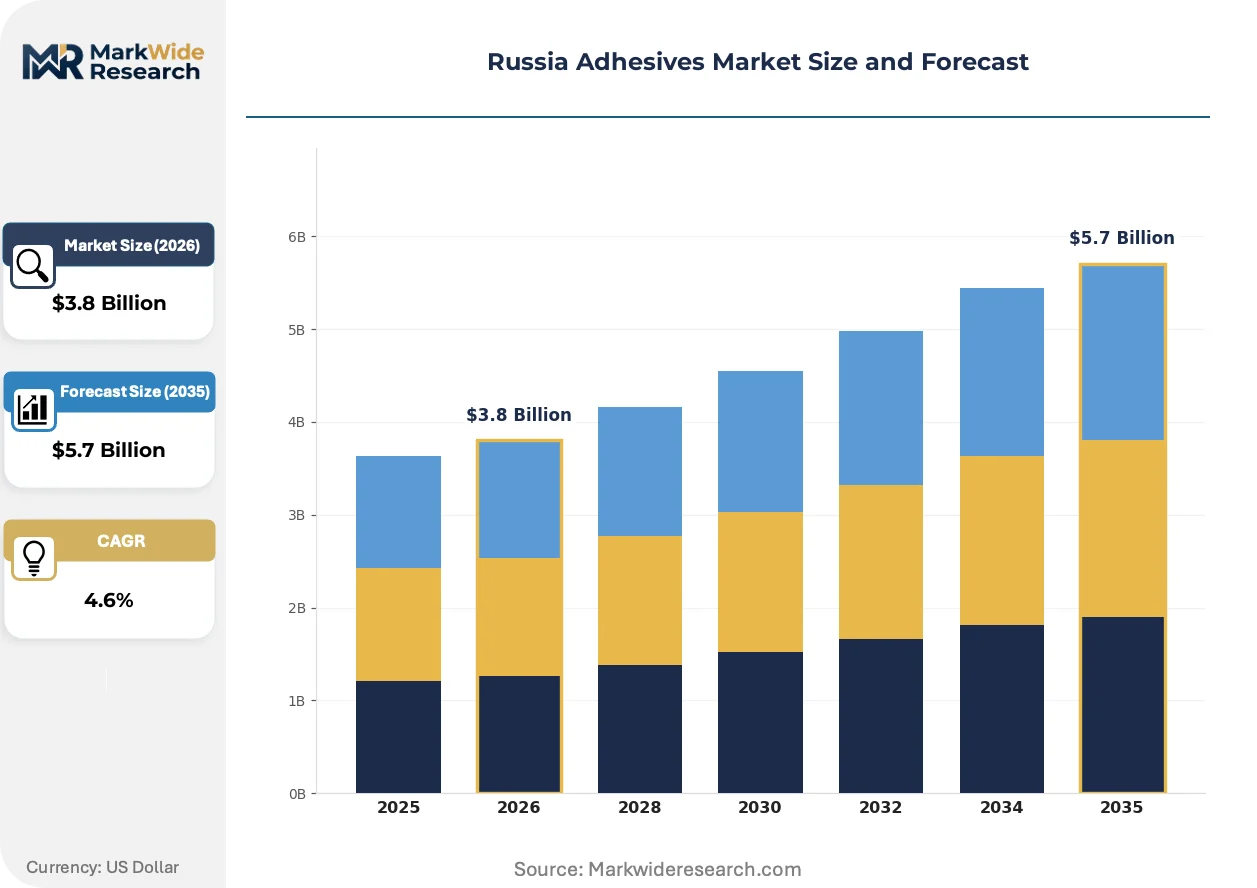
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone Application: Construction, Automotive, Packaging, Woodworking Technology: Hot Melt, Water-Based, Solvent-Based, Reactive End User: Manufacturers, Contractors, Retailers, DIY Consumers |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, H.B. Fuller Company, RusTA LLC, Kiilto, Arkema Group, MAPEI S.p.A., Huntsman International LLC, KLEBCHEMIE M. G. Becker GmbH & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Adhesives Market Evolving Landscape
Formulation chemistry is hybridizing across cure mechanisms while regulatory pressure on volatile organic compounds intensifies compliance investment. Distribution models are fragmenting as direct procurement from blenders displaces traditional distributor intermediaries in high-volume segments.
Hybrid cure technology is hybridizing epoxy-acrylic and polyurethane-silicone systems to deliver simultaneous structural strength and environmental resistance. Automotive tier-one suppliers are piloting these formulations in battery enclosure bonding for electric vehicle platforms. The convergence is compressing the traditional segmentation between structural and sealant applications.
TR EAEU technical regulations on chemical safety are mandating expanded substance disclosure and hazard classification for imported adhesive formulations. Foreign suppliers must now maintain in-country testing partnerships to maintain conformity certificates. Construction-grade products face the steepest compliance burden due to broader chemical ingredient portfolios.
Buyer concentration in Moscow's industrial corridor is consolidating procurement authority among large automotive and packaging converters. These purchasers are negotiating direct supply agreements with Volga-region petrochemical blenders, bypassing legacy distributor networks. The disintermediation is most visible in high-volume water-based packaging adhesive categories where specification standardization enables spot purchasing.
Russia Adhesives Market Segmentation
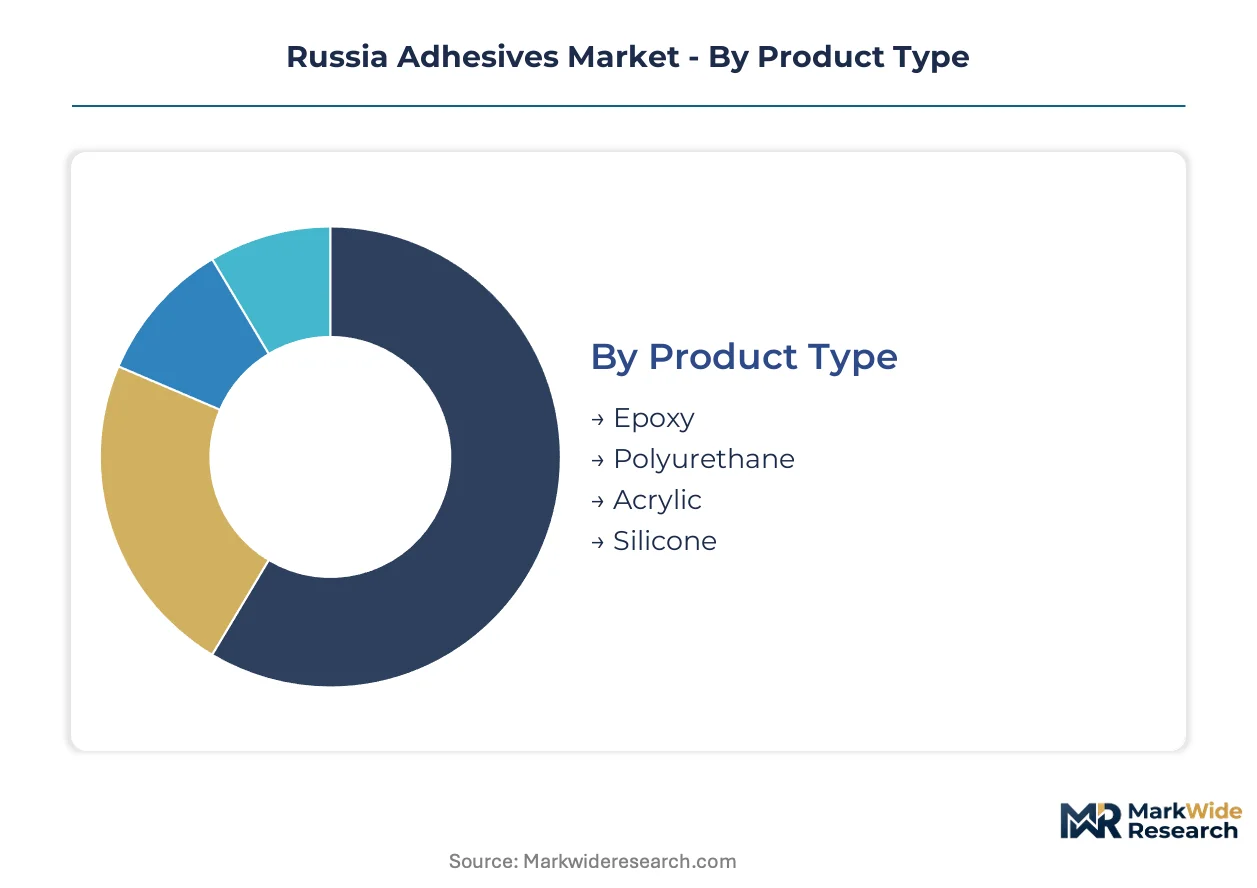
Russia's adhesives market fragments across four critical dimensions that determine formulation chemistry, regulatory compliance burden, and channel economics. Each segmentation axis reveals distinct competitive battlegrounds between multinational suppliers and domestic blenders navigating TR EAEU technical regulations.
Product Type:
Structural bonding requirements span load-bearing assembly through flexible sealing applications, driving specification diversity across Russian industrial procurement.
- Epoxy:Two-part thermosetting systems deliver shear resistance exceeding 20 MPa in automotive chassis bonding and wind turbine blade lamination. Moscow's automotive OEMs specify epoxy for battery enclosure assembly in electric vehicle platforms, though cure time requirements limit line-speed applications.
- Polyurethane:Moisture-cure and two-component formulations dominate construction panel bonding and flexible packaging lamination. Volga-region petrochemical feedstock proximity gives domestic blenders cost advantage in commodity polyurethane dispersions for St. Petersburg's woodworking cluster.
- Acrylic:Pressure-sensitive and structural variants serve electronics assembly and medical device bonding with UV-cure capability. TR EAEU chemical disclosure rules complicate import of acrylic monomers not on the unified EAEU registry.
- Silicone:High-temperature resistant formulations seal automotive underhood components and building envelope joints. Siberian infrastructure projects specify cold-cure silicones for sub-zero application conditions.
The dominant share belongs to Polyurethane, while Epoxy is closing the gap fastest.
Application:
End-use concentration in Moscow's industrial corridor and St. Petersburg's manufacturing zone shapes regional demand patterns and distributor logistics.
- Construction:Ceramic tile adhesives, waterproofing membranes, and insulation panel bonding consume the largest absolute volume. Federal housing programs and commercial real estate development in Moscow drive specification toward cement-modified and dispersion-based systems.
- Automotive:Structural bonding in body-in-white assembly and interior trim attachment commands premium pricing. Russian OEMs are replacing spot welds with adhesive bonding in lightweight aluminum-intensive platforms, pulling demand for crash-durable formulations.
- Packaging:Corrugated box sealing and flexible film lamination accelerate with e-commerce logistics expansion. Cold-chain packaging requirements in Moscow's fulfillment corridor favor hot-melt and water-based systems with low-temperature flexibility.
- Woodworking:Furniture assembly and engineered wood panel production concentrate in St. Petersburg and the Central Federal District. Formaldehyde emission regulations under TR EAEU are displacing urea-formaldehyde resins toward PVAc and polyurethane alternatives.
Construction maintains volume leadership, though Packaging is expanding most quickly.
Technology:
Regulatory pressure on volatile organic compounds is compressing solvent-based share while reactive systems capture performance-critical applications.
- Hot Melt:Thermoplastic EVA and polyolefin formulations dominate high-speed packaging lines and bookbinding. Instant green strength eliminates clamping requirements, critical for Moscow's corrugated box converters serving same-day delivery networks.
- Water-Based:Acrylic and polyurethane dispersions lead environmental compliance in construction and woodworking. VOC limits under TR EAEU technical regulations are accelerating displacement of solvent systems, though cold-temperature performance gaps persist in exterior applications.
- Solvent-Based:Declining share in regulated applications persists in specialty laminating and footwear bonding. Remaining demand concentrates in industrial segments where water-based alternatives lack adhesion to low-surface-energy substrates.
- Reactive:UV-curable, moisture-cure, and two-component systems command premium positioning in electronics and medical device assembly. Siberian electronics manufacturing zones are piloting UV-curable acrylics for display bonding to eliminate thermal cure bottlenecks.
Water-Based technology holds the largest installed base, while Reactive systems are gaining share fastest.
End User:
Procurement authority concentration determines pricing power and technical service requirements across the value chain.
- Manufacturers:Automotive OEMs, packaging converters, and electronics assemblers negotiate direct supply agreements with petrochemical blenders. Volume concentration in Moscow's industrial corridor enables specification standardization and spot purchasing.
- Contractors:Construction firms and installation specialists demand localized technical support and just-in-time delivery. Regional distributors maintain inventory positions across Russia's federal districts to serve project-based procurement.
- Retailers:Hardware chains and specialty distributors stock consumer and light industrial grades. Henkel and Sika maintain shelf presence through captive distribution networks in Russian retail channels.
- DIY Consumers:Small-format packaging and application convenience drive purchasing decisions. E-commerce penetration in Moscow and St. Petersburg is fragmenting traditional retail channel dominance.
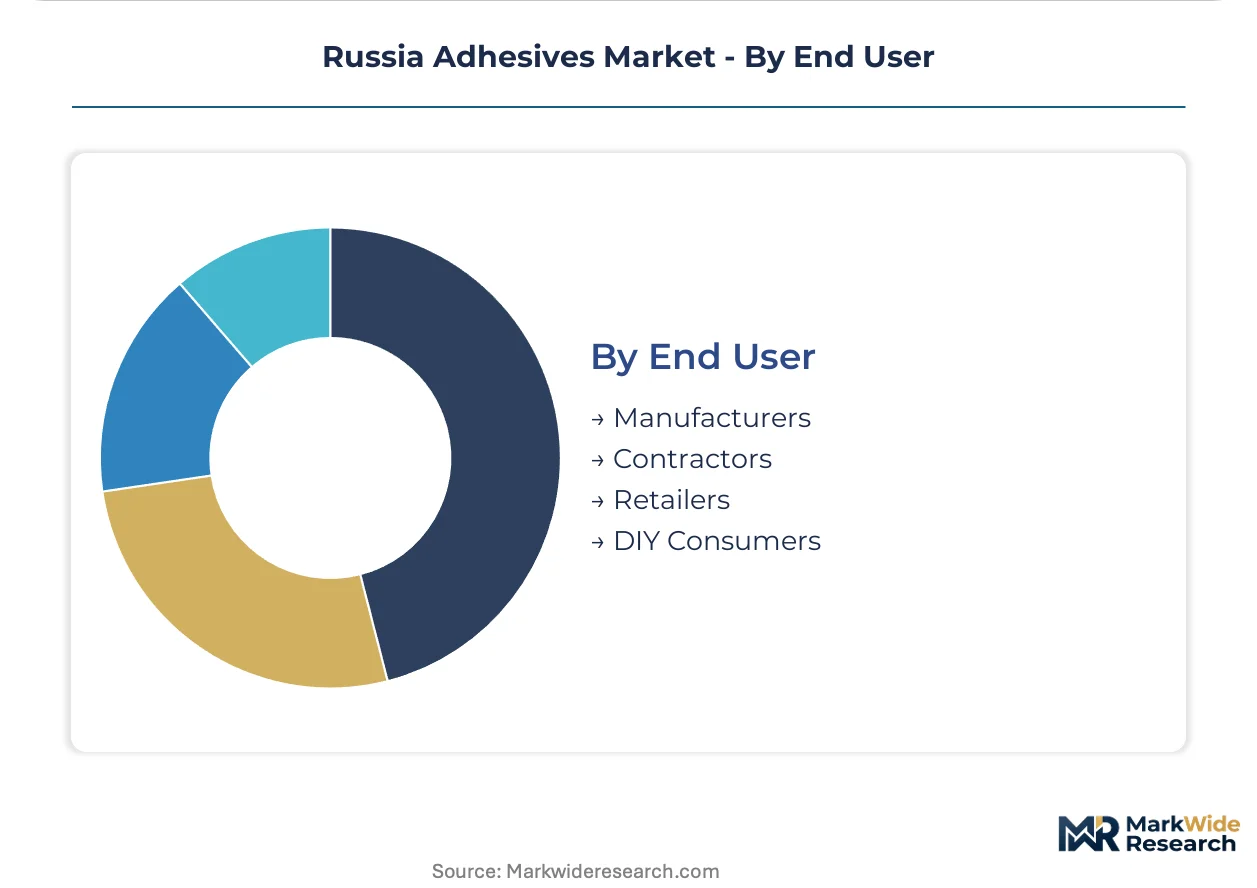
Manufacturers capture the dominant procurement volume, while DIY Consumers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's adhesives trade balance tilts toward net import dependence for specialty formulations, though domestic petrochemical capacity anchors polyurethane feedstock supply. Export flows concentrate on construction-grade dispersions to Belarus and Kazakhstan under EAEU tariff preferences.
Central Federal District
Moscow's automotive OEMs specify crash-durable epoxy systems for aluminum-intensive vehicle platforms. TR EAEU technical regulations mandate localized conformity assessment for all imported adhesive formulations. The Zelenograd electronics cluster pilots UV-curable acrylics for display bonding applications.
Northwestern Federal District
St. Petersburg's woodworking industry consumes PVAc and polyurethane dispersions for engineered panel production. GOST R standards enforce formaldehyde emission limits that displace legacy urea-formaldehyde resins. The port city's logistics infrastructure enables direct procurement from European suppliers for specialty reactive systems.
Volga Federal District
Petrochemical refineries in Tatarstan and Samara supply polyol feedstocks to domestic polyurethane blenders. BIS alignment requirements for imported chemical formulations create compliance friction for Asian suppliers lacking regional testing partnerships. The corridor's blending facilities serve construction adhesive demand across the Urals.
Siberian Federal District
Sub-zero construction conditions specify cold-cure silicone formulations for building envelope sealing. Federal transport spending on rail modernization creates demand for track bonding and composite panel adhesives. Novosibirsk's industrial zone remains underpenetrated for construction-grade adhesive distribution.
Southern Federal District
Rostov-on-Don's agricultural machinery assembly pulls demand for structural bonding in composite component fabrication. Import substitution policies favor domestic blenders for state-funded infrastructure projects. The region's port access supports Black Sea trade routes for epoxy resin imports.
Russia Adhesives Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. Russia's adhesives sector fragments between multinational formulators with captive distribution networks and domestic blenders leveraging petrochemical feedstock proximity. Three archetypes dominate: compliance-heavy foreign suppliers navigating TR EAEU disclosure rules, capital-efficient regional blenders with Volga-region supply chain integration, and specialty chemical distributors serving project-based construction procurement. Competitive moves center on backward integration into polyol production and geographic expansion toward Siberian industrial corridors.
Within the multinational tier, Henkel AG & Co. KGaA and Sika AG exemplify divergent positioning strategies. Henkel occupies a position anchored in retail channel presence across Russian consumer and light industrial segments. Sika sits within the construction-grade specialty tier, with formulation focus on infrastructure project specifications. RusTA LLC represents the domestic archetype, leveraging geographic proximity to Volga-region petrochemical suppliers for polyurethane feedstock cost advantage.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| H.B. Fuller Company |
| RusTA LLC |
| Kiilto |
| Arkema Group |
| MAPEI S.p.A. |
| Huntsman International LLC |
| KLEBCHEMIE M. G. Becker GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Tatarstan's petrochemical refineries anchor feedstock supply for polyurethane dispersions, concentrating cost advantage among domestic blenders while foreign formulators absorb TR EAEU compliance premiums. This geographic asymmetry compresses margin parity between Volga-region producers and imported specialty systems.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with spot purchasing for standardized water-based packaging grades. Price differentiation rests on GOST R certification tier and volume scale, with construction contractors showing highest sensitivity to freight-adjusted delivered costs. Pricing pressure stems from feedstock volatility in polyol and epoxy resin inputs, while automotive OEMs demonstrate lowest price sensitivity for crash-durable structural formulations.
Supply Chain Analysis
Extended payment terms from Moscow's automotive OEMs strain working capital for mid-tier blenders lacking supply-chain finance facilities. Raw material flows draw from Germany, China, and South Korea for specialty epoxy resins and acrylic monomers, with polyol feedstock anchored in domestic Volga-region refineries. Single-source vulnerability concentrates in UV-curable photoinitiator imports. Distribution runs through captive networks for multinational suppliers and regional distributors for construction-grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's adhesives sector sits at a platform-economics inflection where TR EAEU regulatory harmonization is collapsing cross-border certification friction and enabling supplier interoperability across Belarus, Kazakhstan, and Russia.
For Market Incumbents: Insulate formulation portfolios from import substitution pressure by deepening captive polyol production in Tatarstan and securing GOST R certification pipelines for new chemical entities. Channel control through retail shelf presence defends against direct procurement consolidation among Moscow's packaging converters. For New Entrants and Emerging Players: Build out regional blending capacity in Novosibirsk's underpenetrated Siberian corridor to capture construction-grade demand from federal rail modernization spending. A technical service partnership model with local contractors bypasses incumbent distributor lock-in. For Investors and Strategic Acquirers: Carve-out targets emerge from European chemical conglomerates divesting non-core adhesive divisions under TR EAEU compliance burden. The long-term viability window favors specialists with backward integration into petrochemical feedstocks. Watch for GOST R timeline acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Volga-region refinery partnerships secure feedstock cost advantage against imported resin volatility. |
| GOST R Certification Localization | In-country testing partnerships reduce conformity assessment delays for foreign formulation entrants. |
| Siberian Distribution Expansion | Novosibirsk blending facilities capture first-mover position in underpenetrated construction markets. |
| Hybrid Cure Technology Development | UV-moisture dual-cure systems open electronics assembly applications beyond thermal cure limits. |
| Direct Procurement Platform Launch | Spot purchasing portals disintermediate legacy distributors in high-volume packaging adhesive segments. |
Research Methodology
Initial hypotheses were tested against primary input from adhesive formulation chemists, automotive OEM procurement officers, construction contractor purchasing managers, and regional distribution channel heads and refined through secondary validation against customs trade data, EAEU technical regulation filings, GOST R certification registries, and petrochemical refinery output disclosures. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product chemistry, application end-use, cure technology, and procurement authority concentration. CAGRs derived from elasticity-adjusted volume projections incorporating automotive lightweighting penetration rates and e-commerce packaging throughput expansion.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed domestic blenders would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Lamination Adhesive Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Wood Repair Epoxy Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Craft Glue Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
Epoxy Active Diluent Market