
 Nigeria Tile Adhesive Market | 2026-2036
Nigeria Tile Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Tile Adhesive Market Foresight
Modular packaging of tile adhesive in smaller sachets and bucket sizes is decoupling bulk procurement from site-level consumption, letting contractors match purchase volume to project phase. Lafarge Africa Plc leverages its cement distribution network to push bundled adhesive-and-grout offerings through hardware retail chains. Dangote Cement Plc anchors its position via backward integration into limestone-derived binder inputs, cutting raw material transit costs. Sika AG competes on polymer-modified technology leadership, targeting high-specification commercial flooring contracts in Lagos.
Nigeria tile adhesive comprises cementitious or polymer-enhanced bonding compounds formulated to secure ceramic, porcelain, and natural stone tiles to substrates, with open times typically ranging from twenty to forty minutes and shear adhesion strengths exceeding one megapascal after full cure. Thin-set formulations dominate volume flows in residential tiling across Lagos and Abuja due to lower per-square-meter material cost and compatibility with standard notched trowel application. Epoxy segments command premium positioning in industrial food-processing and pharmaceutical clean-room installations where chemical resistance and zero-porosity joints prove mandatory. Polymer-modified technology leads growth trajectory as reformulated latex additives improve flexibility on plywood and concrete-block substrates prone to differential movement.
The Standards Organisation of Nigeria mandates NIS compliance for cement-based adhesives, while imported polymer resins face SONCAP certification scrutiny that lengthens customs clearance cycles. The Federal Ministry of Works and Housing infrastructure procurement guidelines increasingly specify certified adhesive products for public building contracts, redirecting contractor sourcing toward documented supply chains. State-level environmental regulations in Lagos and Rivers govern construction waste disposal, indirectly favoring pre-mixed adhesive bags over site-mixed sand-cement pastes that generate excess spoil. Stakeholders must monitor SON's anticipated tightening of VOC limits in polymer-modified formulations, as compliance recalibration will reshape import sourcing and domestic blending capacity decisions.
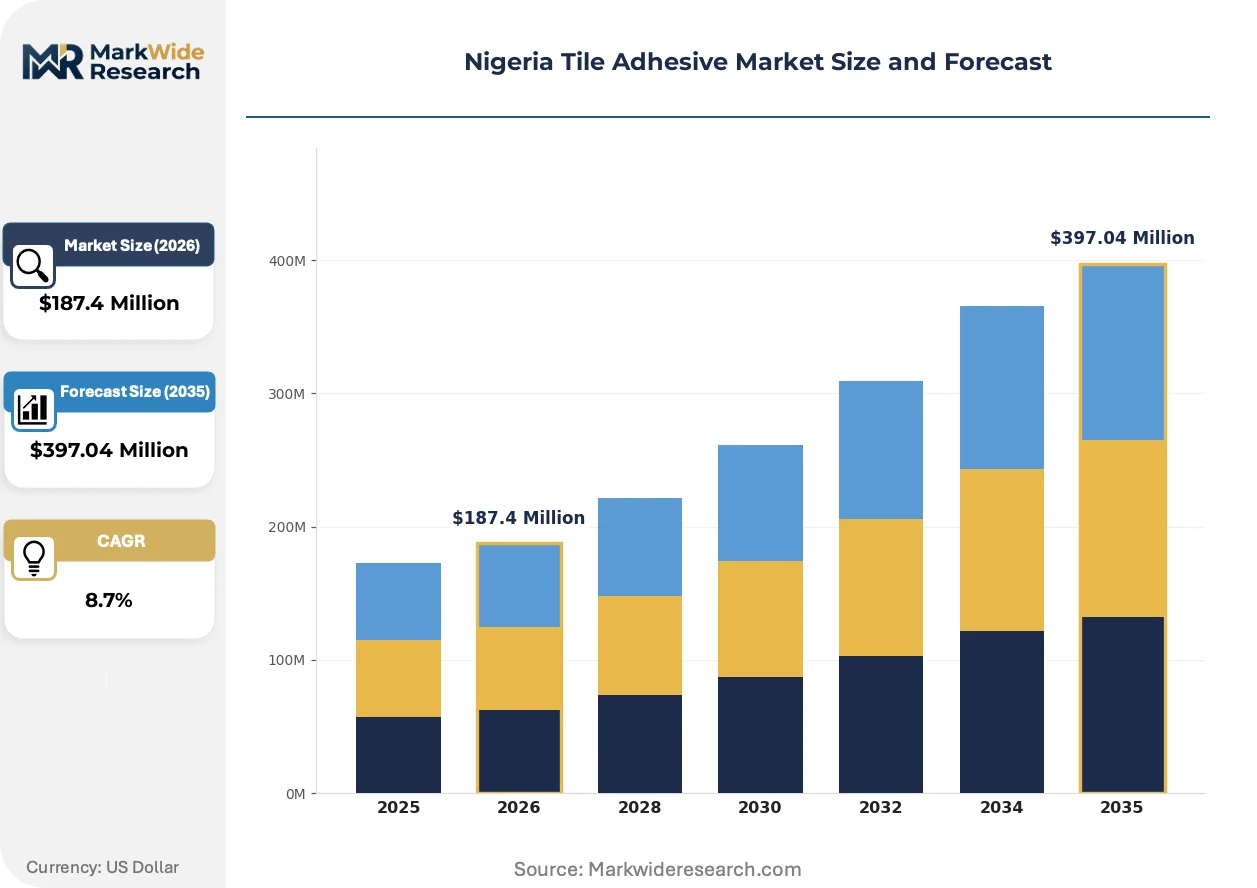
Market Dynamics
Polymer-modified thin-set formulations are displacing conventional cement-sand site mixes across Nigerian residential construction, compressing application labor hours while forcing domestic blenders to retrofit production lines for latex additive incorporation.
Growth Catalysts
- Federal Ministry procurement mandates:Public building contracts now require certified adhesive documentation, redirecting contractor sourcing toward compliant domestic supply chains and away from informal site-mixed alternatives.
- Lagos-Rivers housing stock renewal:State-level urban regeneration programs in Nigeria's South-West corridor accelerate tile replacement cycles in aging residential blocks, concentrating volume demand in polymer-enhanced thin-set categories.
- Epoxy technology penetration:Industrial food-processing and pharmaceutical clean-room specifications now mandate zero-porosity joint systems, opening premium contract segments previously served by conventional grouted installations.
Market Restraints
- Imported polymer resin dependency:SONCAP certification scrutiny at Nigerian customs lengthens clearance cycles for latex additives, creating inventory volatility for domestic blenders without captive resin supply.
- Limestone transport cost concentration:Backward-integrated cement producers control binder input logistics, raising effective barriers for independent adhesive manufacturers sourcing clinker from dispersed quarry locations.
- Site-mix substitution persistence:Informal sand-cement pastes retain cost advantage in rural construction segments, capping price realization for packaged pre-mixed products outside major urban corridors.
Strategic Opportunities
- North-Central corridor penetration:Abuja satellite city developments and Nasarawa state housing projects remain under-supplied by certified adhesive distributors, offering first-mover positioning for SON-compliant logistics networks.
- Modular sachet distribution:Smaller packaging formats decouple bulk procurement from phased construction consumption, enabling hardware retail penetration in secondary cities lacking organized contractor purchasing.
- VOC limit anticipation:Standards Organisation of Nigeria's expected tightening of volatile organic compound thresholds in polymer-modified formulations creates compliance-first positioning for domestic blending capacity investments.
Industry Challenges
- Skilled applicator scarcity:Notched trowel technique certification for polymer-modified open-time management remains concentrated among Lagos and Abuja contractor pools, limiting product performance realization in secondary markets.
- Blending line capex intensity:Latex additive metering equipment and controlled humidity storage requirements demand capital deployment that mid-scale domestic producers struggle to finance without cement group backing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Tile Adhesive Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-set, Thick-set, Epoxy, Urethane Application: Residential, Commercial, Industrial, Renovation Technology: Cement-based, Polymer-modified, Hybrid, Anhydrite End User: Contractors, DIY Enthusiasts, Architects, Retailers |
| Companies Covered | Helmar Building Materials Ltd., Lafarge Africa Plc, Henkel Corporation, BUA Group, Dangote Cement Plc, Sika AG, Cormart, Interteck Group, Fosroc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Tile Adhesive Market Shifts & Advancements
Formulation chemistry and procurement logistics are converging to reshape competitive positioning in Nigerian tile adhesive, with technology diffusion outpacing regulatory calibration and distribution infrastructure adaptation.
Polymer-modified thin-set technology is expanding into plywood and concrete-block substrates previously considered unsuitable for ceramic installation due to differential movement risks. High-rise residential developers in Lagos Island and Ikoyi districts are specifying these formulations for balcony and wet-area tiling at accelerating rates. The shift is compressing demand for traditional thick-bed mortar systems while elevating shear adhesion performance benchmarks across residential contract specifications.
Standards Organisation of Nigeria enforcement of NIS compliance for cement-based adhesives is tightening product certification documentation requirements for imported binder shipments. Customs clearance delays for non-compliant consignments are redirecting contractor procurement toward domestic manufacturers with established SON laboratory relationships. Small-scale importers lacking in-country testing partnerships face effective market exclusion from public sector and commercial flooring contracts.
Site-level purchasing is fragmenting across phased project consumption patterns, with contractors abandoning bulk upfront procurement in favor of just-in-time hardware retail acquisition. Lagos hardware chains are responding with inventory positioning of 5kg and 20kg sachet formats matched to apartment-renovation scale. The behavioral shift is compressing distributor credit terms and elevating working capital requirements for manufacturers serving retail channel partners.
Nigeria Tile Adhesive Market Segmentation
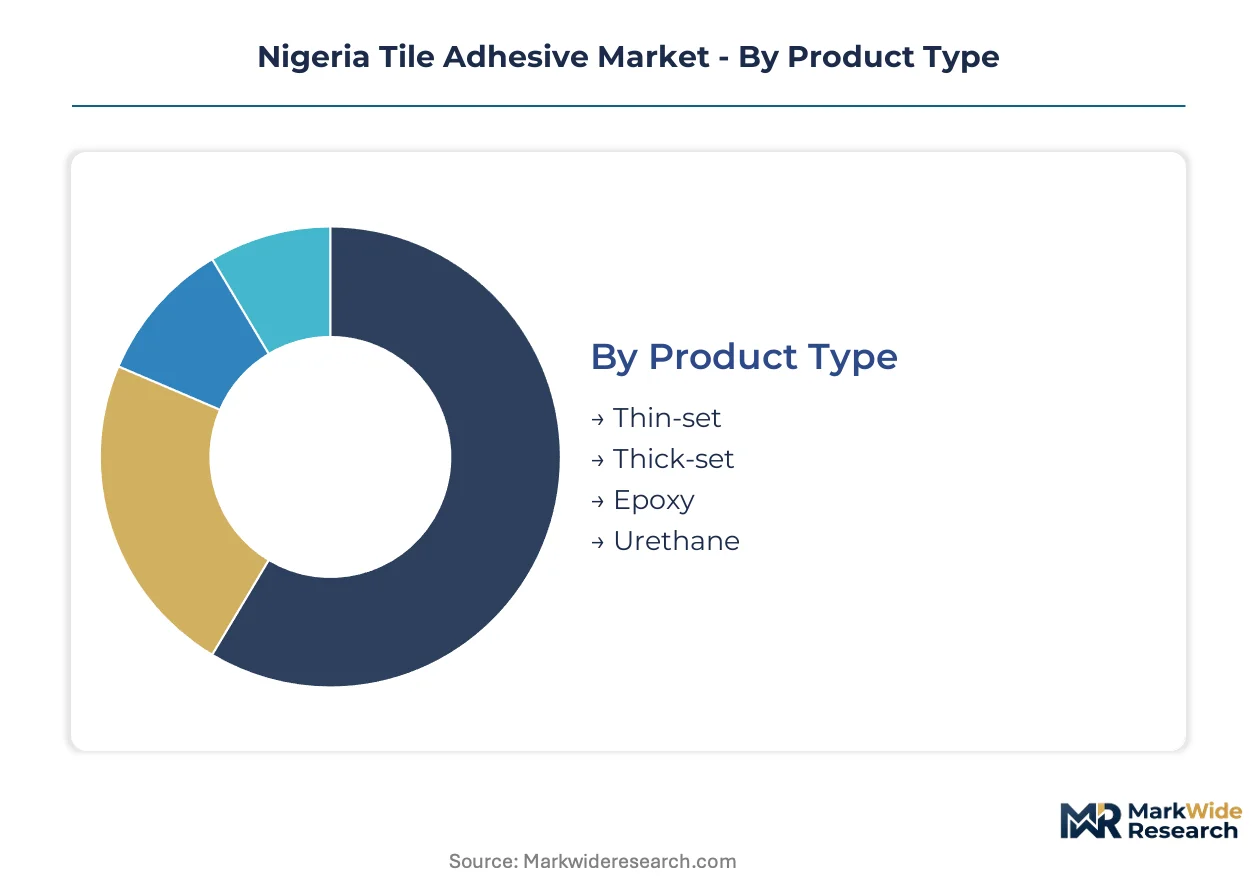
Segmentation in Nigeria's tile adhesive market reveals how procurement patterns diverge across construction types and buyer sophistication. Specification-grade products command premium positioning in formal contracts, while cost-optimized formulations penetrate informal residential channels.
Product Type:
Buyers select product type based on substrate complexity and performance warranty requirements, with labor cost savings often outweighing material price differentials.
- Thin-set:Cementitious or polymer-enhanced formulations applied in 3-6mm layers dominate Lagos and Abuja residential volume. Contractors favor these for standard ceramic and porcelain installations where substrate flatness permits direct bonding without screed preparation.
- Epoxy:Two-component resin systems deliver zero-porosity joints mandatory for pharmaceutical clean-rooms and food-processing facilities in Lagos industrial zones. Premium pricing reflects chemical resistance specifications and specialized applicator certification requirements.
- Thick-set:Traditional sand-cement mortars applied 12-25mm thick retain cost advantage in rural construction where substrate leveling consumes labor hours anyway.
- Urethane:Flexible single-component adhesives penetrate balcony and exterior tiling specifications in high-rise Ikoyi developments, accommodating thermal movement without joint failure.
Thin-set leads on scale; Epoxy leads on momentum.
Application:
Application segmentation tracks construction cycle timing, with new-build specifications differing sharply from renovation procurement patterns in hardware retail channels.
- Residential:Volume concentrates in South-West corridor housing stock renewal, where polymer-modified thin-set displaces site-mix alternatives in Lagos apartment renovations and Abuja satellite city developments.
- Commercial:Office and retail flooring contracts in Lagos Island business districts specify extended open-time formulations, compressing installation schedules for fast-track tenant fit-outs.
- Industrial:Food-processing and pharmaceutical installations in Rivers State drive epoxy specification for chemical resistance compliance.
- Renovation:Phased consumption patterns favor modular sachet packaging through hardware retail, decoupling procurement from bulk contractor purchasing.
Residential commands volume concentration; Renovation shows steepest expansion trajectory.
Technology:
Technology selection hinges on substrate movement risk and Standards Organisation of Nigeria certification status, with polymer content directly correlating to specification tier.
- Cement-based:Unmodified Portland cement formulations with sand aggregate serve cost-sensitive rural markets and basic residential tiling where substrate stability permits rigid bonding.
- Polymer-modified:Latex-enhanced systems dominate Lagos high-rise specifications, improving flexibility on plywood and concrete-block substrates prone to differential movement.
- Hybrid:Dual-binder systems combining cement and polymer resins penetrate mid-tier commercial contracts seeking performance without full epoxy cost.
- Anhydrite:Calcium sulfate-based formulations serve specialized underfloor heating installations in premium Abuja residential developments, offering thermal conductivity without cement shrinkage.
Cement-based retains volume leadership; Polymer-modified gains share fastest.
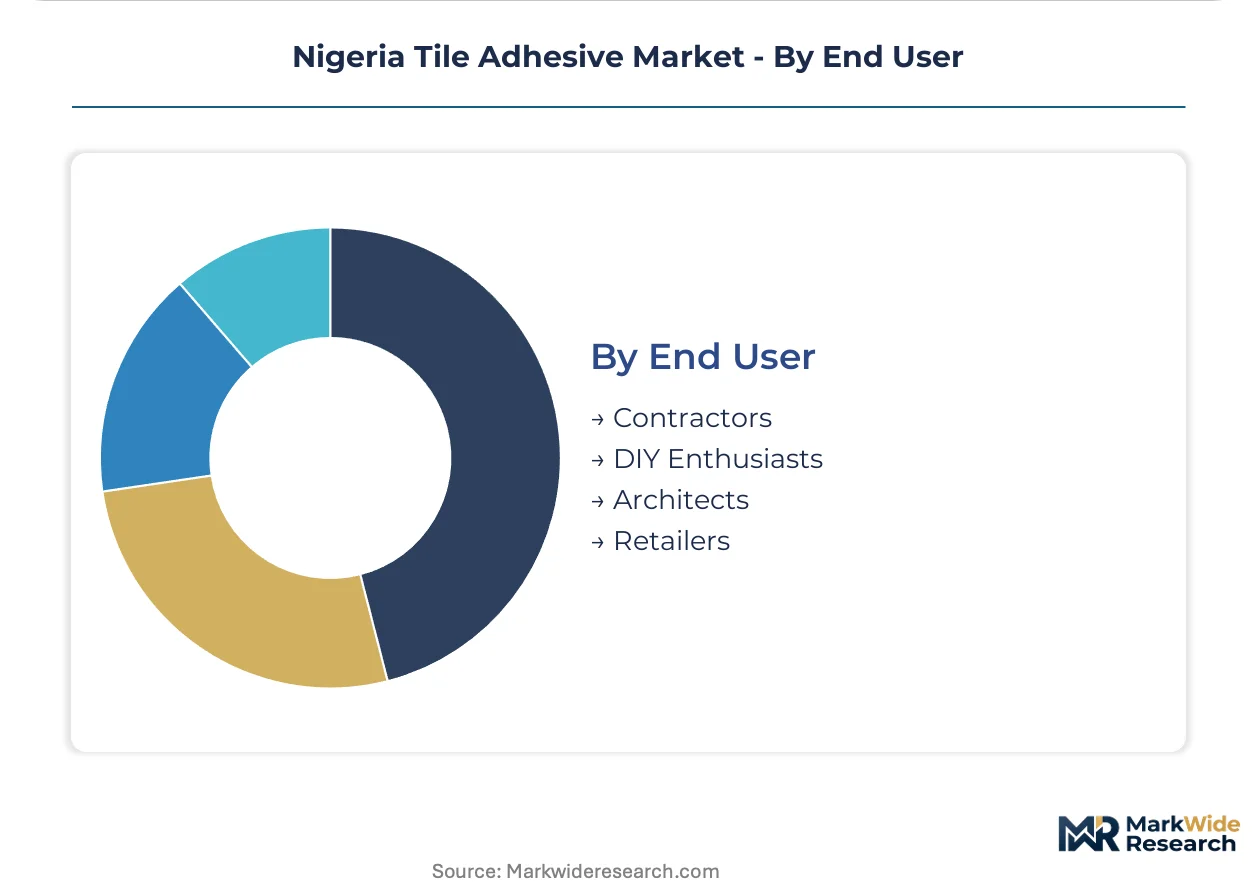
End User:
End user segmentation captures purchasing authority dispersion, with specification influence residing separately from procurement execution and consumption.
- Contractors:Organized tiling crews in Lagos and Abuja drive bulk procurement through distributor relationships, prioritizing open-time consistency and batch-to-batch color matching.
- Architects:Specification writers in commercial and industrial projects mandate certified products with NIS documentation, redirecting contractor sourcing toward compliant supply chains.
- DIY Enthusiasts:Apartment owners in Lagos secondary districts purchase 5-20kg sachets through hardware retail for bathroom and kitchen renovations, price-sensitive but brand-aware.
- Retailers:Hardware chains in South-West corridor cities inventory modular formats, managing working capital compression from just-in-time contractor purchasing shifts.
Contractors anchor volume flows; Architects steer specification value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tile adhesive demand in Nigeria traces its commercial lineage to the cement industry's post-colonial expansion, when Portland cement distributors first bundled bonding compounds with bulk construction materials. Regional differentiation now reflects state-level urbanization intensity and enforcement capacity for building standards.
Lagos State
High-rise residential towers in Ikoyi and Victoria Island specify polymer-modified thin-set for balcony waterproofing and wet-area tiling. The Lagos State Environmental Protection Agency enforces construction waste disposal rules that favor pre-mixed adhesive bags over site-mixed spoil. Lekki-Epe corridor developers source certified products through organized hardware retail chains serving fast-track tenant fit-outs.
Federal Capital Territory
Abuja satellite city developments in Kubwa and Lugbe drive volume for modular sachet formats matched to phased housing construction. Federal Ministry of Works and Housing procurement guidelines mandate NIS-compliant adhesive documentation for public building contracts. Jabi and Wuse districts concentrate distributor warehousing for North-Central corridor logistics.
Rivers State
Industrial food-processing and pharmaceutical installations in Port Harcourt specify epoxy systems for zero-porosity clean-room compliance. SONCAP certification scrutiny at Onne and Port Harcourt ports lengthens customs cycles for imported polymer resins. Trans-Amadi industrial zone anchors specialized applicator certification programs for chemical-resistant flooring.
Oyo State
Ibadan residential stock renewal accelerates thin-set displacement of traditional sand-cement site mixes in middle-income housing estates. Standards Organisation of Nigeria regional laboratory partnerships expedite product certification for domestic blenders serving South-West corridor demand. Moniya and Challenge districts concentrate mid-scale contractor purchasing through independent hardware distributors.
Kano State
Informal construction segments in northern Nigeria retain cost-optimized cement-based formulations where substrate stability permits rigid bonding. State-level building control enforcement remains less intensive than in southern corridors, capping premium product penetration. Sabon Gari and Bompai industrial zones host small-scale blending operations supplying regional retail networks.
Nigeria Tile Adhesive Market Competitive Landscape
The competitive structure tilts toward cement-group-backed integrated manufacturers with captive binder supply and distribution infrastructure. Three archetypes dominate: backward-integrated cement producers leveraging limestone quarry control; polymer-technology specialists competing on formulation performance; and regional distributors with SON laboratory relationships expediting certification. Capacity expansion and retail channel penetration constitute the dominant competitive moves, as players retrofit blending lines for latex additive incorporation and push modular packaging through hardware chains.
Among cement-group-affiliated manufacturers, Lafarge Africa Plc, Dangote Cement Plc, and BUA Group occupy positions defined by captive limestone inputs and pre-existing construction material distribution networks. Polymer-technology leadership sits with Sika AG and Henkel Corporation, representing European formulation expertise targeting high-specification commercial contracts. Regional supply chain specialists include Helmar Building Materials Ltd. and Cormart, exemplifying domestic distributors with established SON compliance pathways. The remaining competitive set—Interteck Group, Fosroc, and fragmented local blenders—clusters around project-specific procurement relationships and secondary city retail penetration.
| Leading Market Players |
|---|
| Helmar Building Materials Ltd. |
| Lafarge Africa Plc |
| Henkel Corporation |
| BUA Group |
| Dangote Cement Plc |
| Sika AG |
| Cormart |
| Interteck Group |
| Fosroc |
| Others |
Supply & Pricing Matrix
Federal Ministry procurement mandates for NIS-compliant adhesive documentation are forcing contractor sourcing toward certified domestic supply chains, compressing price realization for informal site-mix alternatives while elevating premium positioning for polymer-modified formulations with full certification traceability.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates epoxy systems for pharmaceutical clean-rooms from polymer-modified thin-set for Lagos high-rises and unmodified cement-based bags for rural construction. Price differentiation rests on SON certification status and latex additive content, with polymer-enhanced grades commanding material cost premiums that contractors accept for labor-hour compression. Pricing pressure stems from site-mix substitution persistence in northern corridors, where informal sand-cement pastes retain cost advantage. DIY enthusiasts purchasing 5-20kg sachets through hardware retail prove most price-sensitive, while architects specifying NIS-compliant products for Federal contracts show least elasticity.
Supply Chain Analysis
Dual-sourcing requirements from major contractors mandate qualified backup suppliers for polymer resins, forcing domestic blenders to maintain relationships with both European latex additive producers and cement-group captive binder networks. Geographic supply concentration centers on Nigeria's South-West limestone quarries for clinker, European specialty chemical producers for polymer resins, and Asian manufacturers for epoxy hardeners. Raw material dependencies include Portland cement, styrene-butadiene latex, and calcium aluminate cements for rapid-setting grades. Supply chain risk concentrates in SONCAP certification scrutiny at Lagos and Port Harcourt ports, where customs clearance delays for imported resins create inventory volatility. Distribution runs through cement-group-affiliated hardware chains and independent distributors with established SON laboratory partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Nigeria tile adhesive market functions as a regulatory compounder, where Standards Organisation of Nigeria enforcement of NIS compliance and anticipated VOC limit tightening continuously redirect procurement toward certified supply chains and away from informal alternatives.
For Market Incumbents: Extend backward integration into limestone-derived binder inputs to match Dangote and Lafarge cost positions, while retrofitting blending lines for latex additive incorporation ahead of anticipated VOC regulatory tightening. Cement-group backing provides the capital intensity required for controlled-humidity storage infrastructure that mid-scale competitors cannot finance. Channel control through hardware retail chains locks out smaller importers lacking SON laboratory relationships. For New Entrants and Emerging Players: Hardware distributors in Abuja satellite cities and Nasarawa state housing corridors represent the most penetrable channel entry point, as these North-Central markets remain under-supplied by certified adhesive logistics networks. Modular sachet formats decoupled from bulk contractor purchasing enable working capital-light penetration of secondary cities lacking organized purchasing. Positioning on SON compliance-first credentials ahead of VOC limit tightening captures regulatory-driven demand redirection. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic blending operations with established SON laboratory partnerships and captive limestone supply agreements, as regulatory enforcement tightens market access for import-dependent competitors. Long-term viability over the analysis window favors integrated manufacturers with retrofit blending capacity already deployed. The signal to watch is Federal Ministry procurement guideline expansion beyond public buildings into state-level infrastructure contracts, which would accelerate certified product demand compression of informal site-mix share.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Quarries | Dangote and BUA Group leverage captive clinker supply to cut raw material transit costs below independent blenders. |
| Latex Additive Blending Line Retrofit | Domestic manufacturers upgrade controlled-humidity storage to meet polymer-modified formulation demand from Lagos high-rise developers. |
| SON Laboratory Partnership Expansion | Regional certification pathways expedite product approval for South-West corridor distributors serving Ibadan housing renewal. |
| Modular Sachet Format Launch | 5kg and 20kg packaging decouples bulk procurement from phased renovation consumption in Lagos hardware retail chains. |
| VOC Compliance-First Positioning | Anticipated Standards Organisation of Nigeria threshold tightening rewards early investment in low-emission polymer formulations. |
Research Methodology
Direct dialogue with plant managers at domestic blending facilities, procurement leads at Lagos and Abuja contractor firms, distribution channel partners in South-West hardware chains, and technical R&D directors at polymer resin suppliers grounded qualitative findings. Secondary validation drew from Standards Organisation of Nigeria certification records, Federal Ministry of Works and Housing procurement guidelines, customs import data for polymer resins, and SEC filings from cement-group parent companies. Bottom-up volume estimates from product-type and application segmentation triangulated against top-down construction activity indicators across Nigeria's six geopolitical zones.
Segmentation outputs across product type, application, technology, and end user dimensions combined with regional construction permit data and housing stock renewal rates throughout the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical cement consumption patterns and adhesive penetration ratios in comparable emerging markets. Industry-specific forecast inputs included SON enforcement intensity indices and Federal infrastructure budget allocation trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SON regulatory calibration timing and limestone transport cost volatility. Deviation in Federal Ministry procurement mandate expansion pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market
Adhesives & Sealants
Italy Adhesives Market
Adhesives & Sealants
Rubber Repair Adhesives Market
Adhesives & Sealants
Vietnam Construction Chemicals Market
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
American Epoxy Adhesives Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
Dural Sealant Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market