
 North America Automotive Adhesives and Sealants Market | 2026-2036
North America Automotive Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Adhesives and Sealants Market Analytics
The gap between premium structural formulations and commodity sealants is shifting as OEMs demand crash-durable, corrosion-resistant bonding for aluminum-intensive vehicle architectures. Henkel AG & Co. KGaA leverages its epoxy and polyurethane portfolios to anchor supply relationships with Detroit-based automakers. Dow competes through silicone and acrylic technologies optimized for glass bonding and thermal management applications. H.B. Fuller Company differentiates via hot-melt and water-based platforms serving interior trim and acoustic dampening segments.
Automotive adhesives and sealants comprise formulated polymer systems—typically epoxies, polyurethanes, silicones, or acrylics—engineered to achieve specified shear strengths, cure profiles, and environmental resistance for permanent or semi-permanent joining of vehicle substrates. These materials enable weight reduction, NVH control, and sealed protection against fluids, dust, and galvanic corrosion in assembled automobiles. Structural adhesives dominate value capture as OEMs substitute mechanical fasteners in unibody and battery enclosure designs, while UV-cured technologies represent the fastest-expanding technology category due to line-speed advantages and reduced volatile organic compound exposure. Sealants maintain mature, high-volume positions in body assembly and glass bonding applications where flexibility and long-term durability outweigh strength requirements.
EPA emission mandates and NHTSA corporate average fuel economy standards compel adhesive suppliers to validate products for dissimilar metal bonding and recycling compatibility. OSHA workplace exposure limits and state-level VOC regulations in California and Michigan constrain solvent-based formulation growth, redirecting R&D investment toward water-based and reactive hot-melt platforms. Stakeholders must monitor how battery electric vehicle platform architectures reshape adhesive specification requirements for thermal runaway containment and module-to-pack structural integrity.
Market Dynamics
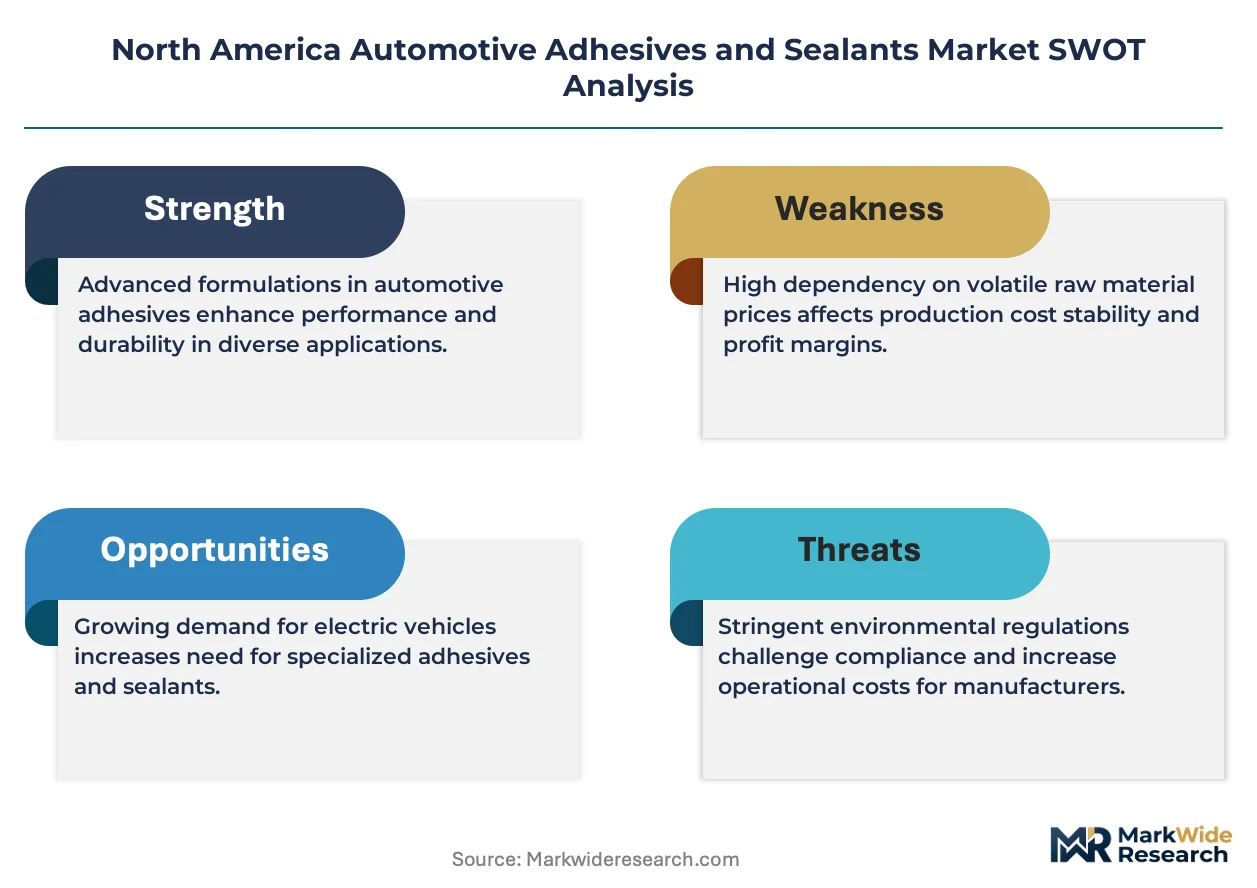
Electric vehicle platform architectures are forcing adhesive suppliers to reengineer formulations for thermal runaway containment and module-to-pack structural integrity, compressing qualification timelines while expanding specification complexity across the value chain.
Growth Catalysts
- EPA Vehicle Emission Standards:NHTSA fuel economy rules compel automakers toward adhesive-intensive multi-material designs that reduce vehicle weight and improve fleet efficiency metrics.
- Battery Pack Assembly:Electric vehicle manufacturers are expanding structural adhesive use for module bonding, thermal interface materials, and enclosure sealing in high-volume production.
- Great Lakes Manufacturing Corridor:Demand concentrates in Michigan, Ohio, and Indiana where Detroit-based OEMs and tier suppliers anchor adhesive procurement volumes.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy and polyurethane resin costs fluctuate with crude oil and propylene pricing, compressing formulation margins during upstream spikes.
- Supplier Concentration Risk:Specialty curing agents and isocyanate precursors depend on concentrated Gulf Coast chemical production vulnerable to hurricane disruption.
- Recycling Compatibility Constraints:Permanent structural bonds complicate end-of-life vehicle disassembly and aluminum recovery, creating friction with circular economy mandates.
Strategic Opportunities
- Mexico Nearshoring Expansion:OEM assembly capacity growth in Nuevo Leon and Baja California creates adhesive specification opportunities for suppliers with cross-border technical service.
- UV-Cured Technology Convergence:Line-speed advantages and reduced volatile organic compound exposure position UV-cured platforms for glass bonding and interior trim expansion.
- Inflation Reduction Act Incentives:Domestic battery cell manufacturing tax credits accelerate US-based gigafactory construction, pulling adhesive demand into new production geographies.
Industry Challenges
- Formulation Chemistry Talent Gap:Polymer science and rheology expertise shortages delay product development cycles as OEMs compress qualification timelines.
- Multi-Material Bonding Certification:Validating crash-durable, corrosion-resistant adhesion for aluminum-intensive vehicle architectures requires extensive OEM-specific testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Adhesives and Sealants Market |
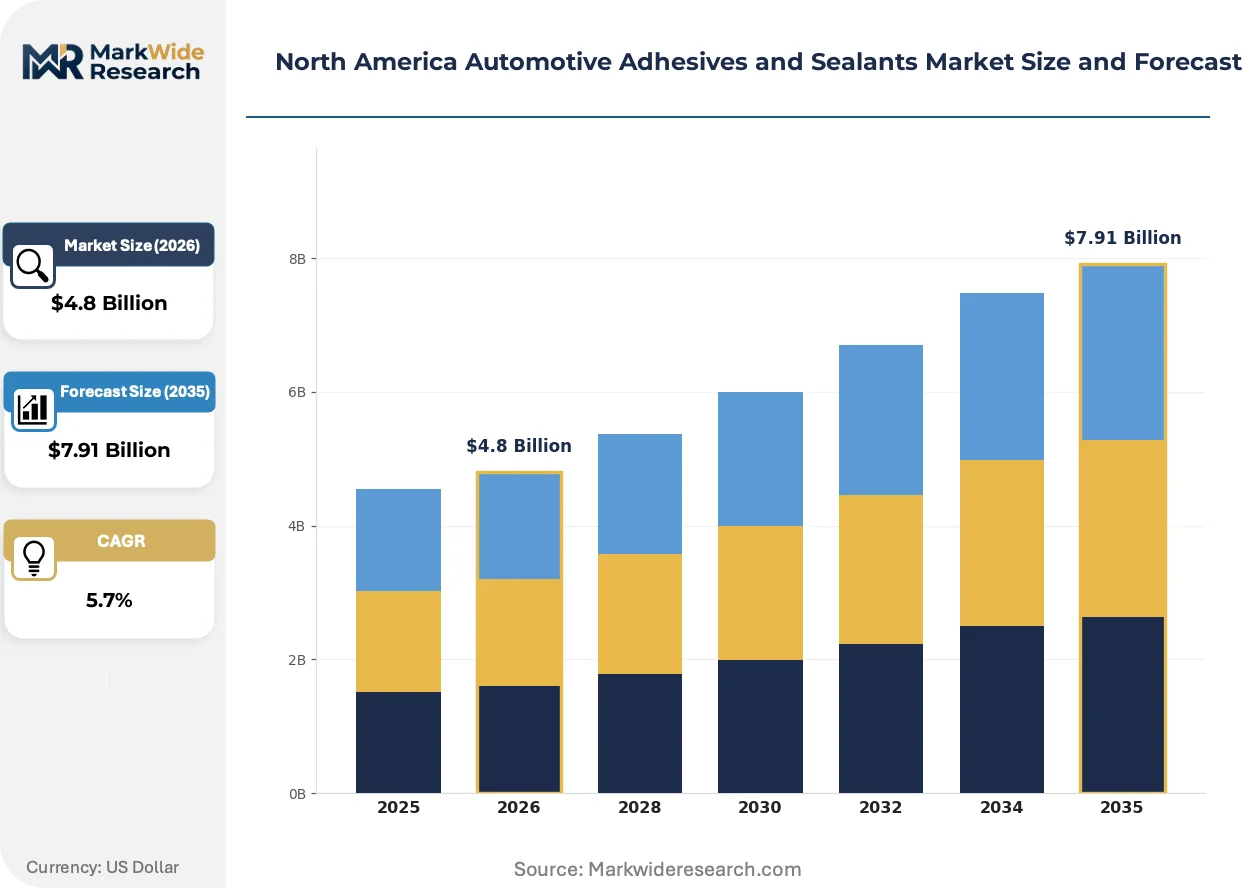
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Adhesives, Sealants, Pressure-Sensitive Adhesives, Reactive Adhesives Application: Body Assembly, Interior Trim, Glass Bonding, Engine Compartment Technology: Water-Based, Solvent-Based, Hot-Melt, UV-Cured End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Automotive Manufacturers |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Dow, H.B. Fuller Company, Sika AG, Arkema Group, Illinois Tool Works Inc, Huntsman International LLC, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Adhesives and Sealants Market Evolving Landscape
Formulation platforms are fragmenting as OEMs demand application-specific performance profiles, pulling investment away from general-purpose chemistries toward engineered systems with validated durability data.
Thermally conductive adhesives are modularizing battery pack architectures by replacing mechanical fasteners and gap pads in module-to-cold-plate assemblies. Cell manufacturers in Nevada and Tennessee are specifying these materials for thermal runaway propagation resistance. The technology is compressing pack assembly steps while enabling higher energy density configurations.
NHTSA corporate average fuel economy standards and EPA greenhouse gas regulations are tightening adhesive performance requirements for dissimilar metal bonding. Suppliers must validate products for galvanic corrosion prevention and long-term durability under cyclic loading. The structural adhesive segment bears the heaviest compliance burden as OEMs substitute welds and rivets in unibody designs.
Fleet procurement offices at commercial vehicle operators are consolidating specification authority previously held by regional maintenance managers. National account structures now dictate adhesive selection for aftermarket collision repair and glass replacement. This concentration is most visible in US Class 8 truck and last-mile delivery van segments where total cost of ownership calculations override local brand preferences.
North America Automotive Adhesives and Sealants Market Segmentation
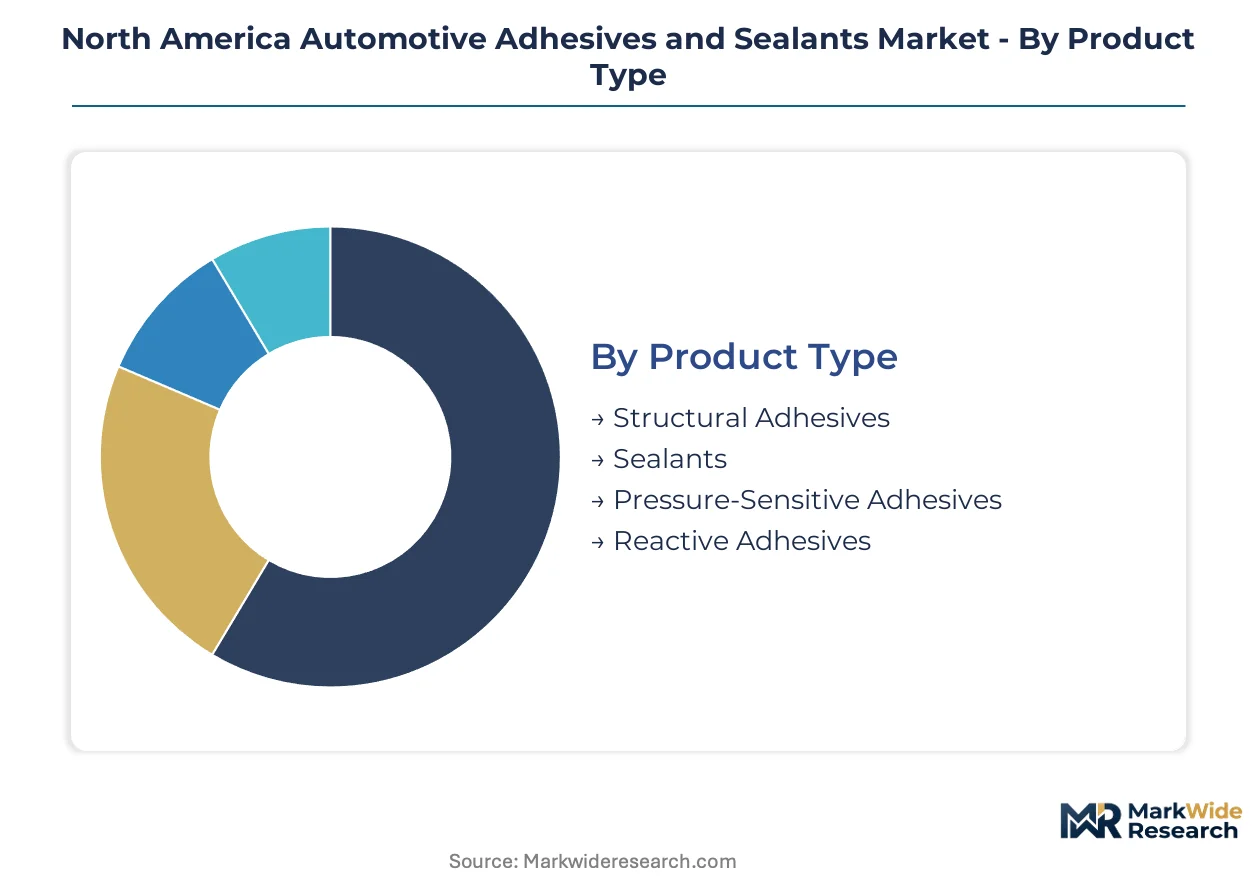
Automotive adhesive purchasing decisions split across formulation chemistry, assembly process requirements, and supply chain position. Each segmentation axis reveals distinct margin profiles and qualification barriers that shape supplier strategy in the Great Lakes manufacturing corridor.
Product Type:
Capital intensity peaks with structural adhesive production, where polymer synthesis and crash-durability testing demand dedicated pilot lines and OEM-specific validation protocols.
- Structural Adhesives:High-strength epoxy and polyurethane formulations engineered for load-bearing joints in unibody and battery enclosure architectures. Michigan-based OEMs specify these for aluminum-intensive vehicle programs where weld substitution reduces weight. EPA fuel economy mandates accelerate specification for multi-material designs.
- Sealants:Flexible polymer systems—primarily silicones and modified acrylics—providing environmental sealing and NVH dampening across body seams and glass interfaces. Demand concentrates in Ohio and Indiana assembly plants where robotic dispensing integrates with paint shop operations. NHTSA corrosion warranties drive specification for long-term durability.
- Pressure-Sensitive Adhesives:Tackified elastomer systems for interior trim attachment and temporary fixturing applications.
- Reactive Adhesives:Two-component chemistries curing through moisture, heat, or substrate catalysis for engineered bonding of dissimilar materials.
Structural adhesives absorb the bulk of installed capacity; reactive adhesives are expanding most quickly.
Application:
Application selection tracks directly with vehicle platform architecture, where electric vehicle designs reallocate adhesive volumes toward thermal management and battery protection.
- Body Assembly:Structural bonding of closures, pillars, and floor pans where crash-energy management demands validated shear and peel performance. The Great Lakes corridor anchors procurement volume as Detroit-based OEMs convert steel-intensive platforms to aluminum and carbon fiber reinforced polymer designs.
- Glass Bonding:Direct glazing systems using polyurethane and silicone technologies for windshield and backlight structural attachment. Indiana and Ohio plants specify these for rollover strength and pedestrian protection compliance. NHTSA Federal Motor Vehicle Safety Standards govern adhesive selection for bonded glass retention.
- Interior Trim:Hot-melt and water-based systems for dashboard, door panel, and headliner assembly where aesthetic finish and low-VOC emission dominate specification.
- Engine Compartment:High-temperature resistant formulations for gasketing, hose bonding, and sensor mounting in powertrain and thermal management systems.
Body assembly commands the largest formulation volumes; glass bonding shows the steepest specification growth trajectory.
Technology:
Technology choice reflects regulatory pressure and line-speed economics, with water-based and UV-cured platforms capturing investment as OSHA and state VOC limits tighten.
- Water-Based:Acrylic and polyurethane dispersions for interior and non-structural applications where low flammability and workplace safety outweigh cure speed limitations. Michigan OSHA workplace exposure enforcement redirects specification from solvent alternatives.
- UV-Cured:Photoinitiator-activated acrylates enabling instant cure for glass bonding and interior trim where line-speed advantages justify capital investment in curing equipment. Nevada and Tennessee battery cell manufacturing facilities specify these for module assembly throughput.
- Solvent-Based:Traditional rubber and acrylic solutions maintaining position in engine compartment and exterior sealing where solvent resistance and substrate wetting prove critical.
- Hot-Melt:Thermoplastic formulations for interior assembly and temporary bonding where reversible adhesion supports end-of-life disassembly requirements.
Water-based technology carries the heaviest regulatory compliance burden; UV-cured platforms are gaining share fastest.
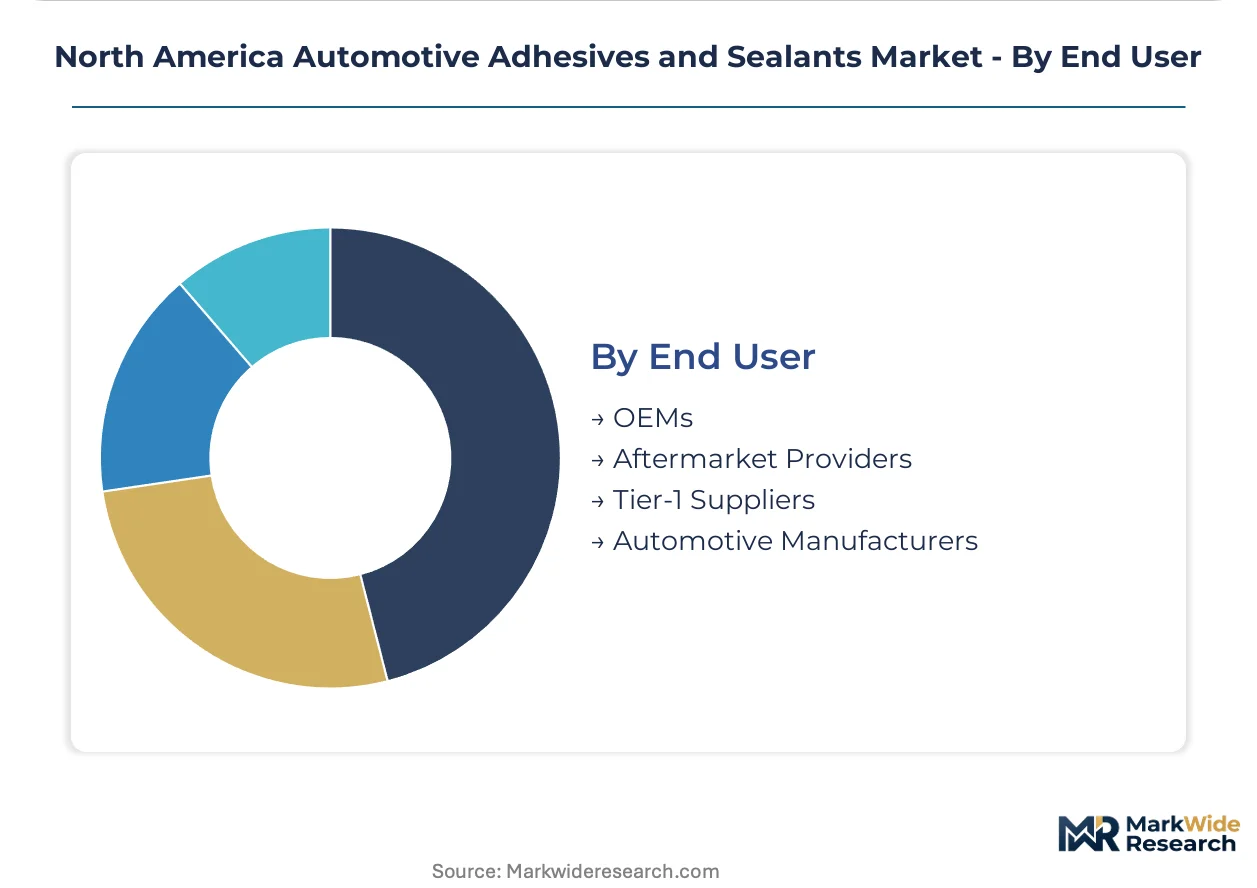
End User:
End-user segmentation reveals divergent procurement authority, with OEMs and tier-1 suppliers consolidating specification control while aftermarket channels fragment.
- OEMs:Detroit-based vehicle manufacturers dictating adhesive specification through platform engineering and direct supplier qualification. Ford, General Motors, and Stellantis maintain approved product lists with crash-durability validation requirements spanning 10-year corrosion warranties.
- Tier-1 Suppliers:Magna, Lear, and Adient anchoring procurement for seating, closure, and electronics module assembly where subsystem integration demands application-specific formulation.
- Automotive Manufacturers:Battery cell and pack producers including Tesla, SK On, and LG Energy Solution specifying thermal interface materials and structural bonding for gigafactory operations in Texas and Tennessee.
- Aftermarket Providers:Collision repair networks and glass replacement shops sourcing through distribution for warranty-compliant service applications.
OEMs dominate value capture through specification authority; battery manufacturers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes automotive manufacturing corridor spanning Michigan, Ohio, and Indiana anchors North American adhesive procurement volumes, with Detroit-based OEMs driving specification authority for structural bonding and sealing applications.
United States
Battery cell manufacturing tax credits under the Inflation Reduction Act accelerate gigafactory construction in Nevada and Tennessee, pulling thermal interface material demand into new production geographies. EPA vehicle emission standards and NHTSA fuel economy rules compel automakers toward adhesive-intensive multi-material designs that reduce weight and improve fleet efficiency metrics. The Great Lakes corridor concentrates procurement volumes where Ford, General Motors, and Stellantis maintain approved product lists with crash-durability validation requirements.
Canada
Ontario's automotive assembly plants in Windsor and Oshawa specify structural adhesives for aluminum-intensive vehicle programs where weld substitution supports lightweighting targets. Environment and Climate Change Canada regulations on volatile organic compound emissions redirect formulation preference toward water-based and reactive hot-melt platforms. The province's tier-1 supplier ecosystem anchors procurement for seating, closure, and electronics module assembly where subsystem integration demands application-specific chemistry.
Mexico
OEM assembly capacity expansion in Nuevo Leon and Baja California creates adhesive specification opportunities for suppliers with cross-border technical service capabilities. Mexican environmental regulations under SEMARNAT constrain solvent-based formulation growth in border state manufacturing zones. The Bajío Region's emerging automotive cluster attracts adhesive investment as German and Japanese transplant operations localize supply chain procurement.
North America Automotive Adhesives and Sealants Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation chemistry and application engineering tiers. The market structure consolidates around integrated polymer suppliers with captive resin production and crash-durability testing infrastructure, while specialty compounders occupy niche positions in UV-cured and thermally conductive segments. Three archetypes dominate: diversified chemical conglomerates with automotive divisions, adhesive-focused specialists with regional technical service networks, and materials science innovators targeting battery electric vehicle thermal management. Competitive dynamics center on qualification timeline compression and cross-border manufacturing footprint expansion.
Among diversified chemical conglomerates, 3M and Dow exemplify scale-driven positions anchored by broad technology portfolios spanning epoxy, polyurethane, silicone, and acrylic platforms. Henkel AG & Co. KGaA occupies a specialist position within the European-origin tier, while H.B. Fuller Company represents the mid-cap focused archetype with concentrated exposure to hot-melt and water-based interior applications. These three companies illustrate how supplier strategy fragments across capital intensity, geographic service reach, and platform breadth dimensions.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Dow |
| H.B. Fuller Company |
| Sika AG |
| Arkema Group |
| Illinois Tool Works Inc |
| Huntsman International LLC |
| Avery Dennison Corporation |
| Others |
Value Network & Pricing Analysis
EPA vehicle emission standards and NHTSA fuel economy rules gate qualified supply access and premium-tier pricing power by mandating crash-durability validation and corrosion-resistant bonding chemistry that only validated suppliers can deliver. OEMs in Michigan, Ohio, and Indiana restrict approved product lists to adhesive producers with captive resin synthesis and decade-long warranty data, compressing margins for unqualified entrants while sustaining structural adhesive premiums.
Pricing Analysis
Value-based pricing anchored to crash-energy absorption performance and thermal runaway containment outcomes dominates structural adhesive procurement, with OEMs paying premiums for formulations validated through 10-year corrosion warranties. Price differentiation separates EPA-compliant structural epoxies from commodity sealants based on certification grade and volume scale, with battery cell manufacturers showing lowest price sensitivity due to thermal interface material criticality. Cost compression in solvent-based tiers is intensifying because OSHA workplace exposure limits redirect specification toward water-based alternatives. Tier-1 suppliers and aftermarket distributors exhibit highest price sensitivity, driving consolidation around national account structures.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Detroit-based automakers and battery gigafactories in Nevada and Tennessee, bypassing distribution for qualified structural formulations. Geographic supply concentration centers on the US Gulf Coast for specialty isocyanate precursors and epoxy resins, with secondary sourcing from Germany and Japan for high-purity curing agents. Raw material dependencies rest on propylene derivatives, aromatic amines, and photoinitiator chemicals. Single-source vulnerability concentrates in hurricane-exposed Gulf Coast petrochemical corridors. Distribution runs through authorized technical service networks for structural adhesives, while sealants flow through regional distributors serving collision repair and glass replacement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America automotive adhesives and sealants market sits in a technology-transition phase as UV-cured and thermally conductive platforms displace solvent-based and mechanical fastening legacy systems. Battery electric vehicle platform architectures are forcing specification rewiring across the value chain.
For Market Incumbents: Anchor defensive positioning through backward integration into specialty epoxy and polyurethane resin production to secure margin control against petrochemical feedstock volatility. Expand crash-durability testing infrastructure in the Great Lakes corridor to compress OEM qualification timelines and lock out emerging competitors. Prioritize certification investment for thermal runaway containment formulations as battery cell manufacturers consolidate specification authority.
For New Entrants and Emerging Players: Inflation Reduction Act domestic content requirements in the United States open a window for regional compounders to capture thermal interface material demand from gigafactory construction in Texas and Tennessee. Target Mexico nearshoring expansion in Nuevo Leon and Baja California where cross-border technical service capabilities remain underdeveloped. Pursue white-space in UV-cured interior trim applications where line-speed advantages justify capital investment in curing equipment.
For Investors and Strategic Acquirers: OEM qualification timeline compression is the leading indicator that formulation chemistry talent scarcity will drive acquisition premiums for polymer science specialists. Long-term viability favors suppliers with integrated resin production and validated battery platform specifications. Monitor EPA enforcement patterns on multi-material recycling compatibility as the signal for which structural adhesive technologies will face circular economy displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive supply of epoxy and polyurethane precursors insulates margins from Gulf Coast petrochemical volatility. |
| Thermal Interface Material Capacity Expansion | Gigafactory construction in Nevada and Tennessee pulls demand for module-to-cold-plate bonding chemistry. |
| UV-Curing Equipment Partnership | Line-speed advantages in glass bonding justify capital deployment with Indiana and Ohio assembly plants. |
| Cross-Border Technical Service Network | Mexico nearshoring in Nuevo Leon requires localized application engineering support for OEM qualification. |
| Recycling Compatibility Certification | EPA circular economy mandates favor adhesives enabling aluminum recovery and end-of-life disassembly. |
Research Methodology
Multi-period observation of vehicle production volumes, battery cell manufacturing capacity announcements, and adhesive specification trends anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, adhesive R&D directors, and aftermarket distribution managers. Secondary validation drew from EPA regulatory filings, NHTSA fuel economy compliance data, SEC 10-K disclosures from chemical conglomerates, and vehicle registration databases. Bottom-up triangulation across formulation chemistry demand and top-down reconciliation against automotive production forecasts ensured methodological rigor.
Input-output matrices modeled adhesive consumption per vehicle across propulsion architectures, body assembly content requirements, and battery pack thermal management specifications. Segmentation dimensions spanned formulation chemistry, application function, cure technology, and end-user procurement authority. CAGRs were derived from production-weighted volume projections and value-per-vehicle escalation patterns. Industry-specific forecast inputs incorporated OEM lightweighting targets and Inflation Reduction Act incentive impacts on domestic battery manufacturing geography.
Caveats apply where petrochemical feedstock volatility, hurricane disruption to Gulf Coast chemical production, or shifts in EPA enforcement posture on recycling compatibility could materially shift the outlook. Practitioners should monitor OEM qualification timeline compression and battery platform architecture standardization for early signals of specification authority consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
Global EVA Adhesives Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Global Bone Cement and Glue Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Textile Binders Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Laser Self-Adhesive Tear Market
Adhesives & Sealants
Global Silicone Adhesives Market
Adhesives & Sealants
Foam Adhesive Market