
 Gasket and Seal Material Market | 2026-2036
Gasket and Seal Material Market Size, Share, and Industry Trends Forecast 2026-2036
Gasket and Seal Material Market Foresight
Asian fluoroelastomer producers are rebalancing capacity toward specialty grades after years of commodity oversupply. Freudenberg Sealing Technologies leverages its polymer compounding expertise to anchor premium automotive sealing lines. Trelleborg Group dominates marine and offshore segments through advanced rubber formulations. Parker Hannifin Corporation extends its distribution network across North American industrial maintenance channels.
Gasket and seal materials are engineered barrier components manufactured from elastomers, thermoplastics, metals, or compressed fibers, typically specified by compression set resistance, temperature rating, and chemical compatibility metrics to prevent fluid or gas leakage between mating surfaces. They function as critical reliability elements in pressurized systems ranging from pipeline flanges to turbine housings. PTFE and advanced rubber formulations lead material type demand due to their chemical inertness and broad temperature windows, while metal-reinforced graphite composites occupy high-temperature energy sector applications. Molded and pre-cut forms capture the majority of OEM procurement volumes, whereas sheet and tape formats sustain aftermarket maintenance demand across chemical processing and energy infrastructure.
EPA regulations on fugitive emissions from process equipment mandate leak detection and repair protocols that directly specify seal performance standards for valves and pumps in US refineries. REACH restrictions on perfluorinated substances and EU F-Gas Regulation phase-downs are forcing European compounders to reformulate fluoroelastomer grades ahead of compliance deadlines. Stakeholders must monitor regulatory divergence between EPA emission rules and EU chemical restrictions when planning material qualification programs and regional supply strategies.
Market Dynamics
Fluoroelastomer compounders face mounting pressure from REACH perfluorinated substance restrictions and EPA fugitive emission mandates, forcing simultaneous reformulation of material portfolios while maintaining performance thresholds for chemical processing and automotive OEMs.
Growth Catalysts
- REACH chemical restrictions:European compounders accelerate development of low-PFAS fluoroelastomer grades, creating first-mover qualification advantages with automotive OEMs ahead of 2025 compliance deadlines.
- US refinery infrastructure:EPA leak detection protocols mandate seal replacement cycles across valve and pump populations, sustaining aftermarket demand for PTFE and graphite composite formulations.
- German industrial corridor concentration:Machinery and automotive OEMs in Baden-Württemberg and Bavaria source integrated sealing systems, pulling advanced material development toward application-specific performance specifications.
Market Restraints
- Fluoropolymer feedstock volatility:Tetrafluoroethylene monomer supply concentrates with Chinese and US chemical producers, exposing compounders to input cost swings and force majeure risks.
- High-temperature metal composite technical ceiling:Graphite-reinforced gaskets face oxidation degradation above 450°C in turbine applications, limiting addressable market in next-generation power generation.
- EU F-Gas Regulation phase-down:Perfluorinated sealant gas restrictions create compliance friction for installed base maintenance, compressing demand for legacy fluorocarbon formulations.
Strategic Opportunities
- Hydrogen economy infrastructure:Germany and Netherlands pipeline projects specify hydrogen-compatible elastomer seals, opening material qualification opportunities for EPDM and specialized FKM grades.
- Carbon capture equipment:Amine solvent handling systems require chemically resistant sealing solutions in US Gulf Coast and North Sea installations, expanding addressable market beyond traditional hydrocarbon processing.
- Digital distribution platforms:Industrial maintenance procurement migrates to specialized B2B marketplaces, enabling direct compounder-to-plant relationships that bypass traditional distributor markups.
Industry Challenges
- Polymer compounding expertise scarcity:Formulation chemists with fluoroelastomer specialization command premium compensation, constraining R&D throughput at mid-tier material suppliers.
- Multi-jurisdiction certification timelines:Simultaneous EPA, REACH, and FDA material approvals extend qualification cycles to 18-24 months, delaying revenue recognition for new product introductions.
- Legacy system integration friction:Pre-cut gasket inventories and established maintenance protocols at US refineries slow adoption of molded seal designs despite performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gasket and Seal Material Market |
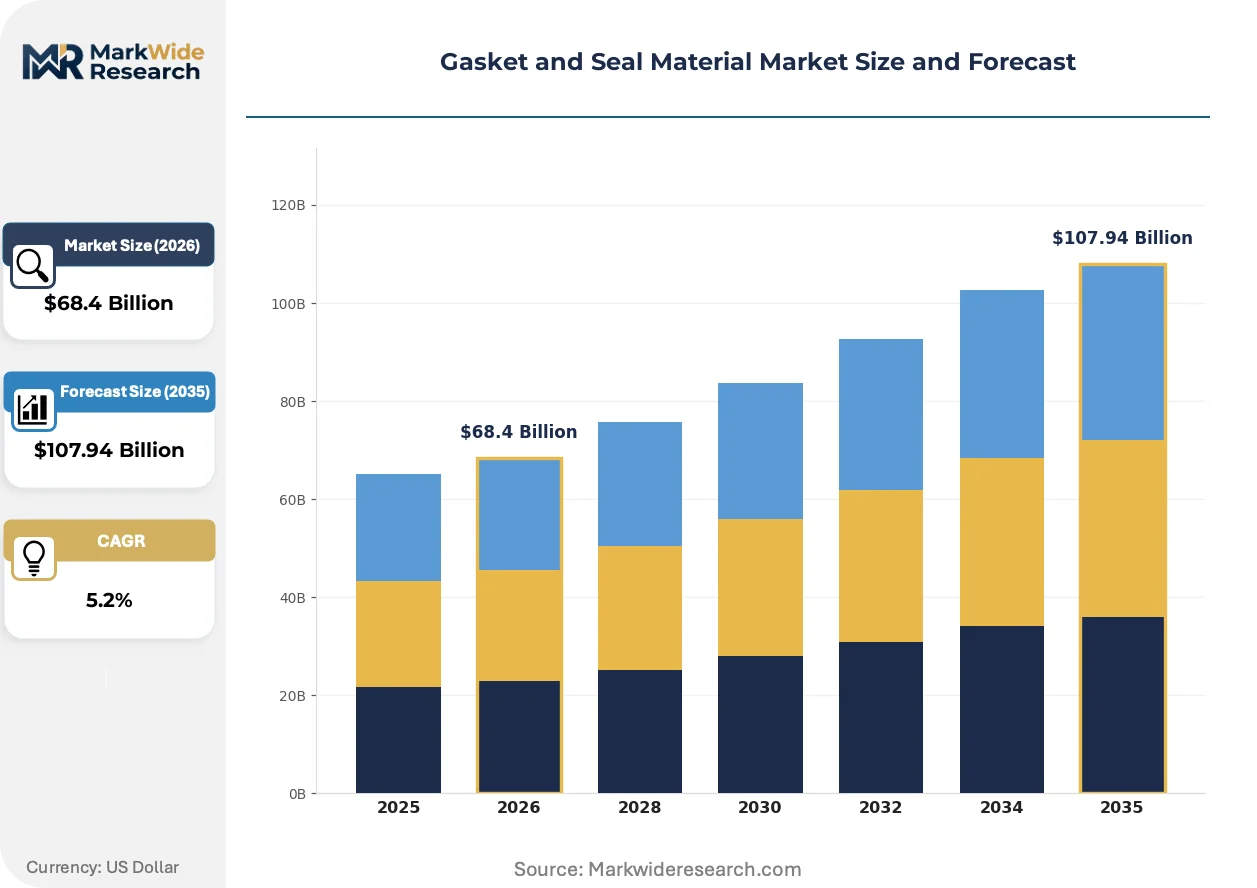
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $107.94 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Rubber, PTFE, Graphite, Metal, Cork, Silicone Form: Sheet, Tape, Rope, Liquid, Molded, Pre-Cut Application: Pumps, Compressors, Valves, HVAC Systems, Marine Engines, Aerospace Equipment End User Industry: Energy & Power, Chemical Processing, Construction, Electronics Manufacturing, Food & Beverage, Pharmaceuticals |
| Companies Covered | Trelleborg Group, Freudenberg Sealing Technologies, Parker Hannifin Corporation, ERIKS NV, ElringKlinger Kunststofftechnik GmbH, Saint-Gobain Performance Plastics, John Crane, W.L. Gore & Associates, Garlock Sealing Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gasket and Seal Material Market Shifts & Advancements
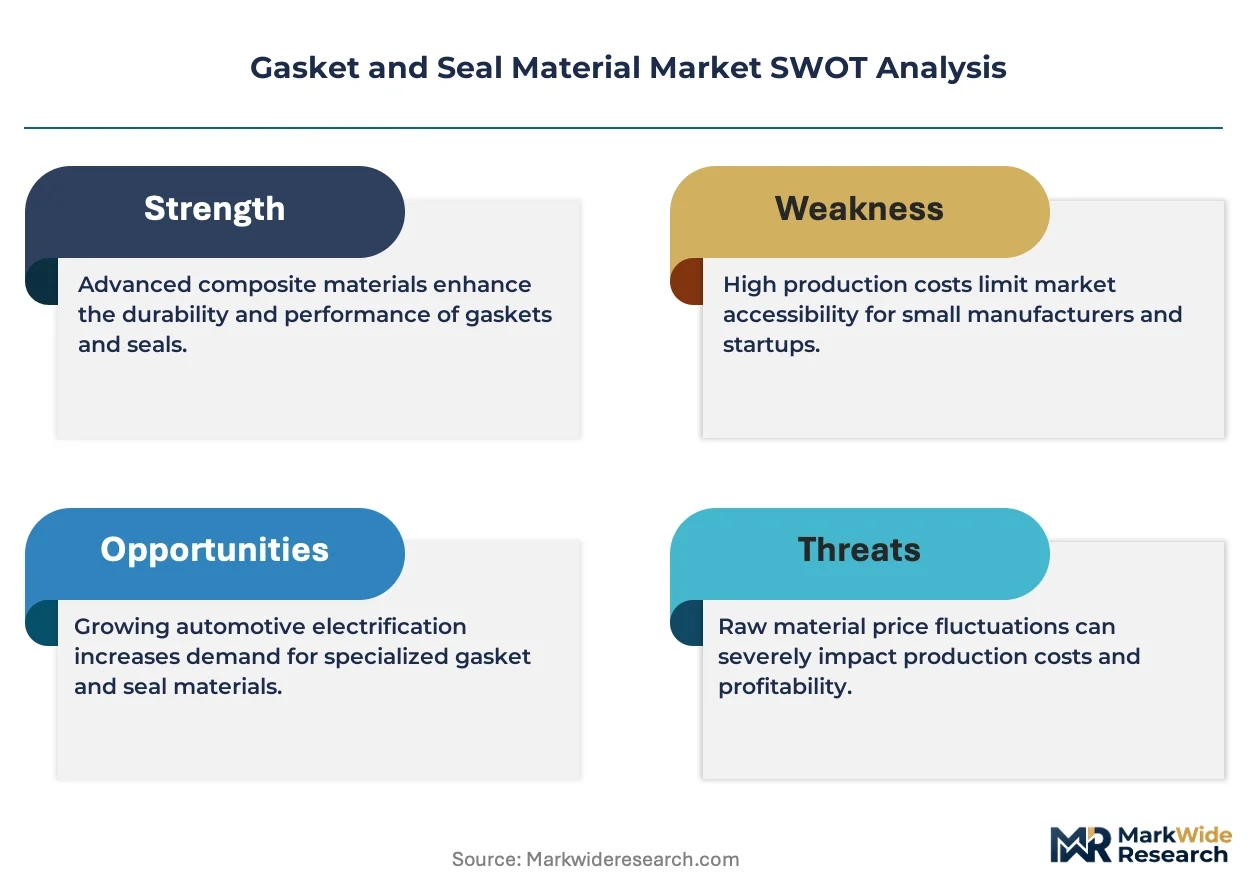
Material science advances and regulatory chemistry restrictions are compressing traditional product lifecycles while opening specification windows for novel polymer architectures in critical sealing applications.
Perfluoroalkoxy alkane (PFA) and modified PTFE compounds are overtaking conventional filled PTFE in chemical processing valve seals. German and US pump manufacturers specify these materials for sulfuric acid and caustic service. The shift compresses commodity PTFE margins while elevating compounders with polymerization capabilities to preferred supplier status.
EPA fugitive emission standards tighten leak-rate thresholds for valve and pump seals in US refineries. Refinery operators must upgrade seal specifications or face penalty structures. Texas and Louisiana processing clusters drive demand for low-emission packing and gasket designs that satisfy both environmental compliance and fire-safe API standards.
Maintenance procurement at North American chemical plants consolidates through integrated supply contracts with preferred distributors. Regional maintenance, repair, and operations distributors capture seal and gasket volume through vendor-managed inventory programs. The Gulf Coast petrochemical corridor exhibits the fastest migration toward consolidated procurement, compressing spot-buy opportunities for non-contracted suppliers.
Gasket and Seal Material Market Segmentation
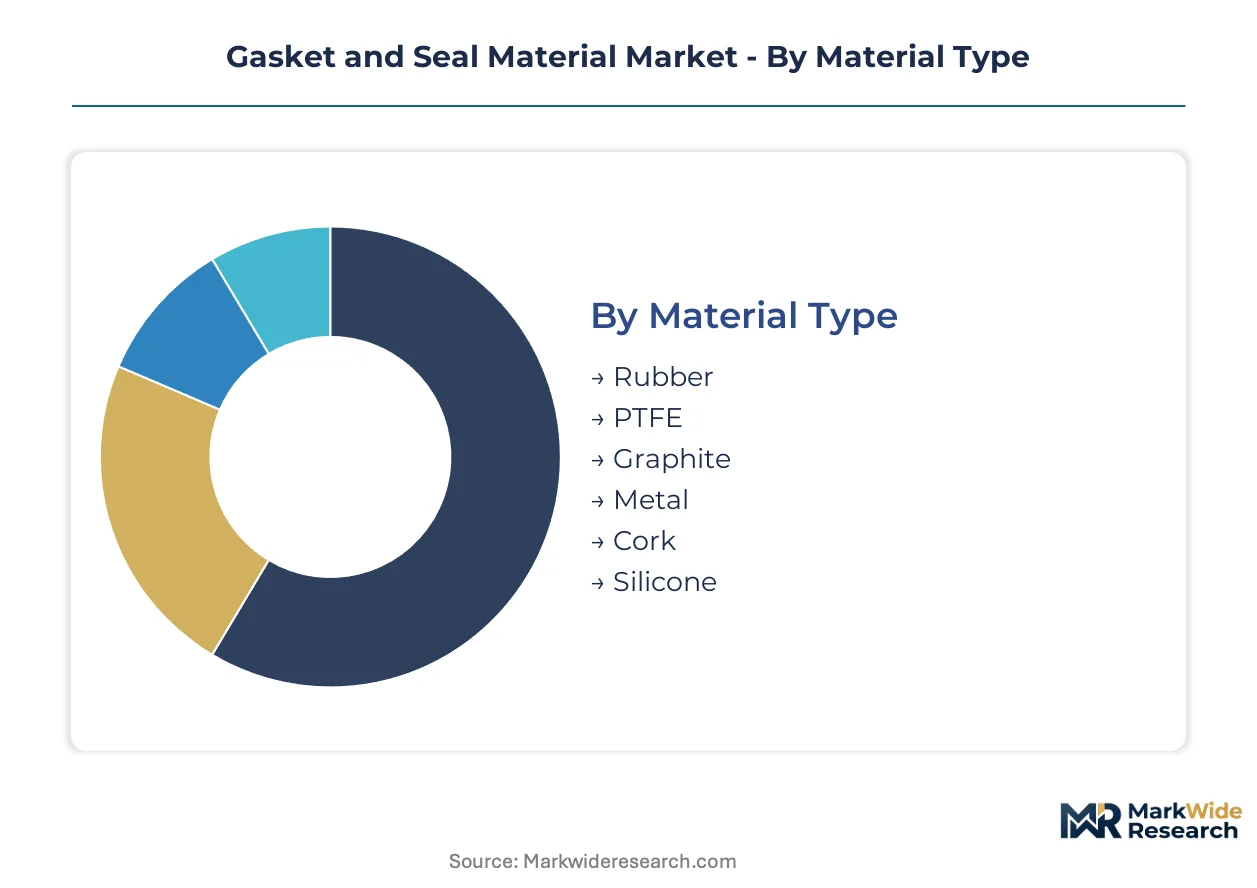
Segmentation in gasket and seal materials determines procurement pathways, certification requirements, and margin structures across industrial supply chains. Material type dictates regulatory burden, while form factor shapes inventory economics and distributor relationships.
Material Type:
PTFE and fluoroelastomer grades require REACH perfluorinated substance compliance documentation, while metal-reinforced graphite composites face API fire-safe certification mandates for refinery applications.
- PTFE:Polytetrafluoroethylene delivers chemical inertness across -200°C to 260°C operating windows. German pump manufacturers specify modified PTFE for sulfuric acid service, with ECHA restrictions forcing compounders toward low-PFAS formulations ahead of compliance deadlines.
- Rubber:Nitrile, EPDM, and fluoroelastomer formulations dominate dynamic sealing applications. US Gulf Coast refinery operators source FKM grades for amine solvent exposure in carbon capture retrofits, balancing EPA emission standards against feedstock volatility.
- Graphite:Flexible graphite sheet and laminate structures withstand extreme thermal cycling. Metal-reinforced grades serve turbine flanges in combined-cycle power plants, though oxidation degradation above 450°C limits next-generation deployment.
- Metal:Spiral-wound and ring-type joint designs handle ultra-high pressure differentials. LNG liquefaction trains specify Inconel-wound configurations for cryogenic flange sealing.
- Cork:Compressed cork-rubber composites address low-pressure, low-temperature utility applications. Water treatment infrastructure in Netherlands municipalities specifies cork-based gaskets for cost-sensitive pipeline maintenance.
- Silicone:VMQ and FVMQ grades provide biocompatibility and electrical insulation. FDA material approvals extend qualification timelines for pharmaceutical processing equipment suppliers.
Leading the category by volume: Rubber. Growing fastest: PTFE compounds gaining specification share in chemical processing valve seals.
Form:
Form selection drives inventory carrying costs and shapes the distributor-compounder power balance across maintenance procurement channels.
- Molded:Compression and injection-molded geometries deliver dimensional precision for OEM assembly lines. Automotive powertrain suppliers in Baden-Württemberg specify liquid silicone injection molded seals for turbocharger interfaces.
- Pre-Cut:CNC-cut gasket kits match specific flange dimensions from digital asset records. Refinery maintenance contractors in Texas prefer pre-cut inventories for rapid turnaround on valve overhaul schedules.
- Sheet:Bulk sheet stock enables field fabrication for non-standard flange configurations. Industrial maintenance distributors capture margin through value-added cutting services.
- Tape:PTFE thread seal tape and expanded graphite ribbon address pipe fitting applications. Plumbing and HVAC contractors represent the primary demand channel.
- Rope:Braided and twisted packing configurations suit pump stuffing box and valve stem sealing. API 622 emission testing protocols govern specification for refinery rotating equipment.
- Liquid:Anaerobic and RTV silicone formulations cure in-place for complex joint geometries. Aerospace equipment manufacturers specify liquid gasket solutions for turbine housing assemblies.
Volume concentrates in Molded and Pre-Cut formats for OEM procurement. Steepest expansion trajectory: Liquid formulations displacing solid gaskets in aerospace and electronics manufacturing.
Application:
Application-specific performance requirements determine material qualification depth and the regulatory scrutiny intensity governing procurement decisions.
- Valves:Stem packing and bonnet gaskets face the most stringent EPA fugitive emission mandates. Low-emission packing designs incorporating live-loading systems command specification premiums in US refinery valve populations.
- Pumps:Mechanical seal faces and stuffing box packings balance leakage control against friction losses. Chemical processing plants specify PTFE-impregnated aramid packing for abrasive slurry service.
- Compressors:Piston rings and valve plate gaskets withstand cyclic pressure loading. Natural gas compression stations in Netherlands hydrogen pipeline pilots test EPDM compatibility for blended gas service.
- HVAC Systems:Chiller and heat exchanger gaskets prioritize thermal conductivity and ease of replacement. Commercial building maintenance contractors favor non-asbestos fiber sheet for cost-sensitive retrofits.
- Marine Engines:Cylinder head and exhaust manifold gaskets resist saltwater corrosion. Classification society type approval extends material qualification cycles for ocean-going vessel applications.
- Aerospace Equipment:Fire-resistant elastomer seals satisfy FAR 25.853 flame propagation standards. Turbine engine manufacturers specify fluorosilicone grades for fuel system interfaces.
Valve and Pump applications dominate procurement volume. Compressor sealing solutions are climbing fastest on hydrogen economy infrastructure deployment.
End User Industry:
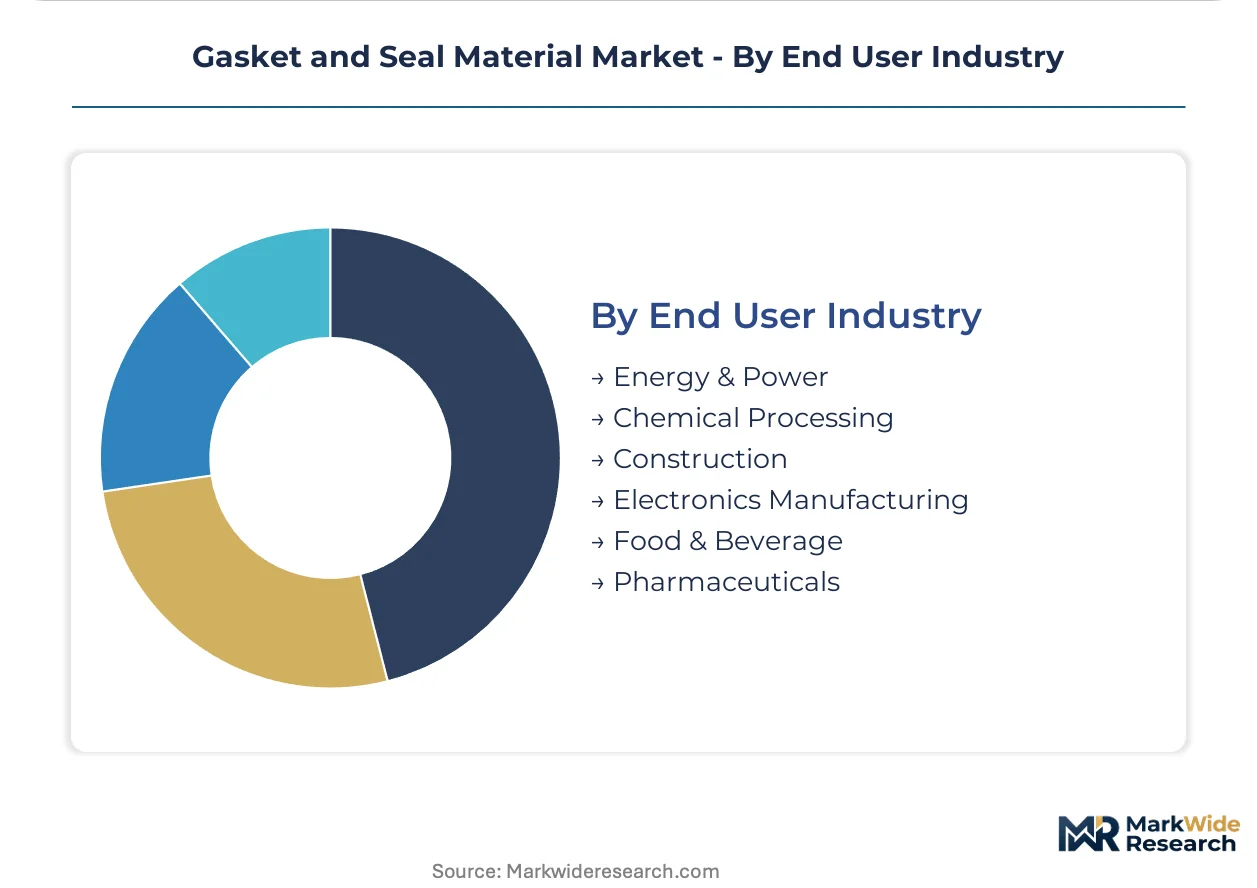
End-use concentration determines geographic demand clustering and shapes the regulatory compliance burden structure facing material suppliers.
- Chemical Processing:Aggressive media exposure demands broad chemical compatibility portfolios. US Gulf Coast and German Ruhr Valley chemical corridors pull specialty fluoroelastomer development toward application-specific formulations.
- Energy & Power:Combined-cycle turbines and nuclear steam generators specify metal-reinforced graphite for thermal and radiation resistance. ECHA restrictions on perfluorinated substances complicate legacy seal replacement protocols.
- Pharmaceuticals:FDA 21 CFR 177.2600 compliance and USP Class VI biocompatibility testing govern elastomer selection. Aseptic processing equipment requires platinum-cured silicone validation packages.
- Food & Beverage:FDA and EU 1935/2004 food contact approvals limit acceptable material chemistries. Brewery and dairy processors specify EPDM for steam-in-place cleaning compatibility.
- Electronics Manufacturing:Semiconductor fabrication demands ultra-high purity sealing solutions. Fabs specify perfluoroelastomer grades for aggressive plasma etch chemistries.
- Construction:Building envelope and plumbing applications prioritize cost over performance specification. Regional distributors capture volume through contractor supply relationships.
Chemical Processing leads procurement volume by material value. Pharmaceuticals and Electronics Manufacturing are expanding most quickly on purity and precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tetrafluoroethylene monomer production concentrates with Chinese and US chemical producers, anchoring regional supply security calculations. German automotive OEMs and Gulf Coast petrochemical operators pull specialty compounding capacity toward their respective industrial corridors.
United States
EPA fugitive emission mandates drive seal replacement cycles across valve and pump populations in Texas and Louisiana refineries. The agency's leak detection protocols specify performance thresholds that elevate demand for PTFE and graphite composite formulations. Houston's petrochemical corridor hosts integrated maintenance contractors consolidating procurement through vendor-managed inventory programs.
Germany
REACH perfluorinated substance restrictions force compounders to reformulate fluoroelastomer grades ahead of compliance deadlines. ECHA regulatory pressure accelerates low-PFAS development timelines for automotive OEM qualification. Baden-Württemberg's machinery manufacturers and Bavaria's automotive suppliers source application-specific sealing systems from regional compounders.
China
Tetrafluoroethylene feedstock supply dominance exposes downstream compounders to input cost volatility and force majeure exposure. The country's dual carbon goals reshape industrial emissions standards for chemical processing equipment. Yangtze River Delta fluoropolymer producers rebalance capacity toward specialty grades after years of commodity oversupply.
Netherlands
Hydrogen pipeline infrastructure projects specify hydrogen-compatible elastomer seals for blended gas service. EU F-Gas Regulation phase-downs compress demand for legacy fluorocarbon formulations in maintenance protocols. Rotterdam's port industrial cluster and North Sea carbon capture installations require chemically resistant sealing solutions for amine solvent handling.
Japan
Semiconductor fabrication demand pulls ultra-high purity perfluoroelastomer development toward aggressive plasma etch specifications. METI industrial policy supports domestic material qualification for critical supply chain security. Kyushu's fab concentration and Nagoya's precision equipment manufacturers anchor specialty seal procurement volumes.
Gasket and Seal Material Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hydrogen economy and carbon capture adjacencies with specialized formulations. The vendor base stratifies across integrated polymer compounders, regional fabrication specialists, and maintenance distribution networks. Three archetypes dominate: multinational material science conglomerates with captive compounding, mid-tier regional fabricators serving industrial maintenance channels, and niche specialists targeting aerospace or semiconductor purity requirements. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with compounders securing feedstock agreements and distributors building vendor-managed inventory programs.
Within the integrated material science tier, Freudenberg Sealing Technologies and Trelleborg Group represent archetypal positions. Freudenberg exemplifies the polymer compounding-to-systems supplier model anchored in German industrial corridors. Trelleborg occupies a parallel position with marine and offshore segment concentration. Parker Hannifin Corporation sits within the distribution-anchored archetype, extending North American industrial maintenance channel reach.
| Leading Market Players |
|---|
| Trelleborg Group |
| Freudenberg Sealing Technologies |
| Parker Hannifin Corporation |
| ERIKS NV |
| ElringKlinger Kunststofftechnik GmbH |
| Saint-Gobain Performance Plastics |
| John Crane |
| W.L. Gore & Associates |
| Garlock Sealing Technologies |
| Others |
Supply & Pricing Matrix
Modified PTFE compounding and low-PFAS fluoroelastomer reformulation are compressing legacy material margins while concentrating premium pricing power with compounders possessing captive polymerization capabilities. REACH compliance documentation and EPA emission certification requirements simultaneously elevate service-bundled offerings and fragment spot-buy markets across industrial maintenance channels.
Pricing Analysis
Warranty-backed material qualification packages and compliance documentation bundles now separate premium compounders from transactional suppliers. Three-tier pricing structure across certified-performance, standard-grade, and economy bulk tiers reflects differentiation by REACH documentation depth and API fire-safe certification status. Pricing pressure stems from Chinese tetrafluoroethylene feedstock volatility transmitting into compounder cost bases. Maintenance contractors at US Gulf Coast refineries exhibit highest price sensitivity due to consolidated procurement contracts, while German automotive OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese tetrafluoroethylene monomer producers and US Gulf Coast fluoropolymer resin manufacturers. Raw material dependencies encompass tetrafluoroethylene monomer, specialty fluoroelastomer base polymers, and high-purity graphite flake. Supply chain risk centers on force majeure exposure at integrated chemical complexes following extreme weather events. Distribution runs through regional maintenance distributors with vendor-managed inventory programs and direct compounder relationships with large OEM procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race where backward control over tetrafluoroethylene feedstock and forward capture of OEM qualification programs determine margin sustainability. Players are pursuing captive polymerization capacity as the decisive upstream lever.
For Market Incumbents: Anticipate REACH perfluorinated substance restrictions accelerating customer qualification timelines for low-PFAS grades by securing ECHA pre-registration documentation ahead of compliance deadlines. Deepen backward integration into tetrafluoroethylene monomer supply through long-term offtake agreements with Chinese and US chemical producers. Defend distributor relationships by embedding vendor-managed inventory programs at Texas and Louisiana refinery maintenance contractors.
For New Entrants and Emerging Players: Hydrogen pipeline infrastructure maintenance contractors represent an underserved buyer archetype with unconsolidated procurement and limited incumbent qualification presence. Carbon capture equipment seal requirements at US Gulf Coast and North Sea installations offer specification entry points before large compounders complete amine-compatibility testing. Pursue direct digital marketplace relationships with mid-size chemical processors bypassing traditional distributor markups.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated material science conglomerates seeking fluoroelastomer formulation capabilities. Long-term viability favors compounders with demonstrated REACH compliance documentation and established automotive OEM qualification relationships. Watch for EPA fugitive emission standard tightening as the inflection signal accelerating seal replacement cycle demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive tetrafluoroethylene access insulates compounders from Chinese feedstock volatility and force majeure disruption. |
| REACH Pre-Registration Investment | Early ECHA documentation completion secures first-mover qualification advantages with German automotive OEMs. |
| Vendor-Managed Inventory Expansion | Embedded distributor programs at US Gulf Coast refineries capture consolidated maintenance procurement volumes. |
| Hydrogen Compatibility Testing | EPDM and specialized FKM validation for Netherlands pipeline projects opens material specification in emerging infrastructure. |
| Digital Marketplace Direct Relationships | B2B platform sales to mid-size chemical processors bypass traditional distributor margin capture. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with plant maintenance directors, OEM procurement managers, fluoroelastomer R&D directors, and industrial distribution channel heads provided operational validation. Secondary sources encompassed ECHA REACH substance registrations, EPA emission compliance databases, ACC and Cefic industry statistics, and SEC 10-K disclosures from listed material suppliers. Bottom-up demand modeling across end-use industries triangulated against top-down macroeconomic indicators.
Granularity-level modeling operated at material-grade tier, end-use industry, form factor, and regional production hub dimensions across the analysis window. CAGRs derived from segment-level volume trajectories weighted by value-per-unit differentials. Industry-specific forecast inputs incorporated REACH compliance timeline assumptions and EPA fugitive emission mandate implementation pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between EPA and ECHA frameworks, tetrafluoroethylene feedstock supply disruptions, and hydrogen economy infrastructure deployment pacing. Forecasts reflect documented assumptions on material substitution rates and qualification cycle durations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
EMEA Epoxy Adhesives Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Roofing Adhesive Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Anti-Tack Agents Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
Global Silicone Adhesives Market
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market