
 Craft Glue Market | 2026-2036
Craft Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Craft Glue Market Analytics
Germany's adhesive manufacturing base is fragmenting as specialty craft producers multiply across Bavaria and North Rhine-Westphalia. Henkel AG leverages its European distribution infrastructure to sustain shelf presence in hobby retail chains. Pidilite Industries Limited anchors South Asian supply through localized PVA production. Beacon Adhesives differentiates via museum-conservation-grade formulations for archival paper crafts.
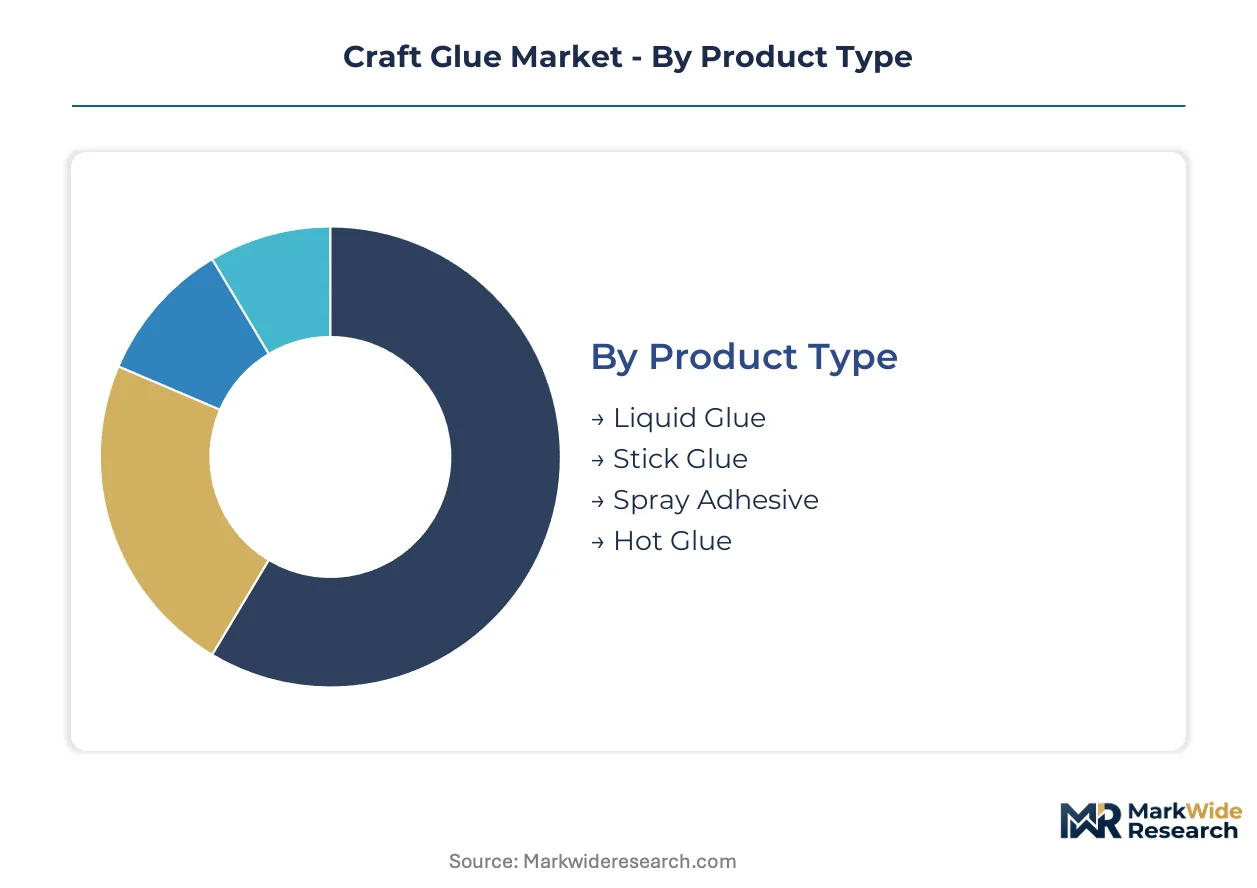
Craft glue comprises formulated adhesives engineered for bonding porous and semi-porous substrates at ambient temperatures, typically exhibiting viscosity ranges of 500–5000 cP and set times under 60 seconds for classroom deployment. Liquid Glue dominates volume through school procurement contracts, while Spray Adhesive commands premium positioning in mixed-media artwork. Hot Glue cartridges are accelerating fastest among home crafters seeking instant tack for fabric bonding and wreath assemblies.
EPA oversees volatile organic compound limits in consumer adhesives under 40 CFR 59, while EU REACH mandates full substance disclosure for resin precursors crossing into European hobby channels. The EU F-Gas Regulation indirectly pressures solvent-based alternatives as propellant chemistry faces phase-down schedules. Stakeholders must monitor evolving state-level green chemistry laws in California and New York that threaten to bifurcate domestic formulation standards from export-optimized products.
Market Dynamics
Formulation chemistry fragmentation is splitting craft glue production between legacy solvent-based systems and water-borne bio-adhesives, forcing manufacturers to maintain dual R&D tracks as regional regulatory thresholds diverge.
Growth Catalysts
- EU REACH substance disclosure mandates:Full chemical transparency requirements are accelerating investment in bio-based resin platforms across European hobby supply chains.
- Millennial homeowner DIY adoption:First-time property ownership in suburban corridors is expanding home décor project frequency and adhesive consumption intensity.
- Hot melt cartridge technology:Instant-tack bonding systems are displacing liquid alternatives in fabric and floral wreath applications among home crafters.
Market Restraints
- Petrochemical feedstock volatility:Ethylene-vinyl acetate and synthetic rubber precursor costs swing with crude oil indices, compressing margin predictability for volume producers.
- German specialty chemical concentration:Bavaria and North Rhine-Westphalia host disproportionate formulation capacity, creating geographic supply vulnerability.
- EU F-Gas propellant phase-down:Aerosol-based spray adhesives face reformulation pressure as hydrofluorocarbon propellants retreat from consumer product channels.
Strategic Opportunities
- Archival conservation certification:Museum-grade acid-free formulations command 3-4x pricing multiples in paper preservation and heritage restoration verticals.
- Indian domestic production scaling:Localized polyvinyl acetate manufacturing in Maharashtra and Gujarat bypasses import duty exposure for South Asian hobby retail.
- California green chemistry preemption:State-level safer product mandates are creating first-mover advantage windows for bio-adhesive formulations ahead of federal alignment.
Industry Challenges
- Dual-track formulation compliance:Maintaining separate product lines for REACH-export markets versus domestic U.S. VOC thresholds strains quality assurance bandwidth.
- Adhesive chemist talent scarcity:Formulation science programs at technical universities produce fewer graduates than specialty chemical sector hiring demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Craft Glue Market |
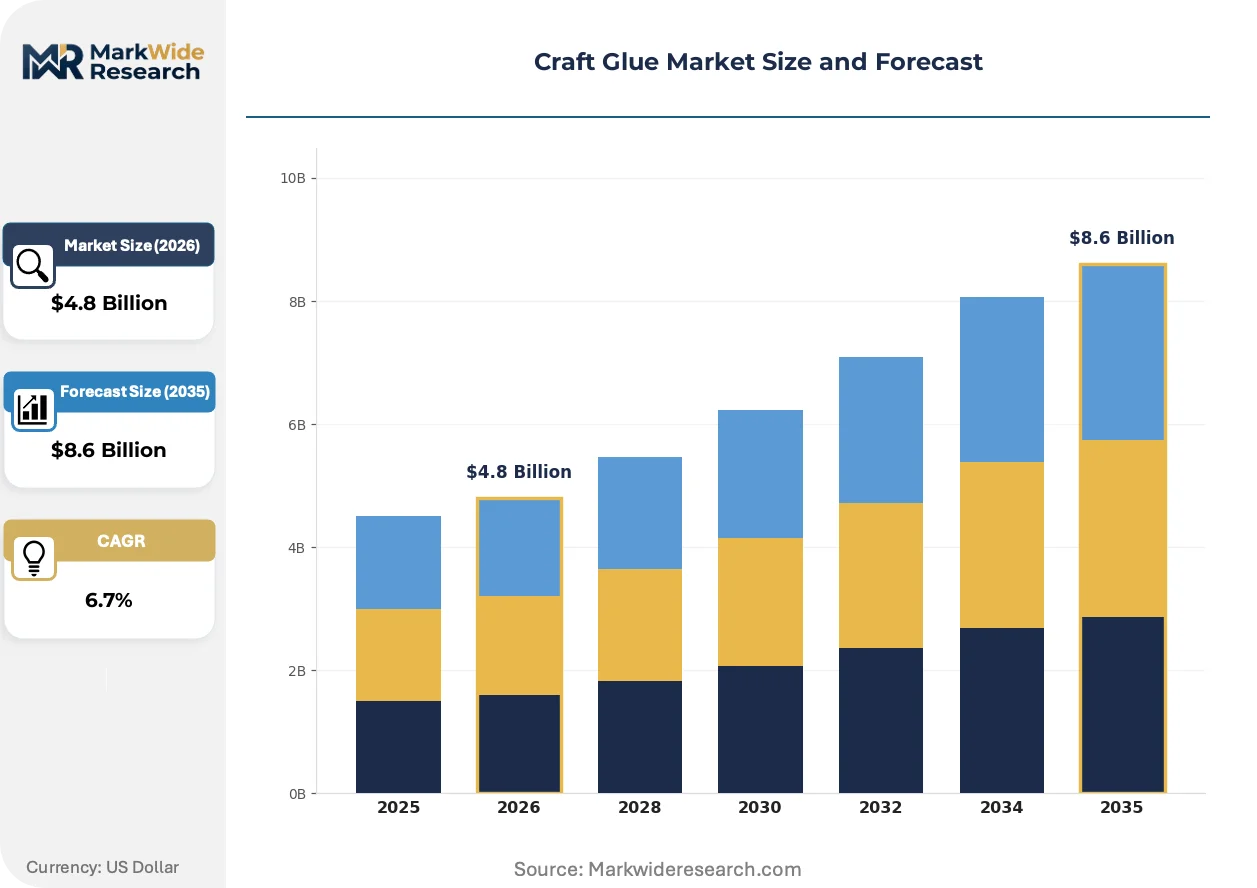
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Glue, Stick Glue, Spray Adhesive, Hot Glue Material: PVA, Epoxy, Silicone, Acrylic End User: Schools, Artists, Crafters, Hobbyists Application: Paper Crafts, Wood Projects, Fabric Bonding, Model Making |
| Companies Covered | DAP Products Inc., Plaid Enterprises, Henkel AG, 3M Company, UHU, Franklin International, Beacon Adhesives, Pidilite Industries Limited, Gorilla Glue Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Craft Glue Market Evolving Landscape
Bio-based resin platforms are collapsing the traditional separation between performance and sustainability claims, while regulatory chemistry disclosure rules and direct-to-hobbyist e-commerce channels are compressing established supply hierarchies.
Water-borne polysaccharide adhesives derived from corn starch and cellulose feedstocks are collapsing the cost premium historically attached to solvent-free formulations. School procurement offices and children's craft kit assemblers are adopting these systems at accelerated tender cycles. The technology is collapsing the two-tier pricing structure that separated educational-grade from premium archival products.
EU REACH Annex XVII restrictions on substance of very high concern (SVHC) thresholds are forcing reformulation of legacy acrylic and epoxy resin systems. Industrial consequence includes accelerated substitution of formaldehyde-releasing precursors in classroom-grade white glue. German and French hobby retail chains are responding by demanding full material safety data sheet transparency from Asian contract manufacturers.
Subscription box curation services are consolidating individual crafter demand into predictable monthly volume commitments. Traditional distributor markups in hobby retail are compressing as direct brand-to-consumer logistics bypass wholesale tiers. This pattern is most visible in U.S. and U.K. urban markets where millennial consumers prioritize project variety over bulk economy purchasing.
Craft Glue Market Segmentation
Craft glue demand fragments across distinct user workflows, from classroom bulk consumption to precision archival work. Each segmentation axis reveals divergent price sensitivities, regulatory exposure, and formulation requirements that reshape competitive positioning.
Product Type:
Mature liquid formats dominate procurement channels while emerging instant-tack systems capture home crafting growth.
- Liquid Glue:Water-borne polyvinyl acetate suspensions with viscosity calibrated for controlled flow through narrow applicator nozzles. School district procurement contracts in suburban U.S. corridors concentrate volume demand, though REACH substance disclosure is forcing reformulation of legacy preservative systems.
- Hot Glue:Thermoplastic ethylene-vinyl acetate formulations delivered through heated cartridge systems enabling sub-30-second tack development. Home crafters in Germany's DIY retail corridor are displacing liquid alternatives for fabric and floral wreath assemblies, driving fastest-format expansion.
- Stick Glue:Solid PVA extrusions in twist-dispense barrels offering portable application without drying time risk.
- Spray Adhesive:Aerosol-dispersed synthetic rubber systems facing EU F-Gas propellant phase-down pressure.
Liquid Glue handles the majority of throughput; Hot Glue is gaining share fastest among non-institutional users.
Material:
Cost tier separation runs from commodity PVA to specialty epoxy systems commanding certification premiums.
- PVA:Polyvinyl acetate emulsions polymerized in aqueous suspension, forming flexible films with moderate water resistance upon drying. Maharashtra and Gujarat production clusters in India bypass import duty exposure for South Asian hobby retail, anchoring regional supply.
- Epoxy:Two-part thermosetting systems combining bisphenol-A resin with amine hardeners, achieving structural bond strength exceeding substrate cohesion. Museum conservation workshops demand acid-free archival grades at 3-4x pricing multiples over standard formulations.
- Silicone:Room-temperature-vulcanizing elastomeric adhesives tolerating thermal cycling and moisture exposure.
- Acrylic:Solvent-borne or emulsion polymer systems with rapid skin formation and UV stability.
PVA commands volume leadership across institutional channels; Epoxy climbs fastest on heritage restoration demand.
End User:
Customer type determines packaging scale, from metric-ton school tenders to individual artisan SKUs.
- Schools:Bulk procurement of classroom-grade white glue in gallon containers and dispenser systems, subject to EPA VOC limits under 40 CFR 59 and accelerating substitution of formaldehyde-releasing preservatives.
- Crafters:Home-based project enthusiasts purchasing through subscription box curation services and direct-to-consumer channels, consolidating demand into predictable monthly volume commitments.
- Artists:Professional practitioners requiring archival certification and substrate-specific performance.
- Hobbyists:Casual makers prioritizing project variety over bulk economy purchasing.
Schools drive the largest single-channel volume; Crafters show steepest expansion trajectory as millennial homeownership rises.
Application:
Substrate specificity dictates adhesive selection, with porous materials enabling water-borne systems and non-porous surfaces demanding solvent or reactive chemistries.
- Paper Crafts:Bonding of cellulose fiber substrates including cardstock, origami paper, and archival documents, where acid-free PVA formulations prevent long-term embrittlement. German and French hobby retail chains now demand full material safety data sheet transparency from Asian contract manufacturers.
- Fabric Bonding:Textile lamination requiring flexible, wash-resistant bonds without stiffness or discoloration, driving hot melt cartridge adoption among wreath assemblers and quilting circles.
- Wood Projects:Structural joining of timber and engineered wood products where gap-filling and creep resistance matter.
- Model Making:Precision assembly of miniature components across plastic, resin, and wood substrates.
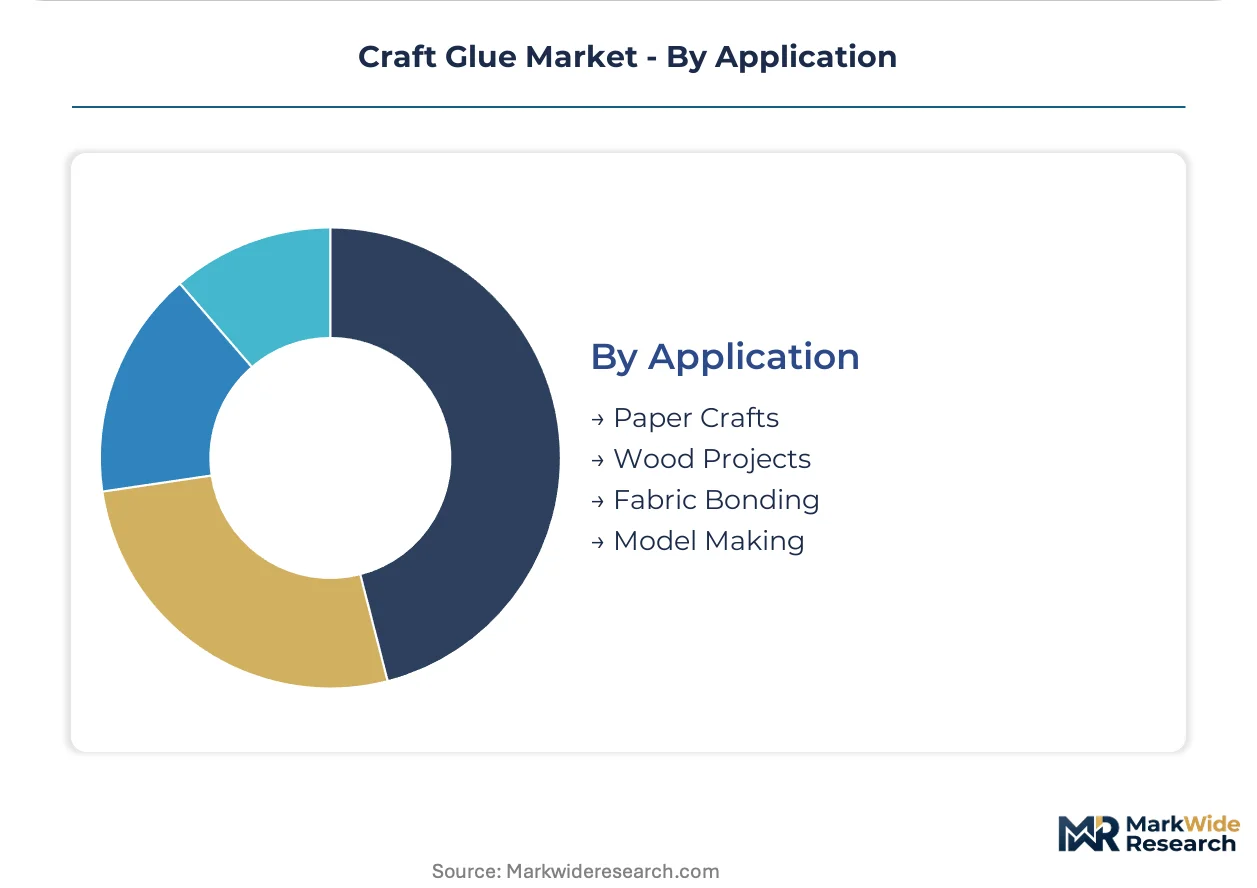
Paper Crafts handles the majority of volume; Fabric Bonding expands most quickly on home décor project frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance disclosure mandates from the European Chemicals Agency are tightening formulation requirements across craft adhesive supply chains. The United States and Germany concentrate regulatory enforcement capacity, while India and China scale domestic manufacturing to serve regional hobby retail expansion.
United States
Millennial suburban homeownership in Texas and Florida corridors is expanding DIY décor project frequency. EPA oversight of volatile organic compound limits under 40 CFR 59 is forcing reformulation of legacy solvent-based classroom adhesives. California's green chemistry preemption is creating first-mover advantage windows for bio-adhesive producers ahead of federal alignment.
Germany
Bavaria and North Rhine-Westphalia host disproportionate specialty chemical formulation capacity for European hobby supply chains. EU F-Gas Regulation phase-down schedules are pressuring aerosol propellant chemistry in spray adhesive segments. Frankfurt and Munich retail corridors are demanding full material safety data sheet transparency from Asian contract manufacturers.
India
Localized polyvinyl acetate manufacturing in Maharashtra and Gujarat is bypassing import duty exposure for South Asian hobby retail. BIS certification requirements are tightening quality thresholds for classroom-grade adhesive imports. Mumbai and Pune production clusters are scaling water-borne bio-adhesive output for domestic craft kit assemblers.
China
Yangtze River Delta manufacturing bases are supplying volume contract manufacturing for European and North American private label brands. MEE enforcement of dual carbon goals is accelerating substitution of formaldehyde-releasing precursors in white glue formulations. Shanghai and Suzhou chemical parks are consolidating water-borne resin production for export-optimized craft adhesives.
United Kingdom
Subscription box curation services in London and Southeast England are consolidating millennial crafter demand into predictable monthly volume commitments. Post-Brexit divergence from REACH is creating parallel compliance tracks for UK versus EU hobby retail channels. Midlands distribution hubs are adapting to direct-to-consumer logistics bypassing traditional wholesale tiers.
Craft Glue Market Competitive Landscape
Multi-product chemical conglomerates and specialty adhesive pure-plays split the craft glue market into distinct competitive orbits. The vendor base concentrates around legacy industrial adhesive manufacturers extending into hobby channels alongside craft-focused specialists defending premium archival positioning. Three archetypes dominate: diversified chemical majors leveraging European distribution infrastructure, regional PVA producers anchoring South Asian supply, and conservation-grade specialists commanding certification premiums. Competitive moves center on dual-track formulation compliance for diverging regulatory markets and backward integration into bio-resin feedstock sourcing.
Within the diversified chemical tier, Henkel AG exemplifies the European distribution-heavy archetype, while Pidilite Industries Limited occupies the South Asian regional anchor position. Beacon Adhesives represents the conservation-grade specialist model. These three companies collectively illustrate how geographic origin and strategic focus determine competitive positioning across institutional procurement, home crafting, and heritage restoration verticals.
| Leading Market Players |
|---|
| DAP Products Inc. |
| Plaid Enterprises |
| Henkel AG |
| 3M Company |
| UHU |
| Franklin International |
| Beacon Adhesives |
| Pidilite Industries Limited |
| Gorilla Glue Company |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Antwerp chemical corridor's freight cost volatility compresses margin buffers for craft adhesive producers while amplifying price spreads between bulk institutional contracts and premium archival grades. This logistics chokepoint concentrates supply-side leverage among German and Dutch formulators who can absorb transport surcharges, forcing smaller competitors to retreat from pan-European distribution or accept compressed returns on water-borne bio-adhesive lines.
Pricing Analysis
Geographic price spreads between German hobby retail and Indian domestic channels exceed threefold for equivalent PVA formulations, reflecting divergent certification burdens and duty structures. The market operates through a contract-based long-term offtake model for school procurement, while direct-to-consumer channels favor transactional spot purchasing. Price differentiation rests on archival certification grade and volume scale, with museum-grade epoxy systems commanding substantial premiums over classroom white glue. Cost compression in standard PVA tiers is intensifying as Maharashtra production clusters scale output, though margins are tightening for European producers facing REACH compliance overhead.
Supply Chain Analysis
EU REACH substance disclosure mandates function as de facto export controls on legacy solvent-based formulations, restricting their flow into European hobby channels. Manufacturing gravity centers on Germany, India, and China, with Bavaria and North Rhine-Westphalia hosting disproportionate specialty chemical capacity. Raw material dependencies draw from ethylene-vinyl acetate feedstocks, corn starch polysaccharide precursors, and synthetic rubber propellant systems. Single-source vulnerability concentrates in German adhesive chemist talent pools, where technical university output lags sector hiring demand. Distribution runs through hobby retail chain procurement offices and direct-to-consumer e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The craft glue market sits in early-cycle expansion as millennial suburban homeownership accelerates DIY décor project frequency beyond historical household penetration rates.
For Market Incumbents: Entrench position through backward integration into bio-resin feedstock sourcing and captive PVA production in Maharashtra or Gujarat to neutralize import duty exposure. Henkel AG and Pidilite Industries Limited should prioritize dual-track formulation compliance infrastructure, as diverging REACH and EPA VOC thresholds threaten quality assurance bandwidth. Channel control through direct-to-consumer logistics investments will defend against subscription box curation services compressing traditional distributor markups. For New Entrants and Emerging Players: Build out presence in California's green chemistry preemption window, where state-level safer product mandates create first-mover advantage ahead of federal alignment. The archival conservation certification segment offers the most penetrable white-space target, with museum-grade acid-free formulations supporting premium positioning. A go-to-market angle through heritage restoration workshops and paper preservation specialists bypasses entrenched school procurement channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors conservation-grade specialists with established archival certification and defensible pricing multiples. Long-term viability hinges on bio-adhesive platform transitions completing across the projection horizon, with water-borne polysaccharide systems displacing legacy solvent chemistries. The signal to watch is formaldehyde-releasing precursor substitution rates in classroom-grade white glue, as this indicates regulatory compliance velocity and reformulation capex requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Resin Feedstocks | Corn starch and cellulose sourcing from agricultural processors secures cost position against petrochemical volatility. |
| Dual-Track Formulation Compliance Investment | Parallel REACH and EPA VOC testing infrastructure prevents market exclusion from regulatory divergence. |
| Archival Conservation Certification Acquisition | Museum-grade acid-free accreditation unlocks heritage restoration verticals at premium pricing multiples. |
| Direct-to-Consumer Channel Buildout | Subscription box partnerships and e-commerce fulfillment bypass wholesale tier compression in urban millennial markets. |
| Indian Domestic Production Scaling | Maharashtra and Gujarat PVA manufacturing clusters neutralize import duty exposure for South Asian hobby retail expansion. |
Research Methodology
Operator-level perspectives from adhesive formulation chemists, hobby retail procurement managers, school district purchasing officers, and museum conservation specialists anchored the qualitative base. Primary interviews across these stakeholder categories combined with secondary validation from customs trade data, BIS certification filings, SEC 10-K disclosures from diversified chemical majors, and ECHA REACH substance registration databases. Bottom-up volume modeling from school tender records and subscription box shipment data triangulated against top-down market sizing from regional production cluster output estimates.
Scenario-bracketing around regulatory compliance timelines and bio-adhesive substitution rates framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product format, material chemistry tier, end-user archetype, and application substrate specificity. CAGRs derived from weighted average of historical procurement growth patterns and forward-looking adoption curves for hot melt cartridge systems and water-borne polysaccharide platforms. Feedstock cost indices for ethylene-vinyl acetate and corn starch derivatives informed margin trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed chemical conglomerates or accelerated EU F-Gas phase-down schedules would shift outcomes substantially. Cross-checking against ECHA SVHC threshold revision announcements and California DTSC safer product regulatory updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Sealants Market
Adhesives & Sealants
Wood Adhesives Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
Waterproof Tapes Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market