
 Latin America Adhesives and Sealants Market | 2026-2036
Latin America Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Adhesives and Sealants Market Foresight
Brazilian adhesive producers is shifting capacity toward low-VOC water-based systems as environmental enforcement tightens across the region. Henkel AG & Co. KGaA anchors its Latin American position through extensive distribution networks serving construction and automotive OEMs. Sika AG specializes in structural adhesives for infrastructure projects, leveraging its technical service presence in São Paulo and Mexico City. Dow competes on material science breadth, sustaining regional supply through localized polymer production.
Adhesives and sealants comprise formulated bonding substances that polymerize under controlled conditions to create load-bearing or environmental barriers between substrates, with tensile shear strengths ranging from flexible sealant grades below one megapascal to structural epoxy systems exceeding thirty megapascals. Their primary commercial purpose centers on replacing mechanical fasteners, reducing assembly weight, and enabling dissimilar material joining across manufacturing sectors. Water-based adhesives now lead volume consumption in Latin America as regulatory pressure and end-user sustainability mandates reshape procurement criteria, while hot melt adhesives capture expanding share in packaging lines seeking solvent-free, rapid-set bonding. Pressure-sensitive adhesives occupy the highest margin tier within technology segments, driven by label and tape applications in Brazil's food export sector.
CONAMA in Brazil, PROFEPA in Mexico, and ANVISA for consumer goods contact applications collectively govern permissible chemical content, emissions thresholds, and product registration requirements across the region. These frameworks elevate compliance costs for imported formulations while creating preferential market access for locally certified producers. Stakeholders must monitor evolving state-level environmental enforcement in Brazil and pending Mexican updates to NOM-018-SCFI labeling standards to anticipate reformulation timelines and certification bottlenecks.
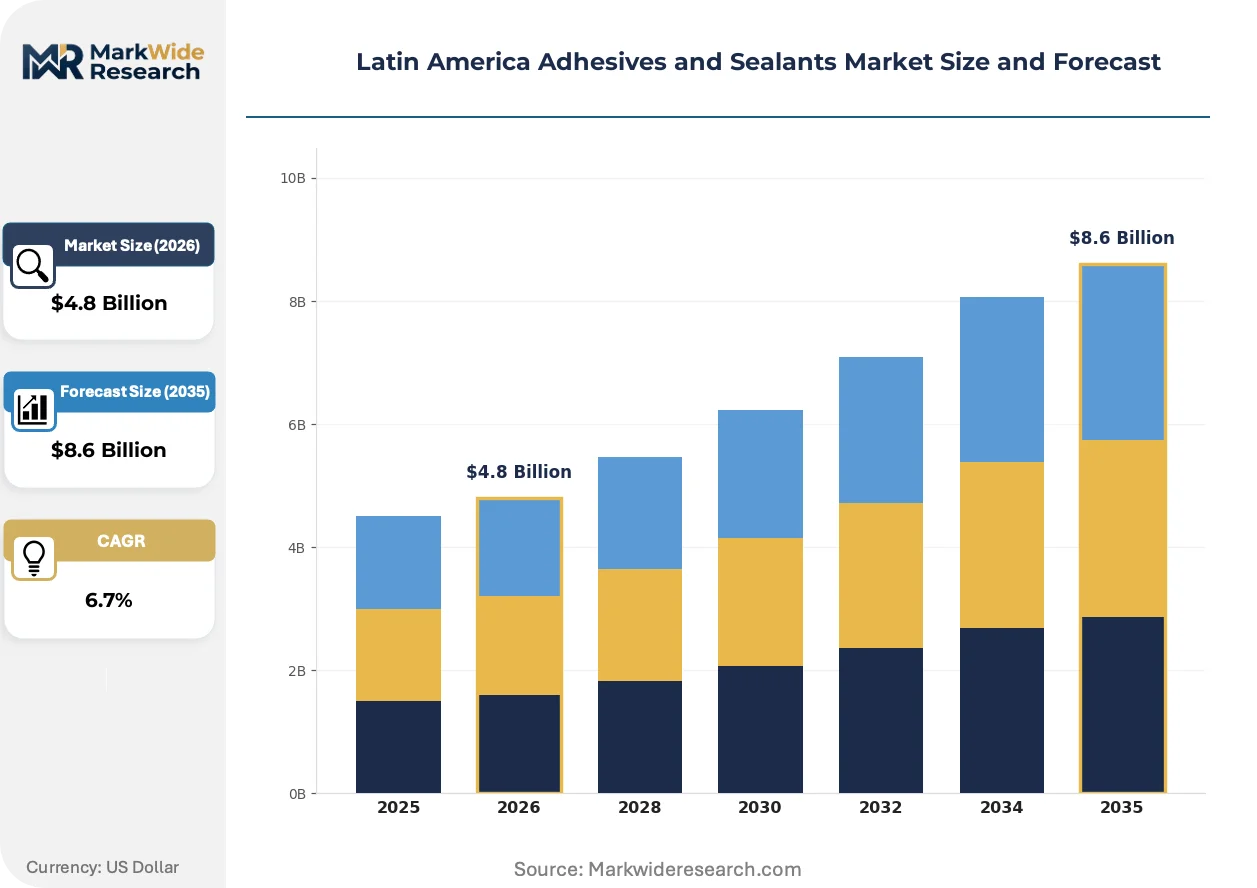
Market Dynamics
Brazil's updated CONAMA resolutions on VOC emissions are forcing adhesive producers to abandon solvent-based chemistries and retool manufacturing lines for water-based systems. This regulatory compression is redirecting capital flows across the Latin American region.
Growth Catalysts
- Automotive lightweighting mandates:Brazil's southeastern manufacturing corridor is accelerating structural bonding adoption as OEMs replace mechanical fasteners with high-strength adhesives to reduce vehicle weight.
- PROFEPA enforcement tightening:Mexico's environmental regulator is driving packaging converters toward hot melt systems that eliminate solvent emissions from food export lines.
- Water-based formulation advances:Polymer chemistry improvements are closing the performance gap with solvent systems, enabling substitution in construction and furniture applications.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and polyurethane resin costs fluctuate with regional naphtha and propylene supply, squeezing formulation margins unpredictably.
- Import dependency for specialty monomers:Brazil and Mexico rely on US and Asian suppliers for epoxy hardeners and silane coupling agents, creating supply vulnerability.
- ANVISA registration timelines:Brazil's health regulator requires 18-24 month approval cycles for adhesives with food contact applications, delaying product launches.
Strategic Opportunities
- Colombia's underdeveloped automotive supply base:The Andean nation lacks localized adhesive technical service infrastructure, creating first-mover advantage for producers establishing compounding facilities.
- Biobased feedstock incentives:Brazil's RenovaBio program offers carbon credit advantages for adhesives incorporating sugarcane-derived ethanol in polyurethane synthesis.
- E-commerce packaging surge:Pressure-sensitive tape demand is outpacing box production in Mexico's northern border states as fulfillment center density increases.
Industry Challenges
- Formulation chemist scarcity:Latin American universities produce limited polymer science graduates, forcing producers to recruit from European and US talent pools.
- Legacy equipment retrofit costs:Converting solvent-based coating lines to water-based systems requires drying oven modifications and humidity control investments that strain mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Adhesives and Sealants Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Adhesives, Solvent-Based Adhesives, Hot Melt Adhesives, Structural Adhesives Application: Construction, Automotive, Electronics, Packaging Technology: Reactive Adhesives, Thermal Adhesives, Pressure-Sensitive Adhesives, Anaerobic Adhesives End User: Manufacturers, Contractors, DIY Enthusiasts, Retailers |
| Companies Covered | Sika AG, Dow, 3M, Avery Dennison Corporation, BASF SE, Henkel AG & Co. KGaA, Bostik, Arkema, H.B. Fuller Company, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Adhesives and Sealants Market Shifts & Advancements
Water-based adhesive technology is overtaking solvent systems across multiple end-use verticals, while regulatory frameworks and procurement patterns are compressing traditional supply relationships. These forces are restructuring competitive positioning in the region.
Polyurethane dispersion adhesives are overtaking contact cements in Brazil's furniture and footwear sectors. São Paulo-based manufacturers are adopting these systems to meet CONAMA VOC limits without sacrificing bond strength on leather and engineered wood substrates. The technology is overtaking conventional solvent neoprene formulations that previously dominated these applications.
CONAMA Resolution 491/2018 and subsequent state-level enforcement protocols are mandating real-time emissions monitoring at adhesive production facilities. Brazilian producers must install continuous VOC detection systems and report quarterly to environmental agencies. Small and mid-sized compounders in the ABC Paulista industrial zone are consolidating or exiting as compliance costs escalate.
Automotive OEMs in Mexico are consolidating adhesive suppliers from twelve-plus vendors to three approved partners per vehicle platform. Tier-1 seating and interior suppliers must now qualify through centralized procurement committees rather than plant-level purchasing. This concentration is most visible in Guanajuato's automotive cluster, where Volkswagen and Toyota assembly operations have standardized bonding system specifications.
Latin America Adhesives and Sealants Market Segmentation
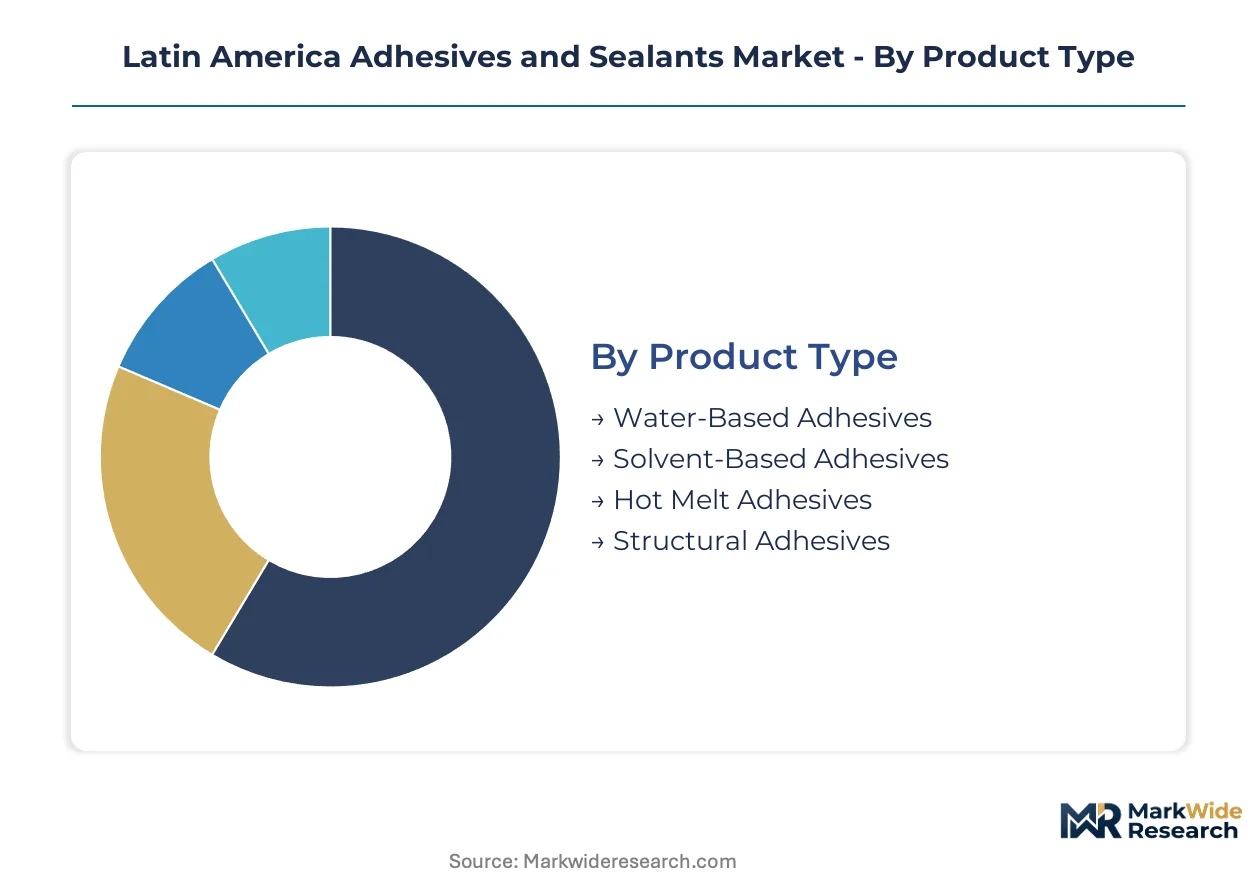
Segmentation in Latin America's adhesives and sealants market reveals how regulatory pressure and end-use specialization are fragmenting demand across incompatible chemistries. Each dimension exposes distinct margin structures, compliance burdens, and upgrade cycles that determine supplier profitability.
Product Type:
Upgrade cycles vary dramatically by chemistry family, with water-based systems forcing the most aggressive retooling investments as Brazilian manufacturers abandon legacy solvent lines.
- Water-Based Adhesives:Acrylic and polyurethane dispersions that cure through moisture evaporation rather than solvent release. São Paulo furniture manufacturers are converting spray lines to these systems to meet CONAMA VOC thresholds without sacrificing bond strength on engineered wood substrates.
- Hot Melt Adhesives:Thermoplastic polymers applied molten and set through rapid cooling, eliminating solvent emissions entirely. Mexican packaging converters in Guanajuato are adopting these systems for food export lines as PROFEPA enforcement tightens on solvent-based alternatives.
- Solvent-Based Adhesives:Traditional neoprene and contact cement formulations facing regulatory compression across Brazil's southeastern manufacturing corridor.
- Structural Adhesives:High-strength epoxy and polyurethane systems exceeding thirty megapascals tensile shear strength for load-bearing applications.
Volume placements concentrate in water-based adhesives; the faster expansion belongs to hot melt adhesives.
Application:
Cost tier differentiation separates commodity construction grades from specification-driven automotive and electronics bonding systems.
- Construction:Bulk consumption of tile adhesives, waterproofing membranes, and structural bonding systems for Brazil's residential and infrastructure buildout. CONAMA-compliant water-based formulations are displacing solvent contact cements in flooring and panel installation across the ABC Paulista industrial zone.
- Automotive:Structural adhesives enabling multi-material vehicle construction as OEMs replace mechanical fasteners to reduce weight. Volkswagen and Toyota operations in Guanajuato have standardized bonding specifications, consolidating supplier bases from twelve vendors to three approved partners per platform.
- Electronics:Precision dispensing of thermally conductive and electrically isolating adhesives for device assembly.
- Packaging:High-speed carton sealing and flexible film lamination driven by Mexico's northern border state fulfillment center density.
Construction absorbs the largest volume placements; automotive claims the steepest expansion trajectory.
Technology:
Application requirements dictate technology selection, with reactive systems commanding premium pricing for permanent bonds versus removable pressure-sensitive alternatives.
- Pressure-Sensitive Adhesives:Permanently tacky formulations requiring only contact pressure to adhere, occupying the highest margin tier within technology segments. Brazilian food exporters drive demand for label and tape applications compliant with ANVISA food contact registration timelines.
- Reactive Adhesives:Two-component epoxy and polyurethane systems that polymerize through chemical reaction to form irreversible bonds. Infrastructure projects in São Paulo and Mexico City specify these for structural load-bearing applications where Sika AG maintains technical service presence.
- Thermal Adhesives:Hot melt and thermosetting systems activated by heat application and cooling.
- Anaerobic Adhesives:Single-component liquids that cure in the absence of oxygen, used for threadlocking and retaining applications.
Pressure-sensitive adhesives dominate margin capture; reactive adhesives are expanding most quickly in infrastructure specifications.
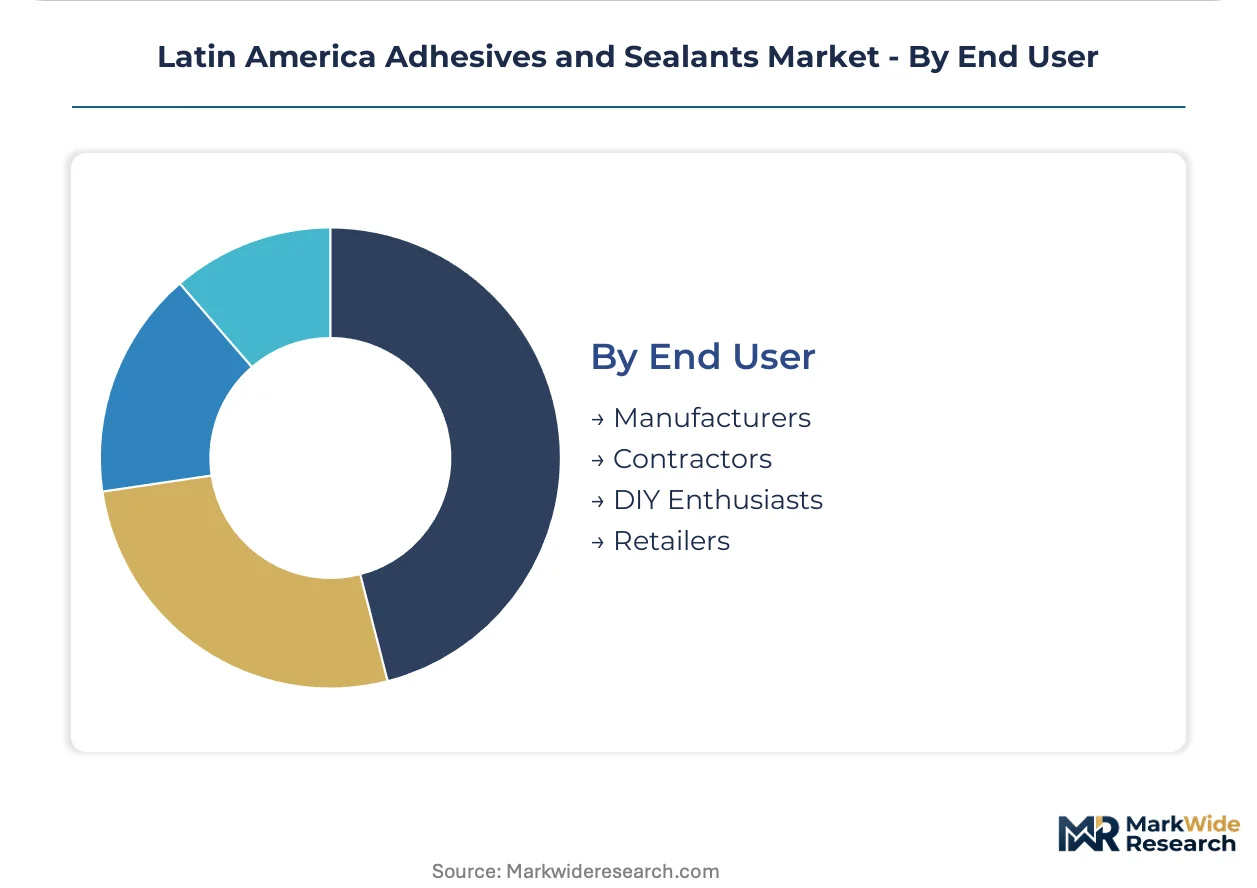
End User:
Customer type determines procurement sophistication, with manufacturers demanding technical service integration that DIY and retail channels cannot support.
- Manufacturers:OEM and tier-1 suppliers requiring formulation customization, joint design engineering, and batch certification. Automotive seating and interior suppliers in Brazil's southeastern corridor must now qualify through centralized procurement committees rather than plant-level purchasing.
- Contractors:Professional installation crews specifying construction adhesives with documented cure schedules and warranty backing.
- DIY Enthusiasts:Consumer retail purchasers of small-format adhesives for home repair and craft applications.
- Retailers:Distributors and hardware chains stocking standardized product lines with minimal technical support requirements.
Manufacturers command the deepest technical engagement; contractors represent the fastest-climbing volume segment as Brazilian construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in Brazil's southeastern corridor anchors Latin American adhesive production capacity. Regional supply chains concentrate around São Paulo's polymer manufacturing belt and Mexico's northern industrial corridor. Regulatory divergence between CONAMA-enforced Brazil and PROFEPA-monitored Mexico creates distinct formulation requirements across national boundaries.
Brazil
São Paulo furniture manufacturers drive water-based polyurethane dispersion demand for engineered wood bonding. CONAMA Resolution 491/2018 mandates continuous VOC emissions monitoring at production facilities. The ABC Paulista industrial zone witnesses small compounders consolidating or exiting as compliance costs escalate.
Mexico
Automotive OEMs in Guanajuato consolidate adhesive suppliers from twelve vendors to three approved partners per platform. PROFEPA enforcement tightens on solvent emissions from food export packaging lines. Northern border states experience pressure-sensitive tape demand outpacing box production from fulfillment center density growth.
Argentina
Construction sector recovery stimulates tile adhesive and waterproofing membrane consumption in Buenos Aires metropolitan expansion. The country's national environmental regulator imposes emissions thresholds on industrial coating operations. Córdoba's automotive component suppliers seek technical service partnerships for structural bonding qualification.
Chile
Mining equipment maintenance generates demand for high-strength threadlocking and retaining compounds in Antofagasta and Atacama operations. The country's national chemical safety agency enforces workplace exposure limits on adhesive handling. Santiago's packaging converters adopt hot melt systems for food export compliance.
Colombia
Andean automotive assembly growth outpaces localized adhesive technical service infrastructure availability. The national environmental licensing authority requires emissions permits for solvent-based coating operations. Bogotá's manufacturing corridor attracts first-mover producers establishing regional compounding facilities.
Latin America Adhesives and Sealants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biobased feedstock differentiation and specialized technical service capabilities. The market structures around three concentration levels: multinational chemical conglomerates with integrated polymer supply, regional compounders serving construction and packaging verticals, and niche specialists in automotive specification-grade systems. Competitive dynamics center on formulation registration speed and environmental compliance certification rather than price alone. Dominant moves include backward integration into captive resin production and geographic expansion through technical service hub establishment.
Within the multinational tier, Henkel AG & Co. KGaA, Sika AG, and Dow occupy positions reflecting distinct strategic anchors. Henkel exemplifies distribution-network breadth serving construction and automotive OEMs. Sika represents technical service intensity for infrastructure project specification. Dow embodies material science breadth sustained through localized polymer production. These three illustrate how European and US-origin conglomerates structure Latin American presence through differentiated capability emphasis rather than undifferentiated scale competition.
| Leading Market Players |
|---|
| Sika AG |
| Dow |
| 3M |
| Avery Dennison Corporation |
| BASF SE |
| Henkel AG & Co. KGaA |
| Bostik |
| Arkema |
| H.B. Fuller Company |
| Others |
Supply & Pricing Matrix
Automotive OEM procurement committees in Guanajuato and São Paulo concentrate purchasing power across standardized bonding specifications, anchoring contract-based long-term offtake agreements that lock in volume commitments and technical service bundling. This buyer concentration elevates pricing power for specification-grade adhesive producers while squeezing margins on commodity construction grades sold through fragmented distributor networks.
Pricing Analysis
Warranty-backed technical service separates premium structural adhesive tiers from unbundled commodity offerings in Latin American procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—ANVISA-registered food-contact formulations command substantial premiums over general industrial grades. Price erosion runs through solvent-based construction adhesives as CONAMA enforcement accelerates water-based substitution. DIY retail purchasers exhibit highest price sensitivity, while automotive Tier 1 suppliers prioritize bond reliability over unit cost.
Supply Chain Analysis
Epoxy hardener and silane coupling agent supply rests on US Gulf Coast and Northeast Asian specialty chemical producers, creating import dependency for Brazilian and Mexican compounders. Acrylic resin feedstock draws from regional naphtha crackers concentrated in Brazil's southeastern corridor and US propylene supply. Single-source vulnerability characterizes specialty monomer procurement, with limited qualified alternatives for automotive specification-grade systems. Distribution runs through technical service hubs in São Paulo and Mexico City serving OEM direct accounts, supplemented by construction-focused distributor networks penetrating secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American adhesive supply confronts formulation chemist scarcity and legacy equipment retrofit bottlenecks that constrain capacity expansion, propping pricing power for qualified producers as regulatory deadlines compress.
For Market Incumbents: Cement market position through backward integration into captive acrylic dispersion production in Brazil's southeastern corridor, insulating margin structures from naphtha volatility. Prioritize ANVISA registration pipeline investment to capture food-contact specification premiums before enforcement timelines harden. Consolidate technical service presence in Colombia's emerging automotive corridor ahead of competitor facility announcements. For New Entrants and Emerging Players: Regional distributors serving mid-sized furniture manufacturers in Brazil's ABC Paulista industrial zone offer lowest barrier-to-entry channel access for water-based polyurethane dispersion specialists. Target Colombia's underdeveloped automotive technical service infrastructure through compounding facility establishment with localized application engineering support. Penetrate Mexican e-commerce packaging converters in northern border states via hot melt adhesive sampling programs tied to fulfillment center expansion timelines. For Investors and Strategic Acquirers: The window for entry favors mid-tier Brazilian compounders with CONAMA-compliant water-based capacity and established automotive qualification records. Acquisition target archetype: São Paulo-based producers with installed continuous emissions monitoring systems and pending ANVISA registrations. Watch for PROFEPA enforcement escalation in Mexican food export packaging as inflection indicator for hot melt substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin Production | Captive supply of dispersion feedstock shields Brazilian compounders from propylene volatility. |
| ANVISA Registration Pipeline Investment | Accelerated approval cycles capture food-contact adhesive premiums in Brazilian export packaging. |
| Technical Service Hub Establishment in Colombia | First-mover positioning addresses automotive OEM demand outpacing local adhesive infrastructure. |
| Continuous Emissions Monitoring Installation | CONAMA Resolution 491/2018 compliance preserves operating permits in ABC Paulista zone. |
| Hot Melt Capacity Expansion in Northern Mexico | PROFEPA-driven solvent substitution creates packaging converter demand in border fulfillment corridor. |
Research Methodology
Multi-period observation of CONAMA enforcement intensity, PROFEPA inspection frequency, and automotive OEM supplier consolidation patterns anchored the trend analysis, supplemented by interviews with adhesive formulation chemists, automotive Tier 1 procurement directors, construction distributor sales managers, and polymer plant operations heads. Secondary validation drew from customs trade data, ANVISA registration databases, SEC filings of multinational chemical conglomerates, and Brazilian environmental agency enforcement records. Bottom-up volume modeling triangulated against top-down market sizing across chemistry family, end-use vertical, and national regulatory cluster dimensions.
Input-output matrices mapped polymer feedstock availability, formulation capacity utilization, and end-use demand elasticity across the projection horizon. Segmentation dimensions modeled include chemistry family, application sector, technology type, and customer procurement sophistication tier. CAGRs derived from elasticity-adjusted volume projections incorporating regulatory phase-in schedules and OEM platform standardization timelines. Industry-specific forecast inputs encompassed RenovaBio carbon credit eligibility for biobased polyurethane synthesis and state-level Brazilian environmental enforcement variation.
Caveats apply where ANVISA registration timeline extensions, PROFEPA enforcement intensity recalibration, or automotive platform specification reversals could materially shift the outlook. A small set of named triggers—CONAMA Resolution 491/2018 state-level implementation pace, Mexican NOM-018-SCFI labeling standard updates, and Colombian automotive assembly capacity announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
Singapore Adhesives Market
Adhesives & Sealants
Contact Cement Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
Marine Sealants Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
Middle-East and Africa Waterborne Adhesives Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Spray Fluxer Market