
 North America Ethylene Dichloride (EDC) Market | 2026-2036
North America Ethylene Dichloride (EDC) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ethylene Dichloride (EDC) Market Intelligence
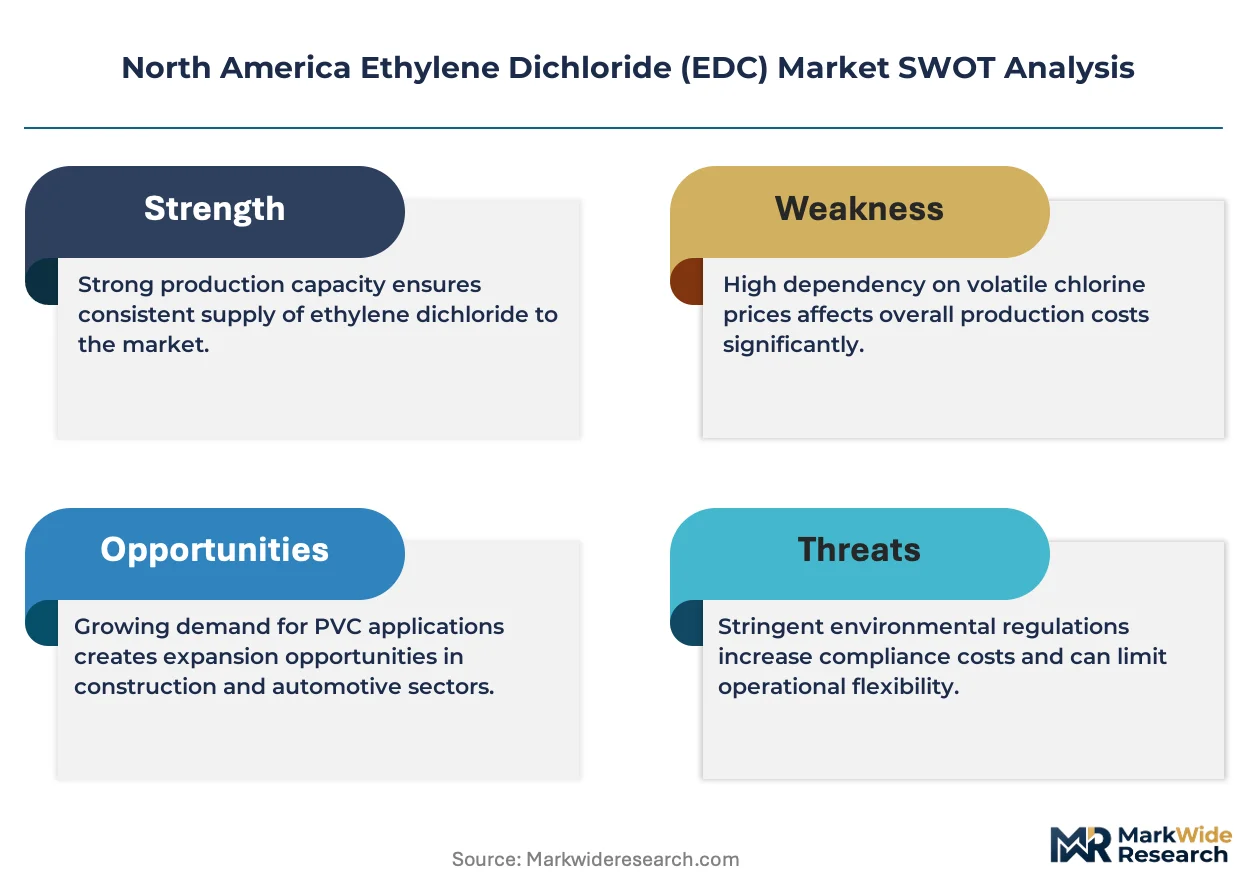
Asset-light leasing structures for chlor-alkali infrastructure are reshaping capital deployment across the North America Ethylene Dichloride (EDC) landscape. Westlake Chemical Corporation leverages its integrated PVC chain to sustain margin capture from salt to finished resin. Olin Corporation anchors its competitiveness through large-scale diaphragm and membrane cell operations across the US Gulf. Dow Inc. differentiates via technology leadership in energy-efficient EDC cracking and purification systems.
Ethylene dichloride is a chlorinated hydrocarbon with the formula C2H4Cl2, produced primarily through direct chlorination or oxychlorination of ethylene, and serves as the principal precursor to vinyl chloride monomer for PVC production. The compound boils at 83.5 degrees Celsius and requires careful handling due to its volatility and classification as a probable carcinogen under EPA guidelines. Industrial grade material dominates volume flows into chemical intermediate applications, where margin pools remain deepest due to long-term supply contracts with PVC resin producers. Specialty grade segments are expanding fastest within adhesive formulations, driven by electronics manufacturers seeking higher purity specifications for laminate bonding processes.
EPA National Emission Standards for Hazardous Air Pollutants and OSHA Process Safety Management standards govern EDC production facilities, with state-level air quality districts in Texas and Louisiana imposing additional permitting requirements that shape plant location decisions. The US Chemical Safety Board investigates major releases, creating reputational and financial exposure that influences insurer requirements and capital access for facility upgrades. Stakeholders must monitor proposed revisions to NESHAP rules for organic hazardous air pollutants, as tighter limits on 1,2-dichloroethane emissions could trigger significant abatement investments or capacity rationalization at older integrated sites.
Market Dynamics
Integrated petrochemical complexes along the US Gulf Coast are consolidating EDC offtake through captive chlorine-ethylene chains, compressing merchant market liquidity and favoring producers with backward integration into salt and ethylene feedstocks.
Growth Catalysts
- EPA NESHAP revisions:Proposed tighter 1,2-dichloroethane emission limits are accelerating abatement investments at older chlor-alkali sites, creating replacement demand for membrane cell upgrades and vapor recovery systems.
- PVC construction demand:Residential and infrastructure spending in Texas and Louisiana is pulling EDC through vinyl chloride monomer into pipe, siding, and window profiles.
- Oxychlorination efficiency gains:Catalyst improvements in fluid-bed reactors are reducing ethylene feedstock intensity per ton of EDC output at integrated Gulf Coast facilities.
Market Restraints
- Ethylene price volatility:Naphtha-cracker margins in the US Gulf fluctuate with global olefin balances, transmitting cost instability into EDC contract pricing.
- Merchant chlorine supply concentration:Diaphragm and membrane cell capacity clusters with three major producers, limiting bargaining power for non-integrated EDC buyers.
- Caustic soda co-production imbalance:Chlor-alkali economics tie EDC output to caustic demand cycles in pulp and alumina sectors, creating output constraints.
Strategic Opportunities
- Electronics-grade specialty EDC:Laminate adhesive applications for printed circuit boards in Mexico's maquiladora corridor are demanding higher purity specifications at premium spreads.
- Carbon capture integration:IRA 45Q tax credits for industrial CO2 sequestration are incentivizing EDC producers to retrofit crackers with post-combustion capture at Texas facilities.
- Membrane cell technology convergence:Ion-exchange membrane advances from chlor-alkali are transferring to EDC purification trains, enabling single-digit ppm impurity levels.
Industry Challenges
- Process safety engineering talent:OSHA PSM compliance and CSB investigation exposure require specialized chemical process safety expertise that commands premium compensation in the Houston Ship Channel labor market.
- Legacy control system integration:Distributed control system upgrades at 1980s-era crackers must interface with modern digital twin platforms without disrupting continuous operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ethylene Dichloride (EDC) Market |
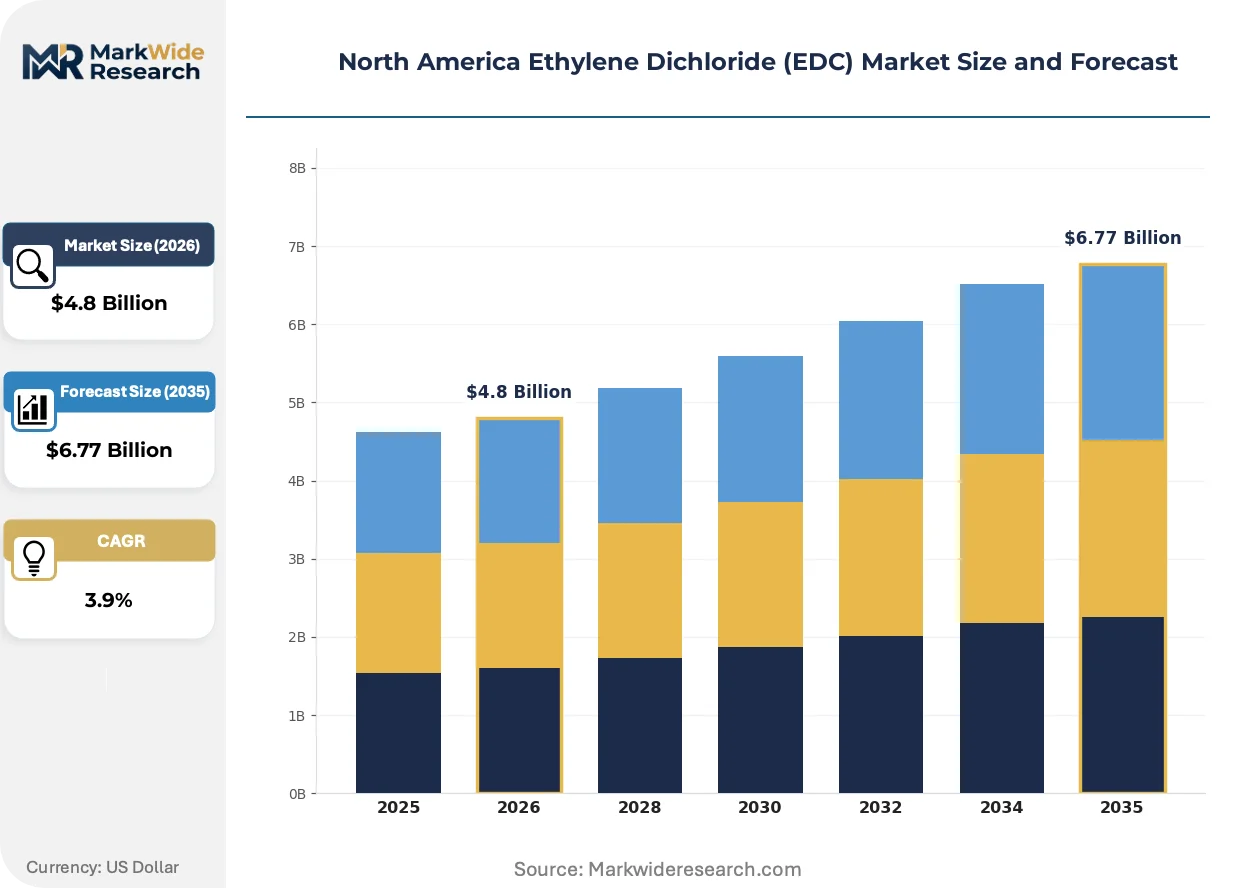
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Commercial Grade, Specialty Grade, Technical Grade End Use Industry: Construction, Automotive, Agriculture, Electronics Application: Solvent, Chemical Intermediate, Plasticizer, Adhesive Distribution Channel: Direct Sales, Online Sales, Wholesale Distribution, Retail |
| Companies Covered | Formosa Plastics Corporation, Chevron Phillips Chemical, Olin Corporation, Dow Inc., Shell Chemical, Westlake Chemical Corporation, INEOS Group, Shintech Inc., Occidental Petroleum Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ethylene Dichloride (EDC) Market Strategic Shifts & Innovations
Digital twin platforms and advanced process control systems are compressing the design-operate-optimize cycle for EDC crackers, enabling real-time yield adjustments that were previously manual and batch-based.
Digital twin software is virtualizing the entire EDC cracking and quench train, creating physics-based simulations that mirror thermal profiles and pressure drops across tube bundles. PVC resin producers with captive EDC units are deploying these models to optimize steam cracking severity without physical experimentation. This virtualization is compressing the experimentation cycle from weeks to hours, enabling faster response to ethylene feedstock quality variations.
OSHA Process Safety Management enforcement is intensifying around reactive chemical hazards, with regional emphasis programs targeting Gulf Coast chlor-alkali and EDC facilities for comprehensive audits. The agency's National Emphasis Program on chemical facilities is driving capital allocation toward inherently safer design modifications and automated emergency isolation systems. Smaller merchant EDC producers without integrated safety engineering depth are outsourcing compliance management to specialized consulting firms.
Long-term offtake contracting is displacing spot market transactions as PVC resin manufacturers seek feedstock security amid ethylene supply uncertainty. Integrated producers with salt-to-resin chains are locking in decade-long supply agreements with volume floors and price collars. This concentration is most visible in Louisiana, where chemical complexes along the Mississippi River corridor are consolidating procurement under master service agreements with single-source EDC suppliers.
North America Ethylene Dichloride (EDC) Market Segmentation
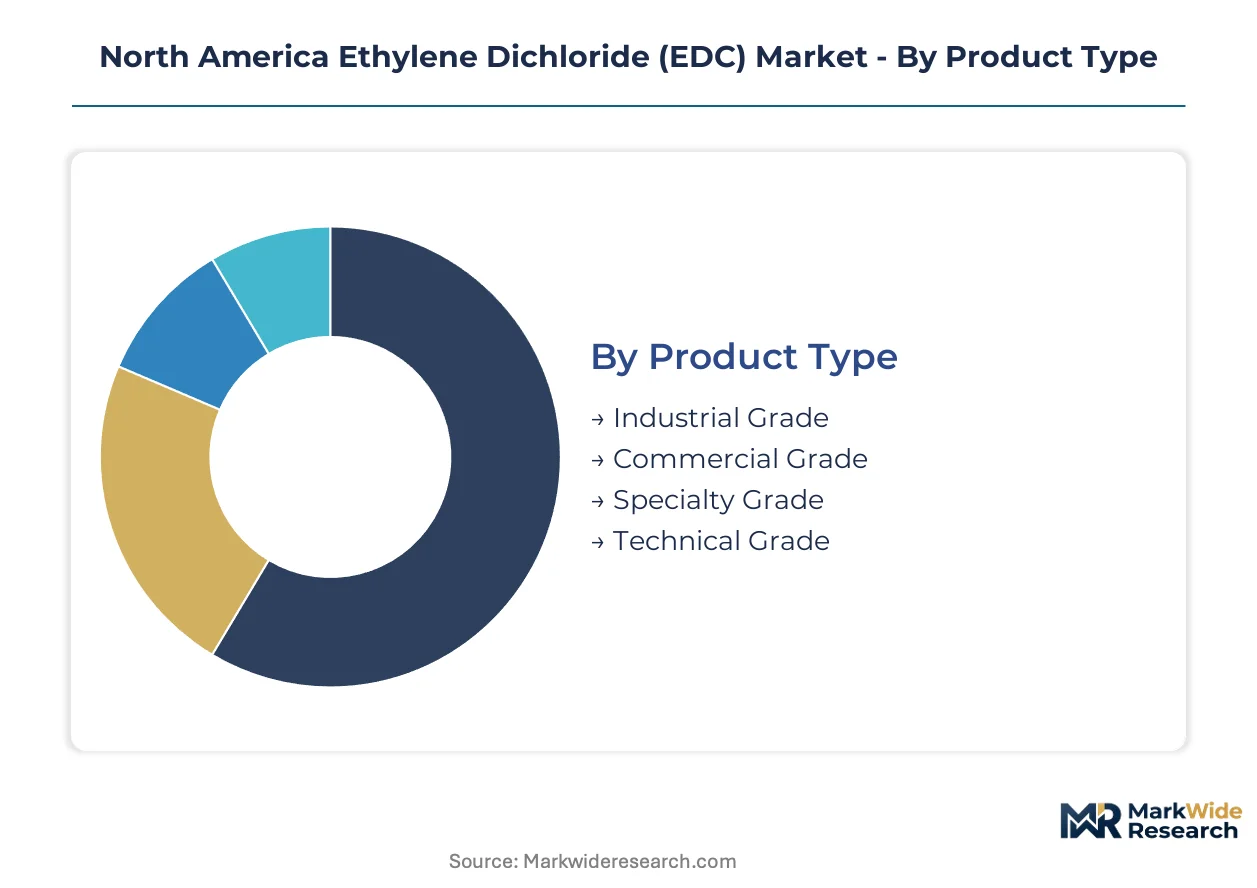
Segmentation in the North America EDC market reveals how purity specifications, end-use requirements, and supply chain configurations fragment procurement patterns. Each dimension carries distinct margin profiles and regulatory exposure that shape producer strategy.
Product Type:
After-sales service intensity varies sharply across purity tiers, with specialty grade demanding technical support for electronics manufacturers while industrial grade flows through commodity channels.
- Industrial Grade:Standard purity material serves as the primary feedstock for vinyl chloride monomer production at integrated Gulf Coast PVC complexes. Demand concentrates in Texas and Louisiana, where chlor-alkali producers with captive ethylene supply leverage long-term offtake agreements to lock in volume floors.
- Specialty Grade:Ultra-low impurity specifications enable laminate adhesive applications for Mexico's maquiladora electronics corridor. Specifications tighten as printed circuit board manufacturers demand single-digit ppm contamination thresholds, compressing the qualified supplier base and sustaining premium spreads.
- Commercial Grade:Mid-tier material bridges industrial and specialty applications with moderate purity controls.
- Technical Grade:Laboratory and analytical applications require documented batch consistency and certificate-of-analysis documentation.
Industrial grade holds the largest share; momentum sits with specialty grade.
End Use Industry:
Application maturity determines margin stability, with construction offering volume scale against electronics delivering pricing power.
- Construction:PVC pipe, siding, and window profile manufacturing consumes the majority of North American EDC output through vinyl chloride monomer intermediation. Residential and infrastructure spending in Texas and Louisiana pulls material through integrated Houston Ship Channel complexes.
- Electronics:Laminate bonding for printed circuit boards demands the highest purity specifications, creating qualification barriers that protect incumbent suppliers. Mexico's maquiladora corridor is expanding fastest as nearshoring accelerates electronics assembly.
- Automotive:Interior vinyl compounds and underbody coatings require consistent plasticizer compatibility.
- Agriculture:Fumigant and pesticide intermediate applications face EPA registration pressure that constrains volume growth.
Construction commands absolute volume; electronics offers the steepest expansion trajectory.
Application:
Functional role in the value chain dictates pricing mechanism, with chemical intermediates trading on cost-plus contracts versus solvents and adhesives on specification premiums.
- Chemical Intermediate:Dominant application channeling EDC into vinyl chloride monomer for downstream PVC resin production. Integrated producers along the Gulf Coast capture margin through salt-to-resin chains, compressing merchant market liquidity for non-integrated buyers.
- Adhesive:Electronics-grade laminate bonding requires sub-ppm impurity controls that command significant specification premiums. Demand is climbing fastest as Mexico's electronics assembly capacity expands.
- Solvent:Degreasing and metal cleaning applications face OSHA exposure limit compliance costs.
- Plasticizer:Vinyl formulation flexibility additives compete with phthalate and non-phthalate alternatives.
Chemical intermediate anchors volume; adhesive is gaining share fastest.
Distribution Channel:
Channel structure reflects customer scale and integration depth, with direct sales dominating captive relationships and wholesale serving fragmented buyers.
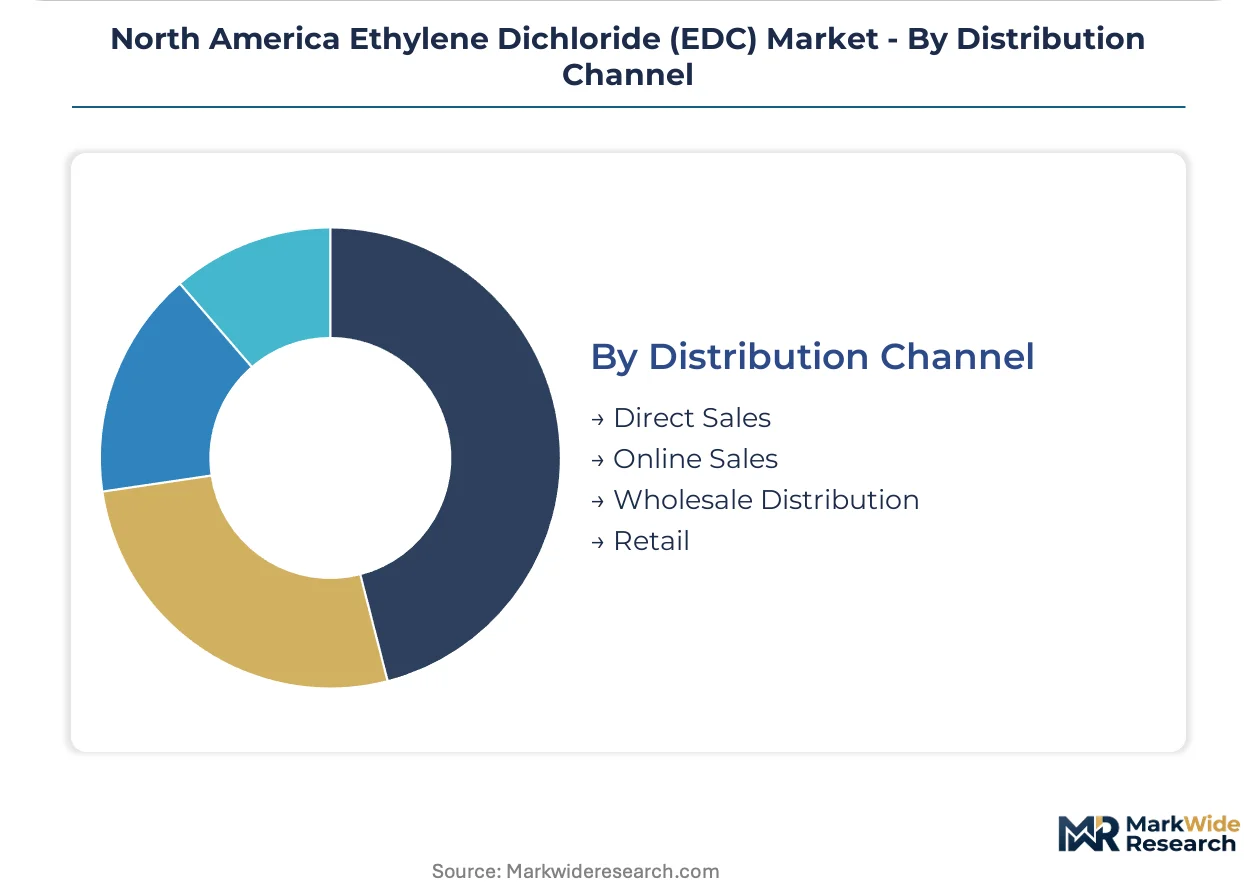
- Direct Sales:Integrated PVC resin manufacturers procure through long-term offtake contracts with volume floors and price collars. Master service agreements in Louisiana consolidate procurement under single-source arrangements that eliminate spot market exposure.
- Wholesale Distribution:Merchant EDC buyers without captive chlorine-ethylene chains rely on regional distributors for smaller volume fulfillment and storage logistics.
- Online Sales:Technical and laboratory grade material moves through specialized chemical procurement platforms with certificate-of-analysis transparency.
- Retail:Limited to consumer-scale solvent applications with minimal EDC volume.
Direct sales holds the largest share; wholesale distribution serves the expanding mid-tier buyer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American EDC trade flows reflect deep integration between chlor-alkali producers and downstream PVC resin manufacturers, with cross-border supply chains linking Gulf Coast production to Mexican manufacturing demand and Canadian construction markets.
United States
Texas and Louisiana host the densest concentration of integrated EDC-PVC complexes along the Houston Ship Channel and Mississippi River corridor. EPA NESHAP revisions targeting 1,2-dichloroethane emissions are accelerating abatement investments at older chlor-alkali facilities. Westlake Chemical Corporation and Dow Inc. anchor production clusters in Lake Charles and Freeport, where captive ethylene supply secures cost positions.
Canada
Ontario and Alberta chemical corridors supply regional PVC compounders serving construction and automotive end-uses. Health Canada and Environment and Climate Change Canada coordinate chemical management under the Chemicals Management Plan, with EDC listed for priority assessment. Sarnia's petrochemical complex maintains membrane cell chlor-alkali capacity feeding provincial pipe and siding manufacturers.
Mexico
Nuevo León and the northern border states are expanding electronics assembly capacity that pulls specialty-grade EDC for laminate adhesive applications. SEMARNAT air quality standards govern chlor-alkali emissions in Monterrey's industrial zone. Maquiladora corridor growth near Tijuana and Ciudad Juárez is concentrating demand for ultra-purity material in printed circuit board manufacturing.
Gulf Coast Corridor
Louisiana's Mississippi River chemical complex consolidates procurement under master service agreements linking EDC producers to PVC resin manufacturers. OSHA Process Safety Management enforcement intensifies around reactive chemical hazards at chlor-alkali sites. Integrated producers leverage salt-to-resin chains to compress merchant market liquidity and lock in decade-long volume commitments.
North America Ethylene Dichloride (EDC) Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in feedstock and purification niches. The North America EDC market consolidates around integrated chlor-alkali-PVC chains, with three major producers controlling diaphragm and membrane cell capacity. Strategic archetypes include salt-to-resin integrators, merchant chlorine suppliers, and specialty-grade purifiers. Competitive moves center on long-term offtake contracting and membrane technology upgrades.
Among integrated chemical producers, Formosa Plastics Corporation, Olin Corporation, and Westlake Chemical Corporation exemplify the dominant archetype of backward-integrated operators controlling feedstock from salt through finished resin. These entities occupy positions defined by captive ethylene supply and long-term supply agreements rather than spot market participation. Their scale and integration depth represent the structural barrier to entry for merchant market challengers.
| Leading Market Players |
|---|
| Formosa Plastics Corporation |
| Chevron Phillips Chemical |
| Olin Corporation |
| Dow Inc. |
| Shell Chemical |
| Westlake Chemical Corporation |
| INEOS Group |
| Shintech Inc. |
| Occidental Petroleum Corporation |
| Others |
Cost & Logistics Intelligence
US Gulf Coast ethylene supply concentration around Houston Ship Channel crackers and Louisiana chlor-alkali complexes funnels margin capture toward integrated producers with captive feedstock access, compressing pricing power for merchant market participants dependent on spot ethylene and third-party chlorine offtake.
Pricing Analysis
Industrial OEM buyers anchor contract pricing through decade-long offtake agreements with volume floors and price collars that insulate integrated producers from ethylene spot volatility. Price differentiation rests on purity grade and captive supply chain depth, with specialty-grade material commanding specification premiums for Mexico electronics applications. Pricing pressure stems from ethylene cost transmission and caustic soda co-production economics, squeezing merchant producer margins. Non-integrated PVC compounders exhibit highest price sensitivity due to feedstock security anxiety, while electronics manufacturers prioritize qualification stability over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China for catalyst and membrane cell components creates procurement vulnerability for chlor-alkali technology upgrades. Geographic supply concentrates in the United States, Canada, and Mexico, with raw material dependencies spanning Gulf Coast ethylene, Rocky Mountain salt, and imported ion-exchange membranes. Single-source vulnerability sits with specialized membrane suppliers for high-purity EDC trains. Distribution runs through direct sales channels for integrated PVC resin manufacturers and wholesale networks for fragmented compounders lacking captive chlorine capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized process safety engineering expertise commands premium compensation in the Houston Ship Channel labor market, creating a capability gap that constrains operational expansion for producers without established technical depth or consulting relationships.
For Market Incumbents: Entrench competitive position through membrane cell technology upgrades that lock in EPA NESHAP compliance ahead of regulatory enforcement waves, while securing long-term ethylene supply agreements that neutralize merchant market price volatility. Expand captive salt-to-resin integration into Mexico's maquiladora corridor to capture specialty-grade demand growth before qualification barriers solidify. For New Entrants and Emerging Players: Establish a beachhead in electronics-grade specialty EDC by partnering with membrane technology licensors to achieve single-digit ppm impurity certification, bypassing the capital intensity of integrated chlor-alkali construction. Target Mexico's northern border states where nearshoring demand outruns qualified supplier capacity, leveraging technical service intensity as differentiation against commodity-focused incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale membrane cell operators with latent capacity for specialty-grade purification retrofits and established EPA compliance records that reduce regulatory execution risk. The inflection signal to monitor is EPA NESHAP final rule publication, which will trigger forced consolidation among legacy diaphragm cell operators unable to fund abatement investments.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Technology Upgrade | EPA NESHAP compliance investments protect operating licenses at Gulf Coast chlor-alkali facilities. |
| Backward Integration into Salt Supply | Captive brine access insulates margin from merchant chlorine market concentration. |
| Specialty-Grade Purification Train Expansion | Single-digit ppm capability opens Mexico electronics laminate adhesive applications. |
| Long-Term Ethylene Supply Agreement | Volume floors with Gulf Coast crackers neutralize olefin price volatility transmission. |
| Carbon Capture Retrofit Integration | IRA 45Q tax credit eligibility reduces net cost of post-combustion EDC cracker modifications. |
Research Approach
Initial hypotheses were tested against primary input from chlor-alkali plant managers, PVC resin procurement directors, electronics manufacturing engineers, and specialty chemical distributors and refined through secondary validation against EPA enforcement databases, OSHA incident reports, SEC 10-K filings, and American Chemistry Council trade statistics. Bottom-up volume estimates from individual facility capacities were triangulated against top-down demand calculations from PVC resin production and electronics assembly activity.
Demand-supply balance modeling across the analysis window incorporated grade tier, end-use industry, regional production hub, and captive versus merchant supply chain configuration as segmentation dimensions. CAGRs were derived from trend extrapolation of ethylene feedstock cost trajectories, regulatory investment cycles, and construction sector PVC consumption patterns, with cross-checks against chlor-alkali capacity utilization rates and membrane cell technology diffusion curves.
Stress conditions across ethylene price volatility bands, EPA NESHAP enforcement timing scenarios, and Mexico electronics demand growth rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation schedules and feedstock cost transmission mechanisms. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Isopropyl Alcohol (IPA) Market
Chemicals
Inorganic Chemicals Market
Chemicals
Amine Oxide Market
Chemicals
Allyl Alcohol Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market
Chemicals
Detergent Alcohols Market
Chemicals
Barbituric Acid Market
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals
Global Cresols Market
Chemicals
Thioacetic Acid Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
Carbon Tetrachloride Market