
 Global Medical Membranes Market | 2026-2036
Global Medical Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Membranes Market Foresight
Modular filtration cartridge design is consolidating buyer preference across hospital procurement departments. Sartorius AG leverages its captive polymer synthesis capabilities to control raw material specifications for biopharmaceutical clients. Merck KGaA sustains dominant positioning in ultrafiltration cassettes through decades of process validation partnerships with European plasma fractionators. Asahi Kasei Corporation anchors its competitive stance via hollow fiber membrane specialization for dialysis device OEMs.
Medical membranes are semipermeable barriers engineered from synthetic polymers such as polyethersulfone and polyvinylidene fluoride, typically manufactured through phase inversion or track-etching processes to achieve precise pore size distributions between 0.01 and 10 micrometers for selective separation of biological fluids and therapeutic compounds. Polyethersulfone formulations command premium positioning in dialysis applications due to superior hydraulic permeability and reduced protein adsorption versus cellulose-derived alternatives. The drug delivery segment exhibits accelerated development of implantable osmotic pumps requiring asymmetric membrane laminates with tunable diffusion coefficients. Hospitals represent the most contested end-user channel, with group purchasing organizations extracting volume commitments that compress margins for standard filtration products.
The FDA enforces biocompatibility standards under ISO 10993 guidelines that mandate exhaustive cytotoxicity and hemocompatibility testing before commercial membrane deployment in blood-contacting devices. The EMA's Medical Device Regulation requires European manufacturers to maintain technical documentation demonstrating traceable polymer supply chains and validated sterilization protocols for implantable membrane systems. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance restrictions that threaten continued production of certain fluoropolymer membranes unless alternative chemistries achieve equivalent performance thresholds.
Market Dynamics
Modular filtration cartridge design is consolidating procurement power within hospital group purchasing organizations, compressing margins for standardized membrane products while rewarding suppliers with captive polymer synthesis capabilities.
Growth Catalysts
- Chronic kidney disease prevalence:Dialysis centers in Germany, Japan, and the United States are expanding membrane procurement volumes to serve aging patient populations requiring hemodialysis three times weekly.
- FDA biocompatibility acceleration:Updated ISO 10993 validation protocols are compressing approval timelines for new polyethersulfone formulations entering blood-contacting device applications.
- Implantable osmotic pump development:Asymmetric membrane laminates with tunable diffusion coefficients are enabling next-generation drug delivery systems for chronic condition management.
Market Restraints
- Fluoropolymer regulatory threat:EPA per- and polyfluoroalkyl substance restrictions threaten continued production of polyvinylidene fluoride membranes unless alternative chemistries achieve equivalent performance thresholds.
- Raw material concentration:Polyethersulfone resin supply concentrates among a limited cohort of European and Asian chemical manufacturers, exposing membrane fabricators to input cost volatility.
- Protein adsorption limitations:Cellulose-derived alternatives retain inferior hydraulic permeability versus synthetic polymers, constraining their deployment in high-flux dialysis applications despite lower material costs.
Strategic Opportunities
- Indian contract manufacturing expansion:CDSCO regulatory harmonization with ISO 13485 standards is attracting membrane module assembly for export to European and Middle Eastern markets.
- Point-of-care filtration devices:Miniaturized hollow fiber systems for emergency medicine and military field hospitals represent underpenetrated demand outside traditional dialysis center channels.
- EU Medical Device Regulation technical documentation:MDR traceability mandates for implantable membrane systems create service revenue streams for validated sterilization protocol consulting.
Industry Challenges
- Phase inversion process engineering talent:Specialized expertise in track-etching and controlled pore formation commands premium compensation, constraining capacity expansion at mid-scale membrane fabricators.
- Multi-jurisdiction certification complexity:Simultaneous FDA 510(k) clearance and CE marking under MDR Article 10 technical documentation requirements extend commercialization timelines by 18-24 months for novel polymer formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Membranes Market |
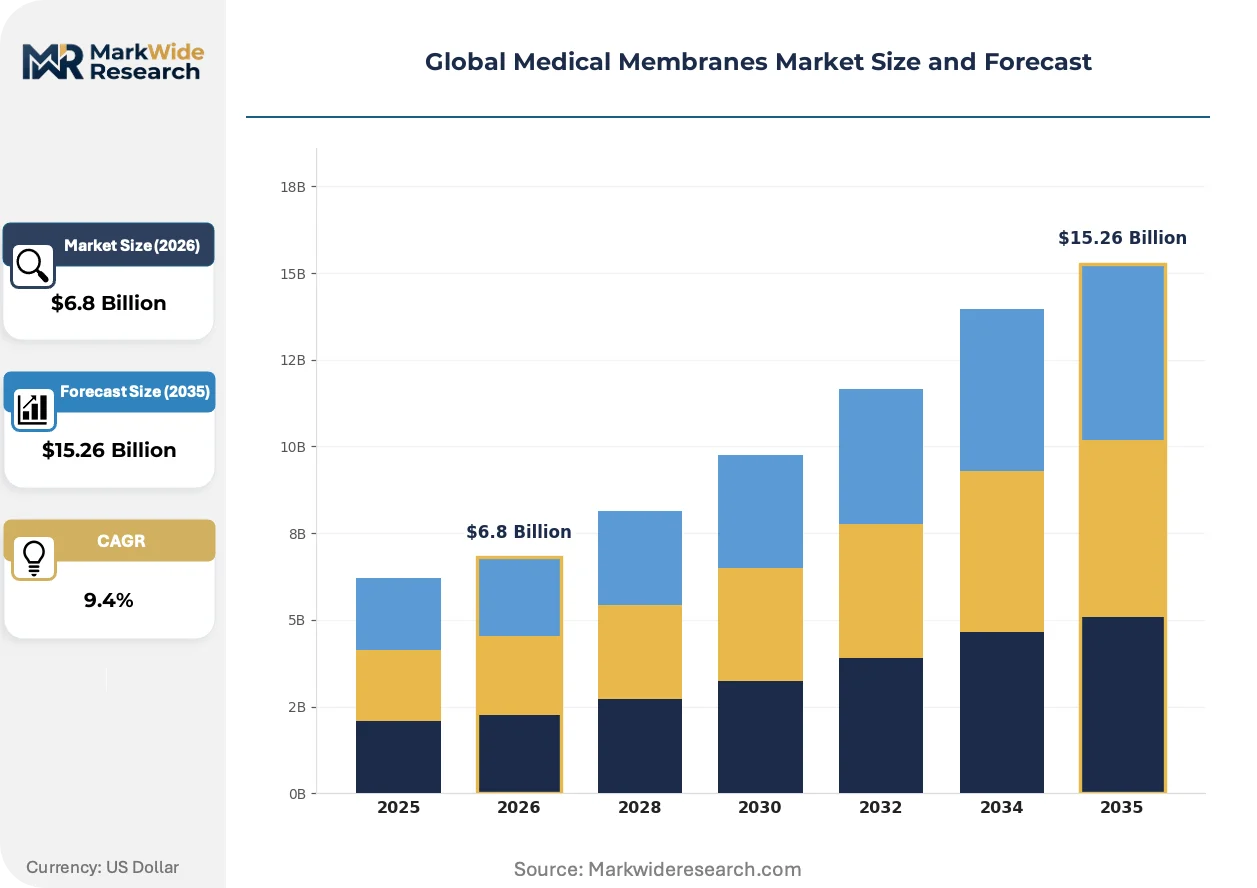
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethersulfone, Cellulose Acetate, Polysulfone, Polyvinylidene Fluoride, Polyamide Application: Dialysis, Blood Oxygenation, Drug Delivery, Tissue Engineering, Filtration End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutes, Outpatient Care Centers Delivery Mode: Sterile, Non-Sterile, Ready-to-Use, Bulk Packaging, Custom Fabricated |
| Companies Covered | Sartorius AG, Merck KGaA, Mann+Hummel, Asahi Kasei Corporation, 3M, Pall Corporation, Koch Membrane Systems Inc., W. L. Gore & Associates, Inc., Cytiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Membranes Market Shifts & Advancements
Surface modification chemistries and additive manufacturing are converging to produce patient-specific membrane geometries, while regulatory data harmonization initiatives are compressing validation redundancy across major markets.
Track-etched polycarbonate membranes with precisely controlled cylindrical pores are rewriting separation performance benchmarks in diagnostic device applications. IVD manufacturers in Switzerland and Massachusetts are qualifying these materials for nucleic acid isolation workflows. The technology is rewriting competitive positioning by enabling membrane suppliers to capture value previously retained by finished device OEMs.
EMA's Medical Device Regulation Annex I general safety and performance requirements now mandate clinical evidence for Class III implantable membrane systems, extending from the prior Medical Device Directive's reliance on equivalence arguments. European plasma fractionators are responding by deepening process validation partnerships with established ultrafiltration cassette suppliers rather than qualifying new entrants. German university hospitals are accelerating clinical investigation site approvals to generate the required performance data.
Hospital procurement departments are consolidating membrane purchases through integrated delivery networks that negotiate multi-year sole-source agreements for standardized filtration cartridges. Group purchasing organizations in the United States are extracting volume commitments that compress margins for commodity dialyzer products. This concentration is most visible in the southeastern United States, where health system mergers have reduced the number of independent purchasing entities by over one-third since 2020.
Global Medical Membranes Market Segmentation
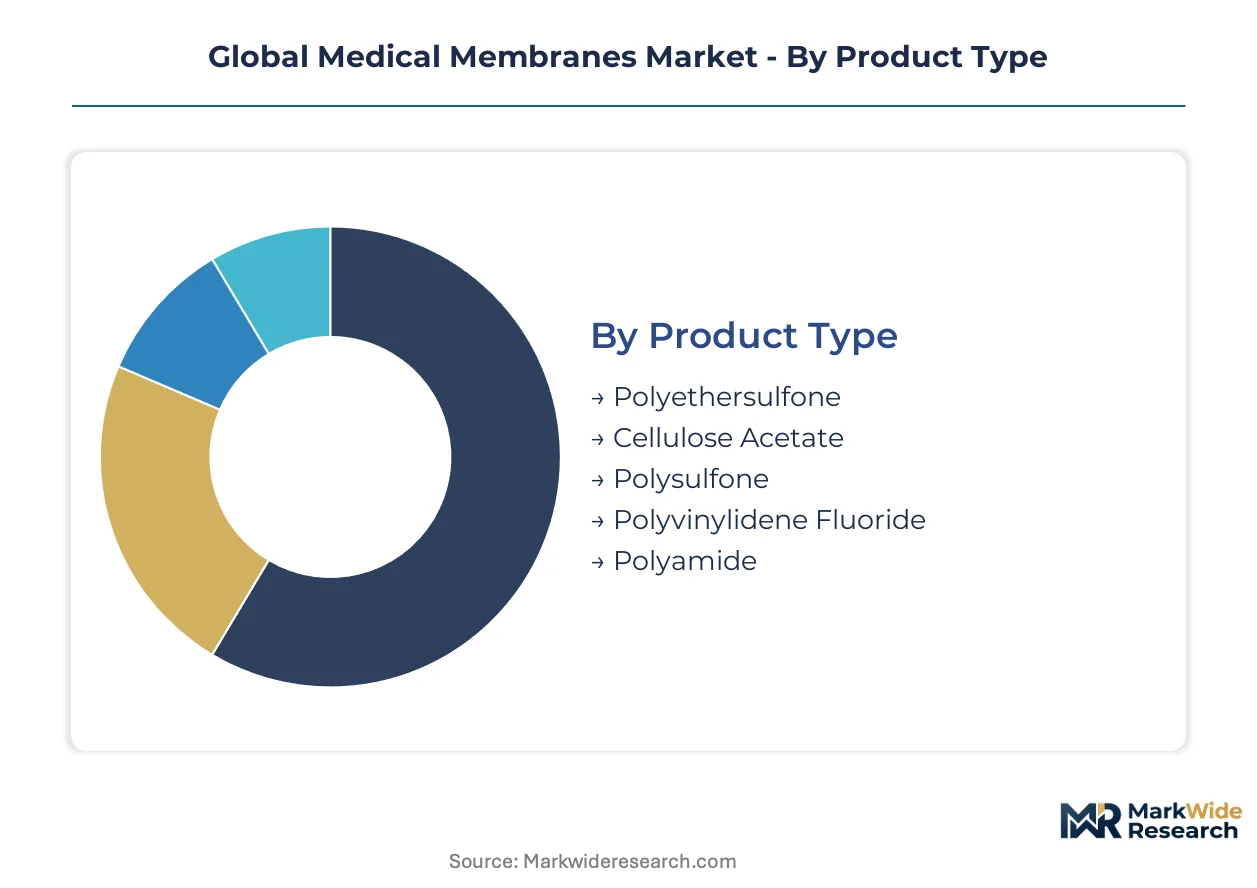
Medical membrane segmentation reveals divergent capital requirements across polymer chemistries and sterilization workflows. Procurement patterns in Germany and Japan demonstrate how end-user concentration reshapes supplier priorities across each category.
Product Type:
Capital intensity peaks with fluoropolymer synthesis infrastructure and captive resin production capabilities.
- Polyethersulfone:Hydrophilic surface chemistry with superior hydraulic permeability and reduced protein adsorption profiles commands premium positioning in high-flux dialysis applications. German university hospitals and Japanese dialysis centers concentrate procurement for chronic kidney disease protocols requiring three weekly treatments.
- Cellulose Acetate:Lower material costs and established manufacturing heritage persist in cost-sensitive markets despite inferior permeability versus synthetic alternatives. Demand concentrates in Indian contract manufacturing facilities serving Middle Eastern export markets under CDSCO harmonization frameworks.
- Polysulfone:Thermal stability and broad pH tolerance support multi-purpose filtration platforms across biopharmaceutical processing.
- Polyvinylidene Fluoride:Chemical resistance specifications face EPA per- and polyfluoroalkyl substance regulatory pressure threatening continued production unless alternative chemistries achieve equivalent performance thresholds.
- Polyamide:Thin-film composite structures dominate diagnostic device applications requiring precise molecular weight cutoffs.
Most installed capacity flows through Polyethersulfone. Expansion is steepest in Polysulfone as biopharmaceutical process validation partnerships deepen.
Application:
Revenue concentration correlates with procedure frequency and reimbursement stability across therapeutic modalities.
- Dialysis:Hemodialysis membranes face procurement consolidation through United States group purchasing organizations extracting volume commitments that compress margins for standardized dialyzer products. German dialysis centers anchor European demand alongside Japanese and American facilities serving aging patient populations.
- Drug Delivery:Implantable osmotic pumps require asymmetric membrane laminates with tunable diffusion coefficients enabling chronic condition management through controlled therapeutic release.
- Blood Oxygenation:Hollow fiber configurations in extracorporeal membrane oxygenation systems demand validated sterilization protocols under FDA and EMA biocompatibility frameworks.
- Tissue Engineering:Scaffold applications prioritize pore interconnectivity and degradation profiles matched to cellular infiltration timelines.
- Filtration:Modular cartridge designs consolidate hospital procurement power across integrated delivery networks in the southeastern United States.
Procedure volume concentrates in Dialysis. Technology development investment flows most heavily into Drug Delivery.
End User:
Customer scale determines contract structure complexity and technical service bundling requirements.
- Hospitals:Integrated delivery networks negotiate multi-year sole-source agreements for standardized filtration cartridges, compressing supplier margins while rewarding scale economies. Health system mergers in the southeastern United States reduced independent purchasing entities by over one-third.
- Diagnostic Laboratories:Track-etched polycarbonate membranes with precisely controlled cylindrical pores enable nucleic acid isolation workflows for IVD manufacturers in Switzerland and Massachusetts.
- Clinics:Outpatient dialysis facilities prioritize cost efficiency over performance optimization in membrane selection criteria.
- Research Institutes:Custom specifications and small-batch flexibility command premium pricing from academic medical centers.
- Outpatient Care Centers:Point-of-care filtration devices for emergency medicine represent underpenetrated demand outside traditional hospital channels.
Contract value concentrates in Hospitals. Site expansion is accelerating fastest in Outpatient Care Centers.
Delivery Mode:
Regulatory validation burden and sterilization infrastructure requirements segment supplier capabilities.
- Sterile:Gamma irradiation and ethylene oxide validation protocols extend commercialization timelines by 18-24 months for novel polymer formulations requiring simultaneous FDA 510(k) clearance and CE marking under MDR Article 10 technical documentation requirements.
- Ready-to-Use:Pre-assembled cartridge formats reduce hospital pharmacy compounding labor and contamination risk in critical care settings.
- Non-Sterile:Bulk membrane rolls serve research and process development applications with downstream sterilization responsibility transferred to end users.
- Bulk Packaging:Volume discounts attract large-scale biopharmaceutical manufacturers with captive sterilization capacity.
- Custom Fabricated:Patient-specific membrane geometries through additive manufacturing command premium positioning in specialized therapeutic applications.
Validation investment concentrates in Sterile. Format innovation is progressing most rapidly in Ready-to-Use configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The medical membrane industry traces its commercial origins to German polymer science laboratories in the 1960s, where phase inversion techniques for synthetic hollow fibers were first industrialized for dialysis applications. This technical heritage continues to shape geographic concentration patterns across membrane manufacturing and procurement.
Germany
Dialysis centers in Bavaria and Baden-Württemberg anchor European membrane procurement volumes for chronic kidney disease protocols. The EU Medical Device Regulation Annex I requirements mandate clinical evidence for Class III implantable systems, driving process validation partnerships between university hospitals in Heidelberg and established ultrafiltration suppliers. Frankfurt's dense network of contract research organizations accelerates biocompatibility testing timelines for new polymer formulations.
United States
Hospital group purchasing organizations in the southeastern states extract volume commitments that compress margins for standardized dialyzer products. FDA 510(k) clearance pathways under updated ISO 10993 protocols validate new polyethersulfone formulations for blood-contacting devices. Massachusetts and California host diagnostic device manufacturers qualifying track-etched polycarbonate membranes for nucleic acid isolation workflows.
Japan
Aging patient populations in Tokyo and Osaka drive hemodialysis membrane procurement three times weekly across outpatient facilities. METI industrial standards coordinate with PMDA biocompatibility frameworks for hollow fiber specialization in dialysis device supply chains. Nagoya's automotive polymer heritage has transferred technical talent into medical membrane process engineering.
India
CDSCO regulatory harmonization with ISO 13485 standards attracts membrane module assembly for export to European and Middle Eastern markets. Contract manufacturing facilities in Gujarat and Maharashtra serve cost-sensitive demand for cellulose-derived alternatives. Hyderabad's pharmaceutical services cluster supports sterilization protocol consulting for MDR technical documentation compliance.
Switzerland
Swissmedic oversight of implantable membrane systems reinforces technical documentation requirements for traceable polymer supply chains. Basel's biopharmaceutical concentration sustains demand for ultrafiltration cassettes in plasma fractionation processes. Zurich-based diagnostic manufacturers qualify precision track-etched membranes for IVD applications.
Global Medical Membranes Market Competitive Landscape
The competitive structure tilts toward integrated polymer specialists with captive resin production capabilities. Mid-scale fabricators face talent constraints in phase inversion process engineering while hospital procurement consolidation rewards suppliers with validated sterilization infrastructure. Two archetypes dominate: diversified life science conglomerates with decades of regulatory validation partnerships, and focused membrane specialists leveraging hollow fiber or track-etching specialization. Capacity expansion and strategic partnerships represent the primary competitive vectors as multi-jurisdiction certification requirements extend commercialization timelines.
Among German-headquartered diversified players, Sartorius AG and Merck KGaA occupy positions exemplifying the conglomerate archetype with extensive European regulatory validation heritage. Asahi Kasei Corporation represents the specialization vector, with its corporate name indicating Japanese origin and hollow fiber membrane concentration. These three entities anchor the competitive landscape across distinct strategic positions without overlapping core technical specializations.
| Leading Market Players |
|---|
| Sartorius AG |
| Merck KGaA |
| Mann+Hummel |
| Asahi Kasei Corporation |
| 3M |
| Pall Corporation |
| Koch Membrane Systems Inc. |
| W. L. Gore & Associates, Inc. |
| Cytiva |
| Others |
Supply & Pricing Matrix
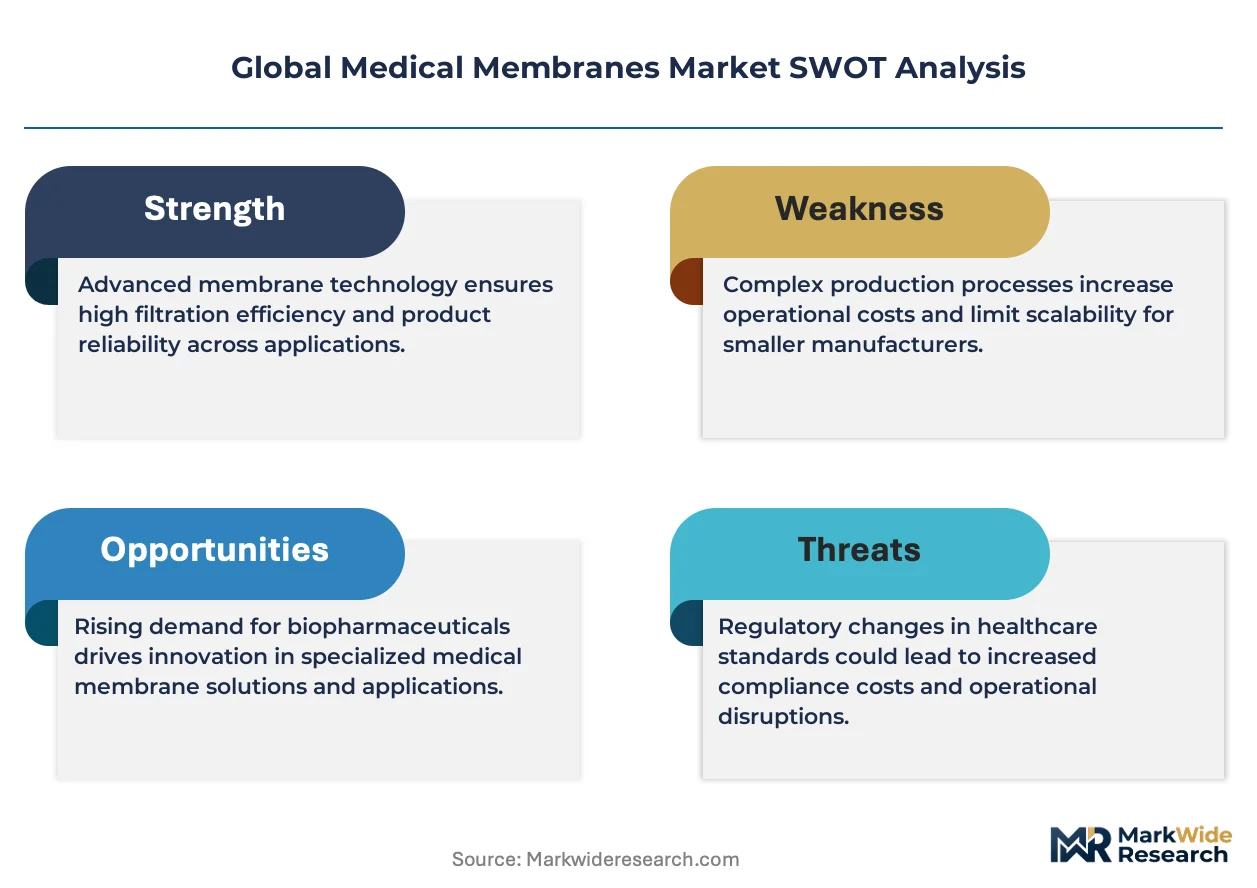
Phase inversion process engineering specialization simultaneously elevates production cost structures and consolidates supply power among German and Japanese membrane fabricators with captive polymer synthesis capabilities. This technical gating mechanism allows qualified suppliers to extract premium positioning while hospital group purchasing organizations compress margins for standardized dialyzer products.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates polyethersulfone formulations validated under FDA ISO 10993 protocols from cellulose-derived alternatives and unvalidated commodity membranes. Price differentiation hinges on biocompatibility certification tier and volume commitment scale within integrated delivery networks. Cost compression in economy-tier dialyzers is intensifying because southeastern United States health system mergers consolidated purchasing entities by over one-third since 2020. Outpatient dialysis clinics exhibit highest price sensitivity, while German university hospitals prioritize performance optimization over unit cost.
Supply Chain Analysis
CE marking under MDR Article 10 and FDA 510(k) clearance requirements gate supplier participation, extending commercialization timelines by 18-24 months for novel polymer formulations. Polyethersulfone resin production concentrates in Germany, Japan, and South Korea, exposing membrane fabricators to input cost volatility from limited chemical manufacturer cohorts. Raw material supply draws from specialty polymer synthesis, hollow fiber spinning equipment, and gamma irradiation sterilization infrastructure. Single-source vulnerability threatens continuity for fluoropolymer membranes facing EPA per- and polyfluoroalkyl substance restrictions. Distribution runs through hospital group purchasing organizations and biopharmaceutical process validation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in medical membranes rests on captive polymer synthesis capabilities that insulate qualified suppliers from raw material volatility while enabling premium-tier positioning in high-flux dialysis applications.
For Market Incumbents: Deepen process validation partnerships with European plasma fractionators to defend against track-etched polycarbonate membrane specialists rewriting competitive positioning in diagnostic applications. Expand captive polyethersulfone resin production capacity in Germany to reduce exposure to Asian chemical manufacturer supply concentration. Investment in simultaneous FDA and EMA certification infrastructure compresses commercialization timelines for new entrants. For New Entrants and Emerging Players: Additive manufacturing-enabled patient-specific membrane geometries offer white-space penetration in tissue engineering scaffolds and implantable osmotic pump laminates underserved by standardized hollow fiber suppliers. Point-of-care filtration devices for emergency medicine and military field hospitals represent underpenetrated demand outside traditional dialysis center channels. Qualification under CDSCO harmonization frameworks enables contract manufacturing assembly for export to Middle Eastern markets as a capital-efficient entry path. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale membrane fabricators lacking validated sterilization infrastructure but possessing specialized phase inversion engineering talent. Long-term viability across the analysis window favors targets with backward integration into polymer synthesis and established MDR technical documentation capabilities. The signal to watch is EPA regulatory finalization on fluoropolymer restrictions, which would trigger replacement chemistry investment cycles and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | CE marking pathway for Class III implantable systems deepens process validation partnerships with German university hospitals. |
| Captive Polymer Synthesis Expansion | Backward integration into polyethersulfone resin production insulates margin compression from raw material volatility. |
| Track-Etching Specialization | Precision polycarbonate membranes capture value previously retained by IVD manufacturers in nucleic acid isolation workflows. |
| Point-of-Care Device Development | Miniaturized hollow fiber systems penetrate emergency medicine and military field hospital channels outside dialysis centers. |
| Indian Contract Manufacturing Scale-Up | CDSCO harmonization with ISO 13485 standards attracts module assembly for European and Middle Eastern export markets. |
Research Methodology
Multiple input streams — primary interviews with membrane fabrication executives, biomedical engineers at German university hospitals, and group purchasing organization contracts managers — were reconciled against FDA 510(k) clearance databases, EMA MDR technical documentation filings, and hospital procurement contract records. Secondary validation drew from SEC filings of diversified life science conglomerates, customs data on polyethersulfone resin trade flows, and ISO 10993 biocompatibility testing registries. Bottom-up membrane unit demand estimates and top-down therapeutic procedure frequency data were triangulated to constrain forecast variance.
Historical volume trajectories in dialysis, drug delivery, and diagnostic applications were cross-referenced against expert panel inputs on regulatory approval timelines and polymer formulation development cycles. Segmentation dimensions modeled encompass polymer chemistry tier, application modality, end-user scale, and sterilization validation burden across the projection horizon. CAGRs were derived from procedure volume growth in chronic kidney disease protocols, implantable device adoption curves, and biopharmaceutical processing capacity expansion. Forecast inputs incorporated EPA regulatory scenario analysis for fluoropolymer restrictions and CDSCO harmonization progress in Indian contract manufacturing.
The model holds under stable ISO 10993 and MDR regulatory frameworks; deviation in EPA per- and polyfluoroalkyl substance enforcement timelines or raw material supply disruptions would shift capacity expansion assumptions and pricing trajectories. A model refresh is warranted upon material change in biocompatibility validation protocol harmonization across FDA, EMA, and PMDA jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Geomembrane Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
North America Single-Ply Membrane Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
Membrane Separation Market
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Membranes Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Global Membrane Structures Market
Membrane Materials
Global Chemical Separation Membranes Market
Membrane Materials
Microporous Materials Market
Membrane Materials
North America Transparent Conductive Films Market
Membrane Materials
US Commercial Restoration Waterproofing Membranes Market
Membrane Materials
Global Membrane Separation Technology Market