
 Barbituric Acid Market | 2026-2036
Barbituric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Barbituric Acid Market Analysis
Multi-source procurement among active pharmaceutical ingredient buyers is broadening as formulators reduce dependency on single-origin barbituric acid supply. Hebei Chengxin Co., Ltd. anchors northern China's production corridor with integrated malonic acid feedstock access. Zhengzhou Lifeng Chemical Co., Ltd. leverages Henan province's logistics hub status to serve domestic distributors and export channels. Hunan HongQiang Chem Technology Development Co., Ltd. competes on specialized high-purity grades for European contract manufacturers.
Barbituric acid, chemically 2,4,6-pyrimidinetrione, is synthesized through the condensation of malonic acid with urea in the presence of phosphorus oxychloride or sodium ethoxide, yielding a white crystalline powder with melting point near 245°C decomposition. This heterocyclic compound serves as the foundational scaffold for barbiturate drugs, dyes, and polymer crosslinking agents across pharmaceutical and materials science applications. The Intermediates segment dominates volume throughput as bulk synthesizers feed downstream barbiturate manufacturing, while the Laboratory Chemicals category captures premium pricing through certified reference standards and chromatography-grade specifications. Pharmaceutical Companies represent the most concentrated end-user pool, though Academic Institutions are expanding demand for barbituric acid derivatives in coordination chemistry and supramolecular research.
FDA oversight of controlled substance precursors and ECHA REACH registration requirements for malonic acid derivatives jointly elevate documentation burdens for cross-border shipments. China's NMPA and SAMR enforce Good Manufacturing Practice standards for pharmaceutical intermediates that barbituric acid producers must satisfy to supply domestic drug developers. India's CDSCO and BIS certification protocols similarly constrain informal manufacturers while rewarding established exporters like Ralington Pharma LLP with validated supply agreements. Stakeholders must monitor evolving scheduling classifications for barbiturate precursors in major import jurisdictions to anticipate supply chain disruption risks and compliance cost shifts.
Market Dynamics
REACH registration deadlines for malonic acid derivatives are compressing supplier qualification timelines across European pharmaceutical value chains, forcing intermediate producers to accelerate purity documentation or exit the market entirely.
Growth Catalysts
- Barbiturate API Resurgence:FDA scheduling reviews for certain sedative-hypnotics are reopening therapeutic niches previously abandoned, renewing synthesis demand for high-grade barbituric acid scaffolds in US contract manufacturing.
- China's Dual Carbon Targets:MEE enforcement of carbon intensity benchmarks is pushing Hebei and Shandong bulk chemical clusters toward cleaner malonic acid condensation processes, reducing export disqualification risk for compliant producers.
- Supramolecular Research Expansion:Academic coordination chemistry programs in Germany and Switzerland are procuring certified reference standards for metal-organic framework studies, creating premium-priced laboratory chemical demand outside traditional pharmaceutical channels.
Market Restraints
- Phosphorus Oxychloride Cost Volatility:Mining disruptions in Moroccan phosphate supply and energy-intensive Chinese production are amplifying input cost swings for condensation reagents, squeezing margin structures for non-integrated synthesizers.
- Single-Origin Malonic Acid Dependency:Northern China's concentration of feedstock capacity exposes downstream barbituric acid producers to concentrated logistics disruption during provincial environmental inspection campaigns.
- Substitution by Non-Barbiturate Sedatives:Z-drugs and melatonin receptor agonists are displacing barbiturate prescriptions in insomnia therapy, eroding volume pull from the largest historical end-use segment.
Strategic Opportunities
- Indian CDSCO Export Pathway:BIS-certified producers in Gujarat and Maharashtra can leverage India's pharmaceutical manufacturing hub status to supply validated intermediates for European generic drug developers seeking dual-source qualification.
- Polymer Crosslinking Applications:UV-curable coating formulators are testing barbituric acid derivatives as radical photoinitiators, opening industrial chemical demand channels with less stringent precursor documentation than pharmaceutical grades.
- EU Green Deal Chemicals Strategy:REACH simplification proposals for low-volume specialty intermediates may reduce registration cost burdens for laboratory-grade producers serving academic research markets.
Industry Challenges
- Analytical Methodology Talent Scarcity:Chromatography and spectroscopy specialists capable of validating sub-ppm impurity profiles for ECHA dossiers command premium compensation, constraining smaller producers' compliance capacity.
- Legacy Equipment Retrofit Requirements:Batch reactor installations predating China's 2015 environmental law revisions require substantial capital expenditure to meet SAMR Good Manufacturing Practice standards for pharmaceutical intermediate classification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barbituric Acid Market |
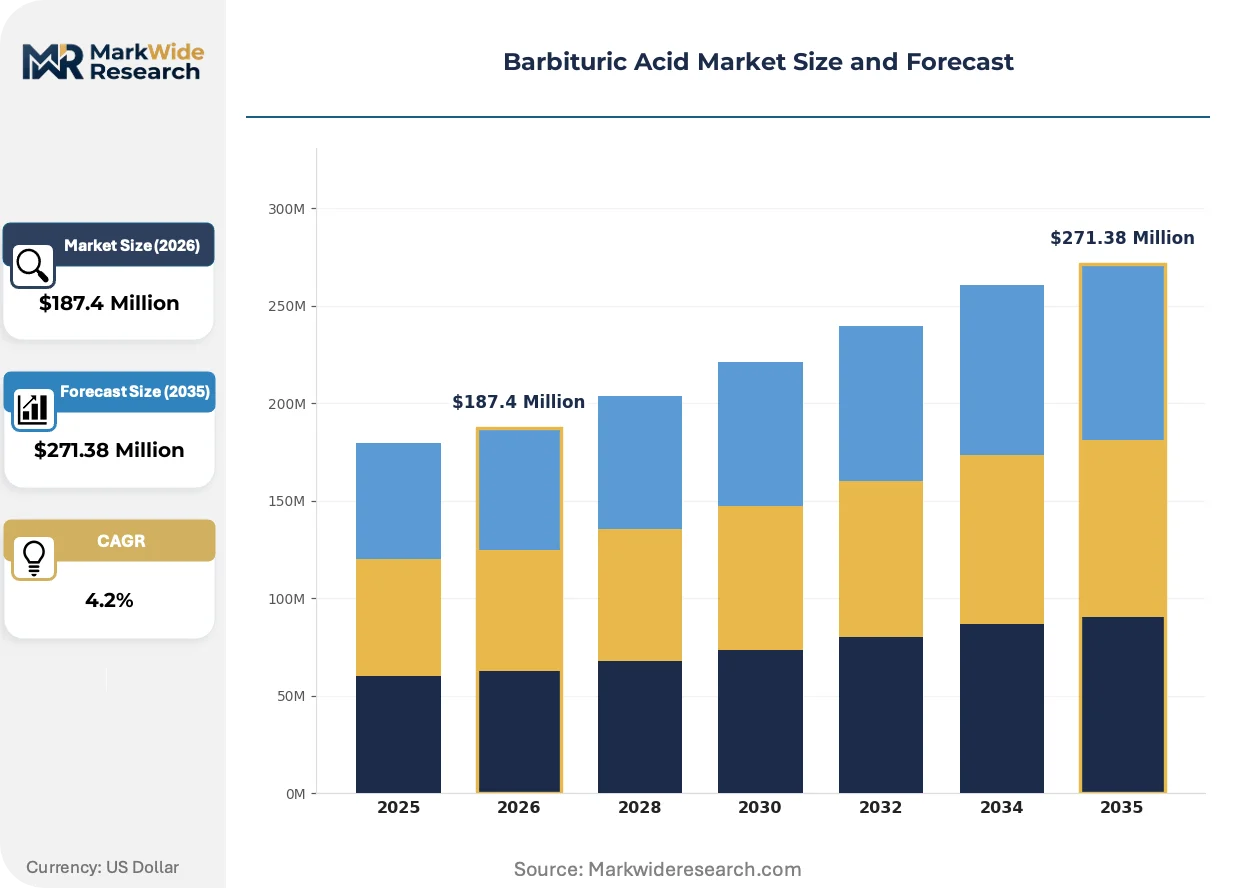
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
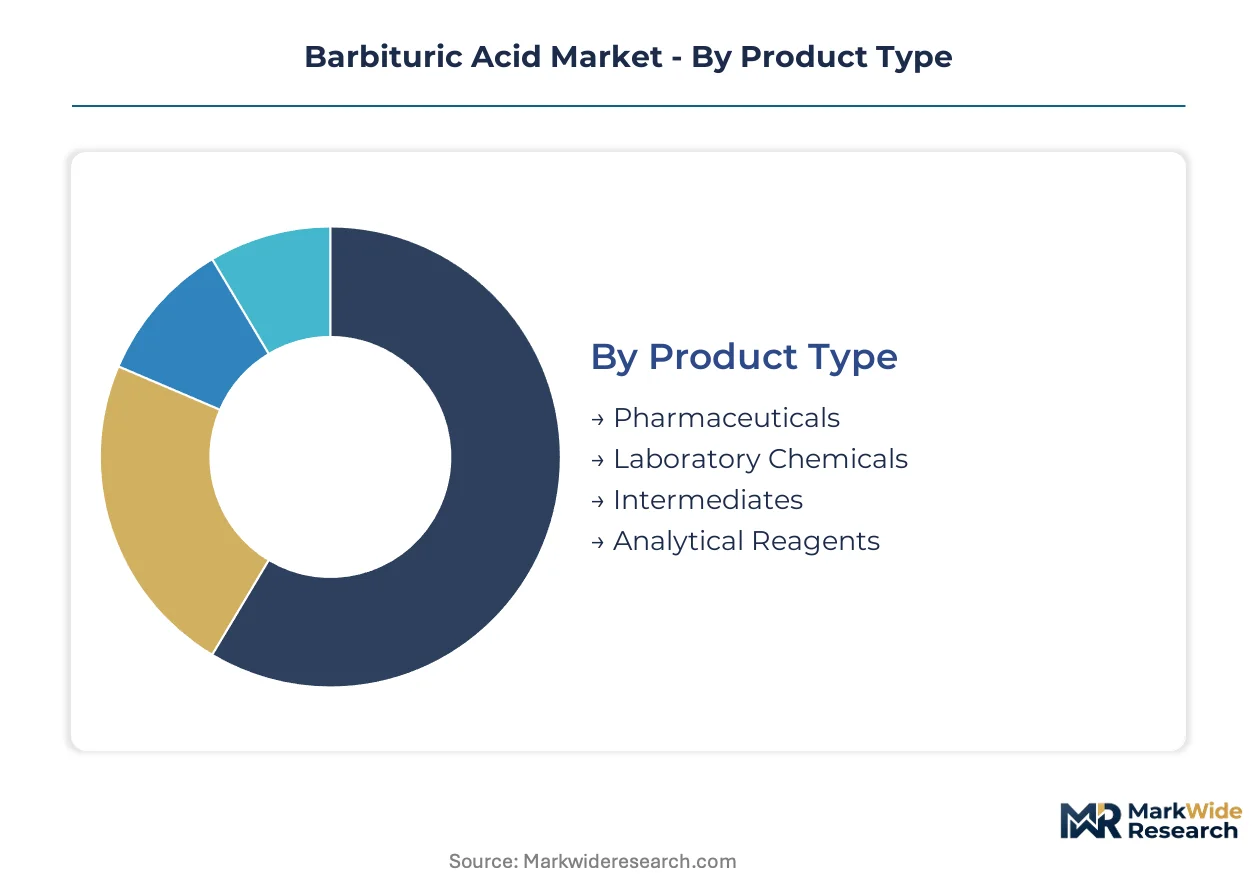
| Segmentation | Product Type: Pharmaceuticals, Laboratory Chemicals, Intermediates, Analytical Reagents End User: Pharmaceutical Companies, Research Laboratories, Academic Institutions, Manufacturers Application: Synthesis, Drug Development, Analytical Testing, Chemical Research Sales Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Zhengzhou Lifeng Chemical Co., Ltd., Hebei Chengxin Co., Ltd., Ralington Pharma LLP, Explicit Chemicals Pvt Ltd, Danopharm Chemicals Pvt. Ltd., Central Drug House (P) Ltd, Hunan HongQiang Chem Technology Development Co., Ltd., Sparchem, Hem Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barbituric Acid Market Emerging Trajectories
Continuous flow chemistry adoption is rewriting synthesis economics for heterocyclic intermediates, compressing batch cycle times and enabling real-time impurity monitoring that static reactor configurations cannot match.
Microreactor platforms integrating in-line NMR spectroscopy are rewriting process development timelines for barbituric acid derivatives. Pharmaceutical contract manufacturers in Switzerland and the Netherlands are piloting these systems for high-potency API precursor synthesis. The technology is rewriting competitive differentiation around documentation granularity rather than scale economies alone.
ECHA's 2024 update to REACH guidance on monoconstituent substance identification is tightening analytical requirements for barbituric acid registration dossiers. German and French chemical distributors are demanding enhanced spectral characterization from Asian suppliers to maintain downstream compliance. Laboratory-grade producers serving European academic markets are absorbing the highest documentation cost inflation.
Multi-year offtake agreements are displacing spot market transactions among pharmaceutical API buyers seeking supply security. Contract manufacturers in India and Eastern Europe are locking in eighteen-to-twenty-four month pricing with Chinese intermediate producers. This pattern is most pronounced in sedative-hypnotic synthesis chains where FDA scheduling uncertainty amplifies inventory risk tolerance.
Barbituric Acid Market Segmentation
Barbituric acid's heterocyclic scaffold serves divergent purity requirements across pharmaceutical synthesis and materials science, forcing suppliers to maintain parallel production lines with distinct documentation burdens. Segmentation reveals how procurement patterns split between bulk intermediate buyers seeking cost efficiency and laboratory customers demanding certified reference standards.
Product Type:
Buyers in this category separate by validation depth — pharmaceutical manufacturers require GMP-compliant documentation while research users prioritize analytical certification over batch scale.
- Pharmaceuticals:USP-grade material with sub-ppm impurity profiles supports FDA-regulated barbiturate API synthesis. Demand concentrates among US contract manufacturers reviving sedative-hypnotic production lines after scheduling reviews. EMA batch certification requirements elevate European pricing premiums.
- Intermediates:Technical-grade bulk output feeds downstream barbiturate manufacturing without final dosage-form documentation. Chinese bulk synthesizers in Hebei and Shandong provinces dominate volume throughput through integrated malonic acid access. SAMR environmental inspections periodically constrain export availability.
- Laboratory Chemicals:Chromatography-grade specifications with COA traceability serve academic metal-organic framework research. German and Swiss coordination chemistry programs drive premium pricing.
- Analytical Reagents:Certified reference standards for HPLC and NMR validation support quality control laboratories. CDSCO-certified Indian producers are penetrating European distributor networks.
Intermediates leads volumes today; Laboratory Chemicals is gaining share fastest.
End User:
Customer scale determines procurement modality — large formulators negotiate multi-year offtake agreements while fragmented research buyers rely on distributor stocking.
- Pharmaceutical Companies:Integrated API manufacturers in India and Eastern Europe lock in eighteen-to-twenty-four month supply contracts with Chinese intermediate producers. FDA scheduling uncertainty amplifies inventory risk tolerance across sedative-hypnotic synthesis chains.
- Research Laboratories:Pharmaceutical development and forensic toxicology labs require consistent lot-to-lot reproducibility for method validation. REACH-registered European distributors capture this premium segment through enhanced spectral characterization.
- Academic Institutions:Coordination chemistry and supramolecular research programs in Germany and Switzerland procure certified reference standards outside traditional pharmaceutical channels. ECHA's 2024 REACH guidance updates inflate documentation costs for this customer pool.
- Manufacturers:Industrial chemical formulators test barbituric acid derivatives as UV-curable coating photoinitiators. Polymer crosslinking applications face less stringent precursor documentation than pharmaceutical grades.
Pharmaceutical Companies anchor procurement value; Academic Institutions are expanding most quickly.
Application:
Functional purpose dictates purity thresholds — synthesis applications tolerate technical grades while drug development demands validated starting materials.
- Synthesis:Condensation reactions producing barbiturate scaffolds for sedative-hypnotic APIs consume the largest intermediate volumes. Hebei Chengxin's integrated malonic acid feedstock supports cost-competitive bulk output.
- Drug Development:Preclinical and clinical-phase programs require GMP-documented starting materials with established supply chain security. FDA oversight of controlled substance precursors elevates qualification burdens.
- Analytical Testing:Forensic and quality control laboratories employ barbituric acid derivatives as internal standards and reagents. Chromatography-grade specifications command pricing multiples over technical grades.
- Chemical Research:Metal-organic framework and supramolecular studies exploit the pyrimidinetrione scaffold's coordination chemistry. Swiss and Dutch microreactor pilots serve this exploratory demand.
Synthesis dominates volume consumption; Chemical Research shows steepest expansion trajectory.
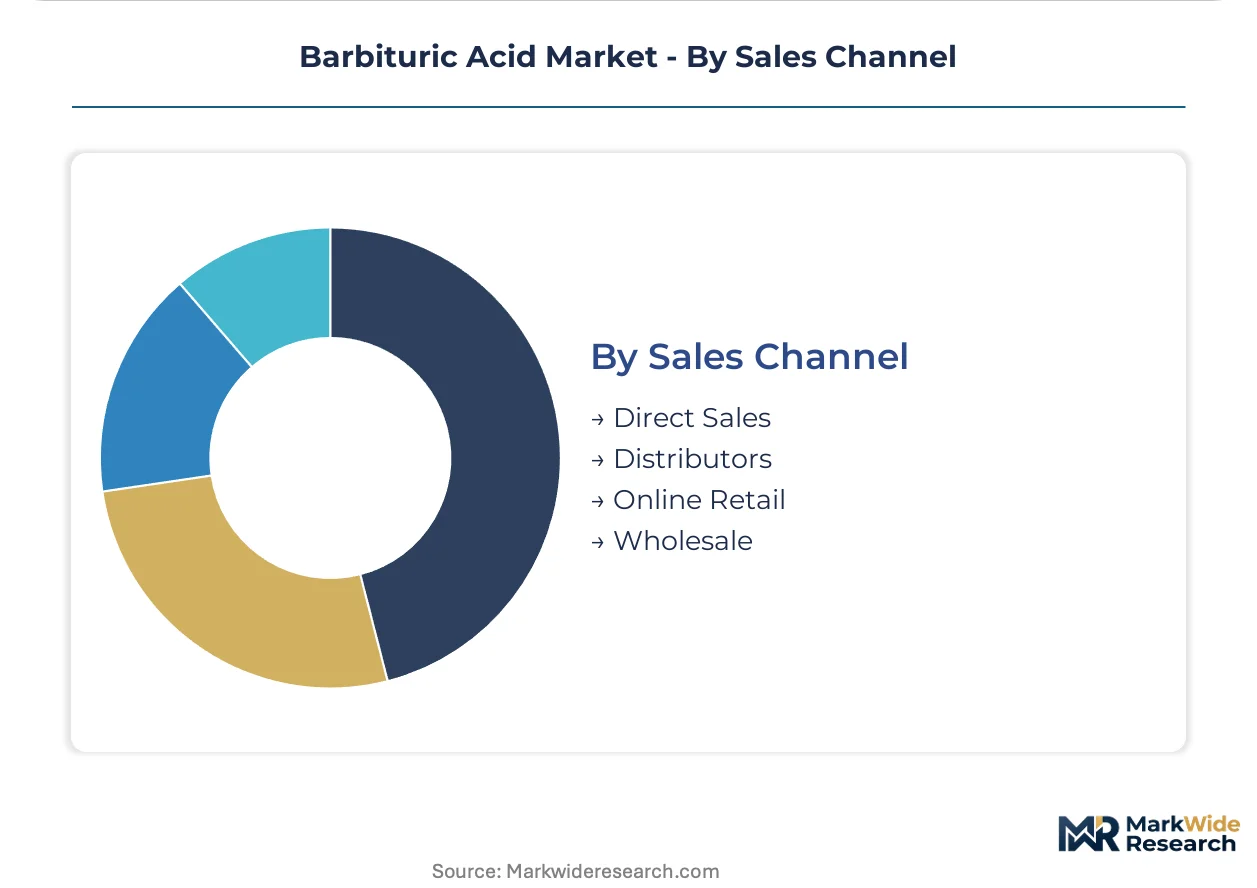
Sales Channel:
Channel selection reflects buyer sophistication — validated pharmaceutical procurement favors direct relationships while fragmented research demand flows through distributor networks.
- Direct Sales:Multi-year offtake agreements between API manufacturers and intermediate producers displace spot transactions. Contract manufacturers seek supply security amid regulatory uncertainty.
- Distributors:German and French chemical distributors aggregate Asian supply for European laboratory markets. ECHA REACH registration requirements force enhanced supplier qualification.
- Online Retail:Small-volume laboratory chemical procurement through specialized platforms serves academic researchers with intermittent demand patterns.
- Wholesale:Bulk intermediates move through regional chemical traders in India and China serving domestic generic drug developers.
Direct Sales captures the largest transaction value; Distributors are climbing the fastest as European laboratory demand fragments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hebei province's malonic acid corridor anchors barbituric acid manufacturing capacity, with northern China's chemical clusters supplying the majority of global intermediate volumes. Regulatory divergence across import jurisdictions is fragmenting procurement patterns as pharmaceutical buyers seek validated supply alternatives.
China
Hebei and Shandong provinces concentrate condensation reactor capacity serving both domestic API manufacturers and export channels. MEE enforcement of dual carbon intensity benchmarks is forcing environmental retrofits at legacy malonic acid facilities. Zhengzhou's logistics hub status enables Henan-based producers to reach European distributors through consolidated rail-sea corridors.
India
Gujarat and Maharashtra pharmaceutical clusters are absorbing CDSCO-certified intermediate volumes for generic barbiturate API synthesis. BIS certification protocols are constraining informal manufacturers while rewarding established exporters with validated European supply agreements. CDSCO's tightened GMP inspections for pharmaceutical intermediates are elevating documentation burdens for cross-border shipments.
United States
Contract manufacturers in New Jersey and North Carolina are reviving sedative-hypnotic production lines following FDA scheduling reviews for specific barbiturate therapies. FDA oversight of controlled substance precursors is elevating qualification timelines for imported barbituric acid scaffolds. Domestic buyers are locking in multi-year offtake agreements with Asian intermediate producers to mitigate supply security risks.
Germany
Rhineland chemical distributors are aggregating Asian intermediate supply for European pharmaceutical developers, absorbing ECHA REACH registration compliance costs. EMA batch certification requirements for GMP-documented starting materials are elevating pricing premiums for validated grades. Bavarian and Baden-Württemberg coordination chemistry programs are driving laboratory-grade demand for metal-organic framework research.
Switzerland
Swiss contract manufacturers in Basel and Zurich are piloting microreactor platforms for high-potency API precursor synthesis, creating premium demand for chromatography-grade barbituric acid derivatives. Swissmedic's stringent import documentation requirements are filtering out non-compliant Asian suppliers. Academic research institutions in Lausanne and Geneva are expanding procurement for supramolecular chemistry applications.
Barbituric Acid Market Vendor Landscape
Global majors compete with regional champions across documentation depth and feedstock integration. The vendor base separates into three tiers: bulk intermediate synthesizers with captive malonic acid supply, laboratory-grade specialists serving European research markets, and Indian exporters leveraging CDSCO certification for generic API channels. Capacity expansion and backward integration into condensation reagent production represent the dominant competitive moves as margin pressure intensifies.
Within the Chinese bulk synthesis tier, Hebei Chengxin Co., Ltd. and Zhengzhou Lifeng Chemical Co., Ltd. occupy positions anchored by northern China's malonic acid corridor infrastructure. Hunan HongQiang Chem Technology Development Co., Ltd. represents the laboratory-grade specialization archetype targeting European contract manufacturers with enhanced purity documentation. Ralington Pharma LLP exemplifies the Indian export pathway, leveraging CDSCO-validated supply agreements to serve European generic drug developers seeking dual-source qualification.
| Leading Market Players |
|---|
| Zhengzhou Lifeng Chemical Co., Ltd. |
| Hebei Chengxin Co., Ltd. |
| Ralington Pharma LLP |
| Explicit Chemicals Pvt Ltd |
| Danopharm Chemicals Pvt. Ltd. |
| Central Drug House (P) Ltd |
| Hunan HongQiang Chem Technology Development Co., Ltd. |
| Sparchem |
| Hem Corporation |
| Others |
Supply Flow & Price Mechanics
API manufacturers in India and Eastern Europe concentrate procurement through eighteen-to-twenty-four month offtake agreements, locking in contract-based long-term pricing that insulates against phosphorus oxychloride cost volatility while squeezing spot-market flexibility.
Pricing Analysis
Phosphorus oxychloride and malonic acid feedstock fluctuations pass through to barbituric acid quotations with a three-to-six month lag, compressing margins for non-integrated synthesizers. Pricing stratifies across pharmaceutical-grade, intermediate-grade, and laboratory-grade tiers, with EMA batch certification and REACH dossier depth as the primary differentiation drivers. Cost compression in technical-grade bulk output is intensifying because Hebei and Shandong producers absorb MEE environmental retrofit expenses. Generic API developers in Gujarat and Maharashtra exhibit the highest price sensitivity, while Swiss contract manufacturers pay premiums for chromatography-grade specifications with enhanced spectral characterization.
Supply Chain Analysis
Chromatography and spectroscopy specialists capable of validating sub-ppm impurity profiles command premium compensation across Hebei and Shandong chemical clusters, constraining smaller producers' compliance capacity and filtering supplier participation. Manufacturing concentrates in China, India, and Switzerland, with Hebei's malonic acid corridor anchoring global intermediate volumes. The supply chain draws from Moroccan phosphate mining, Chinese phosphorus oxychloride synthesis, and northern China's urea feedstock. Single-origin malonic acid dependency in Hebei province creates concentrated logistics disruption risk during provincial environmental inspection campaigns. Distribution runs through German and French chemical distributors aggregating Asian supply for European laboratory markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barbituric acid functions as a stable compounder, with sedative-hypnotic API resurgence and supramolecular research expansion providing steady demand foundations resistant to cyclical volatility.
For Market Incumbents: Extend backward integration into malonic acid feedstock production to neutralize single-origin supply risk and secure cost-competitive positioning against Hebei corridor rivals. Accelerate continuous flow chemistry adoption to compress batch cycle times and differentiate through real-time impurity monitoring documentation. Defend against Z-drug substitution by locking multi-year offtake agreements with US contract manufacturers reviving barbiturate production lines. For New Entrants and Emerging Players: Microreactor platforms integrating in-line NMR spectroscopy offer a technology-first wedge into Swiss and Dutch high-potency API precursor synthesis, where documentation granularity trumps scale economies. Target laboratory-grade supply to German and Swiss coordination chemistry programs as the most penetrable segment, leveraging EU Green Deal Chemicals Strategy simplification proposals for low-volume specialty intermediates. Pursue CDSCO certification pathway to serve European generic drug developers seeking dual-source qualification away from Chinese concentration. For Investors and Strategic Acquirers: CDSCO-certified Indian pharmaceutical intermediate producers are the most active acquirer target category in this space, with validated European supply agreements commanding scarcity premiums. The five-to-ten year viability window favors producers with captive malonic acid access and REACH-registered European distributor relationships. Watch FDA scheduling review outcomes for specific barbiturate therapies as the inflection signal indicating volume pull direction in US contract manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Malonic Acid | Hebei corridor producers secure feedstock cost control against phosphorus oxychloride volatility. |
| Continuous Flow Chemistry Adoption | Swiss and Dutch contract manufacturers enable real-time impurity monitoring for ECHA dossier compliance. |
| CDSCO Certification Investment | Gujarat and Maharashtra producers unlock validated European generic API supply agreements. |
| Long-term Supply Agreement Lock-in | Indian and Eastern European API manufacturers mitigate FDA scheduling uncertainty inventory risks. |
| Green Manufacturing Transition | Shandong bulk synthesizers meet MEE dual carbon intensity benchmarks to maintain export eligibility. |
Methodological Framework
Direct dialogue with pharmaceutical procurement managers, CDSCO regulatory affairs leads, plant managers at Hebei and Shandong chemical facilities, and German chemical distribution channel partners grounded qualitative assessment. Secondary validation drew from ECHA REACH registration databases, FDA controlled substance precursor guidance filings, CDSCO GMP inspection records, and Chinese customs trade data. Bottom-up volume estimates from individual producer capacities triangulated against top-down demand aggregation from downstream barbiturate API synthesis requirements.
Segment-level projections across pharmaceutical-grade, intermediate-grade, and laboratory-grade tiers combined with end-user splits among pharmaceutical companies, academic institutions, and research laboratories. CAGRs were derived from regression analysis of historical price-volume relationships and forward assessment of regulatory compliance cost trajectories. Forecast inputs incorporated MEE environmental enforcement intensity, FDA scheduling review probability, and ECHA guidance update implementation timelines across the analysis window.
The model holds under stable regulatory classification of barbiturate precursors; deviation in FDA scheduling decisions or ECHA substance identification requirement tightening would shift volume and value trajectories. Material deviation in Moroccan phosphate supply disruptions or MEE inspection campaign intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Natural Fatty Alcohols Market
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Global Electronic Grade Phosphoric Acid Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
North America Tartaric Acid Market
Chemicals
Global Aldehyde Market
Chemicals
RO Membrane Chemicals Market
Chemicals
China Amines Market
Chemicals
White Phosphorus Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Malonic Acid Market
Chemicals
Bakers Ammonia Market
Chemicals
Guaiacol Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
Laboratory Chemicals Market
Chemicals
Ethyl Chloride Market