
 Isopropyl Alcohol (IPA) Market | 2026-2036
Isopropyl Alcohol (IPA) Market Size, Share, and Industry Trends Forecast 2026-2036
Isopropyl Alcohol (IPA) Market Foresight
The gap between pharmaceutical-grade and industrial-grade IPA is shifting from a simple purity spread into a structurally different supply chain, with electronics-grade now commanding dedicated production lines and premium offtake terms. Dow Inc. leverages its integrated propylene feedstock position to anchor North American supply reliability. ExxonMobil Corporation competes through Gulf Coast refining scale and export logistics infrastructure. LyondellBasell Industries differentiates via specialty solvent formulations that bridge industrial and cosmetic applications.
Isopropyl alcohol is a secondary alcohol with the formula C₃H₈O, typically manufactured through indirect hydration of propylene or catalytic hydrogenation of acetone, and it functions as a versatile solvent, disinfectant, and chemical intermediate across industrial and consumer applications. Pharmaceutical grade dominates value pools due to compendial compliance burdens and validated manufacturing requirements, while electronics grade represents the fastest-expanding segment as semiconductor fabs tighten particulate and moisture specifications. Industrial grade remains the volume anchor in solvents and cleaning agents, though margin compression from commoditization pushes producers toward higher-specification tiers.
EPA registration requirements for surface disinfectants and FDA oversight of drug manufacturing excipients shape product standards and market access in the United States, while REACH and the EU Medical Device Regulation impose parallel purity and documentation burdens across Europe. China's NMPA and GB standards for pharmaceutical raw materials add a third compliance layer for suppliers serving Asia-Pacific electronics and healthcare clusters. Stakeholders must monitor how evolving semiconductor node geometries and biopharma cleanroom protocols redefine grade-specific demand trajectories.
Market Dynamics
Grade stratification is fragmenting the Isopropyl Alcohol market into three non-interchangeable supply pools, with electronics-grade purity specifications diverging so sharply from pharmaceutical and industrial tiers that producers now face irreversible specialization decisions.
Growth Catalysts
- Semiconductor node advancement:Sub-7nm chip fabrication in Taiwan and South Korea is electrifying demand for sub-10 ppb metal-trace IPA, locking in long-term offtake contracts with solvent suppliers.
- EPA surface-disinfectant registration:Post-pandemic healthcare facility upgrades across the United States are mandating validated sterilization protocols that specify USP-grade IPA.
- China's chip self-sufficiency campaign:Domestic fab construction in Shanghai and Hefei is concentrating electronics-grade consumption within a single national supply zone.
Market Restraints
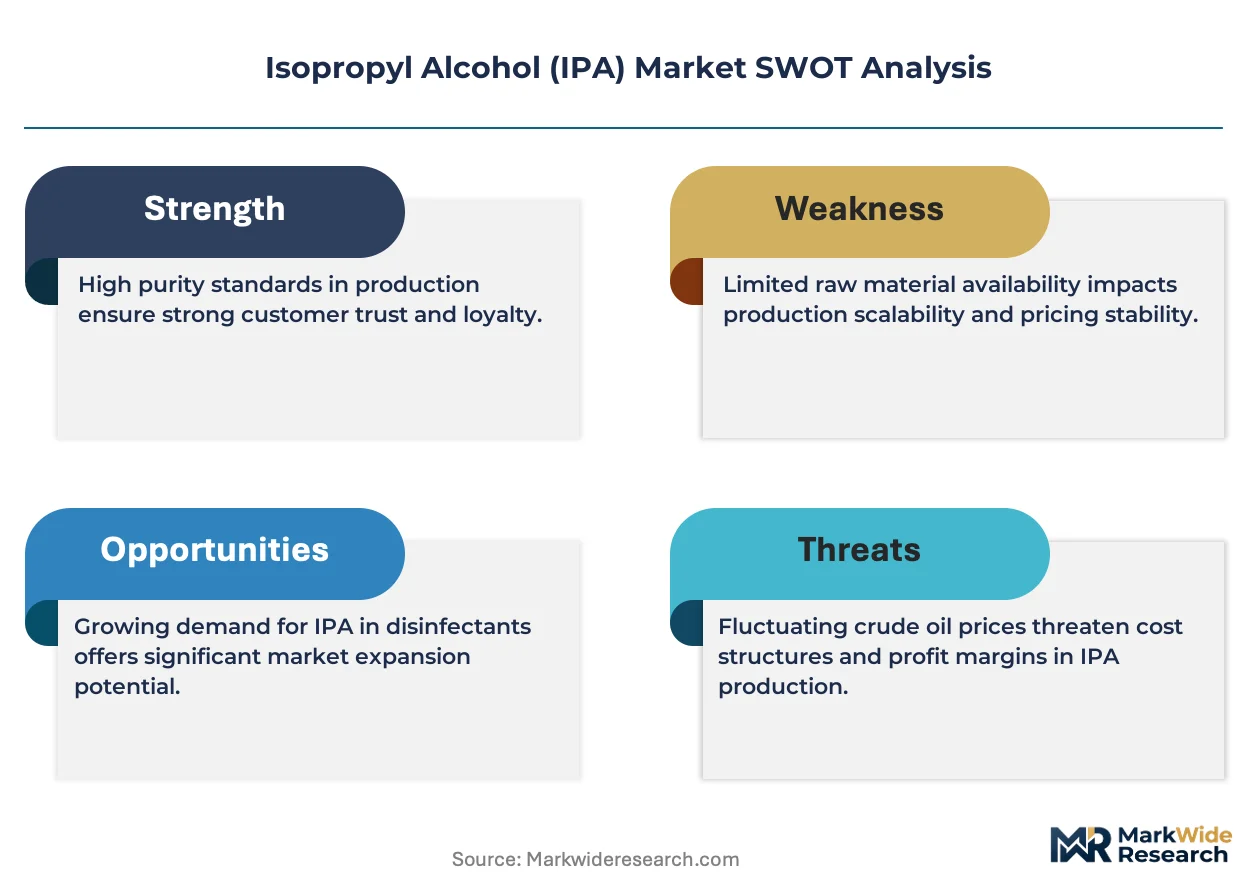
- Propylene feedstock volatility:Crude oil price swings directly compress IPA margin structures, particularly for non-integrated producers lacking captive olefin supply.
- Gulf Coast production concentration:Overreliance on Texas and Louisiana refining corridors exposes supply chains to hurricane disruption and export bottleneck risk.
- Acetone hydrogenation economics:Acetone-to-IPA conversion yields remain structurally disadvantaged versus direct propylene hydration on energy intensity metrics.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO-compliant excipient demand from Ahmedabad and Hyderabad API clusters offers underpenetrated volume growth.
- EU Green Deal solvent circularity:REACH-authorized recycling infrastructure for spent IPA in pharmaceutical and electronics applications creates premium recovery service margins.
- Point-of-use purification systems:On-site distillation and filtration units at semiconductor fabs are displacing bulk ultra-high-purity shipments with chemical-management service contracts.
Industry Challenges
- Cleanroom certification timelines:ISO 14644-1 Class 1 validation for electronics-grade packaging facilities extends facility qualification periods beyond 18 months.
- Analytical method transfer complexity:ICP-MS metal detection protocols must be revalidated across each customer-specific specification, fragmenting quality control workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isopropyl Alcohol (IPA) Market |
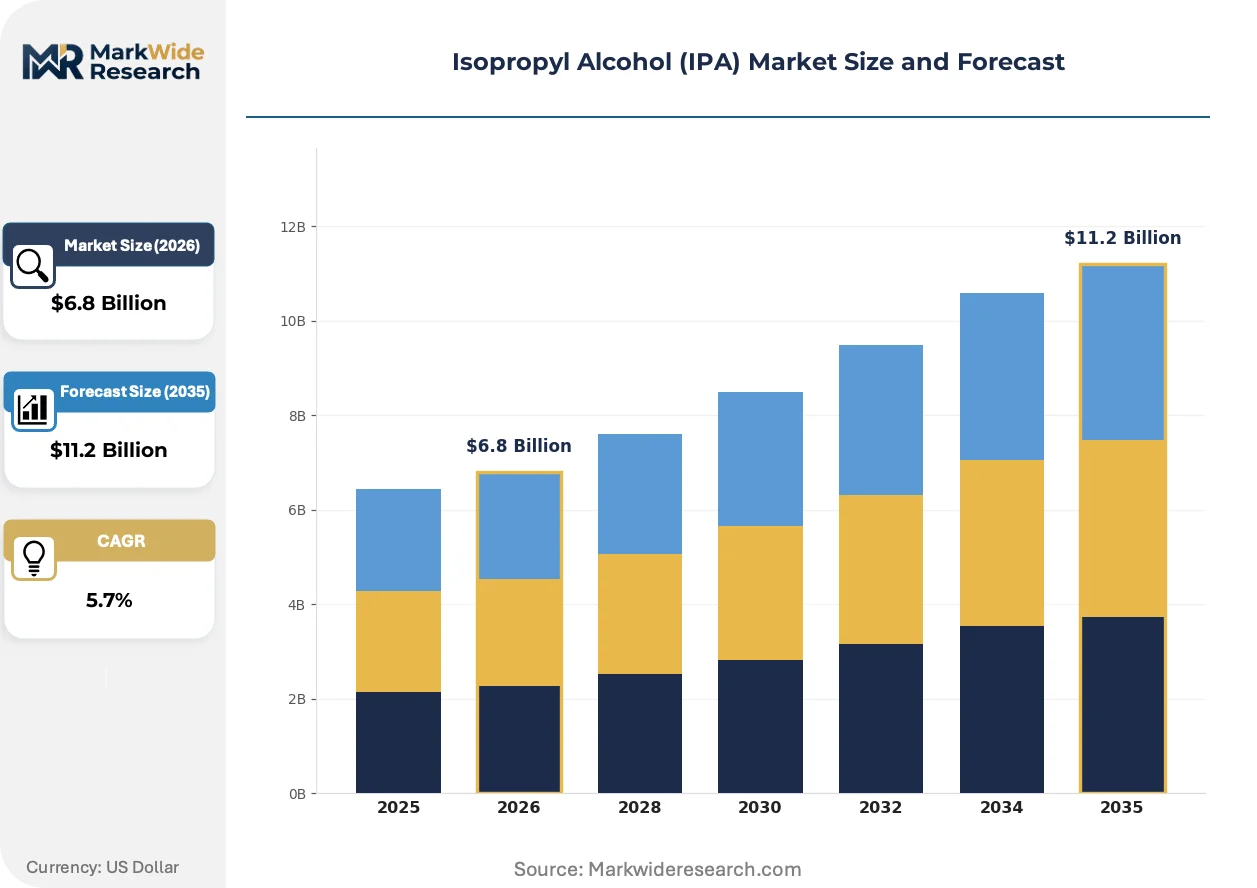
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Industrial Grade, Cosmetic Grade, Electronics Grade Application: Disinfectants, Solvents, Antiseptics, Cleaning Agents End User: Pharmaceuticals, Consumer Goods, Automotive, Electronics Packaging Type: Bottles, Drums, Jerry Cans, Bulk Containers |
| Companies Covered | Dow Inc., ExxonMobil Corporation, Royal Dutch Shell plc, LyondellBasell Industries, INEOS Group, BASF SE, Sasol Ltd., Linde, Avantor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isopropyl Alcohol (IPA) Market Shifts & Advancements
Process intensification and purity analytics are converging to redefine competitive advantage, with solvent suppliers racing to embed real-time contamination monitoring into production streams before customer audits become disqualifying events.
Membrane pervaporation dehydration is electrifying moisture specification compliance for electronics-grade IPA, replacing energy-intensive azeotropic distillation with molecular-sieve separation that cuts unit operating costs. Semiconductor fabs in Taiwan and South Korea are specifying pervaporated material in procurement tenders, forcing retrofit investments among legacy producers still running benzene-based extractive systems.
REACH Annex XVII restrictions on residual acetone and water content are tightening documentation burdens for EU pharmaceutical excipient suppliers, with ECHA guidance pushing toward continuous online chromatographic verification. German and French formulators now demand batch-level digital certificates traceable through blockchain-enabled quality systems, raising compliance infrastructure costs for non-European exporters.
Consolidated chemical management contracts are displacing spot purchasing across North American healthcare networks, with GPOs bundling IPA supply into multi-year sterilization solvent agreements that lock out smaller distributors. This procurement compression concentrates volume with integrated producers capable of guaranteeing 99.9 percent fill-rate performance across pandemic-disrupted logistics corridors.
Isopropyl Alcohol (IPA) Market Segmentation
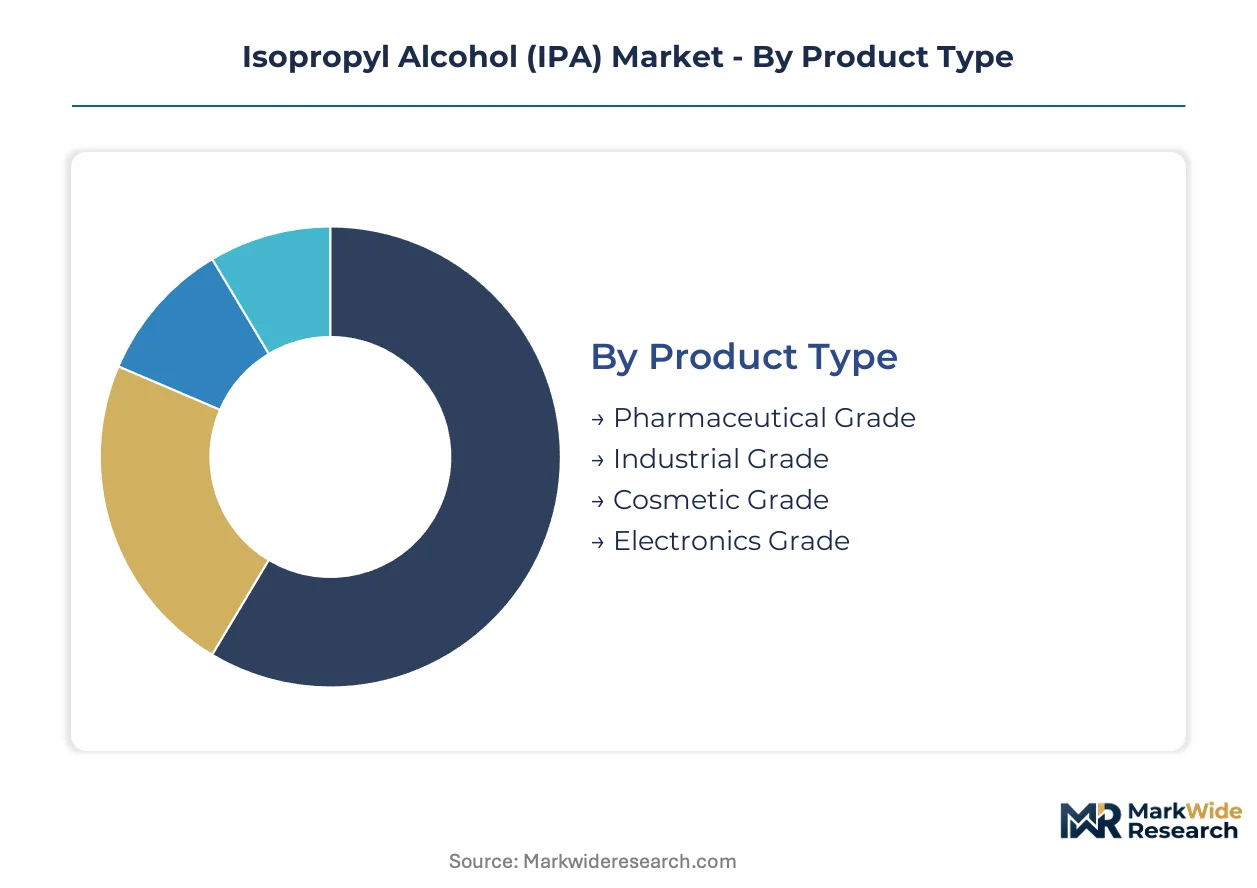
Grade stratification in isopropyl alcohol has fragmented supply chains into non-interchangeable tiers, forcing producers into irreversible specialization decisions. Each segment now operates under distinct purity protocols, regulatory burdens, and customer qualification timelines that prevent cross-tier arbitrage.
Product Type:
Customization intensity spans from commoditized industrial formulations to hyper-specialized electronics specifications requiring sub-10 ppb metal-trace validation.
- Pharmaceutical Grade:USP and EP compendial compliance mandates validated manufacturing with full batch documentation. FDA and EMA audits dominate qualification timelines, locking demand to healthcare sterilization protocols in the United States and European hospital networks.
- Electronics Grade:Sub-7nm semiconductor fabrication in Taiwan and South Korea demands moisture specifications below 100 ppm and particulate control exceeding pharmaceutical tiers. Pervaporation dehydration systems now separate qualified from legacy suppliers.
- Industrial Grade:Solvent and de-icing applications across automotive and coatings sectors.
- Cosmetic Grade:Fragrance and personal care formulations requiring residual acetone limits stricter than industrial tiers.
Most installed capacity flows through Industrial Grade. Expansion is steepest in Electronics Grade.
Application:
Volume concentration versus value capture splits sharply across these use cases, with disinfection commanding premium pricing through regulatory registration barriers.
- Disinfectants:EPA registration requirements and hospital procurement consolidation bundle IPA into multi-year sterilization contracts. Post-pandemic facility upgrades in the United States specify USP-grade material, concentrating volume with integrated producers capable of guaranteed fill rates.
- Solvents:Paint, coatings, and ink formulations represent the volume anchor, though margin compression from acetone-based competition pushes producers toward higher-specification tiers.
- Antiseptics:Pre-surgical skin preparation and wound care with compendial purity mandates.
- Cleaning Agents:Industrial degreasing and electronics assembly line maintenance.
Disinfectants generate the highest per-unit margins. Solvents absorb the greatest absolute tonnage.
End User:
Customer sophistication determines specification stringency, with semiconductor fabs imposing the most demanding supply chain audits.
- Electronics:Taiwan Semiconductor Manufacturing and Samsung Foundry specify locked-in offtake contracts with solvent suppliers running dedicated production lines. China's domestic fab construction in Shanghai and Hefei is concentrating demand within a single national supply zone.
- Pharmaceuticals:API manufacturing clusters in Ahmedabad and Hyderabad drive CDSCO-compliant excipient demand with underpenetrated volume potential.
- Consumer Goods:Personal care and household product formulators with moderate purity requirements.
- Automotive:Windshield washer fluid and coating solvent applications.
Electronics commands the steepest premium pricing. Pharmaceuticals offers the most stable contract structures.
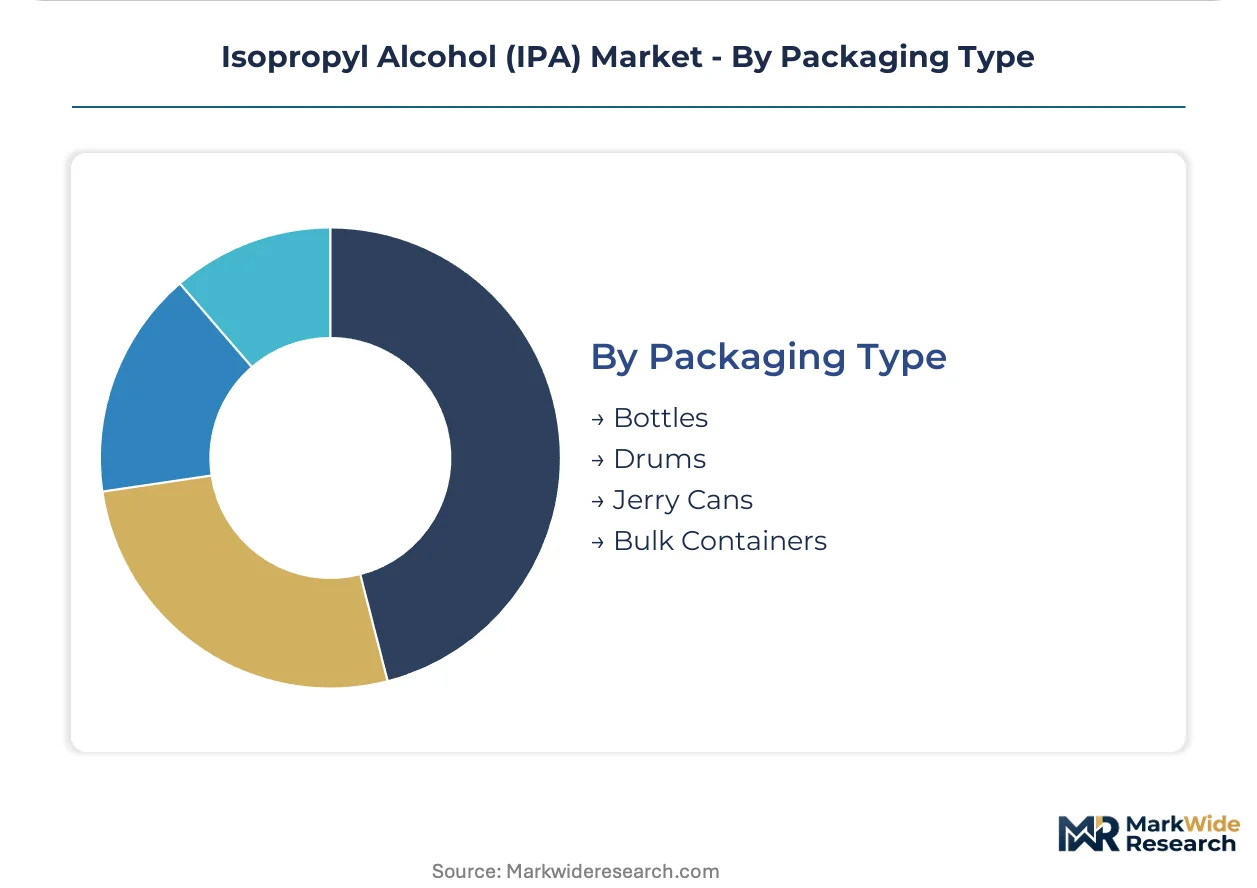
Packaging Type:
Logistics configuration and contamination risk define the selection matrix across these formats.
- Bulk Containers:ISO tank deliveries to semiconductor fabs and pharmaceutical manufacturing sites minimize handling contamination. Dedicated fleet requirements lock out smaller distributors from electronics-grade supply.
- Drums:Standard 200-liter format for industrial solvent distribution.
- Jerry Cans:Retail and healthcare facility replenishment with tamper-evident sealing.
- Bottles:Consumer antiseptic and cosmetic applications.
Bulk Containers dominate electronics and pharmaceutical procurement. Bottles face margin pressure from private-label competition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineers and semiconductor process technicians cluster around electronics manufacturing hubs, creating geographic moats that concentrate electronics-grade IPA demand in East Asian fab corridors and pharmaceutical-grade supply near FDA-inspected API clusters.
United States
EPA-registered surface disinfectant demand from hospital networks drives pharmaceutical-grade consumption, while Gulf Coast propylene crackers anchor industrial-grade supply. Texas and Louisiana refining corridors concentrate production capacity, exposing logistics to hurricane season disruption.
China
Domestic semiconductor fabrication in Shanghai and Hefei electrifies electronics-grade IPA procurement as chip self-sufficiency campaigns accelerate. NMPA pharmaceutical raw material standards and GB compliance frameworks reshape import substitution strategies for domestic suppliers.
Germany
REACH-authorized solvent recycling infrastructure creates premium recovery service margins for pharmaceutical and electronics applications. ECHA guidance on residual acetone documentation pushes batch-level digital certification through blockchain-enabled quality systems.
South Korea
Sub-7nm foundry operations by Samsung Foundry specify locked-in offtake contracts with sub-10 ppb metal-trace requirements. MFDS pharmaceutical excipient standards and KOSHA industrial chemical protocols govern dual-grade supply chain qualification.
India
API manufacturing clusters in Ahmedabad and Hyderabad generate CDSCO-compliant excipient demand with underpenetrated volume potential. PLI scheme incentives for active pharmaceutical ingredients attract pharmaceutical-grade IPA suppliers to Gujarat and Telangana industrial corridors.
Isopropyl Alcohol (IPA) Market Competitive Landscape
Capital-heavy integrated petrochemical producers compete with asset-light specialty chemical distributors for differentiated grade access. The market structures around three tiers: propylene-integrated refiners commanding industrial-grade volume, specialty solvent formulators bridging cosmetic and pharmaceutical applications, and electronics-grade purifiers running dedicated pervaporation dehydration lines. Dominant competitive moves include backward integration into captive propylene supply and multi-year sterilization solvent contracts with consolidated healthcare purchasing organizations.
Among North American integrated producers, Dow Inc. and ExxonMobil Corporation exemplify the scale-driven archetype, leveraging Gulf Coast refining infrastructure to anchor supply reliability. LyondellBasell Industries occupies a position bridging industrial and specialty tiers through differentiated solvent formulations. These three names represent how geographic feedstock access and grade-specific purification capabilities determine competitive positioning in a fragmenting market.
| Leading Market Players |
|---|
| Dow Inc. |
| ExxonMobil Corporation |
| Royal Dutch Shell plc |
| LyondellBasell Industries |
| INEOS Group |
| BASF SE |
| Sasol Ltd. |
| Linde |
| Avantor |
| Others |
Supply & Pricing Matrix
Specialized chemical engineers and semiconductor process technicians clustering around Taiwan and South Korea electronics manufacturing hubs create geographic labor-cost differentials that widen pricing spreads between electronics-grade and industrial-grade tiers.
Pricing Analysis
Bundled chemical-management contracts versus unbundled spot purchasing splits the market into divergent pricing regimes. Three-tier pricing structure across premium electronics-grade, validated pharmaceutical-grade, and commodity industrial-grade levels anchors transactional models, with certification burden and pervaporation dehydration capital intensity driving price differentiation. Pricing pressure stems from acetone-based IPA competition pressuring industrial-grade margins, while semiconductor fabs show least price sensitivity due to locked-in offtake terms.
Supply Chain Analysis
Freight cost exposure concentrates around Gulf Coast export corridors and East Asian fab delivery networks, with ISO tank dedicated fleets locking out smaller distributors from premium tiers. Supply draws from United States, China, and South Korea production bases, with propylene feedstock, pervaporation membrane systems, and cleanroom packaging materials anchoring input dependencies. Single-source vulnerability runs through Texas-Louisiana hurricane corridors, while distribution feeds through consolidated healthcare GPOs and semiconductor direct-procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Isopropyl Alcohol market compounds steadily as semiconductor node advancement and pharmaceutical sterilization upgrades sustain durable demand expansion across specialized grades.
For Market Incumbents: Acquire pervaporation dehydration assets and ISO 14644-1 Class 1 cleanroom certification capabilities to defend electronics-grade positioning against Asian integrated producers. Lock in multi-year sterilization solvent contracts with consolidated healthcare GPOs to secure pharmaceutical-grade volume against acetone-based price competition. Prioritize captive propylene supply through backward integration into Gulf Coast cracking capacity. For New Entrants and Emerging Players: Begin with CDSCO-compliant pharmaceutical excipient supply to Ahmedabad and Hyderabad API clusters, where domestic Indian production remains underpenetrated relative to import dependence. Target electronics-grade point-of-use purification service contracts as semiconductor fabs displace bulk shipments with on-site chemical management. Leverage REACH-authorized recycling infrastructure partnerships for EU pharmaceutical and electronics recovery margins. For Investors and Strategic Acquirers: Specialty chemical distributors with electronics-grade purification capabilities are the most active acquirer in this space, as integrated petrochemical players seek grade-specific downstream access without greenfield cleanroom construction timelines. Five-to-ten year viability hinges on locked-in foundry offtake contracts with sub-10 ppb metal-trace specifications. Monitor pervaporation dehydration retrofit announcements as inflection signal for legacy producer competitive displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Dow Inc. and ExxonMobil anchor margin defense through captive Gulf Coast olefin production. |
| Pervaporation Dehydration Retrofit | Membrane system adoption separates qualified electronics-grade suppliers from benzene-based legacy producers. |
| CDSCO Certification Investment | Indian pharmaceutical excipient compliance unlocks Ahmedabad and Hyderabad API cluster procurement. |
| REACH-Authorized Recycling Infrastructure | German and French batch-level digital certification creates premium recovery service margins. |
| Multi-Year Sterilization Solvent Contracts | Consolidated healthcare GPO bundling concentrates volume with guaranteed fill-rate performers. |
Research Methodology
Multiple input streams — solvent plant managers, semiconductor procurement leads at Taiwan and South Korea foundries, pharmaceutical technical R&D directors, and healthcare GPO contracts managers — were reconciled against customs trade data, ACC solvent market reports, SEC 10-K chemical segment disclosures, and ECHA REACH registration databases. Bottom-up grade-specific volume estimates triangulated with top-down propylene derivative consumption models to anchor supply-side calibration.
Historical capacity utilization and panel-based demand projections were cross-referenced across the analysis window, with segmentation modeling spanning grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs derived from weighted average of demand elasticity coefficients and substitution threat parameters, with semiconductor node geometry roadmaps and EPA disinfectant registration timelines as IPA-specific forecast inputs.
Several conditions sit outside the modeled scope, including force majeure disruptions to Gulf Coast refining corridors, abrupt acetone hydrogenation yield breakthroughs, and unanticipated REACH Annex XVII restriction expansions. Forecasts reflect documented assumptions about foundry construction timelines and healthcare facility upgrade cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Calcium Methoxide Market
Chemicals
Global Boron Trifluoride Market
Chemicals
Formalin Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Allyl Chloride Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
Ethanolamine Market
Chemicals
Mercuric Chloride Market
Chemicals
Silicone Textile Softeners Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Asia-Pacific Methyl Acrylate Market
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Cummene Derivatives Market
Chemicals
Pinoxaden Market
Chemicals
Cold Phosphating Chemicals Market