
 Global Cresols Market | 2026-2036
Global Cresols Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cresols Market Foresight
Technical-grade specification and custom synthesis services are broadening what chemical suppliers sell beyond commodity volumes. LANXESS AG leverages its integrated phenolics chain to sustain margin capture across European pharmaceutical and agrochemical accounts. Mitsui Chemicals, Inc. anchors Asian supply through captive cresol-to-derivative conversion, while Sasol Phenolics competes on coal-tar feedstock economics in Southern African export markets.
Cresols are methyl-substituted phenols existing as ortho, meta, and para isomers, typically produced via coal tar distillation or petroleum-derived toluene sulfonation, with boiling points ranging from 191°C to 202°C depending on isomeric purity; they function primarily as chemical intermediates, disinfectant actives, and solvent components across industrial formulations. The pharmaceutical application segment carries premium pricing due to injectable-grade cresol USP requirements, while p-Cresol dominates volume flows into antioxidant and resin manufacturing. Mixed cresol grades serve cost-sensitive disinfectant and solvent markets where isomer separation economics do not justify purification investment.
EPA registration requirements govern cresol-based disinfectant formulations in the United States, while REACH restricts certain cresol impurity profiles in European chemical intermediate trade; China's MEE enforces wastewater discharge standards on coal-tar distillation operations that tighten production cost structures. Manufacturers must monitor how evolving pharmaceutical purity standards and carbon-intensity disclosure rules reshape feedstock sourcing decisions and regional competitiveness.
Market Dynamics
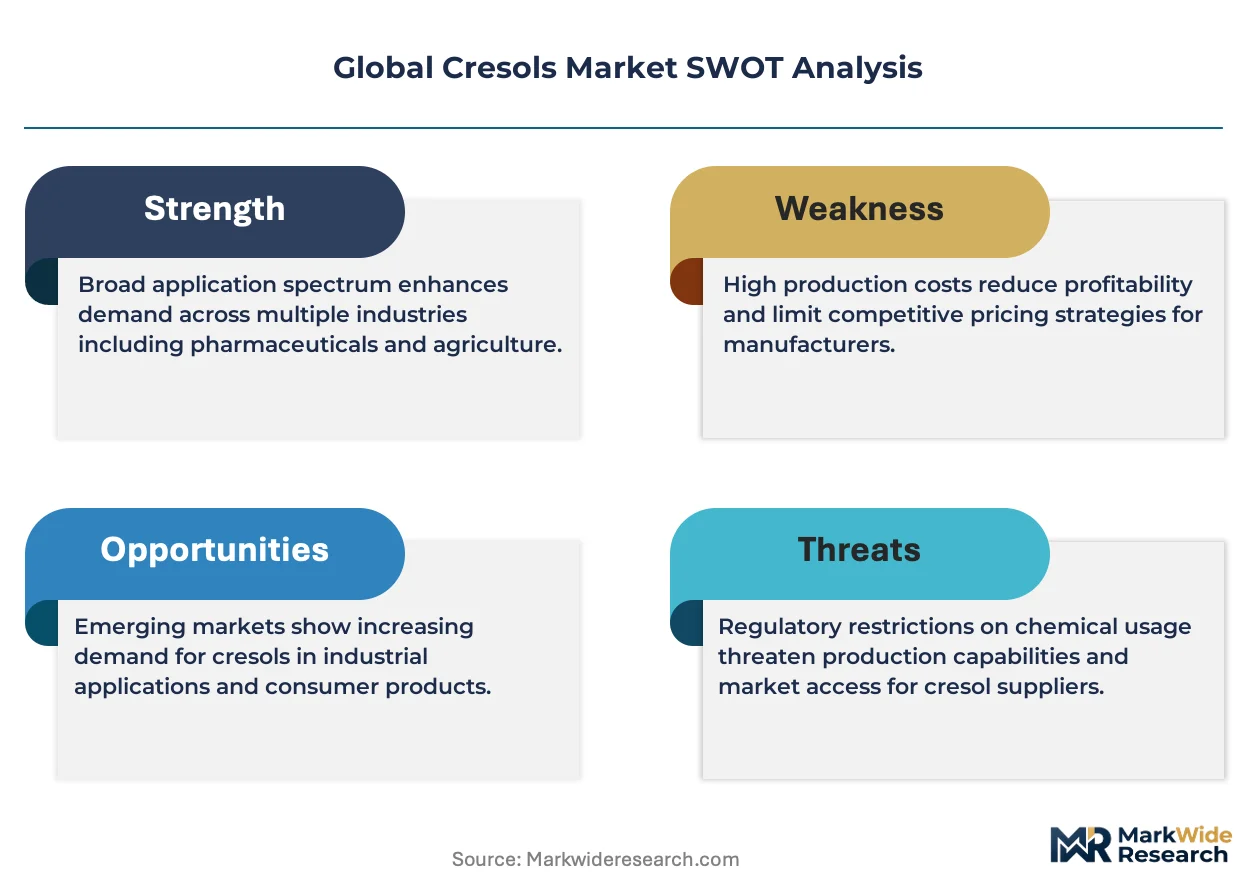
Pharmaceutical-grade purity mandates and coal-tar feedstock economics are compressing margins for non-integrated producers while rewarding suppliers with captive cresol-to-derivative capabilities.
Growth Catalysts
- Injectable drug formulation:USP-grade m-cresol demand is accelerating as biologics manufacturers seek stabilizers for monoclonal antibody formulations. FDA purity requirements for parenteral excipients are tightening specification bands.
- REACH compliance:EU Green Deal carbon-intensity disclosure rules are favoring European producers with verified low-carbon phenolics chains. ECHA registration dossiers now require expanded impurity profiling for chemical intermediate trade.
- Agrochemical intermediates:Herbicide and pesticide synthesis in China is absorbing mixed cresol grades at scale. Domestic resin production is concentrating demand around Shandong and Jiangsu production clusters.
Market Restraints
- Coal-tar feedstock volatility:Coke oven gas economics fluctuate with steel production cycles, destabilizing cresol supply costs for non-integrated distillers.
- Isomer separation limits:Crystallization and extractive distillation energy intensity creates a technical floor on high-purity o-cresol and p-cresol pricing.
- Petroleum-based toluene sulfonation:Synthetic routes from aromatics complexes compete selectively but carry higher carbon intensity under EU CBAM scope.
Strategic Opportunities
- Brazil agrochemical formulation:ANVISA registration pathways for cresol-based disinfectants remain underpenetrated relative to manufacturing scale. Local blending operations seek technical-grade supply partnerships.
- Carbon border adjustments:EU CBAM phase-in creates competitive opening for producers with documented Scope 1-3 emissions below benchmark thresholds.
- Antioxidant polymer stabilization:p-Cresol derivatives for engineered plastics are gaining specification in automotive underhood applications requiring thermal stability.
Industry Challenges
- Analytical chemist scarcity:USP-grade cresol certification requires specialized chromatographic impurity quantification that outpaces available talent pools in emerging production regions.
- MEE wastewater compliance:China's Ministry of Ecology and Environment discharge standards for phenolics-containing effluent demand capital-intensive treatment retrofits at coal-tar distillation facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cresols Market |
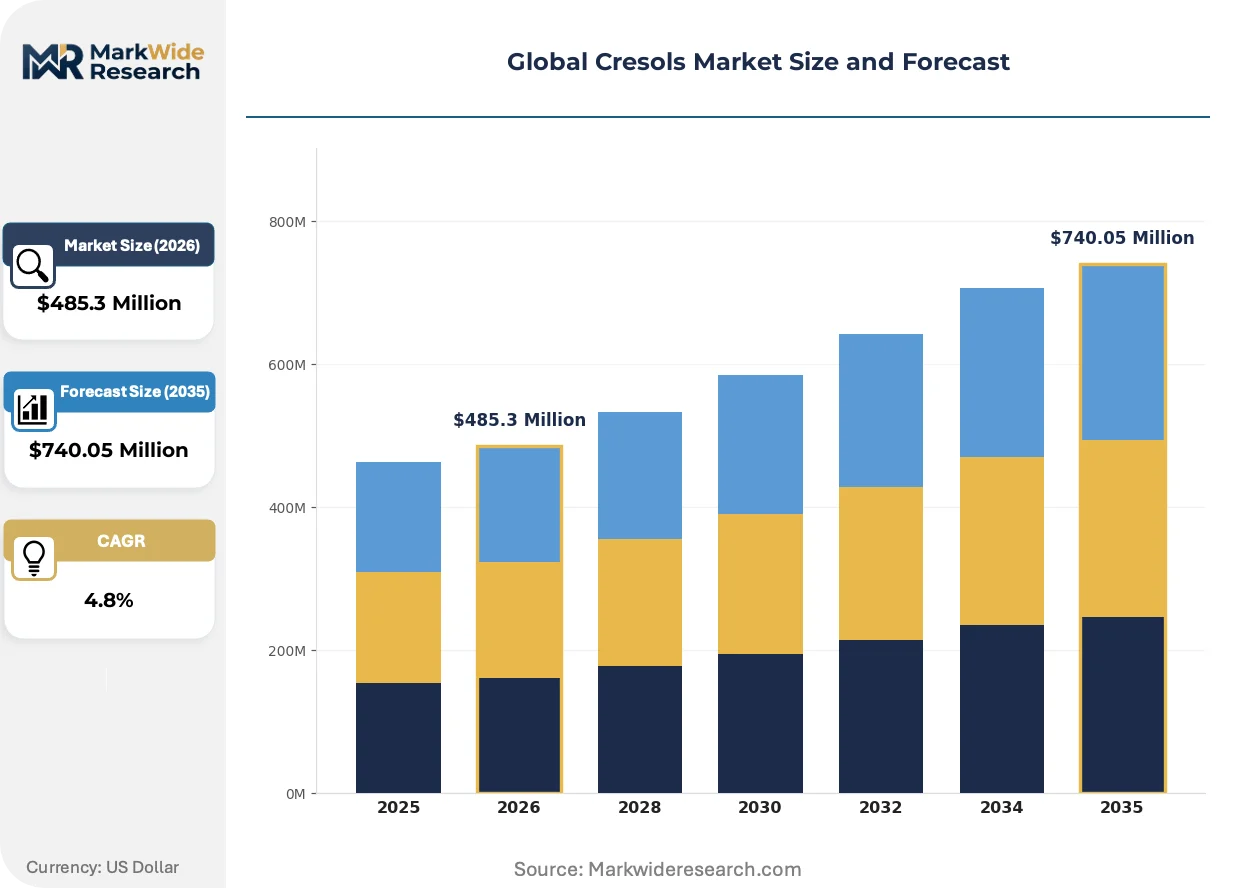
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $740.05 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: p-Cresol, m-Cresol, o-Cresol, Mixed Cresol Application: Disinfectants, Resin Manufacturing, Solvents, Chemical Intermediates, Pharmaceuticals End User Industry: Construction Chemicals, Agrochemicals, Paints & Coatings, Personal Care, Rubber Processing Packaging Type: Drums, Totes, Bulk Containers, Carboys |
| Companies Covered | Merck KGaA, LANXESS AG, Mitsui Chemicals, Inc., Sasol Phenolics, SABIC, KANTO KAGAKU, Dorf Ketal, RÜTGERS Group, Atul Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cresols Market Shifts & Advancements
Process intensification and regulatory disclosure requirements are compressing batch cycle times while expanding documentation burdens across the cresol value chain.
Continuous flow reactor technology for selective methylation of phenol is converging with modular plant designs that reduce solvent inventory and thermal degradation losses. Specialty chemical producers in Germany and Japan are piloting these systems for pharmaceutical-grade output. The technology is converging with distributed manufacturing models that shorten supply chains for time-sensitive injectable formulations.
EU CSRD sustainability reporting mandates now require Scope 3 upstream emissions disclosure from chemical intermediate suppliers. Large EU-based pharmaceutical and agrochemical formulators are cascading these requirements to cresol vendors through supplier qualification questionnaires. REACH-registered producers with verified lifecycle assessments are capturing preferential supply positions in European antibiotic and disinfectant manufacturing.
Long-term offtake contracting is displacing spot market purchasing among North American and European pharmaceutical buyers seeking supply security for parenteral-grade excipients. Three-to-five year volume commitments with fixed-price escalation clauses are replacing quarterly tenders. This pattern is most visible in injectable drug manufacturing clusters in New Jersey, Massachusetts, and the Basel region.
Global Cresols Market Segmentation
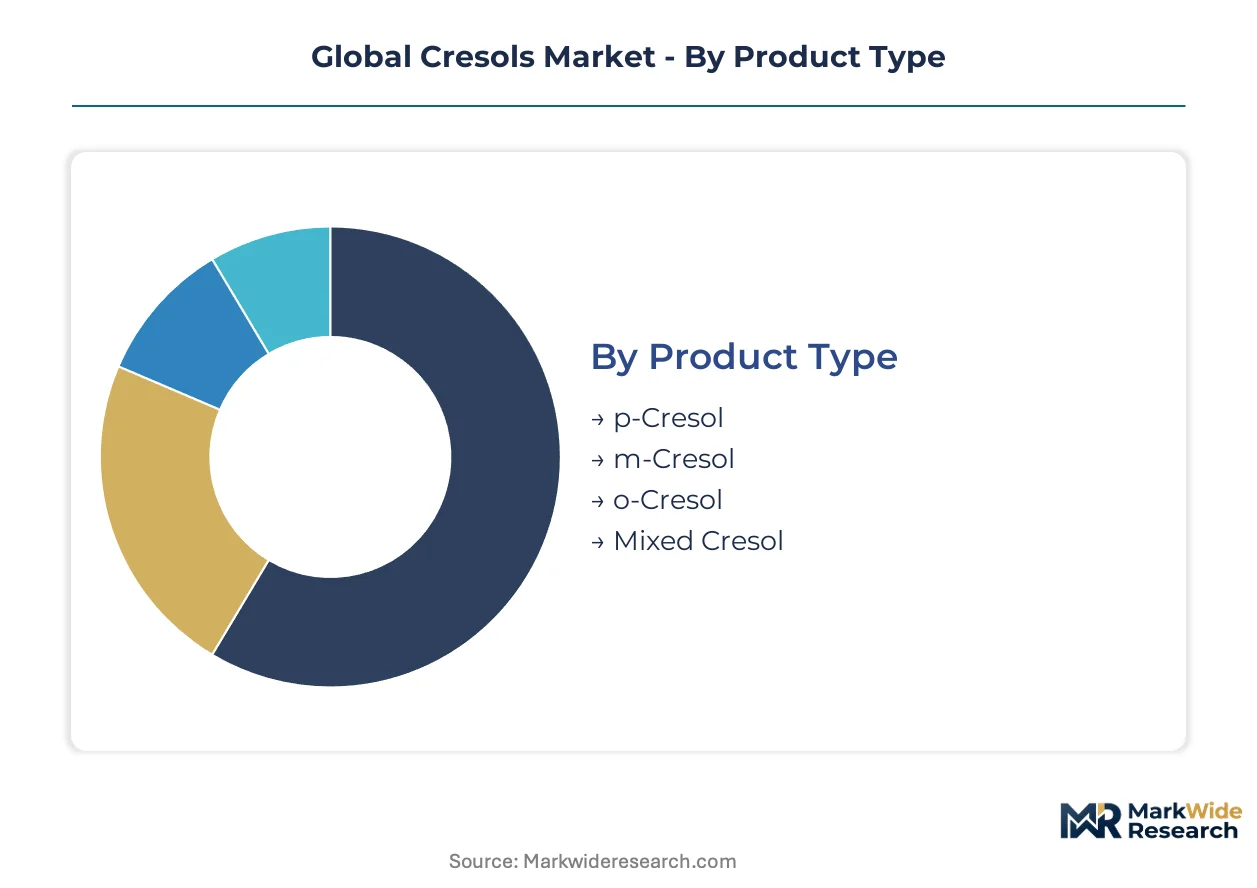
Certification burdens fragment the cresol landscape into tiers where USP-grade pharmaceutical supply commands premium positioning against technical-grade commodity flows. Isomer-specific purity requirements and end-use regulatory exposure determine margin capture across each segment category.
Product Type:
REACH dossier complexity and FDA parenteral excipient rules impose divergent compliance costs across isomer grades, with pharmaceutical applications demanding chromatographic impurity profiling unavailable to commodity distillers.
- p-Cresol:This para-isomer delivers 99% minimum purity specifications required for antioxidant synthesis in engineered plastics. Demand concentrates in China's Shandong resin manufacturing corridor where domestic phenolic output scales for automotive underhood thermal stabilization.
- m-Cresol:The meta-isomer satisfies USP monograph requirements for injectable drug stabilizers in monoclonal antibody formulations. Massachusetts and New Jersey biologics clusters source this grade under three-to-five year offtake contracts with fixed-price escalation clauses.
- o-Cresol:Ortho-isomer separation via crystallization faces energy-intensity constraints that elevate pricing for agrochemical intermediate synthesis.
- Mixed Cresol:Unseparated isomer blends serve cost-sensitive disinfectant manufacturing where purity economics do not justify fractionation investment.
p-Cresol sits at the top of the volume ranking, with m-Cresol climbing the fastest.
Application:
Margin structures stratify sharply between pharmaceutical-grade certification and industrial commodity pricing, with carbon-intensity disclosure rules now layering additional differentiation.
- Pharmaceuticals:Parenteral-grade cresol excipients require USP compliance with endotoxin limits below 10 EU/g and comprehensive impurity quantification via HPLC-UV detection. Basel-region antibiotic manufacturers prioritize European producers with verified Scope 1-3 emissions documentation under EU CSRD mandates.
- Chemical Intermediates:Herbicide and pesticide synthesis in Jiangsu Province absorbs technical-grade m-cresol at scale. ECHA registration dossiers for intermediate trade now demand expanded impurity profiling that favors integrated phenolics chains.
- Disinfectants:EPA-registered formulations in the United States govern phenolic coefficient testing against Salmonella typhi and Staphylococcus aureus.
- Resin Manufacturing:p-Cresol derivatives for phenolic novolac resins face specification tightening from automotive OEMs.
- Solvents:Mixed cresol grades serve industrial degreasing applications with minimal regulatory burden.
Chemical Intermediates generates the largest revenue pool, while Pharmaceuticals delivers the steepest expansion trajectory.
End User Industry:
Customer procurement sophistication varies from spot-market commodity purchasing to multi-year supply security contracting with embedded sustainability auditing.
- Agrochemicals:Glyphosate and 2,4-D synthesis in China consumes mixed cresol grades at volumes that shape regional pricing benchmarks. MEE wastewater discharge standards for phenolics-containing effluent force capital-intensive treatment retrofits at coal-tar distillation facilities serving this segment.
- Construction Chemicals:Phenolic resin adhesives for engineered wood products specify p-cresol derivatives with formaldehyde emission controls.
- Paints & Coatings:Epoxy curing agent applications favor technical-grade o-cresol with hydroxyl functionality requirements.
- Rubber Processing:Antioxidant additives for tire manufacturing demand p-cresol derivatives with thermal stability specifications.
- Personal Care:Disinfectant actives for topical formulations require USP or BP certification with restricted impurity profiles.
Agrochemicals anchors volume demand, with Personal Care gaining share fastest on premium pricing.
Packaging Type:
Logistics configuration aligns with customer scale and regulatory documentation requirements, from drum-level traceability to bulk supply with certificate-of-analysis integration.
- Bulk Containers:Pharmaceutical manufacturers in the Basel region and New Jersey corridor receive ISO-tank deliveries with continuous temperature monitoring and chain-of-custody documentation. EU GDP guidelines for active pharmaceutical ingredient transport favor this format for parenteral-grade supply security.
- Drums:Agrochemical formulators in Brazil and India source technical-grade cresol in 200-liter steel drums with UN certification for phenolics transport. ANVISA registration pathways for cresol-based disinfectants drive drum-level procurement from local blending operations.
- Totes:Mid-scale resin manufacturers favor intermediate-volume packaging with reduced handling costs.
- Carboys:Laboratory and pilot-scale pharmaceutical development requires glass or fluoropolymer-lined containers with extractables testing.
Bulk Containers dominates pharmaceutical procurement, with Totes expanding most quickly among mid-tier chemical intermediate buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting cresol production toward jurisdictions with lower carbon-accounting burdens and streamlined chemical registration pathways. Producers with integrated phenolics chains in China and coal-tar economics in South Africa capture margin advantages as EU compliance costs escalate.
China
Shandong and Jiangsu provinces absorb mixed cresol grades at scale for glyphosate synthesis and phenolic resin manufacturing. MEE wastewater discharge standards force capital-intensive treatment retrofits at coal-tar distillation facilities serving agrochemical formulators. Domestic resin production clusters around Qingdao and Nanjing concentrate demand for p-cresol derivatives in automotive underhood applications.
United States
New Jersey and Massachusetts biologics clusters source USP-grade m-cresol under multi-year offtake contracts for monoclonal antibody stabilizers. EPA registration requirements govern phenolic coefficient testing for disinfectant formulations against standard bacterial strains. Gulf Coast petrochemical complexes explore synthetic toluene sulfonation routes despite carbon-intensity exposure under prospective border adjustment mechanisms.
Germany
REACH dossier complexity and EU Green Deal carbon-intensity disclosure rules favor domestic producers with verified low-carbon phenolics chains. ECHA registration requirements for chemical intermediate trade demand expanded impurity profiling that integrated European suppliers satisfy more readily. Leverkusen and Ludwigshafen chemical corridors anchor pharmaceutical-grade cresol output for parenteral excipient supply.
Brazil
ANVISA registration pathways for cresol-based disinfectants remain underpenetrated relative to agrochemical manufacturing scale. Local blending operations in São Paulo state seek technical-grade supply partnerships with documented import compliance. Domestic herbicide formulation absorbs mixed cresol grades through port terminals serving the broader Mercosur region.
South Africa
Sasol Phenolics leverages coal-tar feedstock economics at Secunda and Sasolburg complexes for export-oriented cresol derivative production. Southern African steel production cycles destabilize coke oven gas economics for non-integrated distillers competing on spot markets. Richards Bay and Durban port infrastructure supports bulk container shipments to European pharmaceutical and agrochemical accounts.
Global Cresols Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade certification creating defensible positions against commodity distillers. The vendor base concentrates around integrated phenolics producers with captive cresol-to-derivative conversion capabilities. Three archetypes dominate: coal-tar-based integrated producers, petroleum-derived synthetic route operators, and custom synthesis service providers. Capacity expansion in China and backward integration into coal-tar distillation represent the primary competitive vectors.
Among European-based integrated producers, LANXESS AG exemplifies the captive phenolics chain archetype, while Mitsui Chemicals, Inc. anchors Asian supply through regional derivative conversion networks. Sasol Phenolics occupies a position within the coal-tar economics tier, leveraging Southern African feedstock access for export market participation.
| Leading Market Players |
|---|
| Merck KGaA |
| LANXESS AG |
| Mitsui Chemicals, Inc. |
| Sasol Phenolics |
| SABIC |
| KANTO KAGAKU |
| Dorf Ketal |
| RÜTGERS Group |
| Atul Ltd |
| Others |
Supply & Pricing Matrix
EU CSRD sustainability disclosure mandates gate qualified supply access and premium-tier pricing power for pharmaceutical-grade cresol producers serving European biologics manufacturers. Coal-tar feedstock economics and carbon-intensity documentation requirements now bifurcate the vendor base between integrated chains with verified Scope 1-3 emissions and commodity distillers facing margin compression.
Pricing Analysis
Capacity additions in China's Shandong corridor are reshaping price floors for technical-grade mixed cresols used in agrochemical synthesis. Three-tier pricing structure across USP-certified pharmaceutical, REACH-registered intermediate, and unseparated disinfectant grades reflects certification burden differentiation. Cost compression in the mixed-grade tier intensifies because MEE wastewater compliance forces capital-intensive treatment retrofits at coal-tar facilities. Agrochemical formulators in Jiangsu Province exhibit highest price sensitivity, while Massachusetts biologics clusters accept fixed-price escalation clauses for parenteral-grade m-cresol security.
Supply Chain Analysis
Analytical chemist scarcity in emerging manufacturing geographies constrains high-purity isomer separation capacity expansion. Supply concentrates in China, Germany, and South Africa, with raw material dependencies on coke oven gas economics, petroleum-derived toluene, and specialized crystallization solvents. Single-source vulnerability runs through Shandong coal-tar distillation corridors serving global agrochemical intermediate demand. Distribution runs through ISO-tank bulk deliveries for pharmaceutical accounts and drum-level procurement for regional disinfectant blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities center on captive cresol-to-derivative conversion and carbon-intensity documentation advantages that command premium positioning in EU pharmaceutical procurement.
For Market Incumbents: Lock in multi-year offtake contracts with Basel-region and New Jersey biologics manufacturers before EU CBAM phase-in accelerates supplier qualification requirements. Defend against petroleum-based synthetic route competitors by investing in continuous flow reactor technology for pharmaceutical-grade output. Prioritize backward integration into coal-tar distillation where coke oven gas economics remain favorable.
For New Entrants and Emerging Players: Capture underpenetrated ANVISA registration pathways for cresol-based disinfectants in São Paulo state blending operations. Target technical-grade supply partnerships with Brazilian agrochemical formulators seeking documented import compliance. Lead with drum-level logistics and UN-certified packaging capabilities that incumbent bulk suppliers overlook.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale custom synthesis providers because pharmaceutical-grade certification scarcity creates defensible niche positions. Five-to-ten year viability favors producers with verified low-carbon phenolics chains and captive derivative conversion capabilities. Watch EU CBAM benchmark threshold announcements as the signal for accelerated consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coal-Tar Distillation | Secures feedstock cost control against steel production cycle volatility at Secunda and Sasolburg complexes. |
| Continuous Flow Reactor Technology Deployment | Reduces solvent inventory and thermal degradation losses for pharmaceutical-grade m-cresol output in German pilot facilities. |
| Long-Term Supply Agreement with Biologics Clusters | Replaces quarterly tenders with three-to-five year volume commitments in New Jersey and Massachusetts corridors. |
| EU CSRD Scope 3 Documentation Investment | Captures preferential supply positions with Basel-region antibiotic manufacturers under sustainability reporting mandates. |
| Joint Venture for Brazil Disinfectant Registration | Accelerates ANVISA pathway penetration through local blending operation partnerships in São Paulo state. |
Research Methodology
Coverage spans China, Germany, the United States, Brazil, and South Africa, with primary inputs from each region's coal-tar distillation and pharmaceutical manufacturing corridors. The analysis combines interviews with plant managers at integrated phenolics producers, procurement leads at downstream agrochemical formulators, distribution channel partners in Mercosur port terminals, and technical R&D directors at specialty chemical firms. Secondary validation draws from customs and trade data, ECHA registration dossiers, SEC 10-K filings, and MEE wastewater discharge compliance records. Bottom-up capacity and demand modeling triangulates against top-down value chain analysis.
Segmentation granularity extends to isomer purity grade, end-use application, packaging format, and regional production hub across the projection horizon. The analytical framework models pharmaceutical-grade, intermediate-grade, and technical-grade tiers separately, with CAGRs derived from volume-demand elasticity and price-premium persistence assumptions. Industry-specific inputs include coke oven gas economics correlation with steel production cycles, USP monograph revision timelines, and EU CBAM carbon-intensity benchmark development.
Coal-tar feedstock volatility, REACH dossier expansion requirements, and analytical chemist availability are the dominant revision risks to forecast assumptions. Material deviation in any of these triggers warrants pause and re-evaluation of capacity expansion and pricing power projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Scouring Agents Market
Chemicals
Global Lactate Salts Market
Chemicals
Carbon Tetrabromide Market
Chemicals
N-Propanol Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Superplasticizer Market
Chemicals
Aircraft Cleaning Chemicals Market
Chemicals
Morpholine Market
Chemicals
Mercuric Chloride Market
Chemicals
Global Bleaching Agents Market
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Lanthanum Nitrate Market
Chemicals
RDX and HMX Market
Chemicals
Asia-Pacific Gamma Butyrolactone Market
Chemicals
Hydrogenated Dimer Acid Market