
 Brazil Adhesives Market | 2026-2036
Brazil Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Adhesives Market Outlook
Technical advisory and formulation customization is repositioning how adhesive suppliers capture value beyond commodity resin sales. Dow leverages its polyurethane research infrastructure to anchor premium bonding solutions for Brazilian automotive assembly lines. Henkel AG & Co. KGaA sustains broad construction-sector coverage through distributor partnerships in Minas Gerais and Rio de Janeiro. H.B. Fuller Company specializes in packaging-grade hot-melt systems for food and beverage exporters navigating shelf-life requirements.
Adhesives are polymeric substances formulated from epoxy, polyurethane, acrylic, or silicone chemistries that create structural or semi-structural bonds through surface wetting, chemical curing, or mechanical interlocking, with specifications typically covering shear strength, cure temperature, and elongation-at-break parameters. These materials serve primarily to replace mechanical fasteners, reduce assembly weight, and enable dissimilar-substrate joining across manufacturing operations. Epoxy formulations dominate heavy-industry applications where load-bearing performance commands price premiums, while polyurethane adhesives represent the fastest-expanding chemistry platform in flexible packaging and automotive interior assembly. Acrylic systems occupy a mature niche in electronics bonding and transparent-display lamination where optical clarity requirements limit substitution.
ANVISA regulates chemical substance registration and safety data sheet disclosure for adhesive formulations sold in Brazil, while the Brazilian Institute of Environment and Renewable Natural Resources enforces VOC emission thresholds that directly constrain solvent-based product lines. The National Institute of Metrology, Quality and Technology certifies performance testing protocols that determine qualification for infrastructure and defense procurement channels. Stakeholders must monitor pending updates to REACH-aligned substance restrictions and decide whether to reformulate domestically or import pre-certified European resin systems.
Market Dynamics
ANVISA's progressive tightening of VOC emission thresholds is forcing wholesale reformulation of solvent-based adhesive portfolios across Brazilian manufacturing corridors, compressing margins for legacy suppliers while opening technical advisory revenue streams for compliant chemistries.
Growth Catalysts
- Construction sector procurement:Federal housing programs and commercial buildouts in São Paulo state's industrial corridor are expanding adhesive volumes for structural panel bonding and flooring installation.
- ANVISA environmental compliance:New substance registration protocols are accelerating substitution of high-VOC solvent systems with waterborne and reactive hot-melt alternatives in packaging applications.
- Polyurethane chemistry platforms:Flexible packaging converters and automotive interior assemblers are adopting moisture-cure and two-component systems for dissimilar-substrate joining.
Market Restraints
- Petrochemical feedstock volatility:Crude-derived polyols and isocyanates expose formulators to margin compression when naphtha cracking economics fluctuate.
- Import dependency for specialty resins:Pre-certified European epoxy and acrylic systems concentrate supply risk with Rotterdam-Antwerp corridor shippers subject to currency and logistics friction.
- Cure temperature limitations:Heat-sensitive substrates in electronics and medical device assembly restrict high-performance adhesive selection, capping premium chemistry penetration.
Strategic Opportunities
- Minas Gerais distributor networks:Underpenetrated construction adhesive channels outside São Paulo's saturated corridor offer first-mover positioning for technical service-heavy suppliers.
- Food and beverage export packaging:Extended shelf-life requirements for protein and processed goods shipments are driving specification upgrades to barrier-grade hot-melt systems.
- REACH-aligned substance pre-certification:Early adoption of EU-equivalent safety data sheet protocols positions domestic formulators for accelerated ANVISA approval timelines.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise in reactive polyurethane and UV-cure systems concentrates with retired petrochemical sector veterans, constraining R&D pipeline velocity.
- INMETRO certification timelines:Performance testing protocols for infrastructure and defense procurement channels extend qualification cycles, freezing supplier switching decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Adhesives Market |
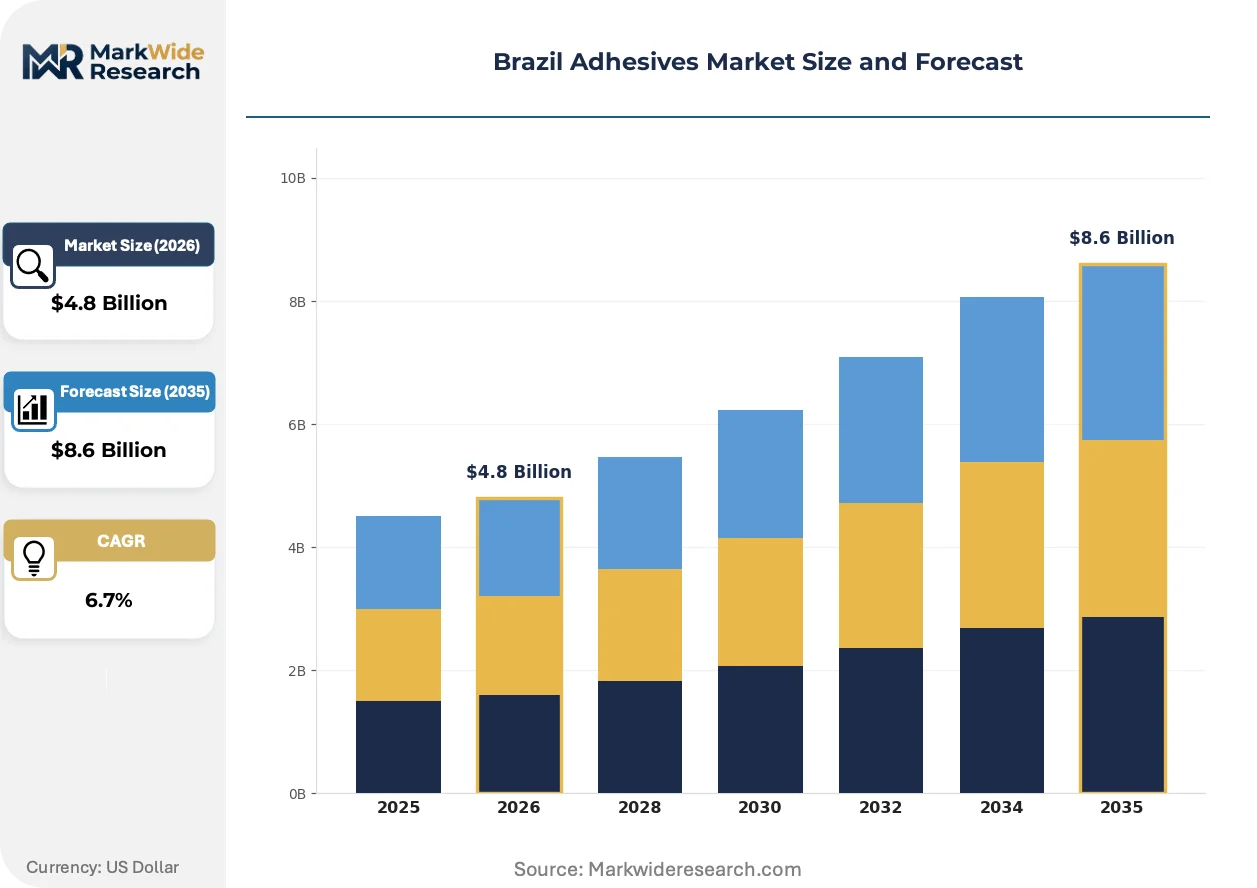
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone End User: Construction, Automotive, Electronics, Woodworking Application: Packaging, Coating, Bonding, Assembly Distribution Channel: Direct Sales, Distributors, Retail, E-Commerce |
| Companies Covered | Dow, BASF SE, Henkel AG & Co. KGaA, Arkema, Sika AG, 3M, Artecola Química, Avery Dennison Corporation, H.B. Fuller Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Adhesives Market Strategic Shifts
Waterborne and reactive hot-melt chemistries are displacing legacy solvent systems as the dominant technical pivot, while regulatory compliance services and formulation customization emerge as value-capture mechanisms beyond commodity resin sales.
Hybrid epoxy-acrylic systems is integrating the structural load-bearing properties of epoxies with the rapid processing speeds of UV-cure acrylics. Automotive assembly plants in São Paulo's ABC industrial zone are piloting these chemistries for structural bonding in lightweight vehicle architectures. This convergence is integrating technical advisory and application engineering into core supplier relationships, compressing pure resin trading margins.
ANVISA's alignment with REACH substance restriction schedules is accelerating disclosure requirements for adhesive formulations sold in Brazil. Industrial users must now document complete supply chain substance inventories, increasing compliance overhead for imported European systems. Food-contact packaging segments are responding fastest, shifting specification authority from procurement to regulatory affairs functions.
Buyers are consolidating adhesive specifications around fewer qualified suppliers capable of delivering integrated formulation, application equipment, and technical service bundles. Large construction groups and packaging converters are displacing fragmented spot purchasing with multi-year framework agreements. This concentration is most visible in Rio de Janeiro state's commercial buildout sector, where general contractors now mandate single-source adhesive accountability for structural warranty compliance.
Brazil Adhesives Market Segmentation
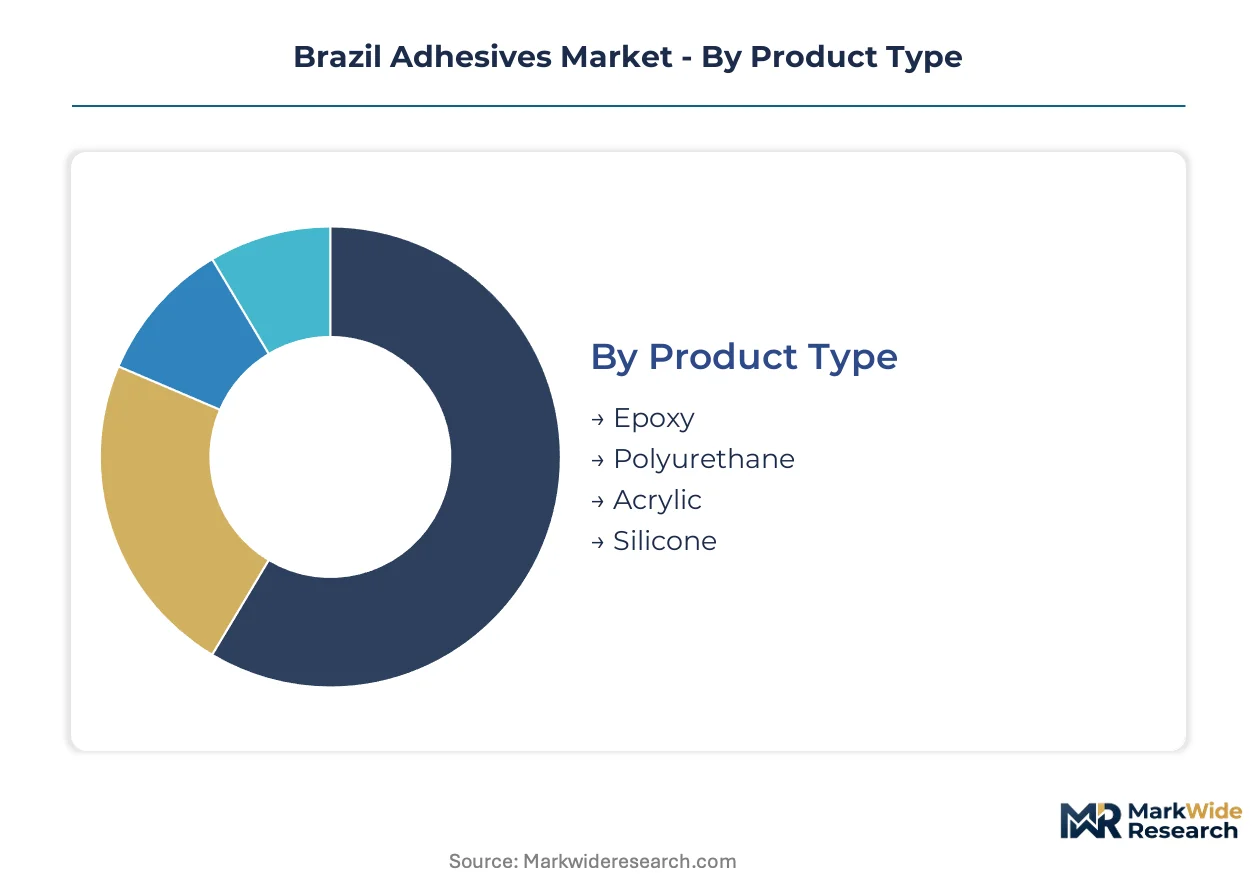
Brazilian adhesive procurement splits across formulation chemistry, end-use industry, and channel configuration, with each axis revealing distinct margin profiles and regulatory exposure. Suppliers must align technical capabilities against these dimensions to capture value beyond commodity resin trading.
Product Type:
Polymer chemistry concentration determines raw material sourcing strategy and reformulation liability under ANVISA's tightening VOC protocols.
- Epoxy:Two-part thermosetting systems built from bisphenol-A and amine hardeners deliver shear strength exceeding 20 MPa for structural panel bonding. São Paulo state's heavy industrial corridor absorbs the majority of Brazilian epoxy volume for infrastructure and defense procurement channels where INMETRO certification is mandatory. Load-bearing specifications command price premiums but cure temperature requirements restrict adoption in heat-sensitive assemblies.
- Polyurethane:Moisture-cure and two-component systems dominate flexible packaging converters and automotive interior assembly in the ABC industrial zone. Dissimilar-substrate joining capabilities—metal to plastic, glass to composite—are displacing mechanical fasteners in lightweight vehicle architectures. This chemistry platform is expanding most quickly as waterborne formulations satisfy ANVISA emission thresholds.
- Acrylic:UV-cure and cyanoacrylate variants serve electronics bonding and transparent-display lamination where optical clarity requirements limit substitution.
- Silicone:Room-temperature-vulcanizing formulations seal HVAC ducting and medical device housings requiring biocompatibility certification.
Epoxy absorbs the bulk of installed capacity; polyurethane is expanding most quickly.
End User:
Demand concentration varies sharply across Brazilian states, with procurement authority shifting between engineering, regulatory affairs, and purchasing functions.
- Construction:Federal housing programs and commercial buildouts in Minas Gerais and Rio de Janeiro drive structural panel adhesive consumption. General contractors now mandate single-source accountability for warranty compliance, consolidating specifications around fewer qualified suppliers.
- Automotive:Assembly plants in São Paulo's ABC zone pilot hybrid epoxy-acrylic systems for lightweight vehicle bonding. Technical advisory and application engineering are compressing pure resin trading margins as OEMs demand integrated service bundles.
- Electronics:Heat-sensitive substrate restrictions cap premium chemistry penetration in PCB and medical device assembly.
- Woodworking:Furniture manufacturers in Rio Grande do Sul specify PVAc and hot-melt systems for panel lamination and edge banding.
Construction claims the largest share of domestic formulation volume; automotive is climbing the fastest as OEMs redesign vehicle platforms.
Application:
Performance specifications and cure mechanisms segment adhesive deployment across manufacturing stages.
- Packaging:Barrier-grade hot-melt systems serve food and beverage exporters navigating extended shelf-life requirements for protein and processed goods shipments. Specification authority has shifted from procurement to regulatory affairs functions under ANVISA's REACH-aligned disclosure protocols.
- Coating:Protective films and corrosion barriers protect infrastructure steel in coastal environments subject to INMETRO performance testing.
- Bonding:Structural and semi-structural joints replace welds and rivets in heavy equipment manufacturing.
- Assembly:Multi-substrate joining enables modular construction and appliance manufacturing.
Packaging dominates adhesive consumption by unit volume; bonding applications are gaining share fastest as infrastructure investment accelerates.
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and geographic penetration strategy.
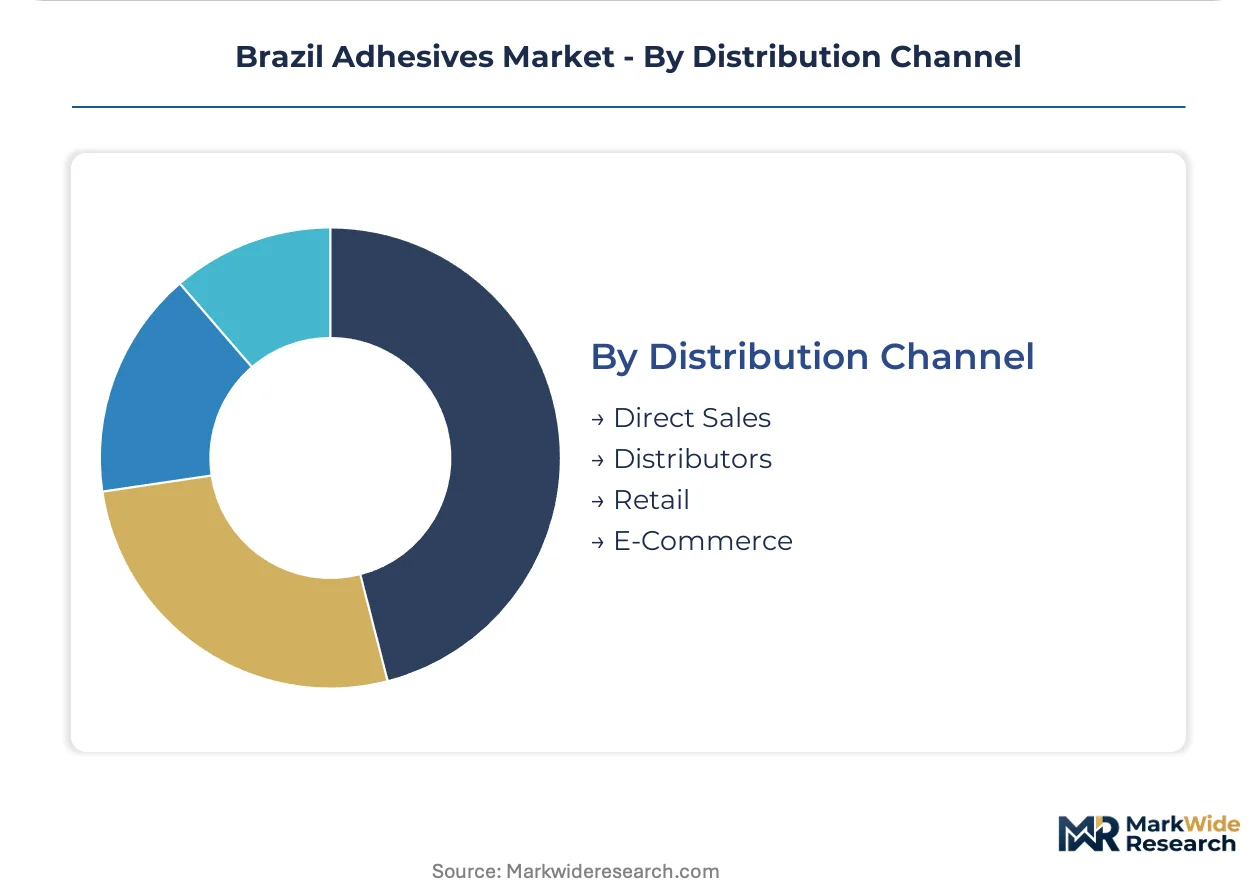
- Direct Sales:Large construction groups and packaging converters negotiate multi-year framework agreements with integrated formulation, equipment, and technical service bundles. Rio de Janeiro's commercial buildout sector exhibits the most visible concentration toward direct supplier relationships.
- Distributors:Henkel and regional players maintain coverage in Minas Gerais and Rio de Janeiro through technical service-heavy distributor partnerships. Underpenetrated channels outside São Paulo's saturated corridor offer first-mover positioning.
- Retail:Hardware and professional trade outlets serve small contractors and maintenance operations.
- E-Commerce:Digital procurement platforms are emerging for standardized formulations and replenishment purchasing.
Direct sales capture the highest-margin procurement; distributor networks are expanding most quickly as suppliers push beyond São Paulo's industrial corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's ABC industrial corridor anchors Brazilian adhesive demand through automotive assembly plants and flexible packaging converters. Federal housing programs and infrastructure procurement extend consumption into Minas Gerais and Rio de Janeiro manufacturing zones.
São Paulo
Automotive OEMs in the ABC zone pilot hybrid epoxy-acrylic systems for lightweight vehicle architectures. ANVISA's REACH-aligned substance disclosure protocols accelerate reformulation timelines for suppliers serving this corridor. São Paulo city's packaging converters drive specification upgrades to barrier-grade hot-melt systems for protein export shipments.
Minas Gerais
Federal housing programs expand structural panel adhesive consumption for residential buildouts. INMETRO certification requirements for infrastructure procurement extend qualification cycles for epoxy suppliers. Belo Horizonte's commercial construction sector consolidates specifications around single-source adhesive accountability for warranty compliance.
Rio de Janeiro
General contractors mandate integrated formulation and technical service bundles for structural bonding applications. ANVISA's tightening VOC thresholds compress margins for legacy solvent-based portfolios. The state's coastal infrastructure projects absorb certified epoxy volumes for corrosion-resistant steel bonding in marine environments.
Rio Grande do Sul
Furniture manufacturers specify PVAc and hot-melt systems for panel lamination and edge banding operations. The state's wood processing cluster drives demand for woodworking-grade adhesives with rapid cure characteristics. Porto Alegre's industrial zone hosts distributors extending coverage beyond São Paulo's saturated corridor.
Paraná
Agricultural machinery assembly plants adopt polyurethane systems for dissimilar-substrate joining in equipment manufacturing. Curitiba's packaging sector responds to ANVISA compliance deadlines with waterborne formulation conversions. The state's underpenetrated distributor channels offer first-mover positioning for technical service-heavy suppliers.
Brazil Adhesives Market Competitive Environment
Capital-heavy petrochemical producers compete with asset-light specialty formulators across Brazilian adhesive procurement. Dow and BASF SE anchor the integrated resin manufacturing tier with captive polyol and isocyanate supply chains. Mid-scale formulators concentrate technical advisory capabilities around application engineering and ANVISA compliance services. Competitive dynamics center on backward integration into raw material production and geographic expansion through Minas Gerais distributor partnerships.
Among Germany-based chemical conglomerates, Henkel AG & Co. KGaA and BASF SE exemplify the technical service-heavy archetype with construction-sector distributor networks spanning Rio de Janeiro. Sika AG represents the specialty chemicals tier with infrastructure-focused certification capabilities. Swiss-based Sika AG and US-based H.B. Fuller Company occupy positions emphasizing formulation customization over commodity resin trading. Dow anchors the integrated petrochemical vector with polyurethane research infrastructure serving automotive assembly lines.
| Leading Market Players |
|---|
| Dow |
| BASF SE |
| Henkel AG & Co. KGaA |
| Arkema |
| Sika AG |
| 3M |
| Artecola Química |
| Avery Dennison Corporation |
| H.B. Fuller Company |
| Others |
Value Chain & Pricing Dynamics
Formulation chemist scarcity in São Paulo state's ABC industrial corridor widens spreads between premium technical-service bundles and economy-grade commodity resins. ANVISA compliance investments concentrate pricing power with suppliers employing in-house regulatory affairs teams, while labor-cost differentials between the southeastern manufacturing zone and peripheral states compress margins for undifferentiated waterborne formulations.
Pricing Analysis
Value-based pricing anchored to production-line uptime and defect-rate reduction commands premiums in automotive assembly contracts. Three-tier pricing structure across premium, standard, and economy levels separates INMETRO-certified structural epoxies from general-purpose PVAc woodworking adhesives. Price differentiation hinges on certification grade and technical advisory bundling. Cost compression in solvent-based portfolios is intensifying because ANVISA's VOC thresholds force wholesale reformulation. Small contractors and maintenance operations exhibit highest price sensitivity; large construction groups negotiating multi-year framework agreements show lowest.
Supply Chain Analysis
Domestic-content mandates under Brazil's industrial policy frameworks reshape sourcing strategies for imported epoxy hardeners and specialty isocyanates. Raw material supply draws from the United States, Germany, and China for pre-certified resin systems, with Rotterdam-Antwerp corridor shippers concentrating import dependency. Naphtha-derived polyols and aromatic amines feed formulation operations. Single-source vulnerability runs through European specialty resin channels subject to currency friction. Distribution runs through technical service-heavy distributor partnerships in Minas Gerais and direct sales to large packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Brazil adhesives market functions as a vertical-integration race where captive polyol production and in-house regulatory certification capabilities determine margin capture. Backward integration into petrochemical feedstocks represents the decisive upstream lever separating integrated producers from asset-light formulators.
For Market Incumbents: Deepen polyurethane research infrastructure to anchor premium bonding solutions as hybrid epoxy-acrylic systems displace legacy chemistries in lightweight vehicle architectures. Expand INMETRO certification capabilities to extend infrastructure procurement channel access. Consolidate distributor partnerships in underpenetrated Minas Gerais construction corridors before regional formulators capture technical advisory revenue streams. For New Entrants and Emerging Players: The price-point gap between Henkel-grade technical service bundles and commodity PVAc woodworking adhesives creates entry space for mid-tier suppliers. Target Rio Grande do Sul furniture manufacturers with rapid-cure hot-melt systems specified for panel lamination. Lead with ANVISA pre-certification services to accelerate approval timelines for food-contact packaging converters shifting specification authority to regulatory affairs functions. For Investors and Strategic Acquirers: Re-rating potential sits with specialty formulators possessing REACH-aligned safety data sheet protocols given ANVISA's accelerating alignment with EU substance restriction schedules. Long-term viability favors mid-scale Brazilian players with captive distributor networks in southeastern manufacturing zones. Monitor INMETRO certification queue lengths as inflection indicator for infrastructure procurement channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Captive isocyanate supply shields Dow and BASF from naphtha cracking volatility. |
| ANVISA Pre-Certification Investment | Early REACH-aligned disclosure protocols accelerate approval for food-contact packaging segments. |
| Minas Gerais Distributor Acquisition | Technical service-heavy partnerships extend coverage beyond São Paulo's saturated corridor. |
| Hybrid Chemistry R&D Partnership | Epoxy-acrylic convergence captures lightweight vehicle bonding specifications in ABC zone. |
| Long-Term Framework Agreements | Multi-year contracts with Rio de Janeiro general contractors lock in structural warranty compliance. |
Study Parameters
Independent corroboration across formulation chemists at São Paulo automotive plants, procurement leads at flexible packaging converters, and regulatory affairs directors at food-contact manufacturers underwrites the qualitative findings. Secondary validation drew from ANVISA substance registration databases, INMETRO certification records, and Brazilian customs trade data for resin system imports. Bottom-up demand modeling triangulated against top-down petrochemical feedstock consumption estimates.
Comparable-period anchoring linked projection assumptions to historical VOC regulatory phase-in timelines and infrastructure procurement cycles across the analysis window. Segmentation dimensions spanned polymer chemistry platform, end-use industry vertical, and distribution channel configuration. CAGRs derived from elasticity-adjusted demand curves incorporating construction sector investment patterns and automotive platform redesign schedules. Forecast inputs included ANVISA compliance cost trajectories and polyurethane chemistry adoption rates.
Inputs from primary interviews and secondary regulatory filings were available through the study window; gaps in real-time distributor margin data introduce uncertainty bands around channel expansion assumptions. Forecasts reflect documented assumptions about ANVISA timeline adherence and petrochemical feedstock price stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Middle-East and Africa Contact Adhesives Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
Asia-Pacific Waterborne Adhesives Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Bio-Based Adhesives Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
Removable Adhesive Market
Adhesives & Sealants
Asia-Pacific Cyanoacrylate Adhesives Market
Adhesives & Sealants
Windscreen Adhesive Market