
 Diethyl Phthalate Market | 2026-2036
Diethyl Phthalate Market Size, Share, and Industry Trends Forecast 2026-2036
Diethyl Phthalate Market Outlook
Technical-grade formulation services is rebalancing what chemical suppliers sell, shifting transactions from bulk commodity orders to specification-driven contracts. Eastman Chemical Company leverages its integrated phthalate and non-phthalate portfolio to sustain supply flexibility across regulatory regimes. BASF SE anchors European demand through REACH-compliant production networks. Mitsubishi Chemical Corporation competes on high-purity grades for sensitive applications.
Diethyl phthalate is a colorless, oily liquid ester produced through esterification of phthalic anhydride with ethanol, characterized by a molecular weight of 222.24 g/mol and a boiling point near 298°C, functioning primarily as a plasticizer and solvent in industrial and consumer formulations. Plasticizers command the dominant volume position as mature demand from flexible PVC applications stabilizes, while personal care applications face contraction from clean-label substitution. Coatings and adhesives represent faster-growing segments where specialty grades command margin premiums over commodity volumes.
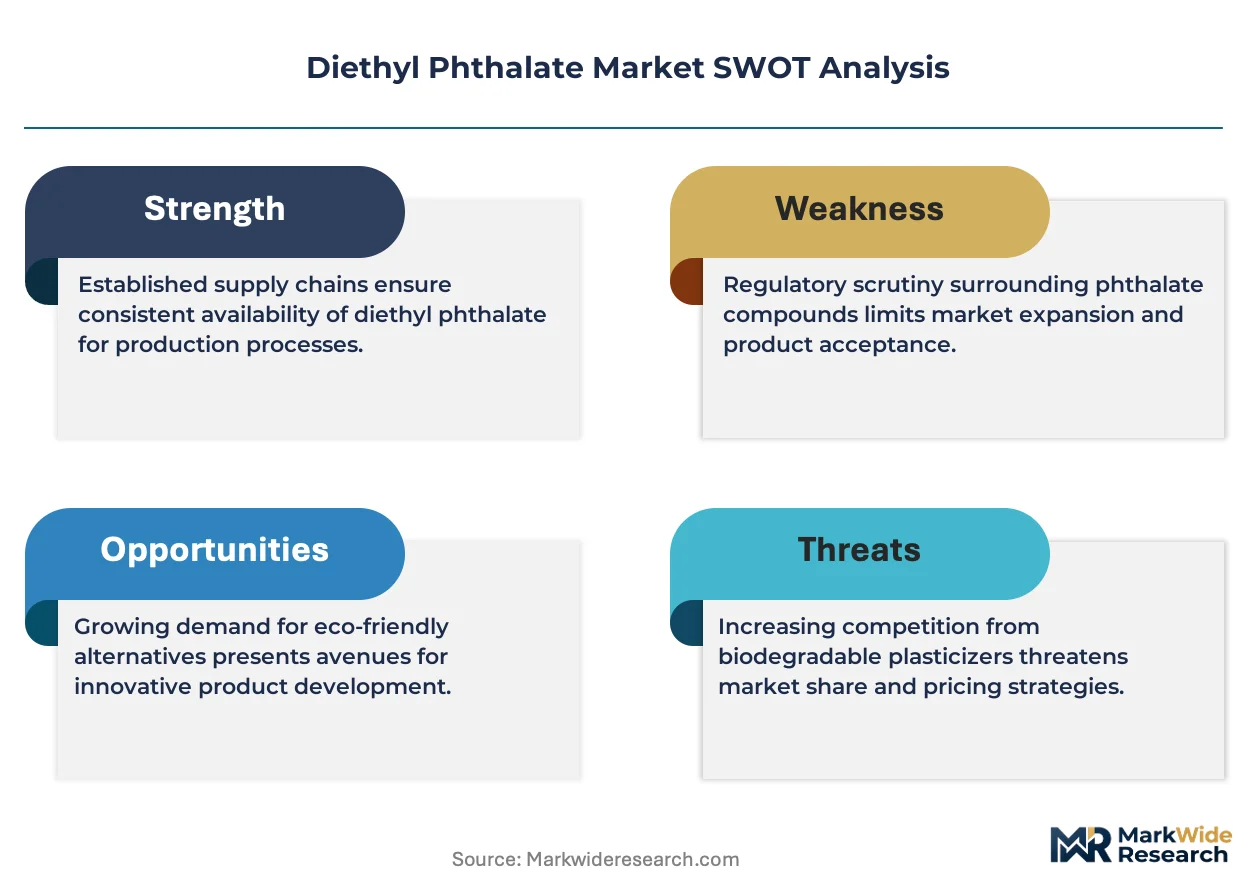
The EPA maintains active screening of phthalates under the Toxic Substances Control Act, while REACH authorization requirements in Europe restrict certain end-use applications, and China's MEE enforces emission standards affecting phthalate manufacturing facilities. These frameworks fragment market access by purity grade and application category. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which product grades retain commercial viability.
Market Dynamics
REACH authorization requirements and EPA screening criteria are bifurcating product specifications, forcing specialty chemical producers to maintain parallel formulation streams for compliant and restricted end-uses.
Growth Catalysts
- Flexible PVC stabilization:Mature construction and automotive sectors in China and India sustain baseline plasticizer consumption despite regulatory headwinds in Western markets.
- REACH-compliant grade specialization:European chemical producers capture margin premiums by certifying high-purity diethyl phthalate for pharmaceutical and food-contact applications exempt from authorization restrictions.
- Coatings solvent substitution:Industrial formulators in Germany and Japan deploy diethyl phthalate as a cost-effective alternative to restricted glycol ethers in protective coatings.
Market Restraints
- Ethanol feedstock volatility:Bioethanol diversion to fuel blending and synthetic ethanol price swings compress esterification margins for commodity-grade producers.
- Phthalic anhydride supply concentration:Chinese and South Korean producers control over half of global anhydride capacity, exposing downstream formulators to regional production disruptions.
- Clean-label substitution acceleration:Personal care brands reformulate with citrate esters and bio-based alternatives as consumer scrutiny intensifies.
Strategic Opportunities
- Pharmaceutical-grade expansion:Indian and Chinese API manufacturers seek compliant excipient suppliers as domestic regulatory inspection capacity expands.
- Adhesive specialty formulations:Pressure-sensitive tape and label producers in Southeast Asia adopt specification-driven solvent systems for electronics assembly.
- MEE emission standard retrofit demand:Chinese manufacturing facilities require upgraded recovery systems, creating service revenue for engineering firms with phthalate process expertise.
Industry Challenges
- Analytical chemist scarcity:Specialized chromatography and impurity profiling skills required for REACH dossier maintenance command premium compensation.
- Multi-jurisdiction certification synchronization:Simultaneous EPA, ECHA, and NMPA registration timelines strain regulatory affairs bandwidth.
- Legacy equipment reconfiguration:Batch esterification assets require substantial capital deployment to meet MEE and EU Industrial Emissions Directive standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diethyl Phthalate Market |
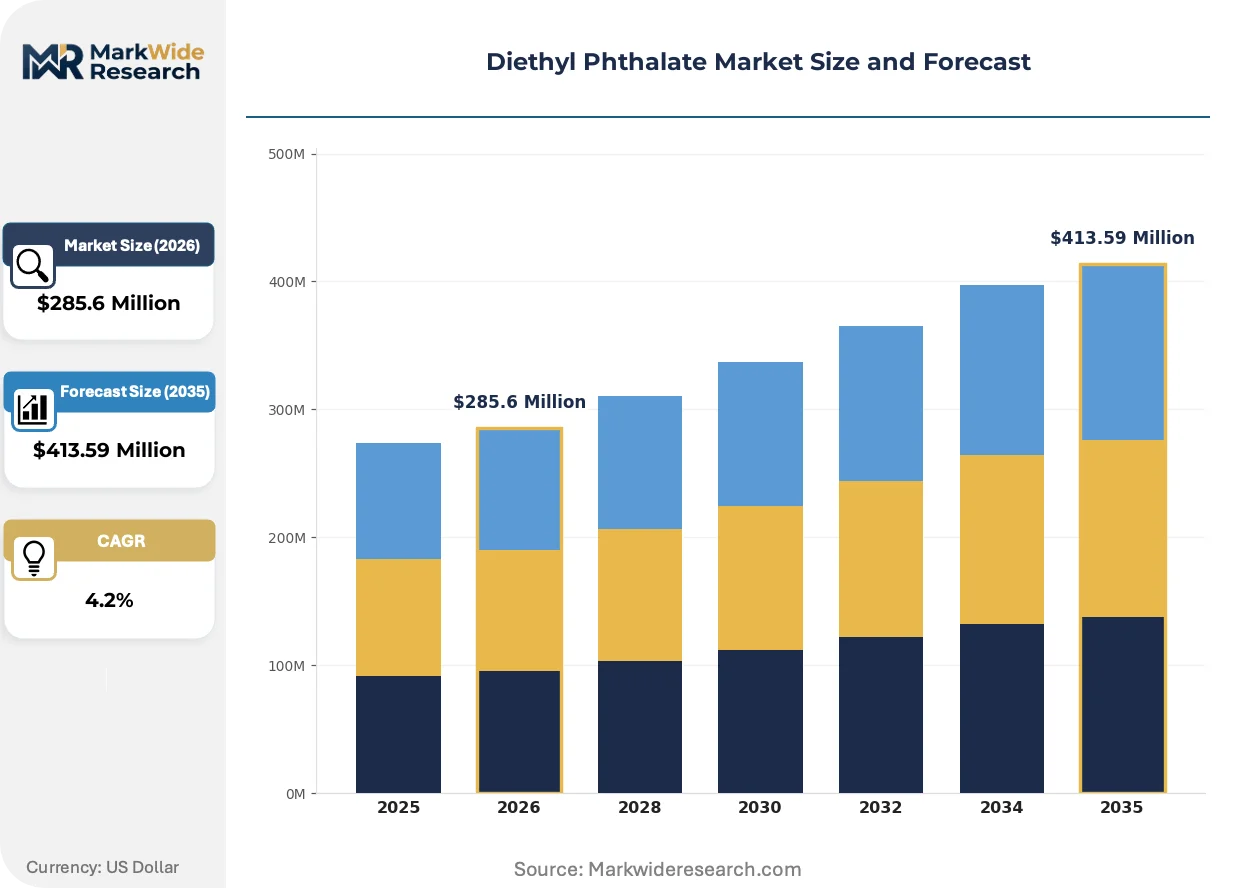
| Market Size in 2026 | $285.6 Million |
| Market Size in 2035 | $413.59 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Coatings, Adhesives, Personal Care End Use Industry: Consumer Goods, Automotive, Textiles, Electronics Form: Liquid, Solid, Gel, Powder Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesalers |
| Companies Covered | Mitsubishi Chemical Corporation, Aekyung Petrochemical, Eastman Chemical Company, Merck KGaA, Polynt Group, BASF SE, LG Chem, Thirumalai Chemicals Ltd, ExxonMobil Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diethyl Phthalate Market Strategic Shifts
Formulation science is fragmenting into purity-tiered product lines as regulatory thresholds harden, while process intensification and bio-based feedstocks reshape production economics.
Continuous flow esterification technology is modularizing plant design for mid-scale producers. Specialty chemical engineers in the Netherlands and Switzerland deploy skid-mounted reactor systems that slash batch cycle times. This architecture is compressing capital barriers for regional entrants targeting pharmaceutical-grade certification.
REACH sunset date extensions for specific authorization uses are creating transitional demand windows. ECHA's staggered phase-out schedule permits continued diethyl phthalate deployment in certain industrial adhesives through controlled supply chains. German and French formulators are securing downstream user exemptions while accelerating alternative testing.
Specification-driven procurement is consolidating buyer power among multinational personal care and pharmaceutical firms. Tier-one suppliers now contract directly for certified purity grades, bypassing traditional distributor channels. This pattern is most visible in North American and Western European markets where audit requirements exceed regional producer capabilities.
Diethyl Phthalate Market Segmentation
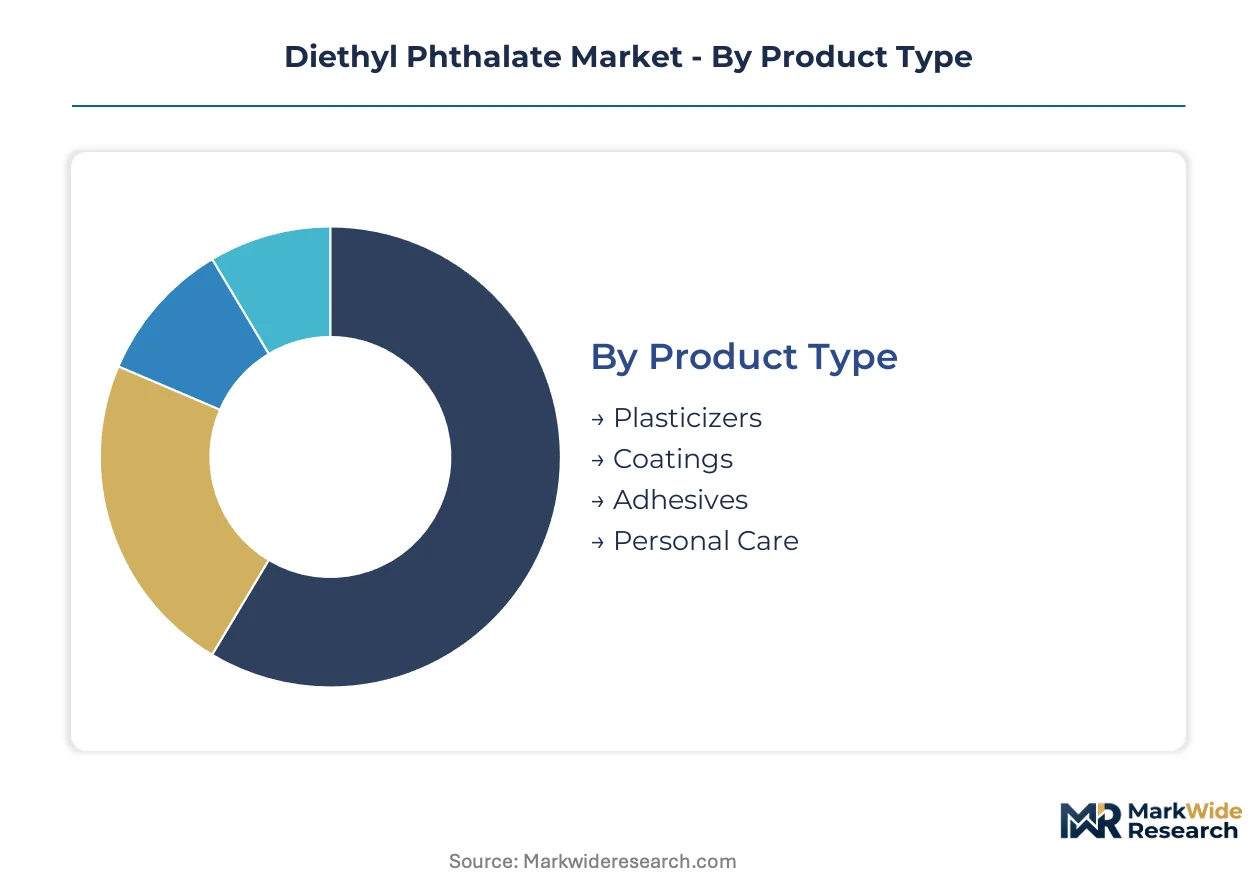
Diethyl phthalate segmentation reveals how regulatory pressure fragments demand across purity grades and application thresholds. Specification tiers now determine commercial viability more than volume scale alone.
Product Type:
Plasticizers dominate tonnage while specialty applications capture margin premiums through certification requirements.
- Plasticizers:High-volume ester formulations serve flexible PVC manufacturing for construction and automotive components. Demand concentrates in China and India where PVC consumption sustains baseline volumes despite REACH authorization pressures in Europe.
- Coatings:Solvent-grade diethyl phthalate replaces restricted glycol ethers in protective industrial formulations. German and Japanese formulators drive adoption as a cost-compliant alternative under evolving EPA screening criteria.
- Adhesives:Pressure-sensitive and industrial bonding applications require controlled volatility specifications.
- Personal Care:Clean-label substitution with citrate esters and bio-based alternatives accelerates contraction in fragrance and cosmetic solvent applications.
Mature deployment sits with Plasticizers. Newer deployment is concentrated in Coatings.
End Use Industry:
Automotive and electronics applications favor specification-driven procurement over commodity sourcing.
- Consumer Goods:Flexible packaging and household products sustain steady plasticizer consumption. Indian manufacturing clusters absorb technical-grade volumes for domestic flexible PVC articles.
- Automotive:Interior trim and underhood applications demand heat-stable plasticizer performance. Tier-one suppliers in Germany certify high-purity grades for cabin air quality compliance.
- Textiles:Fabric coatings and synthetic leather finishing use solvent-grade formulations.
- Electronics:Adhesive and encapsulant applications in Southeast Asian assembly operations require ultra-low moisture specifications.
Specification intensity peaks in Automotive. Volume scale anchors Consumer Goods.
Form:
Liquid dominance reflects esterification economics while solid and gel variants serve niche delivery requirements.
- Liquid:Standard esterification output serves bulk plasticizer and solvent applications. Chinese producers optimize continuous flow systems for technical-grade liquid output.
- Solid:Microencapsulated and prilled forms enable controlled-release applications in specialty adhesives.
- Gel:Thickened formulations support precision application in electronics assembly.
- Powder:Spray-dried grades facilitate dry-blend compounding in PVC masterbatch production.
Process economics favor Liquid. Functional differentiation drives Solid and Gel adoption.
Distribution Channel:
Direct procurement consolidates among multinational formulators while regional distributors serve fragmented demand.
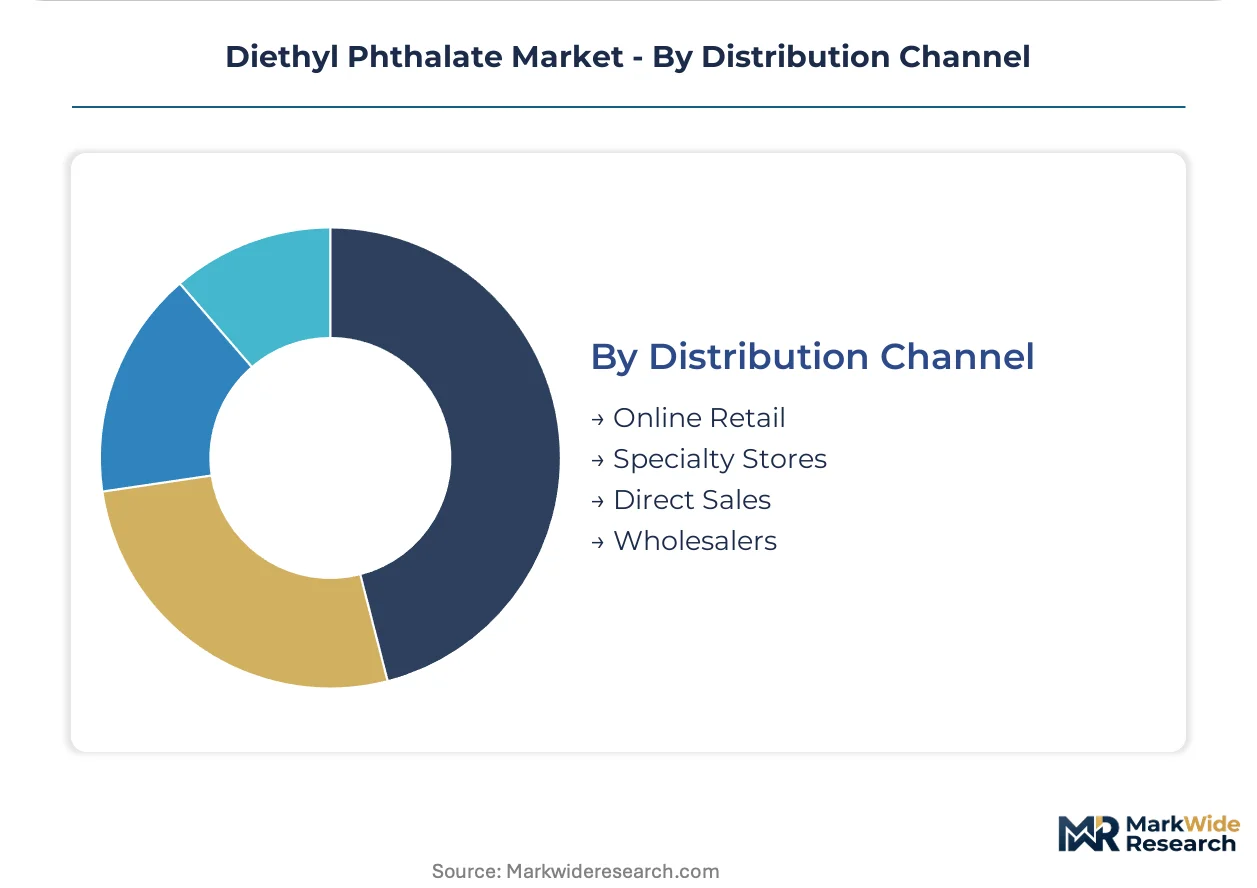
- Direct Sales:Tier-one personal care and pharmaceutical firms contract certified purity grades through audited supply chains. North American and Western European buyers bypass traditional distribution for REACH-compliant documentation.
- Specialty Stores:Regional chemical distributors serve mid-scale coatings and adhesive formulators with technical support.
- Online Retail:E-procurement platforms facilitate small-volume laboratory and pilot-scale orders.
- Wholesalers:Bulk commodity volumes move through established chemical trading networks in China and India.
Certification requirements concentrate procurement through Direct Sales. Price-sensitive volume flows through Wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor global diethyl phthalate manufacturing capacity, with the Yangtze River Delta housing the densest concentration of esterification facilities serving flexible PVC and coatings demand.
China
Shandong and Jiangsu provinces operate the largest phthalic anhydride derivative clusters. The Ministry of Ecology and Environment enforces emission recovery mandates that force facility retrofits. Ningbo and Taizhou chemical parks attract pharmaceutical-grade investment as domestic API producers seek compliant excipient supply.
India
Maharashtra and Gujarat absorb technical-grade volumes for domestic flexible packaging and automotive components. The Bureau of Indian Standards monitors plasticizer purity thresholds for food-contact applications. Ankleshwar and Vapi industrial corridors host specialty chemical formulators adapting REACH documentation for export markets.
Germany
Ludwigshafen and Leverkusen chemical complexes sustain high-purity production for pharmaceutical and automotive cabin applications. ECHA authorization requirements restrict certain industrial end-uses while exempting certified medical grades. Bavarian coatings formulators deploy diethyl phthalate as a glycol ether substitute under EPA-aligned screening protocols.
United States
Gulf Coast petrochemical corridors supply ethanol feedstock for esterification operations serving construction and automotive plasticizer demand. The EPA maintains active TSCA screening of phthalate substances with evolving hazard criteria. Texas and Louisiana specialty chemical producers balance domestic formulation against export certification burdens.
Japan
Chiba and Yokkaichi industrial zones concentrate high-purity solvent production for electronics adhesive applications. METI chemical substance regulations align with REACH thresholds for import-export consistency. Osaka-based formulators specification-grade product for Southeast Asian electronics assembly transfer.
Diethyl Phthalate Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a bifurcated structure where integrated petrochemical groups control feedstock economics while regional formulators specialize in certification-heavy niche grades. The vendor base separates into three archetypes: multinational chemical conglomerates with backward integration into phthalic anhydride, mid-scale regional esterification specialists, and pharmaceutical-grade purity houses serving audit-intensive buyer segments. Dominant competitive moves include portfolio diversification into non-phthalate plasticizers and geographic expansion through distributor partnerships in emerging manufacturing clusters.
Among diversified chemical conglomerates, Eastman Chemical Company and BASF SE exemplify integrated producers with parallel phthalate and non-phthalate portfolios. Mitsubishi Chemical Corporation occupies a position within the high-purity specialty tier, representing the concentration of Japanese producers in electronics and pharmaceutical-grade solvent markets. These three entities anchor distinct competitive vectors: feedstock-integrated scale, regulatory compliance infrastructure, and specification-driven purity certification.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Aekyung Petrochemical |
| Eastman Chemical Company |
| Merck KGaA |
| Polynt Group |
| BASF SE |
| LG Chem |
| Thirumalai Chemicals Ltd |
| ExxonMobil Chemical |
| Others |
Value Chain & Pricing Dynamics
REACH-compliant procurement mandates from European pharmaceutical and automotive OEMs force specialty chemical producers to maintain dual-grade production streams, compressing margins on technical-grade volumes while extracting premiums from certified purity tiers.
Pricing Analysis
Margin tightening in commodity-grade plasticizers reflects ethanol feedstock volatility and phthalic anhydride supply concentration in East Asian production clusters. Three-tier pricing structure across pharmaceutical-grade, REACH-compliant industrial, and technical-grade volumes stratifies buyer segments by certification burden. Cost-down pressure on technical-grade volumes accelerates because Indian and Chinese flexible PVC manufacturers prioritize volume procurement over specification documentation. Pharmaceutical formulators exhibit lowest price sensitivity due to excipient validation costs, while coatings distributors in Southeast Asia drive hardest bargain negotiations.
Supply Chain Analysis
Pharmaceutical-grade certification requirements gate supply chain participation through ECHA dossier maintenance and FDA Type II drug master file submissions. Manufacturing gravity centers on China, India, and Germany, with Jiangsu province and Ludwigshafen chemical complex anchoring distinct purity-tier production. Feedstock supply draws from Chinese and South Korean phthalic anhydride capacity, Brazilian bioethanol diversion, and synthetic ethanol price swings. Single-source vulnerability concentrates in phthalic anhydride intermediates, where regional production disruptions cascade downstream within weeks. Distribution runs through audited direct sales channels for certified grades and established chemical trading networks for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory authorization pressures and feedstock cost volatility are consolidating competitive positions around capital-intensive purity-tier specialists, marginalizing batch-esterification operators lacking certification infrastructure.
For Market Incumbents: Anticipate REACH sunset date extensions creating transitional demand windows by securing downstream user exemptions for adhesive applications while accelerating non-phthalate portfolio diversification. Eastman Chemical Company and BASF SE demonstrate defensive positioning through integrated phthalate and non-phthalate production networks. Capacity addition in Ningbo and Taizhou chemical parks captures pharmaceutical-grade growth as Chinese API producers seek compliant domestic excipient supply. For New Entrants and Emerging Players: Mid-scale Indian API manufacturers represent an underserved buyer archetype seeking compliant excipient suppliers as domestic regulatory inspection capacity expands. Specialty adhesive formulators in Vietnam and Indonesia offer penetrable entry points through specification-driven solvent systems for electronics assembly. Continuous flow esterification technology licensing from Dutch and Swiss engineering firms enables capital-efficient pharmaceutical-grade certification without legacy batch asset reconfiguration. For Investors and Strategic Acquirers: The window for entry favors regional purity houses with established ECHA dossiers and FDA master file documentation. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale, positioning certified-grade specialists for sustained margin capture. Acquisition targets should demonstrate active pharmaceutical ingredient excipient supply relationships and REACH-compliant production networks. The signal to watch is ECHA authorization list expansion, which would accelerate clean-label substitution and compress technical-grade valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phthalic Anhydride | Captive feedstock supply insulates Eastman and BASF from Chinese production disruption exposure. |
| Pharmaceutical-Grade Certification Investment | ECHA dossier maintenance and FDA Type II filings unlock excipient supply contracts with Merck KGaA and Mitsubishi. |
| Continuous Flow Esterification Deployment | Skid-mounted reactor systems from Dutch engineering partners slash batch cycle times for mid-scale entrants. |
| Long-term Supply Agreement with API Manufacturers | Direct procurement contracts with Indian and Chinese pharmaceutical producers bypass distributor margin extraction. |
| Joint Venture in Yangtze River Delta Chemical Parks | Ningbo and Taizhou partnerships access MEE-compliant infrastructure for domestic pharmaceutical-grade output. |
Study Parameters
Multi-period observation of ECHA authorization timelines, EPA TSCA screening criteria, and MEE emission enforcement anchored the trend analysis, supplemented by interviews with plant managers at esterification facilities, procurement leads at flexible PVC compounders, distribution channel partners in Indian chemical trading networks, and technical R&D directors at specialty adhesive formulators. Secondary validation incorporated customs and trade data from Chinese and Indian port authorities, Cefic plasticizer market reports, and SEC 10-K filings from diversified chemical conglomerates. Bottom-up volume estimates from regional production clusters triangulated against top-down demand projections from end-use industry consumption patterns.
Segment-weighting across grade tier, end-use industry, and regional production hub dimensions structured the analytical framework across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and feedstock cost regime shifts. Industry-specific forecast inputs included phthalic anhydride capacity utilization rates from Chinese producers and bioethanol diversion trends from Brazilian fuel blending mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization list expansion, EPA hazard criteria revision, and MEE emission standard tightening. Model outputs reflect assumptions regarding regulatory phase-out schedules and substitute technology penetration rates in personal care applications. A model refresh is warranted upon material change in ECHA sunset date determinations or Chinese environmental enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Chemical Synthesizer Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market
Chemical Intermediates
2-Acetylthiophene Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
Organometallic Compounds Market
Chemical Intermediates
Bromate Substitute Market
Chemical Intermediates
Dimethyl Dicarbonate Market
Chemical Intermediates
Cytosine Market
Chemical Intermediates
United States Cellulose Acetate Market
Chemical Intermediates
3-Chloropropionyl Chloride Market