
 Dural Sealant Market | 2026-2036
Dural Sealant Market Size, Share, and Industry Trends Forecast 2026-2036
Dural Sealant Market Intelligence
North American biologics manufacturers is realigning production priorities toward synthetic polymer platforms. Baxter leverages its hemostasis portfolio to sustain leadership in fibrin-based formats. Integra LifeSciences anchors its position through dural regeneration expertise that extends into adjacent neurosurgical categories. Stryker competes via channel density in hospital operating rooms across major metropolitan clusters.
Dural sealant comprises adhesive or barrier materials applied to achieve watertight closure of the dura mater following cranial or spinal procedures, typically formulated from fibrinogen-thrombin systems, synthetic polyethylene glycol polymers, or collagen matrices that polymerize in situ to prevent cerebrospinal fluid leakage. The product category spans fibrin-based formulations that dominate current surgical protocols, synthetic polymers that are gaining fastest traction due to elimination of human blood-derived components, and hydrogel variants that occupy premium positioning for complex reconstructive cases. Application segmentation reveals neurosurgery as the established volume leader while spine surgery represents the emerging growth corridor fueled by minimally invasive procedural expansion.
FDA oversight of combination biologic-device products shapes clinical trial requirements and labeling claims for manufacturers seeking 510(k) or PMA pathways. ISO 10993 biocompatibility standards and ASTM material specifications govern preclinical validation protocols that determine market access timelines. Stakeholders must monitor evolving reimbursement decisions from CMS and private payers that will determine whether advanced sealant premiums persist or compress toward commodity benchmarks.
Market Dynamics
Neurosurgical departments are consolidating purchasing power around sealant platforms that eliminate human blood-derived components, compressing procurement timelines and forcing manufacturers to revalidate synthetic polymer formulations against stricter biocompatibility benchmarks.
Growth Catalysts
- Minimally Invasive Spine Surgery Expansion:Ambulatory surgery centers are standardizing dural sealant protocols for microdiscectomy and laminectomy procedures, driving volume in synthetic polymer formats.
- FDA 510(k) Pathway Streamlining:The agency's evolving guidance on biologics-device combination products is accelerating premarket notification reviews for hydrogel-based sealants.
- Polyethylene Glycol Chemistry Maturation:Crosslinked PEG hydrogels are achieving polymerization kinetics that match fibrin-based setting times without immunogenicity risks.
Market Restraints
- Human Plasma Supply Concentration:Fibrinogen raw material sourcing clusters among fractionation facilities in the United States and Germany, creating batch-to-batch variability exposure.
- Reimbursement Compression:CMS hospital outpatient prospective payment system bundling is eroding standalone sealant premiums in cranial procedures.
- Synthetic Adhesion Limitations:PEG-based materials exhibit inferior tensile strength on moist dural surfaces compared to fibrin matrices, restricting adoption in complex reconstructive cases.
Strategic Opportunities
- Japan's Aging Surgical Population:METI reimbursement incentives for reduced-complication neurosurgery are creating entry points for premium synthetic sealants in Tokyo and Osaka academic centers.
- India's Tertiary Hospital Buildout:CDSCO fast-track pathways for Class C medical devices are shortening commercialization timelines for collagen-matrix sealants in Mumbai and Delhi private hospital chains.
- Bioresorbable Synthetic Convergence:Integration of tyrosine-derived polycarbonate scaffolds with in-situ hydrogel delivery is opening reconstructive dural repair applications beyond simple closure.
Industry Challenges
- ISO 10993-6 Implantation Study Timelines:Extended histopathological evaluation periods for chronic implantation testing are delaying PMA submissions for novel synthetic platforms.
- Sterile Manufacturing Scale-Up:Aseptic fill-finish capacity constraints at contract manufacturers are throttling commercial batch releases for hydrogel dual-syringe systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dural Sealant Market |
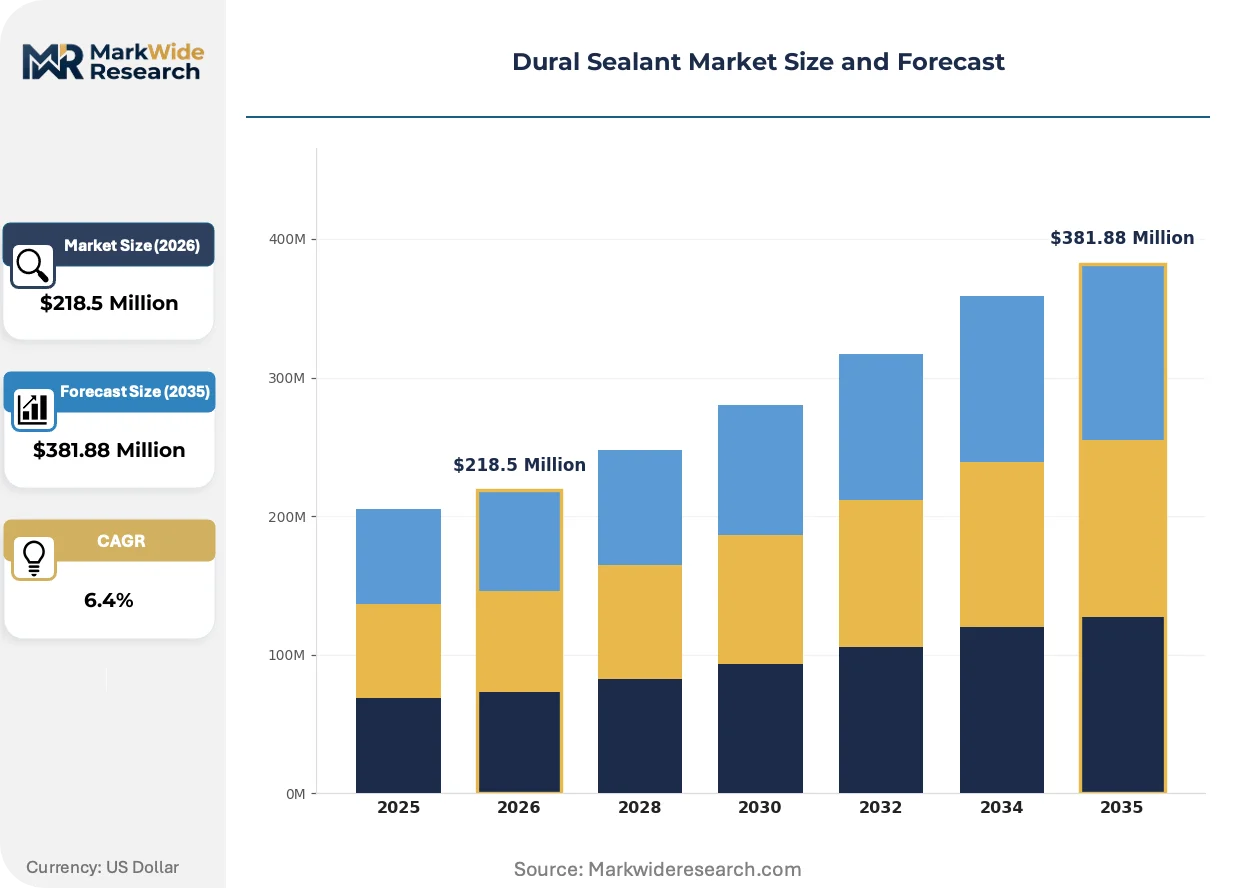
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $381.88 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
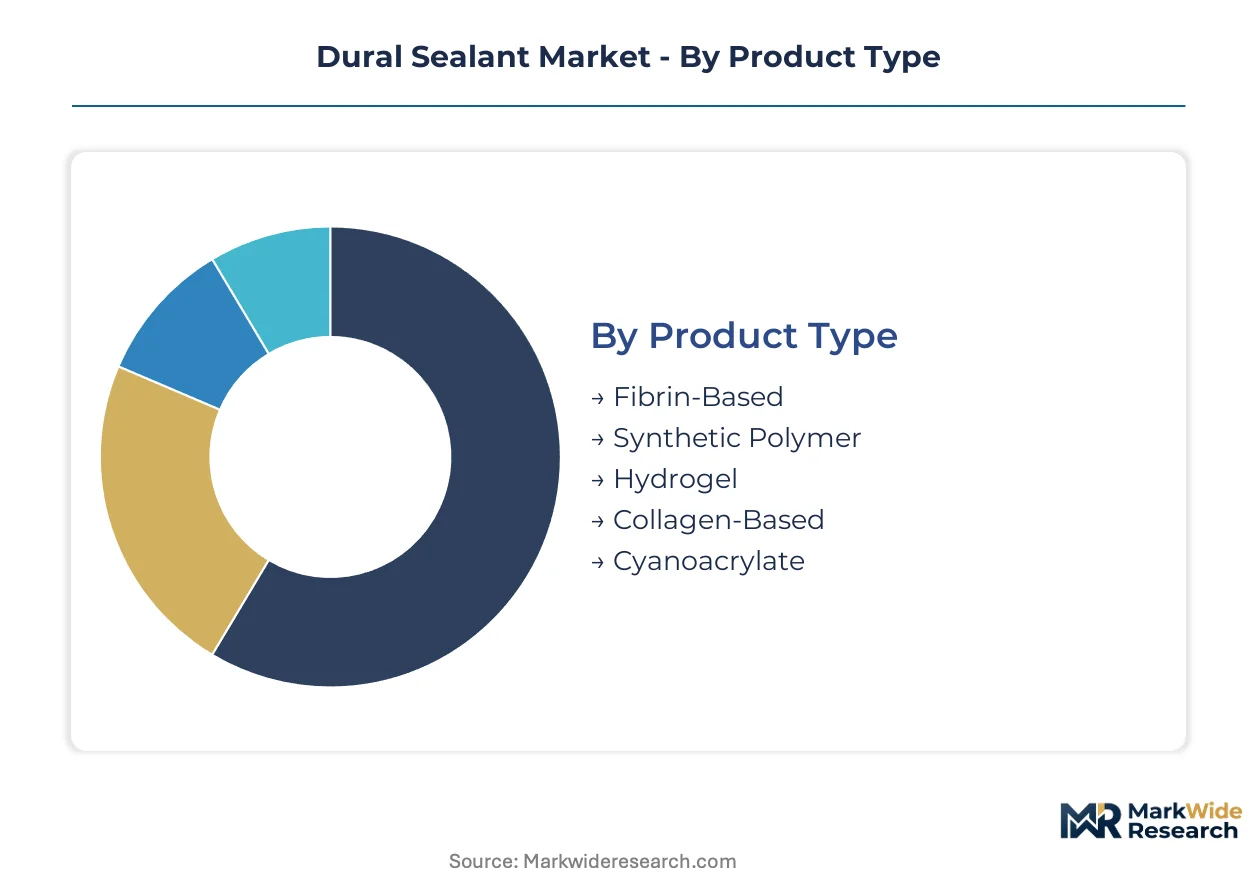
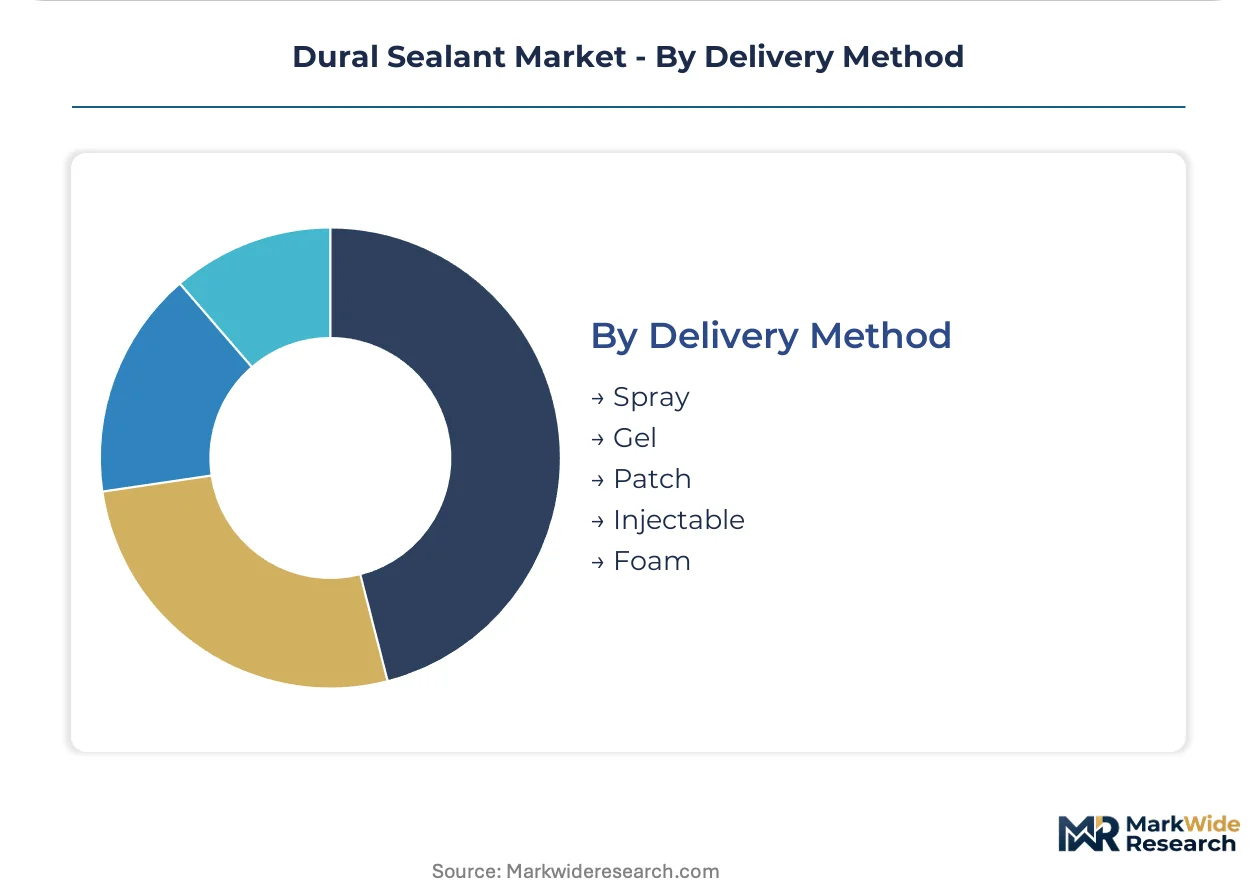
| Segmentation | Product Type: Fibrin-Based, Synthetic Polymer, Hydrogel, Collagen-Based, Cyanoacrylate Application: Neurosurgery, Spine Surgery, Cranial Repair, Aneurysm Sealing, Dural Closure End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Delivery Method: Spray, Gel, Patch, Injectable, Foam |
| Companies Covered | Baxter, B. Braun Medical, Integra LifeSciences, Kuros Biosurgery, Cook Medical, Stryker, Takeda Pharmaceutical, Polyganics, Johnson & Johnson (Ethicon), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dural Sealant Market Strategic Shifts & Innovations
Synthetic polymer platforms are capturing procedural share from fibrin-based formats as surgeons prioritize elimination of blood-borne pathogen transmission risks and supply chain predictability.
Synthetic hydrogel chemistry is expanding into spinal dural repair applications previously dominated by fibrin sealants. Academic medical centers in Germany and the United States are piloting PEG-based systems for minimally invasive discectomy closures. The technology is expanding into outpatient settings where rapid polymerization and elimination of thawing protocols reduce operating room turnover time.
EMA's Medical Device Regulation (MDR) transition is reclassifying dural sealants with ancillary medicinal substances as Class III devices requiring notified body involvement. Manufacturers with legacy CE certificates under the Active Implantable Medical Devices Directive face technical documentation gaps around biological safety and clinical evidence. German and French notified bodies are imposing extended audit timelines, compressing European market entry windows for synthetic polymer entrants.
Hospital value analysis committees are consolidating sealant purchasing around dual-source contracting models that pit fibrin against synthetic platforms. Neurosurgery and spine service lines at US academic medical centers are unbundling sealant selection from kit pricing, enabling direct manufacturer negotiations. This behavioral shift is most pronounced in Texas and California health systems where supply chain rationalization initiatives are centralizing procurement authority.
Dural Sealant Market Segmentation
Dural sealant procurement decisions diverge sharply across surgical settings, with product selection driven by reimbursement pathways, operating room throughput requirements, and biocompatibility risk tolerance. Understanding these segment boundaries reveals where manufacturers can defend premium positioning versus where price compression dominates.
Product Type:
Cost tier differentiation separates emergency stock protocols from elective procedure planning, with raw material sourcing concentration determining supply security premiums.
- Fibrin-Based:Formulated from pooled human plasma-derived fibrinogen and thrombin, these systems polymerize through enzymatic coagulation mimicking physiological wound healing. Demand concentrates in academic medical centers across Germany and the United States where surgeons prioritize established hemostatic performance over synthetic alternatives; supply chain exposure to plasma fractionation bottlenecks constrains volume expansion.
- Synthetic Polymer:Crosslinked polyethylene glycol hydrogels eliminate blood-borne pathogen transmission risks and cold-chain logistics. Adoption accelerates in ambulatory surgery centers throughout Texas and California where rapid polymerization kinetics reduce operating room turnover; elimination of thawing protocols aligns with same-day discharge economics.
- Hydrogel:Absorbable synthetic matrices offering tunable degradation profiles for complex reconstructive dural repair. Premium positioning in Japanese academic centers.
- Collagen-Based:Bovine or porcine-derived matrices providing scaffold architecture for host cell infiltration. Niche applications in dural regeneration protocols.
- Cyanoacrylate:Tissue adhesives with rapid setting characteristics but limited flexibility. Restricted to external dural surface applications due to stiffness concerns.
Volume sits with fibrin-based formats; growth tilts toward synthetic polymer platforms.
Application:
Procedure reimbursement intensity shapes sealant specification, with bundled payment environments favoring lower-cost synthetic options and fee-for-service settings sustaining biologic premiums.
- Neurosurgery:Cranial tumor resections and vascular procedures demand watertight closure under pressure gradients. Fibrin sealants dominate open craniotomy protocols at Massachusetts General Hospital and Johns Hopkins where surgical training curricula reinforce established techniques; CMS inpatient prospective payment bundling compresses standalone sealant reimbursement.
- Spine Surgery:Microdiscectomy and laminectomy durotomies drive synthetic polymer adoption in outpatient settings. Kaiser Permanente and Sutter Health systems in California standardize PEG-based formats for minimally invasive corridors; rapid polymerization enables ambulatory discharge without observation holds.
- Cranial Repair:Traumatic skull fracture management with dural laceration. Emergency department stocking protocols vary by trauma center designation.
- Aneurysm Sealing:Cerebrovascular clipping adjuncts requiring rapid hemostasis under anticoagulation. Limited addressable market due to procedure volume concentration.
- Dural Closure:Generic category spanning primary repair reinforcement. Commoditizing price pressure from hospital value analysis committees.
Revenue concentrates in neurosurgery; spine surgery is expanding most quickly.
End User:
Procurement authority centralization versus clinical autonomy determines vendor access, with consolidated health systems extracting volume discounts unavailable to independent facilities.
- Hospitals:Tertiary academic centers and community hospitals with neurosurgical service lines. Value analysis committees at HCA Healthcare and Tenet facilities negotiate dual-source contracts pitting fibrin against synthetic manufacturers.
- Ambulatory Surgical Centers:Medicare-certified facilities performing spine procedures. Synthetic polymer preference driven by elimination of refrigeration infrastructure and thawing labor.
- Specialty Clinics:Neurological surgery group practices with office-based surgical suites. Limited sealant utilization due to procedure scope constraints.
- Research Institutes:Preclinical and clinical trial sites evaluating novel sealant formulations. Non-commercial volume with protocol-specific sourcing requirements.
Procurement volume sits with hospitals; ASCs are gaining share fastest.
Delivery Method:
Application ergonomics and tissue conformity requirements segment manufacturing capabilities, with dual-syringe systems demanding distinct sterile fill-finish infrastructure from patch or foam formats.
- Spray:Aerosolized delivery enabling broad surface coverage. Preferred for complex craniotomy closures with irregular dural contours.
- Gel:Viscous formulations applied via syringe or spatula. Dominant format for spine surgery durotomy repair.
- Patch:Pre-formed collagen or synthetic matrices requiring suturing or adhesive fixation. Reconstructive applications at Cleveland Clinic and Mayo Clinic.
- Injectable:Low-viscosity systems for minimally invasive delivery through trocars. Fastest-expanding format category.
- Foam:Expandable formulations filling dead space. Limited adoption due to compression concerns on neural tissue.
Utilization sits with gel formats; expansion tilts toward injectable systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma fractionation infrastructure clusters in the United States and Germany anchor raw material security for fibrin-based sealants, while synthetic polymer manufacturing concentrates in Japan and Switzerland where precision chemical synthesis capabilities mature.
United States
Academic medical centers at Johns Hopkins and Massachusetts General Hospital drive clinical protocol standardization for neurosurgical sealants. FDA 510(k) pathway streamlining for biologics-device combinations accelerates premarket reviews for hydrogel entrants. California health systems including Kaiser Permanente consolidate procurement authority around synthetic polymer formats for ambulatory spine procedures.
Germany
Notified bodies in Munich and Berlin impose extended audit timelines under EMA Medical Device Regulation transition, compressing market entry for novel synthetic platforms. Tertiary hospitals in Bavaria pilot PEG-based systems for minimally invasive spinal closures. Plasma fractionation facilities in Frankfurt supply fibrinogen raw material to European manufacturers.
Japan
METI reimbursement incentives for reduced-complication neurosurgery create entry points for premium synthetic sealants in Tokyo and Osaka academic centers. PMDA fast-track designations for innovative medical devices shorten review periods for bioresorbable hydrogel platforms. Aging surgical populations at University of Tokyo Hospital drive demand for rapid-polymerization formats.
Switzerland
Swissmedic oversight of combination products maintains rigorous clinical evidence standards for sealants with ancillary medicinal substances. Precision chemical synthesis capabilities in Basel support polyethylene glycol hydrogel manufacturing for spinal applications. Research institutes in Zurich evaluate tyrosine-derived polycarbonate scaffolds for reconstructive dural repair.
India
CDSCO fast-track pathways for Class C medical devices shorten commercialization timelines for collagen-matrix sealants. Private hospital chains in Mumbai and Delhi expand neurosurgical service lines with standardized sealant protocols. Tertiary hospital buildout in Maharashtra and Karnataka creates procurement volume for synthetic polymer alternatives to imported fibrin systems.
Dural Sealant Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue synthetic polymer specialization and regional licensing partnerships. The vendor base stratifies across three tiers: multinational medical device conglomerates with hemostasis portfolios, mid-cap biologics specialists with regenerative medicine expertise, and regional contract manufacturers supplying private-label formats. Competitive positioning hinges on plasma sourcing security versus polymer chemistry differentiation. M&A activity concentrates on synthetic platform acquisitions; strategic partnerships bridge distribution gaps in Asia-Pacific markets.
Within the multinational tier, Baxter and Stryker occupy positions anchored by channel density in hospital operating rooms and hemostasis portfolio breadth. Integra LifeSciences exemplifies the regenerative medicine specialist archetype, extending dural repair expertise into adjacent neurosurgical categories. Among European entrants, Kuros Biosurgery and Polyganics represent synthetic polymer-focused structures pursuing differentiated hydrogel positioning. Johnson & Johnson (Ethicon) and B. Braun Medical maintain scale-driven presences through diversified surgical portfolio integration. Takeda Pharmaceutical leverages pharmaceutical heritage in Japanese academic center relationships.
| Leading Market Players |
|---|
| Baxter |
| B. Braun Medical |
| Integra LifeSciences |
| Kuros Biosurgery |
| Cook Medical |
| Stryker |
| Takeda Pharmaceutical |
| Polyganics |
| Johnson & Johnson (Ethicon) |
| Others |
Cost & Logistics Intelligence
Hospital value analysis committees at consolidated health systems extract volume discounts through dual-source contracting models that pit fibrin against synthetic sealant manufacturers. Procurement centralization at HCA Healthcare and Kaiser Permanente compresses standalone premiums while rewarding suppliers with cold-chain elimination and rapid polymerization capabilities.
Pricing Analysis
Warranty and technical service bundling separates premium synthetic hydrogel positioning from unbundled fibrin formats where thawing labor and refrigeration infrastructure shift cost to the buyer. Three-tier pricing structure across premium hydrogel, standard synthetic polymer, and economy fibrin levels reflects ISO 10993 biocompatibility certification grades and FDA PMA versus 510(k) pathway differentiation. Cost compression in the fibrin tier intensifies because plasma fractionation bottlenecks concentrate raw material pricing power with United States and German suppliers. Ambulatory surgery centers exhibit highest price sensitivity due to Medicare reimbursement bundling, while academic medical centers sustain biologic premiums for complex reconstructive protocols.
Supply Chain Analysis
Dual-sourcing mandates from hospital value analysis committees require manufacturers to qualify secondary plasma fractionation facilities or polymer synthesis partners. Geographic supply concentration clusters fibrinogen raw material in the United States and Germany, while polyethylene glycol hydrogel production centers on Japan and Switzerland. Human plasma, thrombin concentrates, and crosslinked PEG precursors constitute critical input dependencies. Single-source vulnerability runs through the contracted sterile fill-finish capacity for dual-syringe hydrogel systems. Distribution runs through group purchasing organizations and direct hospital contracts with limited ambulatory surgery center disintermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic polymer chemistry capabilities and plasma fractionation assets constitute the vertical-integration race, with backward integration into PEG precursor manufacturing offering the most defensible cost position.
For Market Incumbents: Acquire sterile fill-finish manufacturing assets to secure dual-syringe hydrogel capacity against contract manufacturer bottlenecks. Defend fibrin-based revenue streams by locking long-term plasma supply agreements with fractionation facilities in the United States and Germany. Channel control through GPO contract exclusivity blocks synthetic entrants from hospital formulary access. For New Entrants and Emerging Players: Ambulatory surgery centers in Texas and California represent the most penetrable buyer archetype, unbundled from academic medical center procurement consolidation. Synthetic polymer formats with rapid polymerization kinetics address same-day discharge economics that fibrin systems cannot match. Direct manufacturer contracting with regional ASC chains bypasses GPO intermediaries. For Investors and Strategic Acquirers: The window for entry favors synthetic polymer specialists with bioresorbable scaffold integration capabilities. Long-term viability hinges on PMA pathway completion for reconstructive dural repair indications beyond simple closure. Watch FDA guidance evolution on biologics-device combination products as the inflection signal for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Contracting Compliance | Hospital value analysis committees at HCA Healthcare mandate qualified secondary suppliers for supply security. |
| Synthetic Polymer Platform Acquisition | Bioresorbable hydrogel chemistry capabilities in Japan and Switzerland command strategic premiums. |
| Plasma Fractionation Partnership | Long-term fibrinogen supply agreements with United States and German facilities anchor cost predictability. |
| PMA Pathway Investment | FDA premarket approval for reconstructive indications extends addressable market beyond 510(k) closure applications. |
| Ambulatory Surgery Center Direct Contract | California and Texas ASC chains unbundle procurement from hospital GPO structures for synthetic formats. |
Research Approach
Multi-period observation of hospital procurement database trends, FDA 510(k) and PMA submission volumes, and CMS reimbursement policy shifts anchored the trend analysis, supplemented by interviews with neurosurgery department heads, hospital purchasing committee chairs, biomedical engineers at academic medical centers, and GPO contracts managers. Secondary validation drew from FDA MAUDE adverse event reports, CMS Medicare cost report data, hospital procurement databases, and ISO 10993 biocompatibility study registries. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation cross-checked segmentation outputs.
Input-output matrix mapping connected surgical procedure volumes by application and setting to sealant utilization rates, pricing tiers, and manufacturer supply capacity across the projection horizon. Segmentation dimensions modeled include product chemistry platform, procedure type, end-user facility category, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to synthetic polymer adoption patterns and fibrin displacement trajectories. Forecast inputs incorporated PMDA fast-track designation timelines and EMA MDR transition audit delays.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance evolution on biologics-device combinations and CMS bundling policy expansion. Forecasts reflect documented assumptions around synthetic polymer tensile strength improvement rates and plasma fractionation capacity expansion. Deviation in sterile manufacturing scale-up timelines or reimbursement compression velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Disposable Hygiene Adhesives Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Waterproofing Admixture Market
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
UV Adhesives Market