
 Latent Curing Agents for Epoxy Resin Market | 2026-2036
Latent Curing Agents for Epoxy Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Latent Curing Agents for Epoxy Resin Market Insights
The capital-intensity divergence between integrated resin producers and specialty additive suppliers is collapsing as mid-scale compounders invest in captive curing-agent synthesis. Mitsubishi Chemical leverages its backward integration into dicyandiamide derivatives to sustain margin capture across the aerospace supply chain. Huntsman Corporation competes through controlled distribution of modified anhydride formulations in European automotive OEM channels. Shikoku Chemicals Corporation anchors its position in Asian electrical laminate markets through proprietary microencapsulation technology.
Latent curing agents for epoxy resin are thermally activated compounds—typically dicyandiamide, boron trifluoride amine complexes, or modified imidazoles—that remain unreactive at ambient temperatures but initiate crosslinking above defined activation thresholds, enabling single-component storage stability with multi-hour pot life. Anhydride formulations dominate high-performance electrical insulation applications where thermal resistance above 150°C is mandatory, while amino-based systems are displacing conventional amines in automotive structural adhesives due to reduced skin-sensitization hazards. Powder-form latent curing agents are capturing share in automated marine coating lines where solvent-free application and precise film-build control reduce volatile organic compound emissions.
EPA industrial chemical regulations and REACH substance restrictions are forcing reformulation of legacy boron trifluoride amine complexes toward lower-toxicity latent activators. China's GB standards for workplace chemical exposure and Japan's METI chemical substance reporting requirements are creating parallel compliance obligations for suppliers serving multiple manufacturing geographies. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and maintain formulation registration validity across export markets.
Market Dynamics
REACH substance restrictions and evolving EPA standards are forcing simultaneous reformulation of legacy boron trifluoride amine complexes across multiple industrial epoxy applications, compressing development timelines while elevating R&D spend.
Growth Catalysts
- Aerospace structural bonding:Composite manufacturing for commercial aircraft and satellite systems is expanding single-component adhesive adoption where thermal activation above 120°C ensures precise assembly control.
- REACH compliance deadlines:European manufacturers are accelerating migration from skin-sensitizing amine hardeners toward latent amino-based systems with reduced hazard classification.
- Marine coating automation:Powder-form latent curing agents are displacing solvent-borne alternatives in Korean and Japanese shipyard lines where VOC emission caps have tightened.
Market Restraints
- Dicyandiamide supply concentration:Chinese producers control upstream cyanamide derivative capacity, exposing formulators to input volatility when environmental inspections curtail regional chemical manufacturing.
- Activation threshold rigidity:Modified imidazole systems require precise thermal profiling that limits adoption in thick-section composites where exotherm management is critical.
- Anhydride moisture sensitivity:Storage and handling protocols for electrical-grade formulations impose infrastructure costs that disadvantage smaller compounders.
Strategic Opportunities
- Indian electrical laminate expansion:Domestic PCB manufacturing under the country's PLI scheme is creating demand for high-Tg anhydride curing systems previously imported from East Asian suppliers.
- Microencapsulation convergence:Advances in melamine-formaldehyde shell chemistry are enabling room-temperature-stable single-component adhesives for automotive crash-resistant structural bonding.
- Japan METI chemical reporting:Streamlined substance notification pathways for pre-registered latent activators are accelerating product registration for exporters targeting Japanese electrical equipment OEMs.
Industry Challenges
- Formulation chemist scarcity:Expertise in epoxy-amine stoichiometry and kinetic modeling is concentrating at integrated resin producers, constraining independent compounder innovation capacity.
- Multijurisdictional registration costs:Maintaining REACH, EPA TSCA, and China MEE chemical inventory listings simultaneously demands dedicated regulatory affairs infrastructure that mid-scale suppliers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latent Curing Agents for Epoxy Resin Market |
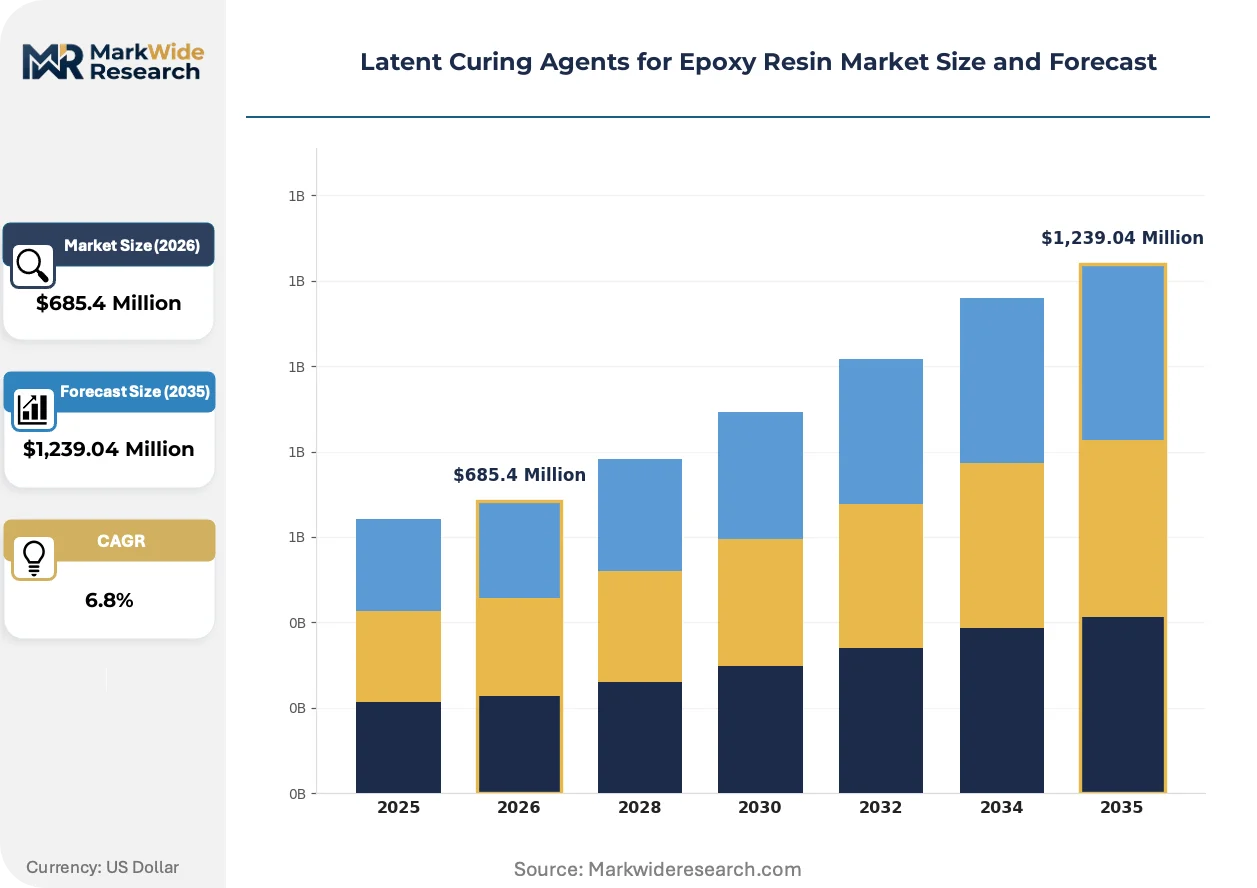
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydride, Amino, Phenolic, Urethane Application: Aerospace, Automotive, Electrical, Marine Form: Solid, Liquid, Powder, Paste End User: Manufacturers, Contractors, Suppliers, Developers |
| Companies Covered | Alzchem Group, T&K toka, Westlake (Hexion), Mitsubishi Chemical, Ajinomoto Fine-Techno, Asahi Kasei, Shikoku Chemicals Corporation, Huntsman Corporation, Dasen Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latent Curing Agents for Epoxy Resin Market Trends and Innovations
Thermal activation chemistry is advancing along two parallel tracks—precision-controlled aerospace systems and cost-optimized industrial grades—while regulatory pressure accelerates toxicity reduction across both pathways.
Microencapsulated dicyandiamide is bifurcating the latent curing agent landscape into shelf-stable single-component formulations and traditional two-part systems. Wind blade manufacturers in Denmark and Germany are adopting encapsulated grades for infusion processes where extended pot life eliminates vacuum-debulk interruptions. This encapsulation technology is compressing the performance gap between commodity dicyandiamide and premium modified imidazoles in structural composite applications.
EPA industrial chemical regulations are tightening permissible emission thresholds for boron trifluoride amine complex handling and disposal. American electrical laminate producers are reformulating toward boron-free latent activators despite higher raw material costs and extended cure cycle requirements. The transition is most acute in high-voltage transformer insulation where thermal resistance above 155°C remains non-negotiable.
Automotive OEMs are consolidating adhesive specifications across platform architectures, reducing approved supplier lists from twelve to three qualified compounders per region. Tier-1 suppliers in Germany and the United States are responding with captive blending facilities that bypass traditional distribution channels. Specification consolidation is most visible in battery enclosure bonding where crash performance certification cycles exceed eighteen months.
Latent Curing Agents for Epoxy Resin Market Segmentation
Latent curing agents serve divergent performance requirements across aerospace bonding, electrical insulation, and marine coating applications. Segmentation reveals how formulation chemistry, physical form, and end-user procurement patterns create distinct competitive arenas with varying margin profiles and technical barriers.
Product Type:
Domestic production capacity for anhydride and amino systems concentrates in Germany, Japan, and the United States, while Chinese manufacturers dominate dicyandiamide-derived amino grades for export markets. Phenolic and urethane curing agents flow through more distributed supply chains with regional compounders serving nearby formulation customers.
- Anhydride:Cycloaliphatic and aromatic anhydride formulations deliver thermal resistance above 150°C for high-voltage transformer insulation and motor winding encapsulation. Demand clusters in Japanese electrical equipment manufacturing and German automotive OEM specification systems where thermal aging performance is non-negotiable.
- Amino:Dicyandiamide and modified amine complexes provide single-component stability with activation thresholds between 120-180°C. Korean marine coating lines and Chinese wind blade manufacturers are expanding procurement of amino-based systems to meet VOC emission caps and extend pot life in automated application equipment.
- Phenolic:Phenol-formaldehyde crosslinkers serve specialized friction material and brake lining applications where thermal degradation resistance exceeds standard epoxy performance.
- Urethane:Blocked isocyanate latent systems enable hybrid epoxy-urethane networks for flexible structural adhesives in automotive crash management components.
Anhydride holds the largest share; momentum sits with amino systems as REACH compliance accelerates reformulation away from skin-sensitizing alternatives.
Application:
Cost tier differentiation separates specification-grade aerospace systems from price-sensitive industrial coating applications, with automotive and electrical segments occupying intermediate positions defined by certification requirements and volume scale.
- Aerospace:Satellite structural bonding and commercial aircraft composite assembly demand precise thermal activation control above 120°C with multi-hour pot life. Boeing and Airbus tier-1 suppliers in the United States, France, and Germany maintain qualified compounder lists with 18-month certification cycles that lock out new entrants.
- Automotive:Battery enclosure structural adhesives and crash-resistant bonding applications require latent systems with controlled exotherm and rapid strength development above 80°C. German and Japanese OEMs are consolidating approved supplier lists from twelve to three qualified compounders per region, forcing tier-1 suppliers toward captive blending facilities.
- Electrical:High-voltage transformer insulation and PCB laminate manufacturing depend on anhydride and boron-free latent activators with thermal resistance above 155°C.
- Marine:Korean and Japanese shipyards are adopting powder-form latent curing agents for solvent-free coating lines where VOC caps have tightened and film-build precision reduces rework.
Electrical applications command the largest volume position; automotive battery bonding represents the steepest expansion trajectory as electrification accelerates platform consolidation.
Form:
Physical form selection tracks customer handling infrastructure and automation level, with powder systems requiring capital investment in dust containment and thermal management equipment that disadvantages smaller compounders.
- Solid:Tablet and pellet forms serve electrical laminate presses and transformer vacuum pressure impregnation systems where precise dosing and minimal volatile release are critical. Japanese electrical equipment OEMs favor solid grades for automated handling compatibility.
- Liquid:Low-viscosity latent activators enable spray and dip coating applications in automotive underbody sealing and general industrial maintenance coatings. Chinese formulation plants in the eastern coastal corridor are expanding liquid-grade capacity to serve domestic automotive supplier clusters.
- Powder:Electrostatic spray-compatible latent curing agents eliminate solvent handling in Korean shipyard coating operations and German wind blade manufacturing lines.
- Paste:Thixotropic formulations support trowel and extrusion application in construction anchoring adhesives and concrete repair systems where sag resistance is essential.
Liquid forms maintain the broadest installed base; powder grades are gaining share fastest in automated marine and wind energy manufacturing lines.
End User:
Procurement authority and technical specification control vary sharply across end-user categories, with manufacturers driving formulation chemistry decisions while contractors and developers operate within pre-approved material lists.
- Manufacturers:Electrical equipment OEMs, automotive tier-1 suppliers, and aerospace composite fabricators maintain direct relationships with curing agent producers for custom specification development. Mitsubishi Chemical and Huntsman Corporation compete for qualified supplier status through backward integration into dicyandiamide derivatives and controlled distribution of modified anhydride formulations.
- Contractors:Marine coating applicators and construction adhesive installers select from distributor-stocked grades with regional technical support. Procurement concentrates on shelf stability and application latitude rather than formulation customization.
- Suppliers:Epoxy resin distributors and specialty chemical merchants carry inventory for spot demand from smaller compounders and maintenance operations.
- Developers:Wind farm and infrastructure project owners influence curing agent selection through performance specifications in engineering procurement construction contracts, particularly for corrosion protection and structural bonding warranties.
Manufacturers represent the largest demand channel; developer specification influence is expanding fastest in renewable energy and infrastructure project finance structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across manufacturing geographies. German electrical OEMs prioritize thermal resistance above 155°C, while Korean shipyards optimize for solvent-free powder application, and Chinese wind blade producers extend pot life for vacuum infusion processes.
United States
Aerospace composite fabricators in Washington State and Kansas drive specification-grade demand for thermal activation systems above 120°C. EPA industrial chemical regulations are tightening permissible emission thresholds for boron trifluoride amine complex handling. Electrical laminate producers in the Southeast are reformulating toward boron-free latent activators despite extended cure cycle requirements.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are consolidating approved adhesive supplier lists from twelve to three qualified compounders per region. REACH substance restrictions are accelerating migration from skin-sensitizing amine hardeners toward latent amino-based systems. High-voltage transformer manufacturers in North Rhine-Westphalia maintain non-negotiable thermal aging performance specifications.
China
Wind blade manufacturers in the eastern coastal manufacturing corridor are expanding procurement of microencapsulated dicyandiamide grades. GB standards for workplace chemical exposure are creating parallel compliance obligations for domestic and export formulations. Epoxy formulation capacity is clustering in Jiangsu and Zhejiang provinces where environmental inspections periodically curtail regional chemical manufacturing.
Japan
Electrical equipment OEMs in the Kanto region favor solid-grade latent curing agents for automated handling compatibility. METI chemical substance reporting requirements are streamlining notification pathways for pre-registered latent activators. Shikoku Chemicals Corporation anchors proprietary microencapsulation technology serving Asian electrical laminate markets from its base in Kagawa Prefecture.
South Korea
Shipyard coating lines in Ulsan and Geoje are adopting powder-form latent curing agents for solvent-free application where VOC emission caps have tightened. Korean marine coating applicators select from distributor-stocked grades emphasizing shelf stability and film-build precision. Domestic formulators are expanding capacity to serve Hyundai Heavy Industries and Samsung Heavy Industries specification systems.
Latent Curing Agents for Epoxy Resin Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the latent curing agents market. Backward-integrated resin producers capture margin across aerospace supply chains through captive dicyandiamide derivative production, while mid-scale compounders invest in in-house curing-agent synthesis to collapse historical capability gaps. Three archetypes dominate: integrated chemical conglomerates with upstream cyanamide control, specialty additive suppliers with microencapsulation IP, and regional compounders serving automotive OEM qualification systems. Competitive moves concentrate on strategic partnerships for regulatory registration coverage and capacity expansion in high-Tg anhydride systems.
Among Japanese chemical conglomerates, Mitsubishi Chemical and Ajinomoto Fine-Techno exemplify the integrated archetype through their positions in dicyandiamide value chains and amino acid-derived specialty chemicals respectively. Huntsman Corporation represents the multinational specialty tier with controlled distribution networks in European automotive OEM channels. These three occupy positions reflecting divergent geographic anchoring and downstream integration depth rather than direct product overlap.
| Leading Market Players |
|---|
| Alzchem Group |
| T&K toka |
| Westlake (Hexion) |
| Mitsubishi Chemical |
| Ajinomoto Fine-Techno |
| Asahi Kasei |
| Shikoku Chemicals Corporation |
| Huntsman Corporation |
| Dasen Material |
| Others |
Pricing and Supply Chain Analysis
Boron-free latent activator substitution for legacy boron trifluoride amine complexes is redrawing procurement geography and compressing margin structures across formulation tiers. This chemistry migration forces compounders to absorb higher raw material costs from German and Japanese specialty suppliers while Chinese dicyandiamide producers retain leverage over amino-grade feedstock pricing.
Pricing Analysis
After-sales technical service and reformulation support contracts generate lifetime value that exceeds initial chemical sales by multiples in aerospace qualification systems. Three-tier pricing structure across aerospace-certified, automotive-qualified, and industrial-commodity levels separates specification-grade anhydrides from standard amino grades and unmodified dicyandiamide commodity lots. Cost compression in industrial-grade powders is intensifying because Korean shipyards are consolidating procurement volumes across fewer approved suppliers. Automotive OEMs exhibit lowest price sensitivity due to eighteen-month crash-performance certification cycles that lock in qualified compounders.
Supply Chain Analysis
China dominates upstream cyanamide derivative production for dicyandiamide extraction while Germany and Japan anchor high-purity anhydride synthesis for electrical insulation grades. The latent curing agent supply chain draws from cyanamide feedstock, boron trifluoride gas, and aromatic anhydride precursors as critical inputs. Single-source vulnerability concentrates in Chinese environmental inspection zones where regional manufacturing curtailments trigger feedstock volatility. Distribution runs through qualified supplier lists maintained by aerospace tier-1 fabricators and automotive OEM specification systems rather than open merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as automotive OEMs collapse approved adhesive supplier lists from twelve to three qualified compounders per region, fragmenting tier-1 supplier negotiating leverage.
For Market Incumbents: Shield aerospace qualification status through captive dicyandiamide derivative production and preemptive REACH registration coverage for boron-free activator portfolios. Backward integration into cyanamide feedstock secures margin capture against Chinese supply volatility. Priority certification investment sits with high-Tg anhydride systems for electrical laminate markets where thermal resistance above 155°C remains non-negotiable. For New Entrants and Emerging Players: Anchor in Indian electrical laminate expansion under the country's PLI scheme where domestic PCB manufacturing creates demand for anhydride systems previously imported from East Asian suppliers. Microencapsulation technology for room-temperature-stable automotive adhesives represents the most penetrable white space. Go-to-market leverage rests on streamlined Japan METI chemical notification pathways for pre-registered latent activators targeting electrical equipment OEMs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale compounders that invested in captive curing-agent synthesis to collapse historical capability gaps with integrated resin producers. Five-to-ten year viability hinges on regulatory registration infrastructure spanning REACH, EPA TSCA, and China MEE chemical inventories simultaneously. Acquisition targets center on regional compounders with automotive OEM qualification status and microencapsulation IP. The signal to watch is specification consolidation velocity in battery enclosure bonding where crash certification cycles exceed eighteen months.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyanamide Feedstock | Mitsubishi Chemical leverages captive dicyandiamide derivatives to sustain aerospace supply chain margin capture. |
| Microencapsulation Technology Development | Shikoku Chemicals Corporation anchors Asian electrical laminate markets through proprietary melamine-formaldehyde shell chemistry. |
| Multi-jurisdictional Registration Infrastructure | Mid-scale compounders struggle to fund dedicated regulatory affairs spanning REACH, EPA, and China MEE obligations. |
| Automotive OEM Qualification Consolidation | German and Japanese tier-1 suppliers respond with captive blending facilities that bypass traditional distribution channels. |
| Boron-Free Activator Reformulation | American electrical laminate producers absorb higher raw material costs to meet EPA emission threshold tightening. |
Research Methodology
A standing panel of epoxy formulation chemists, aerospace composite procurement managers, automotive tier-1 adhesive specialists, and electrical equipment OEM technical directors provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC 10-K filings of integrated chemical conglomerates, ECHA REACH registration databases, Japan METI chemical substance notifications, and China customs trade data for cyanamide derivative flows. Bottom-up volume modeling triangulated against top-down market sizing from regional production capacity assessments.
Consistency checks validated volume and value outputs against external benchmarks including ACC specialty chemical reports and Cefic epoxy resin consumption data across the analysis window. Segmentation dimensions modeled encompass product chemistry tier, end-use application, physical form factor, and regional manufacturing hub clustering. CAGRs were derived from regression analysis of historical consumption patterns and projected capacity expansion schedules, with specific inputs from wind blade manufacturing buildout rates and automotive electrification platform consolidation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained REACH enforcement trajectory and stable Chinese environmental inspection intensity; material deviation would warrant model refresh. Specific risks that could revise forecasts include abrupt dicyandiamide supply disruption from regional environmental shutdowns, accelerated EPA boron trifluoride restrictions, or automotive OEM qualification timeline compression. Recalibration cycles align with material shifts in regulatory enforcement patterns and aerospace platform certification schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
North America and Europe Phenolic Resin Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Polyethylene Furanoate Market
Polymers & Resins
Mixed-Mode Chromatography Resin Market
Polymers & Resins
Metallocene Polyethylene Market
Polymers & Resins
BPA-Free Epoxy Resins Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Synthetic and Bio Thermosets Market