
 North America Sealants Market | 2026-2036
North America Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sealants Market Analytics
LEED v4.1 and the Architecture 2030 Challenge are consolidating specification authority around low-emitting, durable sealant systems across commercial construction. Dow leverages its silicone feedstock integration to sustain pricing leverage in high-performance glazing applications. H.B. Fuller Company anchors its position through construction adhesive and sealant bundling with national distributors. Sika AG competes aggressively in transportation infrastructure with polyurethane formulations engineered for dynamic joint movement.
North America sealants comprise elastomeric compounds—typically formulated from silicone, polyurethane, acrylic, or epoxy chemistries with Shore A hardness ranging from 15 to 50 and elongation at break exceeding 200%—that cure to flexible solids to bond, seal, or fill joints against moisture, air, and thermal transfer. Silicone leads product type value contribution due to UV stability and movement accommodation in curtain wall assemblies, while polyurethane captures faster growth in automotive seam sealing and wind energy blade bonding where toughness and paintability matter. Construction dominates application volume but electronics and aerospace segments concentrate margin pools through qualification-intensive specifications and limited approved supplier lists.
Federal EPA VOC regulations under 40 CFR Part 59, California SCAQMD Rule 1168, and OSHA worker exposure standards collectively constrain solvent-based formulations and elevate waterborne and silyl-terminated polyurethane alternatives. Health Canada and PMRA review requirements for antimicrobial sealant claims add compliance layers for manufacturers serving cross-border building product markets. Stakeholders must monitor evolving state-level embodied carbon disclosure rules and federal Buy America procurement thresholds that will reshape qualified product lists and domestic manufacturing footprints.
Market Dynamics
LEED v4.1 and ASHRAE energy codes are compressing specification windows for sealant systems across commercial construction, forcing manufacturers to consolidate R&D around low-VOC, high-durability formulations that satisfy both performance and disclosure requirements.
Growth Catalysts
- California SCAQMD Rule 1168:This regulation mandates VOC emission thresholds for architectural sealants, accelerating reformulation investments toward silyl-terminated polyurethanes and waterborne acrylics in curtain wall and fenestration applications.
- Wind energy blade manufacturing:Polyurethane structural adhesives and sealants are displacing mechanical fasteners in turbine assembly, driven by blade length expansion beyond 80 meters and fatigue-resistance specifications.
- High-rise construction clusters:Toronto, Vancouver, New York, and Los Angeles are concentrating demand for movement-accommodating silicone systems in curtain wall envelopes, creating specification pull for UV-stable, 50-year durability products.
Market Restraints
- Silicone feedstock concentration:Methyl chloride and silicon metal supply chains concentrate in Chinese and German production basins, exposing North American formulators to freight cost volatility and tariff exposure.
- Polyol input cost instability:Polyether polyol prices fluctuate with propylene oxide supply disruptions, compressing margin visibility for polyurethane sealant manufacturers serving automotive and infrastructure segments.
- Cure-rate limitations in cold climates:Moisture-cure polyurethane and silicone systems exhibit extended tack-free times below 40°F, constraining winter construction scheduling in Canadian and northern US markets.
Strategic Opportunities
- Retrofit building envelope upgrades:Canada and the northern United States hold substantial commercial building stock constructed before 1990, creating demand for air-barrier sealant systems that meet modern blower-door test requirements.
- Electric vehicle battery pack sealing:Thermal runaway protection and IP67 ingress specifications are driving specification of flame-retardant silicone foams and two-part polyurethanes in Michigan, Tennessee, and Ontario assembly plants.
- Federal Buy America procurement thresholds:Domestic content requirements for infrastructure spending are incentivizing sealant production reshoring and qualification of US-manufactured products for DOT-funded transportation projects.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge required for silane-modified polymer synthesis and rheology control is concentrating at a handful of technical centers, constraining new product development velocity.
- Multijurisdictional compliance timelines:Health Canada PMRA antimicrobial claim reviews and EPA 40 CFR Part 59 VOC registrations operate on asynchronous schedules, delaying cross-border product launches by 12-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sealants Market |
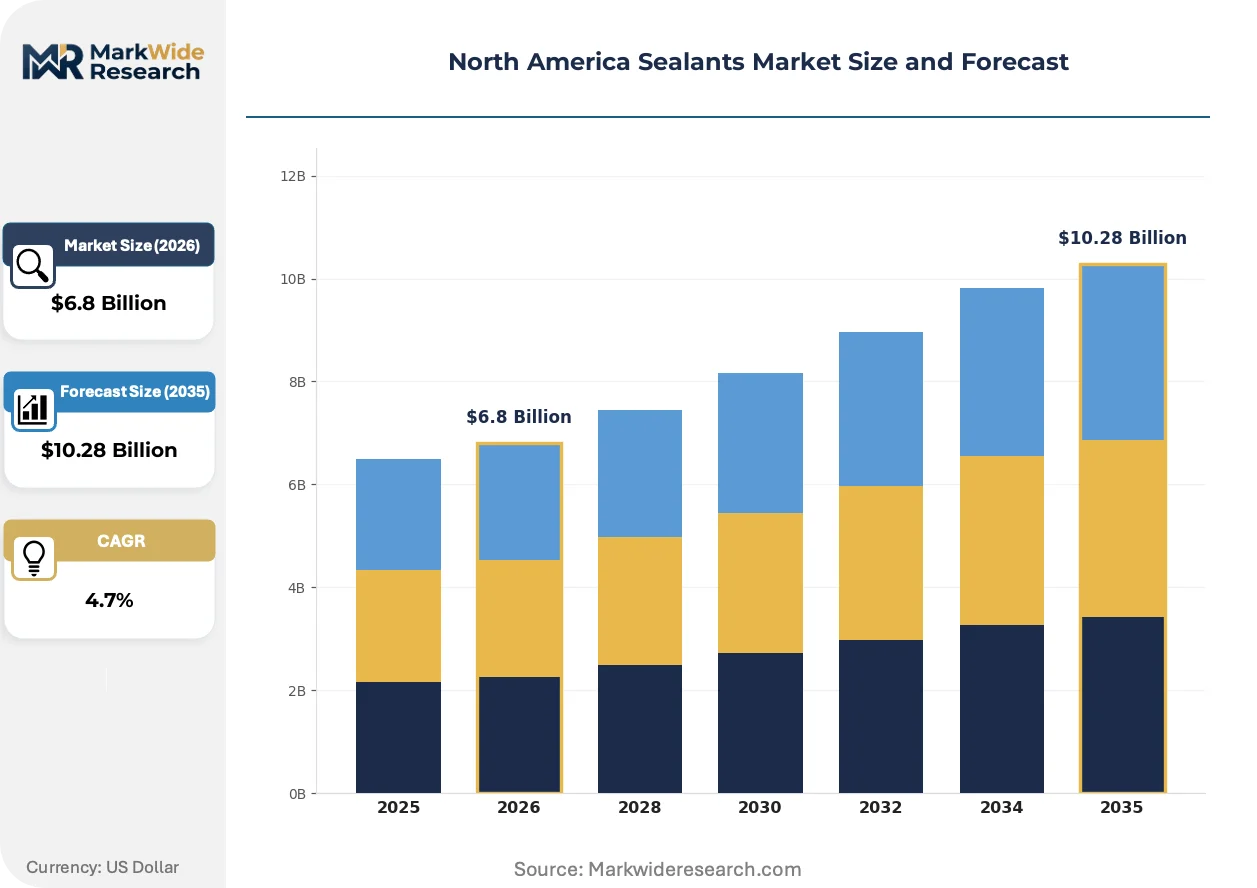
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Silicone, Polyurethane, Epoxy Application: Construction, Automotive, Aerospace, Electronics End User: Residential, Industrial, Commercial, DIY Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | 3M, RPM International, Sika AG, Henkel AG & Co. KGaA, H.B. Fuller Company, Dow, Arkema Group, Wacker Chemie AG, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sealants Market Evolving Landscape
Silyl-terminated polyurethane chemistry is electrifying competitive positioning in construction sealants, while regulatory disclosure requirements and procurement centralization are compressing supplier lists and elevating performance verification standards.
Hybrid silyl-terminated polyurethane technology is electrifying specification capture in high-movement commercial joints. Building envelope consultants in Seattle, Chicago, and Boston are specifying these systems for their combined paintability and 50% joint movement accommodation. The technology is compressing market share for conventional solvent-based polyurethanes that cannot meet SCAQMD Rule 1168 VOC limits.
ASHRAE Standard 90.1 and the Architecture 2030 Challenge are mandating whole-building air leakage testing, forcing sealant manufacturers to publish third-party validated air-barrier assembly ratings. Commercial contractors in California and New York are now requiring ASTM E2357 system testing documentation before specification approval. This is elevating qualification costs and consolidating specification authority around manufacturers with in-house testing capabilities.
Consolidated procurement through national distributor frameworks is displacing project-by-project sealant selection. Large general contractors in Texas, Florida, and Georgia are mandating approved manufacturer lists with pre-negotiated pricing and single-source accountability for adhesive and sealant bundles. This is compressing regional distributor margins and elevating the importance of construction adhesive cross-selling relationships for sealant placement.
North America Sealants Market Segmentation
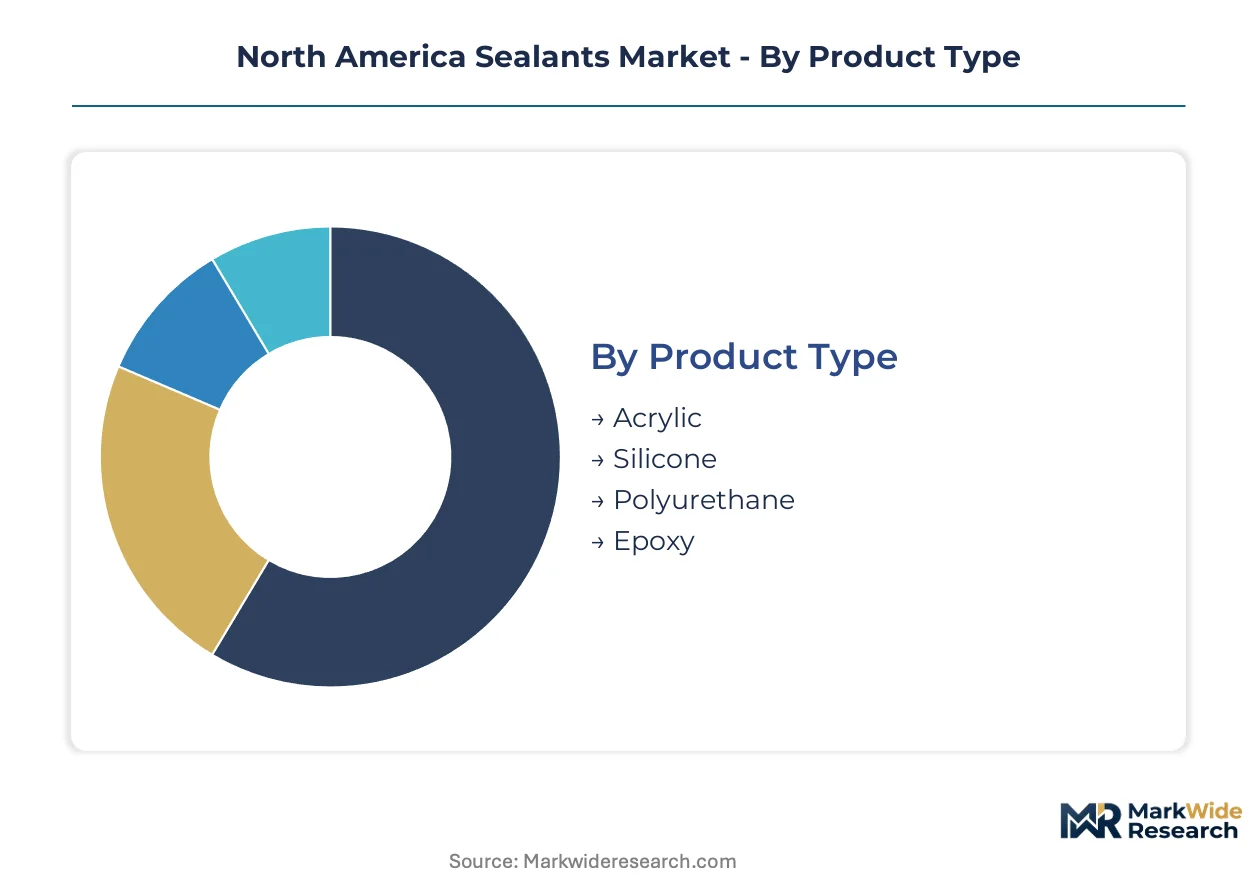
Sealant specification authority concentrates around chemistry-specific performance certifications and end-use qualification requirements. Segmentation reveals how regulatory burden, application criticality, and channel economics partition margin capture across the value chain.
Product Type:
EPA 40 CFR Part 59 and California SCAQMD Rule 1168 impose distinct VOC thresholds by chemistry, forcing manufacturers to maintain parallel formulation portfolios with separate compliance documentation.
- Silicone:UV-stable elastomers formulated from siloxane backbones accommodate ±50% joint movement in curtain wall assemblies. Demand concentrates in Toronto, Vancouver, New York, and Los Angeles high-rise clusters where 50-year durability specifications and LEED v4.1 low-emitting requirements drive specification.
- Polyurethane:Tough, paintable systems derived from isocyanate-polyol reactions bond turbine blades and automotive seams. Wind energy manufacturing in the US Midwest and EV battery pack sealing in Michigan and Ontario accelerate specification of fatigue-resistant formulations with flame-retardant grades.
- Acrylic:Waterborne emulsions serve interior caulking and lower-movement exterior joints with faster cure profiles and lower material cost.
- Epoxy:Rigid, high-strength thermosets anchor structural bonding applications where zero movement tolerance and chemical resistance outweigh flexibility requirements.
Leading the category by volume: Silicone. Growing fastest: Polyurethane.
Application:
End-use criticality determines whether specifications demand third-party validated air-barrier assembly ratings or accept manufacturer-declared performance data.
- Construction:Dominates absolute volume across commercial envelope, residential fenestration, and infrastructure joint sealing. ASHRAE Standard 90.1 whole-building air leakage testing mandates ASTM E2357 system documentation, elevating qualification costs and consolidating specification authority around manufacturers with in-house testing capabilities.
- Automotive:Seam sealing, NVH management, and direct glazing applications require OEM qualification cycles spanning 24-36 months. Paintable polyurethane formulations capture specification in Tennessee, Michigan, and Ontario assembly plants.
- Aerospace:FAA-qualified materials for fuel tank sealing and pressure boundary applications concentrate margin pools through limited approved supplier lists and qualification-intensive specifications.
- Electronics:Thermal interface materials and potting compounds serve PCB protection and battery pack sealing where IP67 ingress and thermal runaway protection specifications apply.
Construction commands the largest volume share. Electronics exhibits the steepest margin expansion trajectory.
End User:
Procurement centralization and specification authority vary sharply across customer types, with bundled adhesive-sealant contracts displacing project-by-project selection in consolidated accounts.
- Commercial:General contractors in Texas, Florida, and Georgia mandate approved manufacturer lists with pre-negotiated pricing and single-source accountability for adhesive and sealant bundles.
- Industrial:Wind energy OEMs and automotive assemblers qualify suppliers through direct technical audits and production part approval processes.
- Residential:Production homebuilders and custom contractors source through national distributor frameworks with regional availability requirements.
- DIY:Retail channel consumers prioritize ease of application and shelf-ready packaging over technical performance specifications.
Commercial segment leads by project value concentration. Industrial users drive fastest technology adoption cycles.
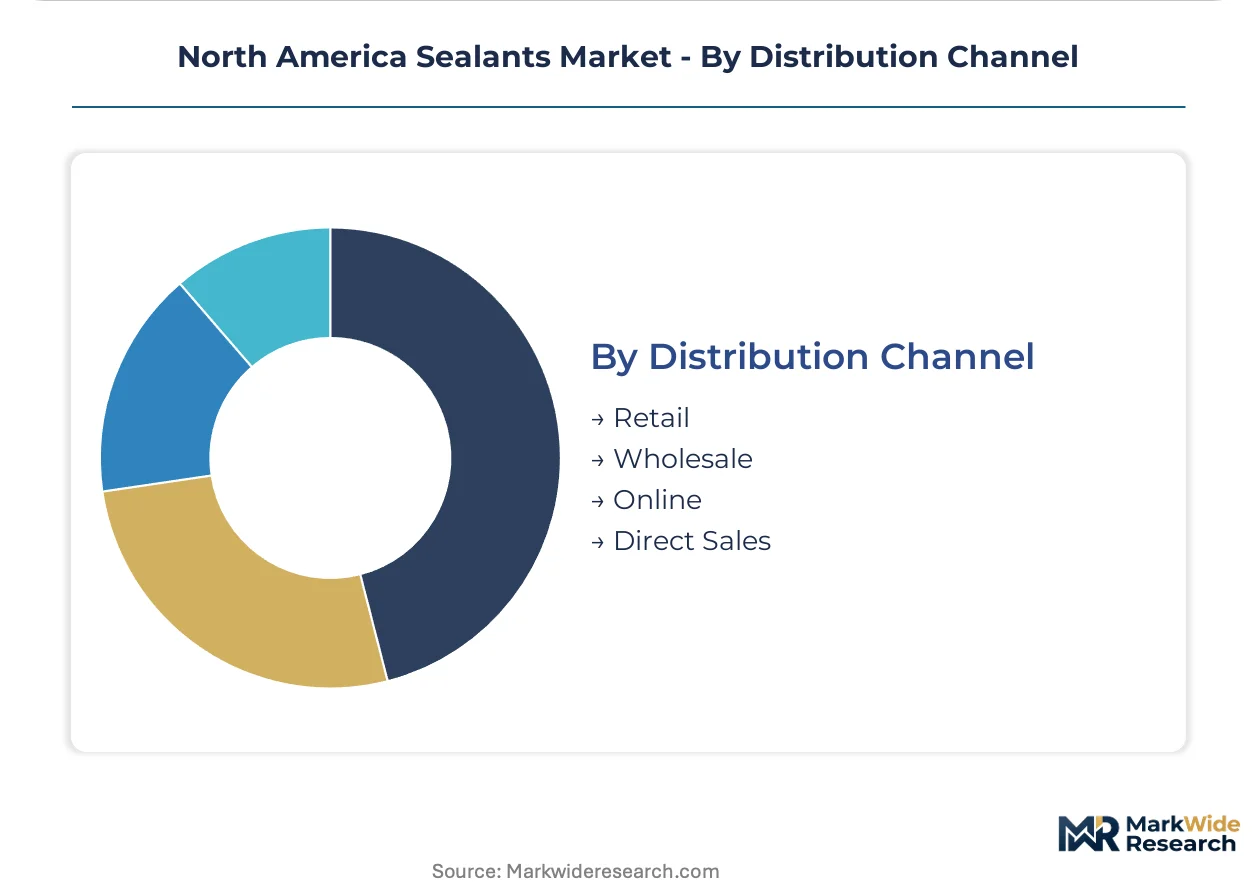
Distribution Channel:
Channel selection determines whether manufacturers capture specification influence or cede authority to distributor private-label alternatives.
- Wholesale:National distributors like H.B. Fuller anchor construction placement through adhesive-sealant bundling and contractor loyalty programs.
- Direct Sales:Automotive and aerospace OEMs require technical service integration and just-in-time delivery coordination.
- Retail:Big-box home improvement chains serve DIY and light commercial maintenance with stocked inventory and project-quantity packaging.
- Online:E-commerce platforms capture specification-grade procurement in remote markets and specialized industrial grades with extended technical data sheet availability.
Wholesale maintains dominant volume position. Online channel shows fastest penetration growth in specification-grade categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toronto, Vancouver, New York, and Los Angeles concentrate demand for movement-accommodating silicone systems in high-rise curtain wall envelopes. EPA 40 CFR Part 59 and California SCAQMD Rule 1168 impose distinct VOC thresholds by chemistry across the region. Health Canada and PMRA review requirements add compliance layers for cross-border building product markets.
United States
Commercial building envelope applications dominate volume as LEED v4.1 and ASHRAE energy codes tighten performance requirements. EPA 40 CFR Part 59 constrains solvent-based formulations and elevates waterborne alternatives. New York and Los Angeles high-rise clusters specify UV-stable, 50-year durability silicone products for curtain wall assemblies.
Canada
Retrofit building envelope upgrades drive demand in commercial stock constructed before 1990. Health Canada and PMRA review requirements for antimicrobial sealant claims delay cross-border product launches. Toronto and Vancouver concentrate specification pull for low-VOC silicone formulations in high-rise curtain wall projects.
Mexico
Automotive assembly plants in northern border states accelerate specification of paintable polyurethane sealants for seam sealing applications. Domestic content requirements for USMCA-regulated trade influence qualified product lists. Manufacturing clusters near the US border serve integrated North American automotive supply chains.
North America Sealants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across chemistry integration and qualification intensity. The vendor base organizes around three tiers: integrated silicone feedstock producers, construction adhesive bundlers, and specialty polyurethane formulators. Dow leverages captive silicone production for pricing leverage in high-performance glazing. H.B. Fuller anchors placement through distributor bundling relationships. Sika AG competes aggressively in transportation infrastructure with dynamic joint movement formulations. Dominant competitive moves include adhesive-sealant portfolio bundling and qualification-intensive specification capture.
Within the integrated chemistry tier, Dow represents feedstock-backed positioning in silicone sealants. H.B. Fuller Company exemplifies construction-focused bundling strategy through national distributor frameworks. Sika AG occupies a position in infrastructure and transportation applications with polyurethane specialization. These three anchors illustrate how chemistry control, channel integration, and application-specific qualification create defendable market positions across distinct margin pools.
| Leading Market Players |
|---|
| 3M |
| RPM International |
| Sika AG |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Dow |
| Arkema Group |
| Wacker Chemie AG |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
LEED v4.1 low-emitting material requirements gate qualified supply access and premium-tier pricing power for sealant manufacturers serving North American commercial construction. EPA 40 CFR Part 59 and California SCAQMD Rule 1168 create compliance moats that stratify pricing across certified and non-certified product tiers.
Pricing Analysis
Value-based pricing anchored to air-barrier performance outcomes dominates specification-grade silicone and silyl-terminated polyurethane segments. Three-tier pricing structure across premium, standard, and economy levels separates ASTM E2357-validated systems from commodity acrylics and private-label alternatives. Price differentiation hinges on certification grade and volume scale, with large general contractors extracting bundled discounts through national distributor frameworks. Pricing pressure stems from polyether polyol cost volatility in polyurethane formulations, compressing margin visibility for automotive and infrastructure suppliers. DIY retail channels exhibit highest price sensitivity, while aerospace and electronics OEMs accept substantial premiums for qualification-intensive materials.
Supply Chain Analysis
Certification and qualification requirements gate supplier entry, with ASTM E2357 system testing and Health Canada PMRA antimicrobial reviews creating 12-24 month approval timelines. Methyl chloride and silicon metal feedstocks concentrate in Chinese and German production basins, exposing North American formulators to freight cost volatility and tariff exposure. Raw material dependencies span silicon metal, propylene oxide for polyether polyols, and isocyanate precursors. Single-source vulnerability characterizes specialty silane-modified polymer synthesis, where formulation chemist scarcity concentrates technical knowledge at limited technical centers. Distribution runs through national wholesale frameworks anchored by adhesive-sealant bundling relationships with contractor loyalty programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
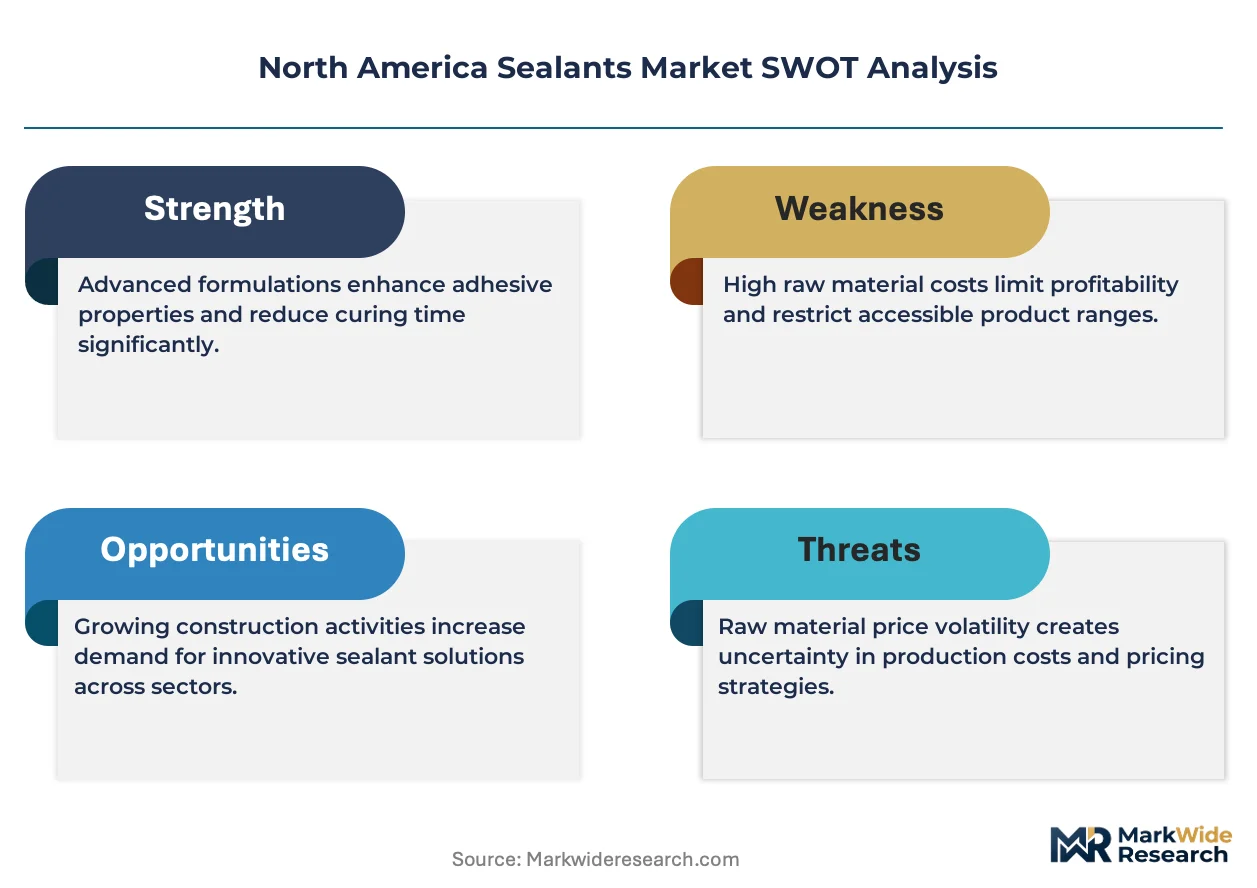
North America sealants function as a cost-of-compliance market where California SCAQMD Rule 1168 and EPA 40 CFR Part 59 erect barrier-to-entry moats favoring incumbent players with established regulatory dossiers and in-house testing capabilities.
For Market Incumbents:Hedge against silicone feedstock concentration by securing long-term offtake agreements with Chinese and German methyl chloride suppliers or investing in captive silicon metal processing capacity. Consolidate specification authority through ASTM E2357 air-barrier assembly pre-certification, creating switching costs for general contractors under consolidated procurement mandates. Prioritize silyl-terminated polyurethane R&D to capture share from solvent-based polyurethane displacement under tightening VOC thresholds.
For New Entrants and Emerging Players:Capture white-space opportunity in electric vehicle battery pack sealing, where thermal runaway protection and IP67 ingress specifications are driving new qualification cycles at Michigan, Tennessee, and Ontario assembly plants. Target retrofit building envelope upgrades across Canada and northern US commercial stock constructed before 1990, where blower-door test compliance creates demand for modern air-barrier systems with limited incumbent penetration. Pursue direct technical audit pathways with wind energy OEMs rather than distributor-dependent construction channels.
For Investors and Strategic Acquirers:Health Canada PMRA antimicrobial claim approval acceleration is the leading indicator that cross-border product launch velocity is improving for qualified manufacturers. The 5-10 year viability window favors acquisition targets with established silicone feedstock integration or silyl-terminated polyurethane synthesis capabilities, positioned to capture specification share from regulatory-driven chemistry transitions. Monitor federal Buy America procurement threshold adjustments as the primary signal for domestic manufacturing reshoring incentives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Metal | Captive methyl chloride supply secures pricing leverage against Chinese and German feedstock concentration. |
| ASTM E2357 Pre-Certification Investment | In-house air-barrier testing capabilities consolidate specification authority under ASHRAE Standard 90.1 mandates. |
| Silyl-Terminated Polyurethane Scale-Up | Paintable, low-VOC formulations capture share from solvent-based polyurethane displacement under SCAQMD Rule 1168. |
| EV Battery Pack Sealing Qualification | Thermal runaway protection specifications at Michigan and Ontario plants open new margin pools outside construction. |
| Buy America Compliance Reshoring | Domestic production qualification for DOT-funded infrastructure projects captures federal procurement preference. |
Research Methodology
Trade association filings, customs and import records, and SEC 10-K disclosures formed the secondary backbone for volume and value estimation. Primary interviews with formulation chemists, commercial contractor procurement managers, national distributor category heads, and wind energy OEM technical auditors validated chemistry-specific demand assumptions. Bottom-up triangulation across product type, application, and end-user segments reconciled with top-down construction spending and automotive production indices.
Historical trendline analysis established baseline growth patterns across silicone, polyurethane, acrylic, and epoxy chemistries. The projection framework modeled demand across chemistry type, application criticality, end-user procurement centralization, and regional regulatory cluster throughout the forecast period. CAGRs derived from segment-level growth drivers including LEED v4.1 adoption velocity, wind turbine blade length expansion, and EV battery pack sealing specification intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal Buy America threshold adjustments and silicone feedstock tariff regimes. Model outputs reflect assumptions around SCAQMD Rule 1168 enforcement consistency and Health Canada PMRA review timeline normalization. A model refresh is warranted upon material change in ASHRAE energy code adoption schedules or EPA 40 CFR Part 59 VOC threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
North America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
Cycloaliphatic Epoxy Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
Russia Adhesives Market
Adhesives & Sealants
Chemical Anchors Market