
 Global Silicone Adhesives and Sealants Market | 2026-2036
Global Silicone Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silicone Adhesives and Sealants Market Foresight
Aftermarket service revenue is rewriting margin capture across the value chain as OEMs extend adhesive lifecycle accountability. Dow leverages backward integration into siloxane feedstocks to sustain cost discipline across construction and electronics grades. Henkel AG & Co. KGaA anchors its position through R&D intensity in automotive bonding applications, while Sika AG dominates distribution channels in European building envelope systems.
Silicone adhesives and sealants are elastomeric materials formulated from siloxane polymers that cure via moisture, heat, or UV activation to form flexible bonds with temperature stability from minus sixty to over two hundred degrees Celsius; their primary purpose is to seal joints, dampen vibration, and thermally interface dissimilar substrates in demanding environments. Neutral cure formulations lead in electronics assembly where acetic acid byproducts would corrode copper traces, while UV cure technology captures the fastest growth as electronics miniaturization demands instantaneous processing without thermal damage. Structural silicone RTV products concentrate margin pools in aerospace component assembly where certification barriers limit supplier entry.
The EPA governs VOC emissions in US construction sealants, while REACH and RoHS in Europe restrict hazardous substances in electronics-grade formulations, collectively forcing reformulation investments that favor solvent-free and water-based technologies. China's MEE enforces dual carbon goals that tighten energy intensity benchmarks for silicone monomer production, reshaping cost structures for domestic and export supply. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which cure chemistry platforms will retain multi-region market access.
Market Dynamics
Electric vehicle battery pack thermal management is concentrating silicone demand among certified suppliers capable of meeting automotive OEM validation cycles, compressing qualification timelines and reshaping formulation R&D priorities across the value chain.
Growth Catalysts
- REACH VOC thresholds:European solvent-free mandates are accelerating water-based and 100% solids formulation shifts, opening substitution windows for compliant producers in construction sealants.
- EV battery assembly:Thermal interface materials for cell-to-pack bonding are expanding silicone volumes as manufacturers prioritize flame-retardant potting compounds with dielectric stability.
- China dual carbon enforcement:MEE energy intensity benchmarks for siloxane monomer production are consolidating domestic supply toward integrated producers with captive chlorosilane capacity.
Market Restraints
- Siloxane feedstock concentration:Four producers control over seventy percent of global dimethylsiloxane supply, creating price volatility transmission to formulated product margins.
- Fluorosilicone substitution:Aerospace fuel-contact applications are migrating toward fluorinated elastomers where extreme chemical resistance outweighs cost premiums.
- RoHS substance restrictions:Legacy tin catalyst systems face phase-out timelines in electronics-grade formulations, forcing reformulation investments without immediate price recovery mechanisms.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and mobile device assembly are creating localized demand for neutral-cure electronics-grade silicones without established domestic supply bases.
- UV-LED cure convergence:Instantaneous processing without thermal damage is enabling miniaturized wearable device assembly where traditional heat-cure systems damage adjacent components.
- Building envelope retrofit mandates:Germany's federal energy efficiency standards for existing commercial structures are expanding renovation-grade structural glazing sealant volumes beyond new construction cycles.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in moisture-cure kinetics and filler-siloxane compatibility is concentrating among aging technical workforces without adequate pipeline replenishment.
- Aerospace certification timelines:FAA and EASA material qualification cycles extend eighteen to thirty-six months, locking working capital and delaying revenue recognition for developmental grades.
- Legacy inventory integration:Acquired product portfolios carry incompatible cure chemistry platforms that fragment production scheduling and complicate customer technical service standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silicone Adhesives and Sealants Market |
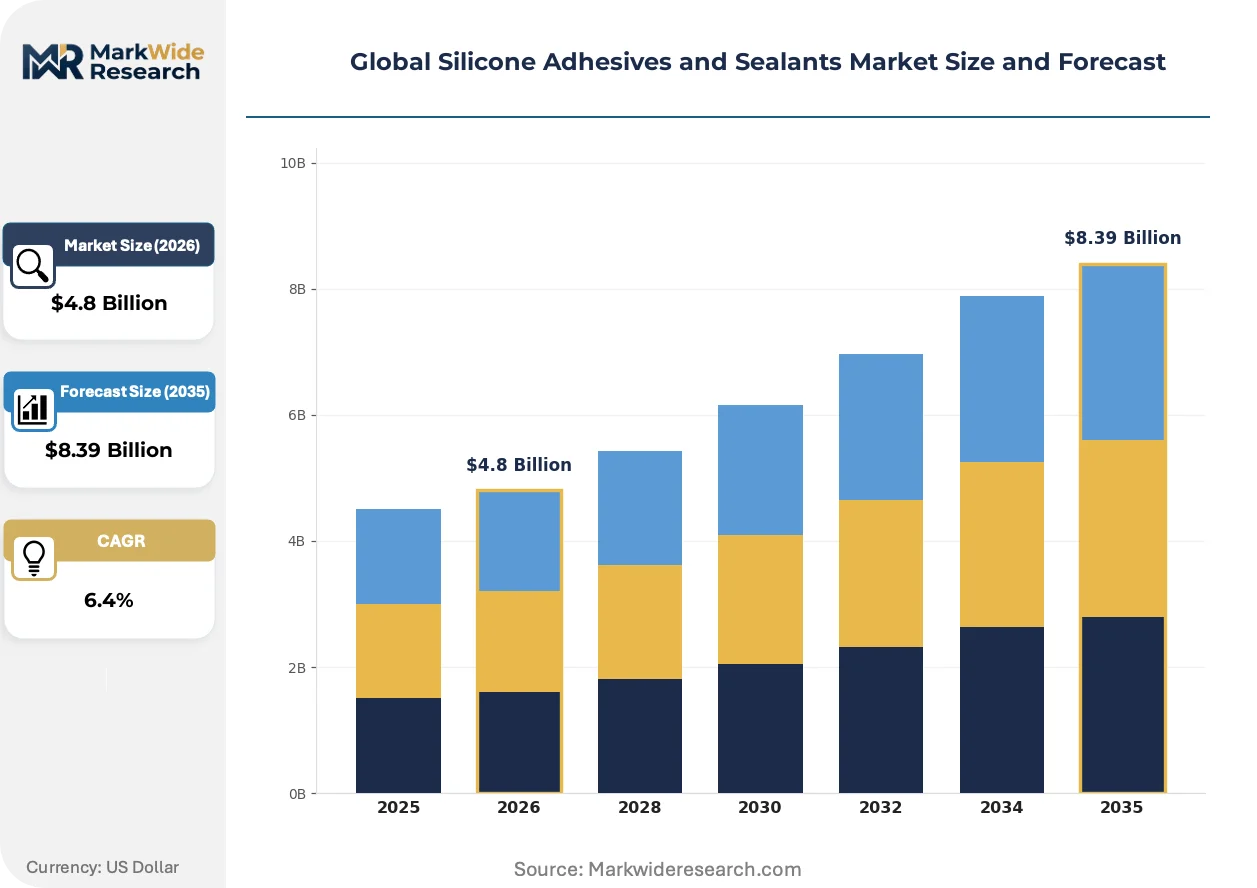
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetoxy Cure, Neutral Cure, High Temperature, Low Modulus, Silicone RTV, Structural Technology: Solvent-Free, Solvent-Based, Water-Based, Hot Melt, Two-Part, UV Cure Application: Electronics Assembly, Construction Sealants, Automotive Bonding, Aerospace Component Assembly, Marine Equipment, Household Appliances End User: OEM Manufacturers, Aftermarket Suppliers, Tier-1 Assemblers, Contract Manufacturers |
| Companies Covered | Dow, Henkel AG & Co. KGaA, Sika AG, Wacker Chemie AG, 3M, H.B. Fuller Company, Shin-Etsu Chemical Company, KCC Silicone Corporation, Chengdu Guibao Science and Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silicone Adhesives and Sealants Market Shifts & Advancements
Formulation chemistry is pivoting toward instantaneous processing platforms and bio-attributed feedstocks, compressing traditional cure timelines while responding to scope-three emissions scrutiny from automotive and electronics OEMs.
Thermally conductive silicone gap fillers with boron nitride or aluminum oxide loading are rendering obsolete traditional thermal pads and greases in power electronics assembly. Automotive inverter and charging module manufacturers are specifying these materials for direct die-to-heatsink bonding. The shift is compressing bill-of-material complexity while demanding tighter viscosity control and automated dispensing compatibility.
EPA VOC emission limits for architectural sealants are tightening allowable solvent content in US construction applications. Formulators are responding with high-solids oxime-cure systems that maintain workability without volatile thinners. The regulatory pressure is most acute in California and Northeast corridor states with overlaying air quality management district rules.
Automotive OEMs are unbundling adhesive specification authority from tier-one module suppliers, centralizing material selection at platform engineering centers to ensure warranty traceability. Tier-one seating and lighting suppliers are losing formulation discretion as Stellantis, Ford, and Volkswagen consolidate approved material lists. This concentration is most visible in German and US Midwest manufacturing clusters where platform engineering authority resides.
Global Silicone Adhesives and Sealants Market Segmentation
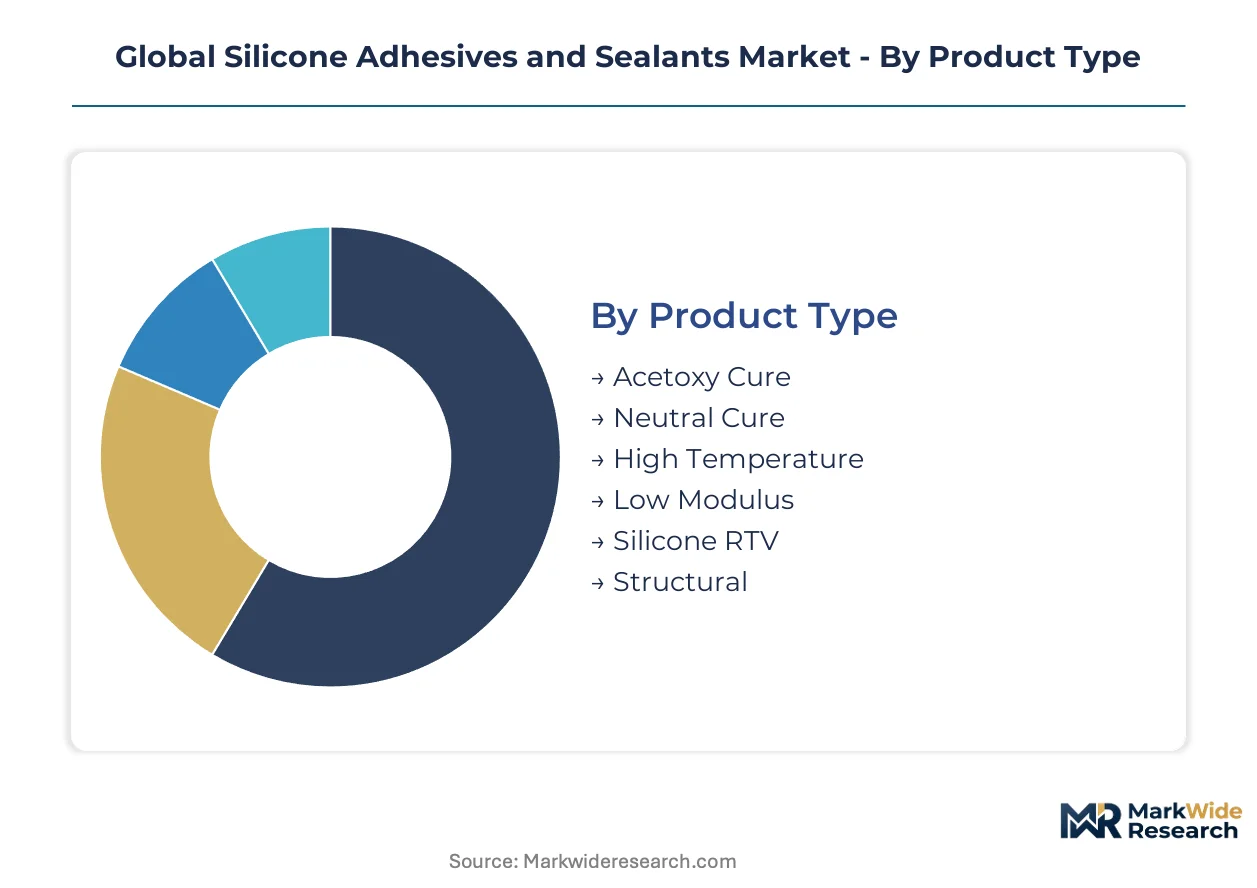
Silicone adhesive formulation chemistry and cure mechanisms fragment the competitive landscape into distinct technical tiers, each commanding different qualification barriers and margin structures. Understanding these segment boundaries reveals where capital deployment encounters regulatory friction versus technology pull.
Product Type:
Mature construction-grade formulations coexist with emerging electronics-specialized variants across this spectrum.
- Acetoxy Cure:Releases acetic acid during moisture-cure polymerization, producing aggressive adhesion to glass and ceramics. Construction glazing in Germany and California retains volume despite workplace ventilation requirements that limit indoor use. Acetoxy systems face substitution pressure from neutral-cure alternatives in healthcare and food-contact applications.
- Neutral Cure:Oxime or alkoxy cure chemistry eliminates corrosive byproducts, enabling direct contact with copper traces and sensitive electronics. Electronics assembly in Shenzhen and Bavaria concentrates demand as semiconductor packaging miniaturization accelerates. Alkoxy variants command premium positioning in automotive sensor modules where outgassing specifications are tightening.
- High Temperature:Phenyl-modified siloxane backbones maintain elastomeric properties above 250°C, serving aerospace engine nacelles and industrial oven gaskets.
- Low Modulus:High elongation formulations accommodate thermal cycling in curtainwall joints without cohesive failure.
- Silicone RTV:Room-temperature vulcanizing systems dominate maintenance-repair-overhaul operations across marine and industrial sectors.
- Structural:High-strength two-part systems bond glass fins in commercial facades, carrying dead loads without mechanical fasteners.
Neutral cure handles the majority of throughput; structural silicone is the fastest mover on share.
Technology:
Cost tier stratification separates commodity construction applications from precision electronics manufacturing.
- Solvent-Free:100% solids formulations eliminate VOC emissions entirely, satisfying California SCAQMD and Northeast Ozone Transport Commission thresholds. Automotive OEMs in Michigan and Stuttgart mandate solvent-free systems for interior air quality compliance. The technology commands formulation complexity premiums that solvent-based alternatives cannot match.
- UV Cure:Photoinitiated polymerization completes in seconds under 365nm LED arrays, enabling high-speed assembly of wearables and medical devices. Electronics contract manufacturers in South Korea and Taiwan specify UV cure for temperature-sensitive substrates adjacent to displays and batteries. Capital equipment requirements limit adoption to high-volume operations.
- Solvent-Based:Hydrocarbon-thinned systems retain workhorse status in exterior construction where open-air application mitigates exposure concerns.
- Water-Based:Emulsion polymers serve interior caulking and DIY markets with reduced odor profiles.
- Hot Melt:Reactive polyurethane-silicone hybrids bond automotive interior trim with rapid green strength development.
- Two-Part:Addition-cure systems with platinum catalysts deliver deep-section cure for potting and encapsulation.
Solvent-free technology carries the volume base; UV cure is climbing the fastest.
Application:
Customer type concentration separates specification-driven OEM procurement from price-sensitive maintenance channels.
- Electronics Assembly:Thermal interface materials, conformal coatings, and display bonding demand sub-ppm ionic purity and precise viscosity control. Semiconductor packaging facilities in Hsinchu and Dresden specify lot-traceable formulations with full material declaration compliance. Miniaturization trends are compressing dispensing tolerance windows to micron-scale repeatability.
- Automotive Bonding:Battery pack assembly, ADAS sensor encapsulation, and lighting module sealing require automotive-grade validation cycles spanning 24-36 months. OEM engineering centers in Wolfsburg and Detroit centralize material approval authority, bypassing traditional tier-one discretion. Flame-retardant specifications are tightening with UN ECE R100 propagation standards.
- Construction Sealants:Curtainwall, window perimeter, and expansion joint applications remain volume anchors despite cyclical new-build exposure.
- Aerospace Component Assembly:FAA and EASA qualification timelines lock suppliers into decade-long platform commitments.
- Marine Equipment:Pleasure craft and commercial vessel applications prioritize UV stability and saltwater immersion resistance.
- Household Appliances:Oven door gaskets and refrigerator liner bonding specify food-contact compliant formulations.
Construction sealants absorb the greatest throughput; electronics assembly is gaining share fastest.
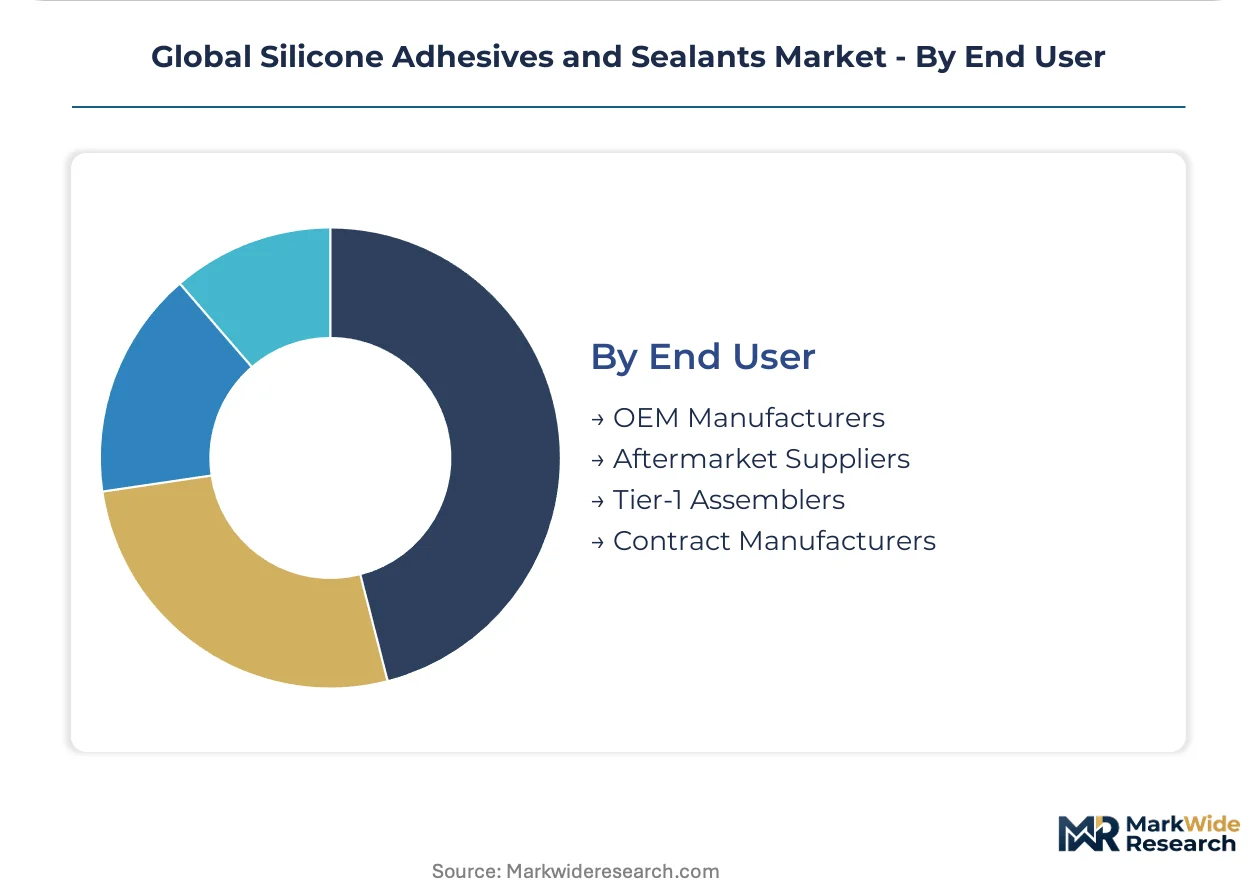
End User:
Supply concentration varies dramatically across direct OEM relationships versus fragmented distribution channels.
- OEM Manufacturers:Automotive and electronics original equipment manufacturers specify materials at platform engineering centers, consolidating procurement leverage. Stellantis, Samsung, and Siemens maintain approved material lists with 18-24 month qualification cycles. Direct relationships capture lifecycle value through warranty traceability requirements.
- Tier-1 Assemblers:Seating, lighting, and electronics module suppliers retain formulation discretion only in non-structural applications. Continental, Aptiv, and Magna source through consolidated supplier frameworks dictated by OEM central engineering.
- Aftermarket Suppliers:Maintenance-repair-overhaul distributors serve fragmented demand through retail and trade channels with lower technical service intensity.
- Contract Manufacturers:Foxconn, Jabil, and Flex operate on specification-driven procurement with limited formulation influence.
OEM manufacturers direct the largest volume flows; tier-1 assemblers are expanding their specification role slowest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: China and Germany absorb the heaviest volumes for automotive battery assembly, while the United States concentrates demand in aerospace and electronics applications with stricter certification requirements.
United States
Automotive OEMs in Detroit and aerospace manufacturers in Seattle specify flame-retardant thermal interface materials for EV battery packs and engine nacelles. The EPA enforces VOC emission limits for architectural sealants, tightening allowable solvent content in California and Northeast corridor states. Michigan and Ohio manufacturing clusters centralize procurement leverage at platform engineering centers.
Germany
Curtainwall retrofit mandates and automotive bonding applications concentrate silicone demand in Bavaria and North Rhine-Westphalia. REACH compliance and evolving VOC thresholds accelerate solvent-free formulation shifts across construction sealants. Stuttgart and Wolfsburg engineering centers unbundle adhesive specification authority from tier-one suppliers.
China
Electronics assembly in Shenzhen and semiconductor packaging in Hsinchu drive neutral-cure silicone consumption for display bonding and conformal coatings. The MEE enforces dual carbon goals that tighten energy intensity benchmarks for siloxane monomer production. Yangtze River Delta manufacturing clusters consolidate supply toward integrated producers with captive chlorosilane capacity.
Japan
Precision electronics and automotive sensor modules demand sub-ppm ionic purity formulations with lot-traceable material declarations. METI standards and JIS specifications govern product quality in semiconductor packaging applications. Kanto and Kansai industrial corridors host concentrated demand for UV-cure systems in wearable device assembly.
South Korea
Electronics contract manufacturers in Seoul and Busan specify UV-LED cure silicones for temperature-sensitive substrates in smartphone and display production. The MFDS regulates food-contact applications while industrial standards align with automotive OEM requirements. Gyeonggi-do manufacturing complexes drive fastest adoption of instantaneous processing platforms.
Global Silicone Adhesives and Sealants Market Competitive Landscape
Capability concentration sits with specialty chemical houses possessing siloxane feedstock control; scale advantage sits with diversified adhesives conglomerates serving multi-sector procurement frameworks. Four producers control over seventy percent of global dimethylsiloxane supply, creating tiered access to formulated product margins. The competitive landscape stratifies into integrated feedstock operators, formulation specialists, and regional distribution anchors. Dominant competitive moves include backward integration into chlorosilane production and consolidation of approved material lists at automotive OEM engineering centers.
Within the integrated feedstock tier, Dow and Wacker Chemie AG exemplify producers with captive siloxane capacity spanning construction and electronics grades. Henkel AG & Co. KGaA and Sika AG occupy positions as formulation specialists with R&D intensity concentrated in automotive bonding and European building envelope systems respectively. H.B. Fuller Company represents the diversified industrial adhesives archetype with multi-sector procurement reach.
| Leading Market Players |
|---|
| Dow |
| Henkel AG & Co. KGaA |
| Sika AG |
| Wacker Chemie AG |
| 3M |
| H.B. Fuller Company |
| Shin-Etsu Chemical Company |
| KCC Silicone Corporation |
| Chengdu Guibao Science and Technology Co., Ltd. |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta's siloxane monomer capacity concentration grants integrated producers outsized leverage over formulated product pricing, compressing margins for non-integrated compounders dependent on spot dimethylsiloxane procurement. This geographic supply dominance translates directly into tiered pricing power where captive chlorosilane operators capture value upstream while downstream formulators absorb volatility.
Pricing Analysis
Long-term offtake contracts dominate procurement between automotive OEMs and certified silicone suppliers, insulating volume commitments from spot siloxane fluctuations. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified grades from construction bulk and DIY retail tiers. Cost compression in construction-grade acetoxy systems is intensifying because Chinese export supply expansion outpaces European demand recovery. Tier-one automotive assemblers exhibit lowest price sensitivity due to warranty traceability requirements, while aftermarket distributors face margin erosion from commoditized retail sealant competition.
Supply Chain Analysis
Export control regimes restricting advanced silicone formulations to designated end-users limit technology transfer in semiconductor-grade materials, fragmenting supply access by application tier. China, Germany, and the United States anchor global dimethylsiloxane production, with South Korea and Japan contributing specialty phenyl-modified feedstocks. Formulated product manufacturing draws from chlorosilane precursors, fumed silica fillers, and platinum catalyst systems. Single-source vulnerability concentrates in aerospace-qualified structural grades where FAA and EASA certification locks suppliers into decade-long platform commitments. Distribution runs through direct OEM specification channels for automotive and electronics grades, with construction sealants flowing via regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as EV battery assembly volumes normalize post-supply-constraint disruption, with thermal interface material demand anchoring silicone consumption expansion through the decade.
For Market Incumbents: Insulate margin pools by deepening backward integration into siloxane feedstocks or securing long-term chlorosilane offtake agreements with Yangtze River Delta producers. Prioritize certification investment in UN ECE R100 flame-retardant grades to defend against fluorosilicone substitution in aerospace fuel-contact applications. Channel control through approved material list consolidation at Stuttgart and Detroit engineering centers locks out non-qualified competitors.
For New Entrants and Emerging Players: Establish a beachhead in India's electronics assembly sector where PLI scheme incentives outrun domestic silicone supply development. Target neutral-cure electronics-grade formulations for semiconductor packaging facilities in Hsinchu and Bengaluru before integrated players localize production. A technical service-heavy go-to-market approach overcomes qualification timeline disadvantages against incumbent relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because formulation chemist scarcity and aging technical workforces concentrate acquirable expertise among mid-cap specialists. Watch for MEE dual carbon enforcement tightening as the inflection signal that vertically integrated Chinese producers will seek Western distribution assets to bypass export cost pressures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Production | Captive siloxane supply insulates margin compression from feedstock volatility concentrated among four global producers. |
| UV-LED Cure Platform Development | Instantaneous processing capability captures wearable device assembly demand in South Korean and Taiwanese electronics clusters. |
| Aerospace Qualification Investment | FAA and EASA certification locks suppliers into decade-long platform commitments with limited competitor entry. |
| India Electronics Manufacturing Localization | PLI scheme incentives create first-mover advantage before domestic supply bases mature in semiconductor packaging. |
| Solvent-Free Formulation Transition | REACH and EPA VOC compliance opens substitution windows in California SCAQMD and Northeast corridor construction markets. |
Research Methodology
Desk research of customs trade databases, SEC 10-K filings, and ECHA REACH registration data preceded structured interviews with silicone plant managers, automotive OEM procurement leads, electronics contract manufacturer technical directors, and European building envelope distributors. Primary fieldwork across Bavaria, Michigan, and Shenzhen manufacturing clusters was cross-referenced against ACC and Cefic industry reports. Bottom-up volume modeling triangulated against top-down value estimates from production capacity disclosures.
Assumptions held fixed include current REACH and EPA VOC regulatory thresholds, existing automotive OEM qualification cycle durations, and siloxane feedstock concentration among four major producers. Segmentation dimensions modeled encompass cure chemistry platform, technology tier, end-use application, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections across the analysis window, with EV battery pack thermal interface material content per vehicle serving as a primary volume driver alongside building envelope retrofit mandate penetration rates.
Stress conditions across siloxane feedstock price volatility, MEE dual carbon enforcement intensity, and automotive platform electrification pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and industry stakeholder consensus. Material shifts in aerospace certification timeline compression or fluorosilicone substitution acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
Global Spray Adhesive Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Germany Sealants Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
Marine Sealants Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
Rubber Repair Adhesives Market
Adhesives & Sealants
Global Anti-Tack Agents Market
Adhesives & Sealants
Thailand Adhesives and Sealants Market
Adhesives & Sealants
Chemical Anchors Market