
 Applicator Tips Market | 2026-2036
Applicator Tips Market Size, Share, and Industry Trends Forecast 2026-2036
Applicator Tips Market Outlook
Medical device distribution is fragmenting across specialized consumable suppliers and integrated platform vendors. Designetics Inc. leverages its precision fluid application expertise to serve automated manufacturing lines. Microbrush International, Ltd. anchors the dental and micro-applicator niche with proprietary fiber technology. James Alexander Corporation competes through backward integration into custom plastic molding for diagnostic applications.
Applicator tips are precision-molded or machined components, typically constructed from polypropylene, stainless steel, or bonded fiber bundles, designed to control fluid volume, flow rate, and placement accuracy in clinical, industrial, and cosmetic procedures. Plastic tips dominate pharmaceutical packaging due to cost scalability and compatibility with blow-fill-seal systems, while disposable metal tips command premium positioning in surgical navigation and robotic dispensing where autoclave sterilization cycles would degrade polymer integrity. The medical devices application segment sustains above-average margins through regulatory certification barriers and long qualification timelines, whereas industrial coating applications occupy a more price-sensitive, high-volume tier.
The FDA enforces biocompatibility testing under ISO 10993 for all patient-contact applicator materials, while the EU MDR requires renewed clinical evaluation and notified body certification for reusable surgical tips. The EPA regulates industrial solvent-based applicators through volatile organic compound emission standards, particularly affecting metal cleaning and coating operations. Stakeholders must monitor evolving polymer recycling mandates and material passport requirements that will reshape sourcing decisions for single-use plastic tips.
Market Dynamics
Precision manufacturing lines in pharmaceutical packaging are forcing applicator tip suppliers to consolidate dispensing accuracy with blow-fill-seal compatibility, compressing supplier qualification timelines from 18 months to under 12 months.
Growth Catalysts
- EU MDR material certification:The EU MDR's renewed clinical evaluation requirements for reusable surgical tips are accelerating demand for pre-certified, single-use polymer alternatives in German and Swiss manufacturing corridors.
- Robotic dispensing adoption:Automated coating lines in automotive electronics are pulling precision-machined stainless steel tips into high-throughput assembly operations.
- Micro-applicator fiber technology:Bonded fiber bundles are displacing molded plastic in dental adhesive applications where controlled fluid retention determines clinical outcomes.
Market Restraints
- Polypropylene feedstock volatility:Crude oil price swings directly compress margins for blow-molded pharmaceutical tips where resin constitutes 60% of unit cost.
- German supply concentration:Tuttlingen's medical device cluster controls precision metal tip machining capacity, creating geographic single-source risk for robotic dispensing OEMs.
- Autoclave degradation limits:Polymer integrity loss after repeated sterilization cycles blocks reusable polymer tips from surgical navigation systems.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO's accelerated approval pathways for imported medical devices are opening qualification windows for disposable tip suppliers in Mumbai-Pune manufacturing zones.
- Bio-based polymer mandates:The EU Green Deal's packaging waste directive is creating first-mover advantage for suppliers with certified compostable polypropylene alternatives.
- Point-of-care diagnostic integration:Lateral flow assay manufacturers are sourcing custom-molded tips with integrated reagent chambers, merging fluid handling with consumable design.
Industry Challenges
- ISO 10993 testing backlog:Biocompatibility certification queues at notified bodies are extending product launch timelines for patient-contact polymer formulations.
- Legacy molding equipment retooling:Converting steel molds for micro-feature precision requires capital outlays that mid-tier suppliers struggle to finance.
- Multi-material recycling complexity:Bonded fiber-plastic composite tips fall outside standard polymer waste streams, complicating compliance with extended producer responsibility schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Applicator Tips Market |
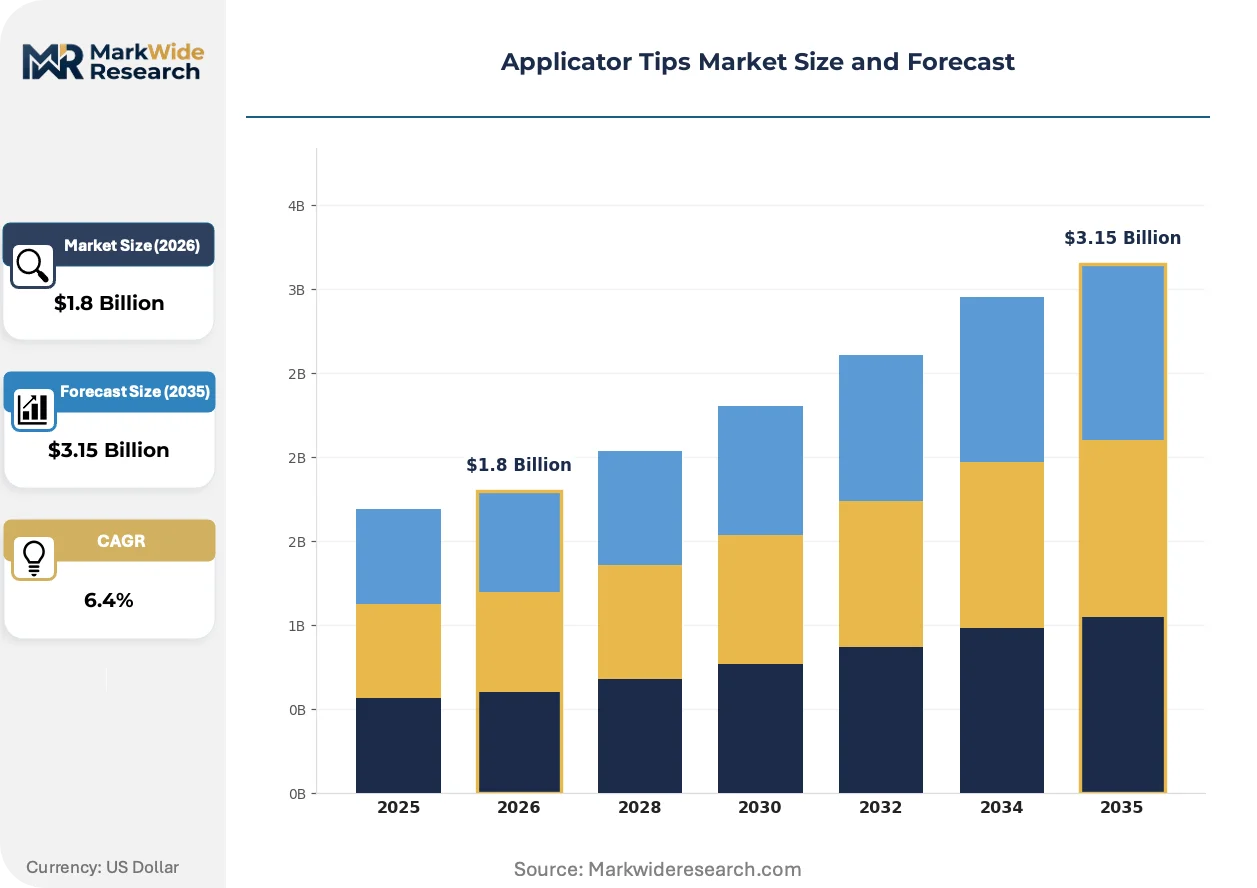
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal, Plastic, Disposable, Reusable Application: Cosmetics, Pharmaceuticals, Industrial, Medical Devices End User: Clinics, Hospitals, Pharmacies, Individuals Size: Small, Medium, Large, Extra Large |
| Companies Covered | Designetics Inc., Microbrush International, Ltd., James Alexander Corporation, TMP Technologies, Inc., Ada Products Company, Inc., HTI Plastics, Inc., Medtronic, Becton Dickinson, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Applicator Tips Market Strategic Shifts
Active dispensing systems are merging mechanical precision with embedded sensing, transforming applicator tips from passive conduits into process-control instruments that feed real-time data back to manufacturing execution systems.
Multi-material extrusion is hybridizing polypropylene with liquid silicone rubber to create tips combining rigid fluid channels with soft patient-contact surfaces. German dental equipment manufacturers are qualifying these hybrid tips for impression material dispensing. The technology is hybridizing previously separate rigid and elastomer tip categories into unified product platforms.
The FDA's updated guidance on ISO 10993-18 chemical characterization is requiring exhaustive extractables testing for all fluid-contact polymers. Small-batch pharmaceutical packagers face six-figure testing costs per material formulation. Disposable diagnostic tip suppliers are responding by consolidating material platforms to amortize certification investments across higher volumes.
Diagnostic OEMs are unbundling tip supply from instrument service contracts, shifting procurement to competitive bidding against specialized consumable catalogs. This disintermediation is compressing pricing power for integrated platform vendors. The pattern is most visible in US clinical laboratory networks where procurement teams now source tips separately from analyzer maintenance agreements.
Applicator Tips Market Segmentation
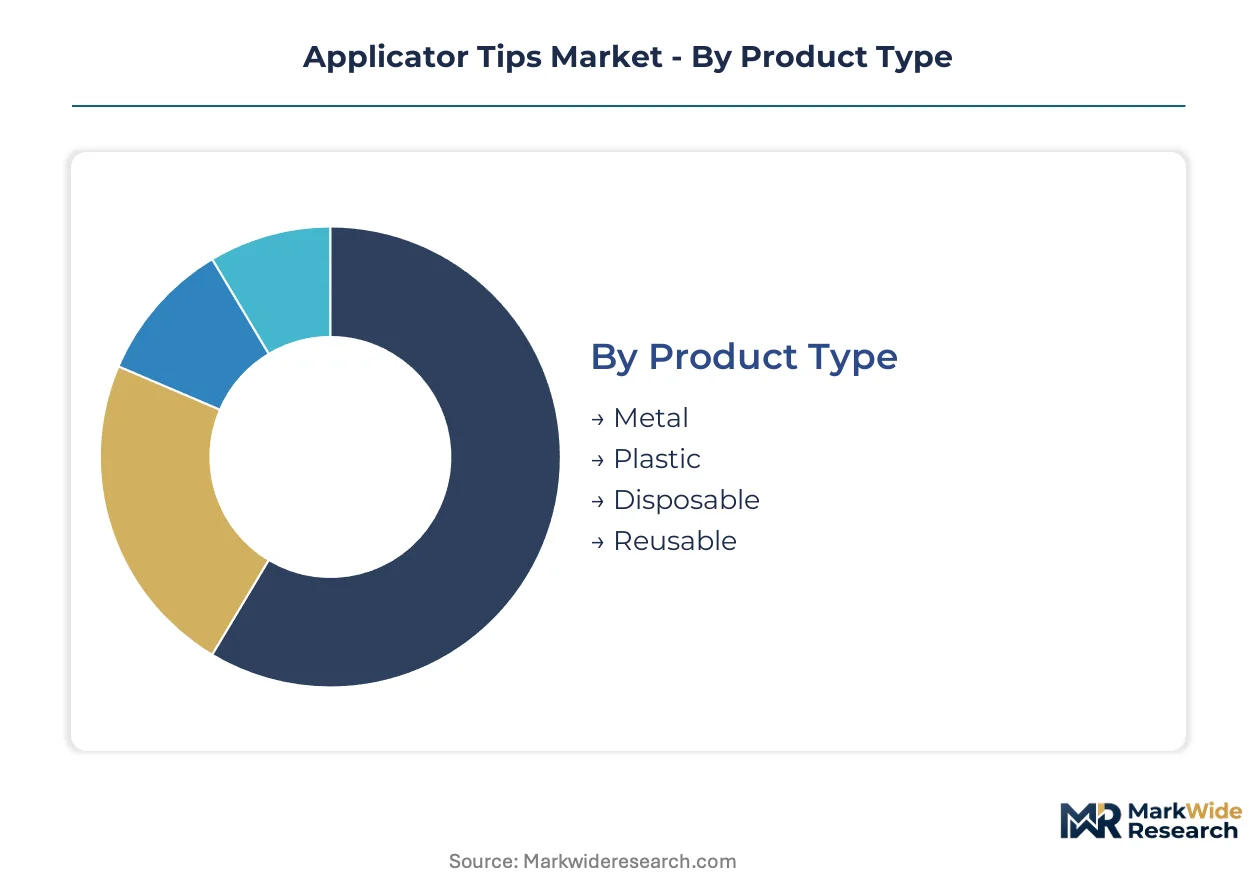
Applicator tip suppliers must align product architectures with distinct sterilization protocols, regulatory pathways, and automation interfaces across end-use environments. Segmentation reveals where technical specifications diverge and where platform designs achieve cross-vertical economies.
Product Type:
After-sales service intensity varies sharply across material categories, with reusable metal tips demanding calibration programs and polymer disposables requiring high-velocity replenishment logistics.
- Metal:Machined stainless steel or nickel-titanium alloys deliver sub-millimeter precision for robotic dispensing and surgical navigation. German automotive electronics manufacturers specify these for coating lines where thermal stability exceeds polymer limits.
- Plastic:Injection-molded polypropylene dominates pharmaceutical blow-fill-seal integration due to cost scalability and gamma sterilization compatibility. Blow-molded variants serve high-volume diagnostic packaging where resin cost sensitivity constrains design freedom.
- Disposable:Single-use polymer tips eliminate cross-contamination risk in point-of-care diagnostics and dental procedures. CDSCO's accelerated device approval pathways in India are expanding qualification windows for imported disposable platforms.
- Reusable:Autoclavable metal or high-performance polymer tips serve surgical navigation systems where instrument longevity amortizes per-procedure costs. EU MDR clinical evaluation requirements are compressing addressable markets for these platforms.
Plastic holds the largest share; momentum sits with Disposable.
Application:
Margin structures diverge across application verticals based on regulatory certification depth and customer concentration.
- Cosmetics:Precision-molded polymer tips control serum and cream dispensing in premium packaging. South Korean beauty manufacturers specify micro-applicators with controlled droplet formation for essence formulations.
- Pharmaceuticals:Blow-fill-seal compatible tips integrate with aseptic packaging lines for ophthalmic and injectable products. FDA ISO 10993 biocompatibility testing mandates extend supplier qualification timelines beyond eighteen months.
- Industrial:Solvent-resistant metal tips serve automotive electronics coating and semiconductor flux dispensing. EPA volatile organic compound emission standards constrain cleaning chemistry options for these applications.
- Medical Devices:Surgical navigation and robotic surgery platforms demand sterilization-stable precision components. Swiss orthopedic instrument manufacturers in the Tuttlingen corridor specify these for navigated implant procedures.
Medical Devices commands premium pricing; Pharmaceuticals is expanding most quickly.
End User:
Procurement authority and volume concentration shape supplier engagement models across customer types.
- Clinics:Outpatient dental and dermatology practices source bonded fiber micro-applicators for adhesive and filler procedures. German dental equipment distributors bundle these with impression material systems.
- Hospitals:Integrated delivery networks negotiate consolidated contracts for surgical and diagnostic consumables. US clinical laboratory networks now unbundle tip procurement from analyzer service agreements.
- Pharmacies:Retail and compounding pharmacies stock standardized dispensing tips for topical medication packaging. Mumbai-Pune manufacturing zones supply these through regional distribution networks.
- Individuals:Direct-to-consumer cosmetic and wellness applicators emphasize ergonomic design and single-use hygiene. E-commerce channels are compressing traditional retail distribution for these SKUs.
Hospitals hold the largest share; Individuals is gaining share fastest.
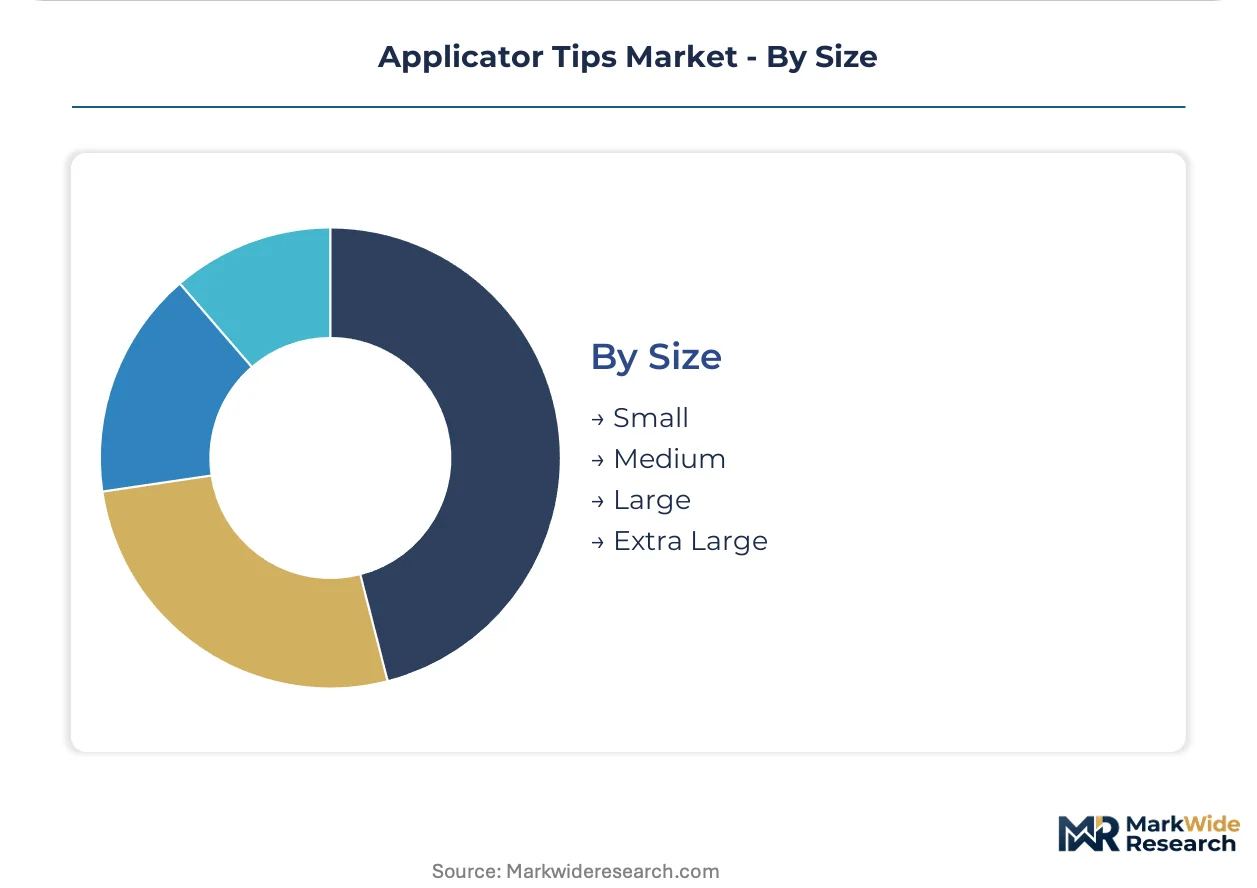
Size:
Dimensional specifications correlate with fluid viscosity ranges and placement precision requirements.
- Small:Micro-bore geometries below 0.5mm diameter serve dental adhesive dispensing and micro-dosing pharmaceutical packaging. Bonded fiber technology achieves these dimensions without mold flow limitations.
- Medium:Standard 0.5-2.0mm bore diameters balance flow rate control with clogging resistance. Most pharmaceutical blow-fill-seal lines specify these for ophthalmic and nasal spray applications.
- Large:2.0-5.0mm bores accommodate high-viscosity industrial coatings and topical pharmaceutical creams. Automotive underbody sealant dispensing employs these geometries.
- Extra Large:Bores exceeding 5.0mm serve construction adhesive and heavy industrial fluid transfer. These fall outside precision medical applications due to placement accuracy constraints.
Medium holds the largest share; Small shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision metal tip manufacturers command 40% pricing premiums over Indian blow-molded polymer suppliers, yet Mumbai-Pune packaging corridors are compressing that gap through CDSCO accelerated approvals.
United States
FDA ISO 10993 biocompatibility mandates drive six-figure testing costs per polymer formulation, favoring consolidated material platforms. EPA volatile organic compound standards constrain industrial solvent-based applicator cleaning chemistries. Boston-area diagnostic OEMs unbundle tip procurement from analyzer service contracts, shifting purchasing to competitive bidding.
Germany
Tuttlingen's medical device cluster controls precision metal tip machining capacity for robotic dispensing systems. EU MDR renewed clinical evaluation requirements compress addressable markets for reusable surgical platforms. Bavarian automotive electronics manufacturers specify stainless steel tips for thermal stability in coating lines.
India
CDSCO accelerated approval pathways for imported medical devices open qualification windows for disposable tip suppliers. Mumbai-Pune pharmaceutical packaging zones source blow-fill-seal compatible polymer tips through regional distribution networks. Domestic compounding pharmacies drive standardized dispensing tip demand for topical medications.
Japan
METI industrial automation initiatives pull precision-machined tips into high-throughput electronics assembly. PMDA quality management system requirements extend supplier qualification timelines for patient-contact polymers. Osaka-area dental equipment distributors bundle bonded fiber micro-applicators with impression material systems.
Switzerland
Swissmedic certification requirements sustain premium positioning for sterilization-stable surgical navigation components. Swiss orthopedic instrument manufacturers in the Tuttlingen-adjacent corridor specify autoclavable metal tips for navigated implant procedures. Geneva-based precision engineering firms supply sub-millimeter bore geometries for micro-dosing applications.
Applicator Tips Market Competitive Environment
Precision fluid application specialists and integrated medical device conglomerates split the market between customized automation solutions and standardized diagnostic platforms. The vendor base concentrates around three strategic archetypes: backward-integrated plastic molders serving pharmaceutical packaging, fiber technology specialists anchoring dental micro-applications, and diversified medtech conglomerates leveraging distribution scale. Competitive moves center on material platform consolidation to amortize biocompatibility certification costs and geographic expansion into CDSCO-accelerated Indian qualification windows.
Among precision engineering specialists, Designetics Inc. and Microbrush International, Ltd. occupy positions reflecting distinct specialization vectors—fluid application automation expertise versus proprietary fiber bundle technology. James Alexander Corporation anchors the backward-integrated molding tier, representing captive plastic production capabilities for diagnostic consumables. These three exemplify how mid-tier suppliers defend positioning through material science differentiation rather than scale-driven cost compression.
| Leading Market Players |
|---|
| Designetics Inc. |
| Microbrush International, Ltd. |
| James Alexander Corporation |
| TMP Technologies, Inc. |
| Ada Products Company, Inc. |
| HTI Plastics, Inc. |
| Medtronic |
| Becton Dickinson |
| Terumo Corporation |
| Others |
Value Chain & Pricing Dynamics
Tuttlingen's precision metal machining corridors are running near-full utilization, forcing buyers into longer lead-time commitments and compressing negotiating leverage for robotic dispensing OEMs seeking stainless steel tip supply. This capacity tightness simultaneously elevates configured-to-order premiums and accelerates substitution toward Indian blow-molded polymer alternatives where CDSCO accelerated approvals have expanded supplier options.
Pricing Analysis
Configured-to-order precision-machined metal tips command 35-50% premiums over standard catalog polymer equivalents, with the spread widening for sub-millimeter bore geometries requiring Swiss-grade tolerances. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 certification tier and autoclave cycle durability rather than raw material alone. Pricing pressure stems from diagnostic OEMs unbundling tip procurement from analyzer service contracts and forcing competitive bidding against specialized consumable catalogs. Pharmaceutical packaging buyers exhibit highest price sensitivity due to resin cost comprising 60% of unit economics, while surgical navigation system manufacturers absorb premium positioning for sterilization-stable metal platforms.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for Mumbai-Pune pharmaceutical packaging corridors, with supply-chain finance facilities emerging as competitive differentiators for mid-tier polymer molders seeking to displace German metal tip suppliers. Manufacturing gravity centers on Germany for precision-machined stainless steel, India for blow-molded polypropylene, and Switzerland for sub-millimeter bore geometries, with each node drawing from distinct feedstock bases. Raw material dependencies span polypropylene resin, nickel-titanium alloys, and bonded fiber bundles, with crude oil price volatility transmitting directly through polymer tip margins. Single-source vulnerability concentrates in Tuttlingen's metal machining cluster for robotic dispensing applications. Distribution runs through specialized medical device distributors in Europe, regional packaging networks in India, and unbundled competitive bidding platforms in US clinical laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR material certification requirements are disrupting established reusable surgical tip economics, creating acceleration windows for pre-certified single-use polymer platforms and compressing qualification timelines for suppliers with consolidated material portfolios.
For Market Incumbents: Pre-empt margin erosion from unbundled diagnostic procurement by consolidating material platforms to amortize ISO 10993 testing investments across higher volumes. Lock in Tuttlingen metal machining capacity through long-term offtake agreements before robotic dispensing OEMs diversify sourcing to Indian alternatives. Deepen backward integration into custom plastic molding for point-of-care diagnostic applications where integrated reagent chamber designs are merging fluid handling with consumable architecture.
For New Entrants and Emerging Players: Mumbai-Pune pharmaceutical packaging zones represent the most penetrable entry point for disposable polymer tip suppliers leveraging CDSCO accelerated approval pathways against entrenched European competitors. Dental micro-applicator niches anchored by proprietary fiber technology offer defensible positioning with lower capital barriers than precision metal machining. Pursue white-label manufacturing partnerships with South Korean cosmetic packaging OEMs seeking micro-applicator sourcing for premium essence formulations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among backward-integrated plastic molders serving diagnostic consumables with multi-year GPO contracts and integrated reagent chamber designs. Long-term viability over the next decade hinges on material platform consolidation capabilities and biocompatibility certification asset bases rather than scale alone. Monitor CDSCO approval velocity and EU Green Deal packaging waste directive implementation as inflection signals for supplier repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Material Platform Consolidation | Amortizes six-figure ISO 10993 testing costs across higher diagnostic tip volumes. |
| CDSCO Accelerated Qualification | Opens Mumbai-Pune pharmaceutical packaging corridors for imported disposable platforms. |
| Multi-Material Extrusion Investment | Hybridizes rigid polypropylene channels with soft liquid silicone rubber for dental applications. |
| Active Dispensing System Integration | Transforms passive tips into process-control instruments feeding manufacturing execution systems. |
| Extended Producer Responsibility Compliance | Anticipates EU Green Deal mandates reshaping single-use plastic tip sourcing decisions. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the applicator tips value chain, including pharmaceutical packaging engineers, surgical navigation system procurement leads, dental equipment distributors, and blow-fill-seal line operators. Primary interview insights were cross-validated against secondary sources spanning FDA 510(k) filings, EU MDR notified body certification databases, CDSCO import approval registries, and customs trade data for polypropylene resin and precision metal components. Bottom-up unit economics modeling and top-down market sizing triangulation ensured convergence across independent estimation approaches.
Calibration against historical volume trajectories and regulatory approval velocities anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass material category, sterilization protocol, end-use application, and regional regulatory cluster complexity. CAGRs were derived from slope-intercept analysis of approval pathway acceleration, automation adoption curves in automotive electronics coating, and substitution dynamics between reusable metal and single-use polymer platforms. Industry-specific forecast inputs incorporated EU MDR clinical evaluation timeline compression and METI industrial automation initiative funding disbursements.
Macroeconomic conditions sit as an overlay; deviation in crude oil price volatility, euro-rupee exchange rates, or polymer recycling mandate enforcement timelines would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval velocity and automation capital expenditure cycles. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
Marine Sealants Market
Adhesives & Sealants
Global Silicone Adhesives Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
Ocular Adhesives and Sealants Market
Adhesives & Sealants
Mexico Adhesives Market
Adhesives & Sealants
Firestop Sealants Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Middle-East and Africa Contact Adhesives Market
Adhesives & Sealants
United States Adhesives Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
Russia Adhesives Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market