
 Dimethylaminoethyl Acrylate Market | 2026-2036
Dimethylaminoethyl Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Dimethylaminoethyl Acrylate Market Analytics
Aftermarket service revenue for specialty acrylate formulation consulting is reshaping margin distribution between raw monomer suppliers and downstream blenders. BASF SE leverages its Ludwigshafen integrated site to sustain captive DMAEA supply for captive polymerization. Evonik Industries AG anchors its position through R&D intensity in amino-functional monomer derivatives. Dow Chemical Company competes via geographic dominance in North American industrial coatings channels.
Dimethylaminoethyl acrylate is a tertiary amine-functional acrylate monomer with a molecular weight of approximately 157.2 g/mol, synthesized through esterification of acrylic acid with dimethylaminoethanol and employed primarily as a reactive diluent and adhesion promoter in radiation-curable and waterborne systems. The monomer segment dominates volume flows due to its role as the foundational feedstock for polymer and copolymer production. Coatings applications lead value capture, while adhesives represent the fastest-growing application as electronics miniaturization drives demand for low-VOC, high-bond-strength formulations.
EPA TSCA Section 5 premanufacture notification requirements govern new DMAEA introductions in the United States, while REACH registration mandates in Europe enforce comprehensive toxicological dossiers for continued market access. China's MEE administers emission standards for acrylate production facilities under its dual carbon policy framework. Stakeholders must monitor evolving chemical hazard classifications across these jurisdictions to anticipate reformulation requirements and supply chain qualification changes.
Market Dynamics
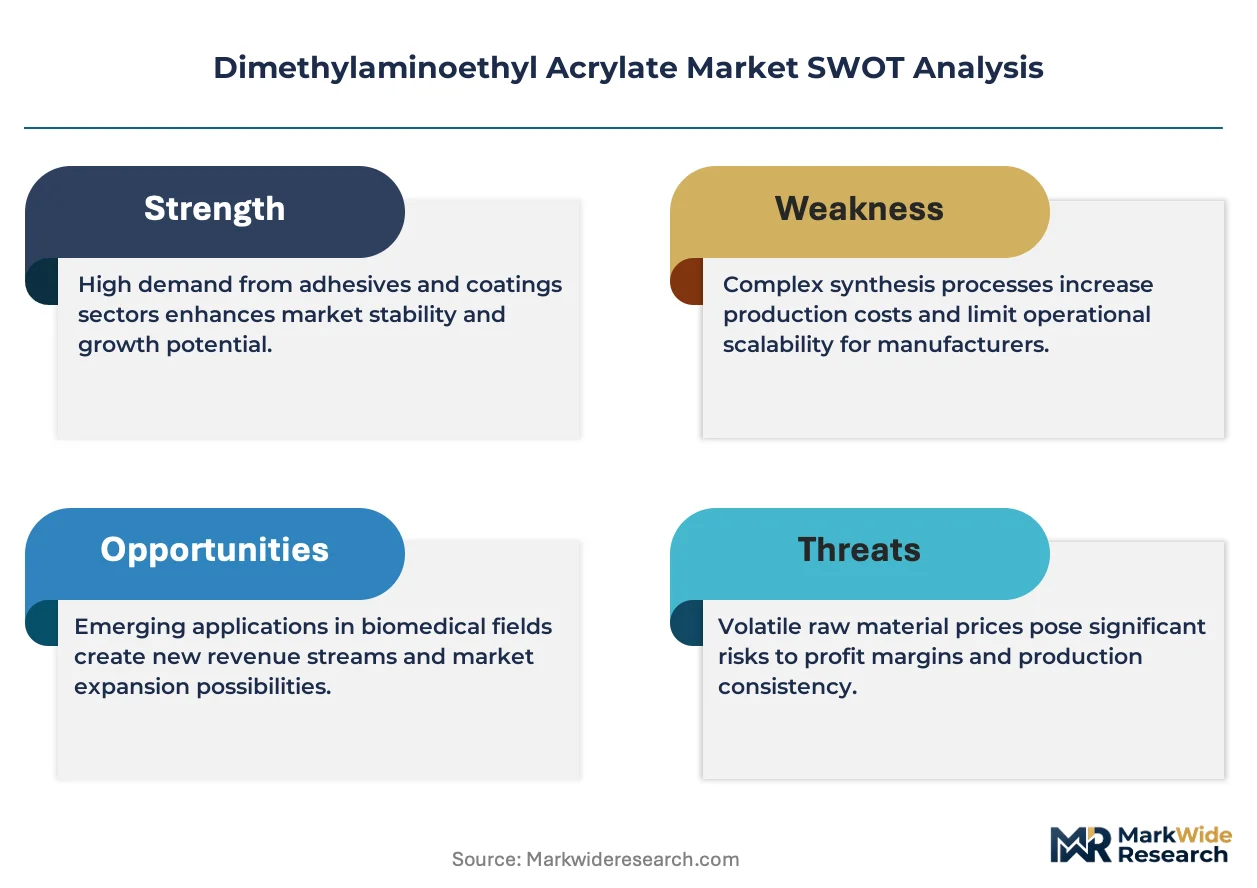
REACH registration mandates in Europe are compressing the supplier base for dimethylaminoethyl acrylate by disqualifying non-compliant producers from the import channel, while electronics-grade adhesive demand in China pulls formulation investment toward higher-purity monomer specifications.
Growth Catalysts
- Waterborne coating formulations:Adhesives producers in Guangdong province are redirecting R&D budgets toward low-VOC DMAEA-based systems for electronics miniaturization applications.
- REACH chemical registration:The tightening purity thresholds for acrylate imports into Europe are forcing incumbent suppliers to upgrade distillation capabilities, inadvertently raising barriers for marginal competitors.
- Radiation-curable systems:UV-LED curing technology adoption in industrial coatings is expanding the addressable market for DMAEA as a reactive diluent with rapid polymerization kinetics.
Market Restraints
- Acrylic acid feedstock volatility:Crude propylene price swings transmit directly into DMAEA production economics, compressing margin predictability for non-integrated formulators.
- Supplier concentration in Ludwigshafen:Captive production at the BASF SE integrated site limits spot market liquidity and creates single-source vulnerability for European buyers.
- Amino-functional monomer substitution:Dimethylaminoethyl methacrylate offers comparable adhesion promotion with lower skin sensitization profiles in certain medical-grade applications.
Strategic Opportunities
- India specialty chemicals:The PLI scheme for chemical manufacturing is attracting greenfield DMAEA investment to serve domestic electronics and automotive adhesive demand.
- Dual carbon policy framework:China's MEE emission standards for acrylate production facilities are accelerating consolidation, creating acquisition targets for compliant operators.
- UV-LED and waterborne convergence:Hybrid curing systems combining both technologies are opening formulation white space in furniture and flooring coatings.
Industry Challenges
- Toxicological dossier compilation:REACH registration requires extensive mammalian study data that smaller producers struggle to fund without consortium participation.
- Electronics-grade certification timelines:Qualification for semiconductor packaging adhesives demands 18-24 month validation cycles that lock up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimethylaminoethyl Acrylate Market |
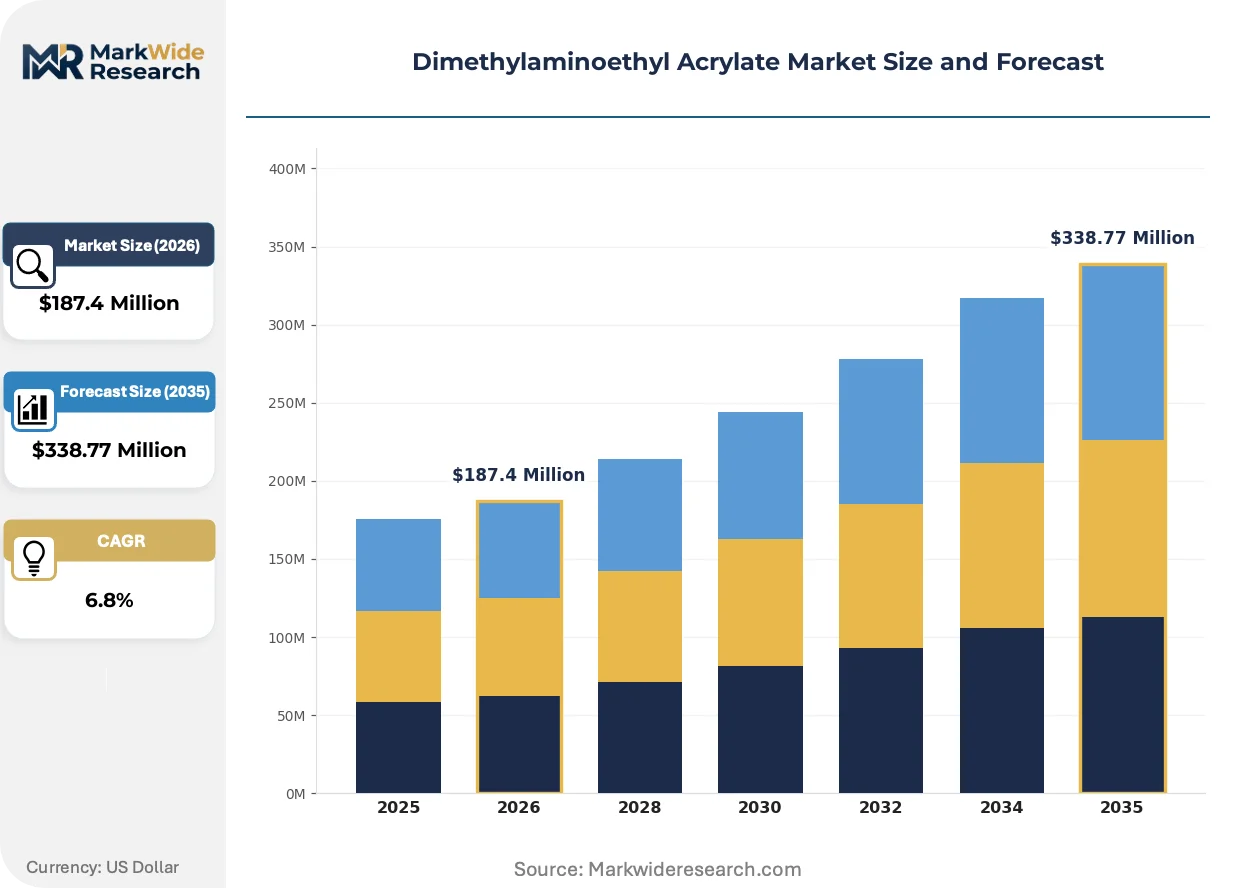
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monomers, Polymers, Copolymers, Emulsions Application: Adhesives, Coatings, Textiles, Inks End User: Construction, Automotive, Electronics, Healthcare Delivery Mode: Liquid, Powder, Paste, Granule |
| Companies Covered | BASF SE, Evonik Industries AG, Dow Chemical Company, Arkema, Nippon Shokubai Co., Ltd., Mitsubishi Chemical Corporation, Huntsman Corporation, Wacker Chemie AG, Royal DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimethylaminoethyl Acrylate Market Evolving Landscape
Formulation chemistry and regulatory compliance are the twin forces reshaping competitive position in dimethylaminoethyl acrylate, with technology convergence and supply chain qualification emerging as the decisive battlegrounds for margin capture.
Photoinitiator-free UV-LED curing systems are collapsing the traditional photoinitiator supply chain by enabling direct excitation of DMAEA's tertiary amine functionality for radical generation. Electronics contract manufacturers in South Korea are piloting these systems for display bonding applications at commercial scale. The structural consequence is compression of the photoinitiator additive market and simplification of formulation bills of materials.
ECHA's 2023-2024 dossier evaluation wave for acrylate substances is accelerating toxicological data generation requirements for DMAEA registrants. Industrial coatings formulators are responding by pre-qualifying alternative amino-functional monomers to derisk supply continuity. The segment most affected is radiation-curable wood coatings, where downstream customers are demanding full substance transparency for LEED v4.1 compliance.
Specification-driven procurement is consolidating buyer power among multinational adhesives producers who now mandate REACH-compliant DMAEA with full supply chain documentation. Distributors serving mid-tier regional formulators are losing volume to direct supplier relationships as qualification costs rise. This pattern is most visible in Germany's automotive adhesives sector, where Tier 1 suppliers have vertically integrated formulation development with captive monomer sourcing.
Dimethylaminoethyl Acrylate Market Segmentation
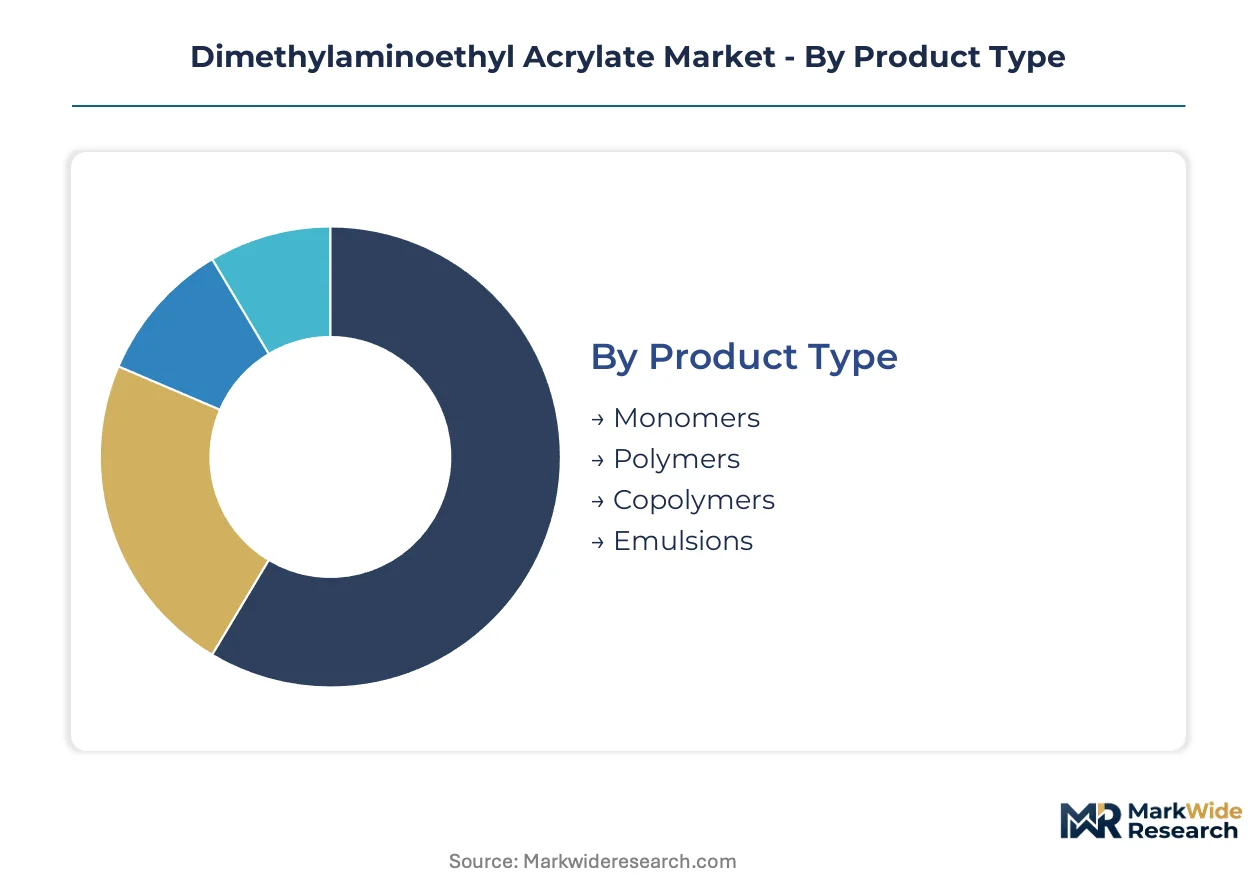
Segmentation in dimethylaminoethyl acrylate reveals distinct velocity profiles across product forms and application channels. Cycle times vary dramatically—liquid monomers turn inventory weekly in Guangdong electronics clusters, while powder grades for construction adhesives sit in 90-day qualification holds.
Product Type:
Inventory velocity separates monomers from downstream derivatives, with reactive diluents clearing formulation floors fastest and emulsion grades facing extended stability testing protocols.
- Monomers:The foundational acrylate feedstock with 157.2 g/mol molecular weight serves as reactive diluent in radiation-curable systems. Electronics-grade specifications in South Korea's display bonding sector pull volumes toward ultra-low residual acrylic acid grades under 50 ppm.
- Polymers:Pre-reacted DMAEA homopolymers eliminate monomer handling hazards in waterborne adhesive plants. German automotive Tier 1 suppliers specify these for interior bonding to meet REACH substance transparency requirements without raw monomer registration burdens.
- Copolymers:Acrylic-DMAEA copolymers balance adhesion and flexibility in pressure-sensitive tapes.
- Emulsions:Aqueous dispersions face 6-month shelf-life validation cycles that slow procurement cadence in textile finishing.
Monomers anchor the volume base while emulsions gain share at the steepest rate as waterborne formulation expands in furniture coatings.
Application:
Margin capture varies sharply across use cases, with semiconductor packaging adhesives commanding specification premiums and textile finishing operating on commodity economics.
- Adhesives:Low-VOC DMAEA systems for electronics miniaturization command 40% formulation premiums over industrial assembly grades. Guangdong contract manufacturers in Shenzhen and Dongguan drive fastest volume expansion as display bonding shifts to UV-LED curing.
- Coatings:Radiation-curable wood and industrial finishes represent the largest value pool. German flooring producers specify REACH-compliant grades with full toxicological dossiers for LEED v4.1 documentation.
- Textiles:Fabric finishing applications prioritize cost over performance in South Asian garment manufacturing.
- Inks:Narrow-web flexographic printing demands rapid cure response in narrow UV-LED wavelength bands.
Coatings generate the highest absolute margins while adhesives climb fastest as electronics contract manufacturers consolidate supplier bases.
End User:
Customer concentration patterns split between project-driven construction procurement and continuous manufacturing in automotive and electronics.
- Construction:Tile adhesives and flooring installation systems consume bulk emulsion grades. Indian infrastructure spending under the PLI scheme for chemical manufacturing is attracting domestic DMAEA capacity to serve this segment.
- Automotive:Interior trim bonding and structural adhesives require thermal stability to 150°C in underhood applications. German OEMs specify full supply chain documentation for CSRD compliance.
- Electronics:Semiconductor packaging and display assembly demand the tightest purity specifications.
- Healthcare:Medical-grade adhesives face biocompatibility testing that extends qualification timelines to 24 months.
Construction anchors volume consumption while electronics expands most quickly as miniaturization drives adhesive specification upgrades.
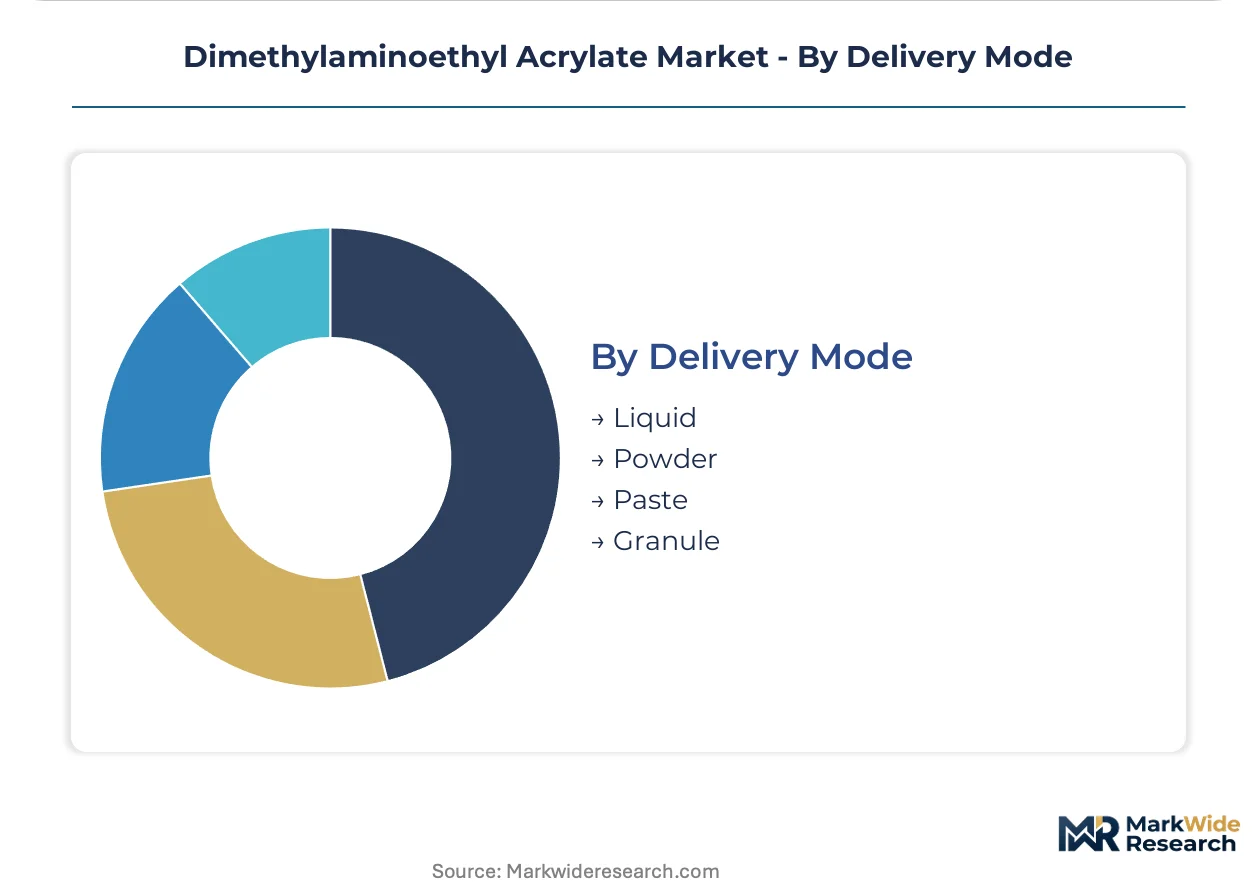
Delivery Mode:
Physical form determines logistics economics and formulation flexibility, with liquid grades dominating tank-car shipments and powder enabling just-in-time compounding.
- Liquid:Bulk tank delivery minimizes handling costs for high-volume waterborne adhesive producers. Ludwigshafen-integrated supply chains serve European coatings formulators via dedicated rail.
- Powder:Free-flowing grades enable dry-blend compounding in remote construction adhesive plants lacking solvent handling permits. Indian distributors stock these for mid-tier regional formulators.
- Paste:Pre-thickened systems reduce mixing energy in small-batch textile finishing operations.
- Granule:Dust-free handling characteristics suit automated dosing in extrusion compounding lines.
Liquid delivery commands the volume base while powder formats gain fastest traction in emerging market infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers absorb volume with limited price elasticity as electronics-grade specifications tighten, while Indian construction adhesive procurement remains acutely sensitive to landed cost fluctuations. European coatings formulators accept specification premiums for REACH-compliant supply chains.
China
Electronics contract manufacturers in Shenzhen and Dongguan drive DMAEA consumption for UV-LED display bonding systems. MEE emission standards under the dual carbon policy framework force facility upgrades among acrylate producers. Guangdong province hosts expanding clusters of semiconductor packaging adhesive operations that specify ultra-low residual acrylic acid grades.
Germany
Automotive Tier 1 suppliers command formulation premiums for interior bonding adhesives with full CSRD-compliant supply chain documentation. ECHA's 2023-2024 dossier evaluation wave accelerates toxicological data requirements for DMAEA registrants. The Ludwigshafen chemical complex sustains captive DMAEA production for integrated polymerization operations serving European coatings channels.
United States
Industrial coatings formulators in the Midwest and Gulf Coast regions demand rapid-cure DMAEA reactive diluents for UV-LED wood finishing systems. EPA TSCA Section 5 premanufacture notification requirements govern new monomer introductions and extend qualification timelines. Texas and Ohio host concentrated radiation-curable coatings manufacturing that pulls tank-car quantities of liquid-grade DMAEA.
South Korea
Display panel manufacturers in the Seoul Capital Area pilot photoinitiator-free UV-LED curing systems using DMAEA's tertiary amine functionality for direct radical generation. MFDS chemical substance notification requirements apply to imported acrylate monomers for electronics applications. Busan-Ulsan industrial corridors house specialty adhesive compounders qualifying for Samsung and LG supply chains.
India
Infrastructure spending on tile adhesives and flooring systems drives bulk emulsion-grade DMAEA demand from price-sensitive construction contractors. The PLI scheme for chemical manufacturing attracts greenfield acrylate investment to serve domestic electronics and automotive adhesive requirements. Gujarat and Maharashtra states concentrate emerging specialty chemical capacity targeting import substitution.
Dimethylaminoethyl Acrylate Market Competitive Landscape
Capability concentration sits with integrated petrochemical majors possessing captive acrylic acid supply; scale advantage sits with regional distributors serving mid-tier formulators. The market structures around three tiers: Ludwigshafen-integrated producers, Asia-Pacific specialty chemical houses, and regional trading distributors. Strategic moves center on backward integration into acrylic acid feedstock and qualification for electronics-grade supply chains.
Within the integrated multinational tier, BASF SE exemplifies captive production economics through its Ludwigshafen site complex. Evonik Industries AG and Dow Chemical Company occupy positions emphasizing amino-functional monomer specialization and North American coatings channel dominance respectively. These three entities represent distinct archetypes: the fully integrated chemical major, the R&D-intensive specialty monomer developer, and the geographic-scale coatings supplier.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Dow Chemical Company |
| Arkema |
| Nippon Shokubai Co., Ltd. |
| Mitsubishi Chemical Corporation |
| Huntsman Corporation |
| Wacker Chemie AG |
| Royal DSM |
| Others |
Value Network & Pricing Analysis
Undercapacity in European DMAEA distillation capacity is compelling buyers to accept longer contract terms and premium pricing for REACH-compliant grades, while simultaneously pushing formulation investment toward Asian supply alternatives.
Pricing Analysis
Long-term offtake agreements dominate procurement for electronics-grade specifications, with annual contracts capturing 70-80% of volume from Ludwigshafen-integrated producers and spot transactions limited to distressed inventory or qualification samples. Price differentiation rests on purity certification tiers and supply chain documentation depth, with CSRD-compliant supply chain transparency commanding 15-25% premiums over standard industrial grades. Cost compression in construction adhesive segments is intensifying because Indian infrastructure contractors prioritize landed cost over specification compliance. Regional formulators in South Asia exhibit the highest price sensitivity, while German automotive Tier 1 suppliers demonstrate minimal elasticity for qualified supply chains.
Supply Chain Analysis
Export-control regimes on dual-use chemical manufacturing equipment are constraining capacity expansion in certain jurisdictions, indirectly tightening global availability of pharmaceutical-grade production assets. Supply concentrates in Germany, China, and South Korea, with Ludwigshafen anchoring European flows and Guangdong province hosting expanding electronics-grade clusters. Raw material dependencies center on acrylic acid feedstock from propylene crackers, dimethylaminoethanol from ethylene oxide derivatives, and specialized catalyst systems for esterification selectivity. Single-source vulnerability around BASF's captive Ludwigshafen production creates structural risk for European buyers seeking spot flexibility. Distribution runs through direct supplier relationships for multinational formulators and regional chemical distributors serving mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat, where REACH registration sunk costs and 18-24 month electronics qualification cycles create switching barriers that protect incumbent positions.
For Market Incumbents: Insulate market position by deepening captive acrylic acid integration and accelerating toxicological dossier updates ahead of ECHA's evaluation waves. Dimethylaminoethyl methacrylate substitution in medical-grade applications threatens amino-acrylate margins; counter through UV-LED curing qualification investments with South Korean display manufacturers. Prioritize direct supply relationships with Shenzhen and Dongguan contract manufacturers to displace distributor intermediaries. For New Entrants and Emerging Players: India's underpenetrated electronics-grade adhesive market offers the most penetrable white space, with PLI scheme incentives reducing capital barriers for greenfield DMAEA investment. Target Gujarat and Maharashtra states for import substitution plays in construction emulsion grades. Qualify for Samsung and LG supply chains through Busan-Ulsan specialty adhesive compounders as the go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronics-grade purification assets, favoring scaled operators with existing distillation infrastructure. Five-to-ten year viability hinges on regulatory compliance capabilities rather than commodity scale. Acquire distressed Chinese acrylate facilities facing MEE emission standard upgrades. Monitor ECHA dossier evaluation outcomes as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive propylene feedstock secures margin stability against crude price volatility. |
| Electronics-Grade Purification Capacity | Ultra-low residual acrylic acid specifications unlock Samsung and LG supply chain access. |
| REACH Consortium Participation | Shared toxicological dossier costs enable smaller producers to maintain European market access. |
| Photoinitiator-Free UV-LED Formulation | Direct amine excitation technology collapses additive supply chains for display bonding. |
| Greenfield Investment Under India's PLI Scheme | Domestic capacity construction serves import substitution in construction and electronics adhesives. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with chemical plant managers, procurement leads at downstream adhesives OEMs, distribution channel partners, and technical R&D directors; and secondary validation through customs and trade flow databases, Cefic and ACC industry reports, SEC 10-K filings of listed chemical majors, and ECHA registration dossiers. Bottom-up volume estimates from application-level consumption patterns were triangulated against top-down capacity assessments from major production sites.
Forecast inputs incorporated grade-tier segmentation across monomer, polymer, and emulsion forms; end-use industry splits between coatings, adhesives, textiles, and inks; and regional production hub dynamics spanning Ludwigshafen-integrated supply, Guangdong electronics clusters, and Indian PLI-driven capacity. CAGRs were derived from elasticity-adjusted demand projections and supply-side constraint modeling. Industry-specific forecast inputs included REACH registration timeline assumptions and UV-LED curing technology penetration curves across display bonding applications.
Practitioners should monitor ECHA dossier evaluation outcomes, MEE enforcement intensity under China's dual carbon framework, and propylene feedstock price volatility for early signals of forecast revision. Material shifts in electronics miniaturization specifications or acrylic acid supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
Europe, Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
Europe Electronics Adhesives Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Canada Sealants Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
North America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
PVA Glue Market