
 China Construction Chemicals Market | 2026-2036
China Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
China Construction Chemicals Market Outlook
GB 8076 concrete admixture standard compliance is unwinding the competitive field, raising barriers for uncertified blenders while rewarding qualified manufacturers. Sika leverages its Swiss-originated technical service model to anchor premium waterproofing positions in tier-one cities. Wanhua Chemical sustains polyurethane raw material dominance through backward integration into MDI production. MUHU Construction Materials competes on admixture customization for high-speed rail concrete specifications.
Construction chemicals encompass formulated additives, binders, and protective materials dosed into concrete, mortar, or applied to structural surfaces to modify rheology, accelerate curing, or enhance durability against carbonation and chloride ingress. These products serve primarily to extend infrastructure service life and enable modern construction methods including self-compacting and ultra-high-performance concrete formulations. Admixtures occupy the largest volume position due to universal concrete modification requirements across all project scales. Sealants command premium margin pools in expansion joint applications for bridges and transit tunnels. Coatings growth concentrates in corrosion protection for industrial facilities along coastal zones where salt-laden atmospheres accelerate rebar degradation.
MIIT enforces GB standard compliance through manufacturing license audits that disqualify subscale producers from supplying state-funded infrastructure projects. SAMR monitors anticompetitive practices in regional admixture markets where local formulation houses historically undercut national brands on price. The dual carbon goals framework pushes demand toward low-carbon cement substitutes and alkali-activated binders that reduce embodied emissions. Stakeholders must track which provincial SOEs receive priority allocation under the 14th Five-Year Plan's construction modernization targets.
Market Dynamics
GB 8076 standard revision is compressing the admixture supply base by disqualifying uncertified blenders from state-funded infrastructure procurement, forcing consolidation around qualified manufacturers with laboratory verification capabilities.
Growth Catalysts
- Dual carbon goals framework:MIIT mandates for embodied carbon reduction are accelerating demand for alkali-activated binders and low-clinker cement substitutes in prefabricated construction supply chains.
- Greater Bay Area infrastructure:Underground waterproofing specifications for transit tunnels and coastal defense projects are pulling advanced polyurethane and crystalline admixture volumes upward.
- 14th Five-Year Plan construction modernization:Provincial SOE priority allocations for high-speed rail and nuclear containment structures are specifying high-performance concrete with customized rheology modifiers.
Market Restraints
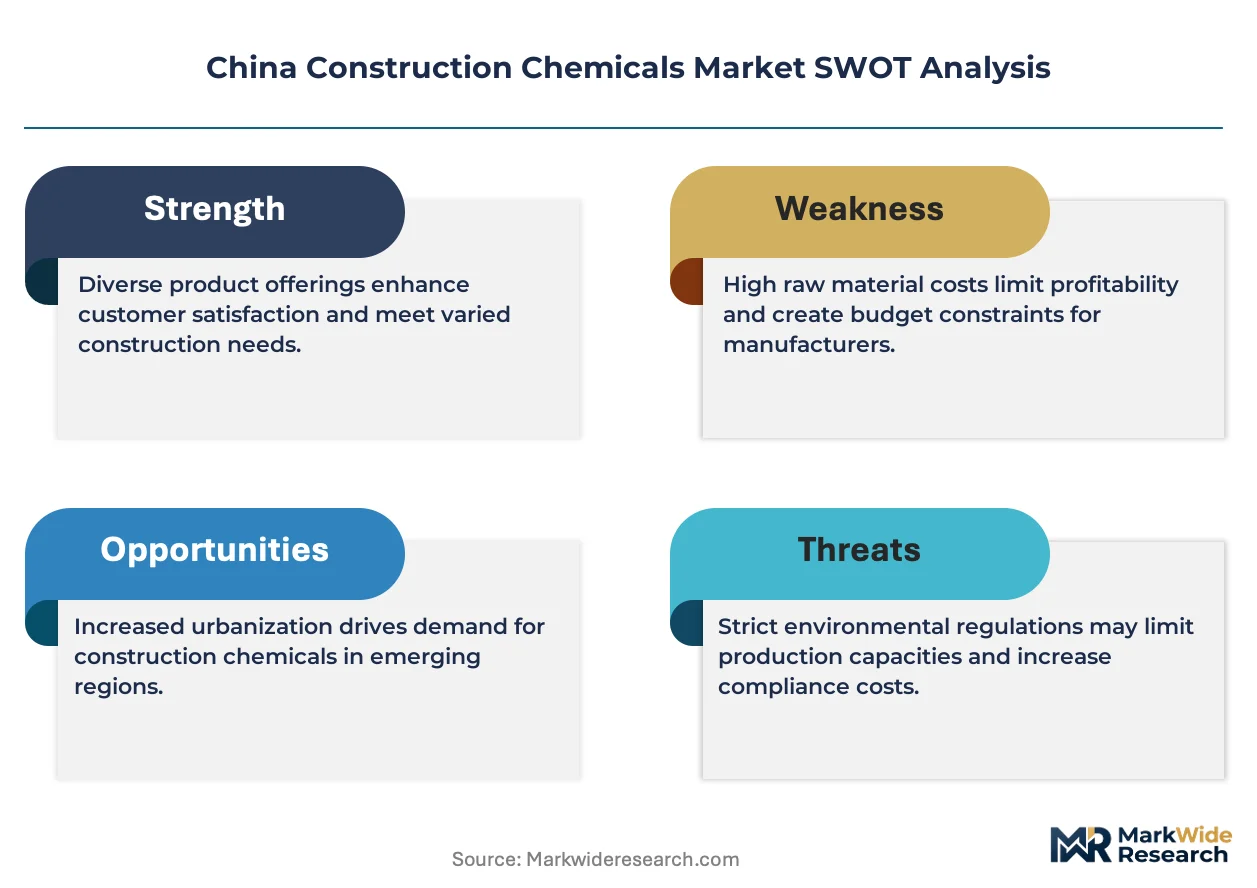
- MDI feedstock concentration:Polyurethane waterproofing membrane producers face input cost volatility tied to Wanhua Chemical's captive MDI supply dominance and import dependency for specialty isocyanates.
- Jiangsu specialty chemical cluster dependency:Prefabricated construction supply chains concentrate admixture sourcing in Yangtze River Delta manufacturing zones, creating geographic concentration risk for nationwide project delivery.
- Chloride ingress test protocol limitations:Accelerated durability testing methods for coastal concrete structures lack standardization across provincial quality supervision bureaus, delaying product qualification timelines.
Strategic Opportunities
- Western region infrastructure gap:Sichuan and Yunnan provinces show underpenetrated admixture markets relative to coastal penetration rates, with hydropower dam construction driving specialty grouting chemical demand.
- Self-healing concrete integration:Convergence of microcapsule-based crack repair systems with conventional superplasticizer dosing protocols opens specification opportunities in nuclear containment and LNG terminal projects.
- SAMR antitrust enforcement:National market regulator scrutiny of regional formulation house price undercutting creates opening for certified national brands to displace local blenders in municipal procurement.
Industry Challenges
- Concrete rheology specialist scarcity:Shortage of technicians capable of calibrating polycarboxylate ether superplasticizer dosages for ultra-high-performance concrete mixes delays project commissioning at high-speed rail sites.
- GB standard certification timeline compression:MIIT manufacturing license audits require 18-24 month laboratory validation cycles that outpace project bid windows, straining working capital for mid-scale admixture blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Construction Chemicals Market |
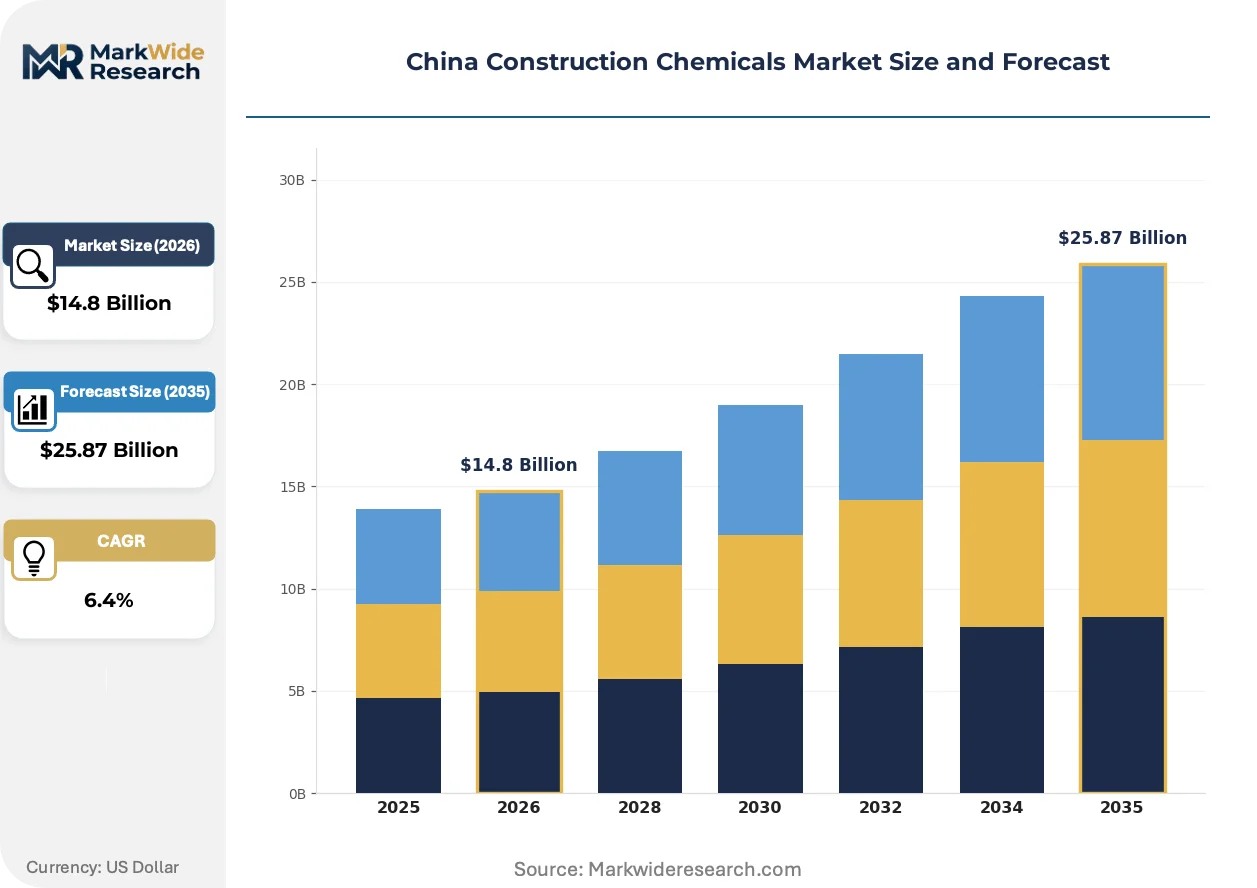
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Adhesives, Coatings Application: Residential Buildings, Commercial Structures, Infrastructure, Industrial Facilities End User: Contractors, Developers, Engineers, Architects Distribution Channel: Direct Sales, Wholesale, E-commerce, Retail |
| Companies Covered | China National Chemical Engineering, Sika, Wanhua Chemical, Henkel, Arkema Group, Sinopec, BASF, Dow, MUHU Construction Materials, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Construction Chemicals Market Strategic Shifts
Formulation chemistry and compliance architecture are converging to reshape competitive positioning, with sustainability mandates and performance verification protocols driving R&D allocation toward next-generation binder systems.
Polycarboxylate ether-based superplasticizers with tailored side-chain architectures are supplanting naphthalene sulfonate formulations in high-speed rail and nuclear containment specifications. China Railway Group and provincial SOE concrete suppliers are completing specification conversions within 24-month procurement cycles. This transition is compressing margins for legacy melamine and lignosulfonate producers while rewarding PCE manufacturers with in-house polymer synthesis capabilities.
MIIT's enforcement of revised GB 8076-2023 concrete admixture standards is disqualifying subscale blenders from state-funded infrastructure supplier lists. Manufacturing license audits now require third-party laboratory verification of performance consistency across temperature and humidity ranges. Prefabricated construction supply chains in Jiangsu and Guangdong provinces are most affected, with project developers consolidating procurement around certified national brands.
Specification-driven procurement is replacing price-first tendering in municipal infrastructure segments. Project owners now mandate certified admixture performance warranties backed by laboratory test data rather than accepting lowest-bid formulations. This behavioral shift is most visible in Shanghai and Shenzhen transit authority concrete supply contracts, where durability verification protocols now precede commercial negotiation.
China Construction Chemicals Market Segmentation
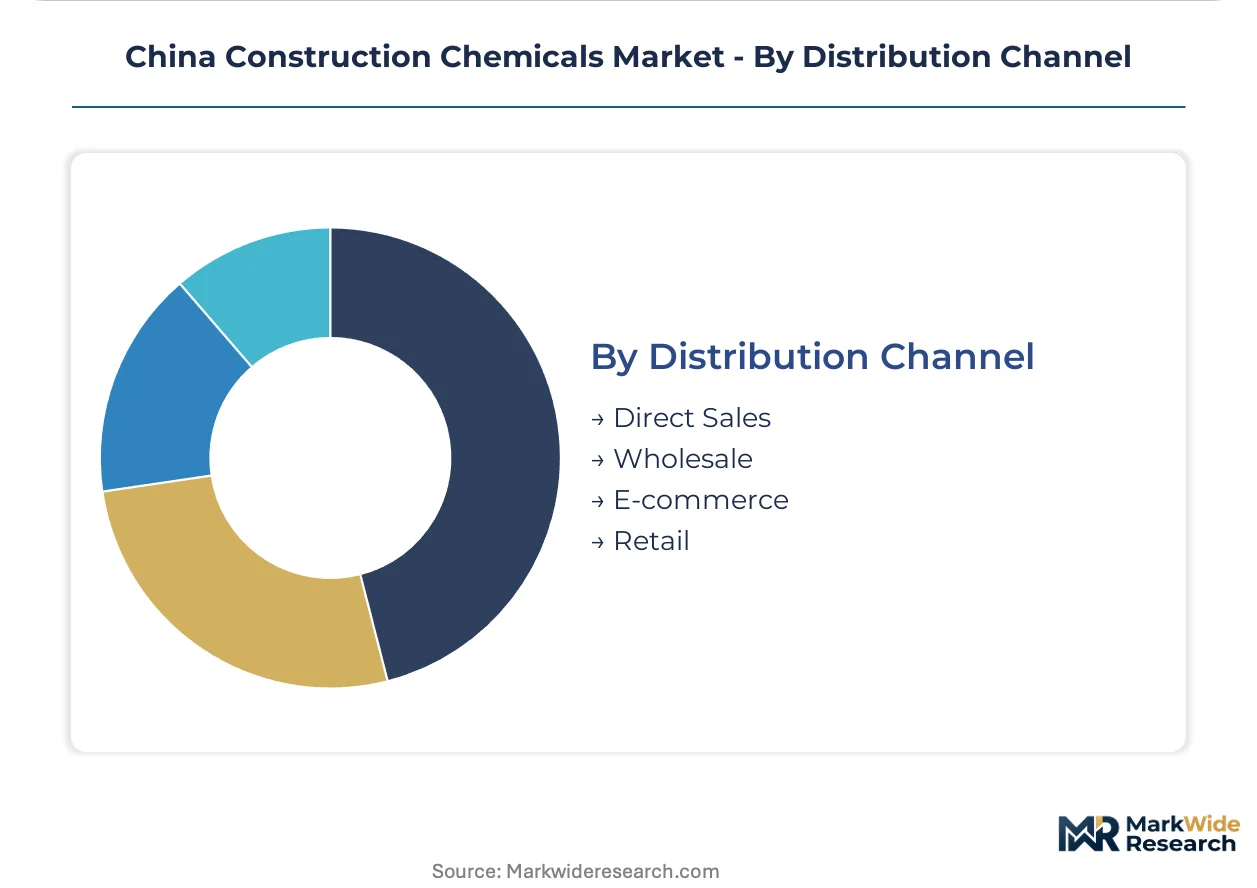
Construction chemicals in China flow through distinct procurement channels that reshape how product categories reach end users. Specification complexity and project scale determine whether admixtures move through direct technical sales or wholesale distribution networks.
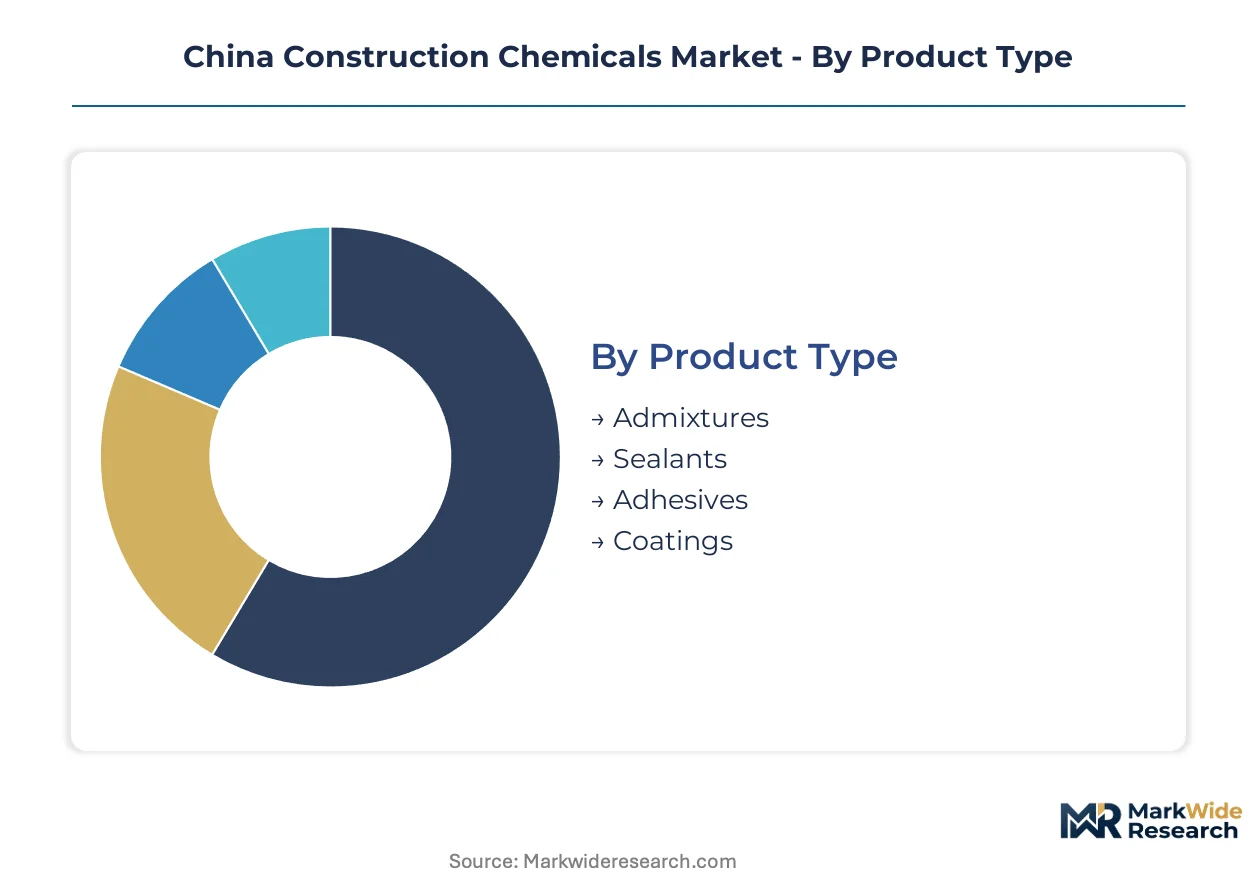
Product Type:
Channel mix varies sharply by product chemistry, with high-specification admixtures flowing through direct sales teams while commodity sealants and coatings penetrate via wholesale distributors.
- Admixtures:Polycarboxylate ether superplasticizers and crystalline waterproofing compounds dominate volume. High-speed rail and nuclear containment projects in Jiangsu and Guangdong provinces pull advanced rheology modifiers through direct technical service channels. MIIT's GB 8076 certification requirements disqualify uncertified blenders from state-funded infrastructure procurement.
- Sealants:Polyurethane and silicone formulations command premium positioning in expansion joint applications. Greater Bay Area transit tunnels and coastal defense structures specify elastomeric sealants with 50-year durability warranties, anchoring direct sales relationships with provincial SOE concrete suppliers.
- Adhesives:Epoxy and acrylic bonding agents serve prefabricated construction connections in Yangtze River Delta manufacturing clusters.
- Coatings:Corrosion protection systems for coastal industrial facilities move through specialty chemical distributors with applicator certification programs.
Admixtures dominate installed base. Sealants are where expansion concentrates.
Application:
Cost tier stratification separates specification-grade products for infrastructure from economy-grade formulations for residential volume construction.
- Infrastructure:High-performance concrete specifications for high-speed rail, nuclear containment, and hydropower dams demand certified admixtures with laboratory-verified durability data. Dual carbon goals framework accelerates alkali-activated binder adoption in state-funded projects. GB 8076 compliance audits disqualify subscale suppliers from provincial SOE procurement lists.
- Industrial Facilities:Coastal petrochemical and LNG terminal projects specify corrosion-resistant coatings and crystalline waterproofing with chloride ingress resistance. Salt-laden atmospheres in Fujian and Zhejiang provinces accelerate rebar protection chemical demand.
- Residential Buildings:Prefabricated housing construction in Jiangsu province concentrates admixture sourcing through integrated supply chain contracts.
- Commercial Structures:Tier-one city skyscraper projects specify self-compacting concrete with customized superplasticizer architectures.
Infrastructure anchors premium pricing power. Industrial facilities are climbing the fastest on coastal corrosion protection mandates.
End User:
Customer type determines technical service intensity, with engineers and architects driving specification authority while contractors execute procurement.
- Engineers:Design institutes and provincial planning bureaus specify admixture performance criteria in tender documents. China Railway Group and municipal transit authorities mandate certified durability warranties backed by third-party laboratory verification.
- Contractors:State-owned construction enterprises execute volume procurement through centralized bidding platforms. Working capital constraints favor suppliers with 18-24 month certification timeline flexibility.
- Developers:Private real estate conglomerates in Shenzhen and Shanghai prioritize cost optimization in residential concrete supply chains.
- Architects:Aesthetic and sustainability specifications influence coating and sealant selection in commercial facade applications.
Engineers control specification authority. Contractors are gaining share fastest on procurement centralization.
Distribution Channel:
Supply concentration in Jiangsu and Guangdong provinces shapes channel effectiveness, with direct sales penetrating high-specification segments while e-commerce gains traction in standardized products.
- Direct Sales:Technical service teams from certified manufacturers calibrate polycarboxylate ether dosages on-site for ultra-high-performance concrete mixes. Sika and Wanhua Chemical anchor premium positions through specification engineering relationships with provincial SOEs.
- Wholesale:Regional distributors serve mid-scale contractors in municipal infrastructure segments with inventory flexibility and local logistics.
- E-commerce:Standardized sealants and commodity adhesives penetrate small contractor segments through B2B platforms with transparent pricing.
- Retail:Hardware channels reach renovation and maintenance applications in residential aftermarket segments.
Direct sales dominates specification-grade revenue. E-commerce is expanding most quickly in commoditized product tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's dual carbon goals framework and provincial SOE procurement centralization are redistributing construction chemical demand across China's economic geography. Prefabricated construction mandates and high-speed rail extensions concentrate specification-grade volumes in eastern manufacturing belts while western infrastructure gaps attract specialty grouting chemical producers.
Yangtze River Delta
Jiangsu province hosts the nation's densest specialty chemical manufacturing clusters, feeding prefabricated construction supply chains with polycarboxylate ether superplasticizers. SAMR manufacturing license audits under revised GB 8076-2023 standards have disqualified numerous subscale blenders from state-funded infrastructure supplier lists. Nanjing and Suzhou industrial zones concentrate certified admixture production capacity serving Shanghai transit authority concrete contracts.
Pearl River Delta
Greater Bay Area underground waterproofing specifications for transit tunnels and coastal defense structures are pulling advanced polyurethane and crystalline admixture volumes upward. Shenzhen and Guangzhou municipal procurement platforms now mandate certified durability warranties backed by third-party laboratory verification rather than lowest-bid formulations. Dongguan manufacturing corridors supply elastomeric sealants with 50-year durability warranties for expansion joint applications.
Beijing-Tianjin-Hebei
Nuclear containment structures and high-speed rail extensions specify ultra-high-performance concrete with customized rheology modifiers. Hebei province's steel industry adjacency creates demand for corrosion-resistant coatings in industrial facility maintenance. Tianjin port logistics enable import distribution of specialty isocyanates for polyurethane waterproofing membrane production.
Sichuan-Chongqing
Hydropower dam construction in the upper Yangtze basin drives specialty grouting chemical demand in an otherwise underpenetrated admixture market relative to coastal penetration rates. Chongqing municipal infrastructure expansion specifies alkali-activated binders to meet provincial embodied carbon reduction targets. Chengdu's growing prefabricated construction sector attracts distributors establishing western regional logistics hubs.
Shandong Peninsula
Coastal petrochemical and LNG terminal projects in Qingdao and Yantai specify corrosion protection systems with chloride ingress resistance. Salt-laden atmospheres accelerate rebar protection chemical demand across industrial facility portfolios. Shandong's cement industry concentration supports local blending operations serving municipal infrastructure segments with economy-grade formulations.
China Construction Chemicals Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with captive raw material positions and specialized construction material formulators with technical service capabilities. Market structure exhibits tiered concentration, with national brands capturing specification-grade infrastructure procurement while regional blenders retain residential and municipal segments. Three archetypes dominate: integrated petrochemical producers with backward integration into polymer feedstocks, Swiss-originated technical service specialists, and domestic formulation houses competing on admixture customization. Competitive dynamics center on GB 8076 certification acquisition timelines and specification engineering relationships with provincial SOEs.
Within the certified national brand tier, Sika and Wanhua Chemical occupy positions shaped by distinct capability foundations. Sika represents the technical service archetype anchored in premium waterproofing positions through specification engineering relationships. Wanhua Chemical exemplifies feedstock-integrated competitive positioning through captive MDI supply dominance. MUHU Construction Materials sits within the domestic customization specialist segment, competing on high-speed rail concrete specification alignment. These three illustrate how certification compliance, raw material control, and application-specific formulation expertise separate viable competitors from disqualified blenders.
| Leading Market Players |
|---|
| China National Chemical Engineering |
| Sika |
| Wanhua Chemical |
| Henkel |
| Arkema Group |
| Sinopec |
| BASF |
| Dow |
| MUHU Construction Materials |
| Others |
Value Chain & Pricing Dynamics
GB 8076-2023 certification compliance gates both supplier qualification and price differentiation simultaneously, compressing the admixture field into certified national brands commanding premium positioning while uncertified blenders retreat to gray-market residential segments.
Pricing Analysis
Project-based cost-plus contracts with naphtha and MDI indexation dominate procurement between polyurethane waterproofing membrane producers and provincial SOE concrete suppliers. Three-tier pricing structure across premium certified, standard qualified, and economy unbranded levels separates Sika and Wanhua Chemical from regional blenders. Pricing pressure stems from Wanhua's captive MDI supply dominance forcing import-dependent competitors into margin squeeze. Municipal contractors exhibit highest price sensitivity, while nuclear containment and high-speed rail projects prioritize performance verification over unit cost.
Supply Chain Analysis
Strategic stockpiling of polycarboxylate ether superplasticizer feedstock prevails among Jiangsu province manufacturers serving prefabricated construction contracts with 18-24 month certification timelines. Supply concentrates in Jiangsu and Guangdong specialty chemical clusters, with MDI and specialty isocyanates drawing from Shandong and imported channels. Single-source vulnerability runs through Wanhua Chemical's MDI production dominance. Distribution runs through direct technical sales for specification-grade admixtures and wholesale networks for commodity sealants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prefabricated construction platform economics are reaching an inflection as MIIT procurement centralization forces interoperability between provincial SOE concrete suppliers and certified admixture manufacturers.
For Market Incumbents: Compound technical service capabilities through on-site polycarboxylate ether dosage calibration teams that lock in ultra-high-performance concrete specifications. Accelerate backward integration into polymer feedstock production to offset MDI cost volatility threatening polyurethane waterproofing margins. Prioritize GB 8076-2023 certification maintenance investments to defend against SAMR manufacturing license audits disqualifying subscale competitors. For New Entrants and Emerging Players: GB 8076 fast-track certification through third-party laboratory verification partnerships offers entry into Sichuan and Yunnan hydropower dam segments where coastal brands maintain thin presence. Target specialty grouting chemical demand in western provinces showing admixture penetration gaps relative to Yangtze River Delta saturation. Lead with alkali-activated binder formulations aligned to provincial embodied carbon reduction mandates. For Investors and Strategic Acquirers: MIIT's dual carbon goals framework reshapes the acquisition landscape toward low-clinker cement substitute technologies and alkali-activated binder IP portfolios. Five-to-ten year viability hinges on positioning ahead of 14th Five-Year Plan construction modernization procurement waves. Target domestic formulation houses with existing high-speed rail specification relationships. Watch for provincial SOE procurement platform consolidation signaling certification-tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Production | Wanhua Chemical's captive supply dominance demonstrates raw material control as margin defense against import volatility. |
| GB 8076-2023 Certification Investment | Third-party laboratory verification capabilities gate state-funded infrastructure procurement lists under MIIT manufacturing license audits. |
| Western Regional Logistics Hub Establishment | Chengdu distribution centers capture Sichuan-Chongqing prefabricated construction growth outside coastal supply chain concentration. |
| Self-Healing Concrete Microcapsule R&D | Convergence with superplasticizer dosing protocols opens nuclear containment and LNG terminal specification opportunities. |
| SAMR Antitrust Compliance Positioning | National market regulator scrutiny of regional blender price undercutting creates certified brand displacement openings in municipal procurement. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant managers at Jiangsu and Guangdong specialty chemical facilities, procurement leads at provincial SOE concrete suppliers, distribution channel partners in Yangtze River Delta manufacturing clusters, and technical R&D directors at certified admixture manufacturers; alongside secondary validation through MIIT GB standard documentation, SAMR manufacturing license audit records, China Railway Group procurement disclosures, and provincial 14th Five-Year Plan construction modernization filings. Bottom-up volume triangulation against top-down value estimates anchored market sizing.
Across the analysis window, the forecasting framework modeled product type segmentation by chemistry complexity, application segmentation by infrastructure versus residential cost tier, end user segmentation by specification authority versus procurement execution, and distribution channel segmentation by technical service intensity. CAGRs derived from trend extrapolation of polycarboxylate ether conversion rates, alkali-activated binder adoption curves under dual carbon mandates, and waterproofing specification upgrades in Greater Bay Area transit tunnels.
The analysis sits within stated boundaries; outcomes outside sustained MIIT enforcement of GB 8076 certification timelines, Wanhua Chemical MDI pricing stability, and provincial SOE procurement centralization would require recalibration. Forecasts reflect documented assumptions around laboratory verification capacity expansion and chloride ingress test protocol standardization progress. Revision becomes warranted when SAMR antitrust enforcement intensity or western infrastructure investment allocation crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Textile Binders Market
Adhesives & Sealants
Asia-Pacific Polyurethane Adhesives Market
Adhesives & Sealants
South America Construction Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Global Bonding Varnish Market
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
North America Hot Melt Adhesives Market
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Global Construction Adhesives and Sealants Market
Adhesives & Sealants
Anti-Seize Compounds Market
Adhesives & Sealants
North America Contact Adhesives Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Contact Cement Market
Adhesives & Sealants
Nigeria Tile Adhesive Market