
 Fiber Reinforced Polymer (FRP) Rebars Market | 2026-2036
Fiber Reinforced Polymer (FRP) Rebars Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Reinforced Polymer (FRP) Rebars Market Analysis
The capital-intensity gap between integrated pultrusion operators and regional distributors is collapsing as continuous fiber processing equipment becomes more accessible. Pultrall Inc. leverages captive resin formulation capabilities to control material consistency across its Quebec manufacturing base. Owens Corning Inc. anchors its position through vertical integration from glass fiber melt to finished rebar, sustaining cost advantages in high-volume infrastructure bids. Schoeck International differentiates through precision-engineered connection systems that simplify contractor adoption in European markets.
Fiber Reinforced Polymer (FRP) Rebars are composite reinforcement bars manufactured by pultruding continuous glass, carbon, basalt, or hybrid fibers through thermosetting resin matrices, typically achieving tensile strengths exceeding 700 MPa with weights one-quarter that of steel. Their primary purpose is to eliminate corrosion in concrete structures exposed to de-icing salts, marine environments, or chemical attack. Glass FRP dominates current volume owing to cost parity with epoxy-coated steel in bridge decks, while Carbon FRP commands premium positioning in pre-stressed applications where modulus requirements exclude alternatives. Marine end users represent the fastest-expanding demand pool as port authorities specify zero-maintenance reinforcement for seawall and pier reconstruction.
ACI 440.1R guides structural design in the United States, while CSA S806 governs Canadian adoption and EOTA TR023 facilitates CE marking across European member states. These frameworks collectively determine allowable stress limits, durability factors, and fire-resistance ratings that engineers must satisfy before specifying FRP in load-bearing elements. Stakeholders should monitor pending updates to Eurocode 2 and ISO 10406-1 that will either expand or constrain FRP rebar eligibility in primary structural members.
Market Dynamics
The bridge rehabilitation wave across North America and Europe is compressing steel rebar's installed base as chloride-induced corrosion failures accelerate specification switches to fiber-reinforced alternatives.
Growth Catalysts
- ACI 440.1R Design Guidelines:The American Concrete Institute's updated structural design framework removed engineering acceptance barriers for FRP reinforcement in load-bearing concrete elements across US infrastructure projects.
- Marine Infrastructure:Port authorities in coastal highway corridors now specify zero-maintenance reinforcement for seawall and pier reconstruction, eliminating lifecycle cost penalties of conventional steel.
- Pultrusion Equipment Accessibility:Continuous fiber processing machinery costs have declined, collapsing the capital-intensity gap between integrated manufacturers and regional distributors.
Market Restraints
- Resin Price Volatility:Epoxy and vinyl ester resin feedstocks fluctuate with petrochemical cycles, compressing margin predictability for pultrusion operators without captive formulation capabilities.
- Modulus Limitations:Glass FRP's lower elastic modulus versus steel restricts deployment in pre-stressed applications where deflection criteria exclude all but carbon fiber alternatives.
- Fire Resistance Certification:Current building codes in multiple jurisdictions mandate supplemental fireproofing for FRP-reinforced primary structural members, adding installed cost premiums.
Strategic Opportunities
- Eurocode 2 Expansion:Pending updates to European structural concrete standards may broaden FRP rebar eligibility in primary members, unlocking public procurement volumes.
- Hybrid Fiber Systems:Combining glass and carbon fiber architectures in single rebar profiles addresses modulus gaps while containing material costs for mid-performance applications.
- Direct Contractor Distribution:Bypassing traditional rebar distributors through jobsite delivery partnerships reduces handling stages and captures margin from specification to installation.
Industry Challenges
- Structural Engineering Familiarity:Design firms require retraining on FRP-specific creep rupture and durability factors, slowing specification velocity despite code compliance.
- Quality Certification Delays:ISO 10406-1 testing protocols for rebar mechanical properties extend product qualification timelines, freezing inventory capital for emerging suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Reinforced Polymer (FRP) Rebars Market |
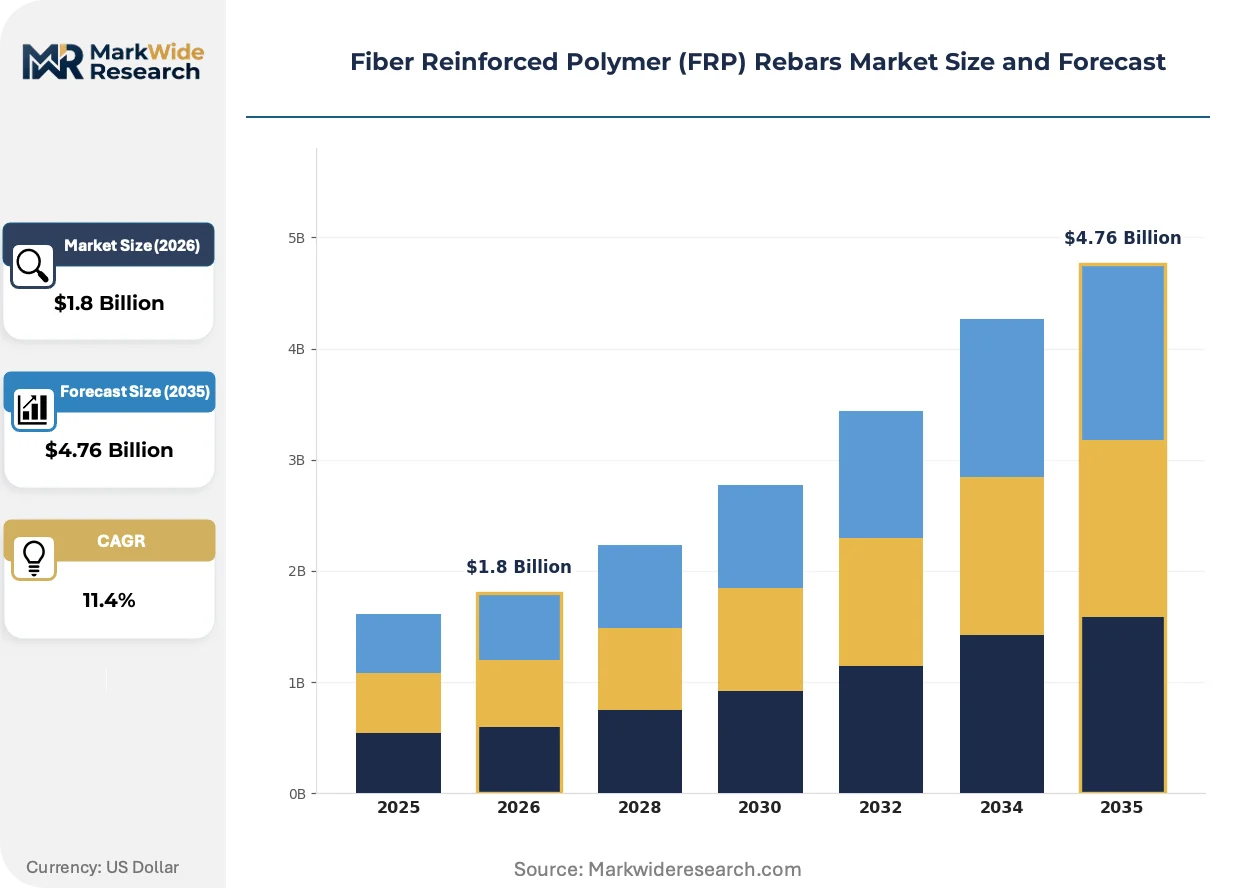
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass FRP, Carbon FRP, Hybrid FRP, Basalt FRP End User: Infrastructure, Residential, Commercial, Marine Application: Bridges, Parking Structures, Building Foundations, Retaining Walls Installation Method: Precast, Cast-in-Place, Post-Tensioned, Pre-Stressed |
| Companies Covered | Pultrall Inc., Kodiak Fiberglass Rebar, Dextra Group, Armastek Co., Schoeck International, Pultron Composites, Hughes Brothers Inc., Aslan FRP, Owens Corning Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Reinforced Polymer (FRP) Rebars Market Emerging Trajectories
Material science advances and code harmonization are compressing the engineering risk premium that has historically constrained FRP rebar to niche corrosion-protection applications.
Continuous basalt fiber pultrusion is supplanting conventional glass fiber in high-pH concrete environments where alkali-silica reaction degrades E-glass performance. European precast manufacturers are adopting basalt-FRP at accelerating rates for tunnel segment and wastewater treatment infrastructure. This substitution is compressing the performance-cost gap between commodity glass and premium carbon fiber reinforcements.
CE marking facilitation through EOTA TR023 technical reports is harmonizing FRP rebar acceptance criteria across EU member states, reducing the regulatory fragmentation that previously forced manufacturers to maintain multiple national approval portfolios. German and French infrastructure agencies are now cross-recognizing certified products, streamlining vendor qualification for transnational contractors.
Engineering-procurement-construction firms are consolidating rebar specifications at the portfolio level rather than project-by-project, favoring suppliers with integrated design assistance capabilities. This concentration is displacing spot-market distributors who lack in-house structural calculation support. The shift is most pronounced in Nordic bridge replacement programs where design-build contracts bundle material and engineering liability.
Fiber Reinforced Polymer (FRP) Rebars Market Segmentation
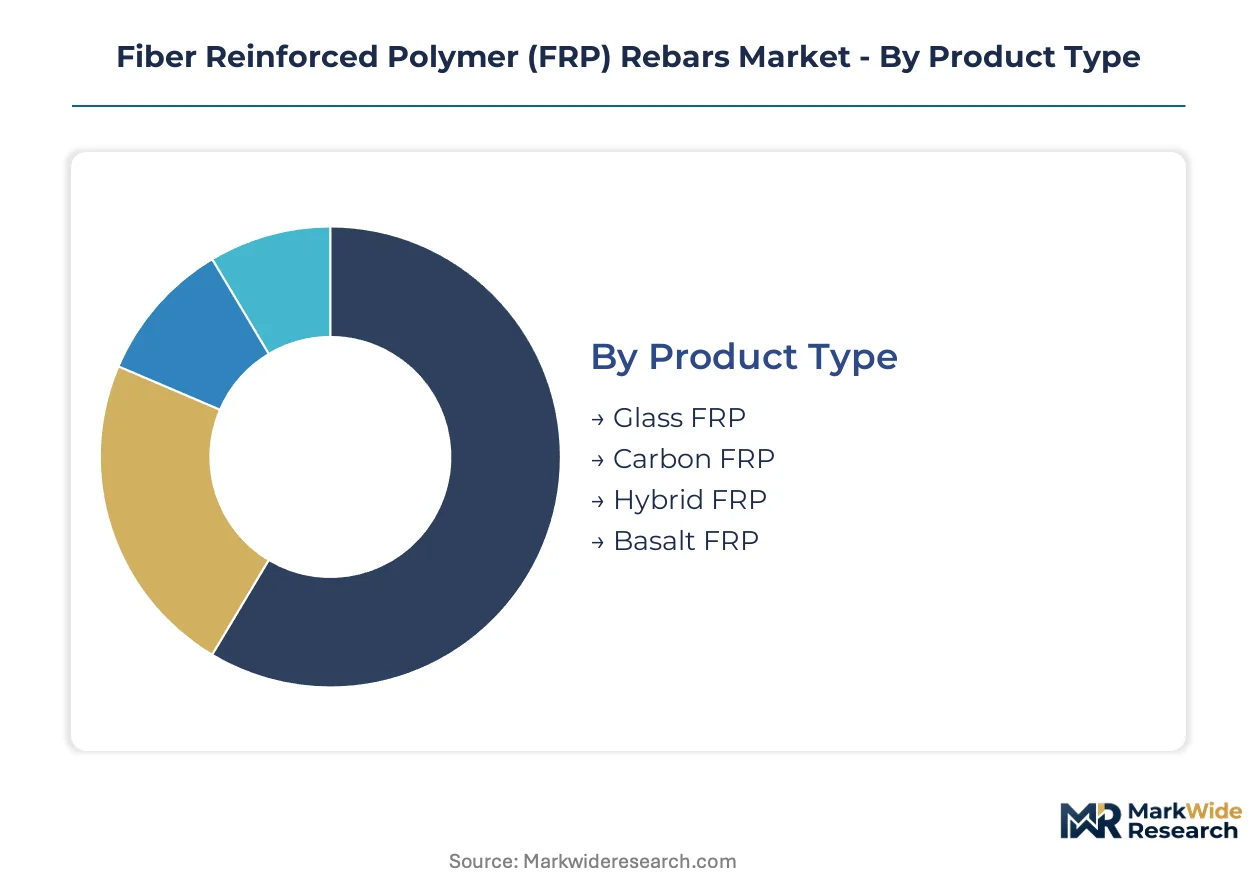
FRP rebar specifications diverge sharply across load-bearing requirements and environmental exposure, creating distinct procurement channels. Engineers select fiber types based on modulus demands, while contractors segment by installation compatibility with existing forming systems.
Product Type:
Glass FRP dominates distributor inventories through construction supply houses serving highway agencies, while carbon FRP moves through specialized precast fabricators with in-house engineering capabilities.
- Glass FRP:E-glass and S-glass variants pultruded with vinyl ester resins achieve tensile strengths of 600-750 MPa at densities one-quarter of steel. State departments of transportation in coastal US corridors specify glass FRP for bridge deck overlays where chloride exposure exceeds epoxy-coated steel durability limits.
- Carbon FRP:PAN-based carbon fibers deliver elastic modulus values approaching 150 GPa, enabling deployment in pre-stressed concrete girders where deflection criteria exclude glass alternatives. Demand concentrates in German and Japanese high-speed rail viaducts requiring 100-year design life without maintenance access.
- Hybrid FRP:Glass-carbon hybrid architectures balance cost and stiffness for mid-performance applications.
- Basalt FRP:Continuous basalt fiber pultrusion resists alkali-silica reaction in high-pH concrete environments where E-glass degrades.
By volume, Glass FRP leads. By growth pace, Basalt FRP is ahead.
End User:
Cost tiers separate specification authority: infrastructure agencies control material standards through public procurement codes, while marine operators prioritize lifecycle cost over first cost.
- Infrastructure:Federal and state highway agencies command the largest specification volumes through design-bid-build and design-build contracts. ACI 440.1R compliance unlocks federal-aid eligibility for bridge rehabilitation projects across the United States.
- Marine:Port authorities in Rotterdam, Singapore, and Long Beach specify zero-maintenance reinforcement for seawall reconstruction where tidal immersion accelerates steel corrosion. Lifecycle cost modeling favors FRP despite 2-3x material cost premiums.
- Residential:Foundation and basement wall applications concentrate in coastal flood zones with saltwater intrusion risk.
- Commercial:Parking garage specifications are shifting as chloride-induced spalling drives insurance liability concerns.
Infrastructure captures the largest absolute volume. Marine end users are climbing the fastest as port modernization accelerates.
Application:
Volume concentrates in horizontal elements where concrete cover requirements for steel create weight penalties FRP eliminates.
- Bridges:Deck slab reinforcement and barrier wall applications dominate current specification as chloride-induced corrosion failures in steel force rehabilitation cycles. Canadian provincial ministries and US state DOTs now mandate FRP in new construction within splash zones.
- Parking Structures:Multi-level garages in northern climates face accelerated deterioration from de-icing salt tracking; FRP eliminates cathodic protection system costs.
- Building Foundations:Coastal residential and commercial footings specify FRP where groundwater salinity exceeds corrosion thresholds.
- Retaining Walls:Mechanically stabilized earth systems incorporate FRP geogrids and rebars for permanent soil retention.
Bridges lead by installed tonnage. Parking structures are gaining share fastest as private owners internalize lifecycle maintenance costs.
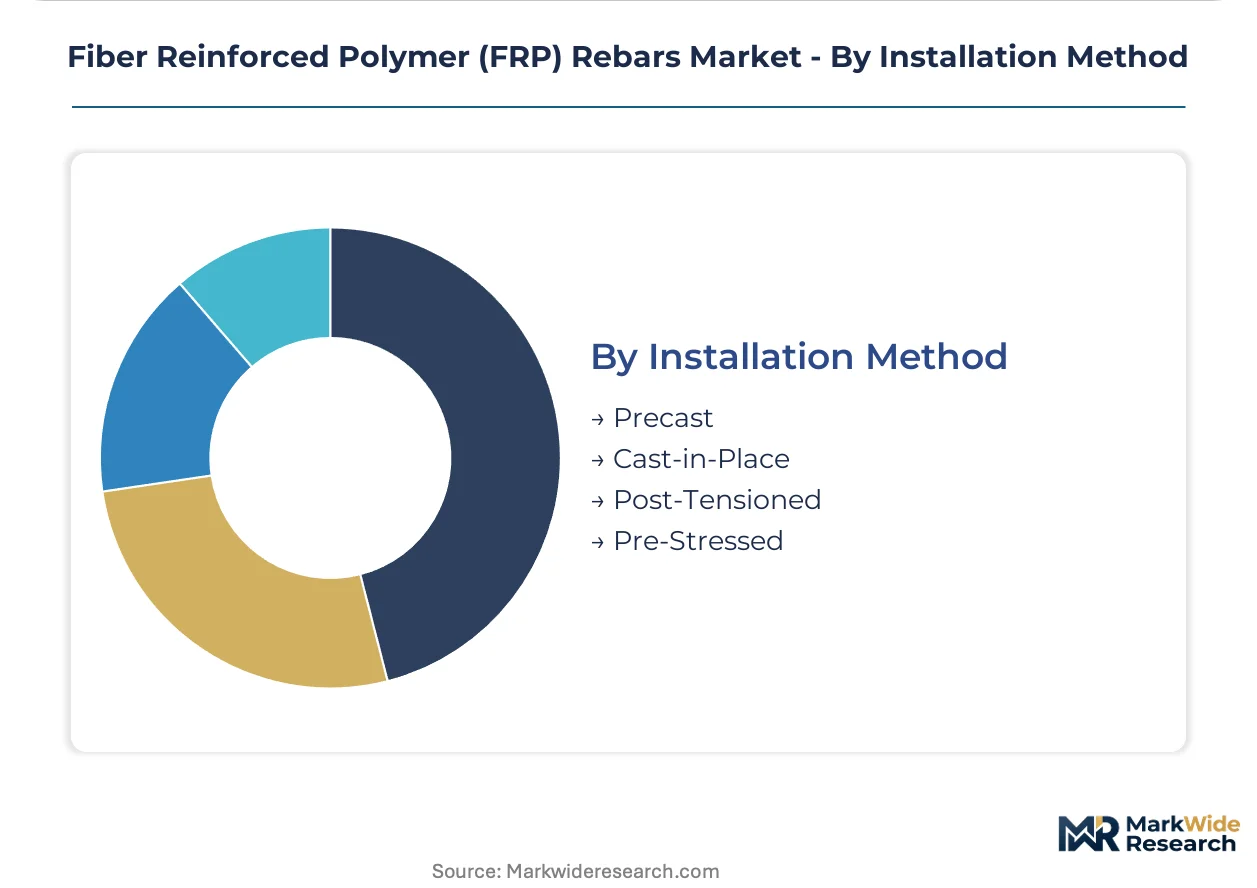
Installation Method:
Customer type determines channel access: precast fabricators purchase direct from pultruders, while cast-in-place contractors source through rebar distributors with cutting and bending services.
- Precast:Factory-controlled curing environments enable tight dimensional tolerances for FRP rebar placement; tunnel segment and bridge girder manufacturers in Italy and Japan lead adoption.
- Cast-in-Place:Field placement requires modified bending equipment and snap-tie techniques; contractor training programs in Quebec and Florida address installation competency gaps.
- Post-Tensioned:FRP tendons eliminate galvanic corrosion concerns in bonded and unbonded applications.
- Pre-Stressed:Carbon FRP's high modulus enables long-span girders with reduced section depth.
Precast commands the highest volume per project. Cast-in-Place is expanding most quickly as field-proven techniques diffuse through contractor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine port authorities in Singapore and Rotterdam accept 2-3x material cost premiums for zero-maintenance reinforcement, while US state DOTs demand cost parity with epoxy-coated steel. This elasticity divide separates specification authority between lifecycle-cost buyers and first-cost-constrained agencies.
United States
State transportation departments in coastal corridors drive bridge deck rehabilitation demand as chloride-induced corrosion failures accelerate. ACI 440.1R compliance unlocks federal-aid eligibility for FRP-reinforced load-bearing elements. The I-95 corridor from Boston to Miami concentrates specification activity where tidal splash zones destroy conventional rebar within two decades.
Germany
High-speed rail viaduct programs specify carbon FRP for 100-year design life without maintenance access. EOTA TR023 CE marking harmonization enables cross-border vendor qualification across EU member states. The Rhine-Ruhr industrial belt hosts precast fabricators adopting basalt fiber for tunnel segment production.
Canada
Provincial ministries mandate FRP in new bridge construction within marine splash zones. CSA S806 governs structural design acceptance, removing engineering barriers that constrained earlier adoption. Quebec's pultrusion manufacturing base supplies North American distributors with captive resin formulation capabilities.
Japan
Metropolitan expressway reconstruction prioritizes carbon FRP for pre-stressed girders where deflection criteria exclude glass alternatives. JIS standards and METI infrastructure guidelines shape allowable stress limits for seismic-resistant applications. The Osaka-Kobe corridor leads cast-in-place contractor training programs for field placement techniques.
United Arab Emirates
Port modernization at Jebel Ali and Khalifa specifies zero-maintenance reinforcement for seawall reconstruction in hypersaline Gulf waters. MOHAP and federal infrastructure codes are adapting to FRP-specific durability factors. Dubai's design-build contracting concentration favors suppliers with integrated structural calculation support.
Fiber Reinforced Polymer (FRP) Rebars Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with resin formulation and fiber processing capabilities determining bid competitiveness. Pultrusion equipment cost declines have compressed the capital barrier between these tiers, enabling mid-scale fabricators to challenge volume positions. Three archetypes dominate: resin-integrated pultruders, fiber-to-finish vertical operators, and connection-system specialists. Capacity expansion and backward integration into captive resin supply represent the dominant competitive moves.
Among North American fabricators, Pultrall Inc. and Hughes Brothers Inc. occupy positions within the integrated manufacturing tier, while Owens Corning Inc. anchors the fiber-to-finish archetype through glass fiber melt capabilities. Schoeck International exemplifies the European connection-system specialist model. These companies represent strategic positioning patterns rather than discrete market shares, with each archetype capturing margin through distinct control points—resin consistency, fiber cost, or engineering simplification.
| Leading Market Players |
|---|
| Pultrall Inc. |
| Kodiak Fiberglass Rebar |
| Dextra Group |
| Armastek Co. |
| Schoeck International |
| Pultron Composites |
| Hughes Brothers Inc. |
| Aslan FRP |
| Owens Corning Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day resin inventory cycles at Quebec and German pultrusion facilities concentrate pricing power with integrated operators who control vinyl ester formulation in-house. This lead-time band compresses margin capture for distributors without captive resin supply, while buyers in coastal US highway corridors face escalating total-cost pressure as chloride-driven steel failures accelerate specification switches.
Pricing Analysis
After-sales engineering support contracts drive lifetime value for FRP rebar suppliers, with project-based pricing dominating infrastructure procurement through state DOT bid processes. Three-tier pricing structure across premium carbon, standard glass, and economy hybrid fiber tiers separates pre-stressed applications from bridge deck overlays. Cost compression in glass FRP is intensifying because pultrusion equipment accessibility erodes regional distributor markups. State transportation agencies exhibit highest price sensitivity, demanding epoxy-coated steel parity, while marine port authorities accept material premiums for zero-maintenance lifecycle guarantees.
Supply Chain Analysis
Inventory cycles at North American and European pultruders hinge on epoxy and vinyl ester resin availability from petrochemical feedstock suppliers in the US Gulf Coast, Germany, and South Korea. Continuous glass fiber supply draws from Owens Corning's vertical melt operations and Chinese E-glass producers, while carbon fiber sources concentrate in Japan and the US. Single-source vulnerability in aerospace-grade PAN precursor creates bottleneck risk for carbon FRP pre-stressed applications. Distribution runs through rebar distributors with cutting and bending services for cast-in-place contractors, while precast fabricators purchase direct from pultruders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
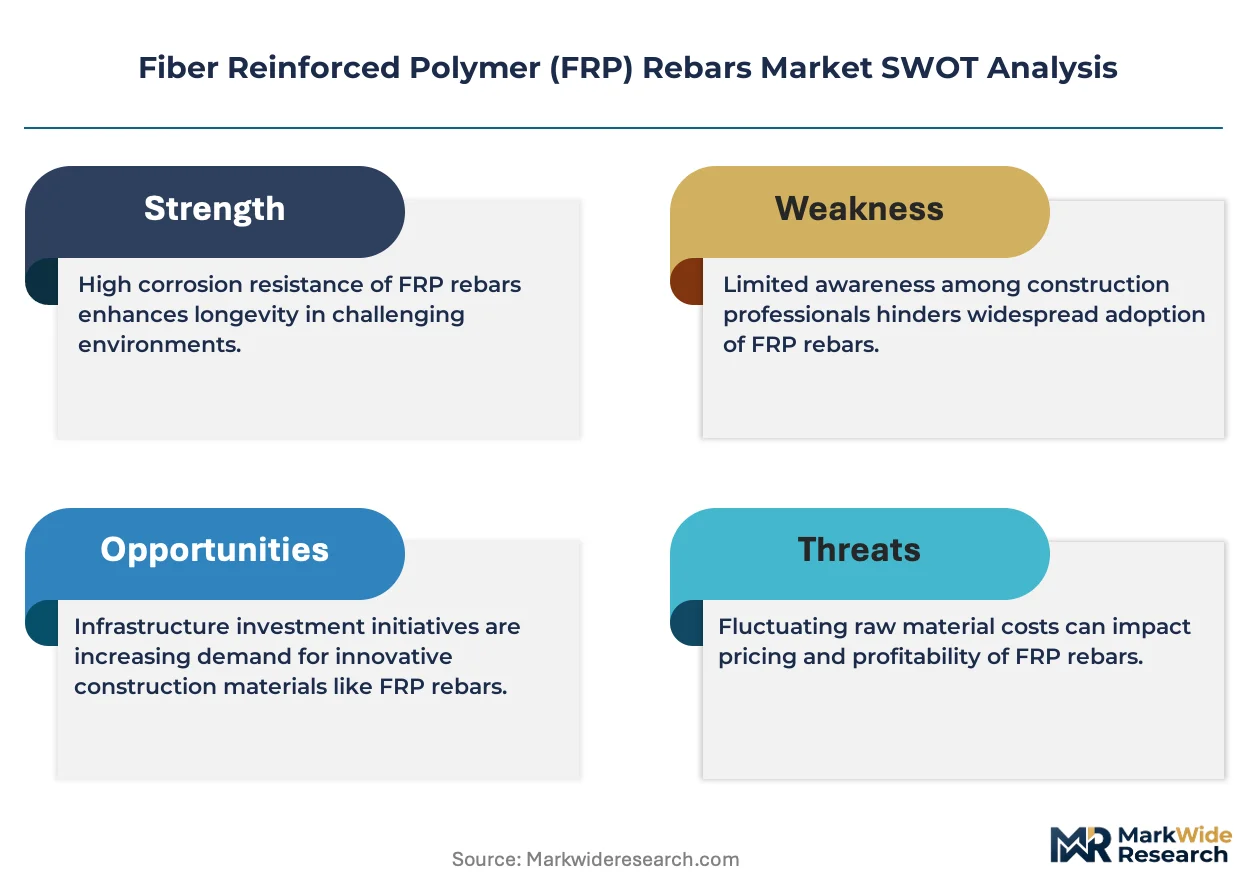
This market sits in early-cycle expansion as ACI 440.1R compliance unlocks federal-aid eligibility for load-bearing applications, compressing the engineering familiarity barrier that historically constrained FRP to niche corrosion protection.
For Market Incumbents: Compound resin formulation advantages by securing captive vinyl ester supply agreements with US Gulf Coast petrochemical producers, insulating margin from feedstock volatility. Add pultrusion capacity in Florida and California to capture I-95 corridor rehabilitation demand before regional distributors upgrade equipment. ISO 10406-1 certification investment blocks emerging suppliers from qualifying inventory. For New Entrants and Emerging Players: EOTA TR023 fast-track certification enables CE marking penetration into German and French infrastructure agencies now cross-recognizing certified products. Target precast concrete fabricators in Italy and Japan with direct technical sales support, bypassing rebar distributor markups. Basalt FRP for tunnel segments offers the most penetrable white-space as European manufacturers accelerate alkali-silica reaction-resistant substitutions. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified composites conglomerates with undermonetized FRP rebar divisions lacking infrastructure-focused sales engineering. Five-to-ten-year viability rests on code expansion into primary structural members rather than rehabilitation niches. Watch pending Eurocode 2 updates as the critical inflection signal for public procurement volume unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive vinyl ester supply insulates Pultrall and Owens Corning from petrochemical cycle volatility. |
| ACI 440.1R Certification Investment | Compliance unlocks federal-aid eligibility for US state DOT bridge rehabilitation contracts. |
| Direct Contractor Distribution Partnerships | Jobsite delivery bypasses rebar distributor handling stages and captures specification-to-installation margin. |
| Hybrid Fiber System Development | Glass-carbon architectures address modulus gaps while containing material costs for mid-performance applications. |
| Eurocode 2 Expansion Lobbying | Broader FRP eligibility in primary members unlocks German and French public procurement volumes. |
Methodological Framework
A standing panel of pultrusion plant managers, state DOT materials engineers, precast concrete fabricators, and marine port authority specification officers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from ACI committee documentation, CSA S806 technical revisions, EOTA TR023 CE marking reports, and customs trade data for FRP rebar imports. Bottom-up volume estimates from pultruder capacity utilization triangulated against top-down infrastructure spending allocations.
Consistency checks against bridge rehabilitation project databases and port modernization contract awards validated volume and value outputs across the projection horizon. Segmentation modeling incorporated fiber type, end-user category, application, and installation method dimensions. CAGRs derived from elasticity-adjusted substitution rates for steel rebar in chloride-exposed environments, with resin price indices and code adoption curves as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued ACI 440.1R and CSA S806 code stability; material deviation in Eurocode 2 expansion timing or resin feedstock disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Lightweight Precast Wall Panel Market
Building Materials
Global White Cement Market
Building Materials
Composite Decking and Railing Market
Building Materials
Qatar Facade Market
Building Materials
United States Architectural Coatings Market
Building Materials
Asia-Pacific Facade Market
Building Materials
Italy Cement Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Concrete Admixtures Market
Building Materials
Cellular Concrete Market
Building Materials
China Cement Market
Building Materials
North America Architectural Coatings Market
Building Materials
Stone Adhesive Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
West Africa Cement Market
Building Materials
US Facade Market